Key Takeaways
- HHLR Advisors, part of Hillhouse, added to PDD Holdings, Alibaba and Legend Biotech last quarter, and together they’re now just over half of its US stock portfolio.
- PDD and Alibaba both reported strong September quarters on Nov. 19. PDD’s ad revenue grew faster and Alibaba’s cloud revenue rose 53%.
- Alibaba is down 23% and Legend Biotech 19% since Sept. 30, while PDD is up 10%.
- PDD is the pick of the three, at about 7x forward earnings now that its ad business is growing faster again.
HHLR Advisors, part of Hillhouse, now has just over half of its US stock portfolio in three names: PDD Holdings (PDD), Alibaba (BABA) and Legend Biotech (LEGN). Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows $1.54 billion of US stocks across 40 positions, and it added to all three.
Two of the three reported their September quarters on Nov. 19, and the fund should like what it saw.
PDD’s ad business picked back up
PDD is the fund’s biggest holding: 4.45 million shares worth $347 million at Sept. 30, or 23% of its 13F. That’s 789% more shares than it held three months earlier, and the stock is up 10% since Sept. 30.
The Nov. 19 report had the number PDD investors most wanted to see. Online marketing revenue, PDD’s ad business, grew 12% from RMB53.3 billion a year earlier, after just 3% growth in the June quarter. GAAP net income attributable to shareholders was RMB29.5 billion, roughly flat against RMB29.3 billion a year earlier.
Analysts spent the year cutting their targets, though. The consensus price target fell by more than a quarter over the past year, all of it before the report:
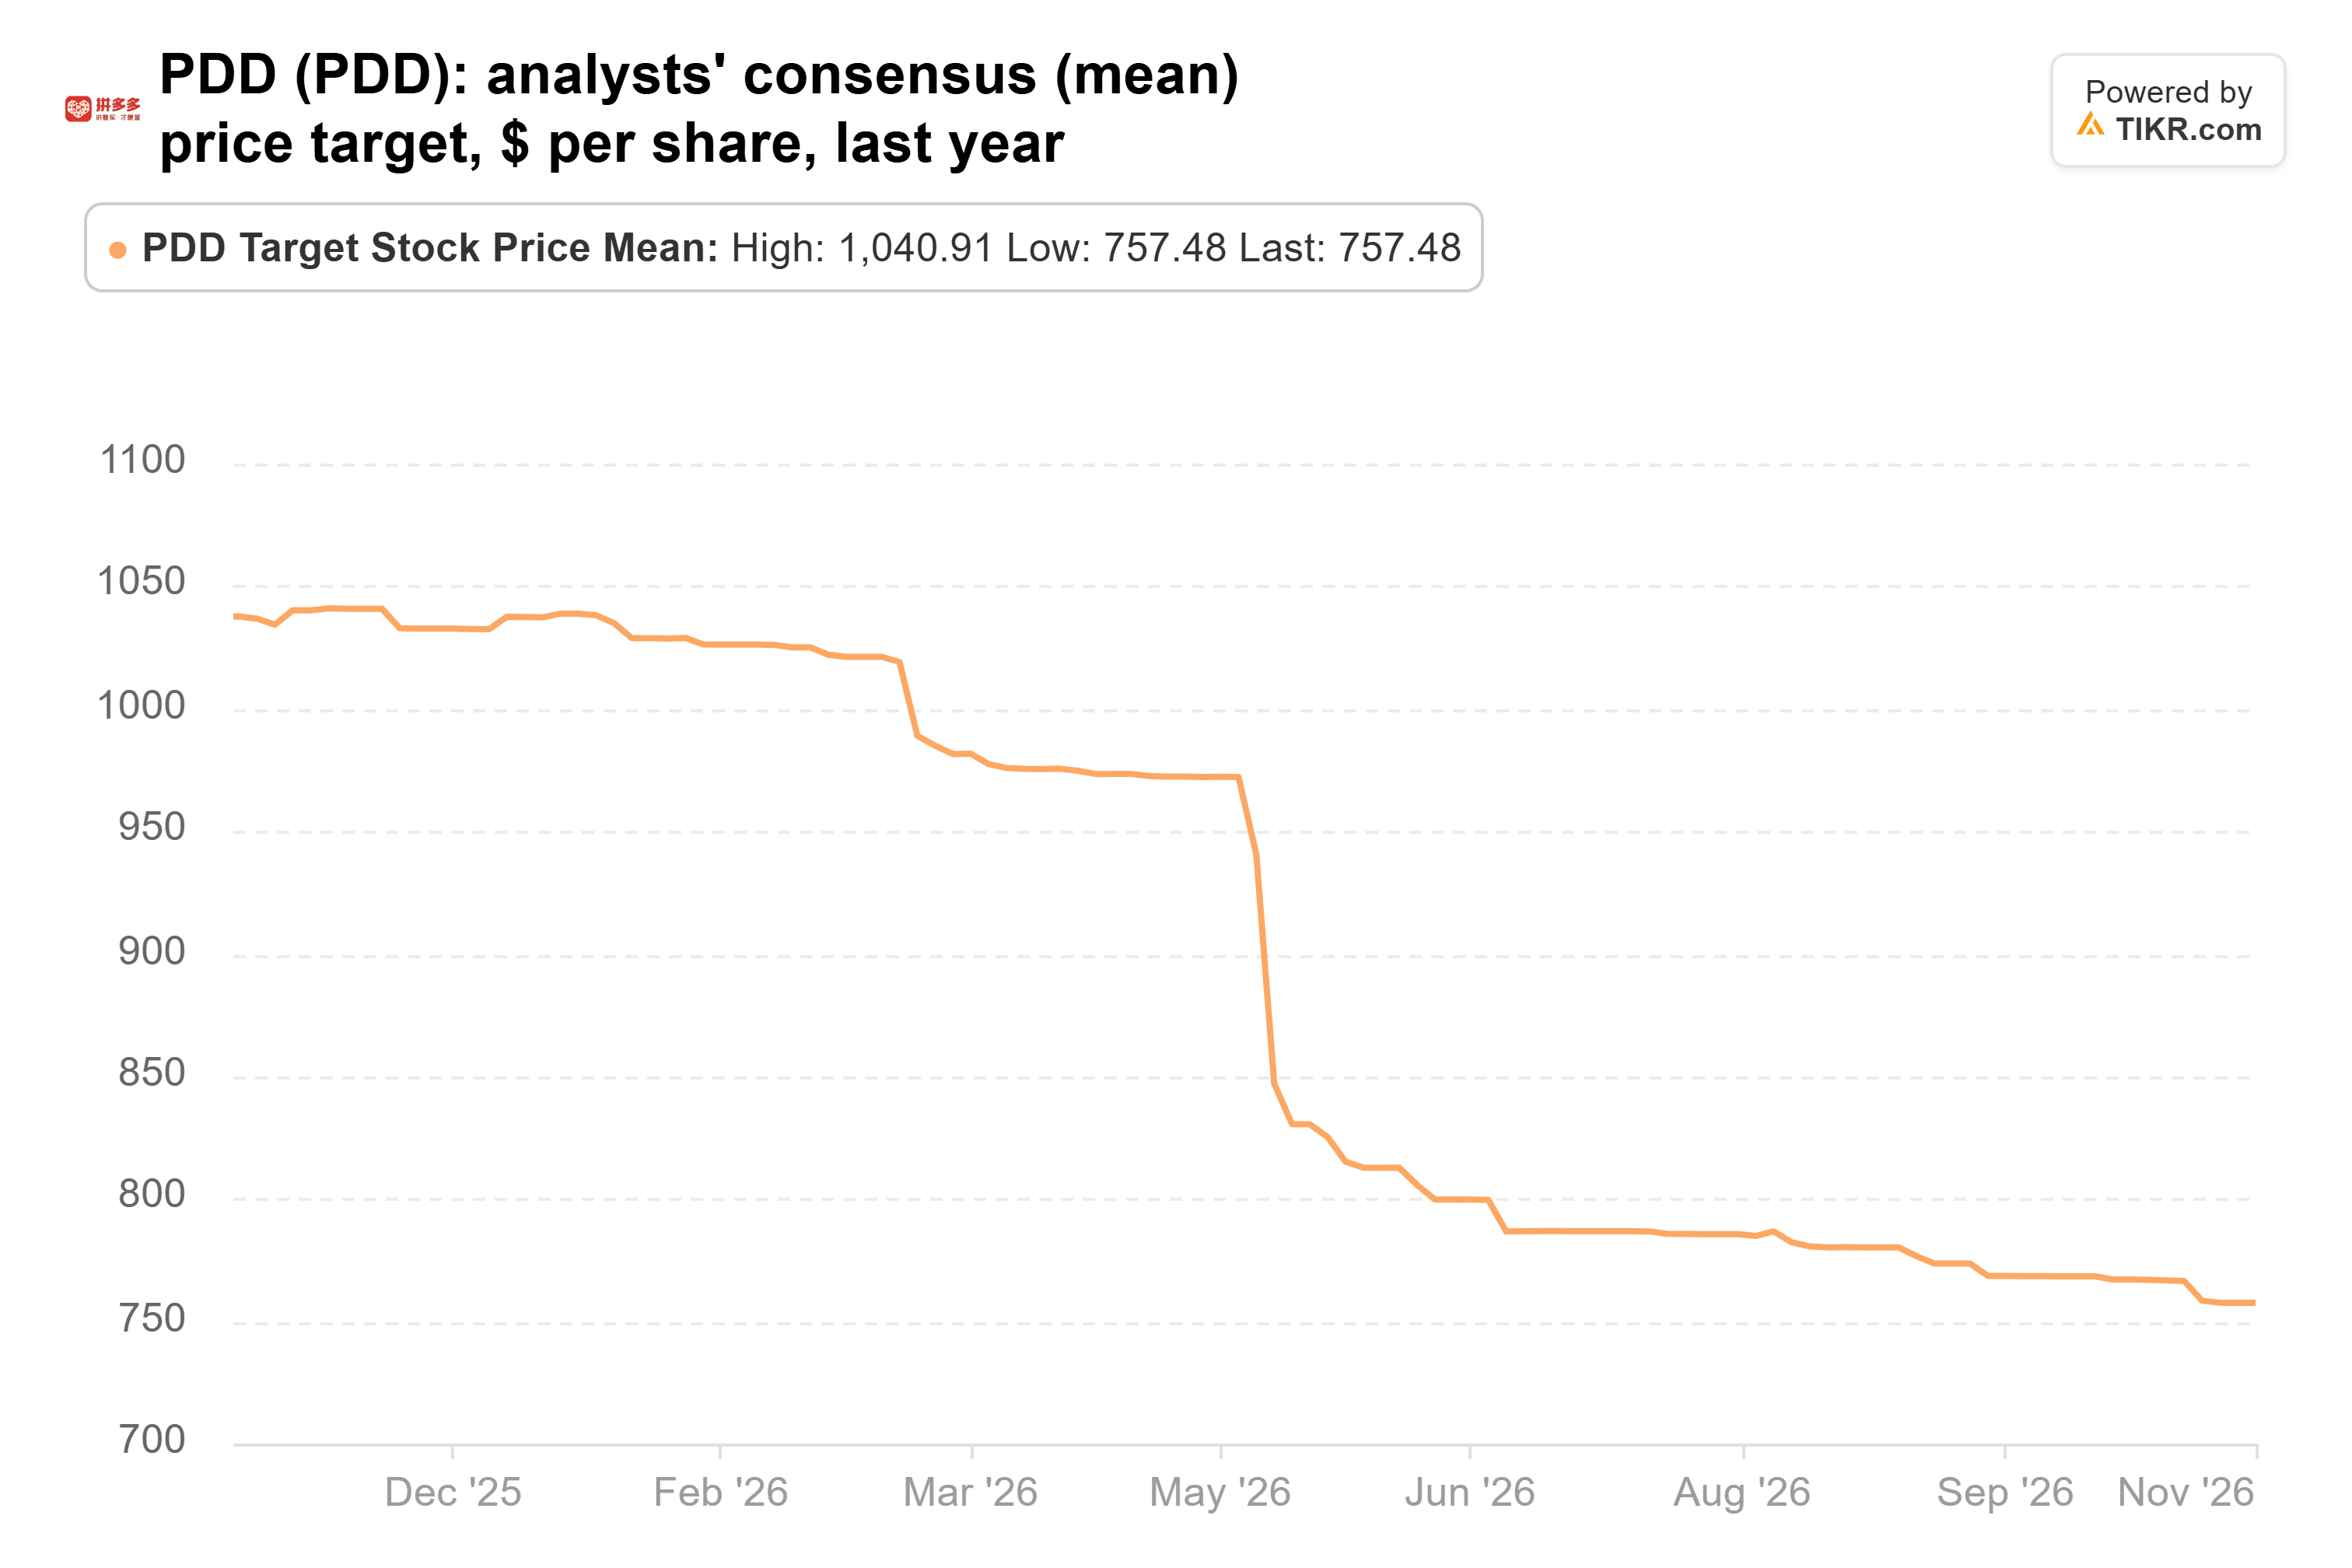
That average target is still 32% above the stock. And PDD trades at about 7x forward earnings, against an average near 11x over the past three years.
TIKR tracks 35 analysts on PDD Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PDD Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PDD Holdings’ Analyst Ratings
Alibaba’s cloud is booming. The stock isn’t
Alibaba is the fund’s No. 2 holding: 2.49 million shares worth $268 million, or 17.4% of its 13F, after its share count rose 1,254%. (The 13F shows only US-listed shares, so any Hong Kong-listed Alibaba stock the fund owns isn’t in it.) The fund wasn’t the only buyer: five funds bought or added to Alibaba’s US shares in the September quarter, Viking Global among them.
The stock has fallen 23% since Sept. 30, and it closed at a 52-week low the day Alibaba reported. That’s an odd reaction to the quarter. Cloud revenue grew 53% to RMB60.97 billion, recurring revenue from external cloud customers grew 67%, and adjusted EBITA rose 260% to RMB32.64 billion.
My read: investors are worried about the cash and the chips. Free cash flow fell from a year earlier, and Alibaba put that down to its spending on cloud infrastructure. And a Commerce Department rule issued Nov. 16 requires a license to ship advanced chips to data centers that sell large amounts of computing to Chinese companies. That rule targets the rented offshore Nvidia computing Alibaba’s cloud reportedly uses.
Analysts have trimmed their targets as well, and the consensus is down about 13% over the past year:
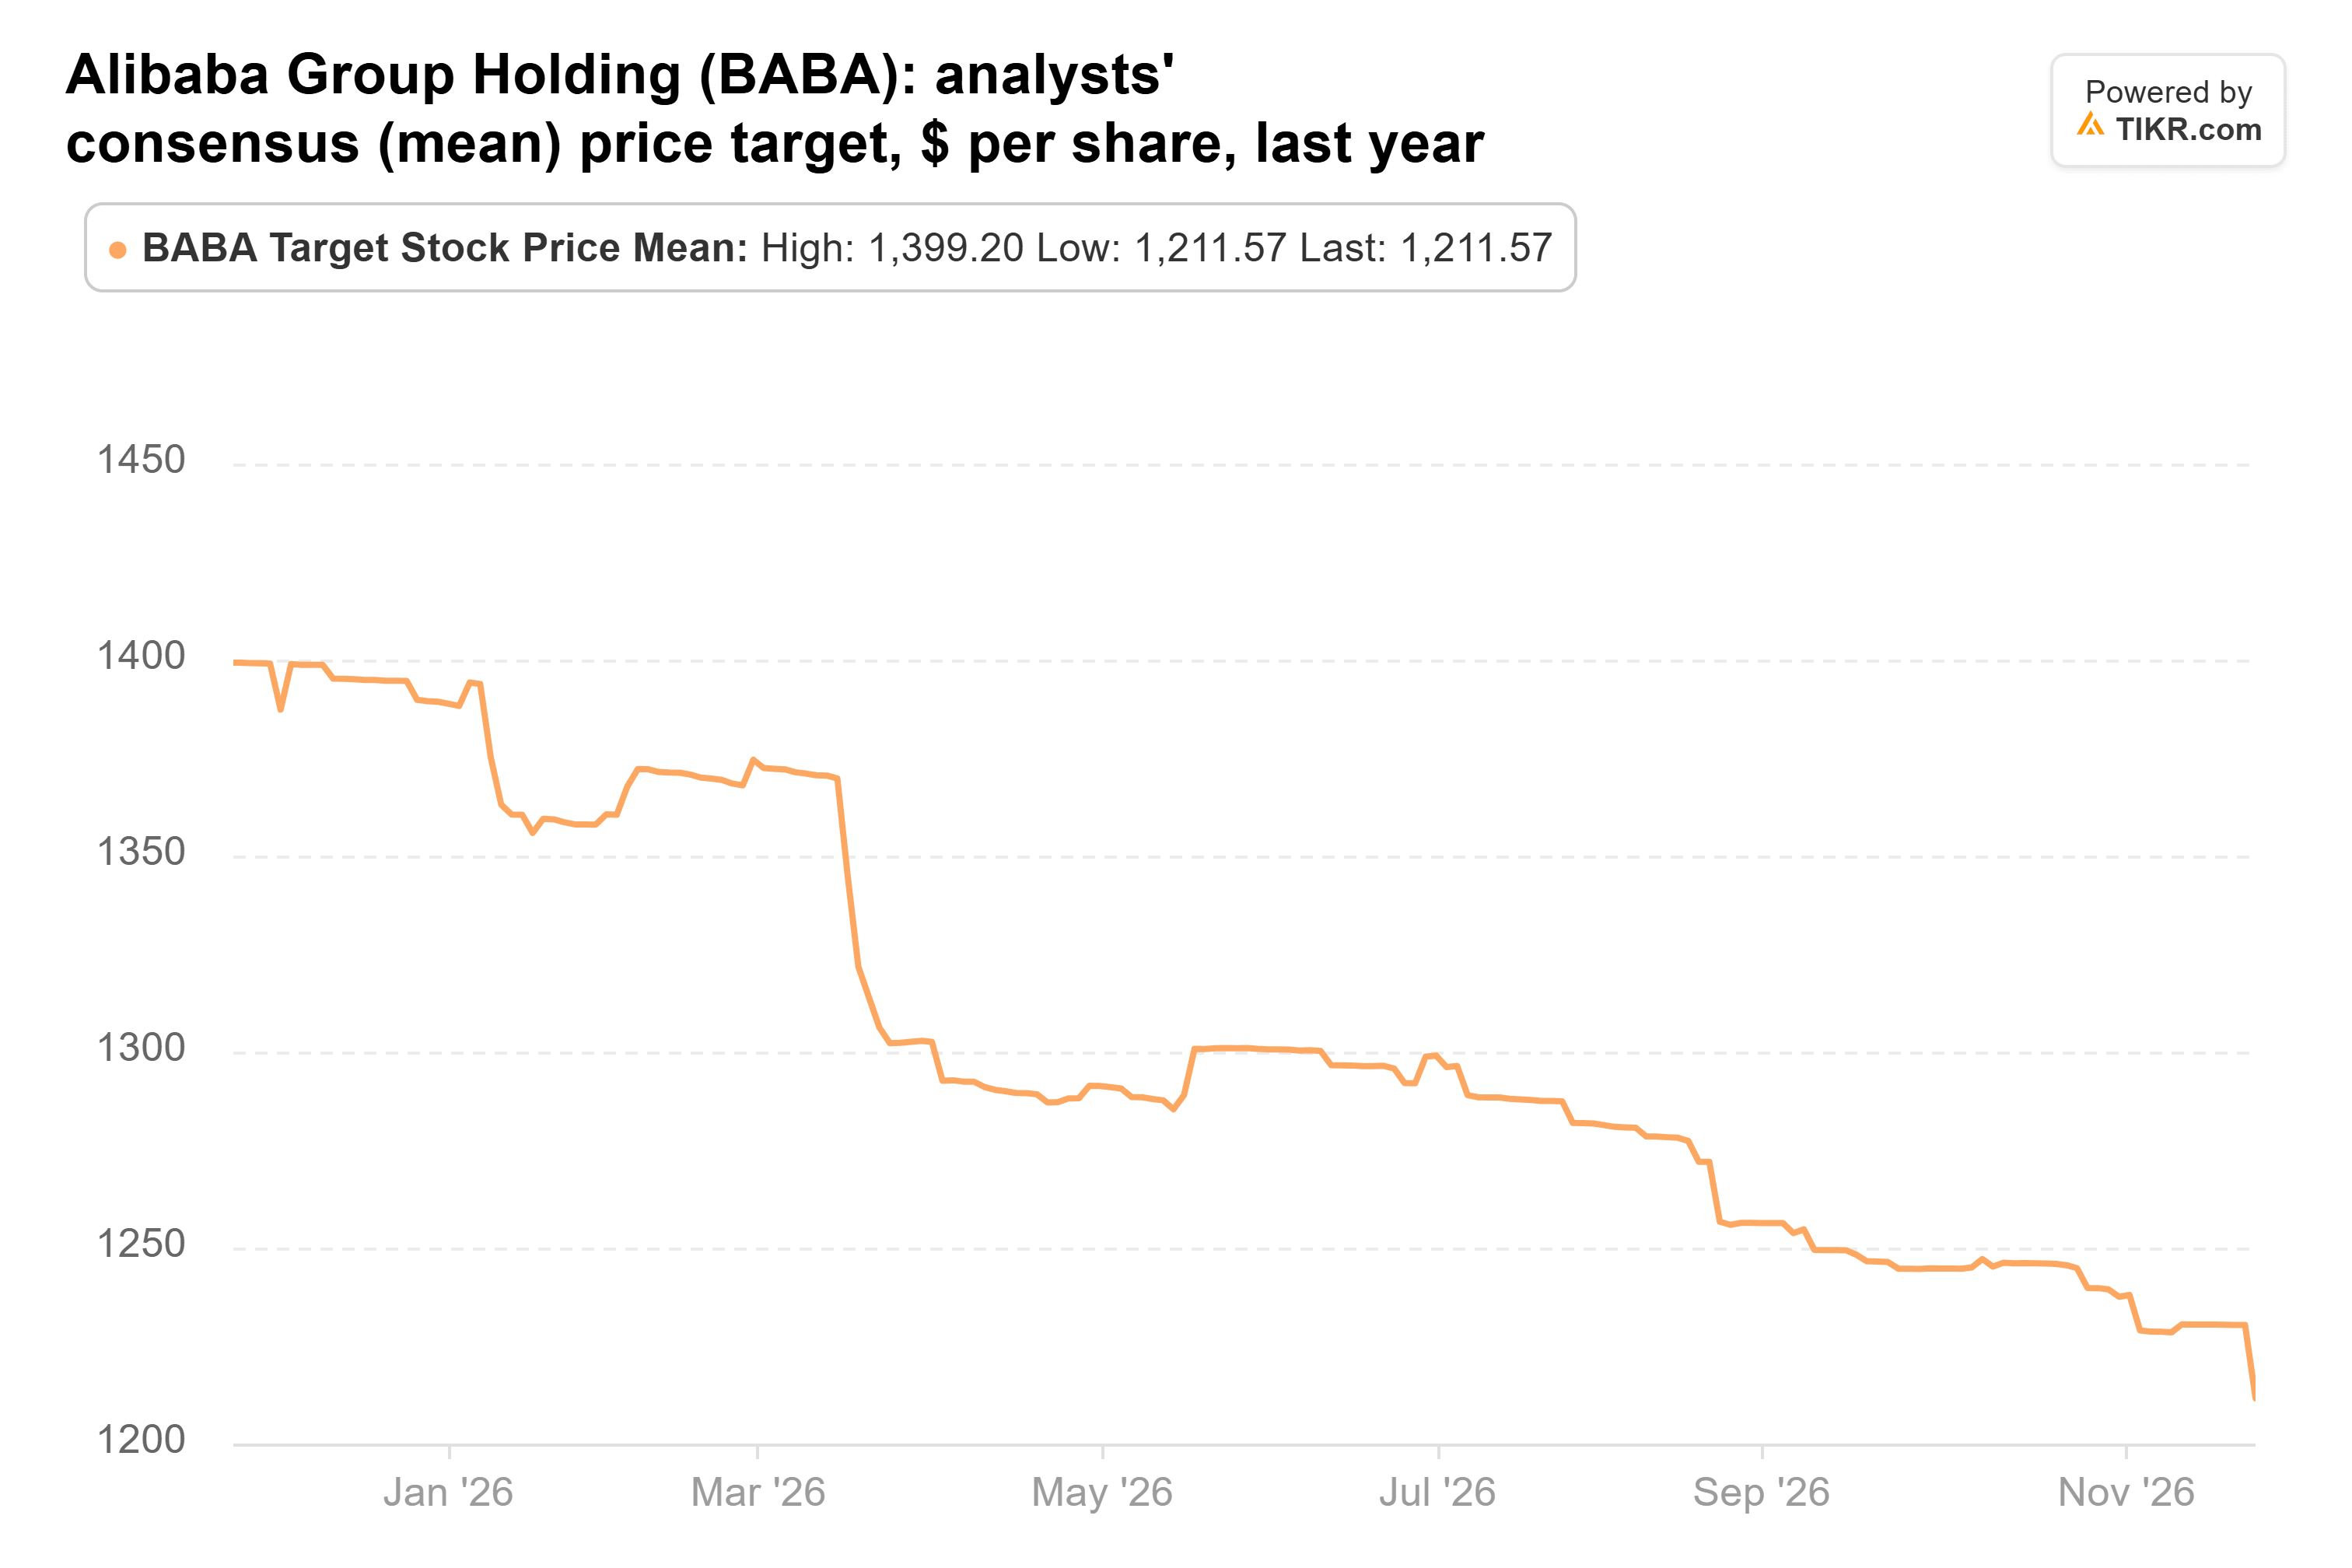
The average target of $173 is still 108% above the stock. Alibaba trades at about 10x forward earnings, below its five-year average of 12.6x.
Legend’s targets keep falling
The fund added less to Legend Biotech than to the other two. It raised its stake 40%, to 8.36 million shares worth $166 million, or 10.8% of its 13F. It had company here too: a $2 billion fund bought Legend Biotech as well.
The stock has fallen 19% since Sept. 30 and is 57% below its 52-week high. Analysts have followed it down. The consensus target has fallen 45% over the past year and hit its low on Nov. 13:
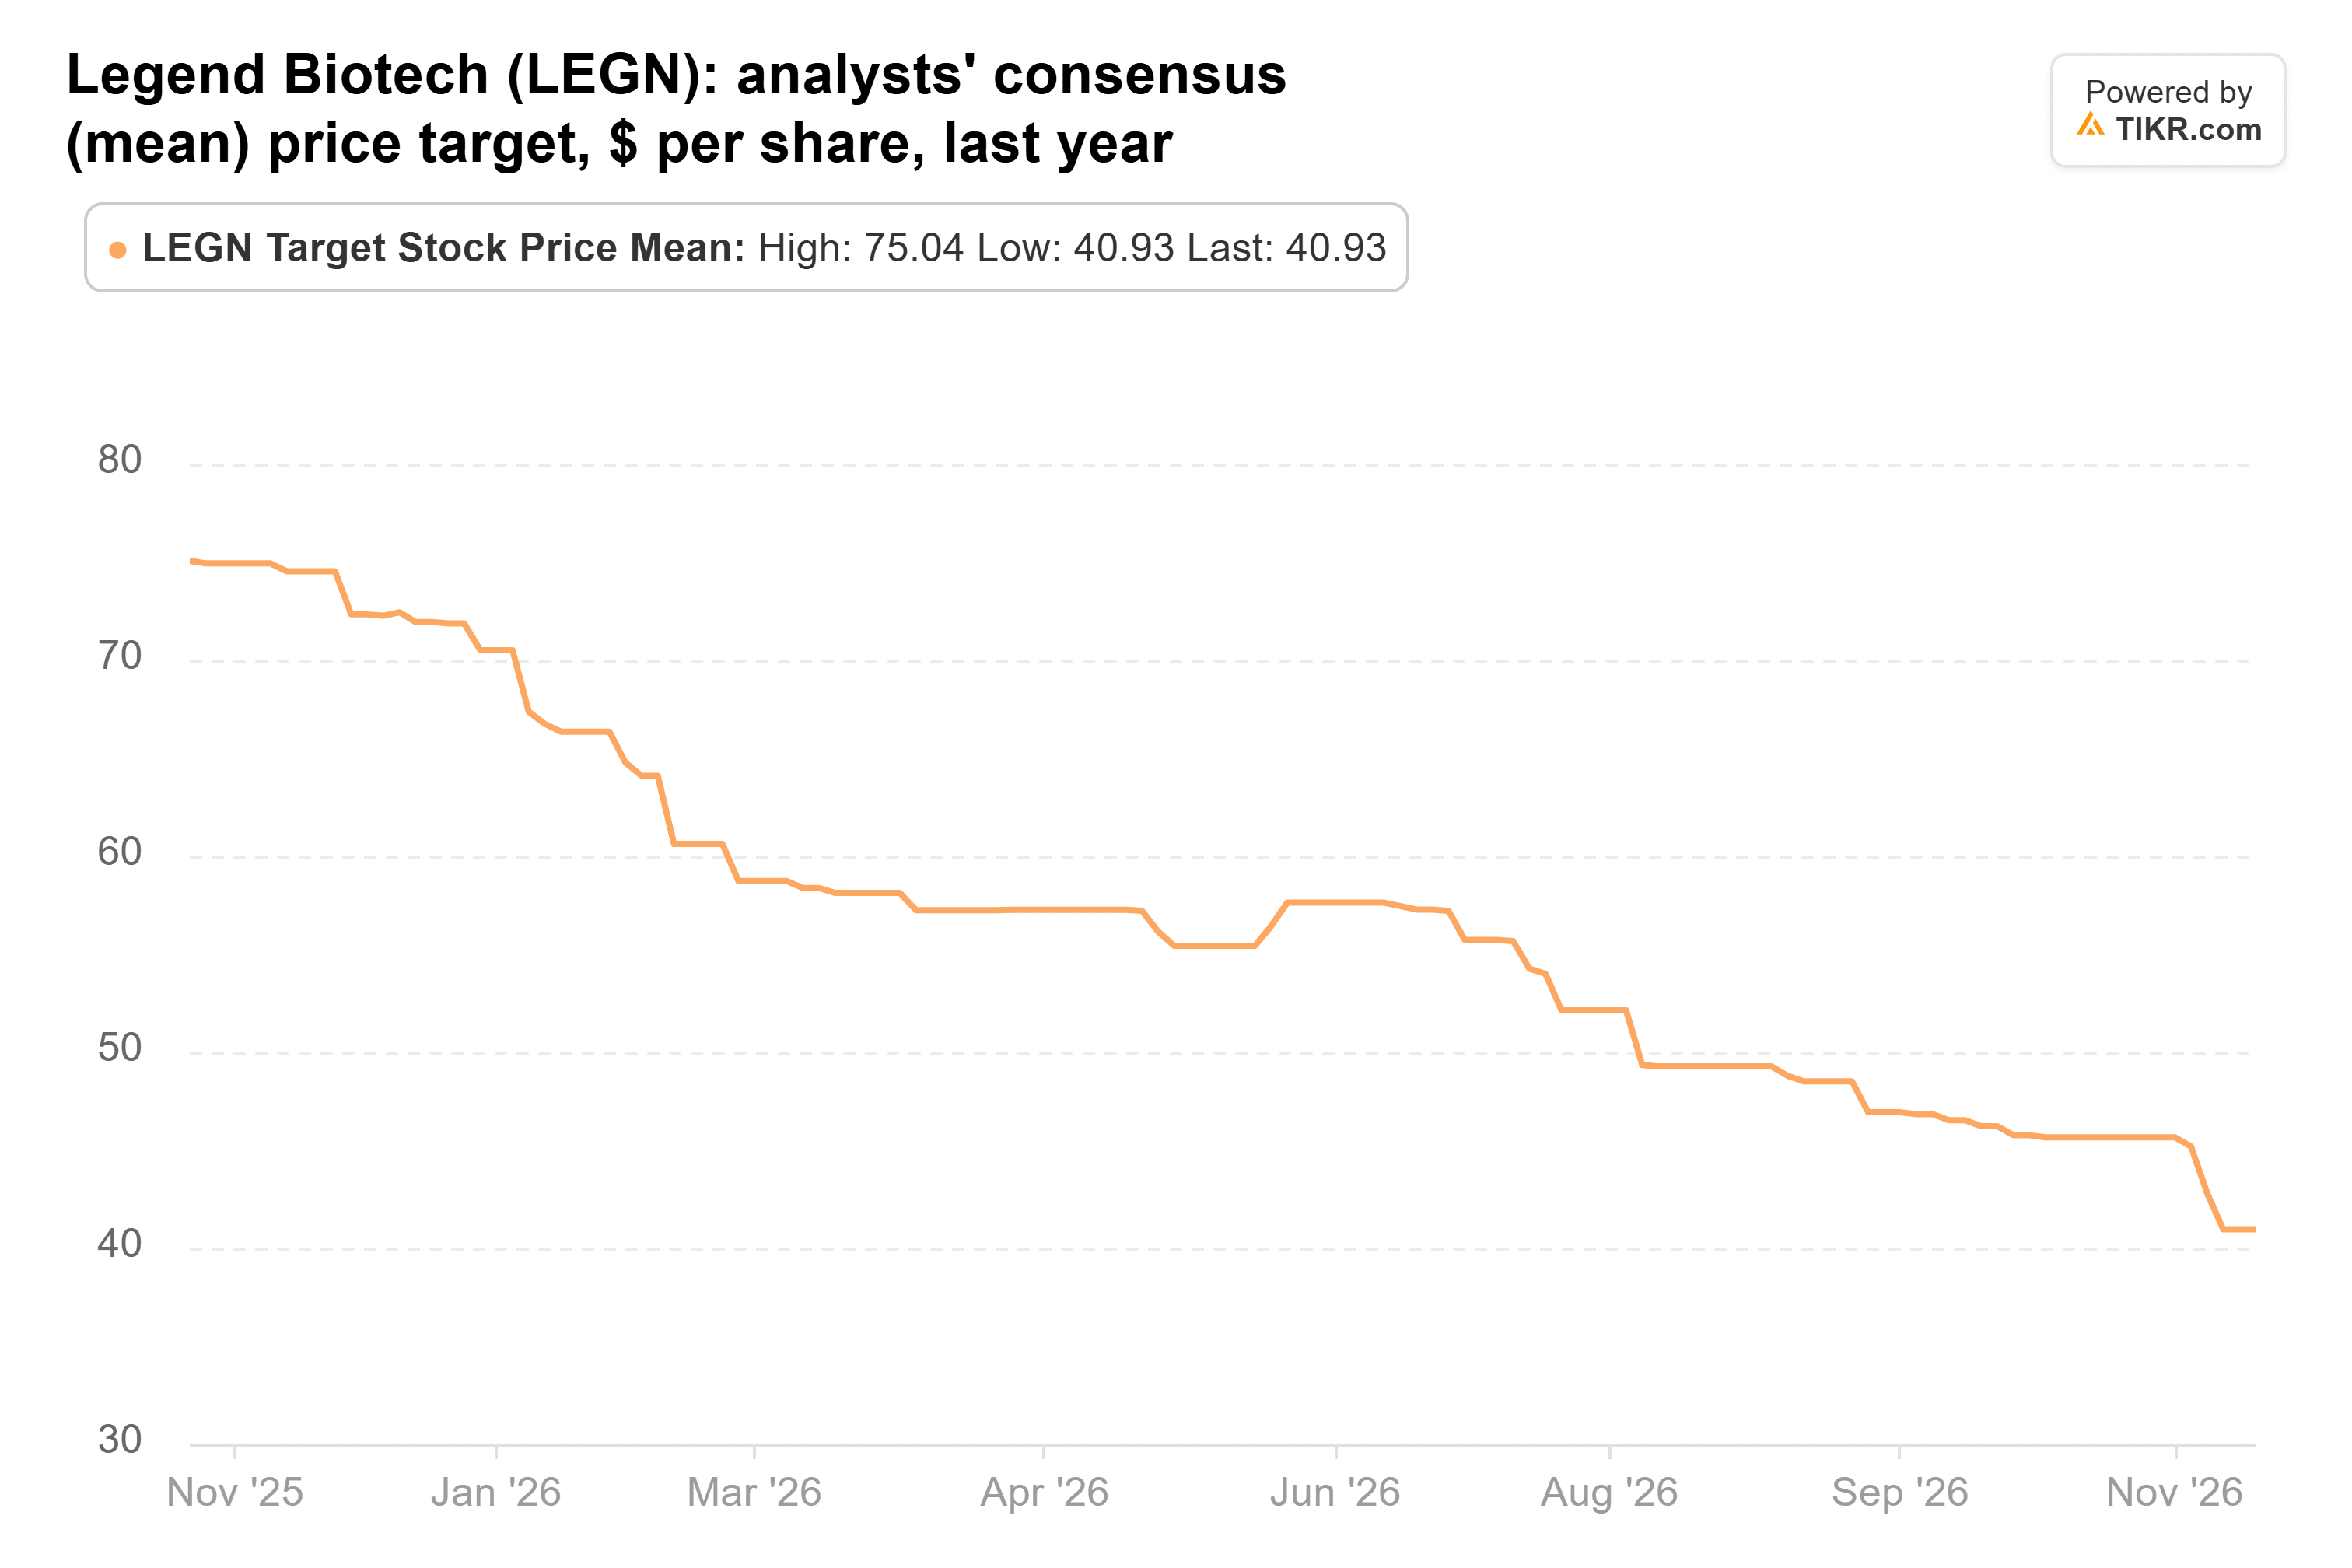
At $40.93, the average target from 14 analysts is still 154% above the stock. But Legend trades at about 31x forward earnings, and with its target nearly halved in a year, I’d want to see that slide stop before following the fund in.
PDD is the one I’d buy now
If I could only buy one of the three right now, it’d be PDD. Its ad business is growing again, and at about 7x forward earnings the stock prices in very little of that.
Alibaba is a close second. Its cloud is growing fast, and the stock’s slide leaves plenty of room if the spending pays off. But it’s spending heavily to get there, and the new chip rule could limit the computing capacity behind that growth.
PDD’s own risk is the cash it keeps: RMB456.4 billion of cash and short-term investments at June 30, with no dividend or buyback since its 2018 listing. Its fourth-quarter report, expected in March, will show whether ad growth holds near the September quarter’s 12%. And the fund’s next 13F, due by mid-February, will show whether it kept buying after the Nov. 19 reports.
So what is PDD stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PDD could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!