Key Takeaways
- PDD shares have fallen 39% over the past year to $83, leaving the stock at just 7.2x forward earnings.
- Second-quarter revenue rose 8% to RMB112.4 billion, but net income fell 12% as PDD “stepped up” ecosystem investments.
- Europe and the UK are tightening rules on cheap cross-border parcels and marketplace taxes, hitting Temu alongside Amazon.
- PDD is expected to report third-quarter results around November 24, which should show whether profit has stopped falling.
PDD Holdings (PDD) keeps getting cheaper while its cash pile keeps growing.
Shares closed at $83 on Friday, down 39% over the past year and far below their $139 52-week high. The company holds about $66 billion more cash than debt, roughly 56% of its market value.
Regulation explains much of the slide. Temu is in the crosshairs in Europe and the UK, and so is Amazon (AMZN): proposed EU fees on cheap parcels could raise €6 billion, and UK finance minister Healey plans to make online marketplaces collect tax from their sellers.
The other drag is self-inflicted. PDD is spending heavily on merchants, so profit is shrinking even as sales grow.
Sales up, profit down
The second quarter split growth from profit:
- Revenue rose 8% to RMB112.4 billion ($16.6 billion), slightly below estimates.
- Transaction services revenue grew 13% to RMB54.7 billion, while online marketing revenue rose about 3% to RMB57.6 billion.
- Net income attributable to shareholders fell 12% to RMB27.2 billion, though adjusted earnings of RMB19.33 per ADS beat forecasts.
Operating profit rose 8% to RMB27.8 billion. Much of the net income damage came from a loss below the operating line.
“We stepped up our ecosystem investments in the second quarter,” said Jun Liu, PDD’s VP of Finance.
Top-line growth has cooled a lot since 2024…
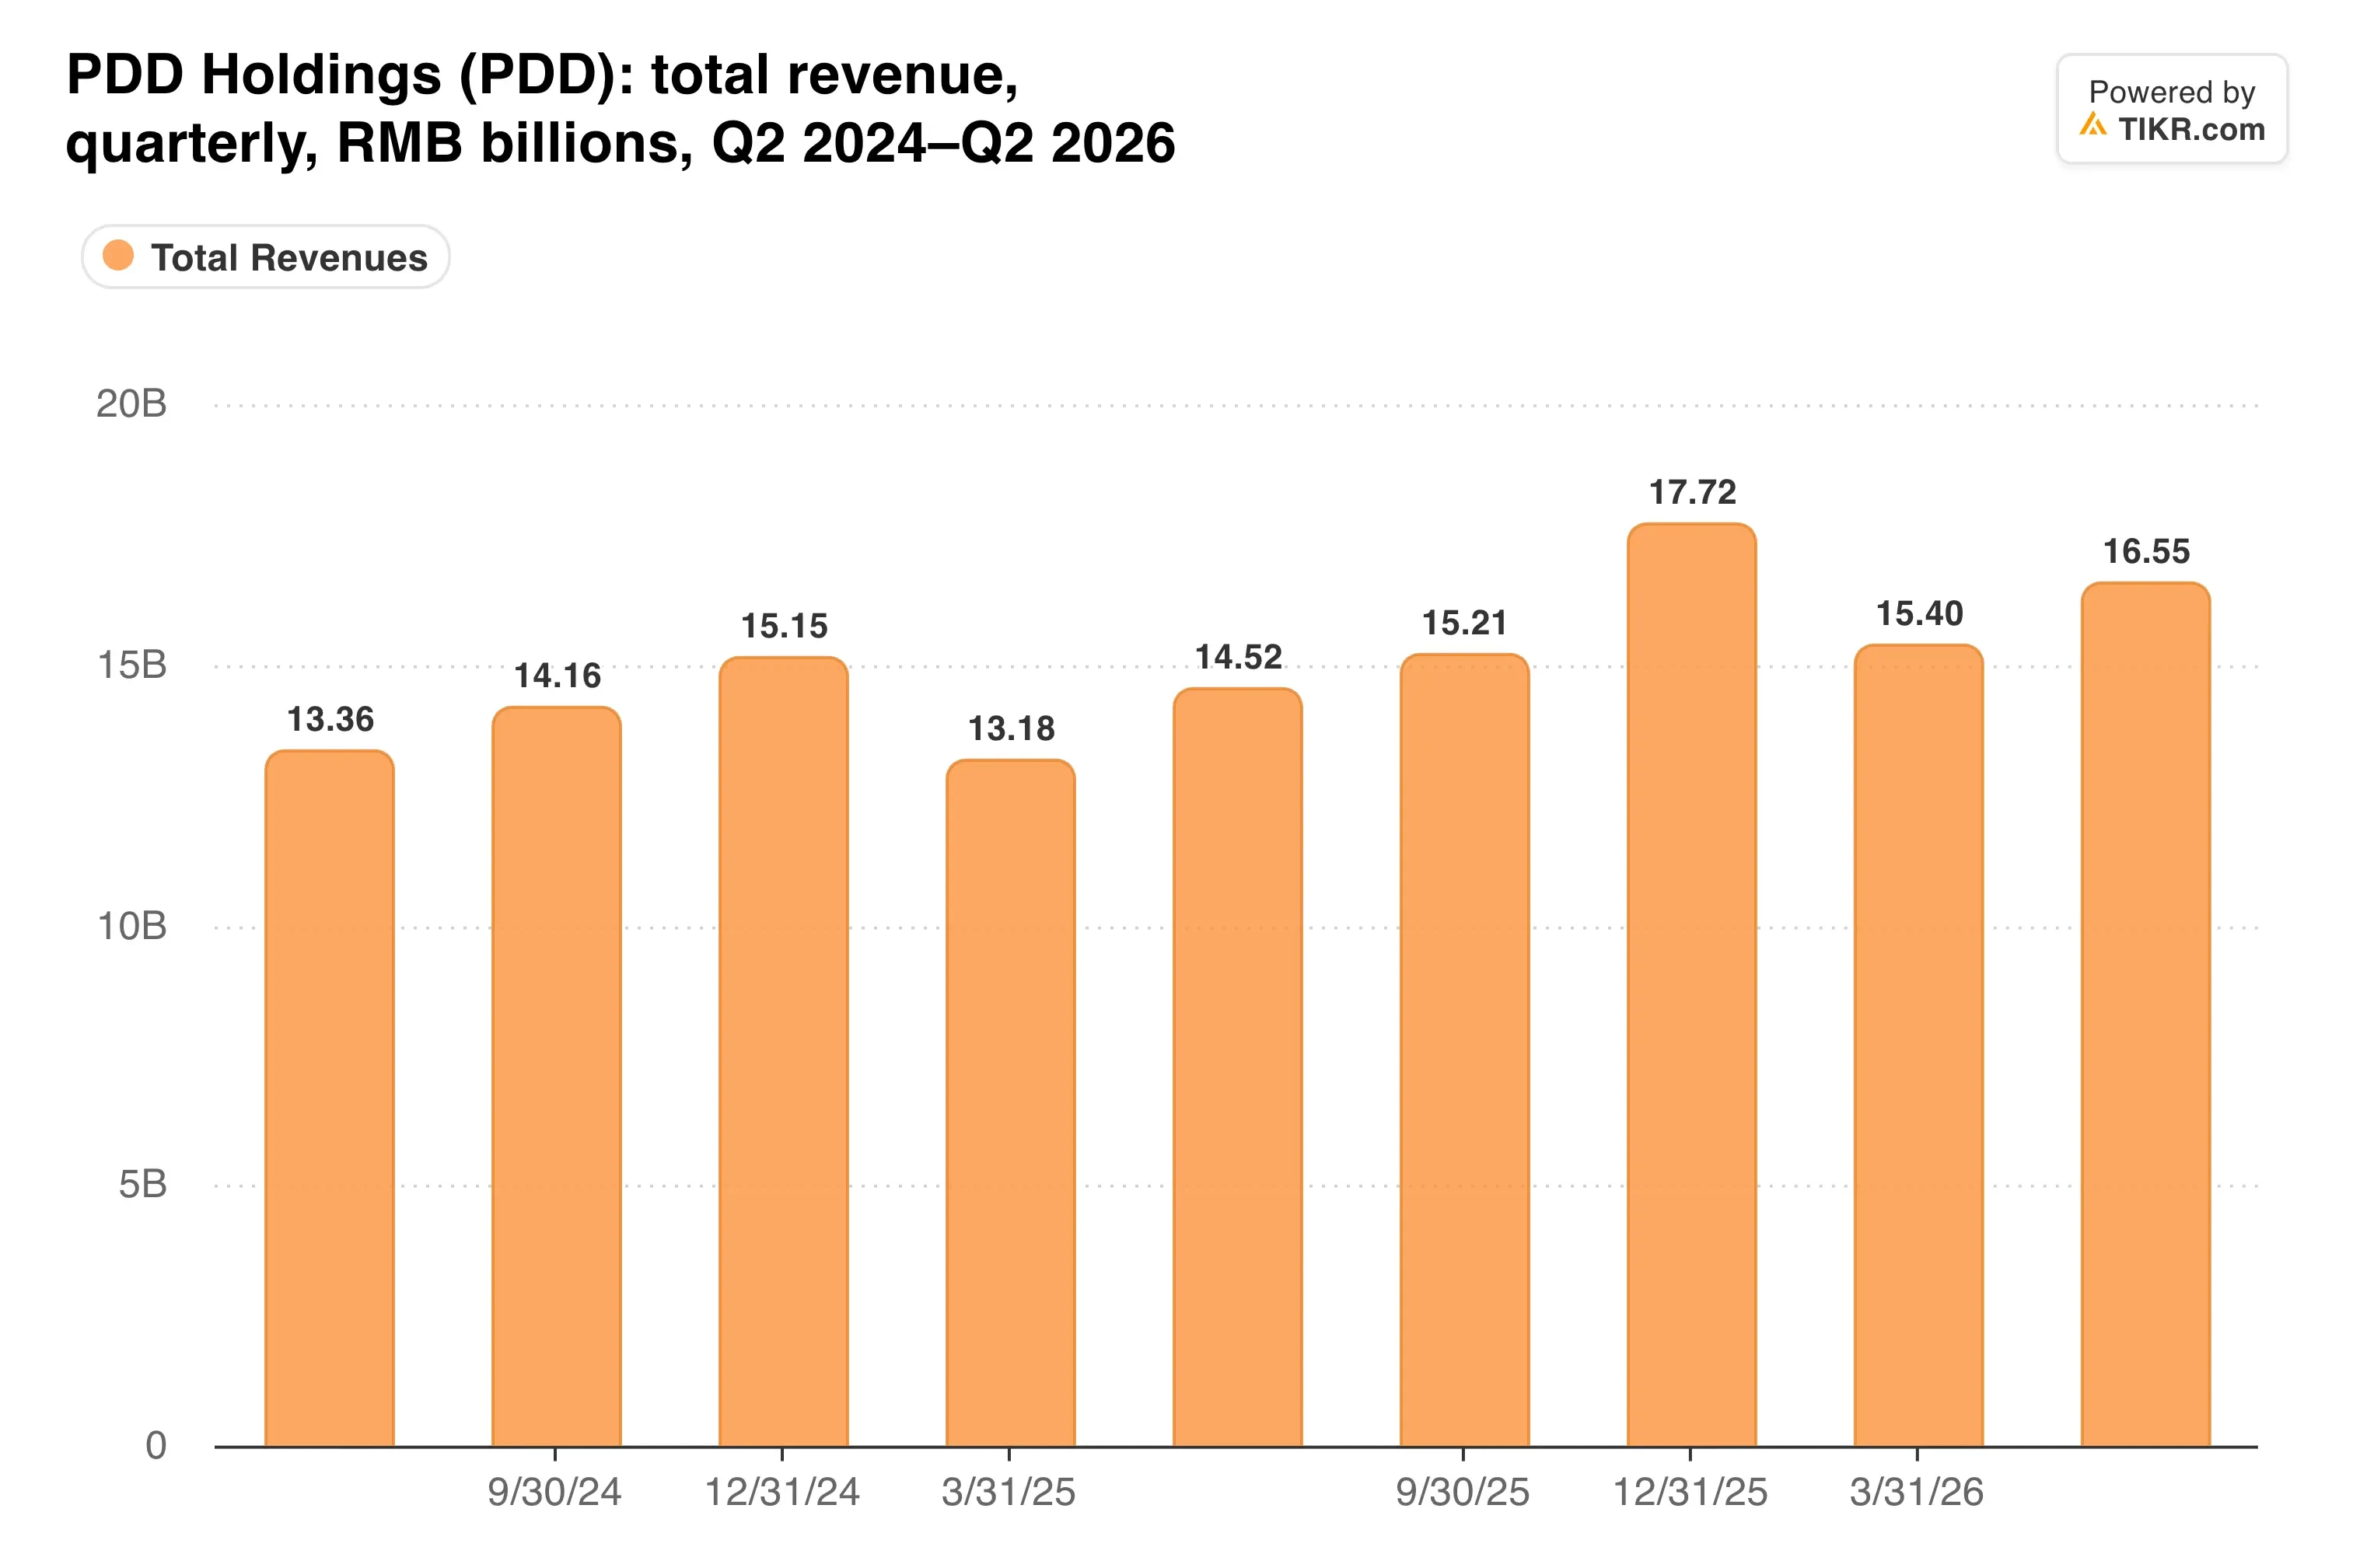
Growth slowed to 8% this quarter. That leaves transaction services doing most of the work, since online marketing barely grew.
Regulation is now a cost line
Cross-border pressure keeps building. In October, the EU accepted Temu’s plan to remedy a Digital Services Act breach, and Temu agreed to data privacy restrictions to settle a Texas lawsuit.
Co-Chairman Lei Chen acknowledged the shift in the earnings release, saying “global trade and regulatory landscapes have continued to evolve, creating significant challenges while also presenting new opportunities.”
The closest rival is feeling it too. Shein cut its Hong Kong IPO valuation to as much as $27 billion before a lackluster debut in September. PDD’s $118 billion market cap dwarfs that, but investors are discounting both for the same rules.
At home, Co-Chairman Zhao Jiazhen admitted the first-party brand push has been “slower than expected” in its first six months.
So who absorbs the cost? Look at profit…
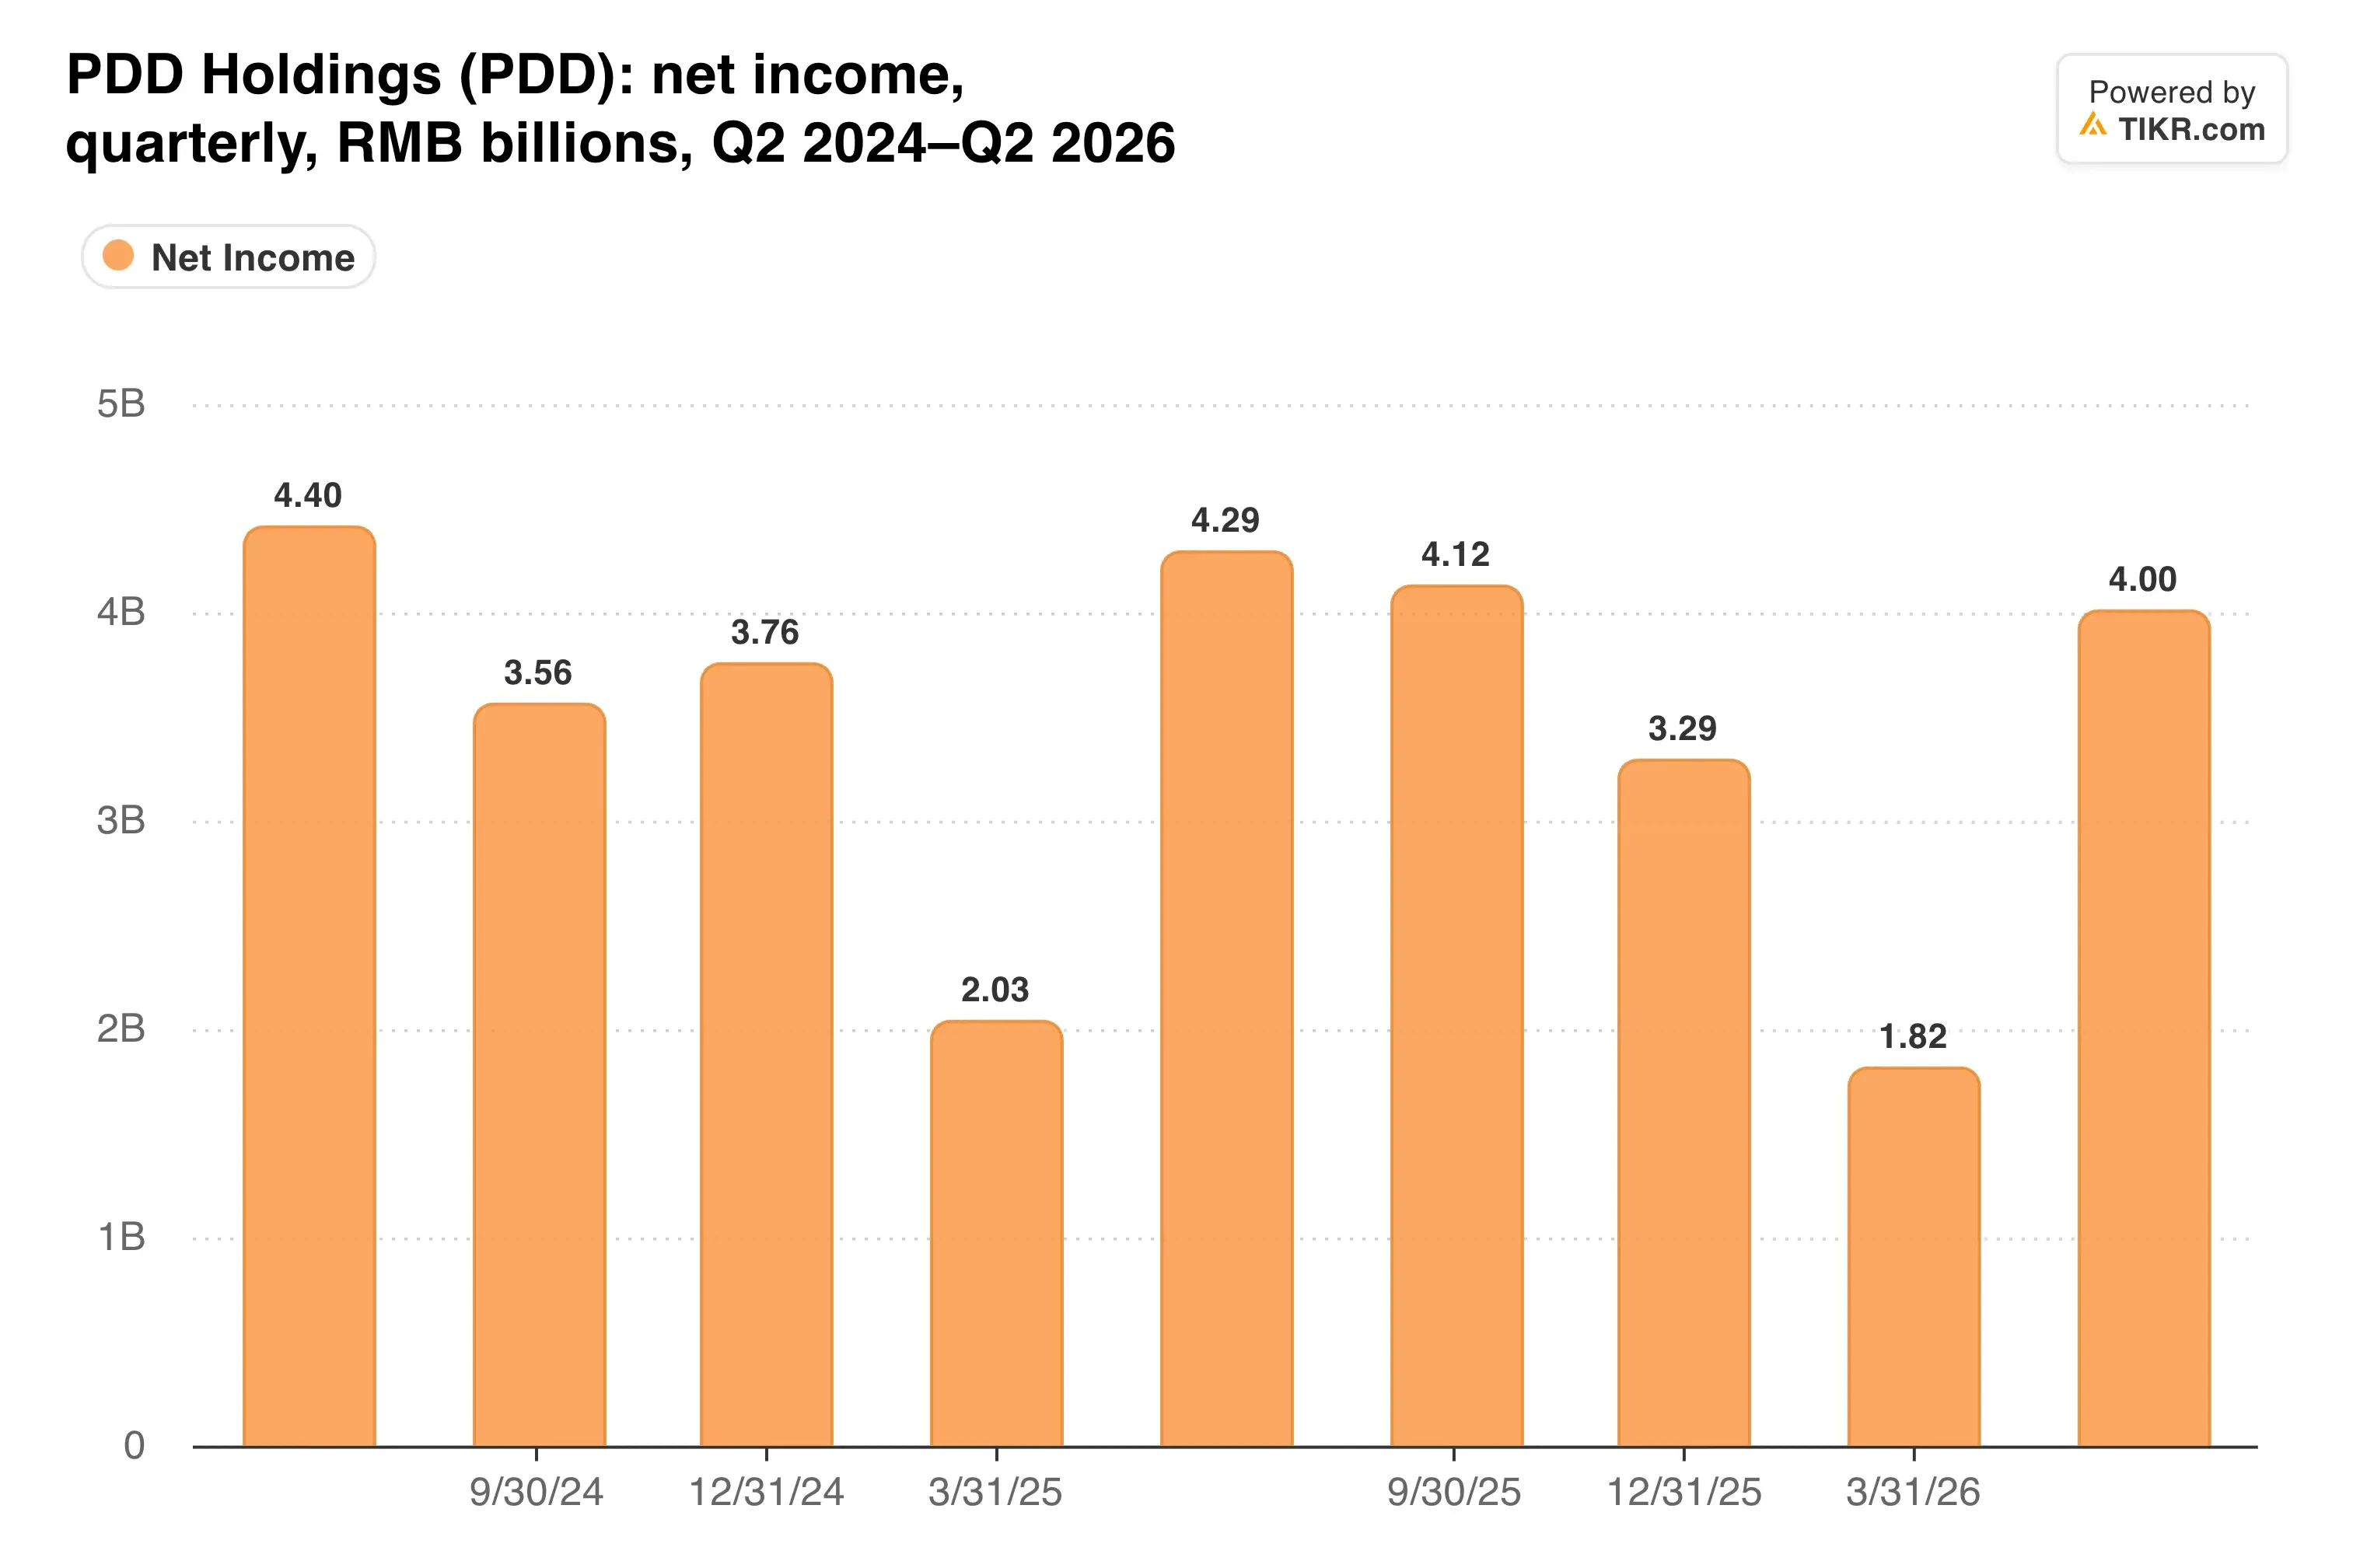
Net income has slipped from a year earlier, even as revenue kept rising.
TIKR tracks 37 analysts on PDD Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PDD Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PDD Holdings’ Analyst Ratings
Cheap, and holding the cash
PDD trades at 7.2x forward earnings and 2.9x forward EV/EBITDA. Take out the net cash and the market values the operating business at about $52 billion.
Operating cash flow rose 19% to RMB25.7 billion in the quarter, and cash and short-term investments reached RMB456.4 billion. Wall Street’s average target of $115 implies 38% upside.
Here’s how far the multiple has compressed.
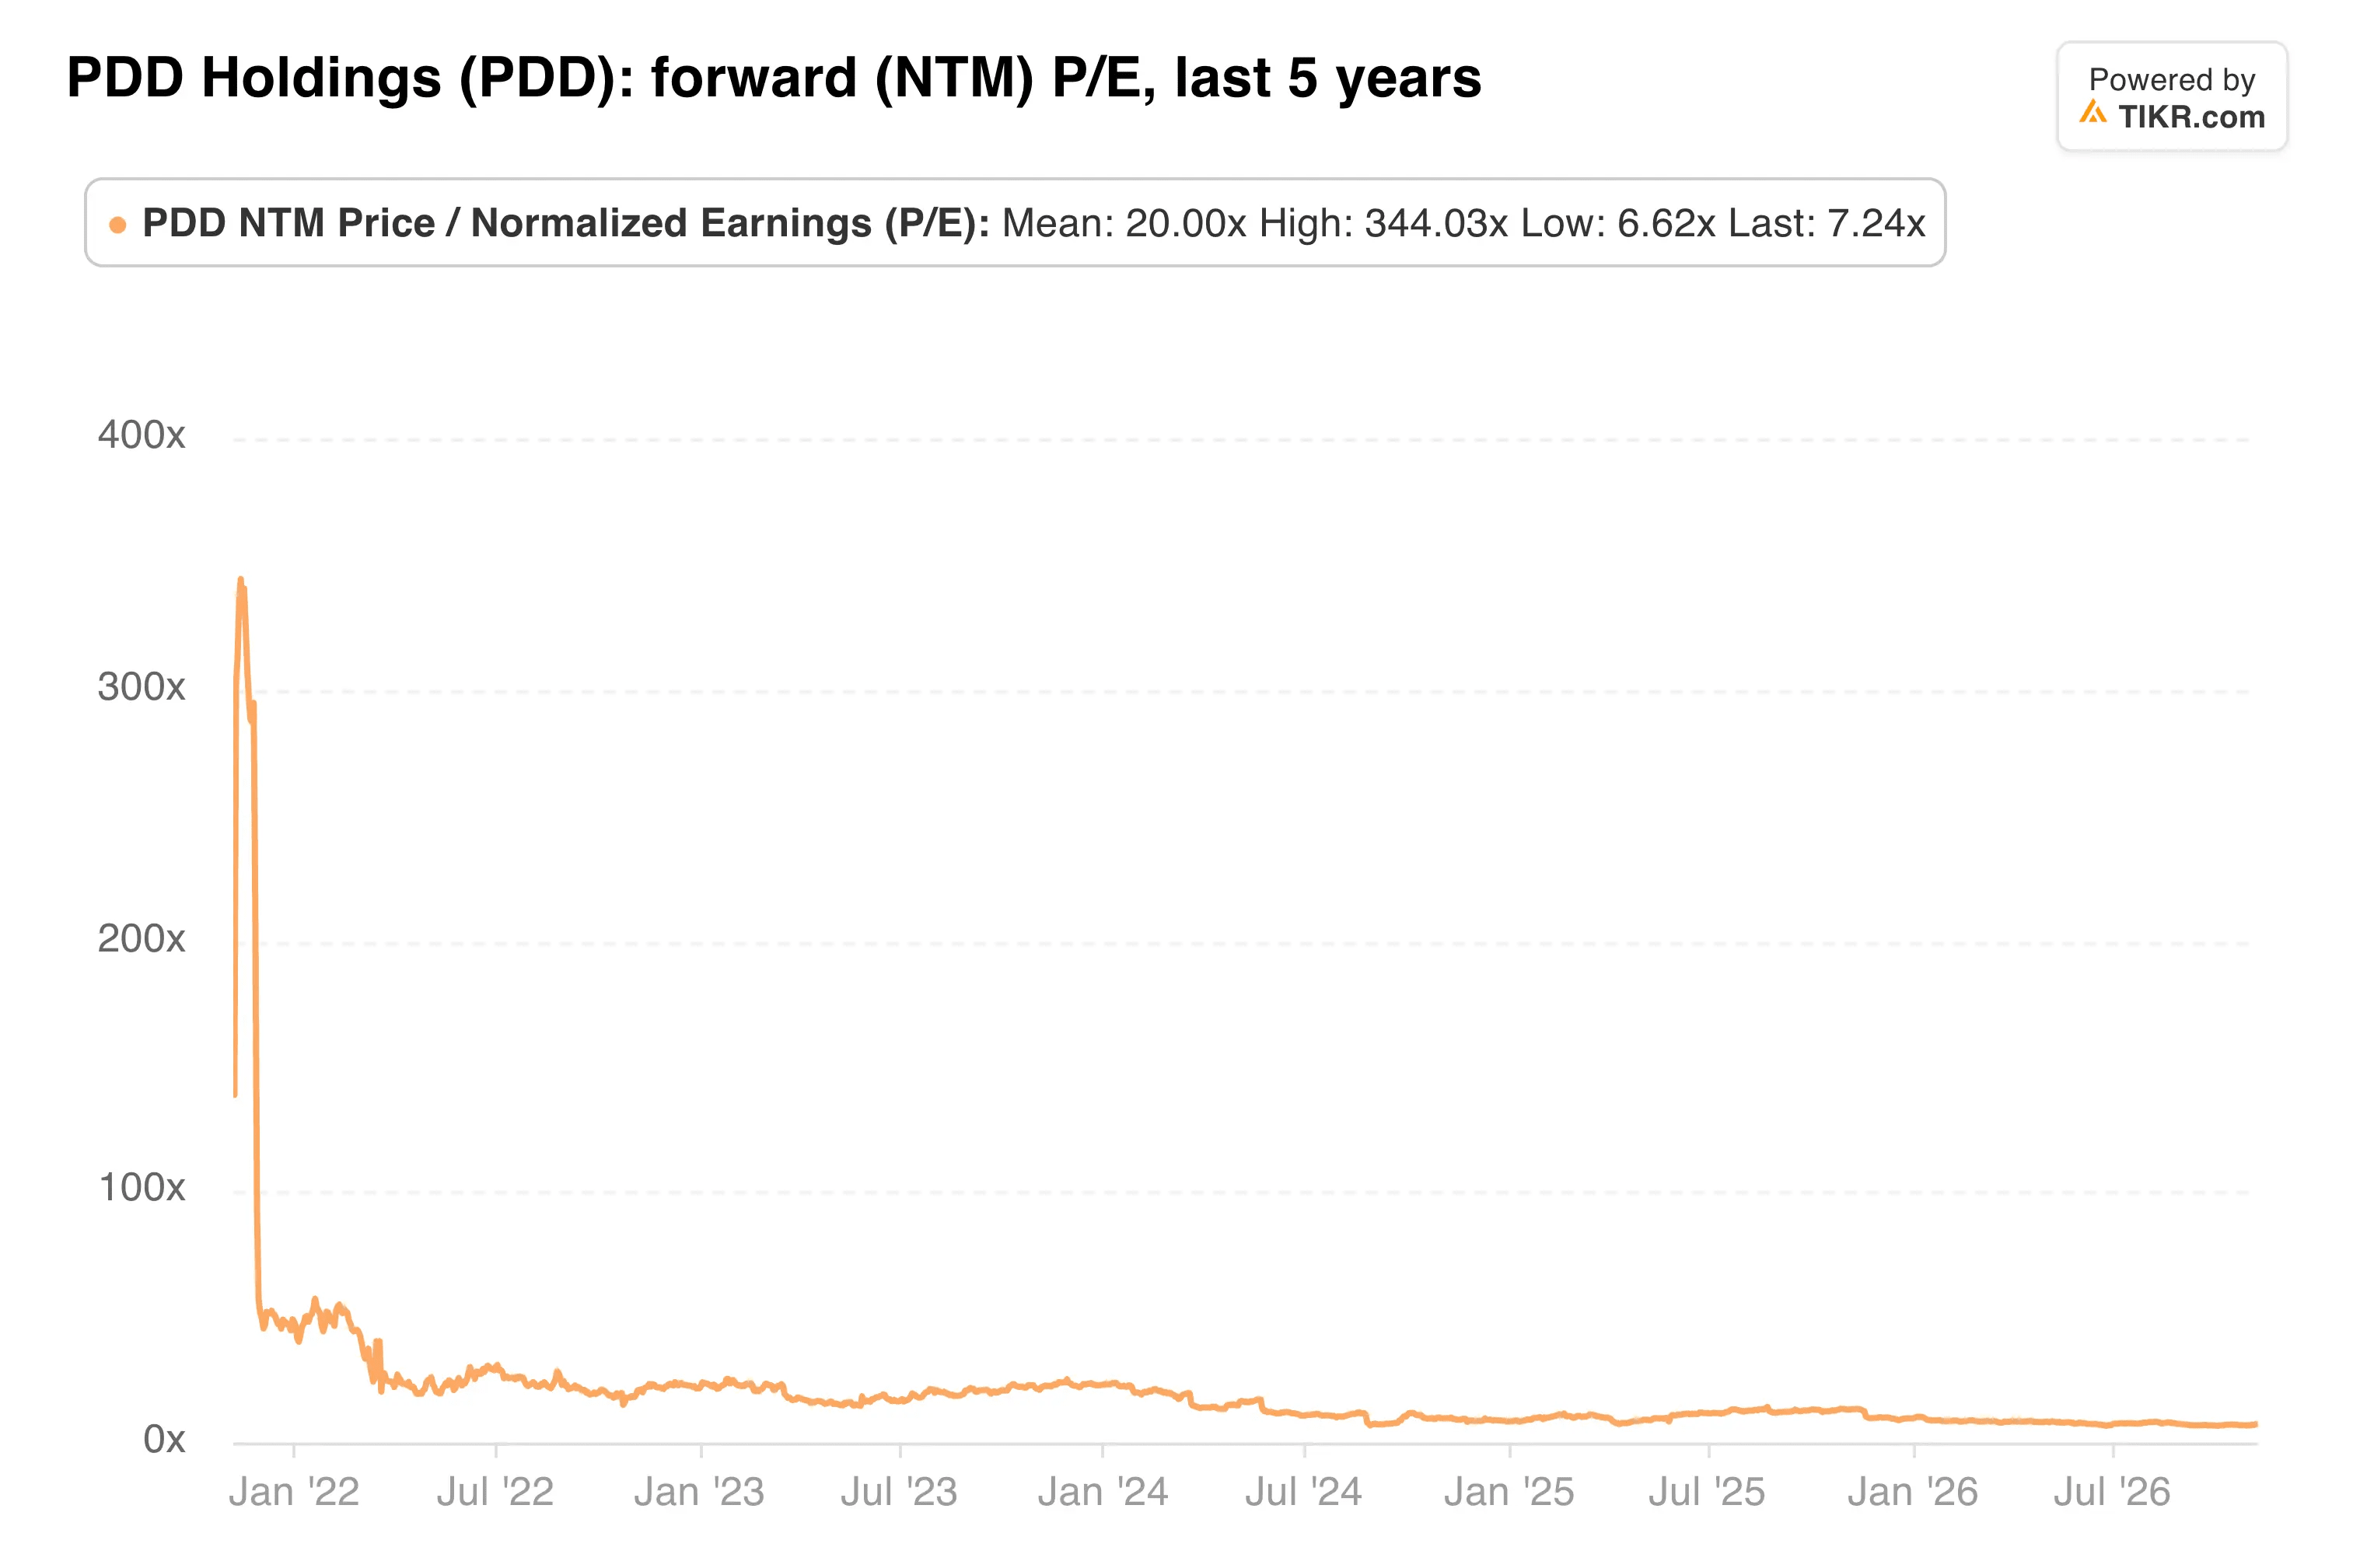
Part of that discount is about capital returns, because PDD pays no dividend.
My take: The valuation is hard to argue with, and the cash gives PDD years of runway. But management keeps choosing merchant spending over profit and returns none of that cash, so the discount could last. I’d want proof that net income has bottomed before buying.
PDD is expected to report third-quarter results around November 24. Watch whether net income stabilizes and what management says about EU parcel costs.
So what is PDD Holdings stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PDD Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!