Key Takeaways
- Energy Transfer yields 7.3% and J.M. Smucker yields 3.4%, and both declared their latest quarterly payouts on Oct. 22.
- Smucker’s dividend uses 29% of its free cash flow over the last twelve months and 40% on next year’s estimates. Energy Transfer’s distributable cash flow covers its payout 1.8x, and 2.2x on 2026 estimates.
- At each dividend’s current pace, $10,000 in Energy Transfer would pay about $23,356 over 20 years, compared with about $8,140 from Smucker.
- Smucker has raised its dividend for 25 fiscal years in a row. Energy Transfer cut its distribution in 2020 and plans about $7 billion of growth spending in 2027.
Energy Transfer (ET) raised its quarterly distribution for the 20th straight time on Oct. 22, to $0.3425 a unit. The same day, J.M. Smucker (SJM) declared its next quarterly dividend of $1.12 a share, up from $1.10.
Energy Transfer yields 7.3%. Smucker yields 3.4% and has 25 straight years of raises behind it. Over the next 20 years, which one deserves the money?
| Metric | J.M. Smucker (SJM) | Energy Transfer (ET) |
|---|---|---|
| Dividend yield | 3.4% | 7.3% |
| Dividend growth, 5 years | 4.1% a year (fiscal 2021-2026) | 7.8% a year (fiscal 2020-2025) |
| Record (company’s own count) | 25 straight fiscal years of raises | 20 straight quarterly increases |
| Coverage, last reported | Cash dividend payout ratio: 29% (TTM to July 31, 2026) | Distributable cash flow coverage: 1.78x (fiscal 2025) |
| Coverage, forward | Cash dividend payout ratio: 40% (fiscal 2027 consensus) | Distributable cash flow coverage: 2.15x (fiscal 2026 consensus) |
| Net debt/EBITDA (LTM) | 2.91x | 3.83x |
| Interest coverage (EBIT/interest, LTM) | 4.68x | 3.13x |
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Smucker’s dividend has room to spare
Smucker’s net sales rose 5% to $2.2 billion in the first quarter of fiscal 2027, the three months to July 31, 2026, as Uncrustables sandwiches grew volume by double digits and Café Bustelo’s net sales jumped 23%. For the full year, management expects net sales to slip 1% to 2%.
The dividend has a big cushion against that slowdown. Over the twelve months to July 31, it took a comfortable 29% of free cash flow. On fiscal 2027 consensus, the ratio rises to a still well-covered 40%. Free cash flow has covered the dividend in every one of the last ten fiscal years:
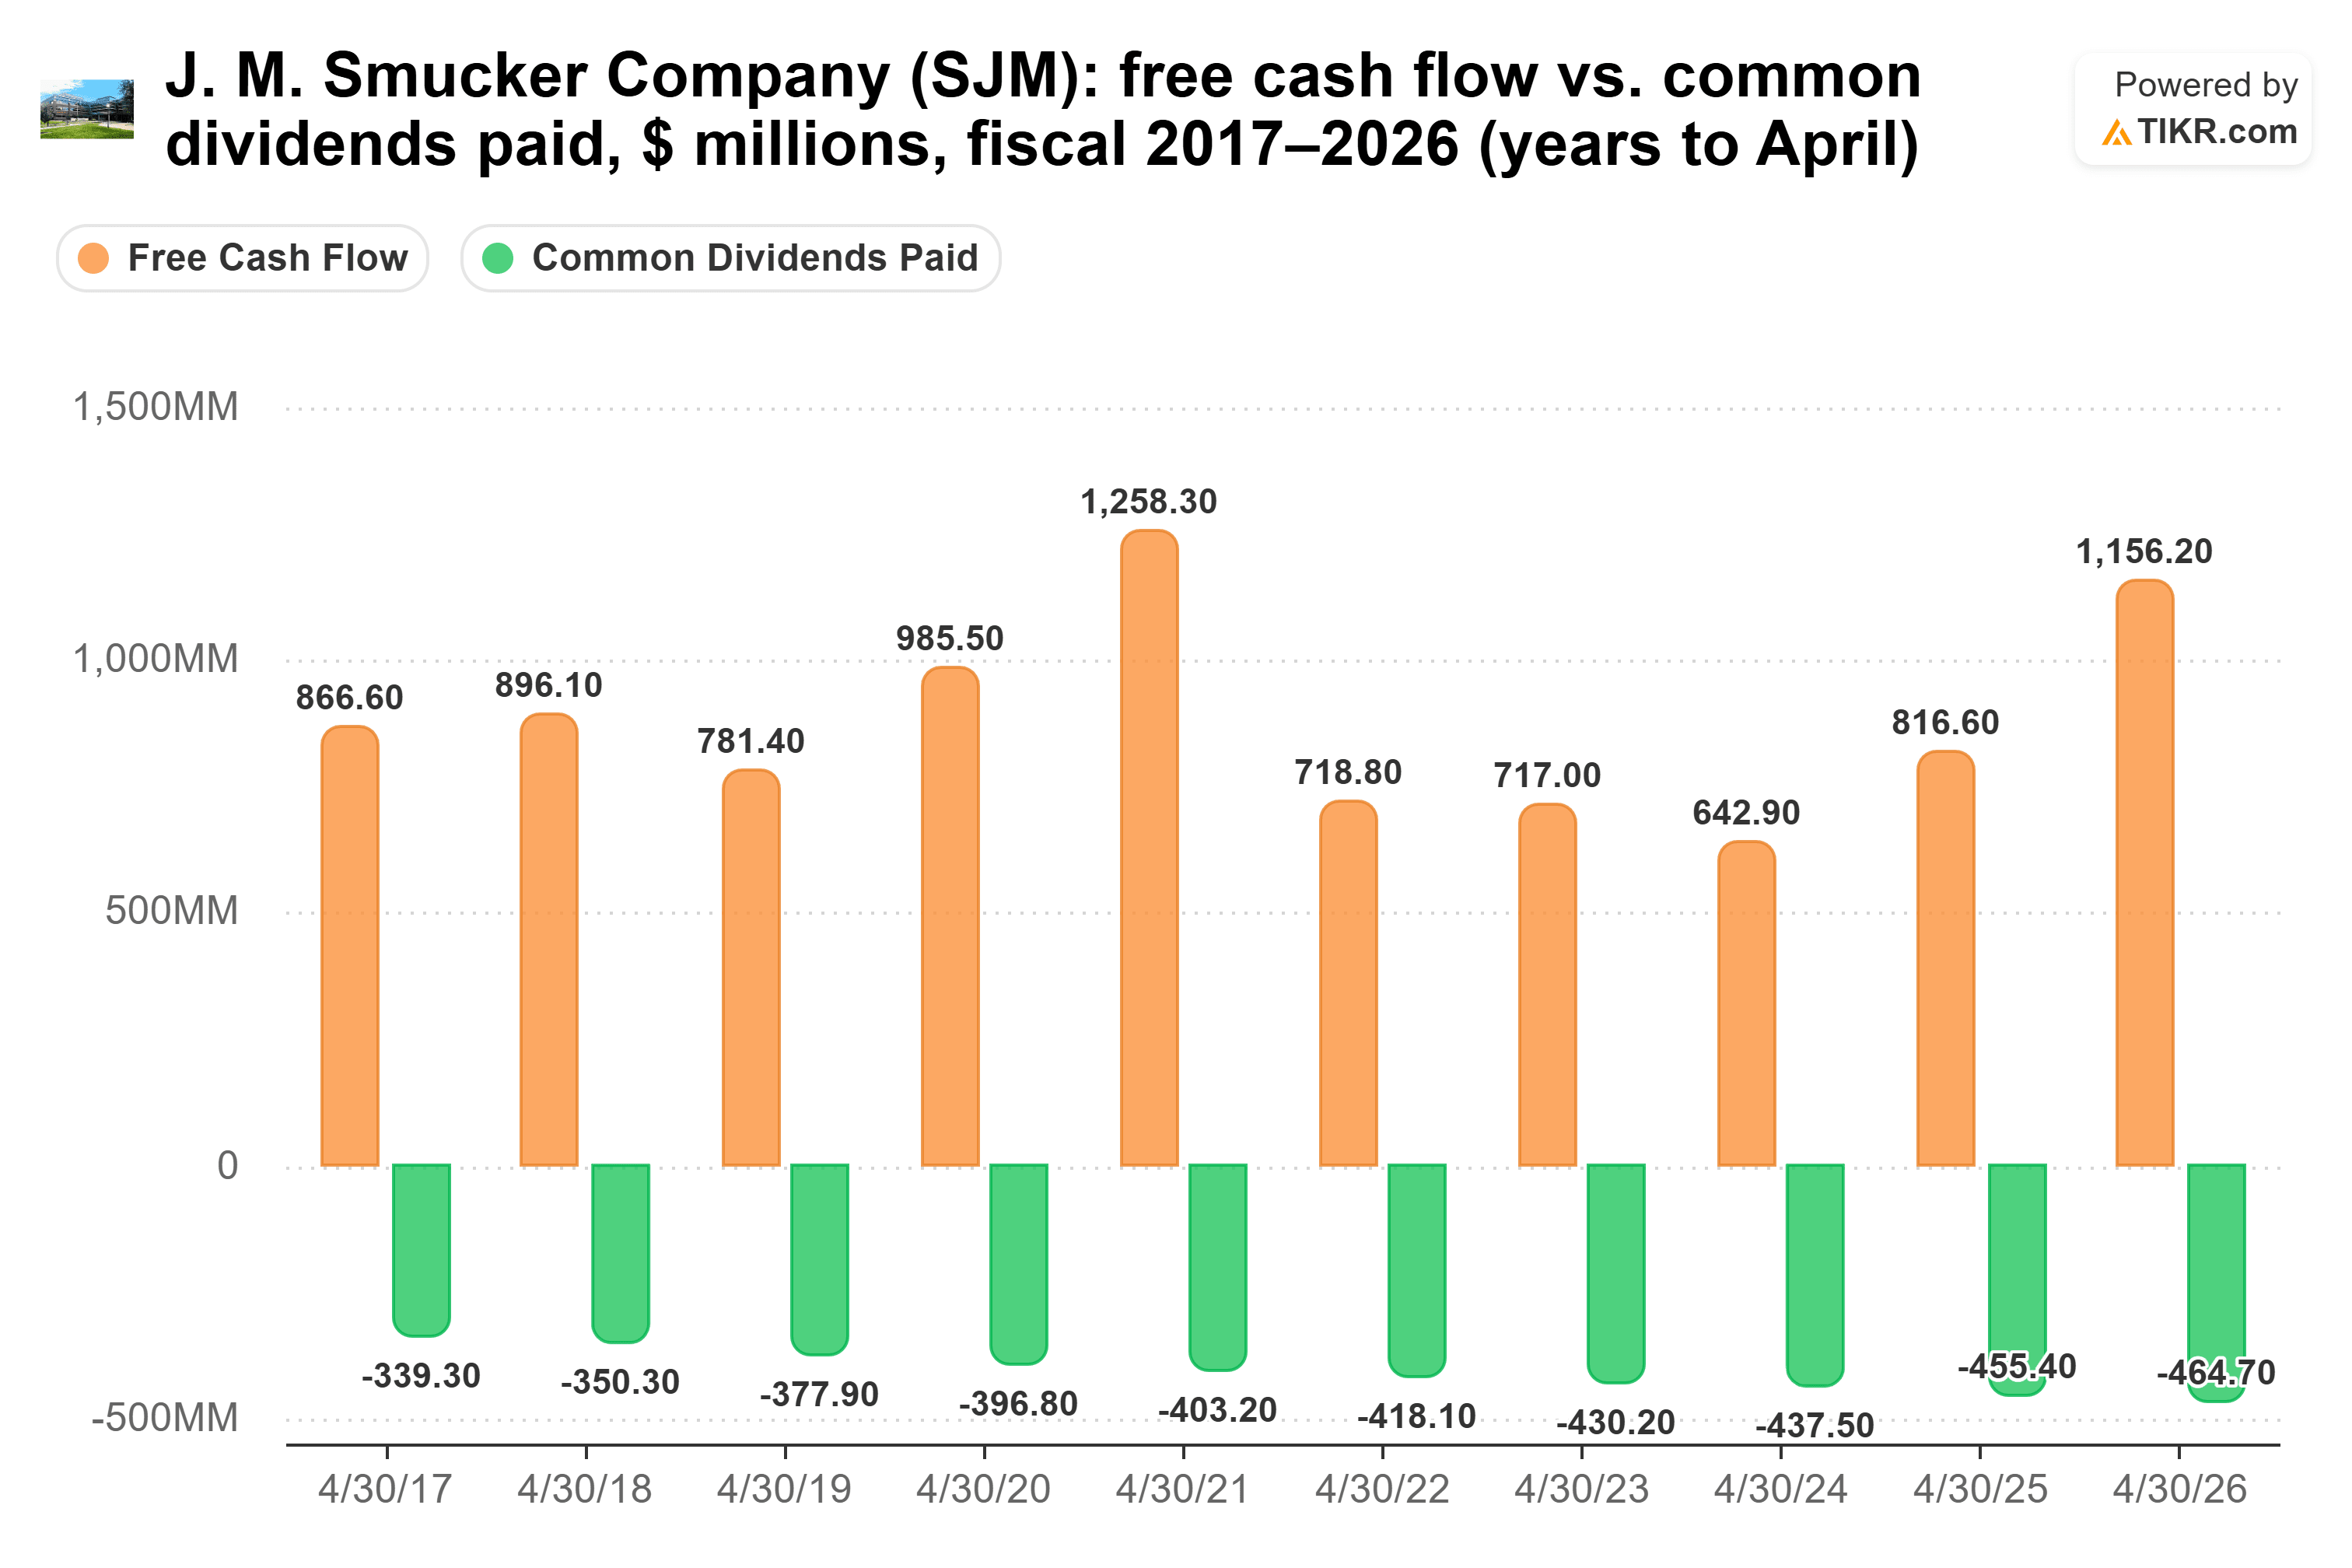
The payout ratio peaked at 68.1% in fiscal 2024 and was back down to 40.2% by fiscal 2026. “In July, we announced that we increased the dividend for the 25th consecutive fiscal year,” management said on the first-quarter call. The main risk is the top line: the dividend rose just 1.9% in fiscal 2026, and sales are guided lower this year.
Energy Transfer’s bigger check comes with bigger bills
Energy Transfer’s business is moving much faster. Its third-quarter adjusted EBITDA rose 31% from a year earlier to $5.03 billion, and on Nov. 3 it raised its 2026 adjusted EBITDA guidance to $19.7-$19.9 billion, from $18.8-$19.1 billion. It’s a master limited partnership, so it pays distributions on units, and holders get a K-1 at tax time.
Distributable cash flow covered those distributions 1.78x in fiscal 2025. On 2026 consensus, coverage rises to 2.15x, because distributable cash flow per unit is expected to jump 24% to $2.94. Management credited market volatility with upside for a third straight quarter, though, so part of this year’s jump may not repeat.
Coverage has been 1.78x or better every year since fiscal 2018, but unitholders still took a cut:
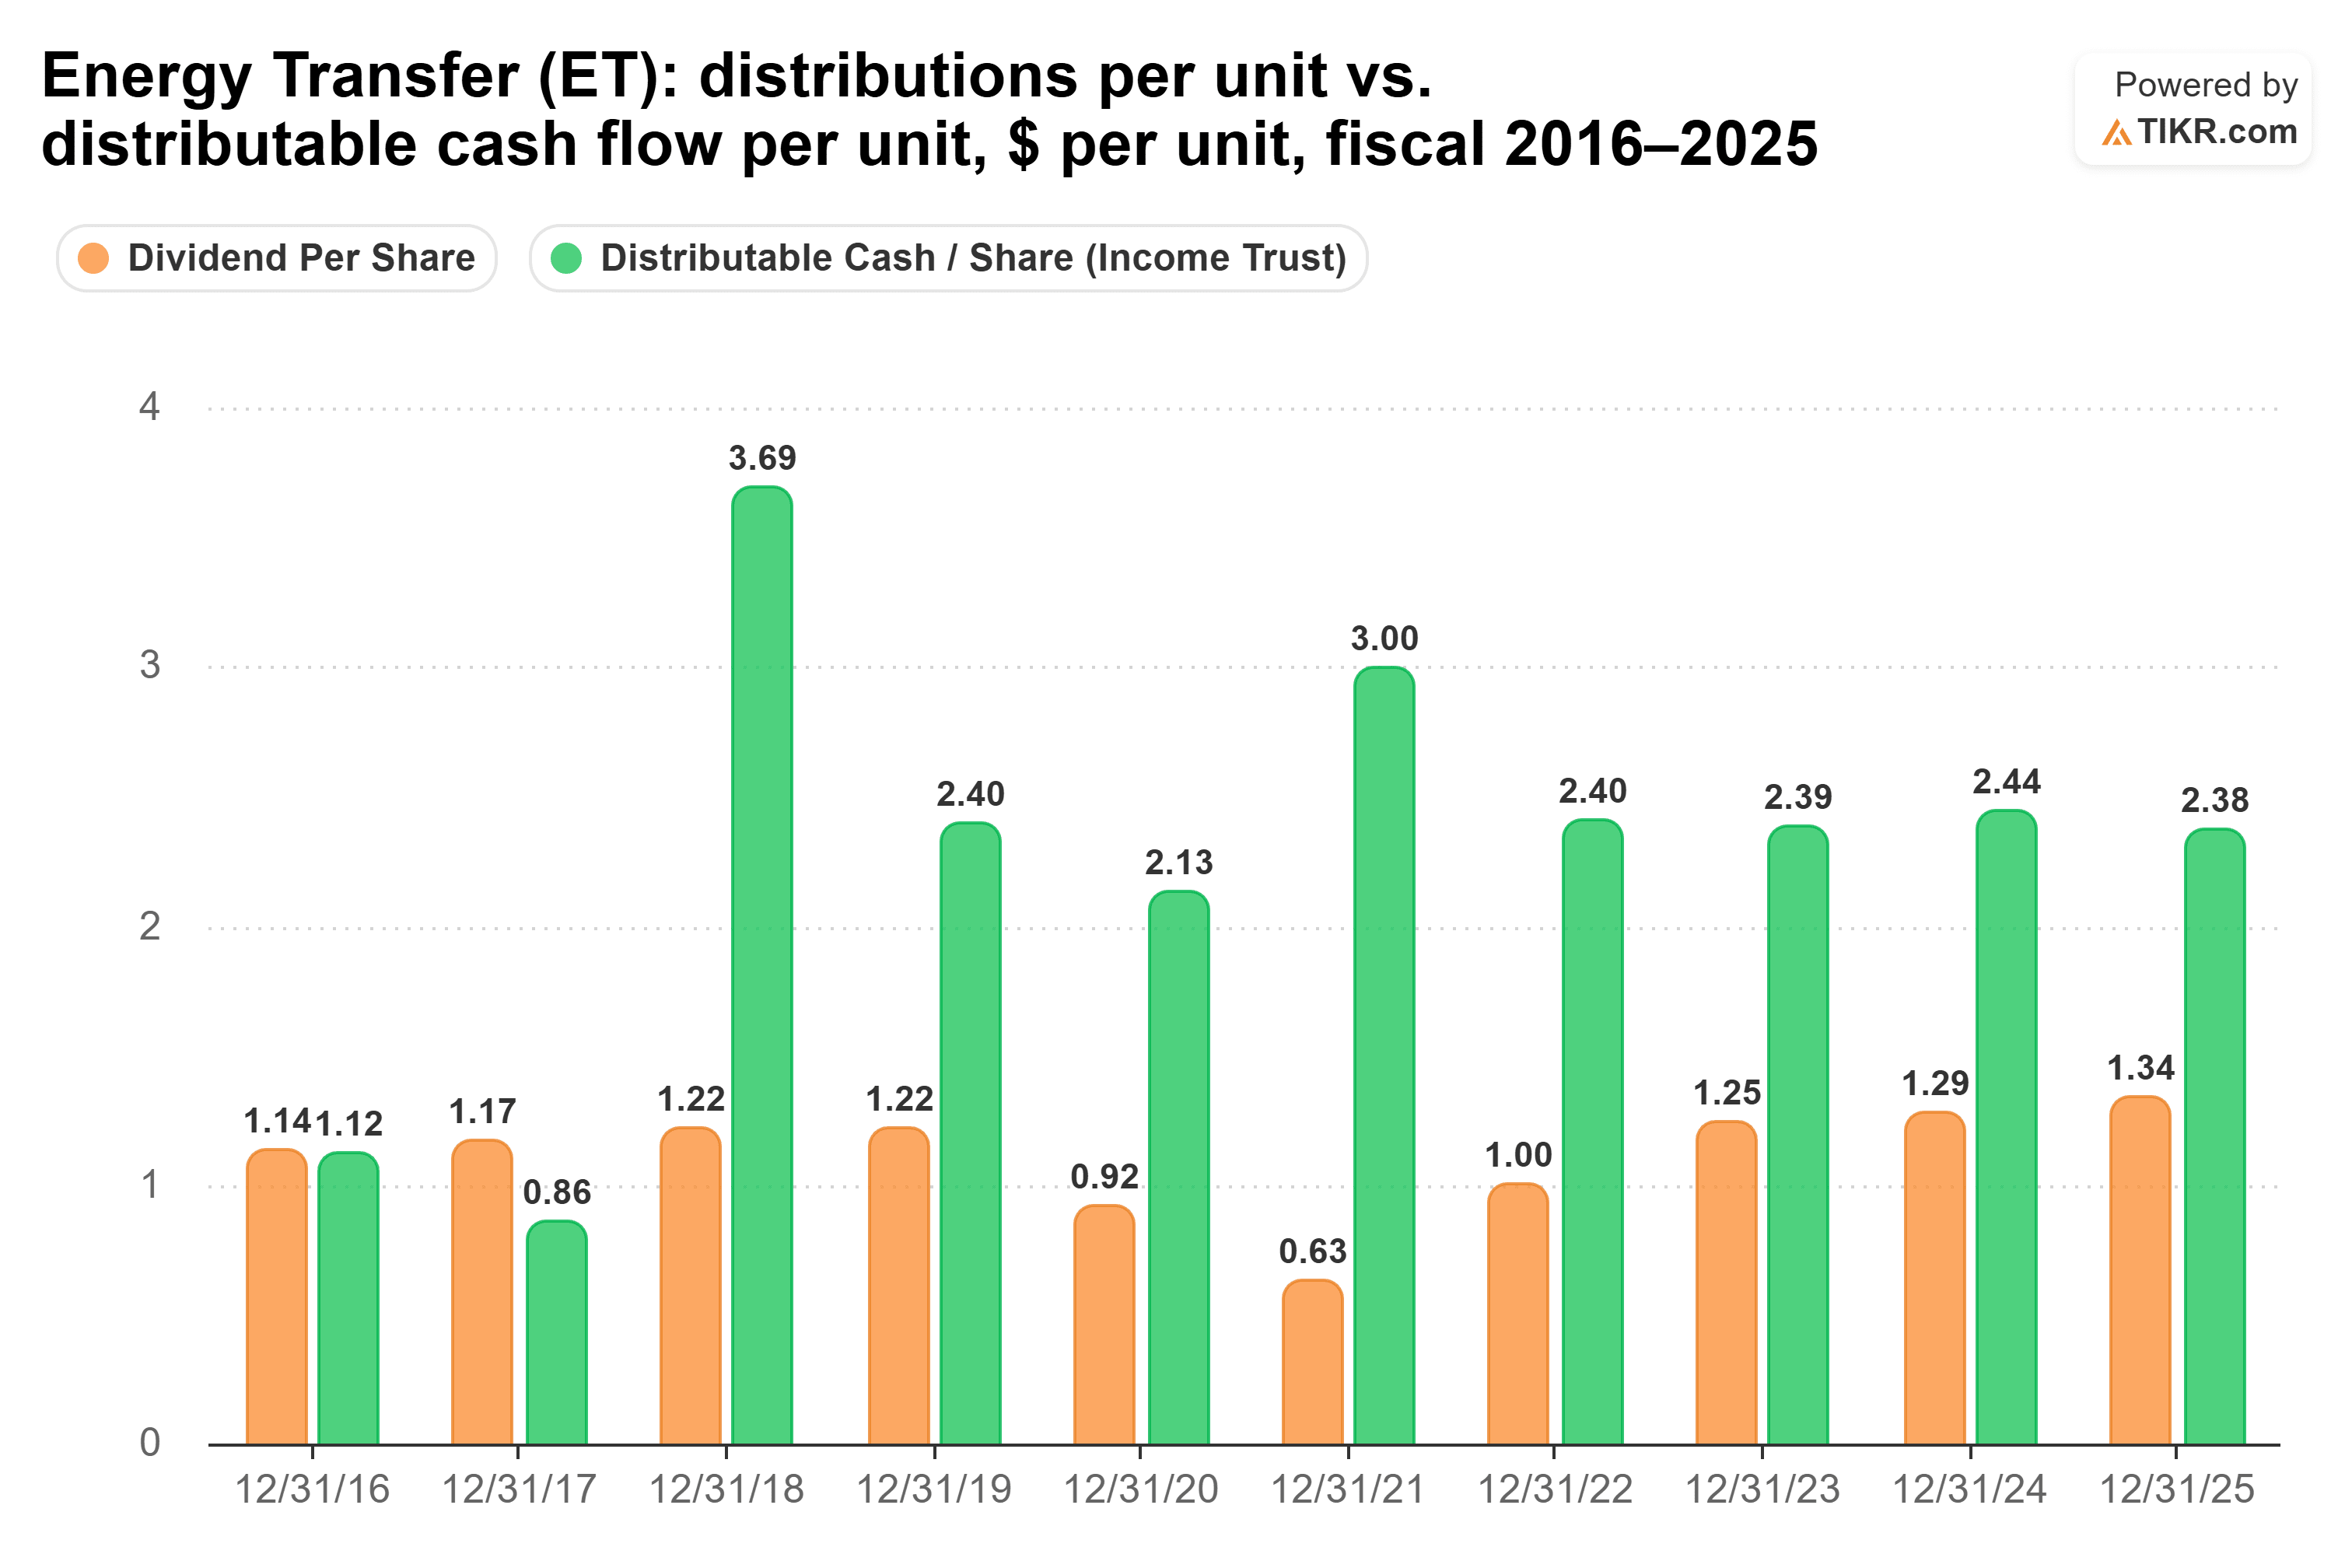
The distribution fell from $1.22 a unit in fiscal 2019 to $0.63 in fiscal 2021, even though distributable cash flow covered fiscal 2020’s payout 2.32x. It’s back to $1.37 a year, and on its second-quarter call, management said it’s “targeting a long-term annual distribution growth rate of 3% to 5% and maintaining our leverage targets of 4 to 4.5x EBITDA.”
So which dividend wins?
If I can only hold one for the next 20 years, it’s J.M. Smucker. Over two decades, I want the dividend most likely to keep rising through whatever comes. Smucker has raised its dividend for 25 fiscal years on a payout well under half its free cash flow, with less leverage and wider interest coverage than Energy Transfer.
That choice costs real money. At fiscal 2026’s 1.9% pace for Smucker and fiscal 2025’s 4.7% for Energy Transfer, $10,000 in Energy Transfer would pay about $23,356 over 20 years, and $10,000 in Smucker about $8,140, and Smucker’s income never catches up. Energy Transfer’s payout is well covered, and its business is growing faster.
But Energy Transfer has already cut its payout once despite strong coverage. Its leverage has also climbed, from 3.9x in fiscal 2021 to 4.5x in fiscal 2025, the top of its target range:
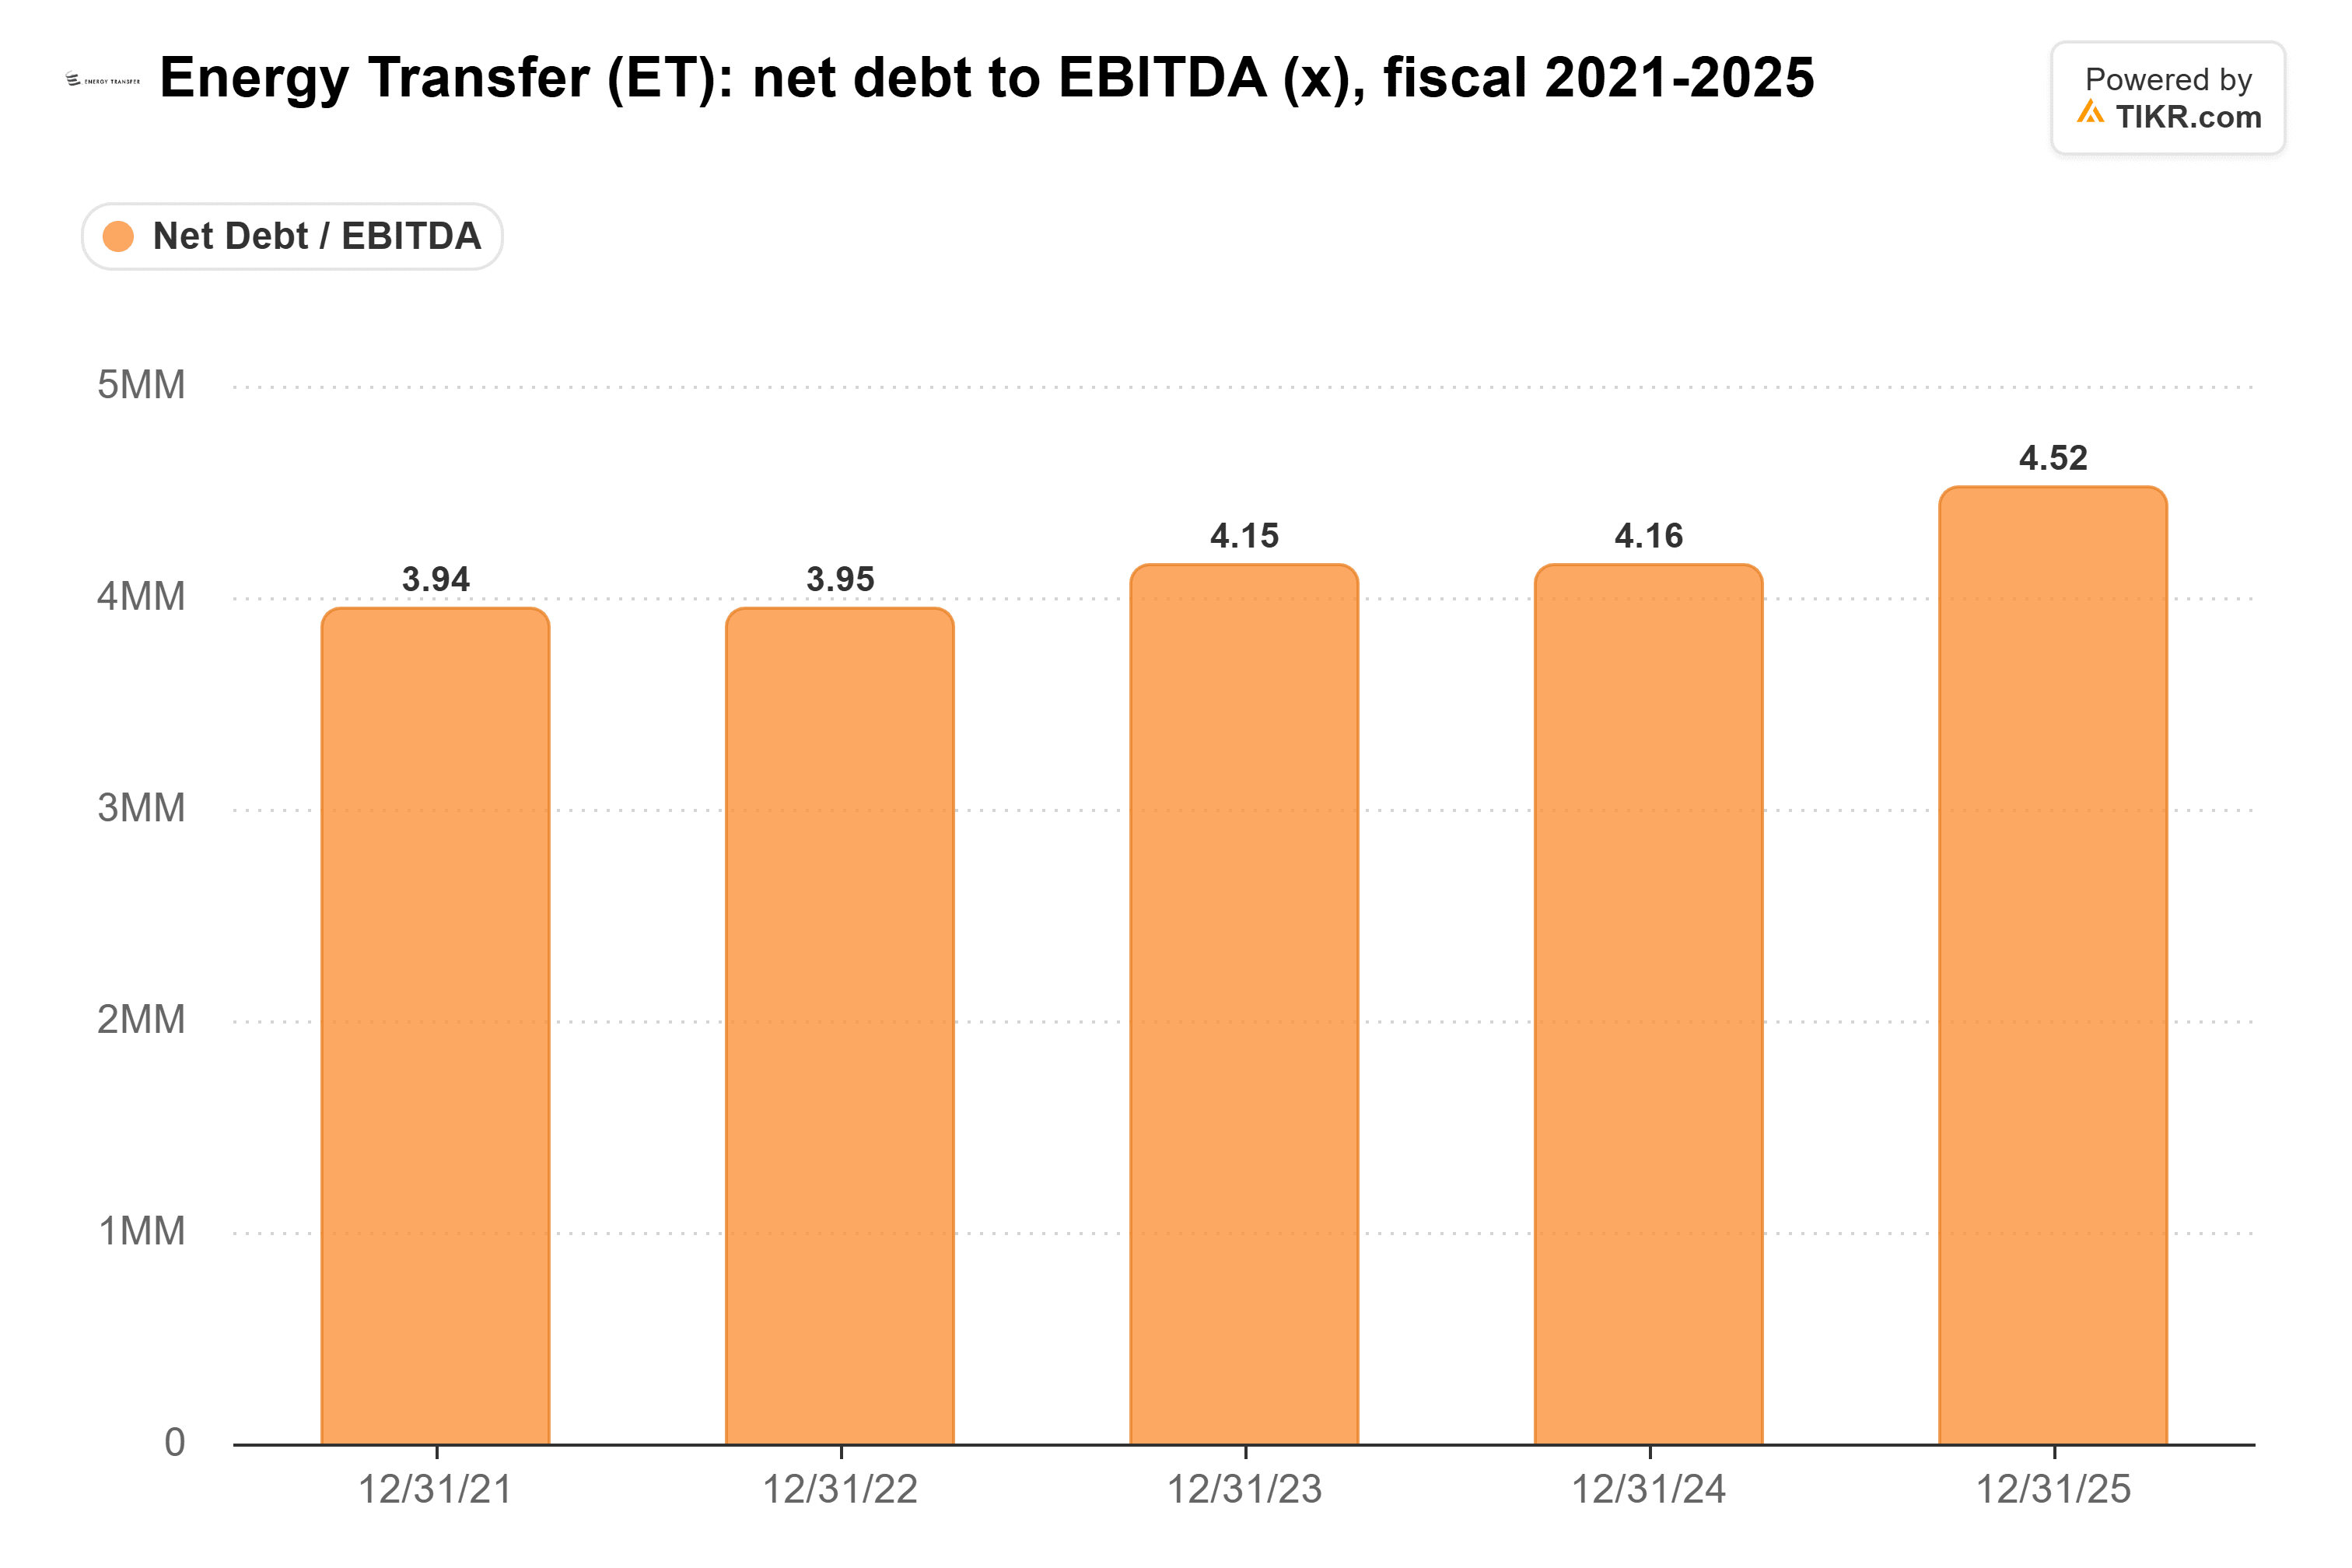
TIKR’s figure for the last twelve months is lower, at 3.83x, after this year’s jump in EBITDA. But more spending is on the way: Energy Transfer plans about $7 billion of growth spending in 2027, up from $5.4-$5.6 billion this year. For a 20-year hold, I’ll take the dividend with less riding on the balance sheet.
Of course, Energy Transfer’s new projects are backed by long-term contracts. If they bring leverage down even as the spending rises, its bigger check gets a lot harder to pass up.
Forget J.M. Smucker: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And J.M. Smucker isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!