Key Takeaways
- Kraft Heinz yields 6.4% and TotalEnergies 4.4%, and each paid out about half its free cash flow in dividends over the twelve months to June 2026.
- TotalEnergies raised its dividend 4.9% a year from fiscal 2020 to fiscal 2025, while Kraft Heinz paid the same $1.60 a share in both years.
- Kraft Heinz carries net debt of 2.7x EBITDA and expects relatively flat organic sales in 2027, against 0.5x for TotalEnergies.
- TotalEnergies has said it may raise its final 2026 dividend if full-year cash flow reaches $43 billion.
Kraft Heinz (KHC) declared its regular $0.40 quarterly dividend on Nov. 4, unchanged from the quarters before it. On the same day, it announced the sale of its North America coffee business at a $650 million value.
A week earlier, TotalEnergies (TTE) confirmed a third interim dividend of €0.90 a share for fiscal 2026, up 5.9% from 2025, and raised its outlook for the year’s cash flow.
So anyone picking one of these to hold for two decades has a real choice: a 6.4% yield that hasn’t grown, or a 4.4% yield that has.
| Metric | TotalEnergies (TTE) | Kraft Heinz (KHC) |
|---|---|---|
| Forward dividend yield | 4.4% | 6.4% |
| Dividend growth, fiscal 2020-2025 | 4.9% a year | 0.0% a year |
| Cash dividend payout ratio (TTM) | 51% | 50% |
| Net debt/EBITDA (LTM) | 0.5x | 2.7x |
| Interest coverage (LTM) | 10.2x | 4.9x |
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
TotalEnergies’ cash swings with oil, and its balance sheet can take it
TotalEnergies’ cash flow rose 25% from the second quarter to $12.3 billion in the third quarter of 2026. Patrick Pouyanné, its chairman and CEO, said on the third-quarter call: “Our strategy is fundamentally oil and gas upstream.”
That ties its dividend coverage to oil and gas prices. Free cash flow covered the dividend in every year on the chart except fiscal 2016 and fiscal 2020:
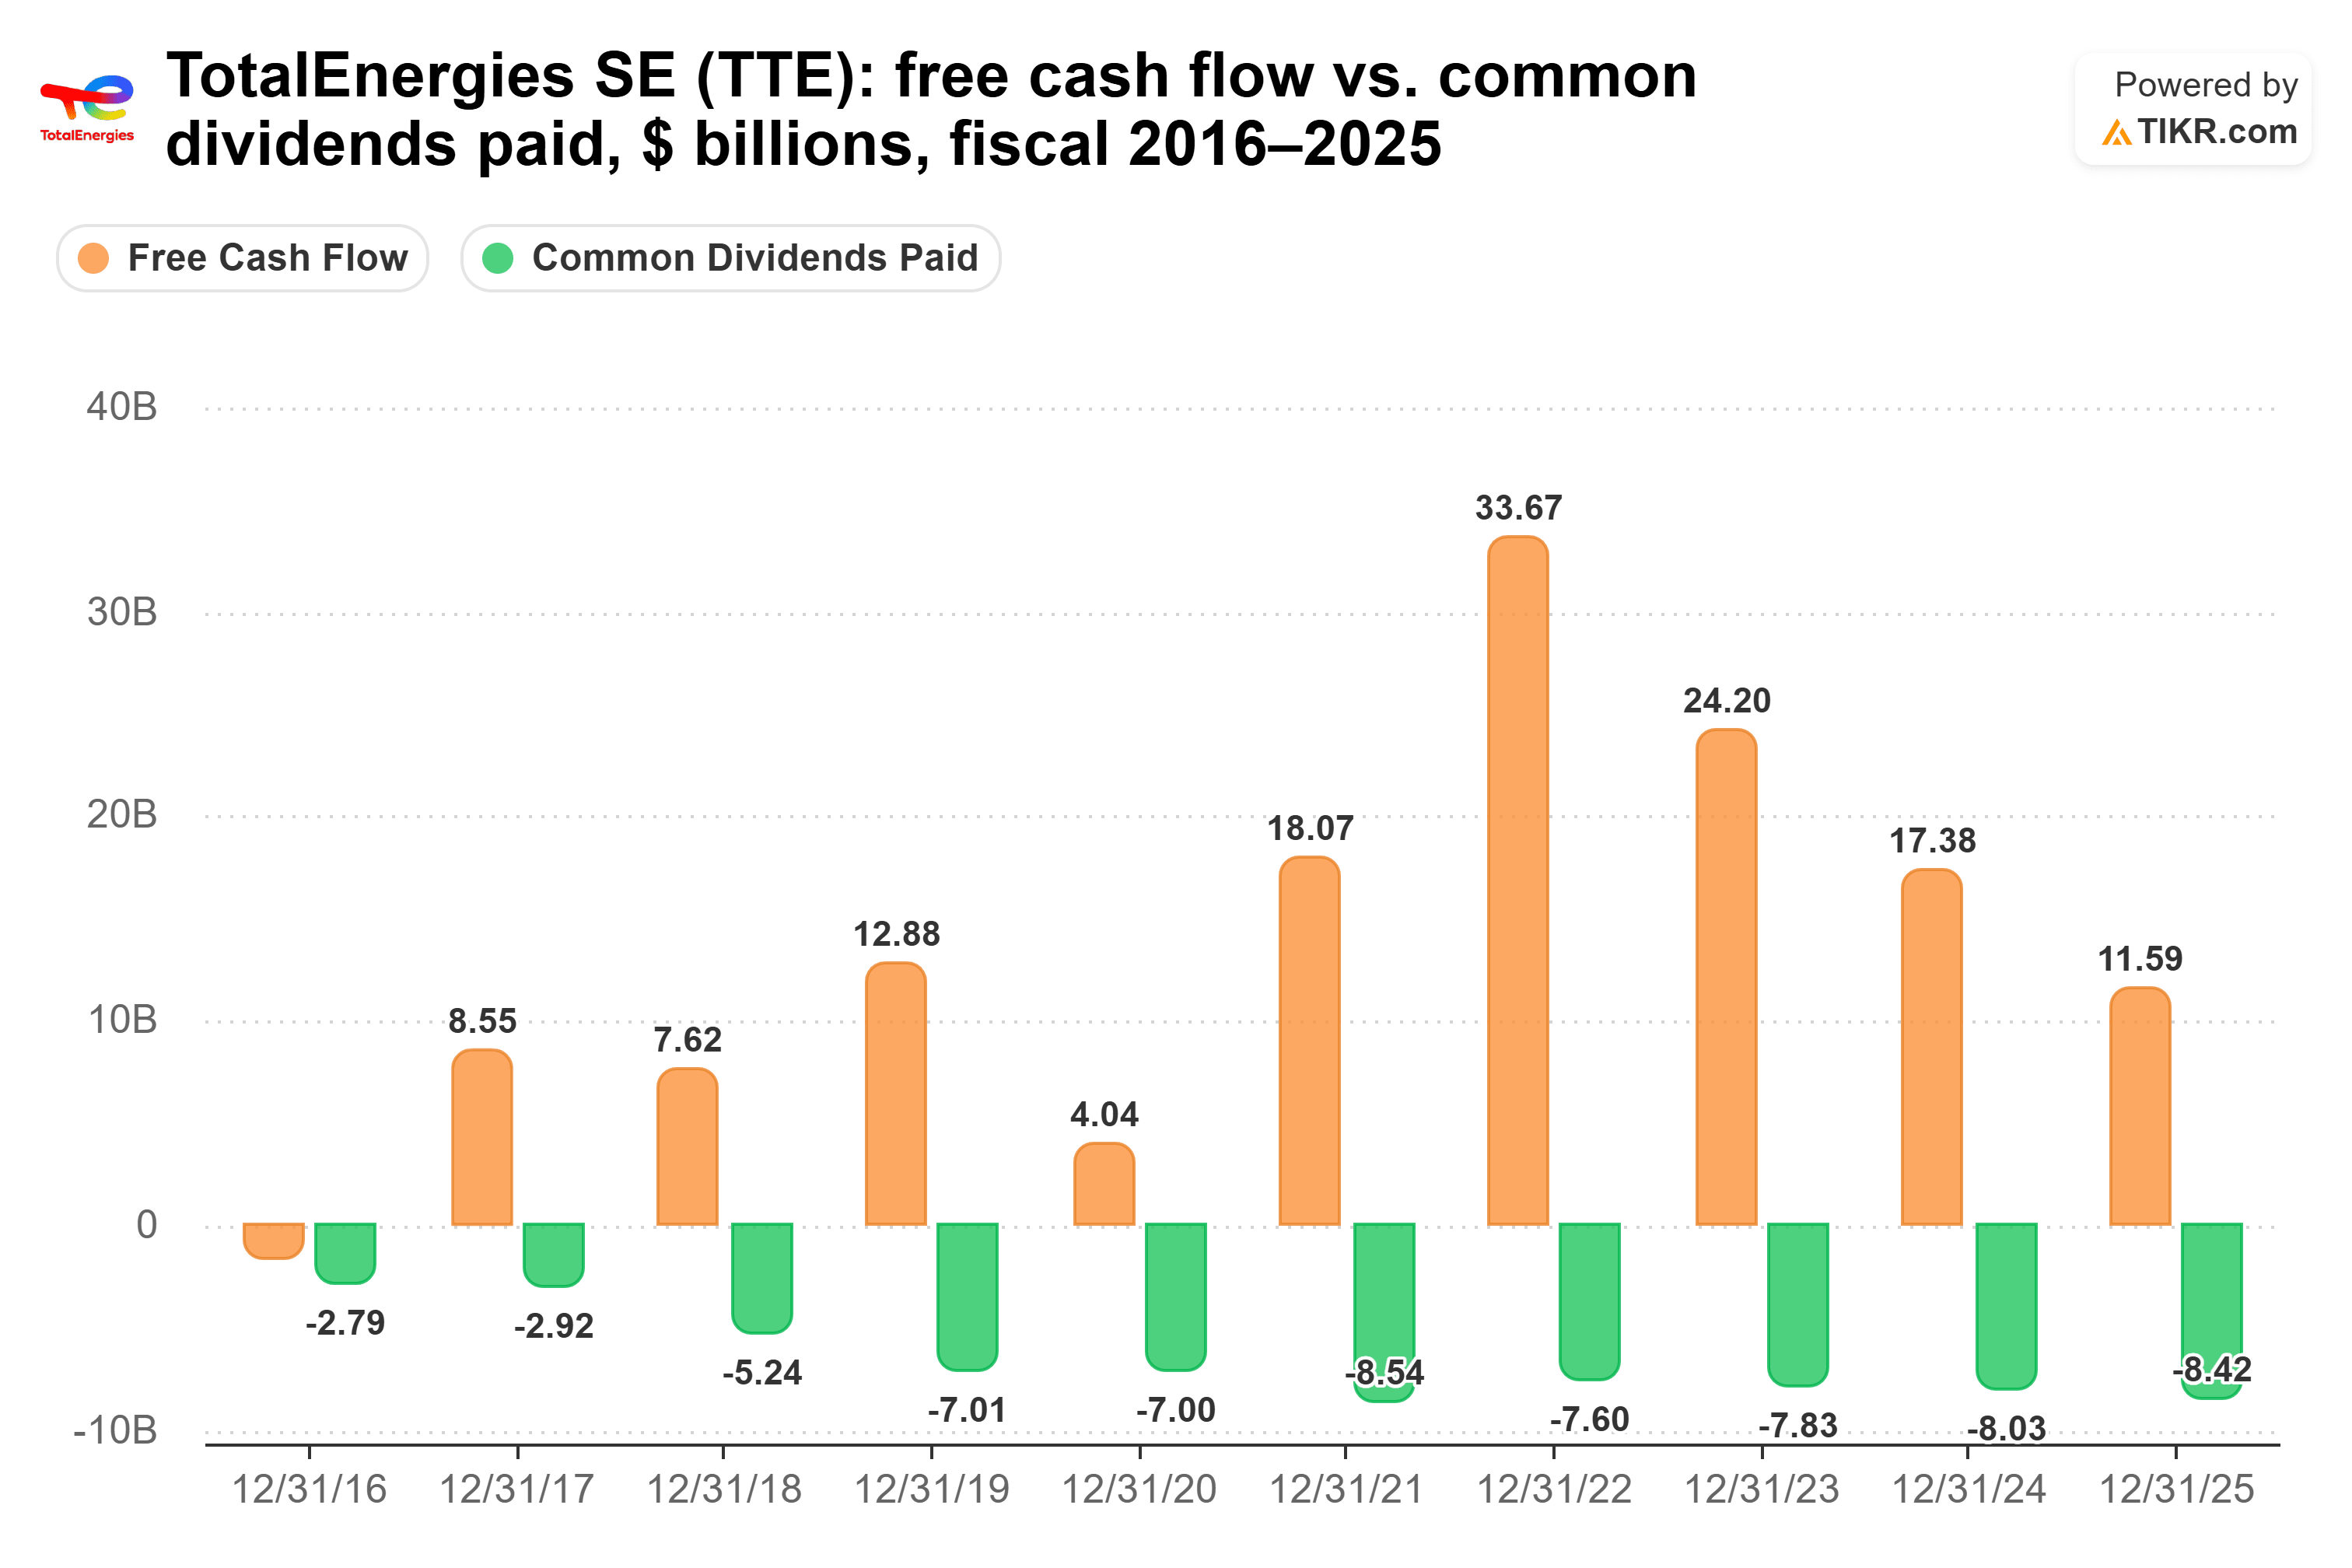
The cash dividend payout ratio climbed from 22.6% in fiscal 2022 to 72.7% in fiscal 2025, then eased to a comfortable 51% over the twelve months to June 30, 2026. With net debt at just 0.5x EBITDA, TotalEnergies has room to ride out the swings. Management also said it may raise the final 2026 dividend if cash flow reaches $43 billion, to meet its commitment to return 40% of cash flow to shareholders.
TotalEnergies sets its dividend in euros, so the dollar amount a US holder gets moves with the exchange rate, and France withholds tax on it. The main risk is a long slide in oil and gas prices.
At its 4.9% yearly pace from fiscal 2020 to fiscal 2025, $10,000 in the stock pays $440 a year now and about $1,082 in year 20, at today’s exchange rate. That’s a 10.8% yield on the cash you put in today.
Kraft Heinz’s bigger check is standing still
Kraft Heinz pays the bigger yield, but its business is heading the other way. Its third-quarter 2026 net sales fell 2.0% from a year earlier to $6.1 billion. At its Nov. 12 investor day, it guided to relatively flat organic sales in 2027, with growth resuming in the second half.
Its coverage has been shakier, too. Free cash flow fell short of the dividend in fiscal 2016, 2017, 2018 and 2022:

Dividends paid dropped from $3.18 billion in fiscal 2018 to $1.95 billion in fiscal 2019. The payout ratio has since eased from 126.2% in fiscal 2022 to a well-covered 50% over the twelve months to June 27, 2026.
Kraft Heinz lists “sustaining the dividend” among its priorities, next to investing in the business and reducing debt. It has done that, paying $1.60 a share in both fiscal 2020 and fiscal 2025. But the cushion is thinner than that 50% suggests. The company expects about $500 million of free cash flow left after dividends in 2027, and its net debt is 2.7x EBITDA.
With no growth, $10,000 pays $640 a year now and the same in year 20.
So which dividend wins?
TotalEnergies is the one I’d hold for the next 20 years. Over that long a stretch, I want a dividend that keeps growing from a business that can afford it. TotalEnergies has the faster-growing dividend and the far stronger balance sheet. At its recent pace, its income on $10,000 passes Kraft Heinz’s around 2034. Over 20 years, it pays about $14,323, which is $1,523 more than Kraft Heinz’s $12,800.
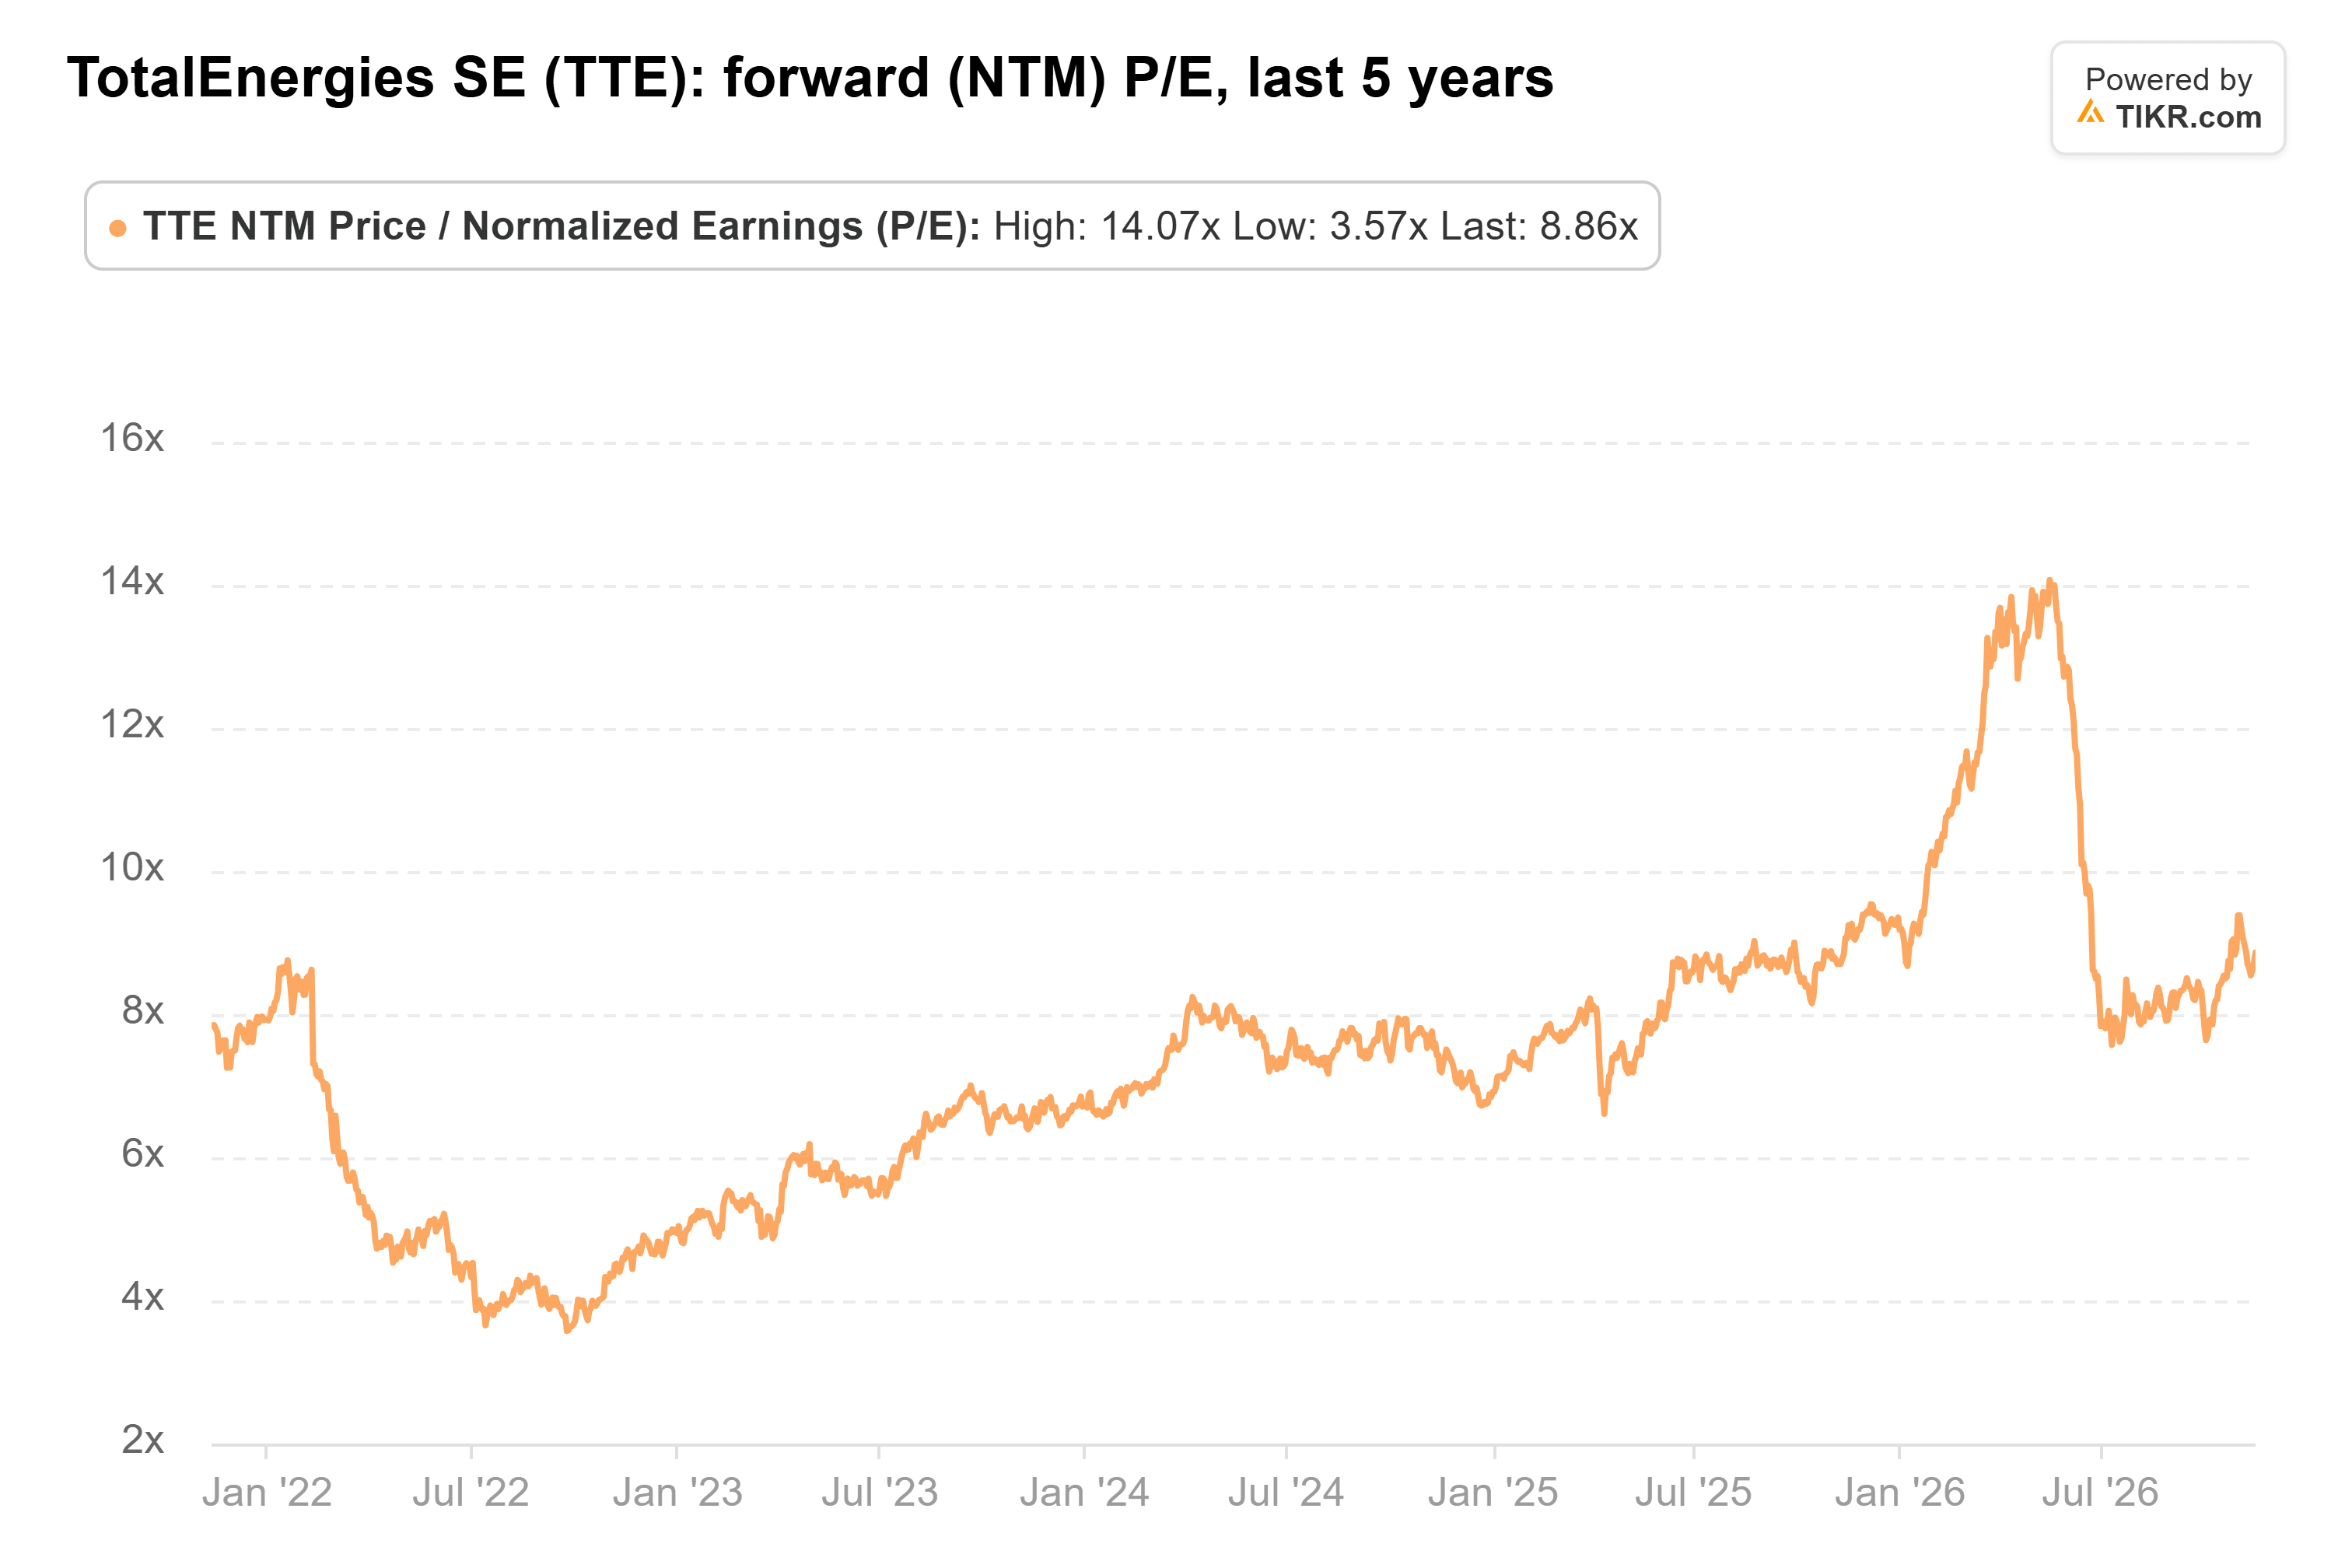
I’m not paying up much for it, either. TotalEnergies trades at 8.9x forward earnings, above its five-year average of 7.3x but well below the 14.1x it hit in May:
This isn’t to say Kraft Heinz’s dividend is in danger. It’s using half its free cash flow. It’s just that, over 20 years, I’d rather own a dividend that’s growing on a strong balance sheet than one waiting on a turnaround.
Of course, if Kraft Heinz’s growth comes back in the second half of 2027 as it expects, I’d feel a lot better about that 6.4%.
Forget TotalEnergies: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And TotalEnergies isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!