Key Takeaways
- Larry Robbins’ Glenview Capital, a hedge fund firm managing $6.37 billion, made Meta Platforms, Advanced Micro Devices and Humana its three biggest additions of the third quarter, per its 13F filed Nov. 16.
- Meta and AMD are down 18% and 20% from their Sept. 30 prices, while Humana is roughly flat.
- Analysts’ average price targets sit 42% above Meta’s last close and 34% above both AMD’s and Humana’s.
- The numbers back Meta best: it trades below its own five-year average multiple and has the most upside to its average target.
Meta Platforms (META) and Advanced Micro Devices (AMD) have both fallen hard since Sept. 30. That makes the stocks a big hedge fund was adding in the third quarter worth a fresh look.
Glenview Capital filed its 13F for the quarter ended Sept. 30 on Nov. 16. It held $5.63 billion of US stocks across 135 positions. Its three biggest new or added positions were Meta, AMD and Humana (HUM).
Meta is cheaper than its own history
Glenview held 495,268 Meta shares worth $359 million at Sept. 30. That’s 39% more than three months earlier, and it made Meta the fund’s fourth-largest position at 6.4% of its 13F stocks. The fund also held Meta call options with a notional value of $36 million. It wasn’t alone: Dan Loeb’s Third Point made Meta its largest US holding in the same quarter.
The spending is the worry. Meta’s third-quarter capex of $34.9 billion was more than its $32.8 billion of operating cash flow, and it guides 2026 capex to $135 billion to $145 billion. Wall Street’s average target has held steady through all of it:
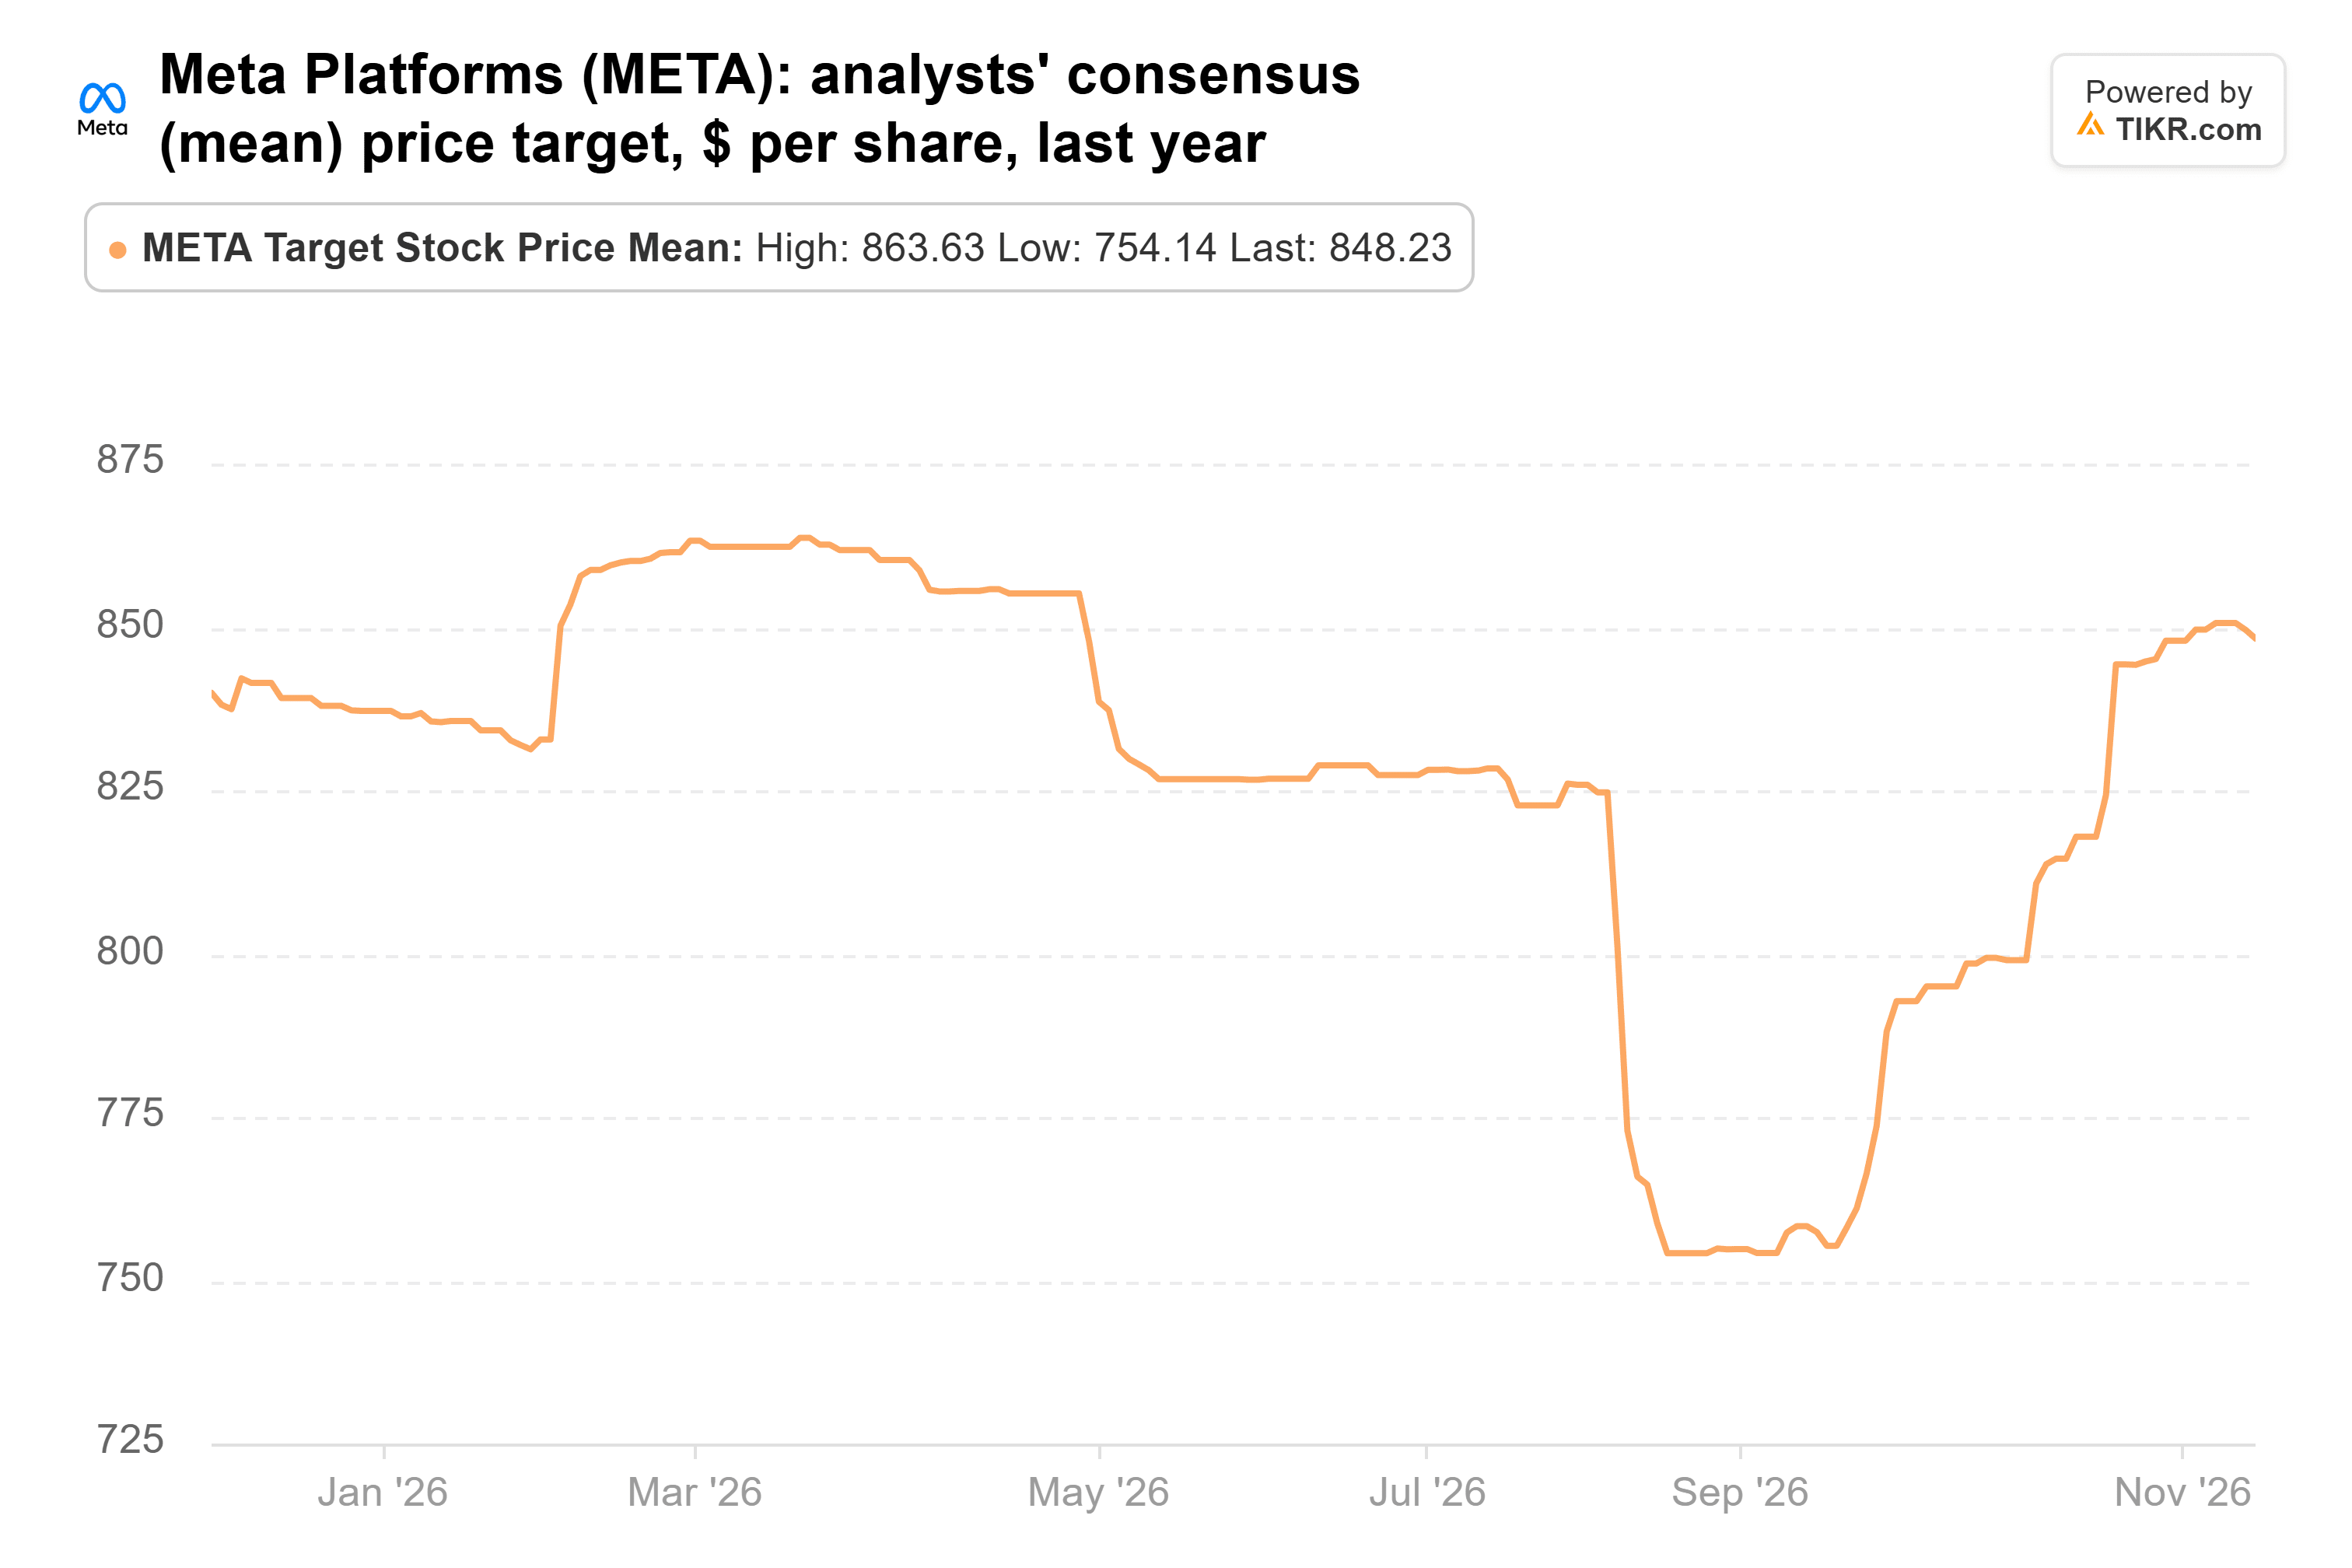
At $848, it’s up from $840 a year ago and sits 42% above the last close. Meta trades at about 18x forward earnings, below its five-year average of 21x.
TIKR tracks 62 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
AMD’s estimates keep rising
The fund grew its AMD stake 31% in the quarter, to 391,267 shares worth $239 million at Sept. 30. That made AMD its eighth-largest position at 4.3% of its 13F stocks. AMD is down 20% from that Sept. 30 price and 26% below the $649.42 high it set on Oct. 6. Since then, AMD has guided to a fourth-quarter gross margin of about 55%, the bottom of its 55% to 58% long-term range, as its Helios racks ramp. And on Nov. 16, the Commerce Department’s Bureau of Industry and Security issued an interim final rule. It requires licenses for advanced US AI chips shipped to Indonesia, Malaysia, Singapore, Thailand and Brazil, and AMD’s Instinct GPUs are covered.
Demand looks better. Anthropic, Meta, Microsoft, OpenAI and Oracle already run workloads on the first Helios units. Consensus normalized EPS for 2028 has climbed to $25.52 from $22.80 earlier this month. Analysts’ average target has more than doubled in a year:
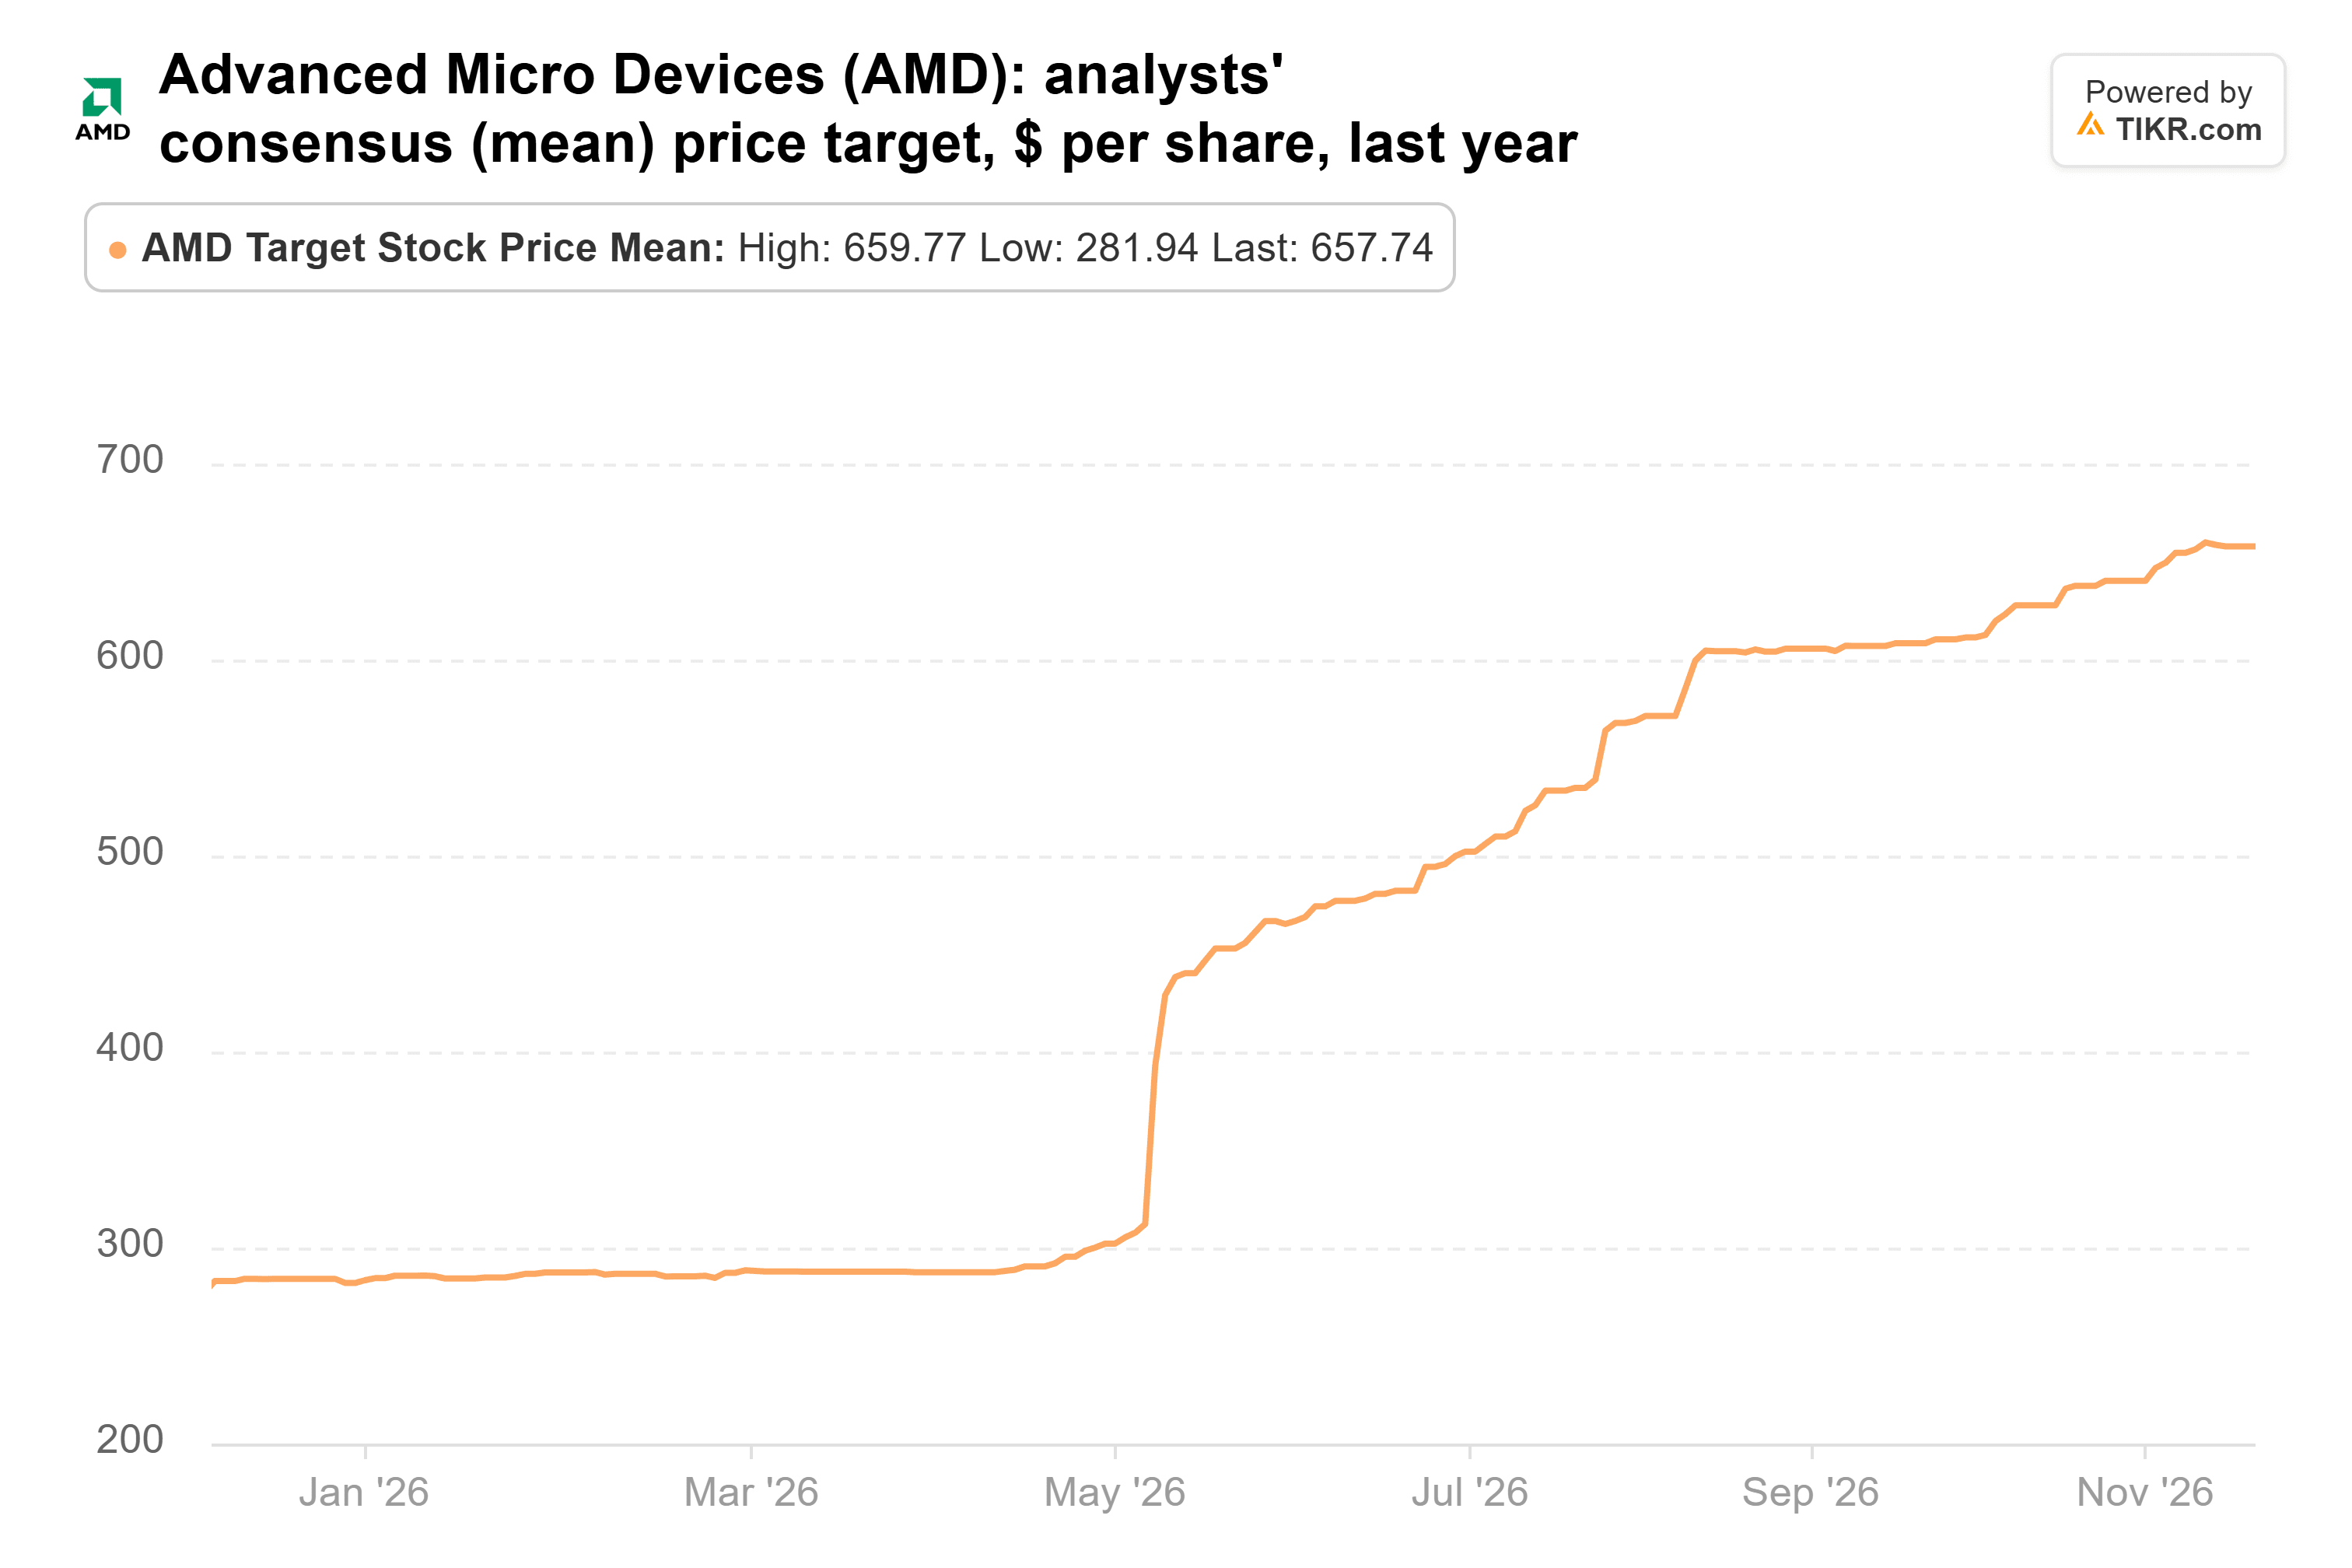
At $658, it sits 34% above the last close. AMD trades at about 32x forward earnings, a bit below its five-year average of 35x.
Humana’s rally ran into Washington
The fund more than doubled its Humana stake, adding 115% to reach 545,385 shares worth $208 million at Sept. 30. That made Humana its 10th-largest position at 3.7% of its 13F stocks. The fund also held Humana put options with a notional value of $6 million. On Nov. 6, Humana raised its 2026 adjusted EPS guidance to at least $9.50 from at least $9.00. It also said its 2027 Medicare Advantage bids should drive progress toward a pretax margin of at least 3% in 2028.
The stock hit a 52-week high of $461.25 on Nov. 16. Then came a federal proposal on Nov. 18 that could let regulators recover Medicare Advantage overpayments going back to 2018, and Medicare Advantage is the business Humana’s margin plan rests on. The stock is now 18% below that high and 0.4% below its Sept. 30 price. Analysts’ average target climbed all year and sits at its high:
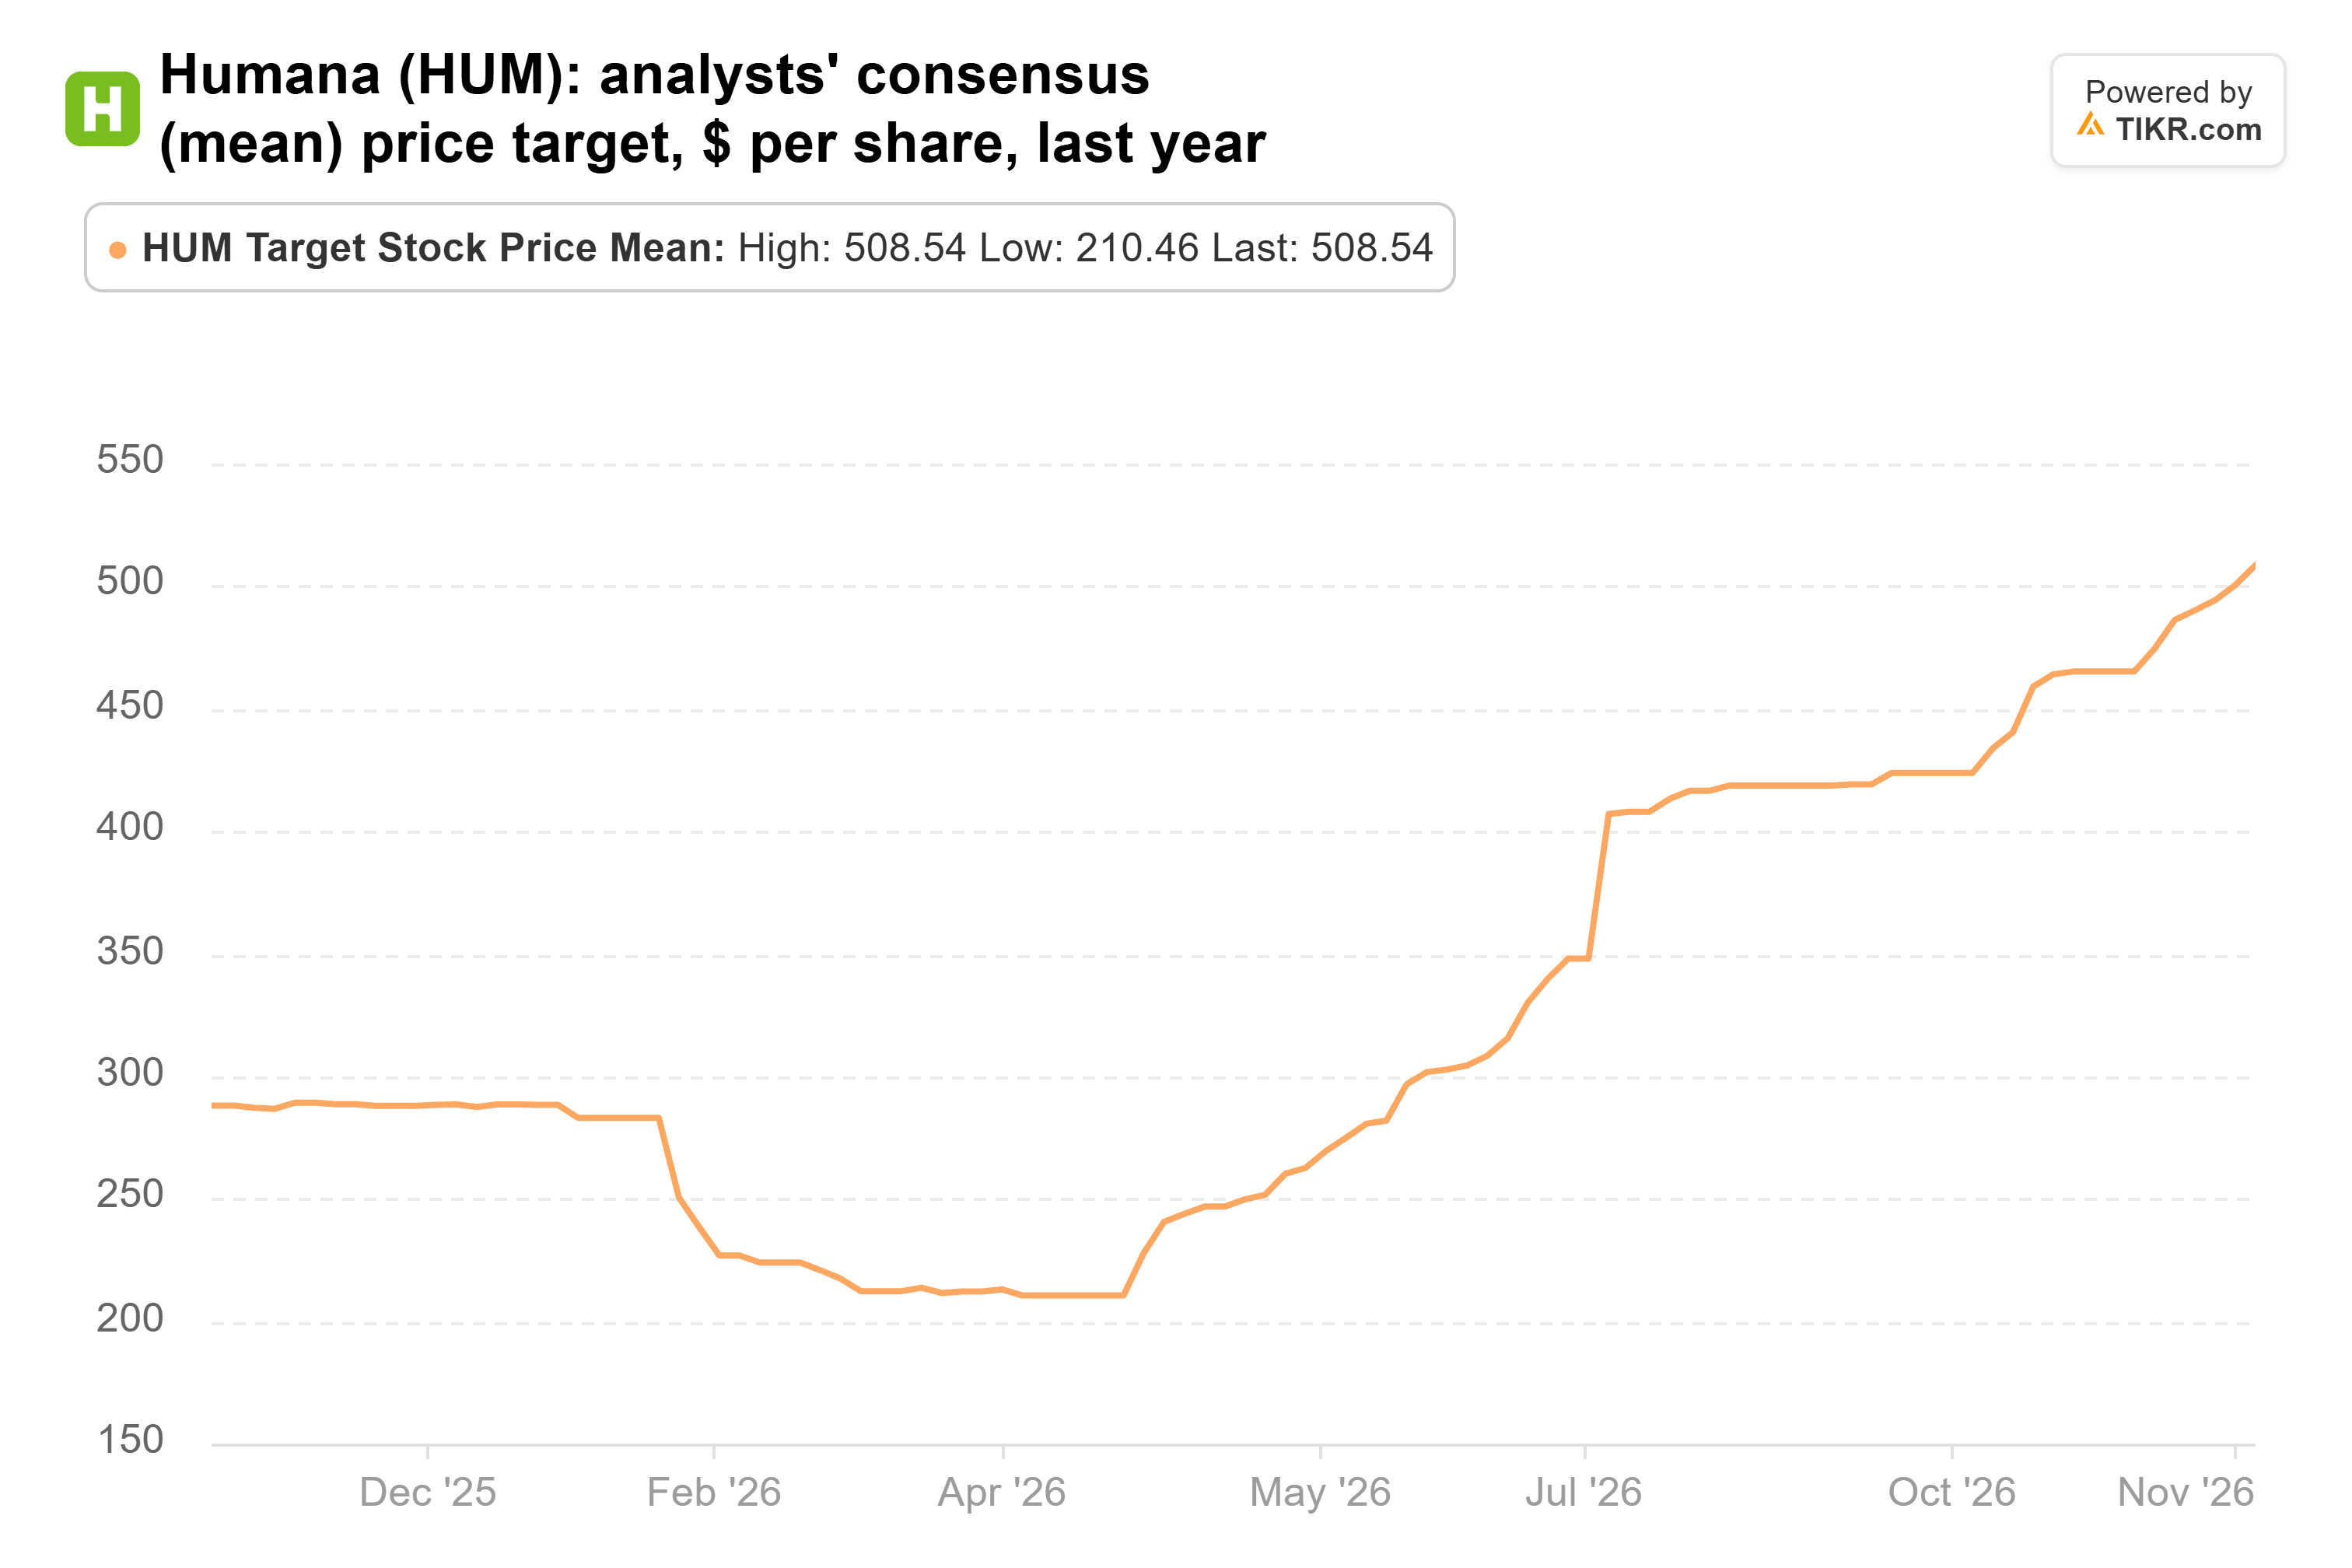
At $509, it’s up from $288 a year ago and 34% above the last close. Humana trades at about 22x forward earnings.
Meta is the one to follow
If I could only buy one of the three right now, it’d be Meta. It trades below its own five-year average multiple and has the most upside of the three to Wall Street’s average target. Analysts also still expect its earnings to grow through 2028, even after cutting their 2027 estimates 4% since the end of June.
The risk is cash. Consensus has Meta’s free cash flow bottoming at negative $48.0 billion in 2027. And a New Mexico court ordered a $25 billion penalty on Oct. 21, which Meta will appeal.
AMD’s estimates are rising faster, and anyone who’d rather own the chipmaker has a fair case. Humana’s guidance raise is real too, but I’d wait until the overpayment proposal plays out.
The test is Meta’s fourth-quarter report in late January, when it sets out its 2027 budget and capex plan. Capex well above the roughly $210 billion analysts expect for 2027, with no revenue outlook to match, would weaken the case. The fund’s next 13F, due by mid-February, will show whether it kept adding.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!