

Key Takeaways
- Sandisk is 60% below its June high. On Nov. 11, Evercore ISI kept its Outperform rating and its $2,500 price target, which is 167% above the Nov. 12 close.
- Evercore argues that Sandisk’s multiyear supply contracts and a more disciplined flash industry should keep its profits high for longer than in past memory cycles.
- At $2,500, Sandisk would trade at 10x expected earnings, which is its average over the past year. It now trades at 3.8x.
- Evercore has the better argument, and Sandisk’s late-January report, with its March-quarter outlook and backlog, is the next test.
Sandisk (SNDK) closed Nov. 12 60% below its June 25 closing high. On Nov. 11, Evercore ISI analyst Amit Daryanani kept his Outperform rating and $2,500 price target, 167% above that close. The stock jumped 13.69% that day, then fell 4.11% to $937.46 on Nov. 12 after Jensen Huang stepped down as Nvidia’s CEO.
Three hits in two weeks
Sandisk’s fiscal first quarter, to Oct. 2, brought $11.0 billion of revenue and $49.51 a share of non-GAAP earnings, both above its guidance. But higher prices drove less of the growth: CFO Luis Visoso put them at about 40% of the sequential gain, down from about two-thirds the quarter before. Then Kioxia, Sandisk’s partner in the fabs, said its own flash price gains had cooled to the mid-20s percent in the September quarter, from about 70%. And Qualcomm blamed part of a 26% drop in its handset chip revenue on “industry-wide memory dynamics,” just before fears that Democrats’ sweep of Congress could slow data center building sent Sandisk down 22% on Nov. 5.
TIKR tracks 25 analysts on Sandisk. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Sandisk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Sandisk’s Analyst Ratings
How Evercore gets to $2,500
“We think investors remain overly focused on how long NAND pricing can stay elevated rather than appreciating the structural changes to SNDK’s model,” Evercore wrote. Those changes start with Sandisk’s multiyear supply contracts. Management says they cover about half of its fiscal 2027 bits and two-thirds of fiscal 2028’s, at floor prices that still earn a gross margin of about 80%. Evercore adds an industry holding back supply (price increases have lasted about six quarters, against about two historically), plus AI demand and the high-bandwidth flash Sandisk plans to sample in 2027. (These per-share figures predate Sandisk’s 8-for-1 split: from Nov. 20, $2,500 becomes $312.50.)
Does $2,500 add up?
Wall Street’s average target is just 8% below its July peak, though the stock has lost more than half its value since June:
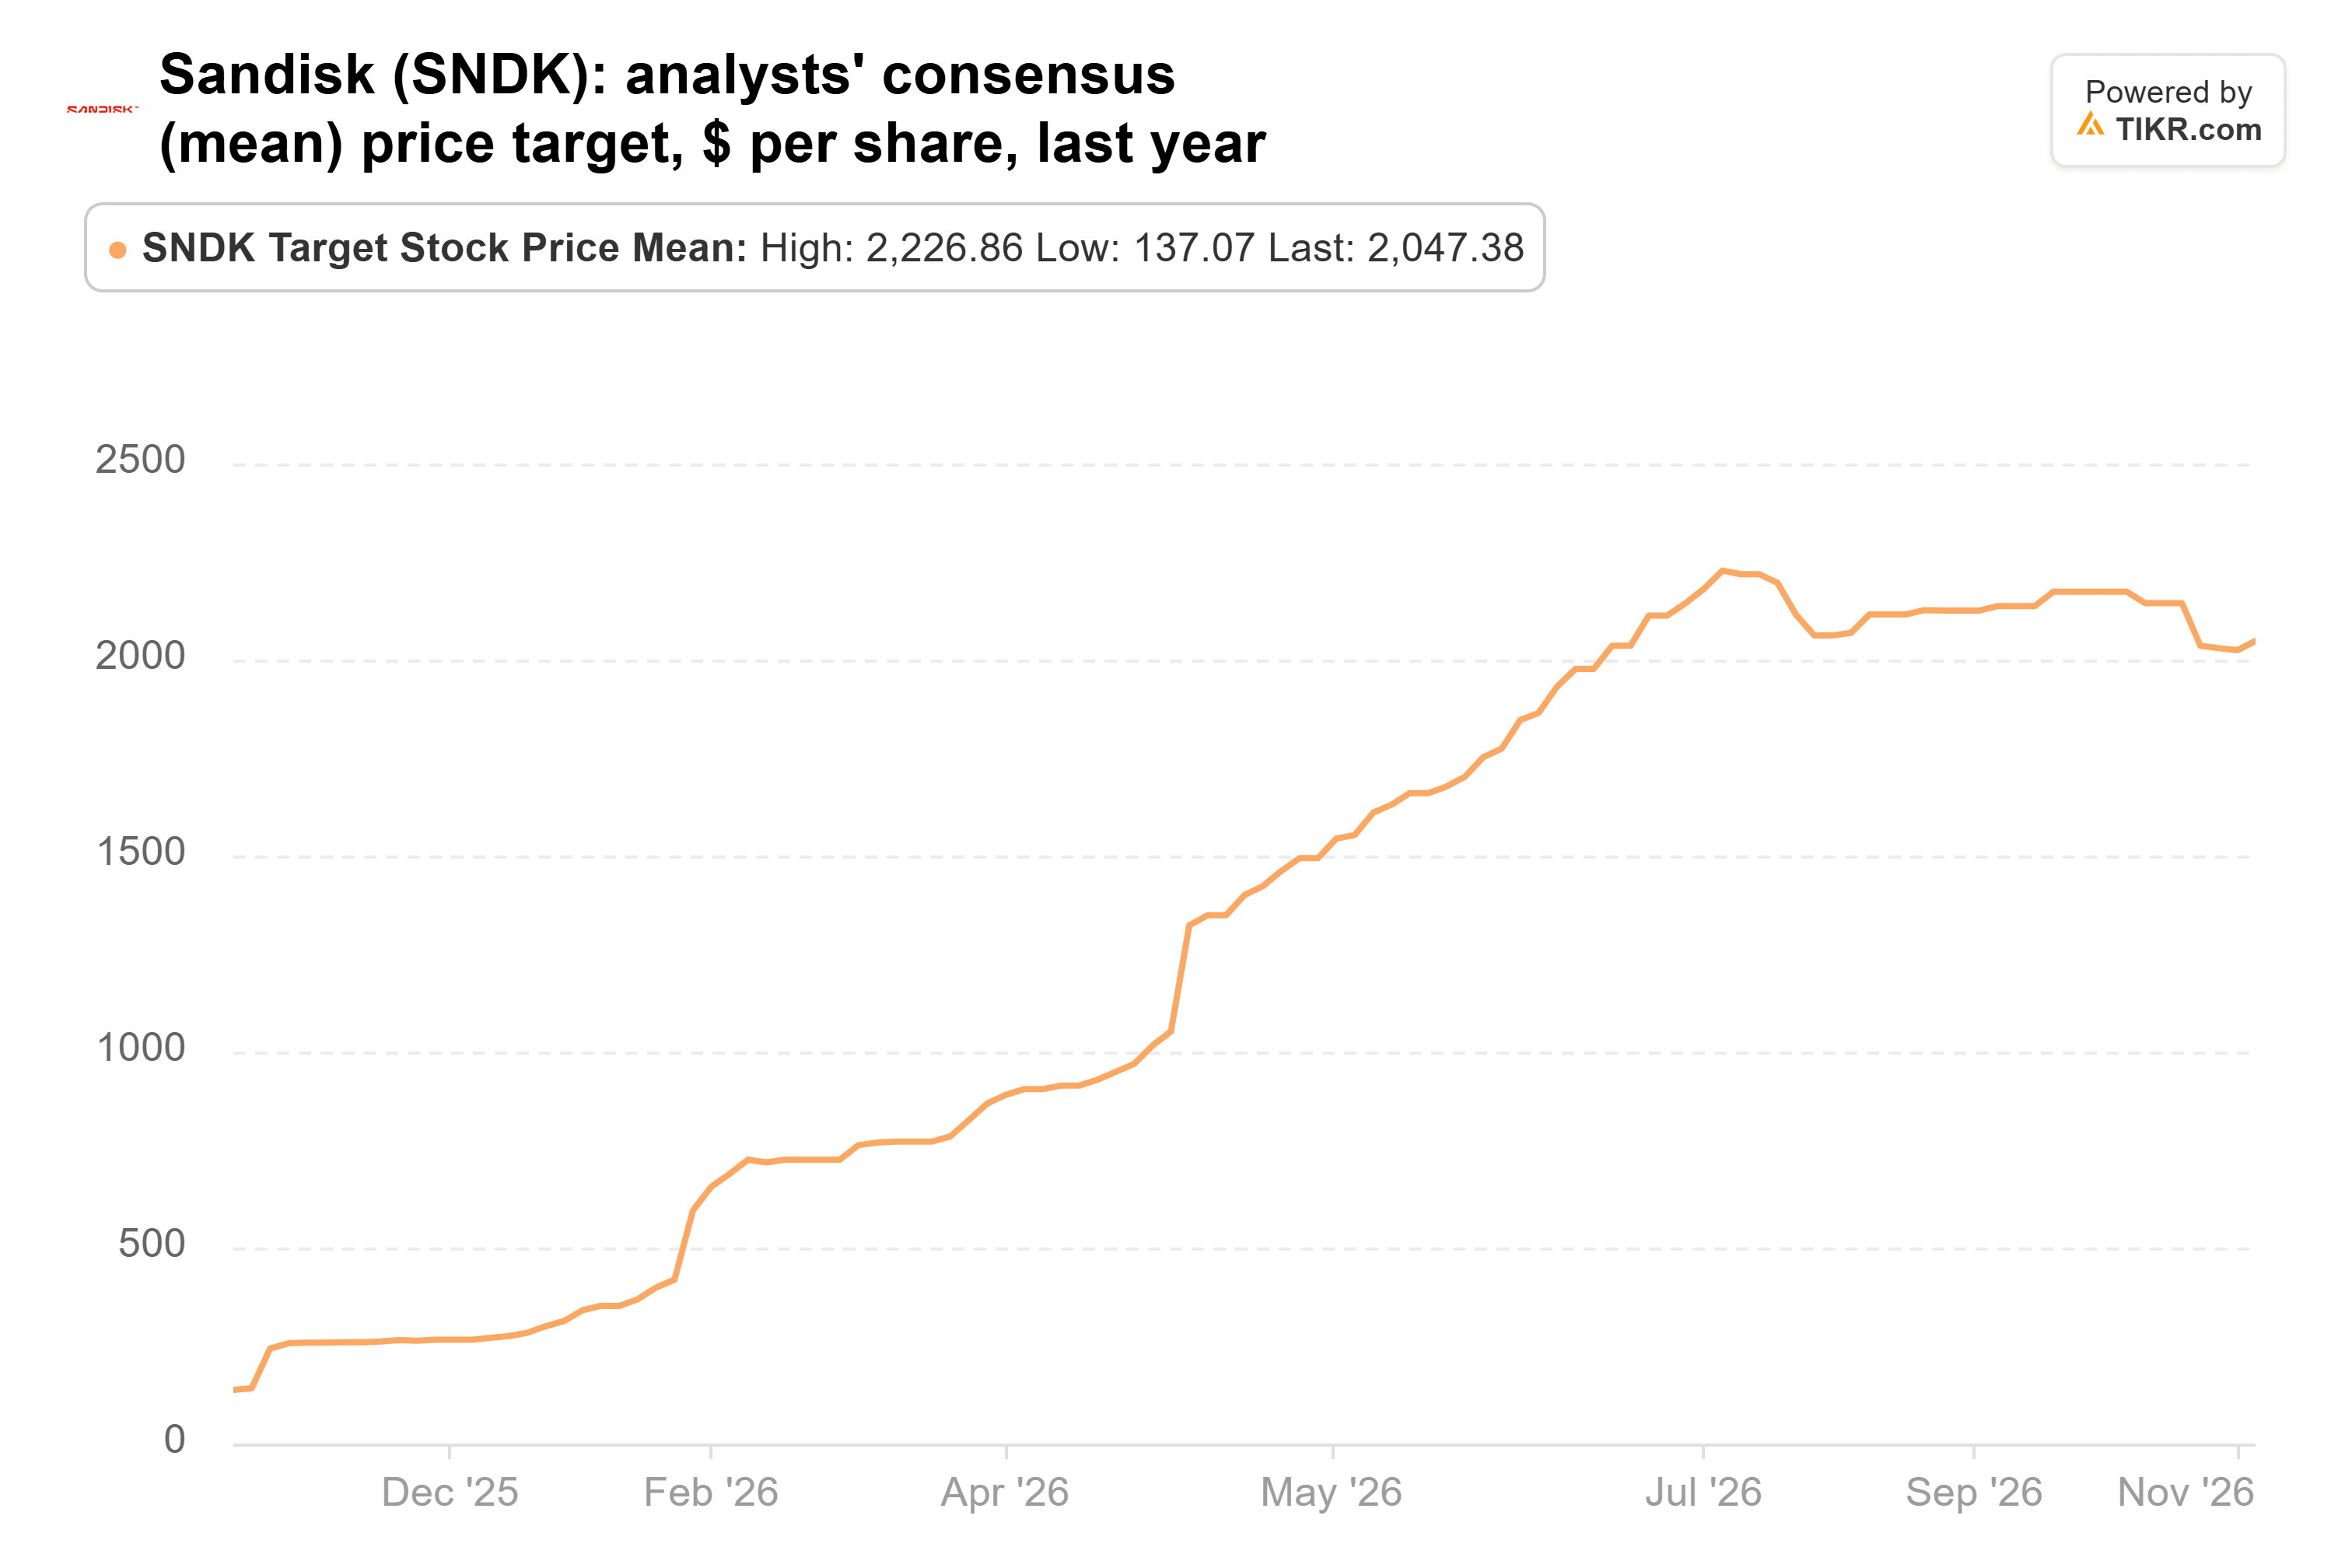
That average is $2,047, 118% above the Nov. 12 close, across 24 price targets ranging from $870 to Bernstein’s $3,000. Evercore’s sits 22% above it.
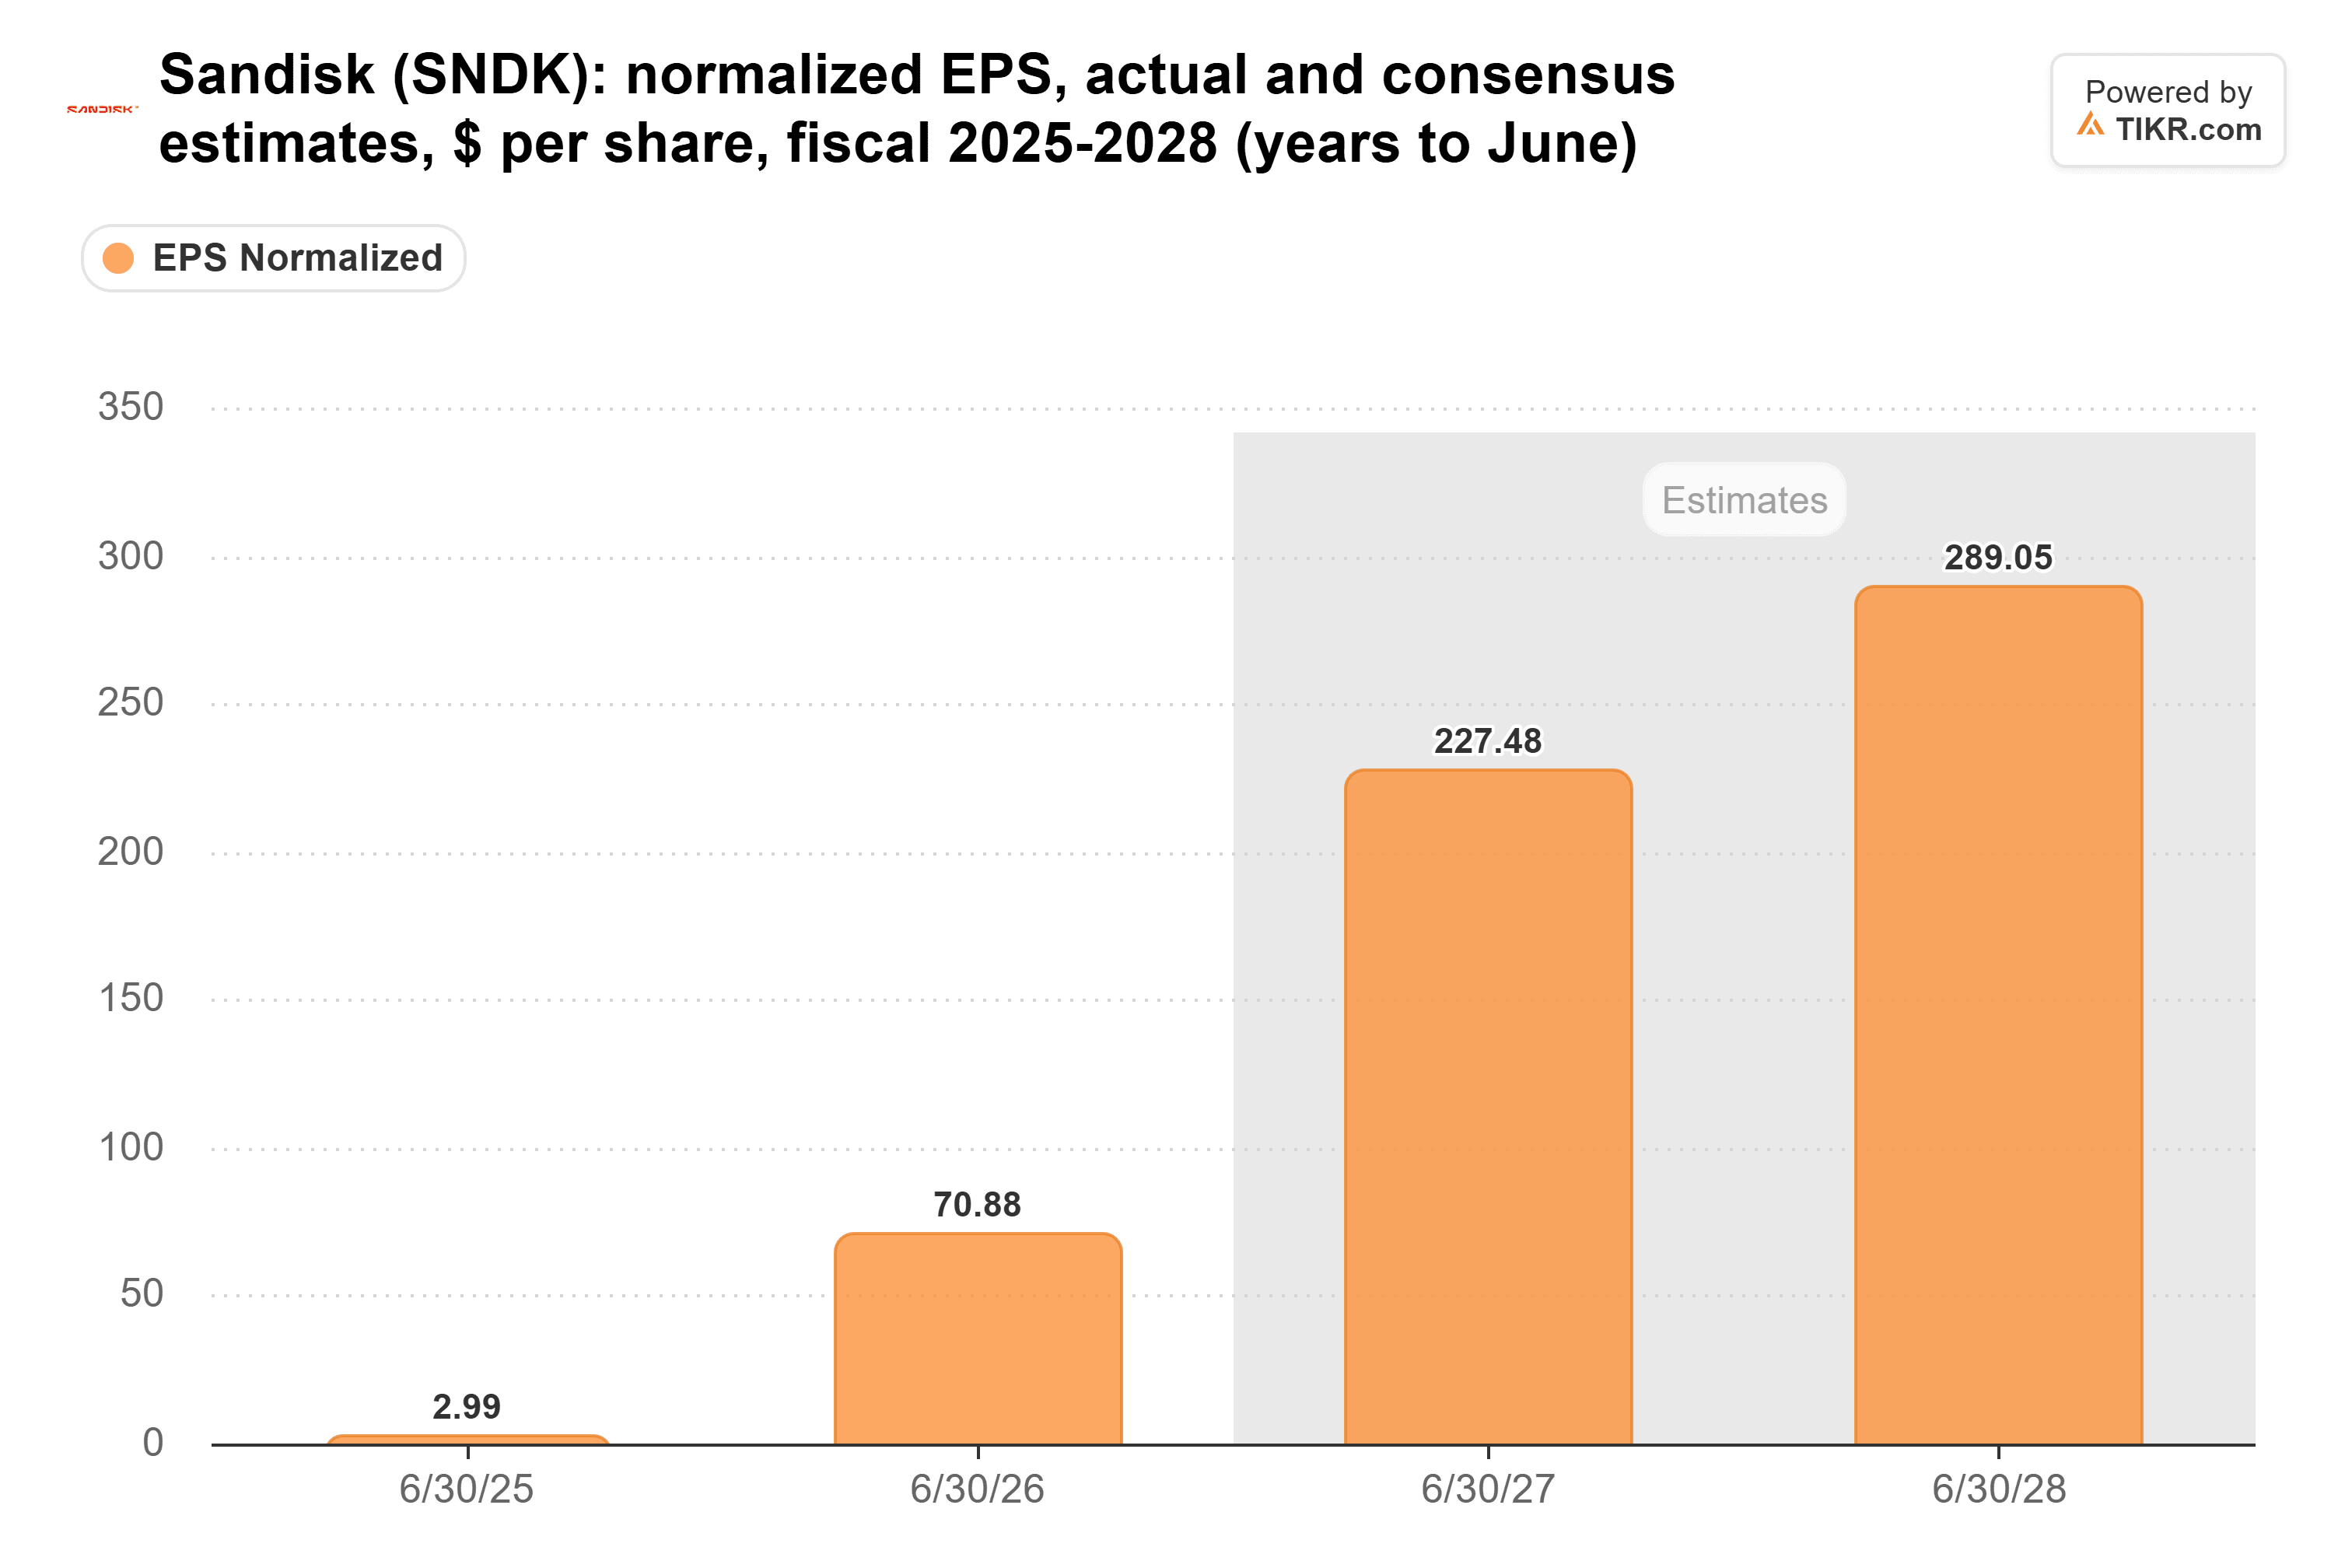
And analysts still expect earnings to more than triple this fiscal year, to $227.48 a share for the year to June 2027, from $70.88:
Yet the stock trades at 3.8x forward earnings, against an average of 10x over the past year:
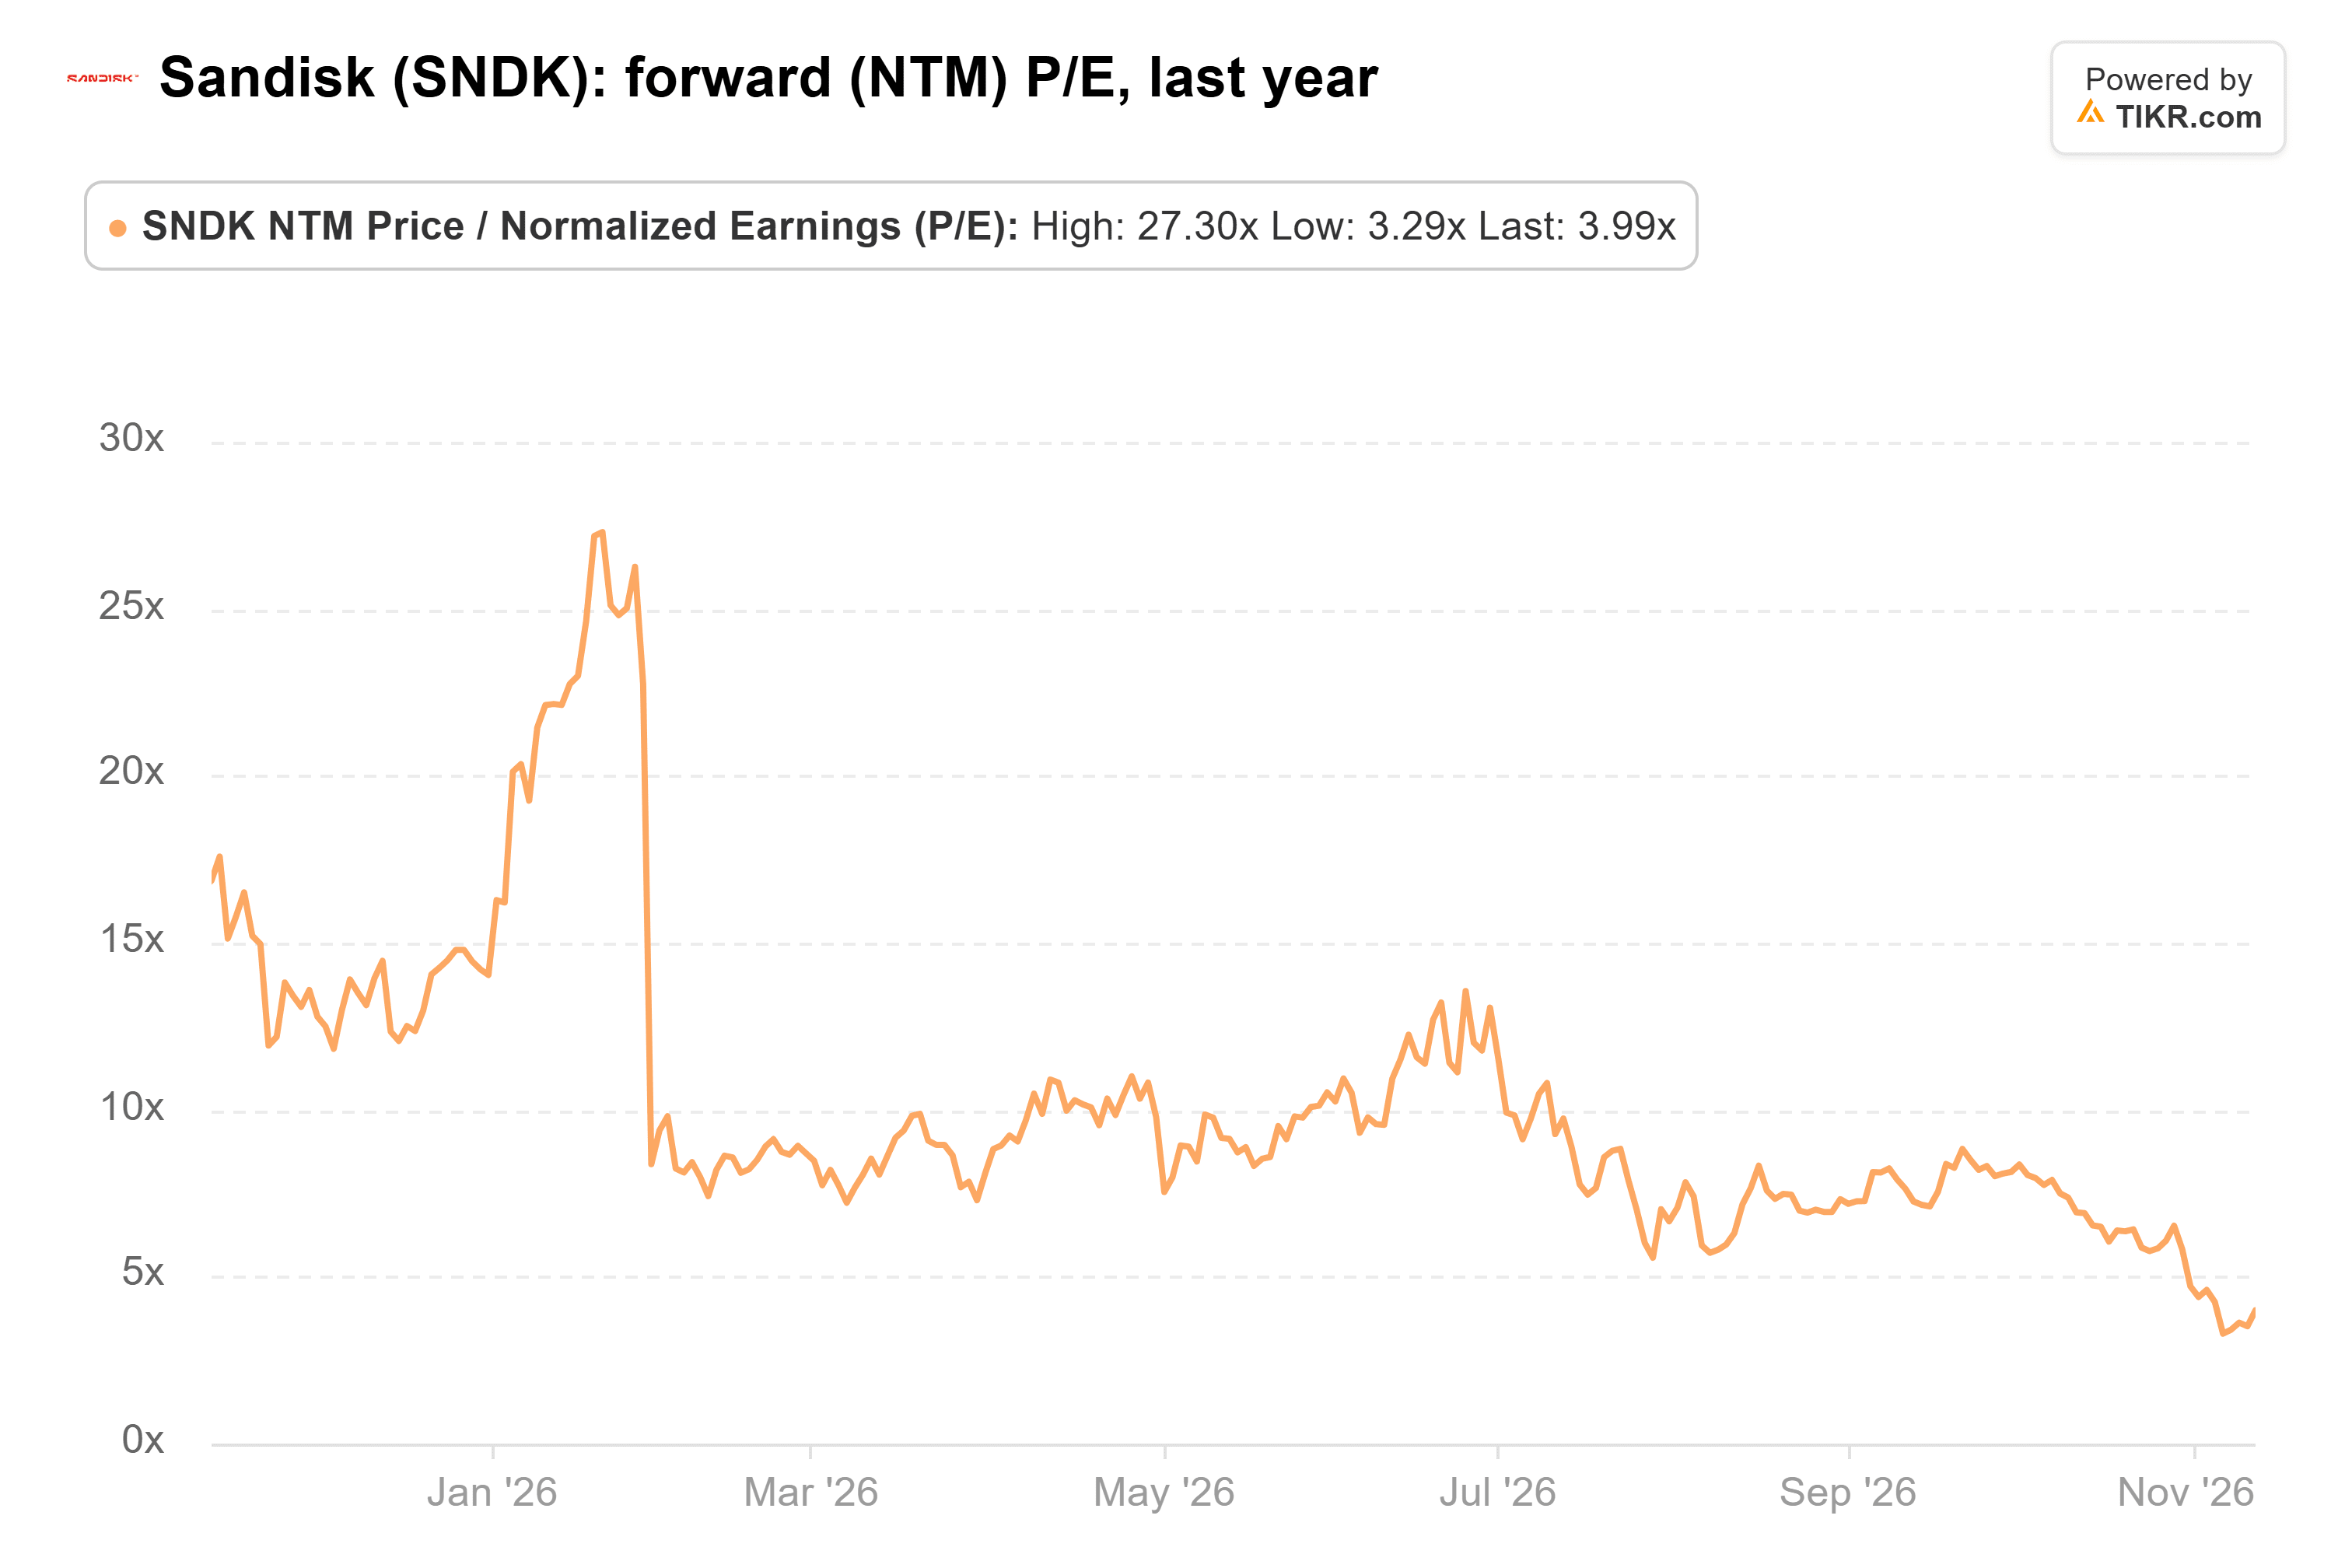
At $2,500, Sandisk would trade at 10x the roughly $245 a share analysts expect over the next twelve months, right at that average. At 3.8x, investors are betting these earnings fall, and the three analysts who estimate fiscal 2030 see earnings falling by about half from fiscal 2029.
Evercore has the better of this argument
Evercore’s case rests on the contracts, and they’re young. The first were signed earlier this year, and Sandisk expects only about a fifth of its $88.9 billion backlog to turn into revenue over the next 12 months.
Still, Daryanani looks right on this one. Getting back to an average multiple on today’s estimates is a modest ask, and investors paying 3.8x give the contracts almost no credit. The next test is the fiscal second-quarter report, expected in late January: the outlook for the March quarter, usually Sandisk’s weakest, and whether that backlog grows.
So what is Sandisk stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Sandisk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



