Key Takeaways
- Sandisk stock is down 51% in a month, including a 22% crash on Nov. 5, despite a record quarter.
- Kioxia signaled slowing flash price gains, Qualcomm blamed memory costs and shortages for weaker handset sales, and Micron and SK hynix sold off too.
- At about 3.4x forward earnings, the stock looks oversold if flash prices only level off.
- Bernstein’s $3,000 pre-split target works out to about 10.4x fiscal 2028 consensus EPS, against 2.9x at today’s price, so the Street’s $2,029 mean looks likelier.
Sandisk (SNDK) stock is down 51% in the past month, including a 22% crash on Nov. 5, right after a record quarter. The worry came from the companies around it: fab partner Kioxia (285A) said its flash price gains are slowing, and Qualcomm (QCOM) blamed memory costs for a 26% drop in its handset chip revenue.
Micron (MU) and SK hynix (SKHY) sold off too. Bernstein hasn’t moved: its Outperform rating and $3,000 target (pre-split) still stand, 259% above the current $835.06.
A Record Quarter Didn’t Help Sandisk
In the quarter to Oct. 2, revenue rose 23% from the prior quarter to $11.0 billion, on an 85.1% adjusted gross margin. Sandisk guided fiscal second-quarter revenue to $12.2 billion to $12.6 billion and announced an 8-for-1 split. The stock still fell 13.5% the next day in a broad chip selloff.
Higher prices drove about 40% of the quarter’s sequential growth, management said, down from about two-thirds the quarter before.
TIKR Tracks 25 Analysts on Sandisk. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Sandisk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Sandisk’s Analyst Ratings
Buyers Are Feeling the Prices
Kioxia put numbers on the slowdown: its NAND price gains cooled to the mid-20s percent in the September quarter, from about 70%, and it guided December-quarter operating profit flat at about ¥2 trillion (about $12.7 billion).
Qualcomm, down 9% over the month, showed what those prices do to buyers. It tied a 26% fall in handset revenue, to $5.14 billion in the quarter to Sept. 27, to “industry-wide memory dynamics on the global smartphone market.”
That matters here: Edge and consumer, Sandisk’s phone, PC and retail business, made up 56.5% of its revenue last quarter. Micron, down 36%, gets about a quarter of its revenue from phone and PC makers. SK hynix, down 35%, still expects memory demand to outrun supply through 2030.
Then Democrats swept the Nov. 3 midterms, and investors dumped AI-infrastructure stocks on fears of slower data-center permits.
What Bernstein’s $3,000 Needs
Analysts haven’t cut yet. Consensus has normalized EPS climbing from $70.88 in fiscal 2026 to $227.80 in fiscal 2027 and $287.26 in fiscal 2028:
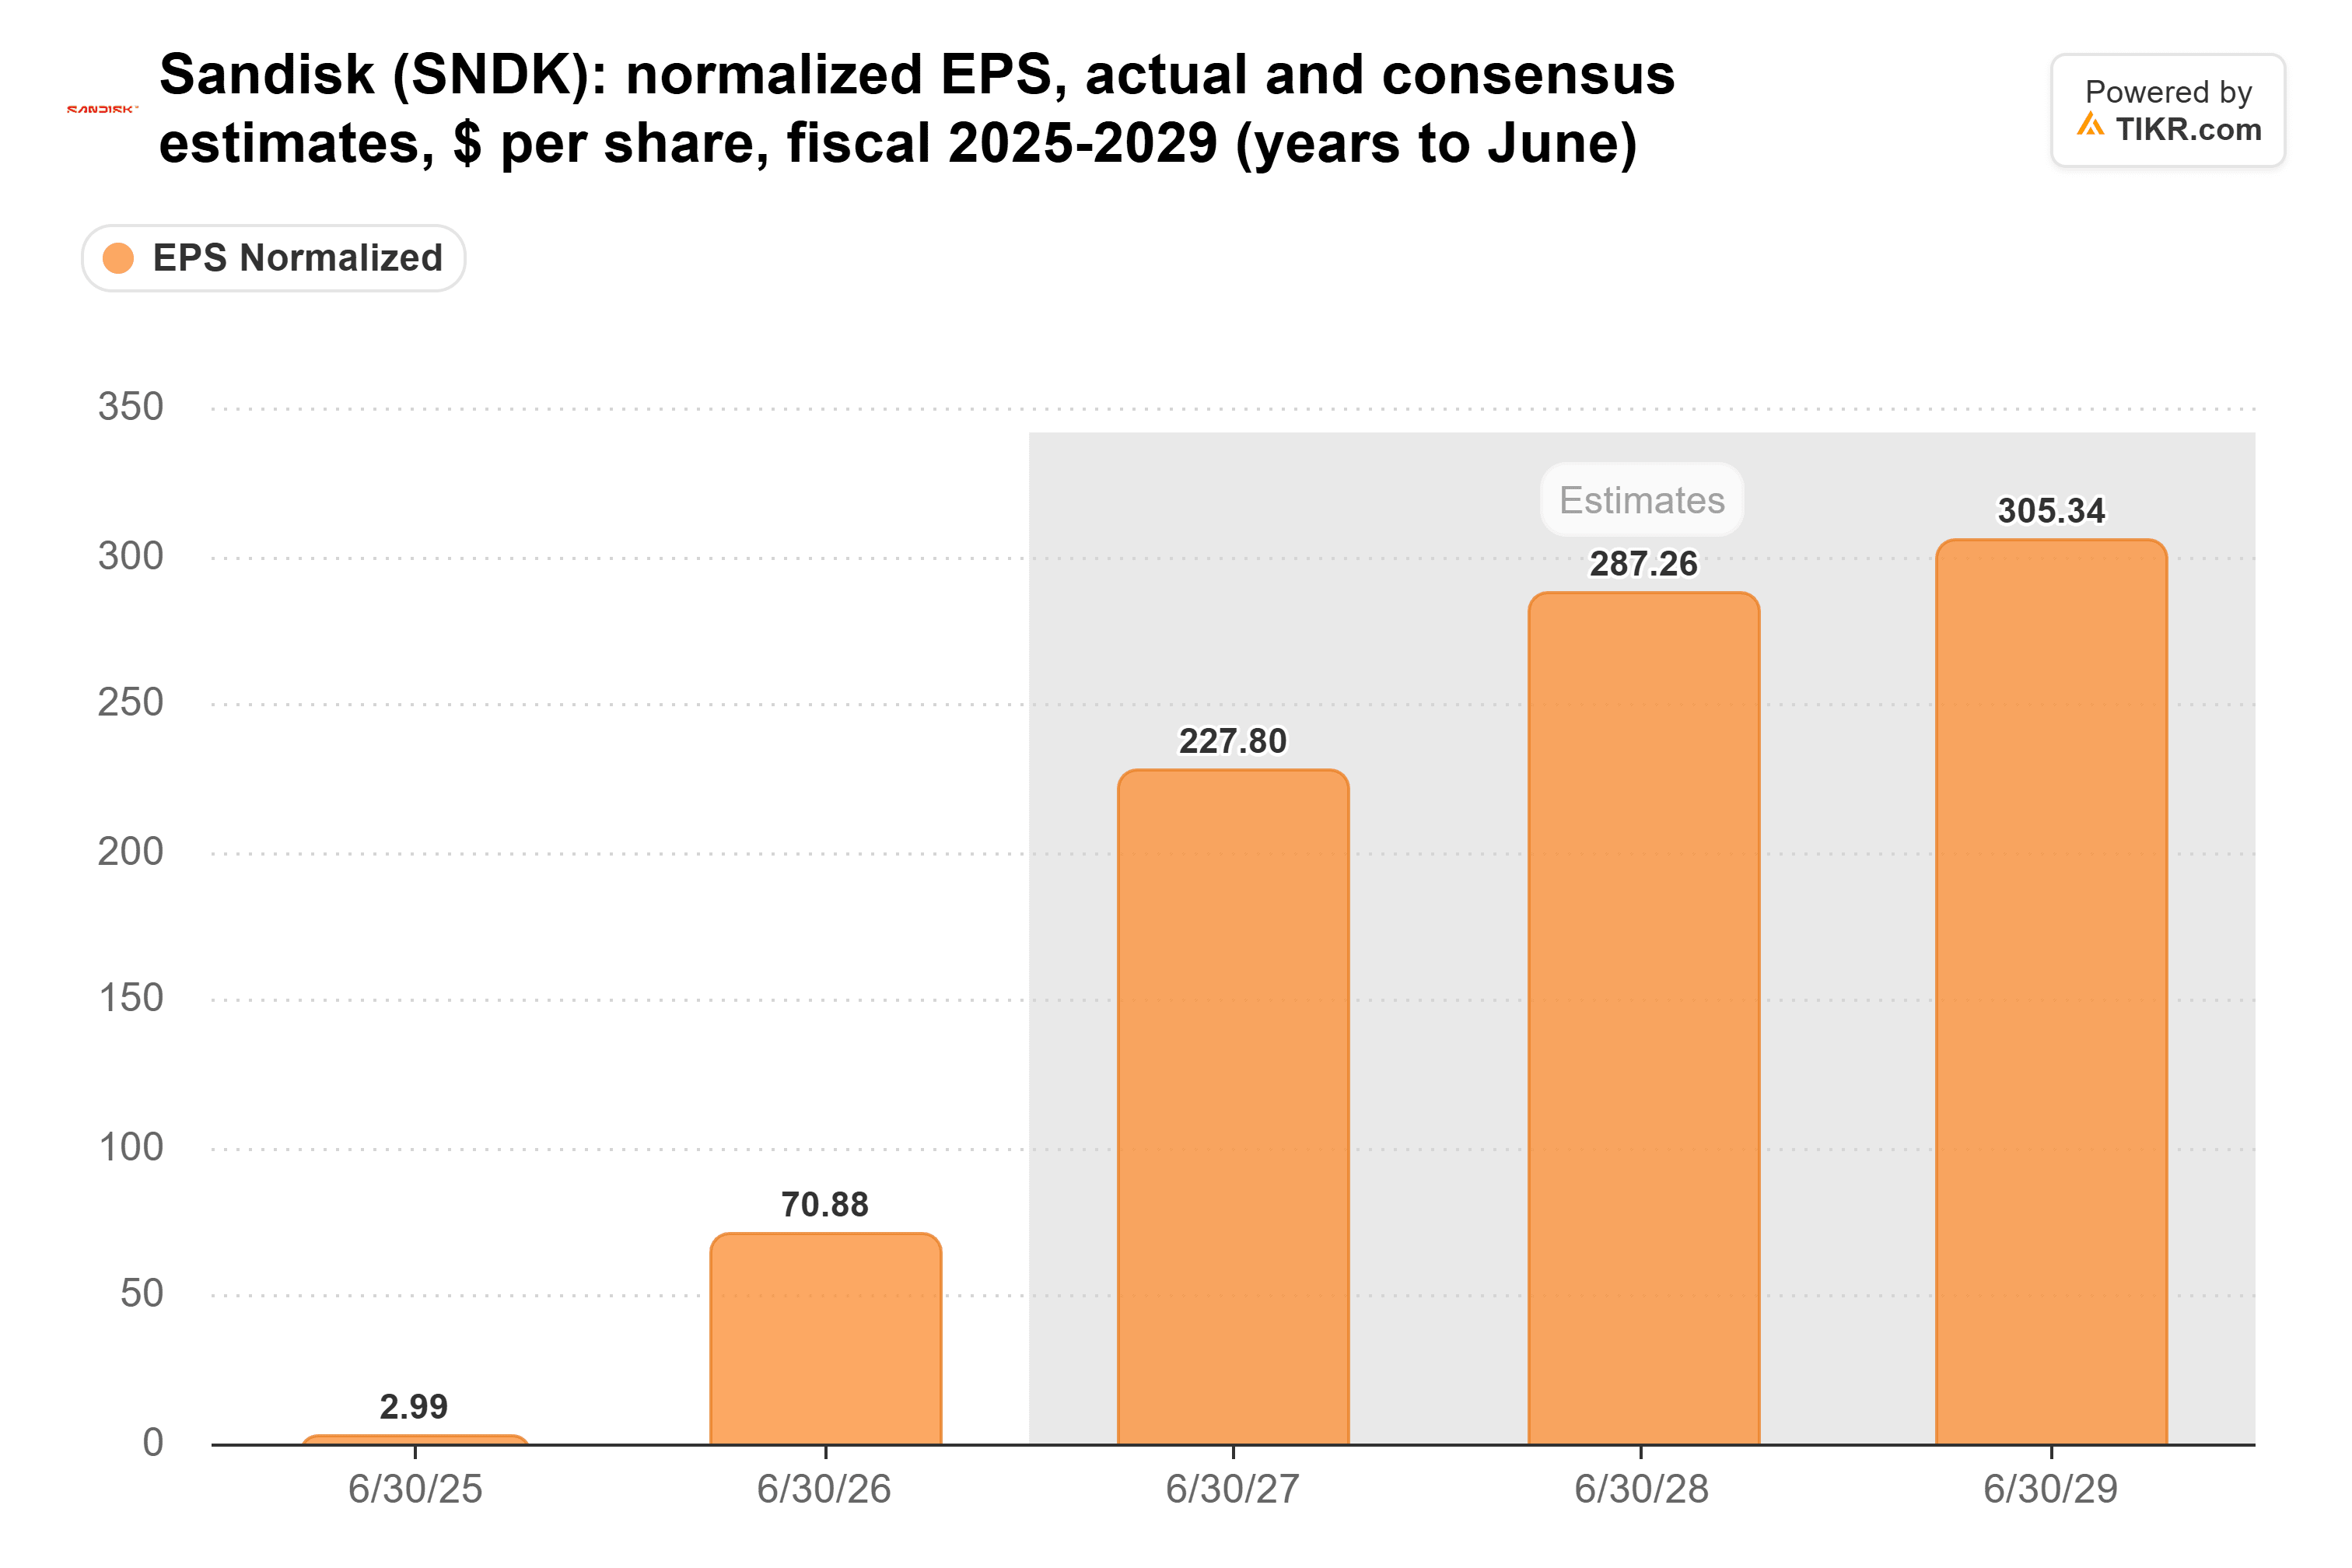
The cushion is Sandisk’s multiyear contracts, covering about half of fiscal 2027’s bits and two-thirds of fiscal 2028’s, at floors that management says still earn about an 80% gross margin. Bernstein’s case leans on those floors.
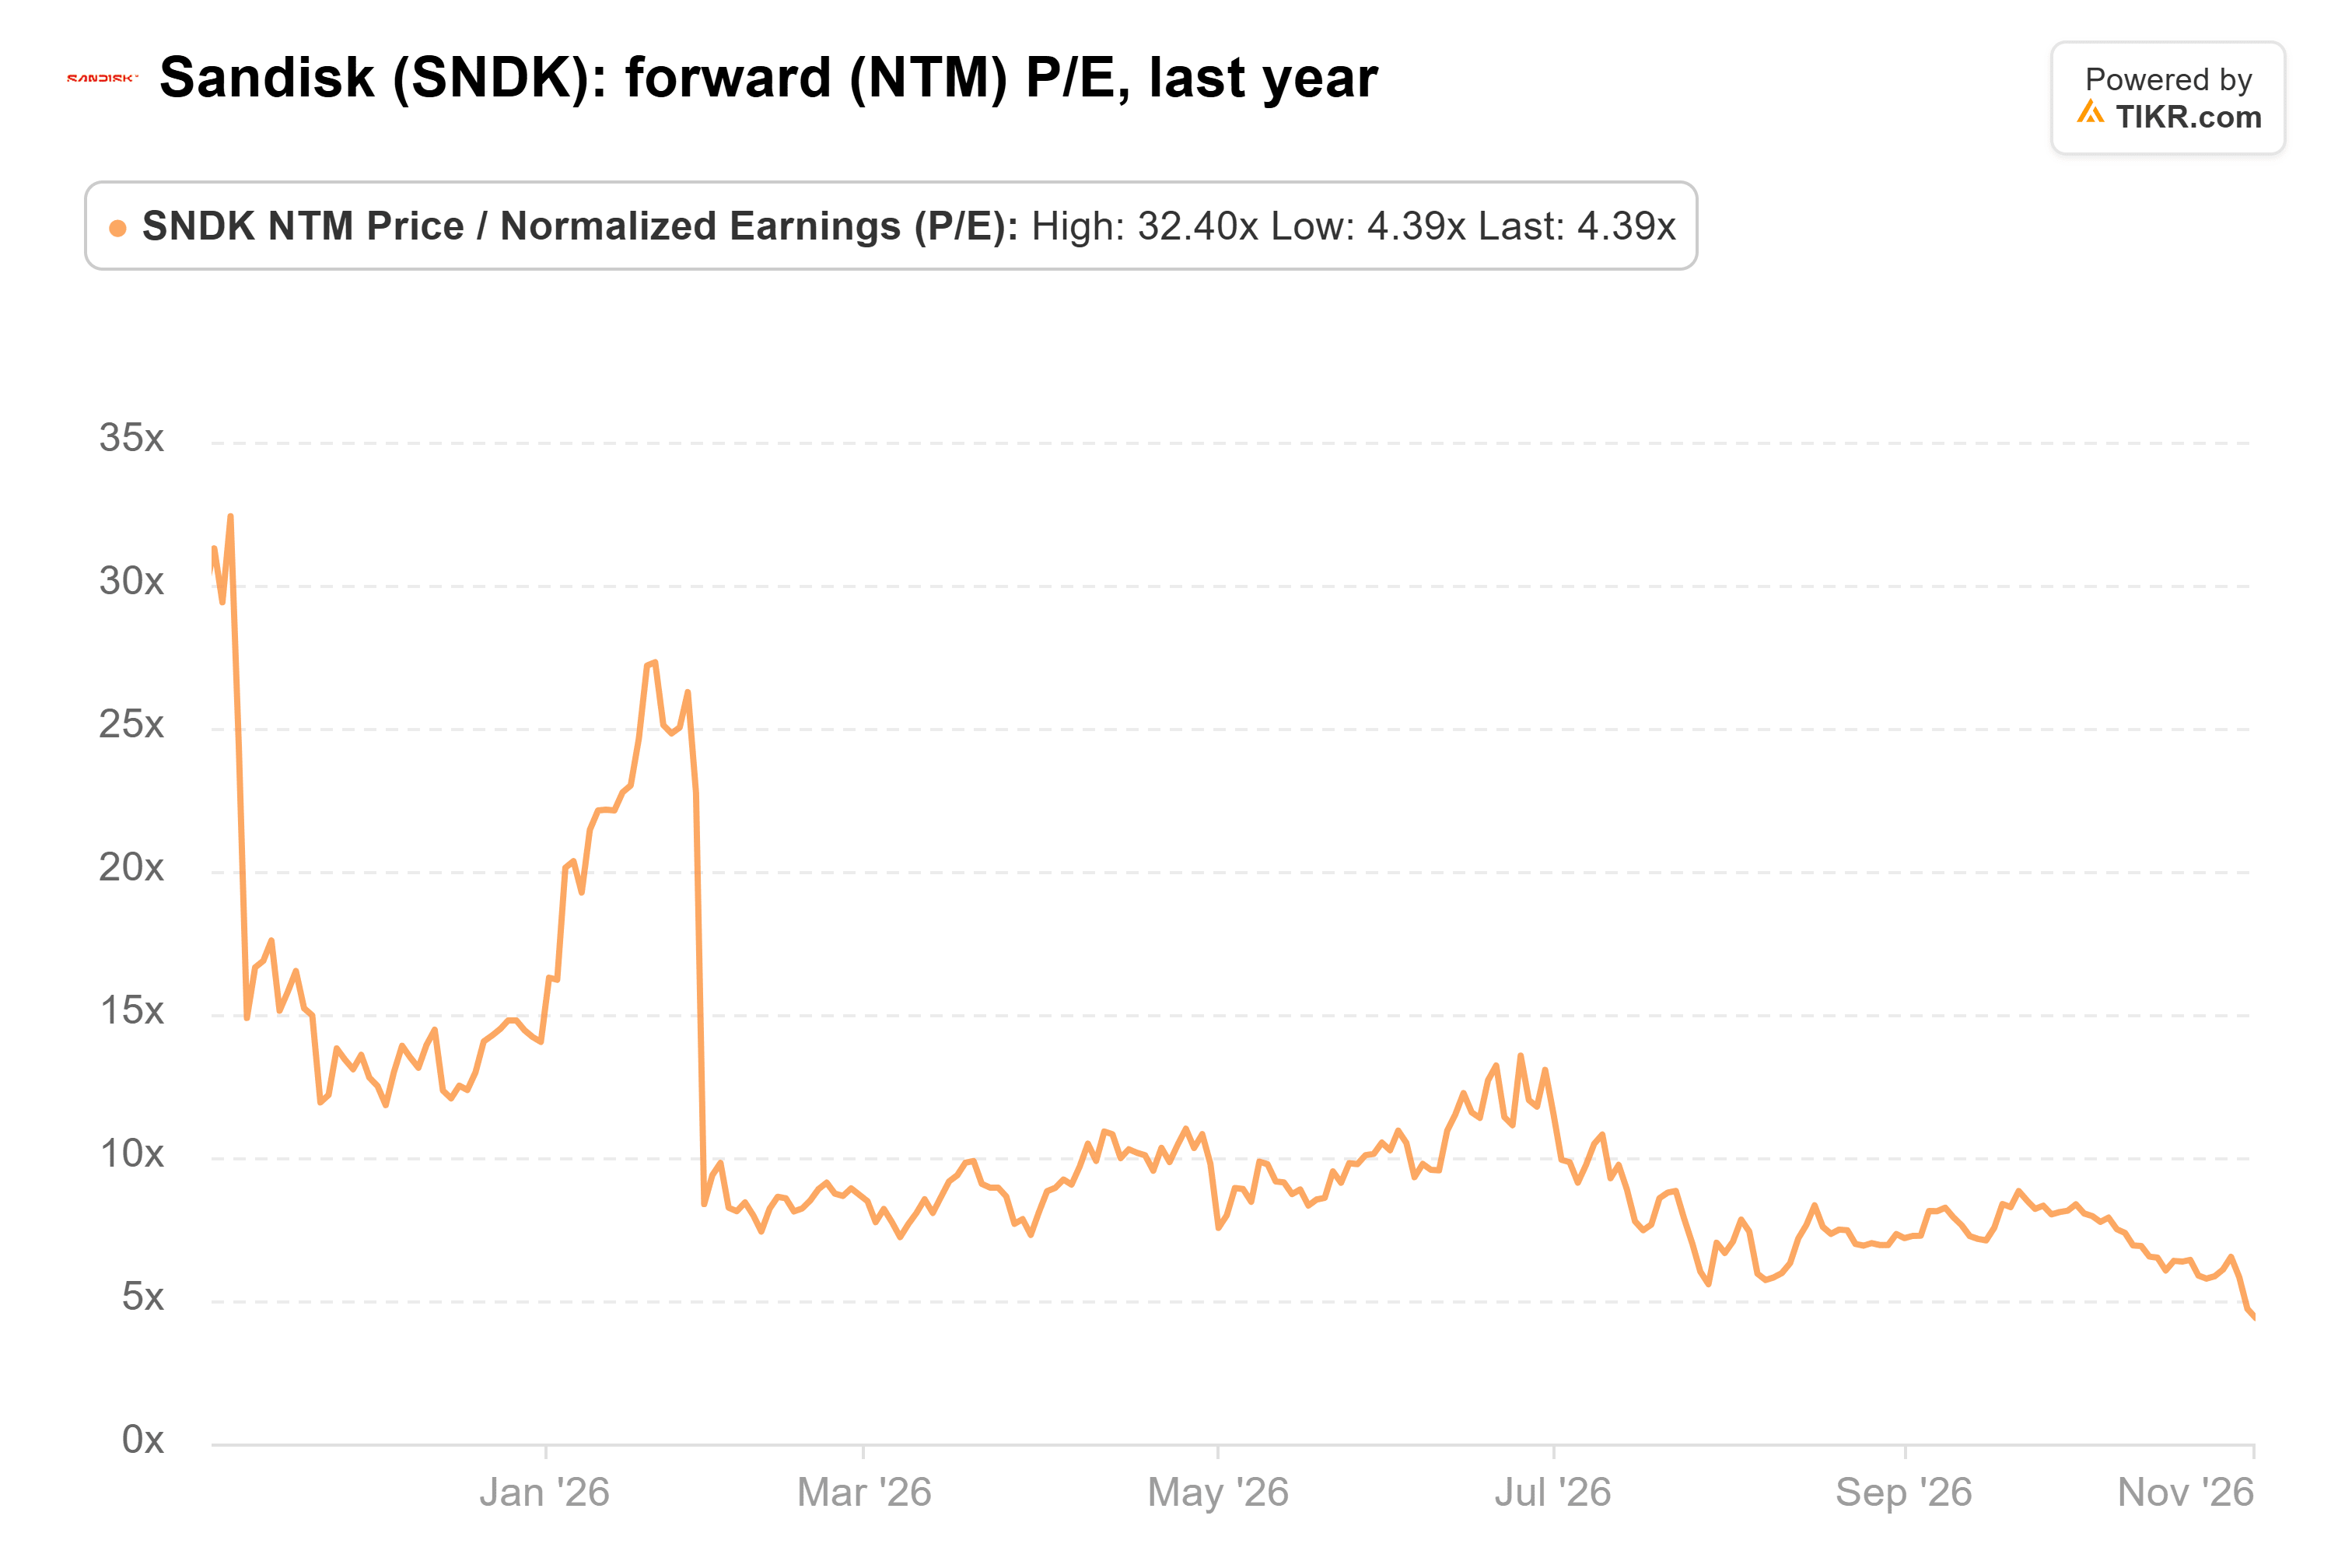
The market is pricing in a bust anyway. The forward P/E hit 4.4x on Nov. 2, a one-year low, against a 10.8x average, and it’s about 3.4x now:
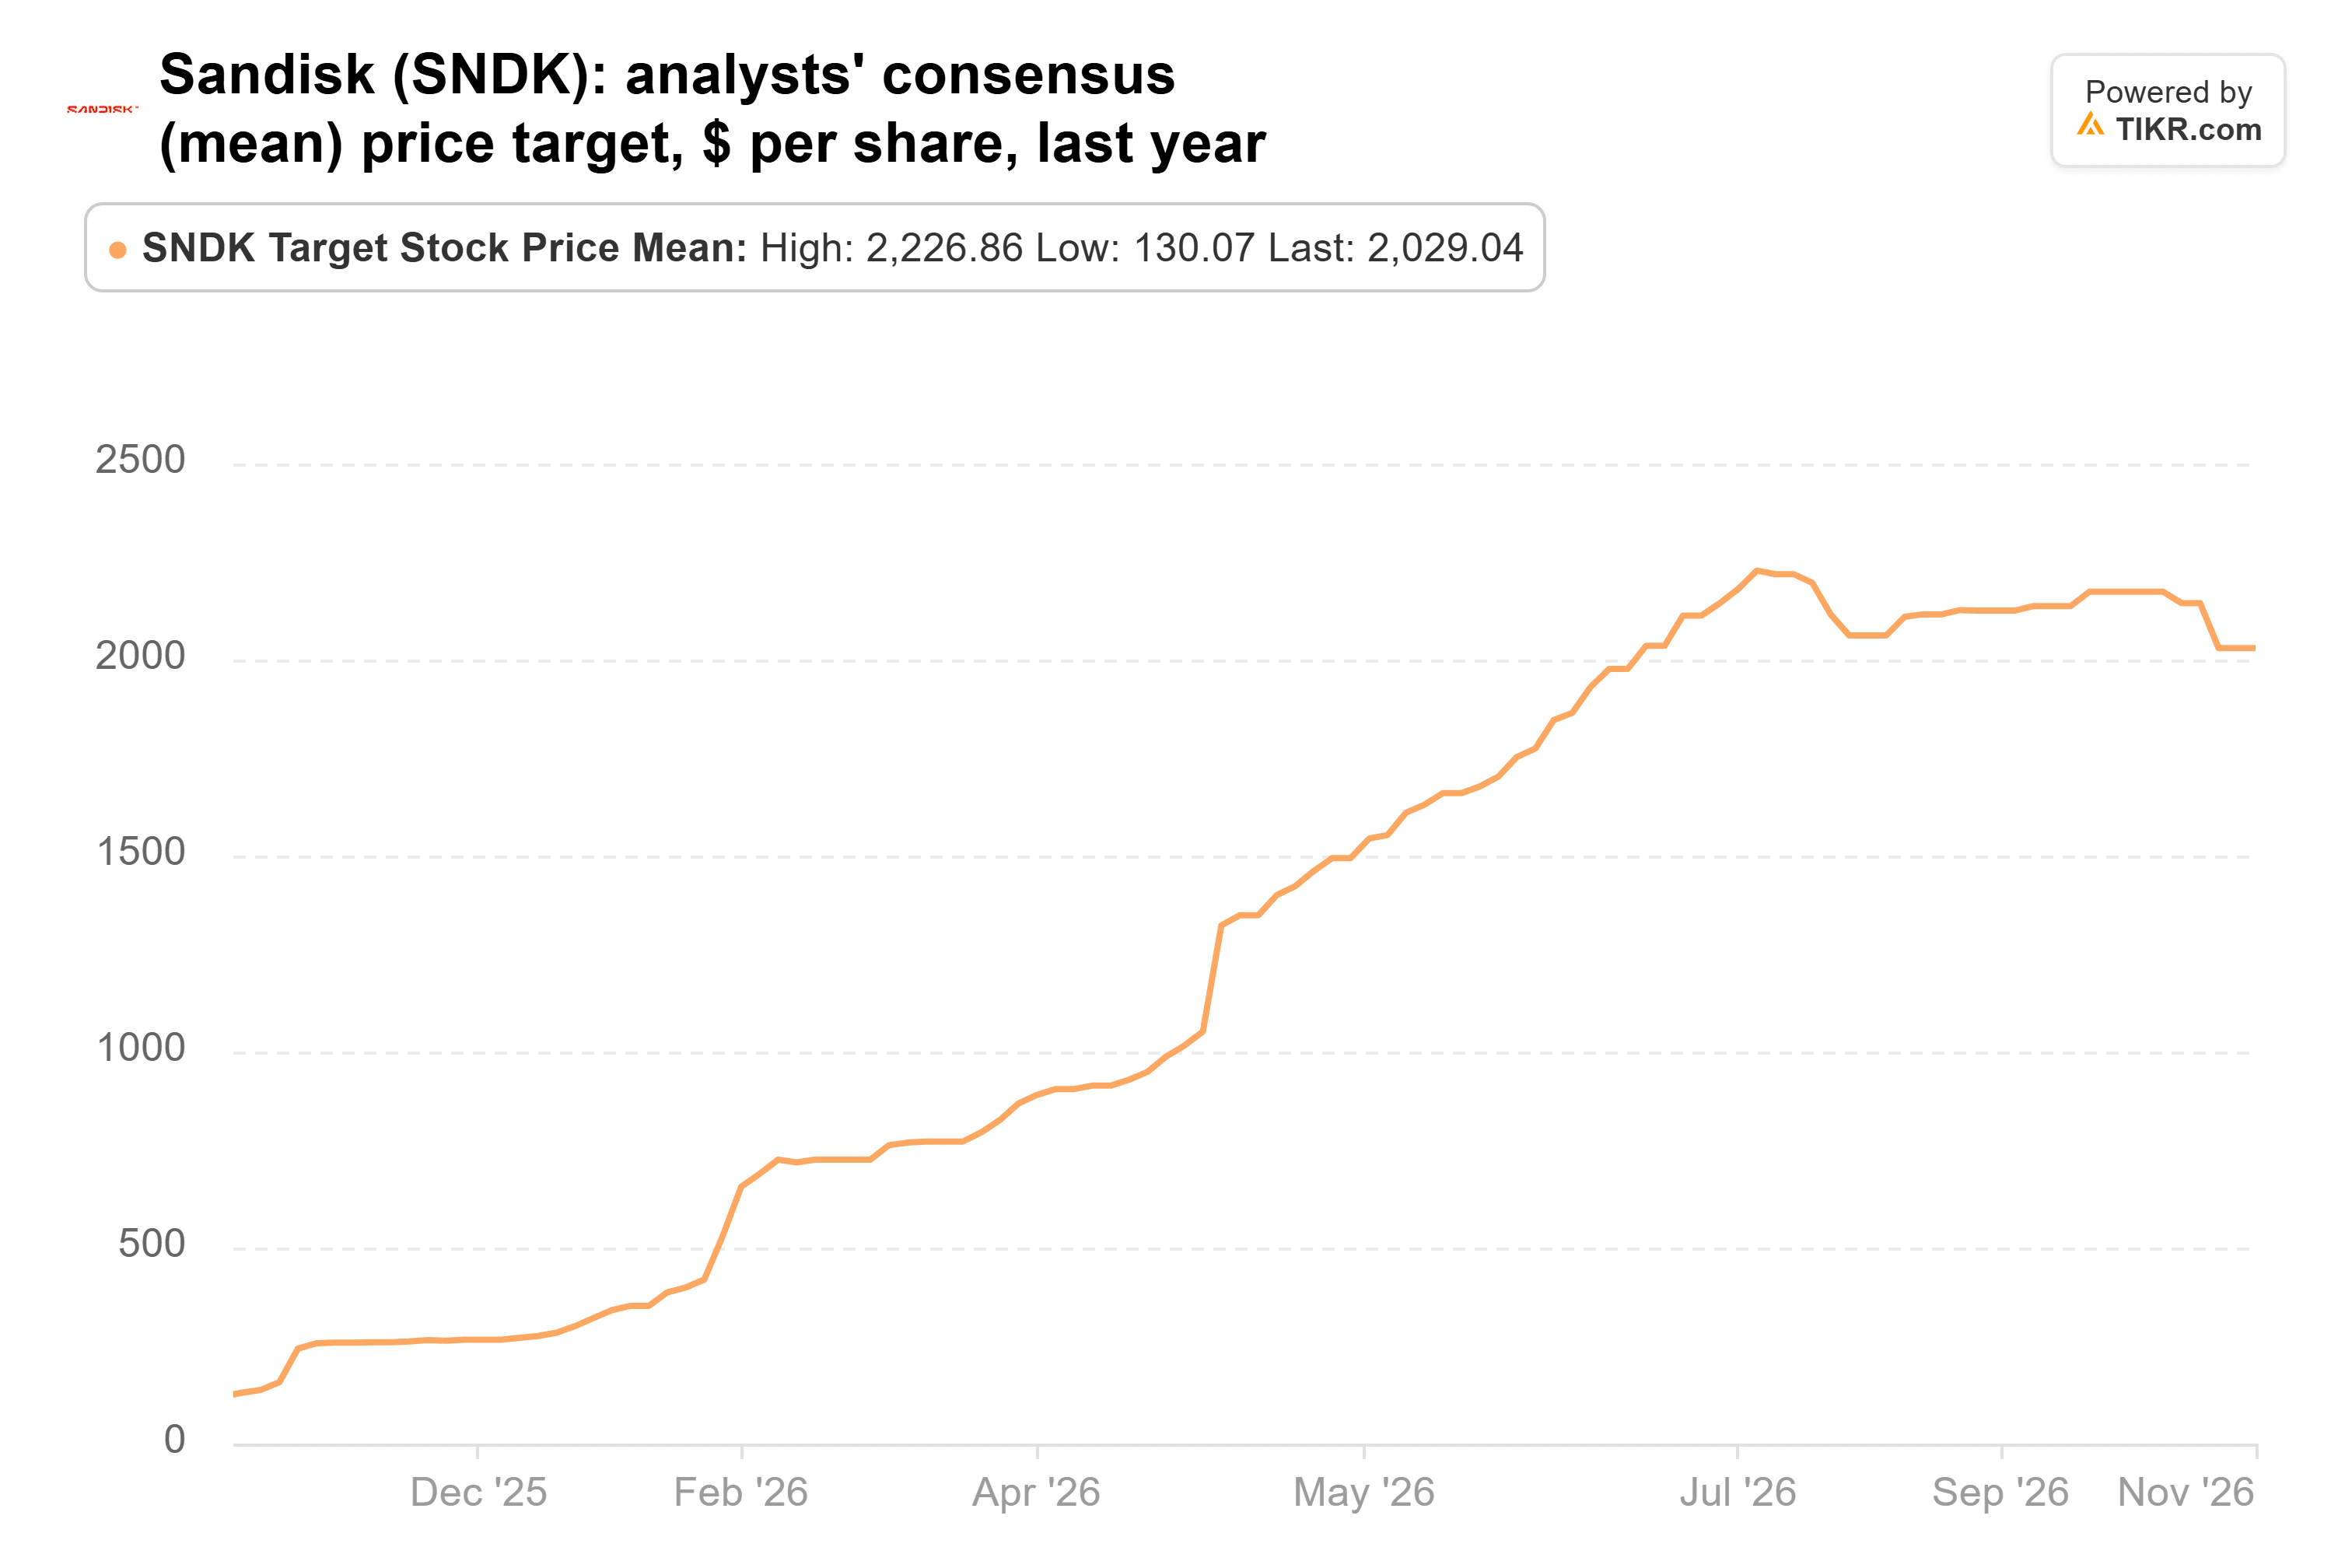
Bernstein’s $3,000 is about 10.4x the fiscal 2028 consensus estimate, against 2.9x at today’s price. The rest of the Street is more careful, with a mean target of $2,029 and a low of $870:
Conclusion
At about 3.4x forward earnings, with floors under half of next year’s output, Sandisk looks oversold. But $3,000 works out to about 10.4x consensus fiscal 2028 EPS, against 2.9x at today’s price, and Qualcomm’s quarter puts the handset side of those estimates at risk. The $2,029 mean, still more than double the price, is the likelier landing.
Watch the 85% margin: if flash prices fall instead of flattening, it gives first. After the Nov. 20 split, those targets become $375 and about $254.
So What Is Sandisk Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Sandisk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!