Key Takeaways
- Sandisk stock jumped 7% today as chip stocks bounced back from Thursday’s selloff.
- IREN’s strong AI-cloud report eased fears about data-center spending, but Sandisk’s worries about flash prices and Chinese supply remain.
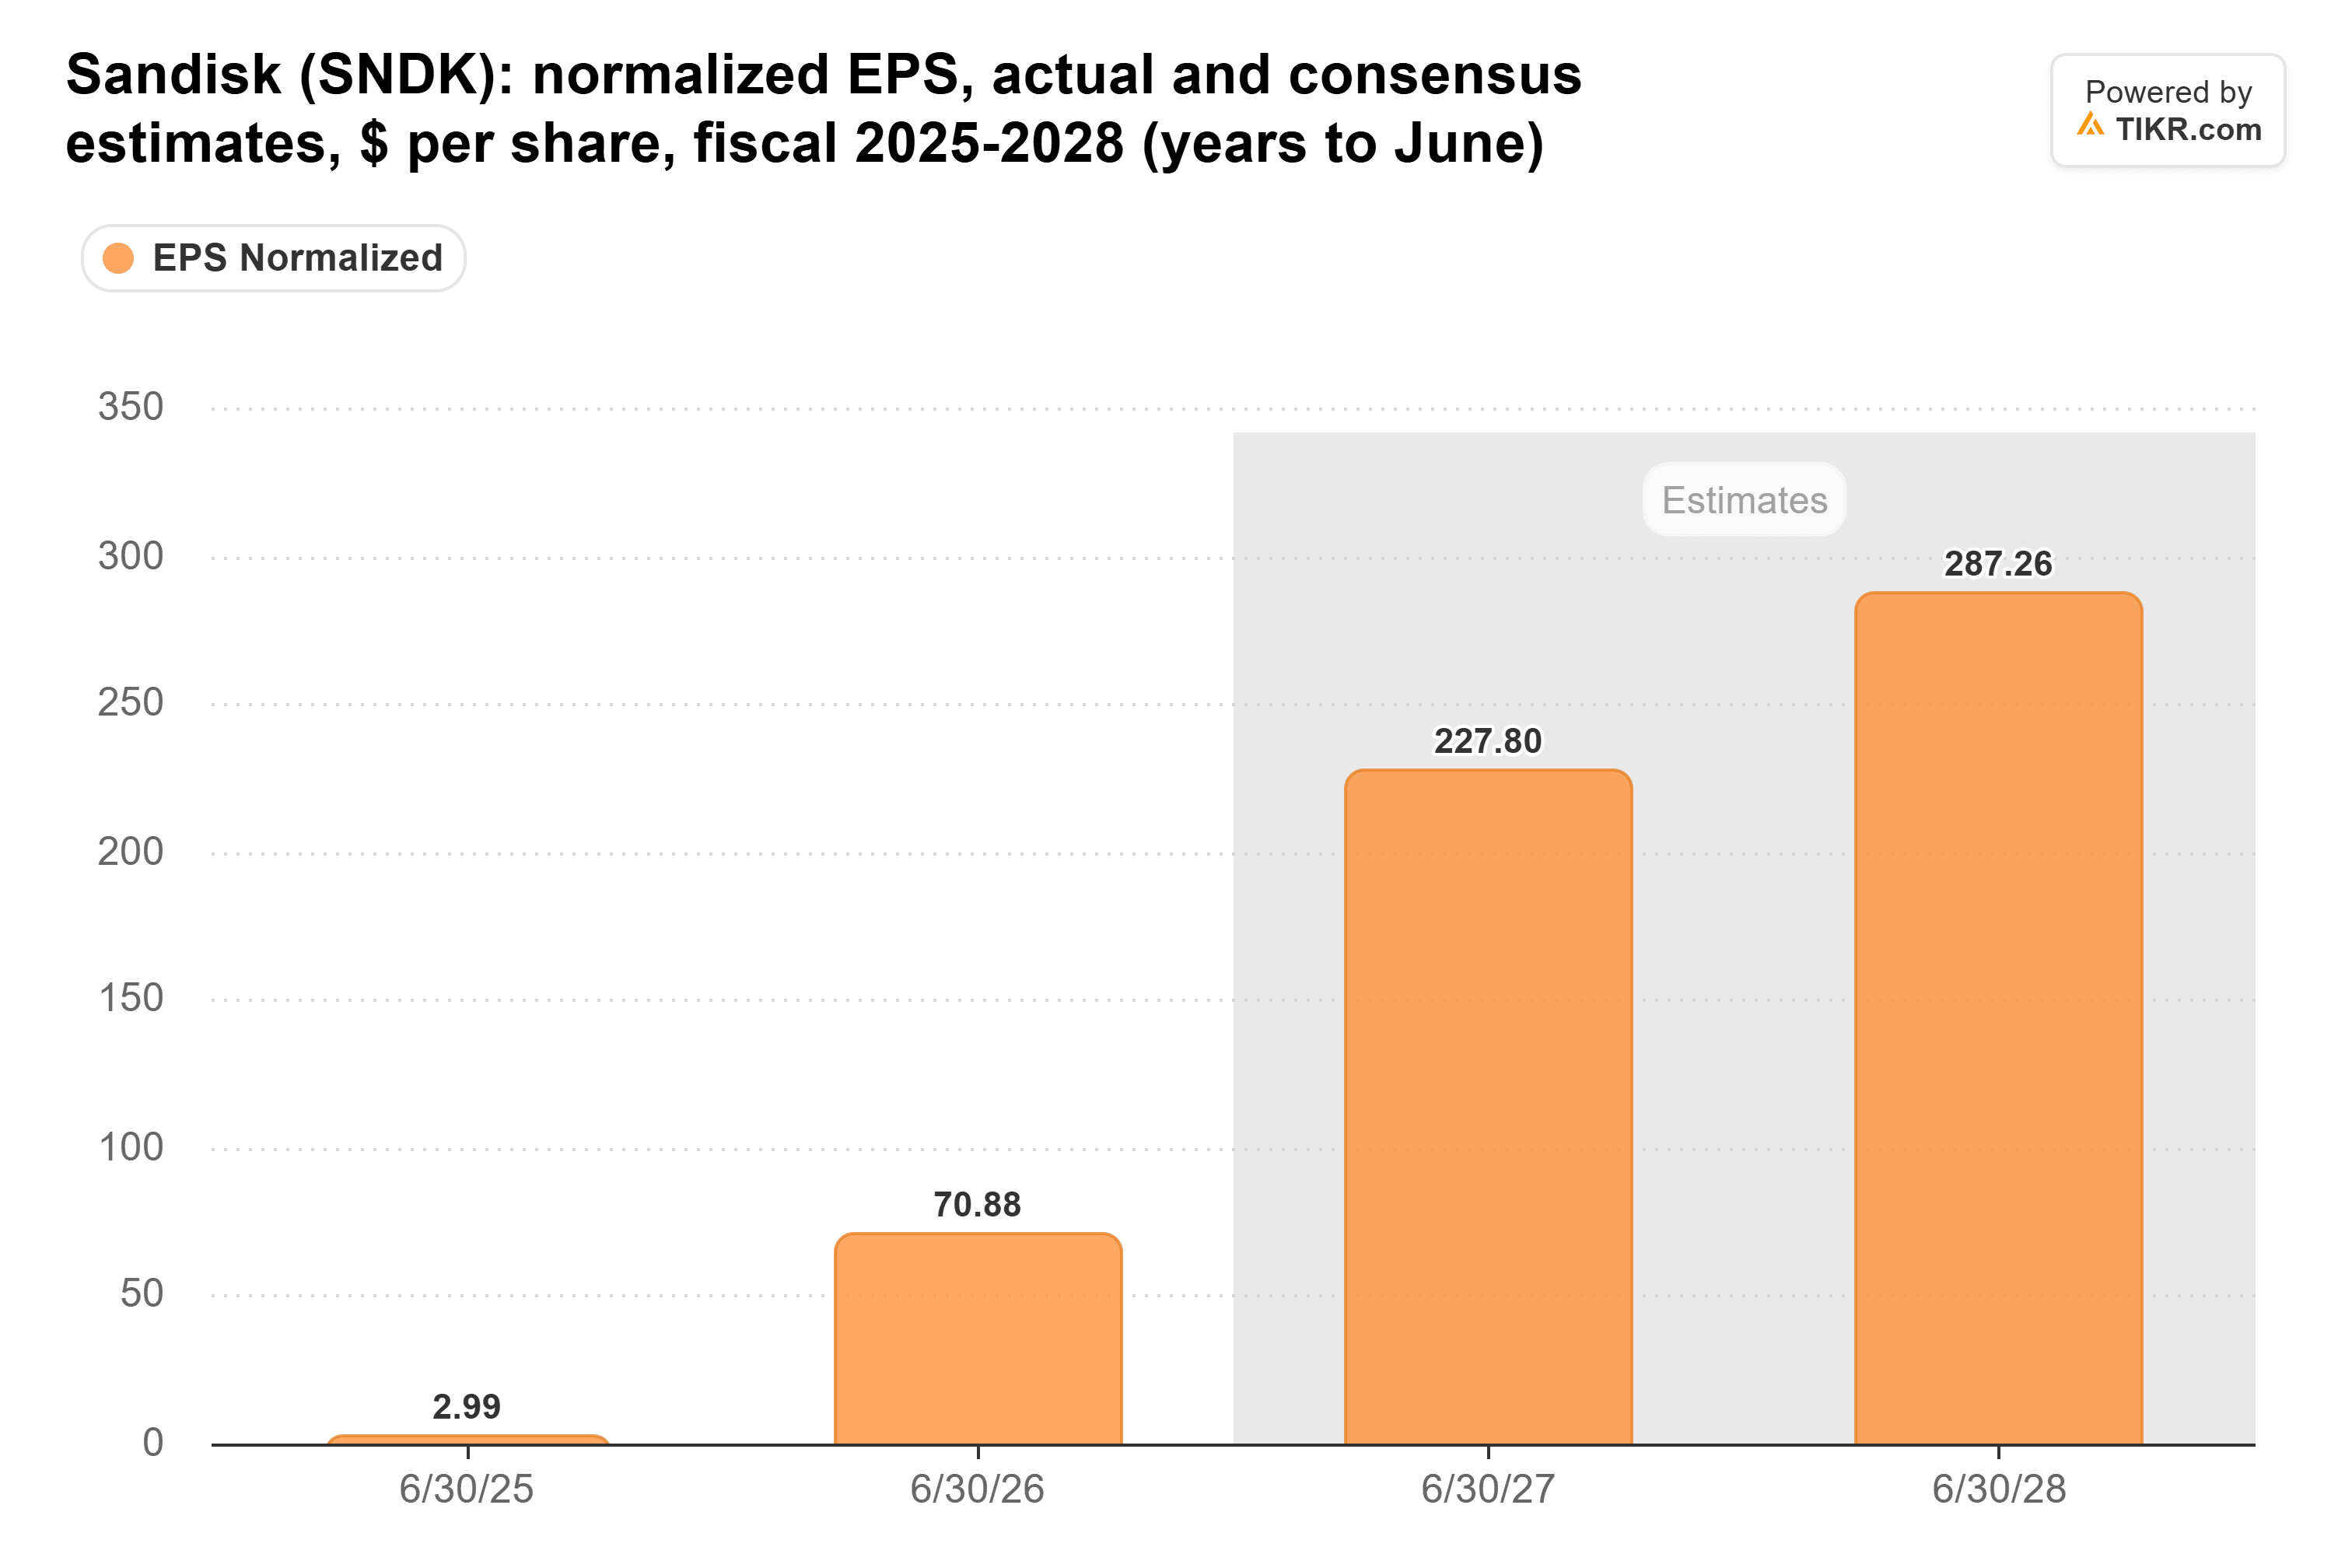
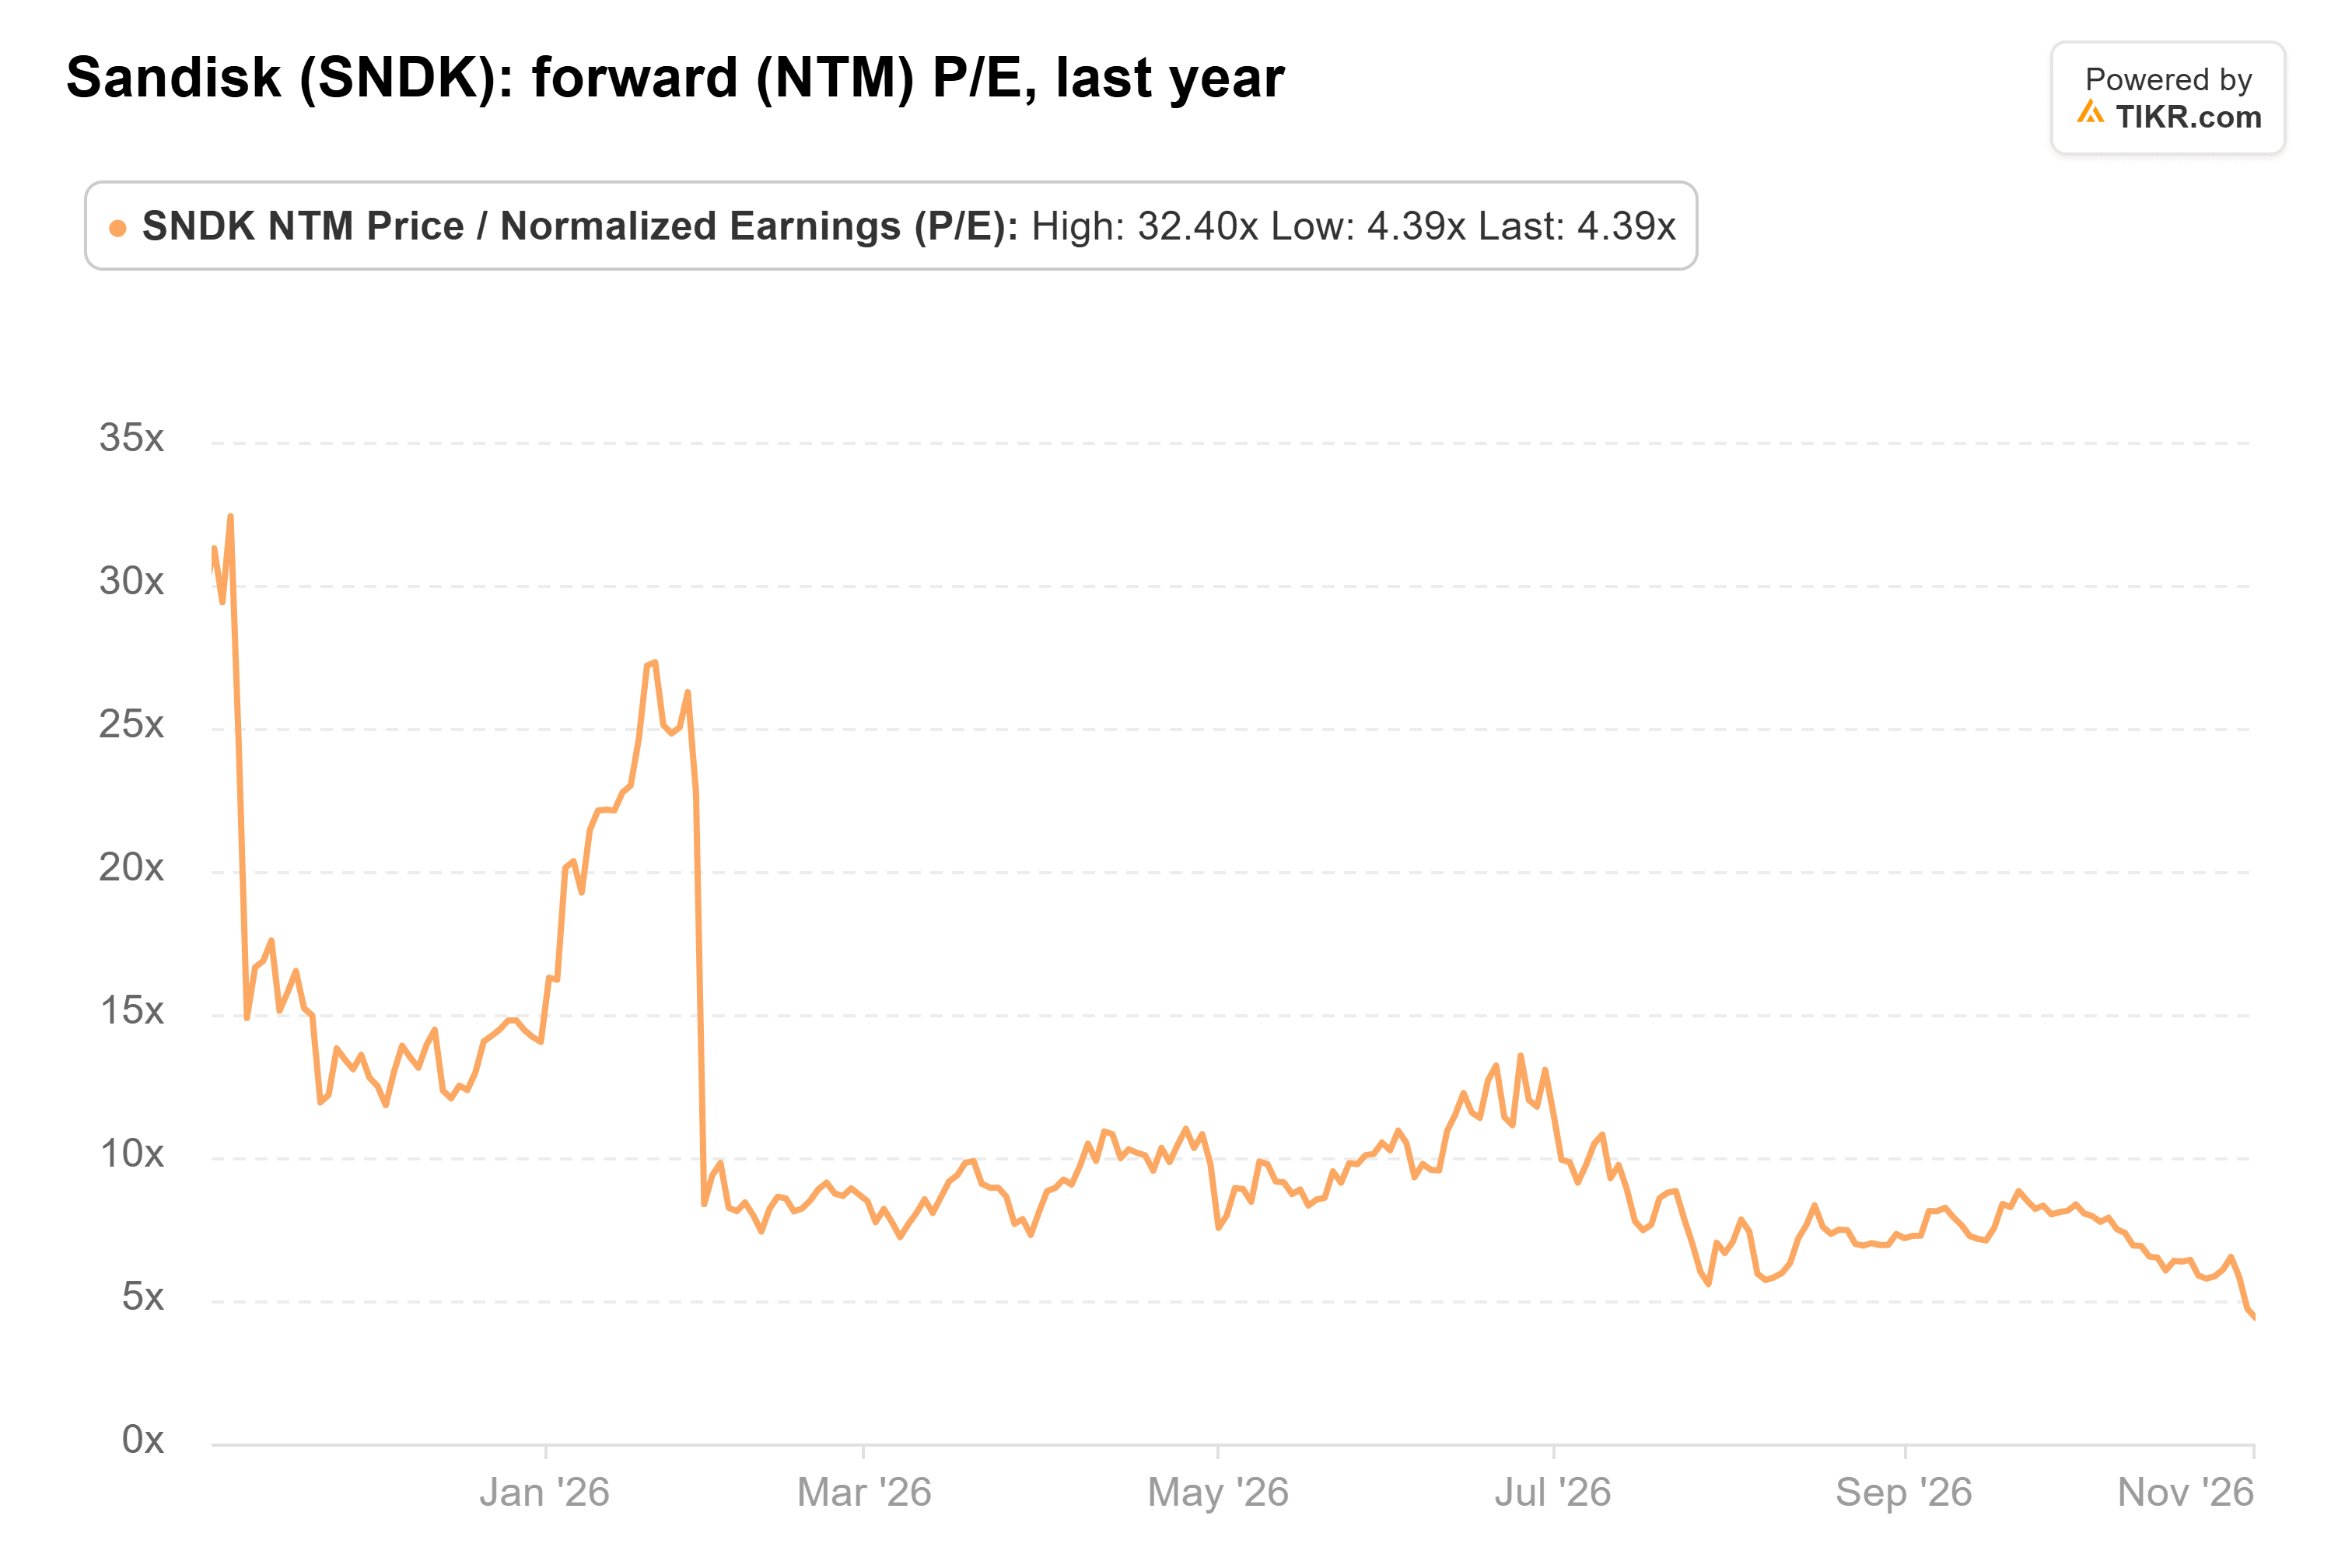
- Analysts expect Sandisk’s earnings per share to more than triple in fiscal 2027, yet its forward P/E is at a one-year low.
- The real test is Sandisk’s report in late January.
Sandisk (SNDK) stock jumped 7% today, winning back part of Thursday’s 22% plunge as AI-chip stocks rebounded.
A customer is paying up
Sandisk put out no news. The best explanation is IREN, which reported after Thursday’s close: AI cloud revenue nearly tripled from the prior quarter to $200 million, its backlog reached $20.3 billion, and it’s charging twice its previous rates on some contracts for older Nvidia H100 chips.
A customer raising prices is still buying AI servers, and those need memory and storage.
Seagate (STX) rose early on the same read. Seagate’s revenue rose 61% to $4.23 billion in the quarter ended Oct. 2, and CEO Dave Mosley said customer demand visibility is “reinforcing our view of a multi-year growth phase.” Revenue at Western Digital (WDC), the other hard-drive maker, rose 55%, and it guides to 66% to 72% growth this quarter.
Yet both trade at 12x to 13x forward earnings, about three times Sandisk’s multiple. The market is betting flash prices have further to fall.
The worries are still here
Kioxia, Sandisk’s fab partner, guided its December-quarter profit flat as its flash price gains slowed. Democrats’ midterm wins raised fears of pauses in data-center building, which UBS estimates could threaten around 30% of expected US capacity additions in 2028. And Reuters reported that China’s YMTC plans a fourth NAND factory.
TIKR tracks 25 analysts on Sandisk. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Sandisk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Sandisk’s Analyst Ratings
Wall Street hasn’t blinked
Analysts see Sandisk’s EPS rising from $70.88 in fiscal 2026 to $227.80 in fiscal 2027:
The stock’s forward P/E hit 4.4x at the start of the month, the low of its past year and well under its 10.8x average, and it’s lower still today:
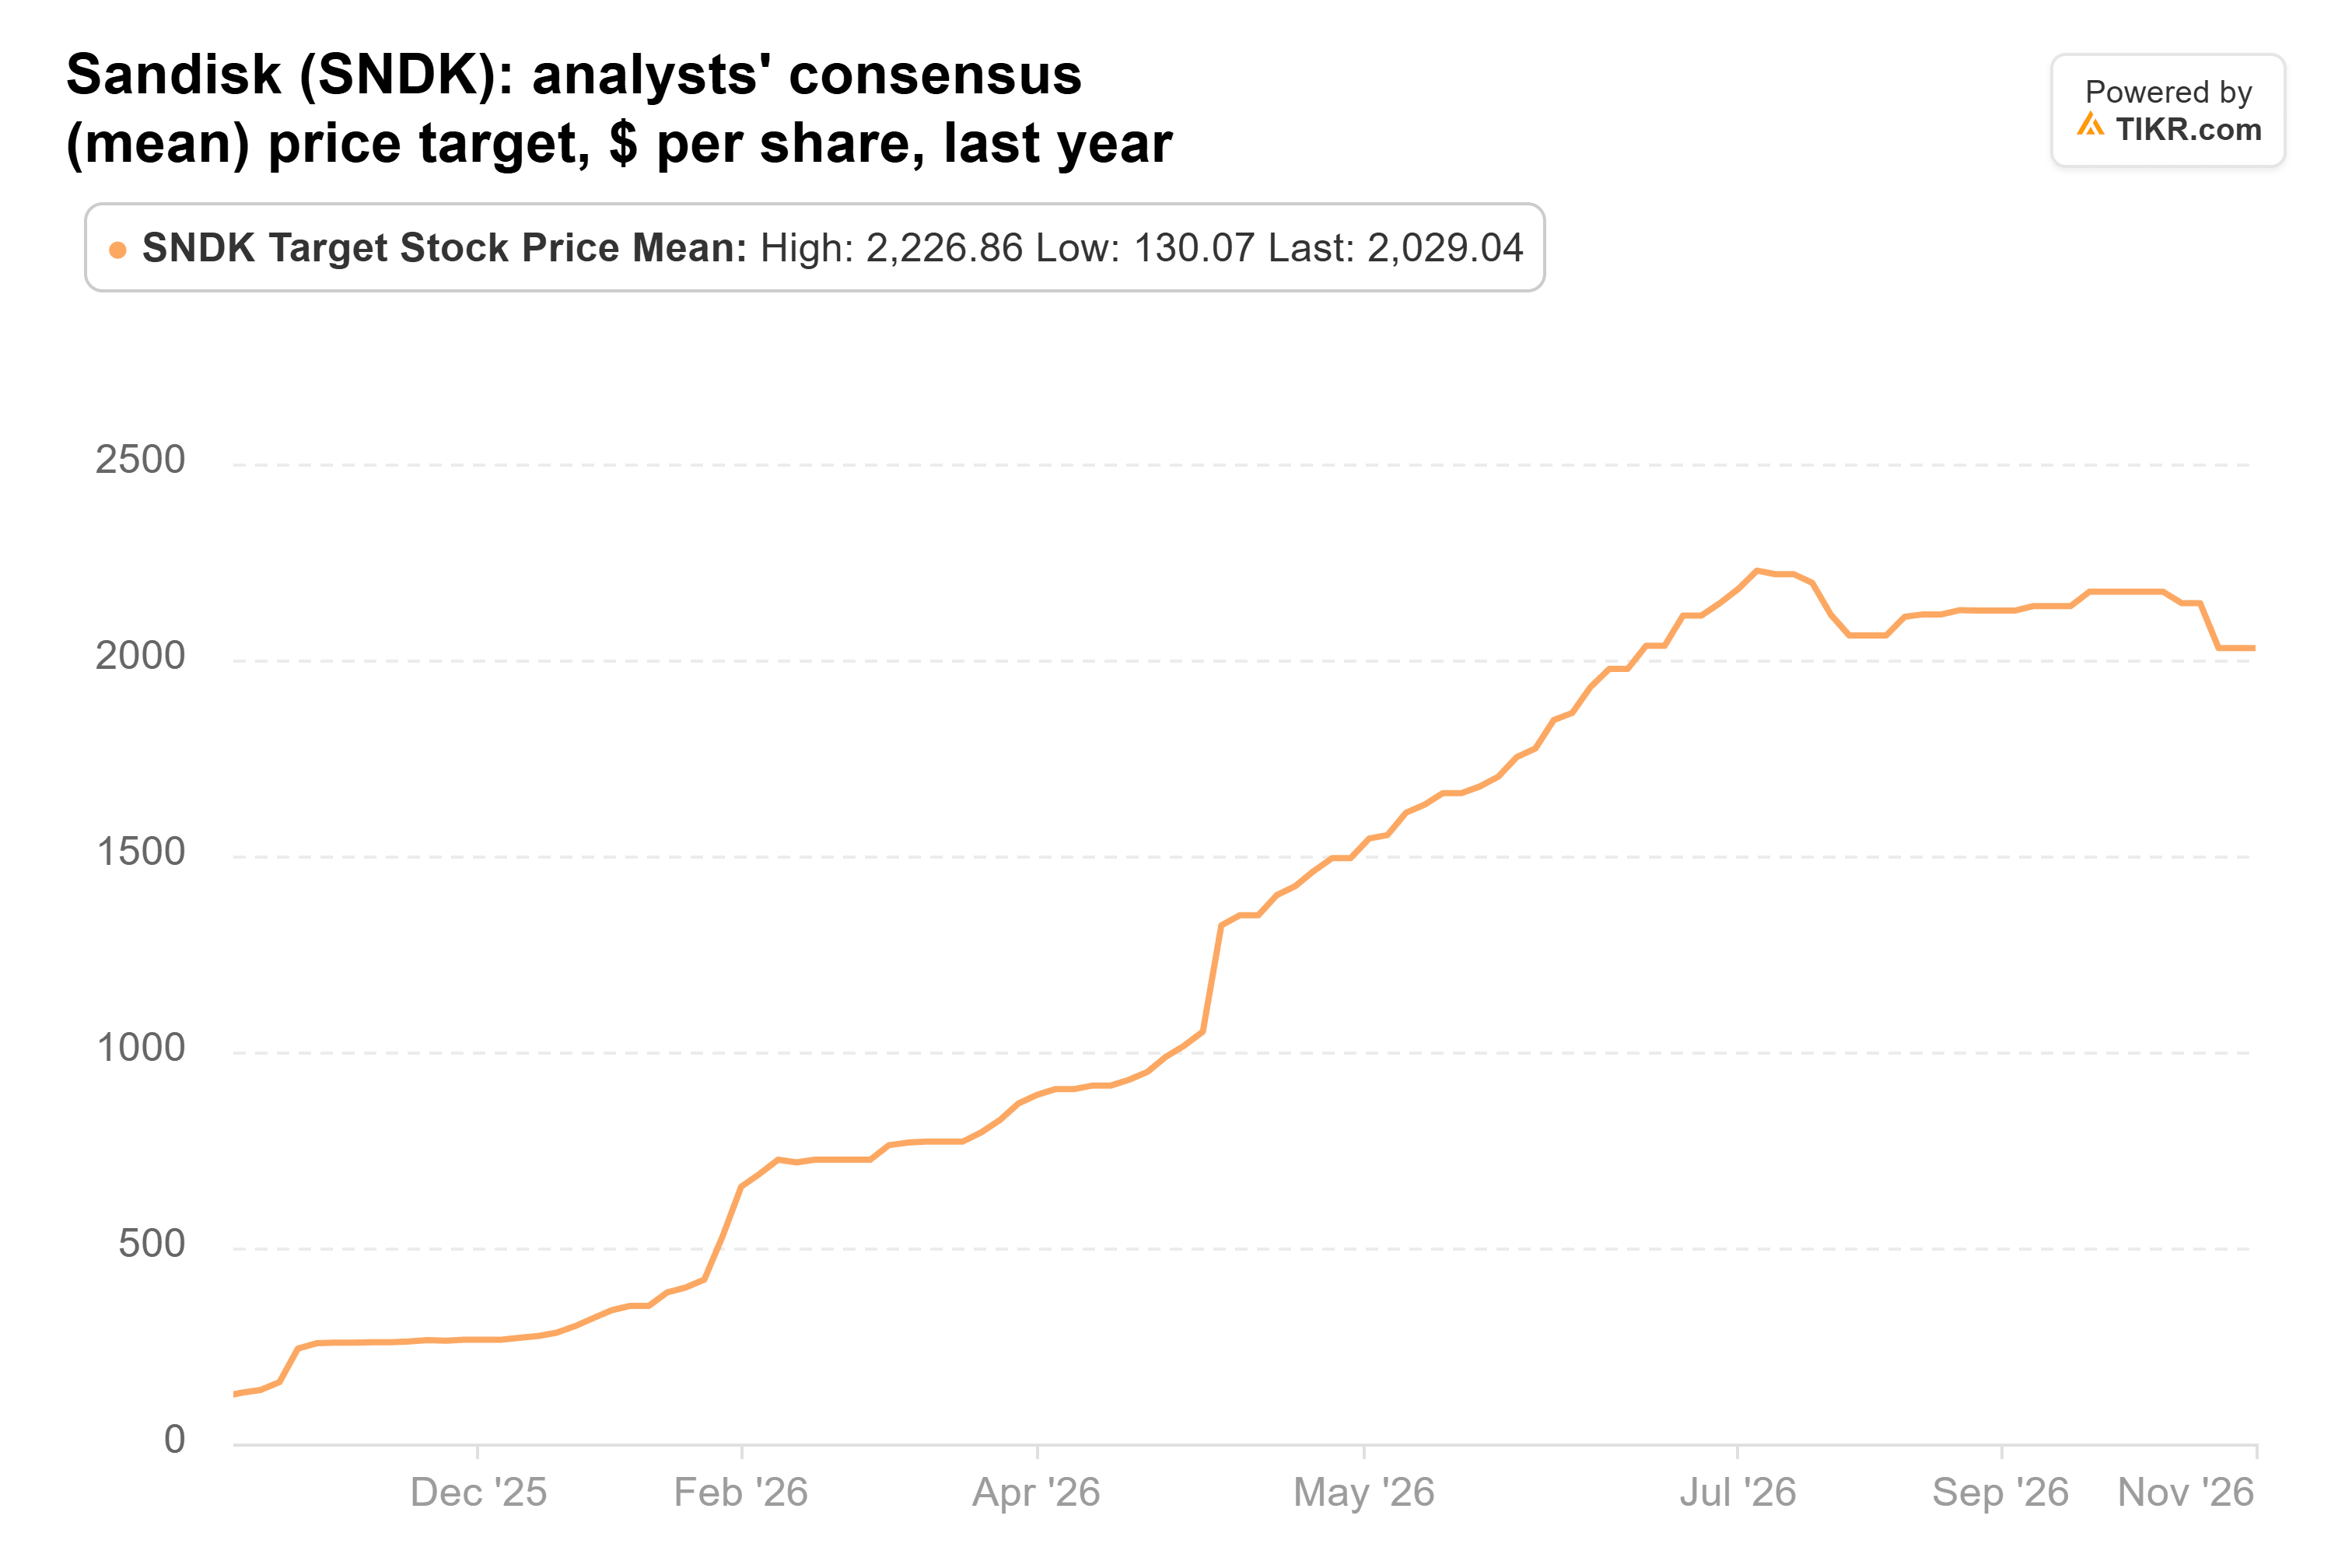
And analysts’ average price target, $2,029, is still more than double the share price:
Call it a bounce until January
Sandisk reports in late January, and its guide for the March quarter, usually its weakest, will show us whether flash prices are still rising.
The way I see it, at a multiple this low, investors are already pricing in a steep fall in flash prices that the estimates don’t show. I’d call today a bounce until that guide is out. But if it holds up, Sandisk has a lot more room to run than to fall.
Of course, another warning from Kioxia or a real pause in data-center building would test that fast.
So what is Sandisk stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Sandisk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!