Key Takeaways
- ServiceNow stock is 42% below its high of last December, and Wall Street’s average price target has fallen from $231 to $156 over the past year.
- Piper Sandler kept its Overweight rating and $175 target on Nov. 11. That’s 74% above the Nov. 12 close, and Piper’s case leans on security and new pricing tiers.
- At $175, ServiceNow would trade at about 39x expected earnings, close to the multiple it had at the end of 2025. Meanwhile, analysts have cut their 2026 and 2027 estimates over the past month.
- A rebound toward the Street’s $156 looks more likely than Piper’s $175, and the first 2027 guide in late January is the next test.
ServiceNow (NOW) is 42% below its December high, and analysts have cut their average target by a third over the past year. Piper Sandler still sees $175.
Wall Street didn’t buy the backlog guide
The slide began in mid-December and deepened this year as investors worried that AI agents would replace the human users ServiceNow charges for. The stock bottomed at $83 in April. It had recovered much of that by Oct. 28, when third-quarter subscription revenue rose 21% to $3.99 billion and management raised its AI contract value target to $1.7 billion.
But management also guided fourth-quarter growth in cRPO (current remaining performance obligations, or contracted revenue due over the next 12 months) to 18.5% in constant currency, down from 21% in the third quarter. Shares fell 27% on Oct. 29, their worst day on record. President and CFO Gina Mastantuono blamed early renewals pulled into the third quarter, adding that “cRPO is a very nuanced accounting metric, and it doesn’t necessarily capture all of the momentum in the business.”
Piper hasn’t budged
Analyst Billy Fitzsimmons raised Piper’s target to $175 from $140 on Oct. 16, when the stock sat near $149. He kept it, with an Overweight rating, after the report and again on Nov. 11, and it’s now 74% above the Nov. 12 close. Piper’s case leans on security, a business already above $1 billion of annual contract value as of the second quarter, and new pricing tiers that lift contract value per user 20% to 30% on average.
TIKR tracks 49 analysts on ServiceNow. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on ServiceNow, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See ServiceNow’s Analyst Ratings
$175 would take ServiceNow back to its 2025 multiple
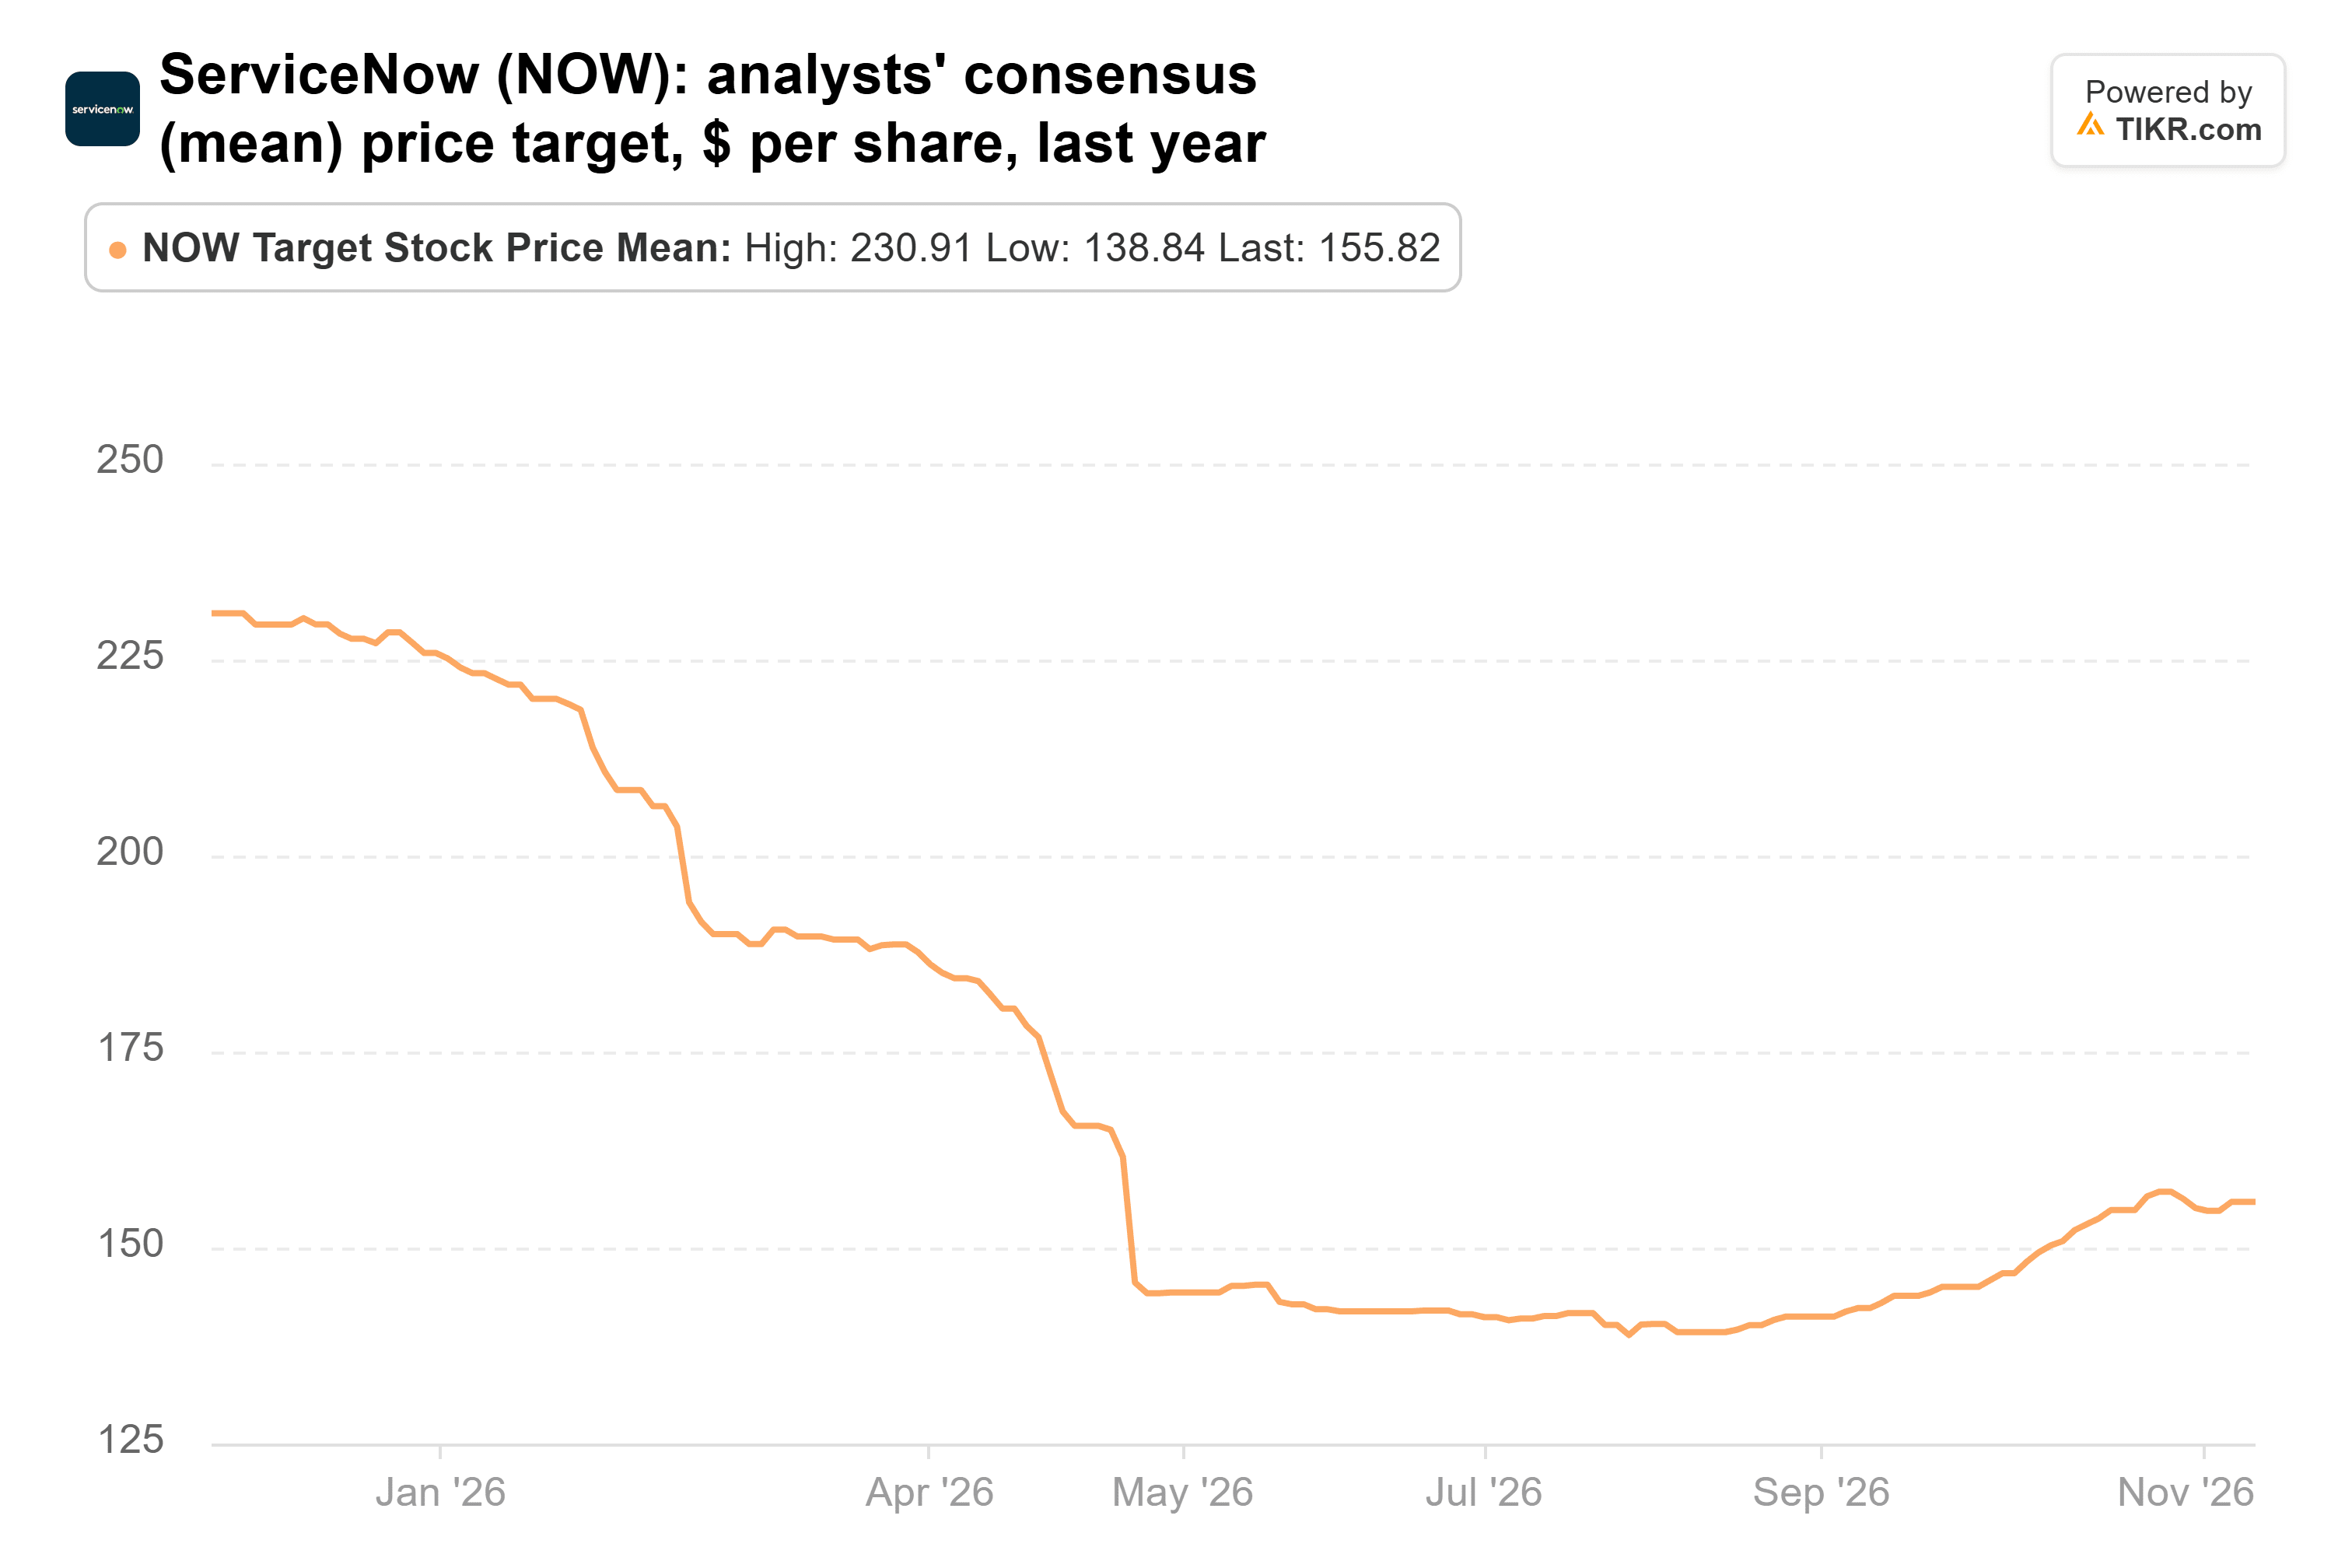
Wall Street’s average target fell from $231 a year ago to a low of $139 in July. It’s back up to $156 now, 55% above the Nov. 12 close:
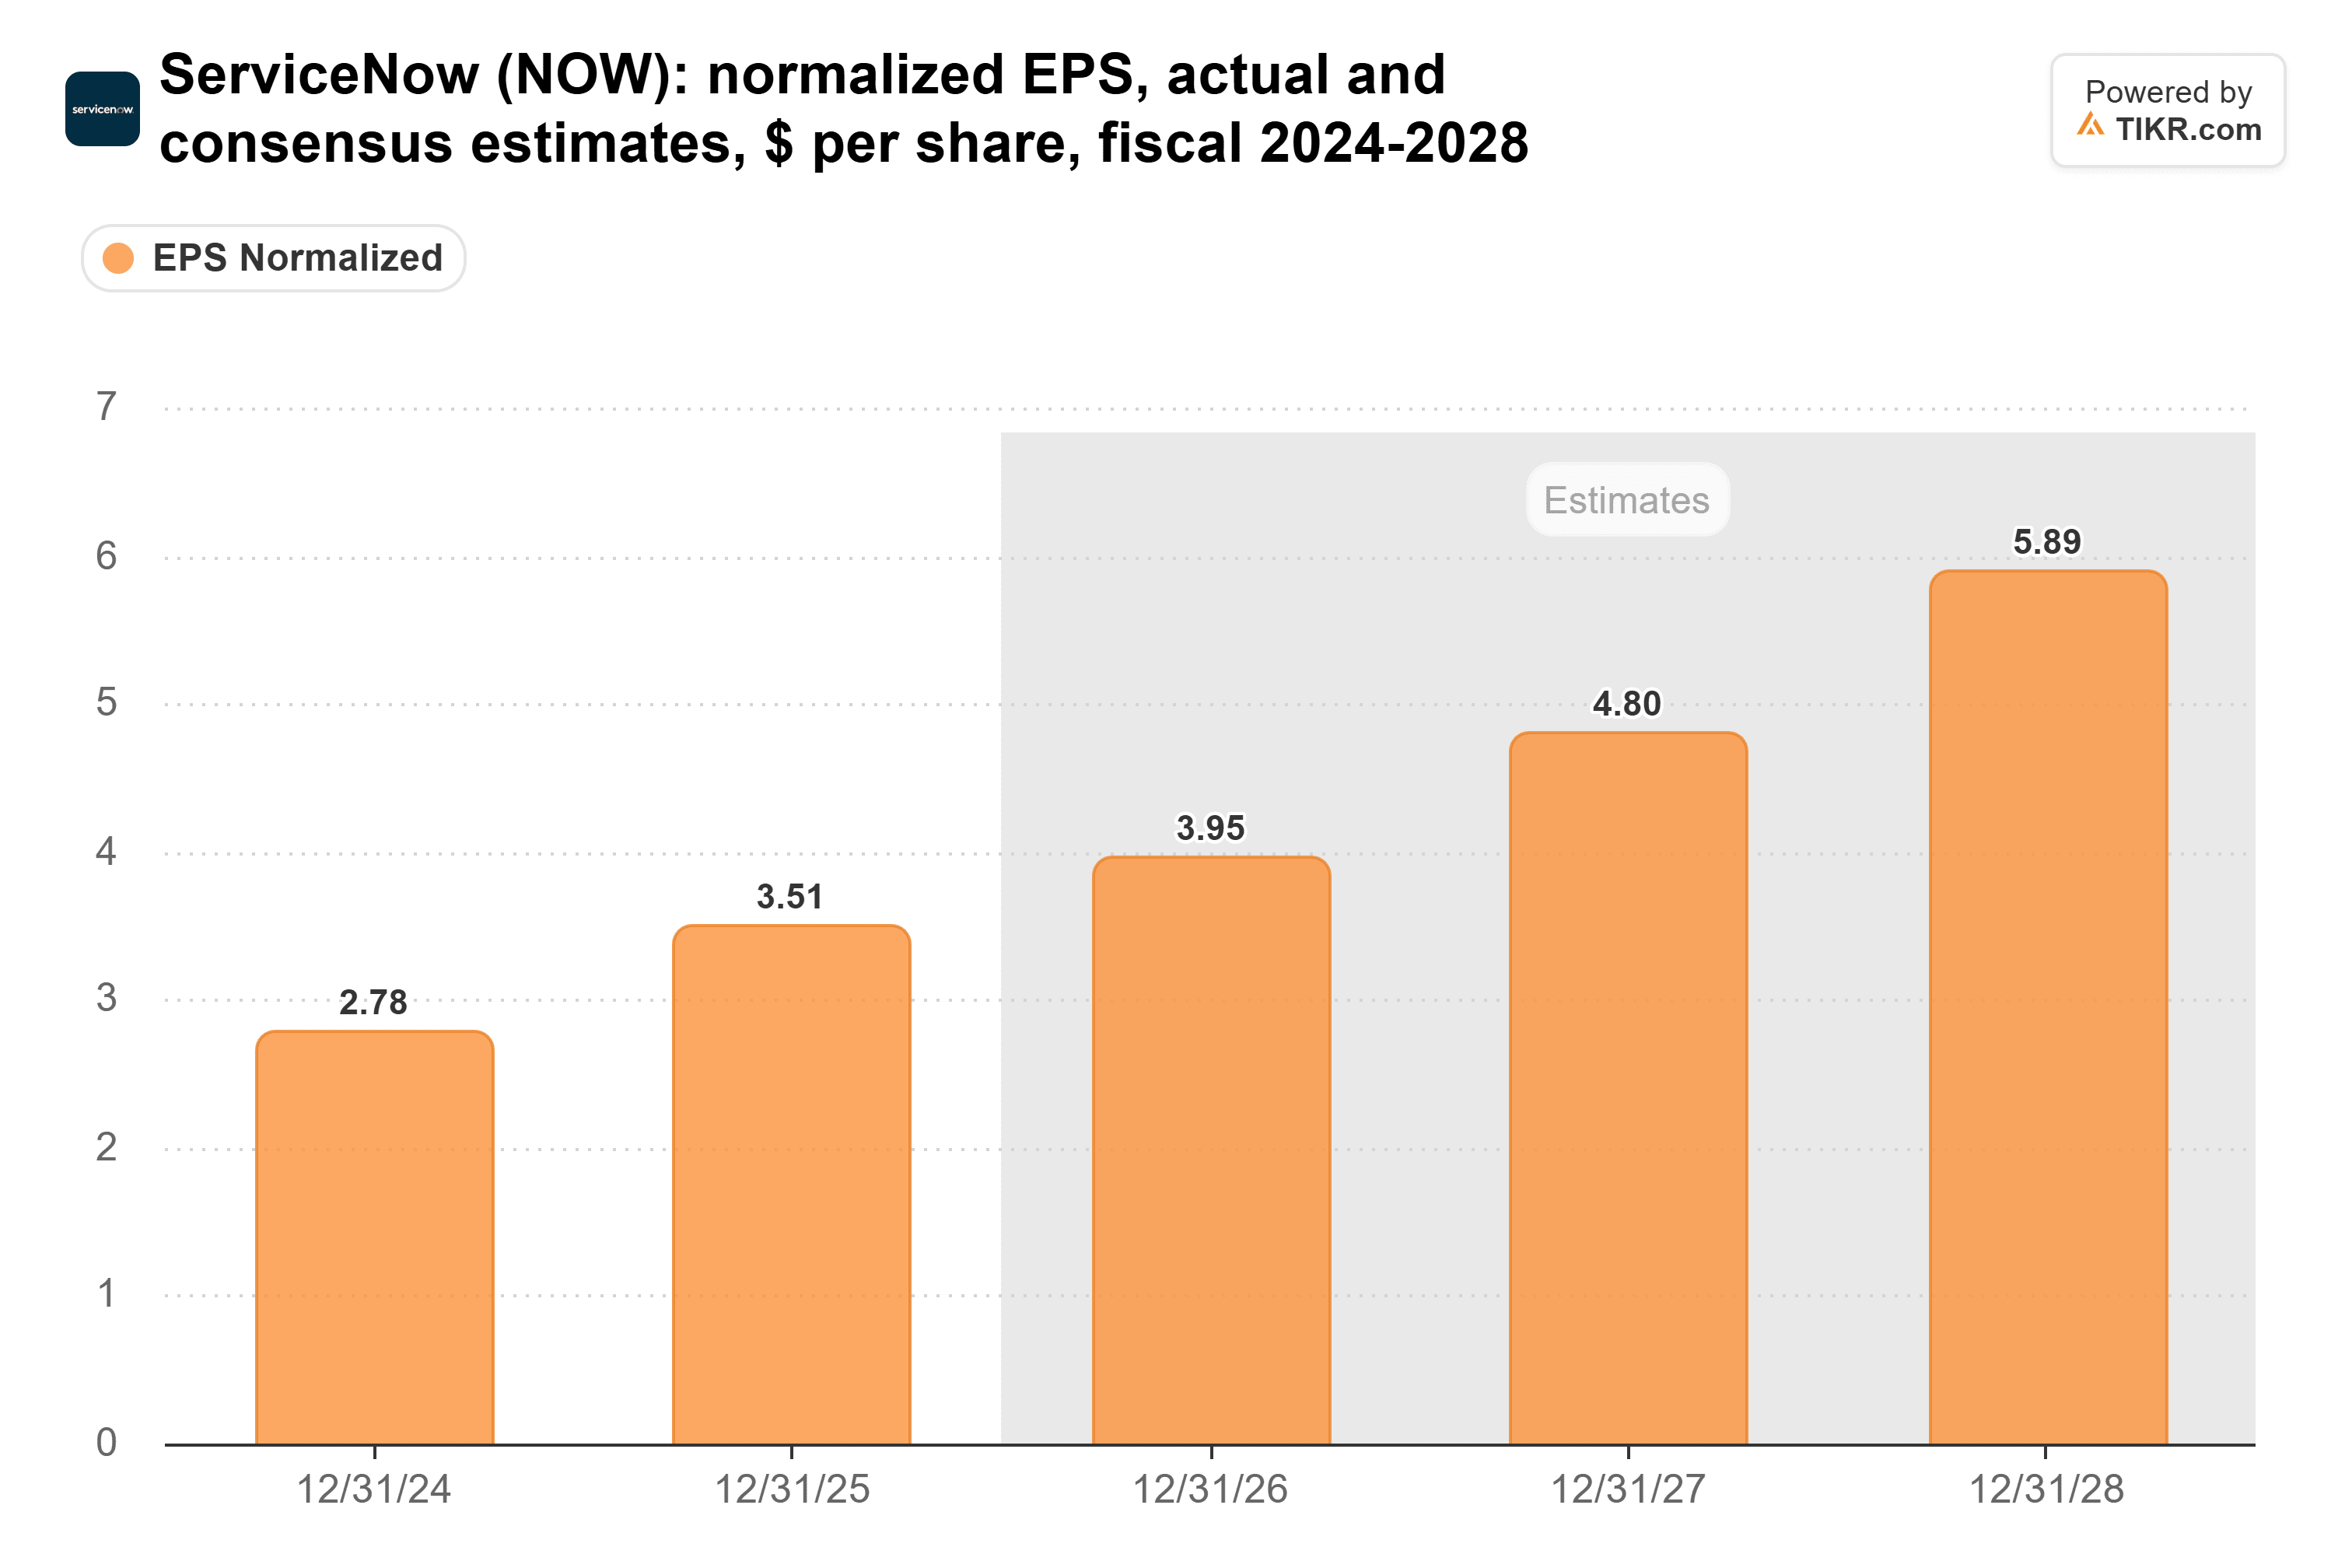
Analysts still expect normalized EPS to rise from $3.51 in 2025 to $3.95 this year and $4.80 in 2027. A month ago, though, those two estimates were $4.07 and $5.01:
At $175, ServiceNow would trade at about 39x the $4.54 a share analysts expect over the next twelve months. That’s below its five-year average of 52x, but that average includes 2021, when the multiple topped 102x. The stock traded at about 22x at the Nov. 12 close and ended 2025 at about 40x:
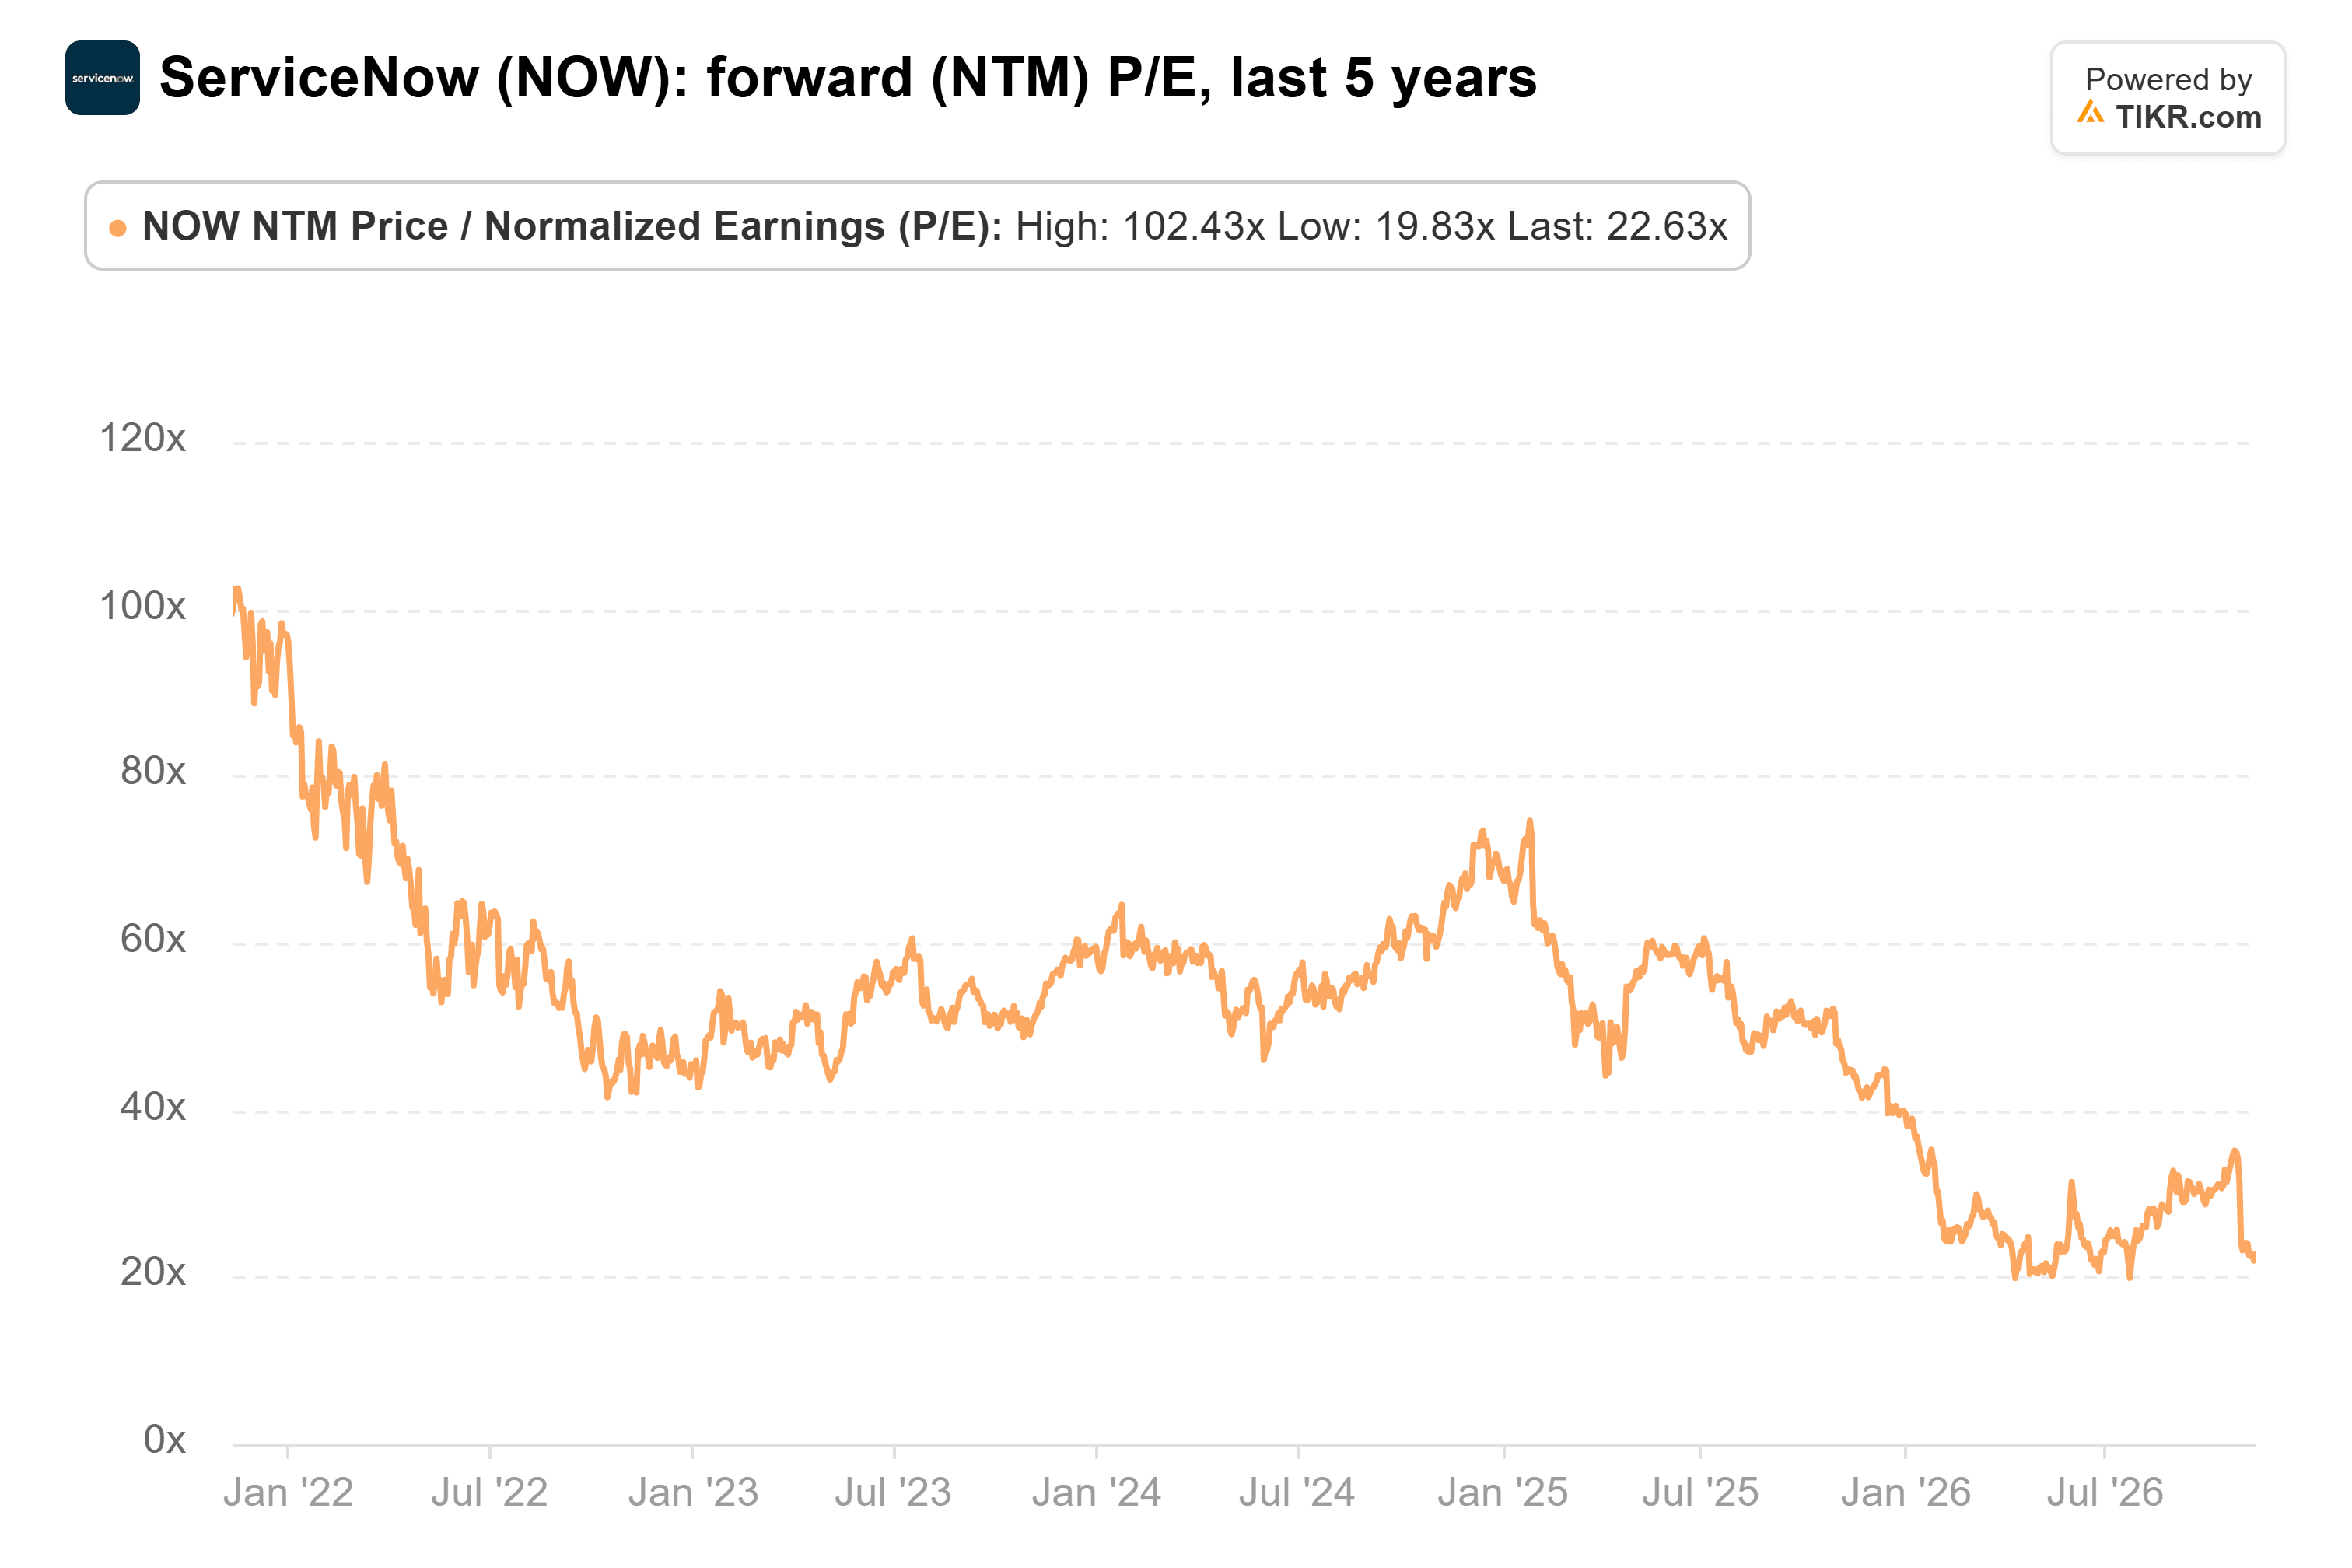
Right after the report, $175 worked out to about 37x. The estimate cuts since then have pushed that up.
The Street’s $156 is the likelier landing
The risk hasn’t changed all year: ServiceNow mostly charges per user, and its own AI agents are built to do those users’ work.
A rebound looks reasonable, with the multiple near the bottom of its five-year range and earnings expected to grow about 22% in 2027. But to reach $175, ServiceNow has to win back its end-of-2025 multiple while analysts are still trimming their numbers, and that looks unlikely within a year. Even the Street’s $156 works out to about 34x, so the cuts have to stop first.
The fourth-quarter report in late January brings AI contract value against the $1.7 billion target, plus the first 2027 guide. Subscription growth guided at 20% or more would put $175 back in reach.
So what is ServiceNow stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ServiceNow could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!