Key Takeaways
- ServiceNow shares fell after its third-quarter results, even though it beat its own guidance, because its backlog guidance for the fourth quarter pointed to slower growth. The stock is now down 38% over the past year.
- Piper Sandler kept its Overweight rating and $175 price target, 56% above this morning’s price.
- Analysts’ earnings estimates for 2026 and 2027 have barely moved in 90 days. The $175 target implies a forward P/E of 37x, against a five-year average of 53x.
- Piper’s call holds up on the numbers, and the 2027 guidance in late January is the next test.
ServiceNow (NOW) just turned in what CEO Bill McDermott called “the inflection point for ServiceNow,” and the stock fell to $112.06 by late morning from yesterday’s $150.13 close. That leaves it down 38% over the past year.
Piper Sandler still likes it. On Oct. 29, the firm kept its Overweight rating and its $175 target, 56% above this morning’s price.
Investors sold the backlog guide
ServiceNow says it beat the high end of its guidance on every growth and profitability measure in the third quarter. Adjusted EPS of $1.00 did miss analysts’ estimates by two cents.
The bigger problem was the outlook. Management expects its 12-month contracted backlog (cRPO) to grow 18.5% in constant currency in the fourth quarter, down from 21% in the third. It raised its full-year subscription revenue guidance by just $15 million at the midpoint.
CFO Gina Mastantuono said early renewals and more on-premise federal deals weigh on that figure without hurting revenue.
Piper sticks with $175
Analyst Billy Fitzsimmons raised his target to $175 from $140 on Oct. 16, and his reasoning came down to three things: strong demand for security products, new pricing tiers that lift contract value per user by 20% to 30%, and growing AI and consumption revenue.
The quarter gave him some backing, with AI net new annual contract value up 65%.
TIKR tracks 49 analysts on ServiceNow. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on ServiceNow, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See ServiceNow’s Analyst Ratings
Does $175 add up?
Wall Street’s average target has fallen from $229 to $157 over the past year, though it’s up from a $139 low in July.

That’s still 24% above this afternoon’s price.
Earnings estimates have barely moved: analysts expect normalized EPS of $4.07 in 2026 and $5.00 in 2027, both within a cent of where they were 90 days ago.

So investors are paying less for the same expected earnings: 31x forward earnings at yesterday’s close, against a five-year average of 53x.
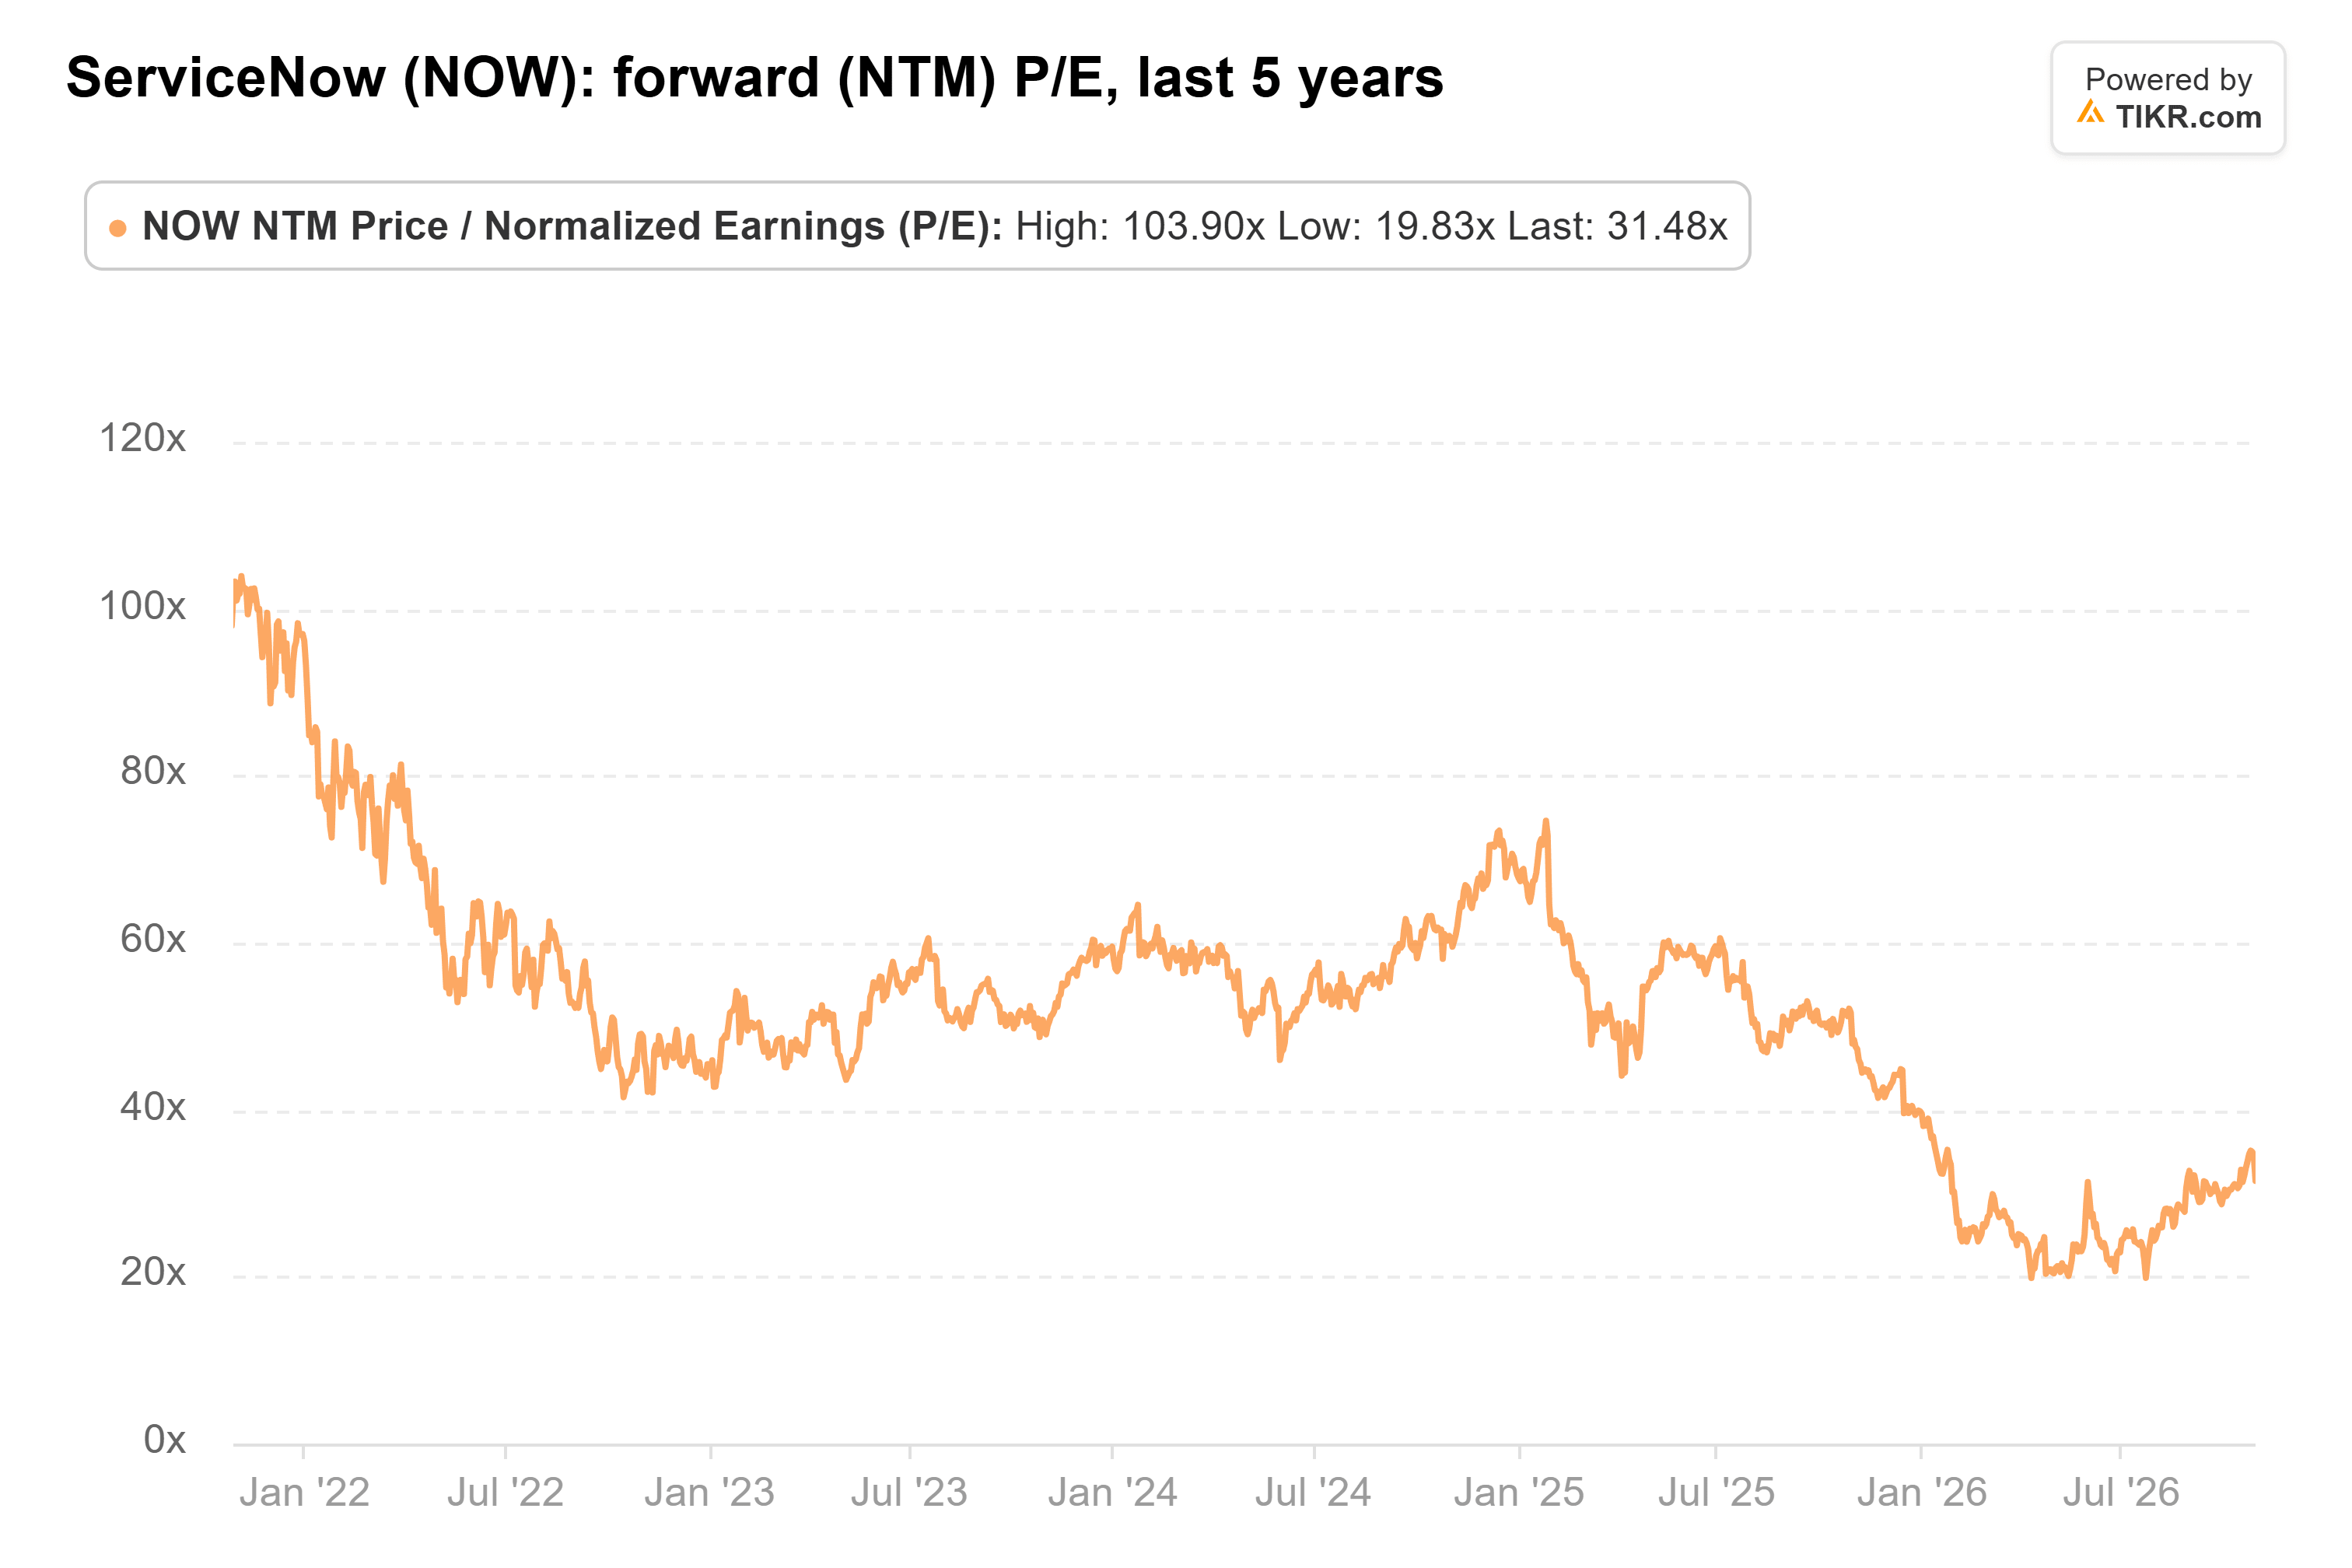
At this morning’s price, it’s lower still.
On the $4.77 a share analysts expect over the next twelve months, Piper’s $175 implies 37x, well below that average.
Piper has this one right
Growth is the risk here. UBS cut its target to $140 on Oct. 29, arguing that the Street’s 2027 growth estimates look too high.
Piper’s target, though, only asks for the earnings analysts already expect and a multiple well below the stock’s five-year average. I think $175 is fair, and even the consensus target of around $160 leaves room from here.
The next test is the 2027 guidance, due with fourth-quarter results in late January. If subscription growth comes in at 20% or more, $175 stays in reach, and anything weaker hands the argument to UBS.
So what is ServiceNow stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ServiceNow could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!