Key Takeaways
- Nebius is still up 38% in 2026 but down 61% from its June high, after a third-quarter report that cut its 2026 revenue outlook because partner data centers were running late.
- Third-quarter revenue rose 571% to $980.8 million, and analysts’ 2027 estimate is still inside Nebius’s new $12 billion to $13 billion range.
- The risks are delivering and paying for the build: the rest of Microsoft’s New Jersey capacity is now due in the second quarter of 2027, Nebius plans $40 billion to $45 billion of 2027 capital spending, and Jensen Huang’s exit at Nvidia raises questions about how the group gets financed.
- The stock’s forward sales multiple is less than a third of its June level, so holding makes more sense than selling or adding until that capacity arrives.
Nebius Group (NBIS) is still up 38% in 2026, but it’s down 61% from its June high. That peak capped a run to about four times its February low.
AI cloud stocks have sold off since the fall over funding and data center power limits. Then Nebius’s own Nov. 12 report beat on revenue but trimmed its 2026 outlook because third-party data centers ran late. One of them is a site in Vineland, New Jersey, where Nebius is building capacity for Microsoft (MSFT). The same day, Jensen Huang left the top job at Nvidia (NVDA). Nvidia supplies Nebius’s GPUs and has been a $2 billion investor in it since March.
CEO Arkady Volozh was blunt about the delays on the third-quarter call:
“Building at this scale is hard, and delays are part of our industry right now. We are not immune.”
TIKR tracks 23 analysts on Nebius. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nebius, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nebius’ Analyst Ratings
Growth was the easy part
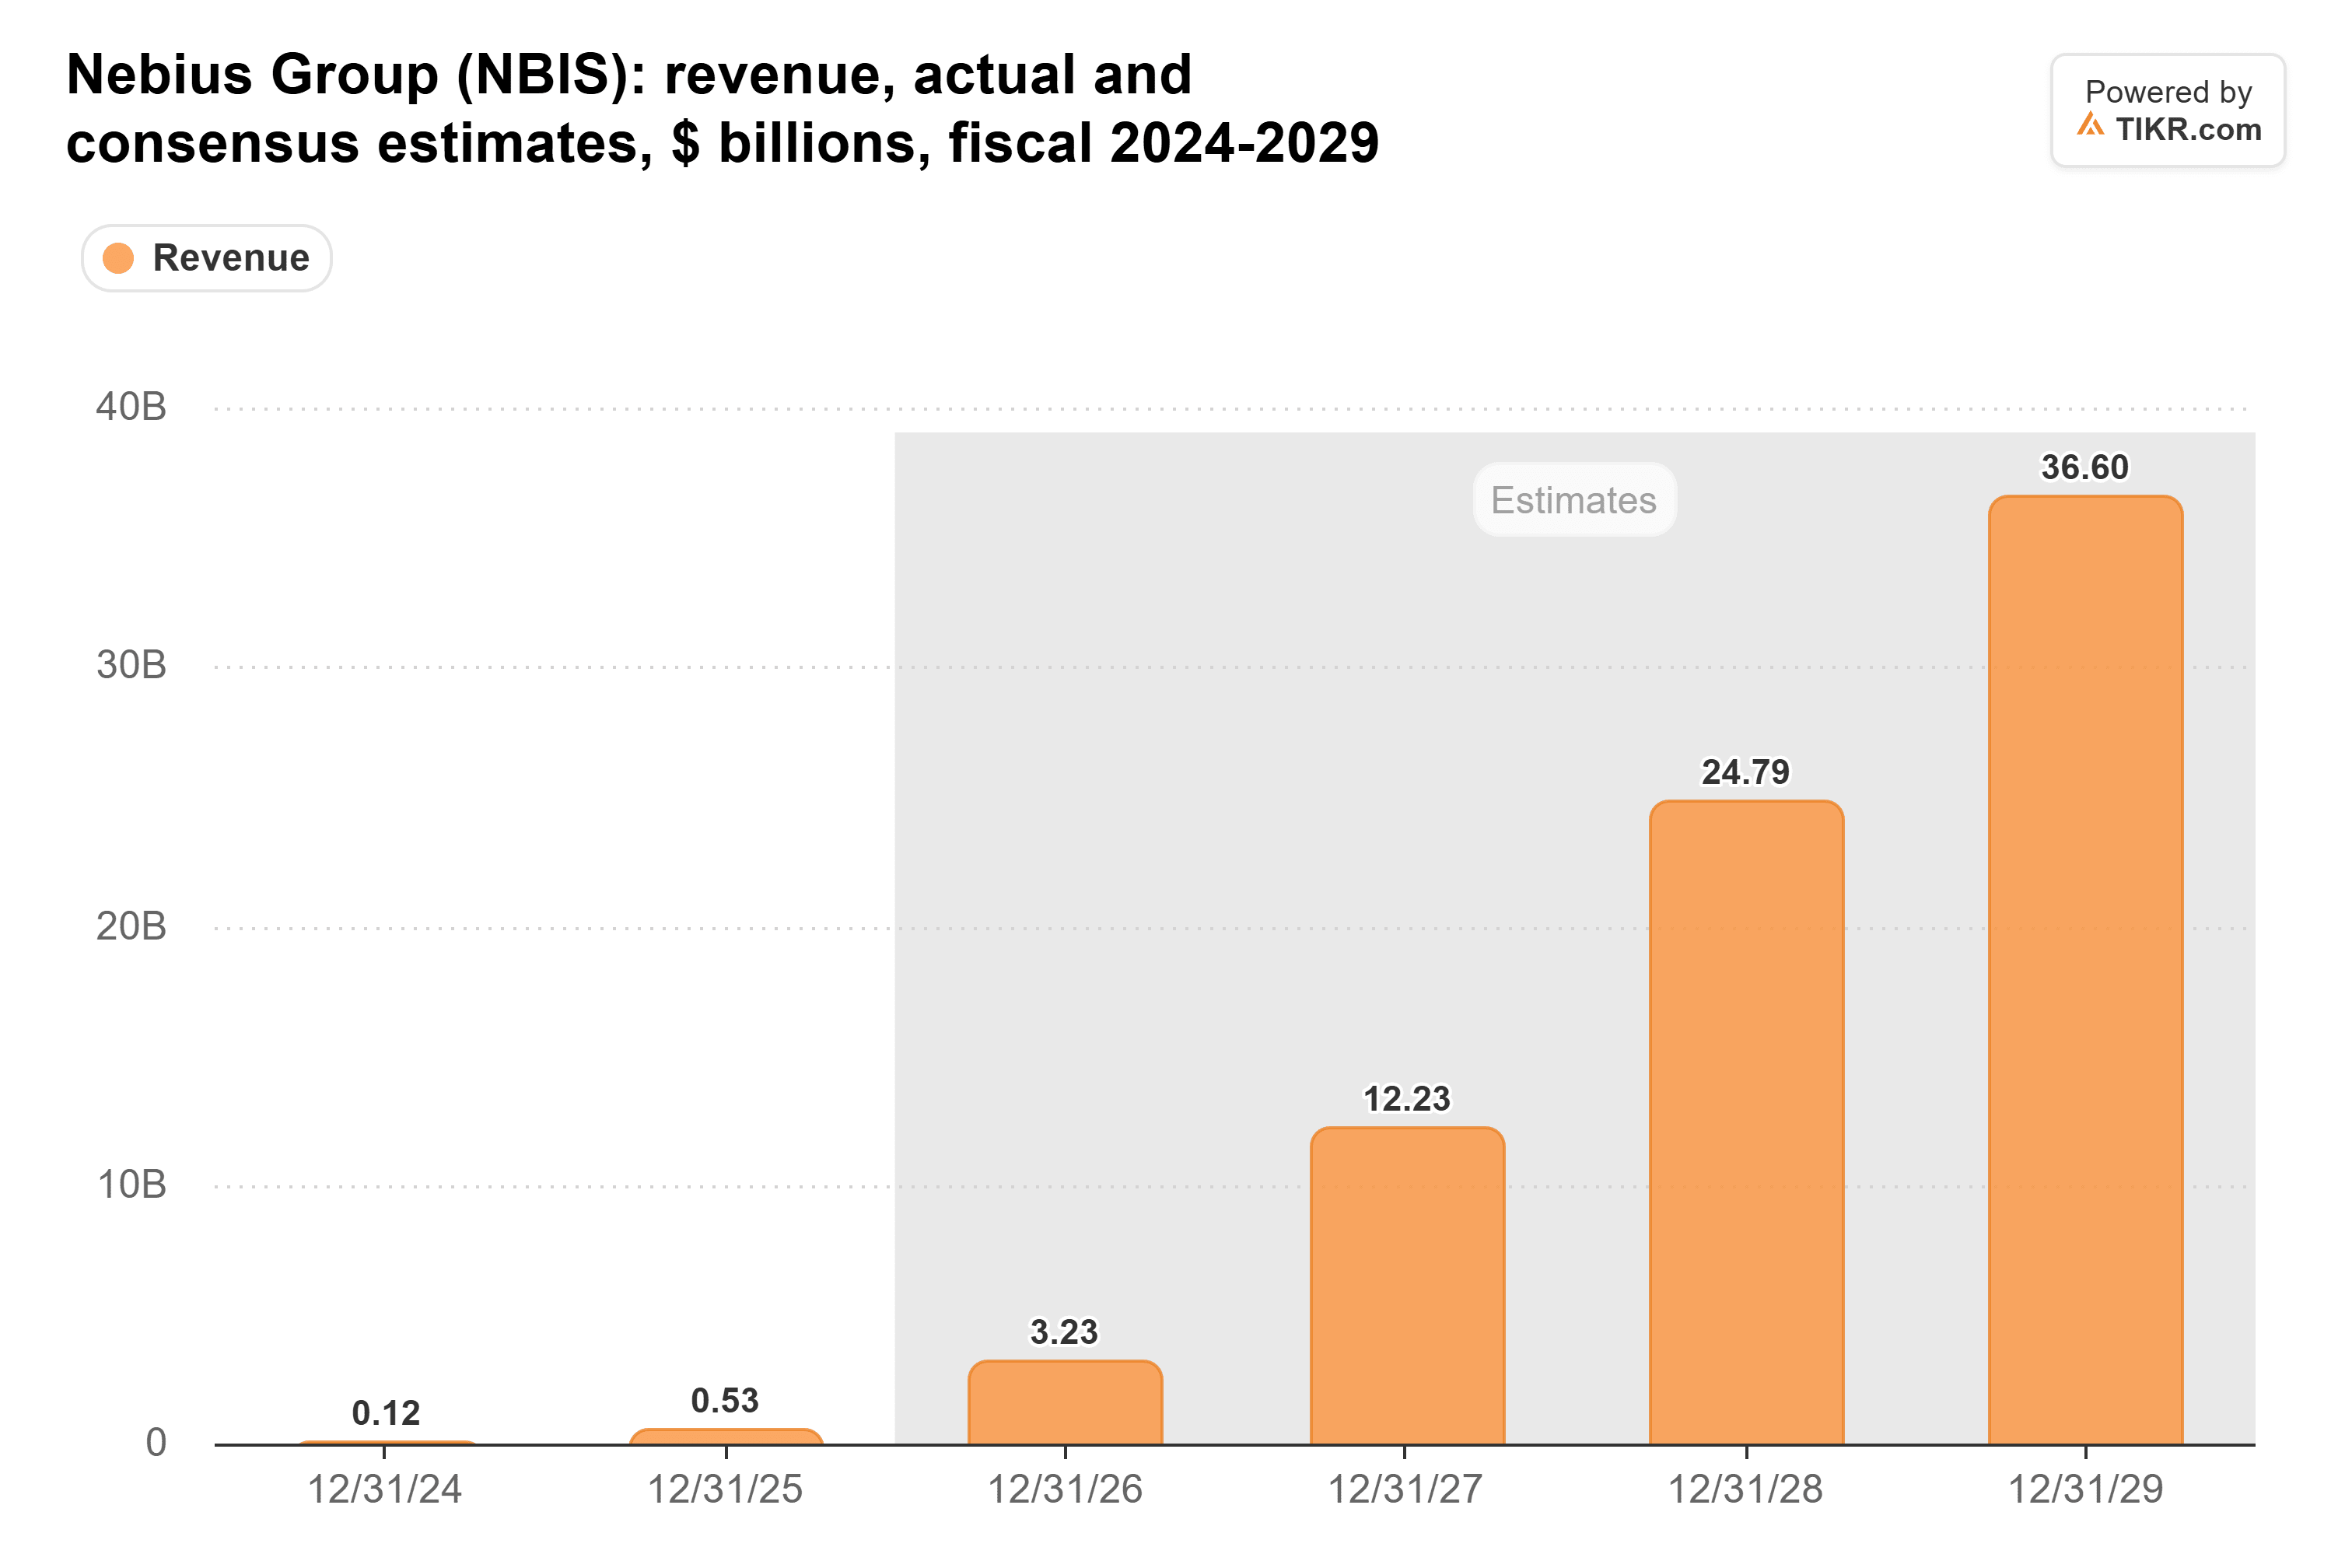
Third-quarter revenue rose 571% to $980.8 million, though Nebius calls $325.1 million of that non-recurring. The outlook is the problem. Nebius cut its 2026 revenue range to $3.0 billion to $3.2 billion, from $3.0 billion to $3.4 billion. It also pushed its goal of more than $7 billion in run-rate revenue out to February. Analysts’ 2027 estimate already sits inside the $12 billion to $13 billion Nebius now guides to:
Short seller Jim Chanos asked on X how that guide fits with contracts signed at $20 million to $25 million per megawatt, given what he puts at about 1,500 megawatts of average 2027 capacity: “That’s $8-9M per MW, the same as the current 2026 run-rate.”
His math checks out. My read: much of the gap is the ramp. Management has said the capacity it connects by the end of 2026 starts earning through the first half of 2027. But Chanos is right that the higher prices haven’t shown up in reported revenue yet.
Vineland is the next test
Microsoft’s contract is worth $17.4 billion to $19.4 billion, part of the more than $40 billion of investment-grade backlog that Nebius borrows against. Over half of Microsoft’s New Jersey capacity should be live by year-end, but the last tranches have slipped to the second quarter of 2027. Bloomberg reported on Nov. 5 that Microsoft is weighing whether to sign new neocloud deals. Hitting that date matters for the next contract too.
Then there’s the bill. Nebius plans $40 billion to $45 billion of capital spending in 2027 and expects prepayments and asset-backed loans to cover 75% to 85% of it. That leaves about $6 billion to $11 billion to come from its $7.4 billion cash pile, more borrowing or new stock. Debt was already $14.2 billion on Sept. 30. Prepayments on third-quarter deals covered more than 100% of their capital spending, up from 50% to 60% in the second quarter.
Nvidia is the wild card. After Huang left, The Information reported that Nvidia is expected to slow its AI investments and credit guarantees. If lenders start charging the whole group more, closing that gap will cost Nebius more.
Cheap for a reason, for now
Nebius’s forward sales multiple has come down hard since June:
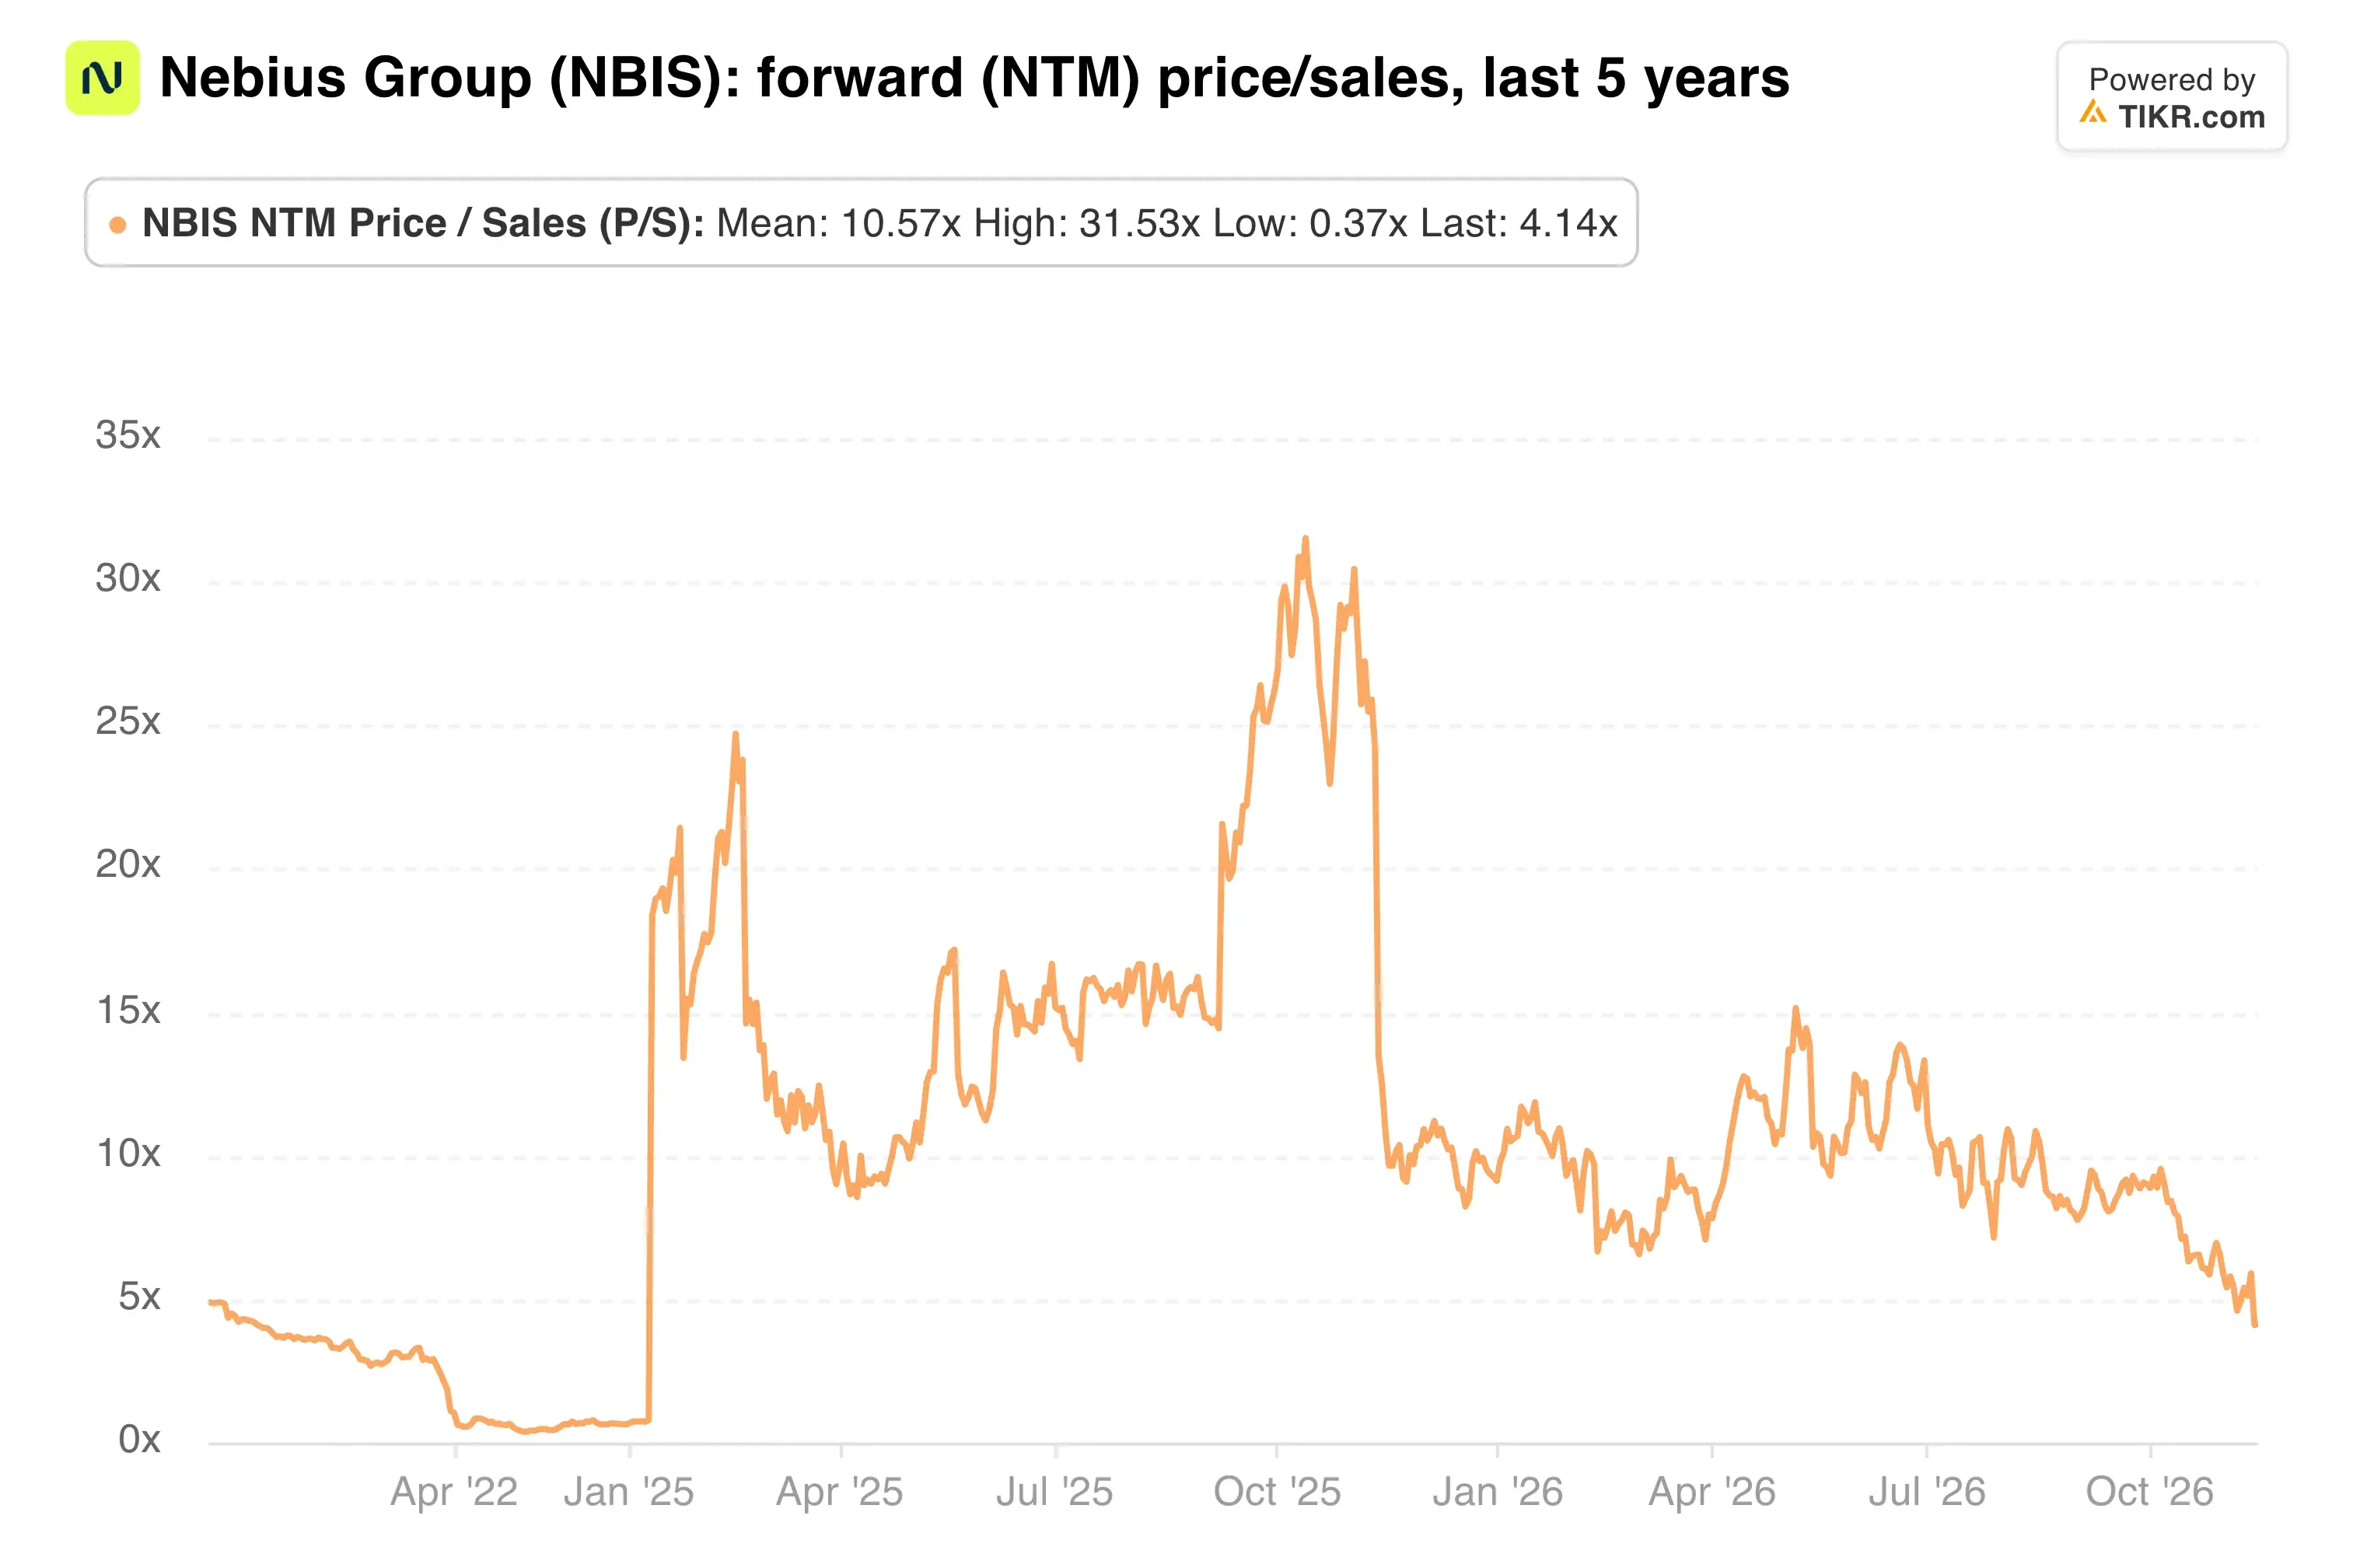
It traded at 4.1x forward sales at the Nov. 13 close, less than a third of the 13.3x at the end of June.
I wouldn’t take profits here: revenue is still on track to nearly quadruple in 2027, and the multiple already prices in plenty of trouble. But I wouldn’t buy more until Nebius shows it can deliver. The fourth-quarter report in early 2027 is the first check. The bigger one is whether Microsoft’s New Jersey tranches arrive on time.
So what is Nebius stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nebius could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!