Key Takeaways
- Block is up 10% in the past month, almost all of it on a third-quarter report that beat its own guidance and raised its 2026 outlook.
- Block’s 2026 guidance adds up to the “rule of 50” its CFO described, and its 2027 outlook comes to about 47.
- Cash App’s loan losses and a pending $764 million Justice Department settlement are the main risks.
- At about 16x forward earnings, below its three-year average, and with estimates rising, Block still looks like a buy.
Block (XYZ) is up 10% in the past month, and almost all of the gain came from one report. A week later, CFO Amrita Ahuja told Mad Money: “Our latest guidance a year later for 2026 is to be a rule of 50 company.”
A beat on every line
Block reported third-quarter results after the close on Nov. 3. Gross profit grew 22% to $3.24 billion, about $110 million above its own guide, and adjusted EPS of $1.13 beat the roughly $1.03 analysts expected.
Block lifted its 2026 adjusted EPS guide to $4.15 from $4.02. Its first 2027 outlook calls for $4.58 billion of adjusted operating income, close to the $4.6 billion it had targeted for 2028 at last November’s investor day. That’s a year early.
Rule of 50 this year, 47 next
At that investor day, Block committed to the “Rule of 40” in 2026. Block’s version is its gross profit growth plus adjusted operating income as a share of gross profit. The new 2026 guidance calls for 22% growth at a 28% margin, which adds up to Ahuja’s 50. For 2027, the outlook of at least 15% growth at a 32% margin comes to about 47. Block has beaten its own gross profit guide in each of the last four quarters, though, so that 15% looks like a floor.
Analysts expect earnings to keep climbing through 2028:
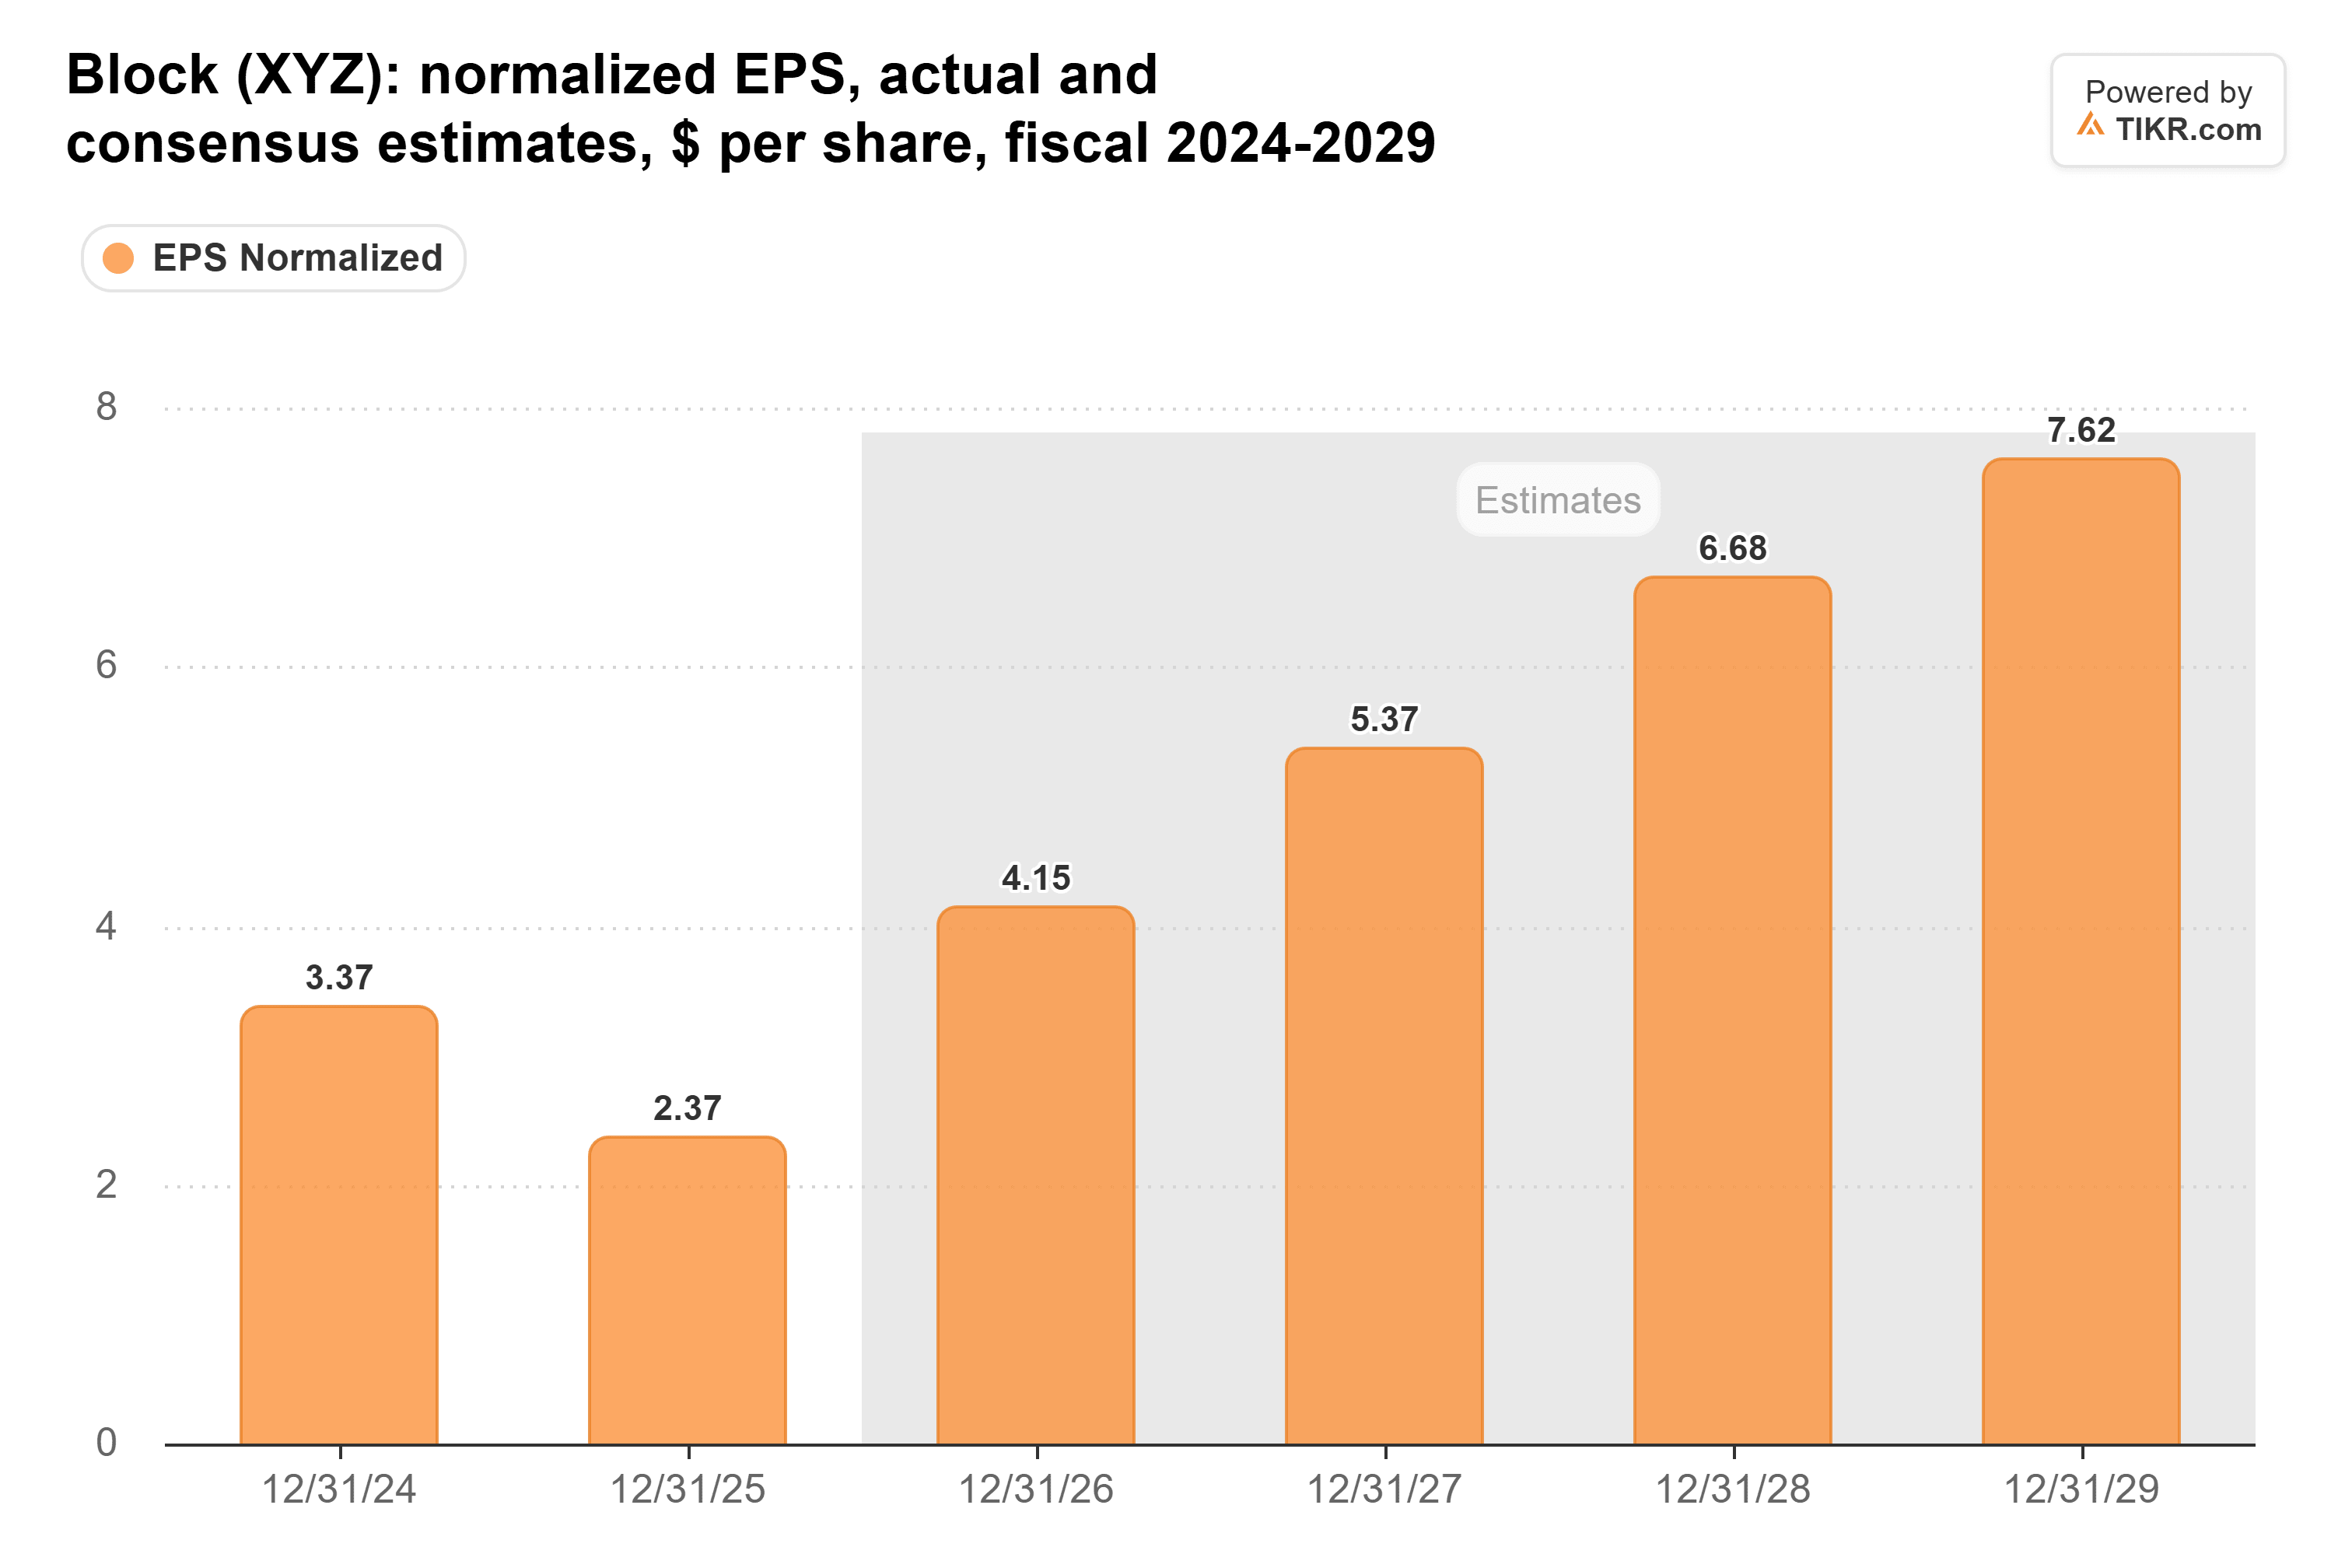
The 2027 estimate is up to $5.37 from $5.21 before the report.
TIKR tracks 47 analysts on Block. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Block, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Block’s Analyst Ratings
Still cheaper than its usual multiple
Block still trades below its recent norm:
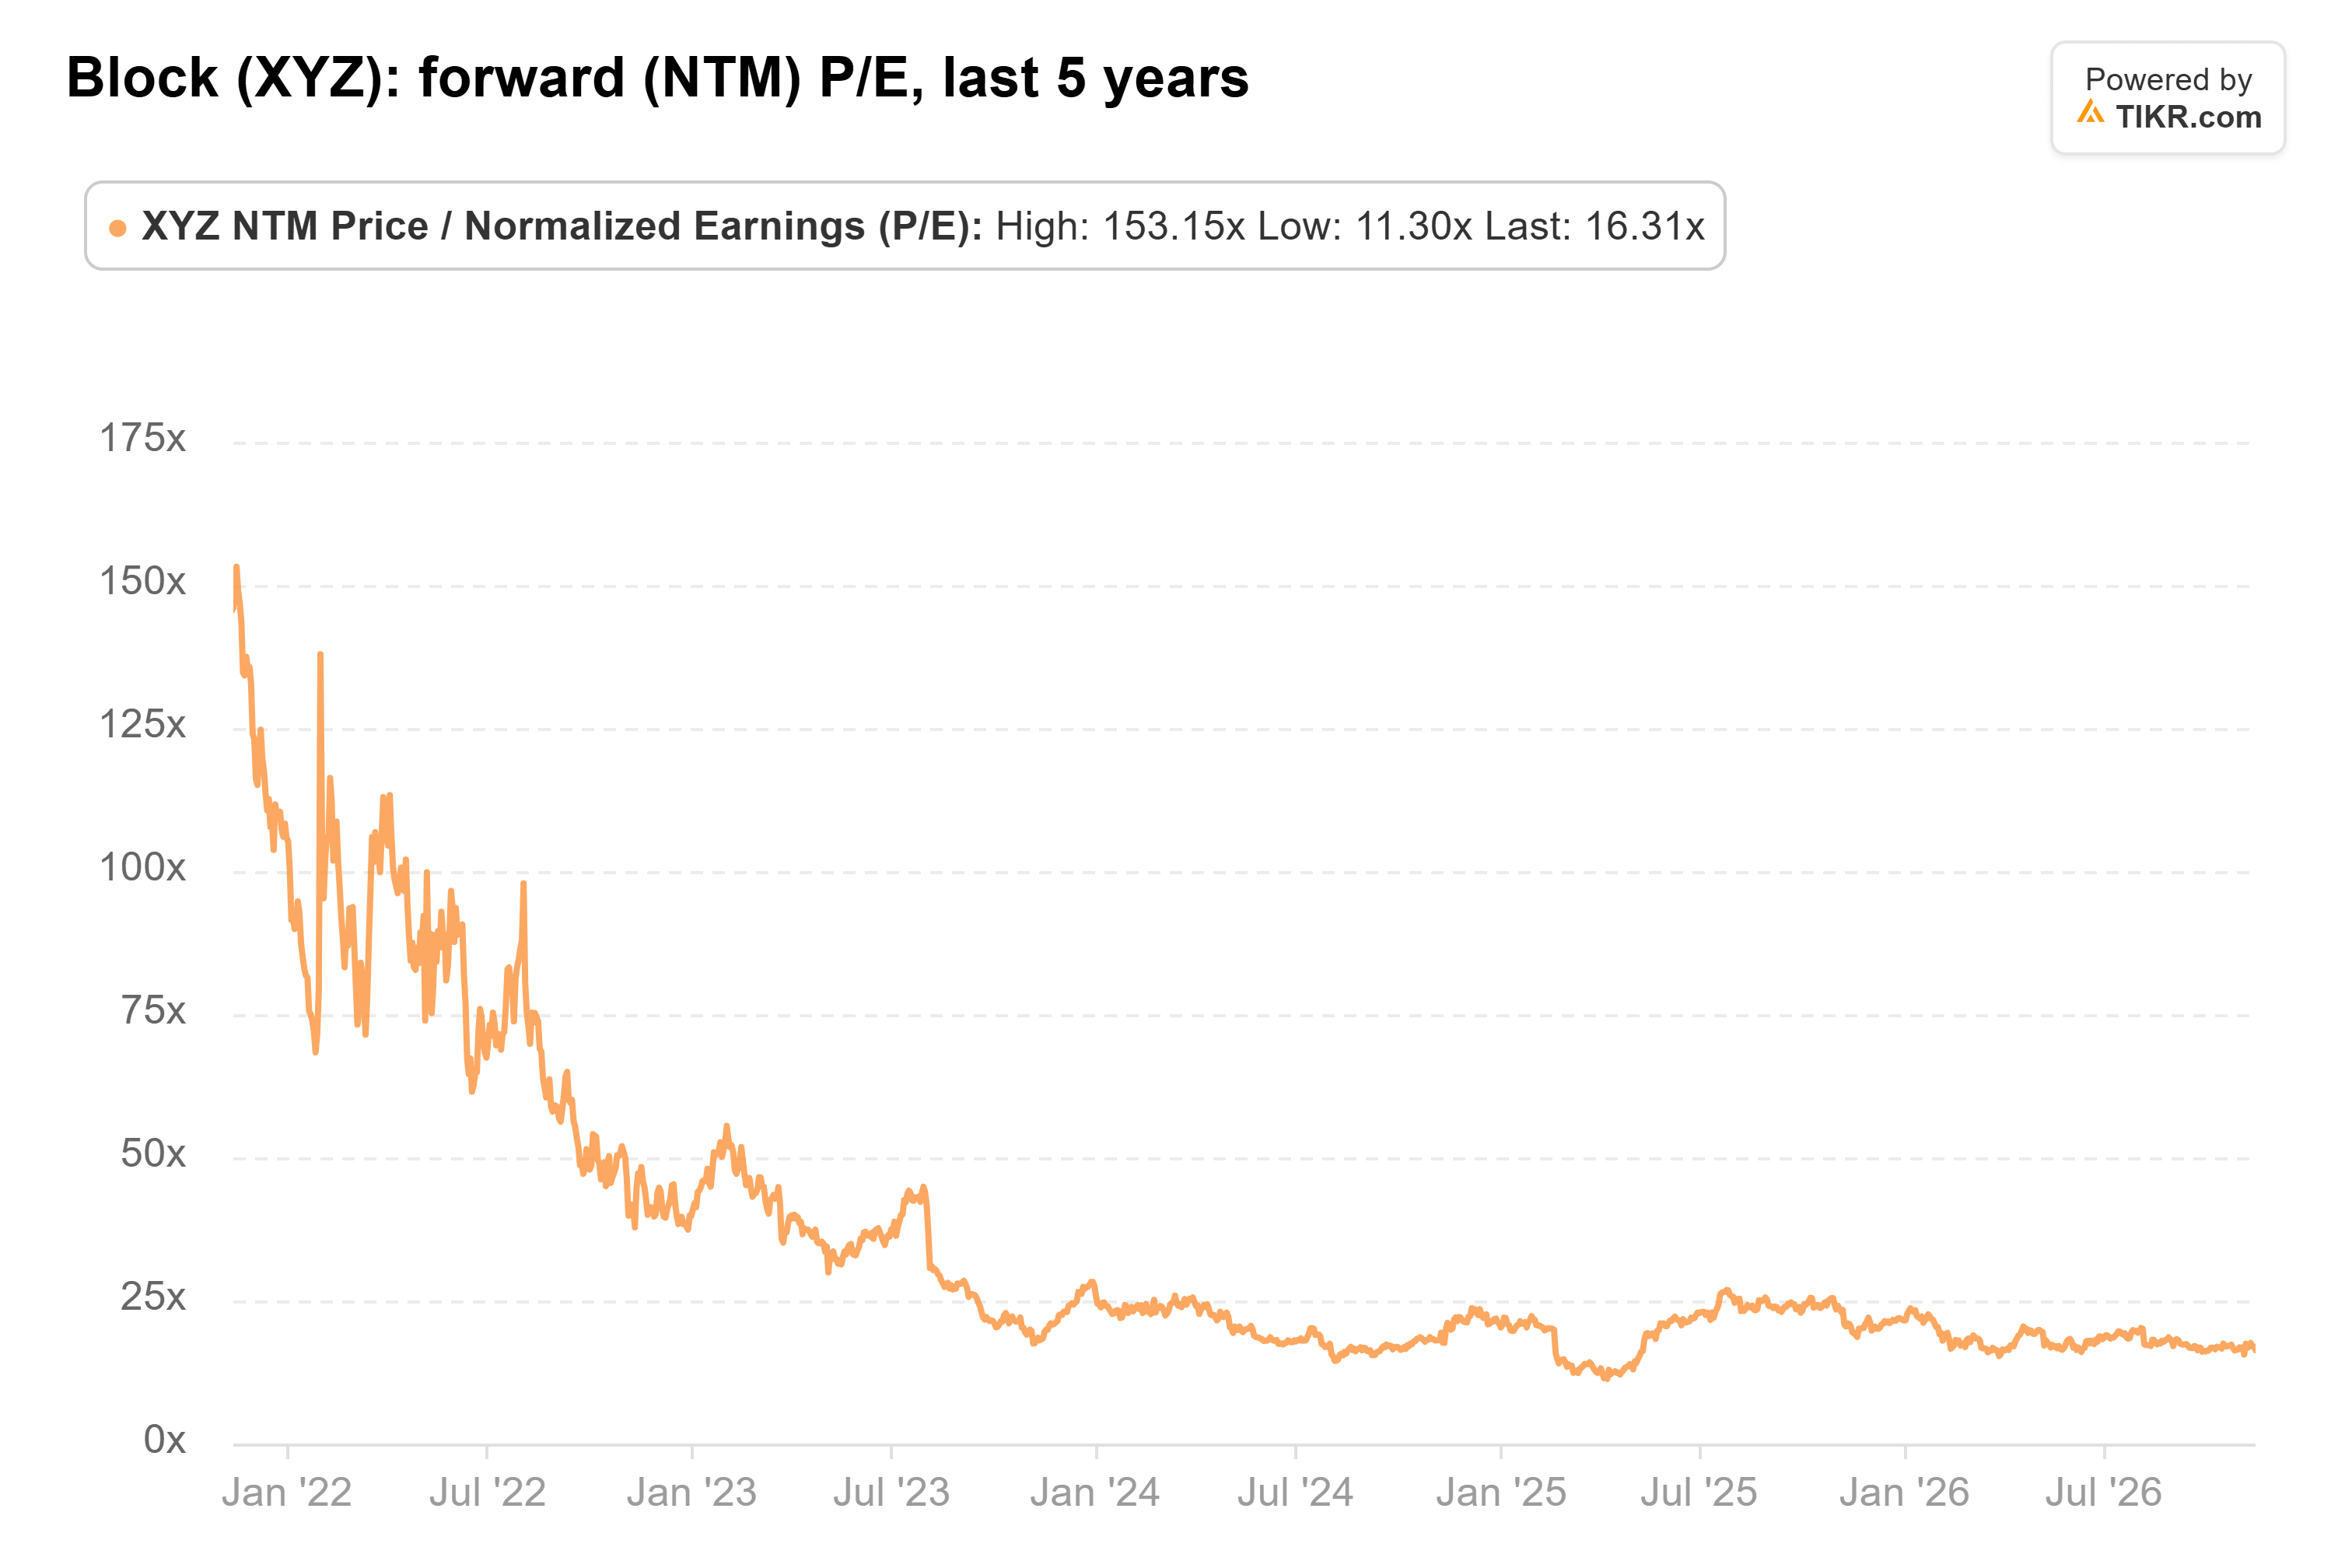
At about 16x forward earnings, it’s under the roughly 20x it has averaged over three years. The $101 consensus target sits about 19% above the last close.
But Block’s losses on loans, receivables and transactions rose 66% to $602 million in the third quarter, or 19% of gross profit. The company has also set aside $764 million for a Justice Department settlement that isn’t final and could cost more.
Block is guiding to 30% growth in operating income next year, and at this multiple I’d buy it. The late-February report needs to show Cash App’s loss growth slowing again.
So what is Block stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Block could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!