


Key Takeaways
- Monolothic Power Systems’s NTM price-to-normalized-earnings multiple has compressed to 38.01x, below its own two-year average of 48.33x, even after Q2 revenue rose 47.6% year over year to a record $980.6 million and management guided Q3 above consensus.
- Wall Street hasn’t followed the stock down. The mean 12-month price target has climbed to $1,839.80 with 13 buy and 3 outperform ratings and zero sells, pushing the target-to-price ratio to 151.1%, the widest gap in over a year of tracked data.
- Free cash flow margin fell to 14.84% in the quarter ended June 30, 2026, down from 22.31% the prior quarter, even as revenue hit a record, suggesting the company’s capacity build-out, including a new GlobalFoundries Singapore fab partnership, is pressuring near-term cash conversion.
- Two directors and an EVP disclosed multiple stock sales over the summer, including a $16.28 million sale by EVP Maurice Sciammas in mid-July, while the stock traded within reach of its year-to-date high.
Some of these numbers don’t sit comfortably next to each other. Explore the full multiples history and analyst target trends on TIKR for free →.
Monolithic Power Stock Has Lost Its Post-Earnings Premium
Monolithic Power Systems (MPWR) closed at $1,217.80 on September 18, 2026. That’s a real gain from a year earlier, but it’s also well off the level the stock traded near right after its Q2 2026 print, and it sits alongside a multiple that has come down hard.
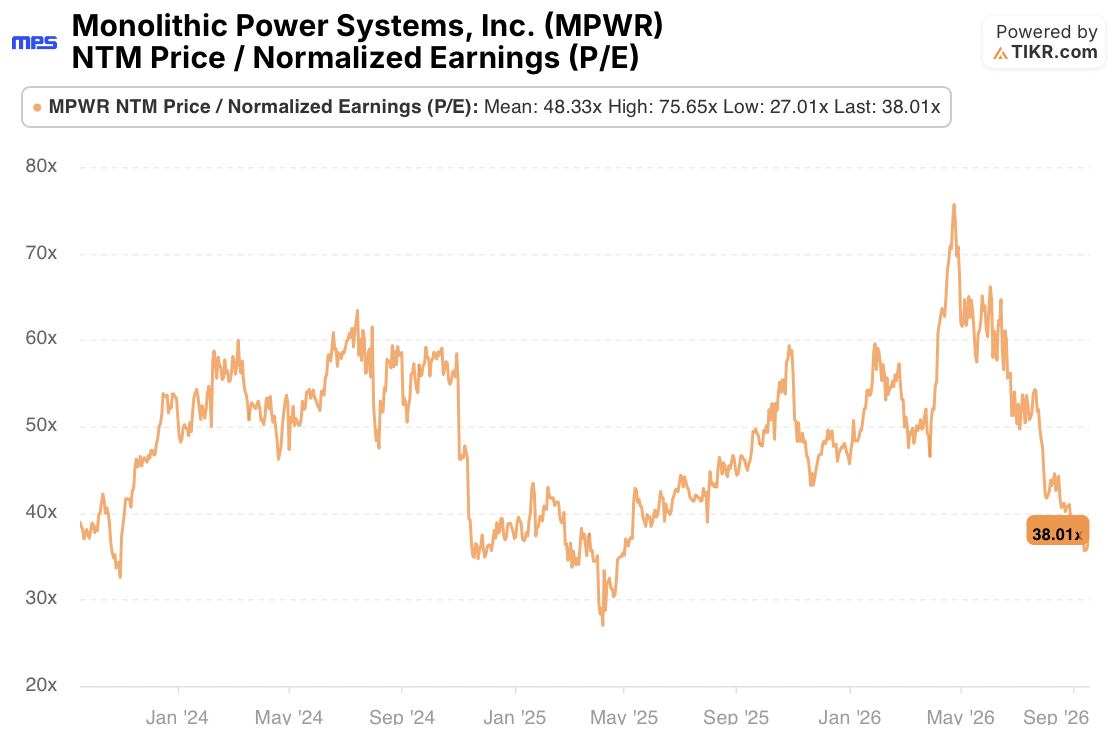
The stock’s NTM price-to-normalized-earnings ratio peaked at 75.65x earlier this year and now sits at 38.01x, below its own trailing two-year mean of 48.33x.
That compression is happening against one of the stronger operating quarters in the company’s history. Q2 revenue hit a record $980.6 million, up 21.9% sequentially and 47.6% year over year, with GAAP net income rising 90.6% and adjusted EPS of $6.50 beating the $5.87 estimate. Management didn’t hedge the outlook either. Q3 guidance of $1.14 billion to $1.16 billion came in well above the Street’s prior estimate of roughly $981.9 million, the board added $500 million to buyback authorization for a total of $1 billion, and the company kept its quarterly dividend at $2.00 per share into Q3.
In early September, MPS also signed a long-term manufacturing agreement with GlobalFoundries to deploy its power process technology at a 300mm Singapore fab, aimed at diversifying supply and supporting new 800-volt data center products. None of that reads like a company whose valuation should be shrinking toward its own historical floor.
Wall Street Hasn’t Backed Off the Bull Case
If the market were simply repricing MPWR for a genuine growth slowdown, the sell side would likely be trimming targets alongside it. It hasn’t.
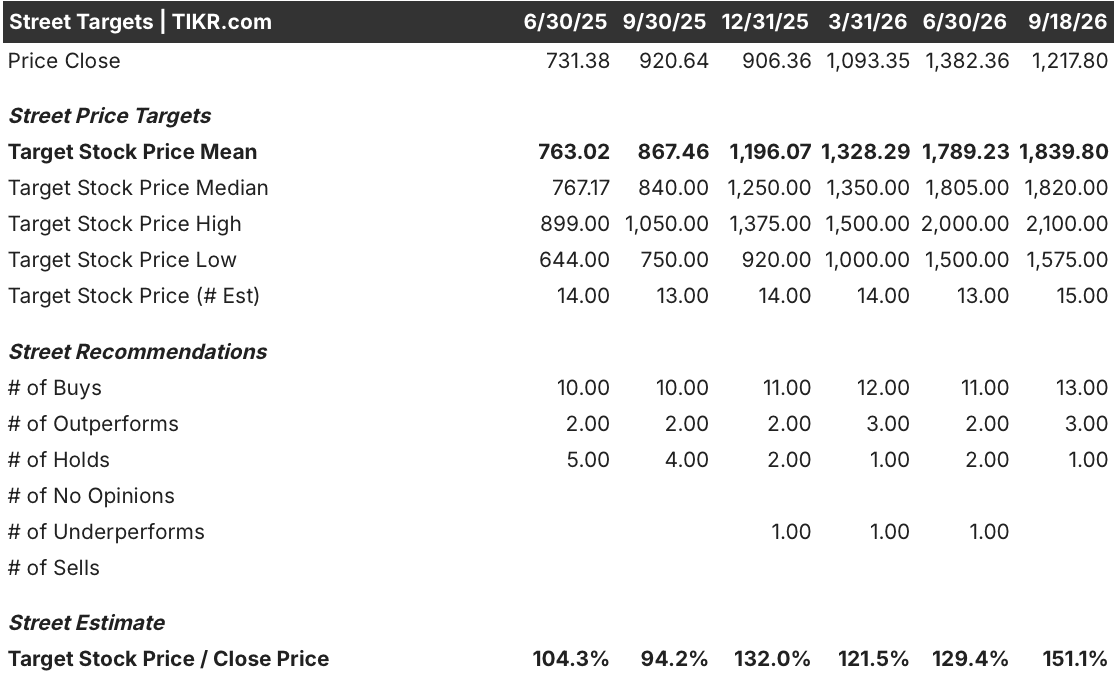
The mean 12-month price target has risen from $763.02 in June 2025 to $1,839.80 as of September 18, 2026, with the median at $1,820.00 and 13 buy and 3 outperform ratings against just a single hold and zero sells. The result is a target-to-close ratio of 151.1%, the highest reading across the past six quarters of tracked data and well above the 104.3% to 132.0% range the stock traded at for most of the prior year.
That’s a wide gap for a stock this closely followed, and it cuts two ways. It could mean the market is undervaluing a company still compounding revenue near 50% year over year, with management describing broad-based order strength in Enterprise Data, Communications, and Automotive on the Q2 2026 earnings call. Or it could mean analyst models haven’t yet caught up to a more cautious read the market is already pricing in.
The insider activity adds a data point worth weighing rather than dismissing: director Herbert Chang disclosed sales in August, and EVP Maurice Sciammas sold $16.28 million in shares in mid-July, all while the stock traded within roughly 15% of its year-to-date high. Insider sales alone don’t settle a valuation argument, but they’re not the signal you’d expect if everyone closest to the business shared the sell side’s growing conviction.
The Cash Flow Question Behind MPWR’s Capacity Build-Out
The clearest evidence for caution shows up not in the multiple or the target table but in cash generation.

Monolithic Power Systems stock’s free cash flow margin was 26.69% in the quarter ended September 30, 2025, fell sharply to 8.51% by December 31, 2025, recovered to 22.31% in the March 2026 quarter, and slipped again to 14.84% in the quarter ended June 30, 2026, even as that same quarter delivered record revenue. Free cash flow in dollar terms was actually lower in the June 2026 quarter ($0.15 billion) than in four of the prior seven quarters shown.
That pattern matters because it lines up with what management described on the call: capacity expansion is no longer just about wafers, but about building out module assembly and back-end qualification, which Michael Hsing called “more complicated than you assemble a phone.”
The GlobalFoundries partnership and the broader push past $6 billion in capacity goals cost money before they show up as revenue. A revenue story growing near 50% year over year should, in a steady state, generate rising free cash flow margin, not a second consecutive sequential decline. That gap between top-line acceleration and cash conversion is a more concrete reason for a valuation reset than sentiment alone.
What Would Actually Resolve MPWR’s Valuation Gap
The honest read is that Monolithic Power Systems’ multiple compression, Wall Street’s rising targets, and the softening free cash flow margin aren’t contradictory so much as they’re describing different time horizons. The Street’s targets assume the capacity investment converts into the durable, diversified growth management keeps describing across Enterprise Data, Communications, and Automotive. The market’s lower multiple reflects that this conversion hasn’t shown up in cash yet, and the insider sales suggest at least some people closest to the numbers aren’t in a hurry to bet otherwise.
Q3 results, expected in late October, will be the test. If free cash flow margin stabilizes back above the 20% range the company posted in most of 2025 while revenue keeps climbing toward the guided $1.14-1.16 billion, that would support the Street’s continued optimism and suggest the current multiple is genuinely cheap relative to the growth on offer.
If margin keeps drifting toward the 8.51% low from late 2025, that’s a sign the capacity build-out is a structural drag on cash conversion rather than a one-quarter anomaly, and the valuation gap may be more rational than it looks.
Watch whether free cash flow catches up to revenue growth before deciding which side of this gap is right. Compare MPWR’s next cash flow print against this quarter’s numbers on TIKR for free →.
Should You Invest in Monolithic Power Systems, Inc.?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up MPWR stock and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Monolithic Power Systems, Inc. alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Access Professional Tools to Analyze MPWR stock on TIKR for Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


