Key Takeaways
- UnitedHealth’s adjusted EPS jumped 61% to $4.69, beating the $4.14 estimate, as the medical cost ratio improved to 88.4%.
- Management raised 2026 adjusted EPS guidance to at least $20.50, its third raise this year, and still targets 13% to 16% long-term growth.
- Revenue slipped to $112.7 billion and UnitedHealthcare served 48.3 million people, down from about 50.1 million, so margins carry the recovery.
- The next test comes in January 2027, when 2027 guidance shows whether reserve releases flattered this year’s margin recovery.
UnitedHealth Group (UNH) has figured out how to grow earnings quickly while getting smaller.
The stock rose 1.9% to $425 on Thursday, about 9% above where it traded before its Q3 report on October 13. Shares now show a 26.4% total return this year, after falling about 20% in the first quarter.
The quarter gave the rally its fuel. Adjusted EPS jumped 61%, the medical cost ratio fell 150 basis points, and management raised 2026 guidance for the third time.
CEO Stephen Hemsley credited “the discipline and execution” of his teams. The numbers mostly back him up, but the revenue line deserves a closer look.
Cheaper care, fatter margins
UnitedHealth beat on nearly every line that matters for profit:
- Adjusted EPS of $4.69, up from $2.92 a year ago and well above the $4.14 estimate
- A medical cost ratio of 88.4%, down from 89.9%
- Operating income of $6.6 billion, up from $4.3 billion
Revenue of $112.7 billion also topped the $111.4 billion consensus, although it slipped from $113.2 billion a year earlier. The operating cost ratio improved to 12.8% from 13.5%, so efficiency helped alongside pricing.
For context, Centene (CNC) posted a 94.3% medical cost ratio in its fourth quarter of 2025, a reminder of how fast cost trends can swamp an insurer.
One caveat deserves a flag. The quarter included $610 million of favorable reserve releases, which flatter a single period and do not repeat on command.
The margin repair is easiest to see quarter by quarter.
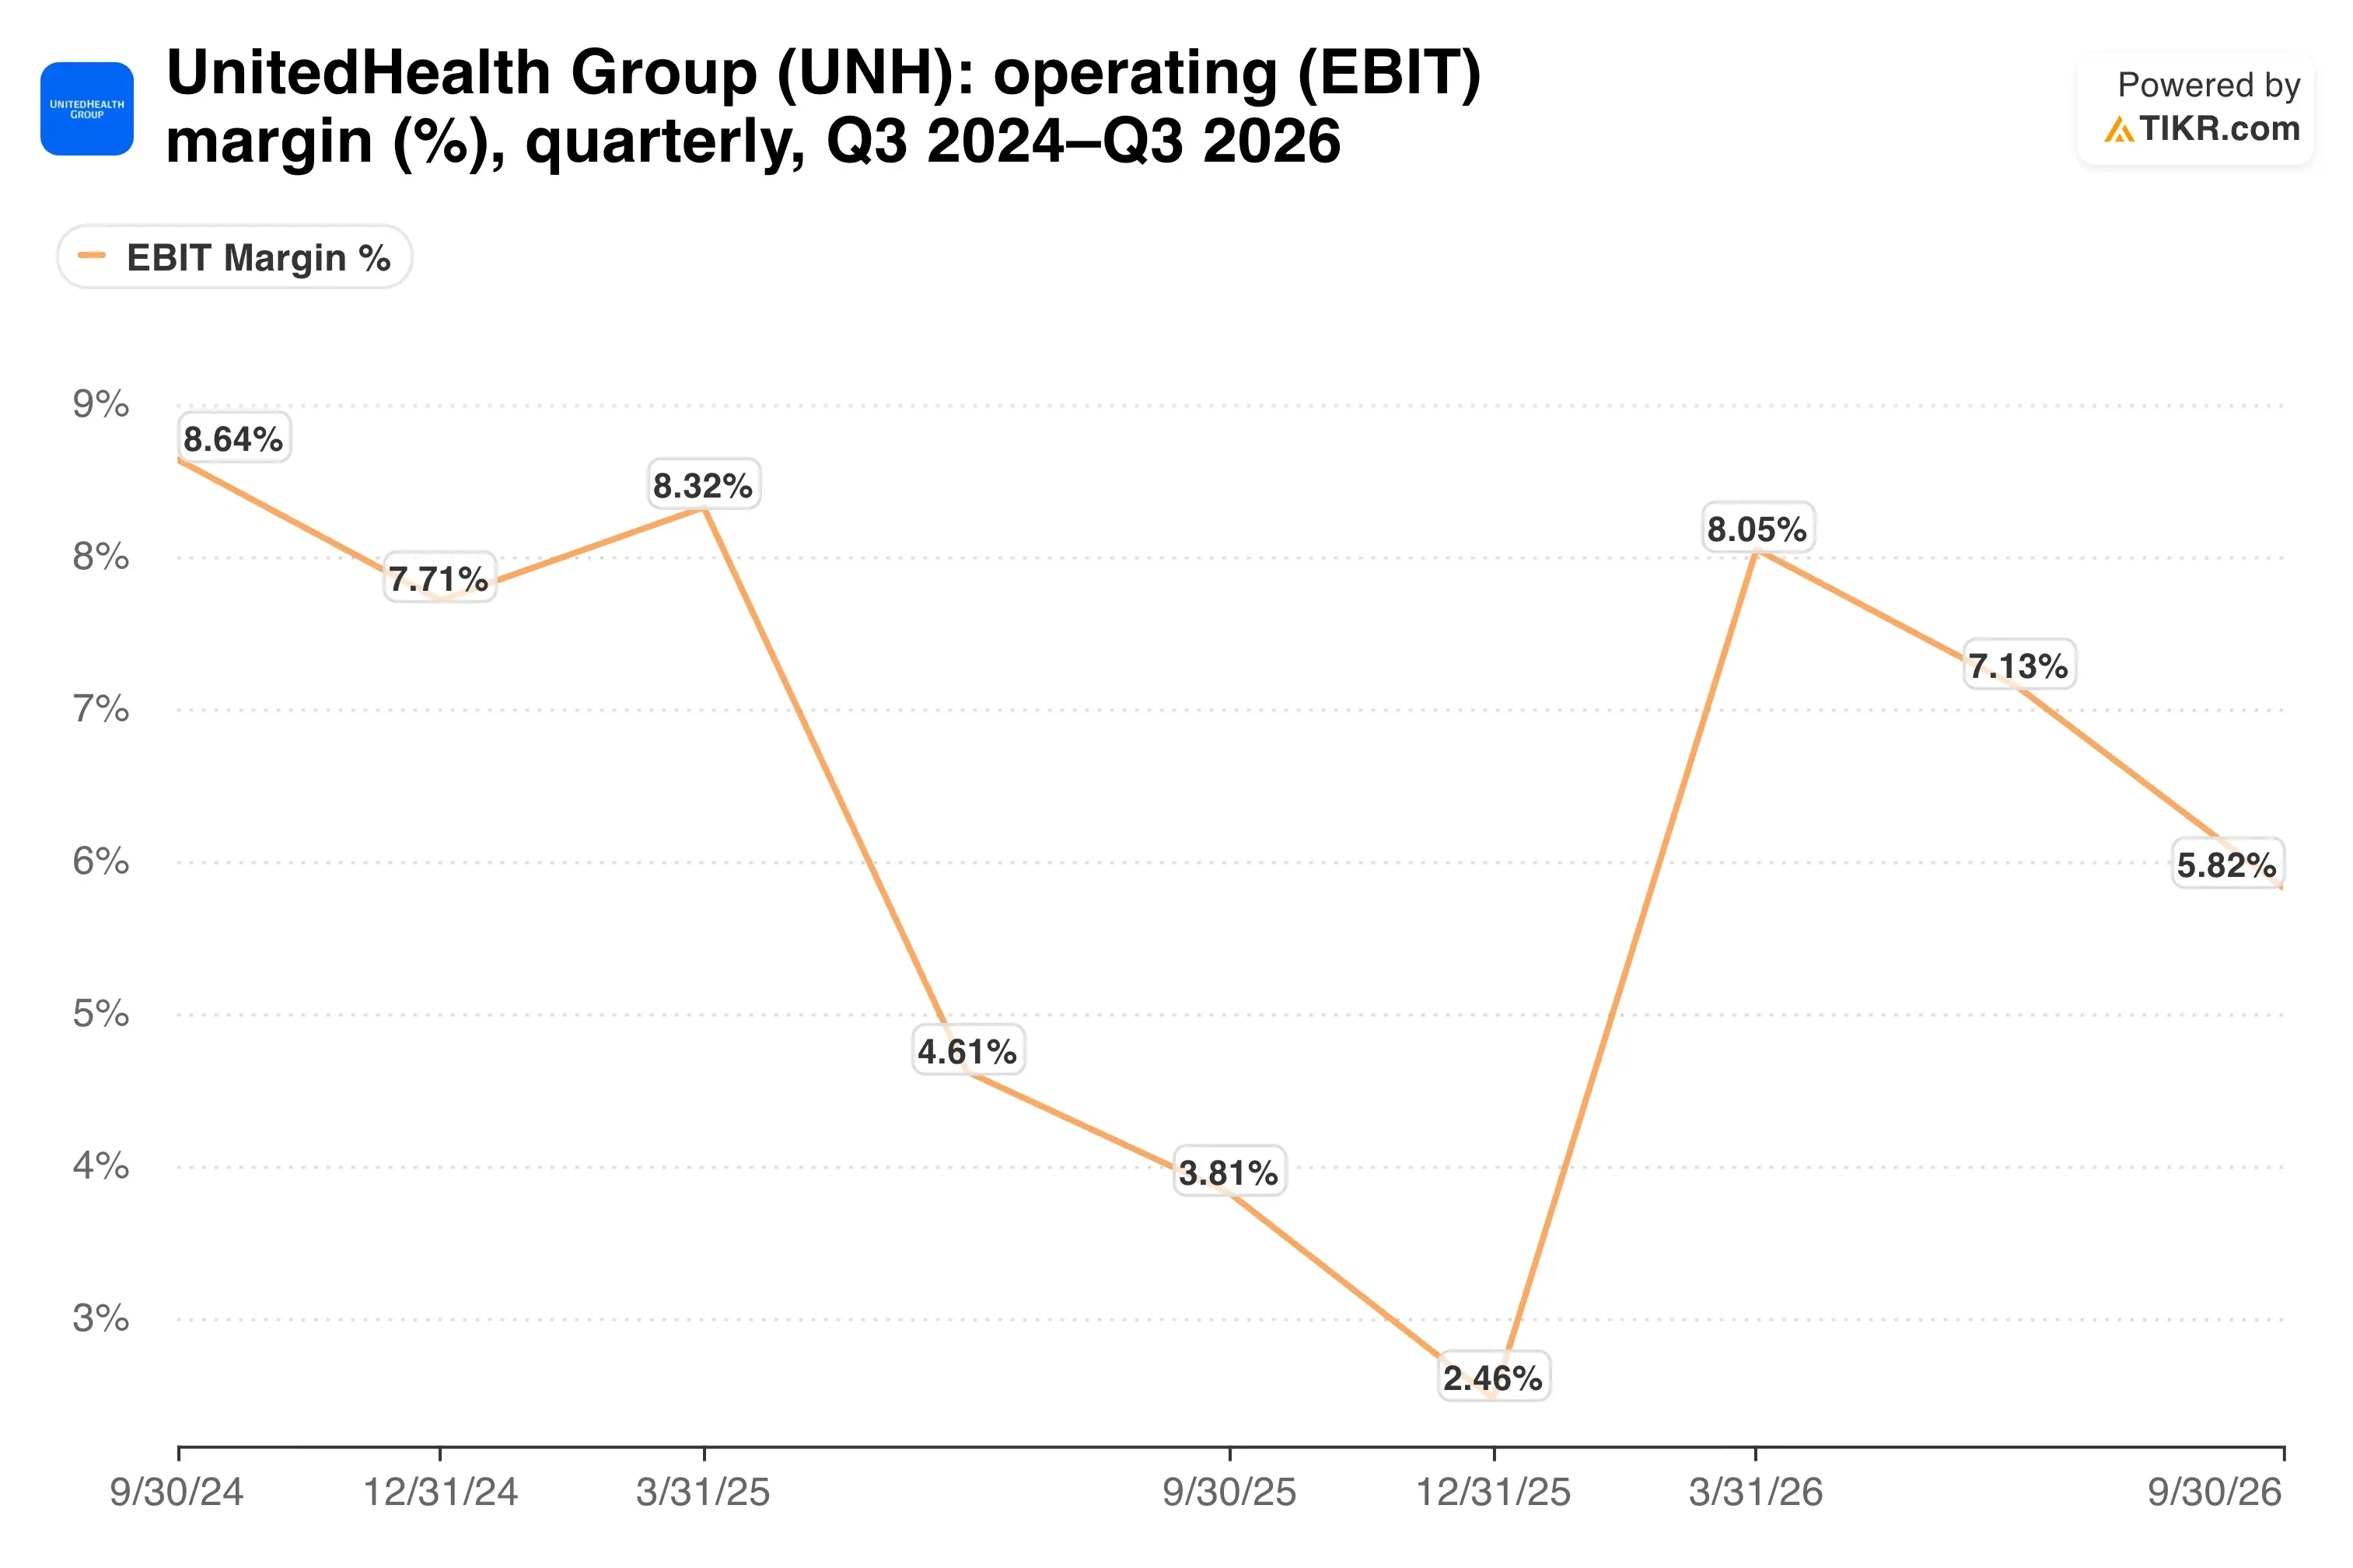
Operating margin is back near 6%, still well short of the 8%-plus UnitedHealth earned in 2023.
Optum shrinks its way to profit
Optum did the heavy lifting. Revenue reached $66.9 billion and operating earnings rose to $3.7 billion from $2.5 billion.
Optum Health is the real swing factor. Its revenue fell 10% as UnitedHealth exited smaller value-based care markets, yet operating earnings jumped to $735 million from $41 million.
Optum Rx gained from biosimilar adoption, though adjusted scripts fell to 393 million from 414 million. And UnitedHealthcare served 48.3 million people, down from about 50.1 million a year earlier.
The company also agreed to exit international private medical insurance, with The Cigna Group (CI) becoming the preferred insurer for its global clients. It is one more step toward a simpler, U.S.-focused company.
So where is the revenue going?
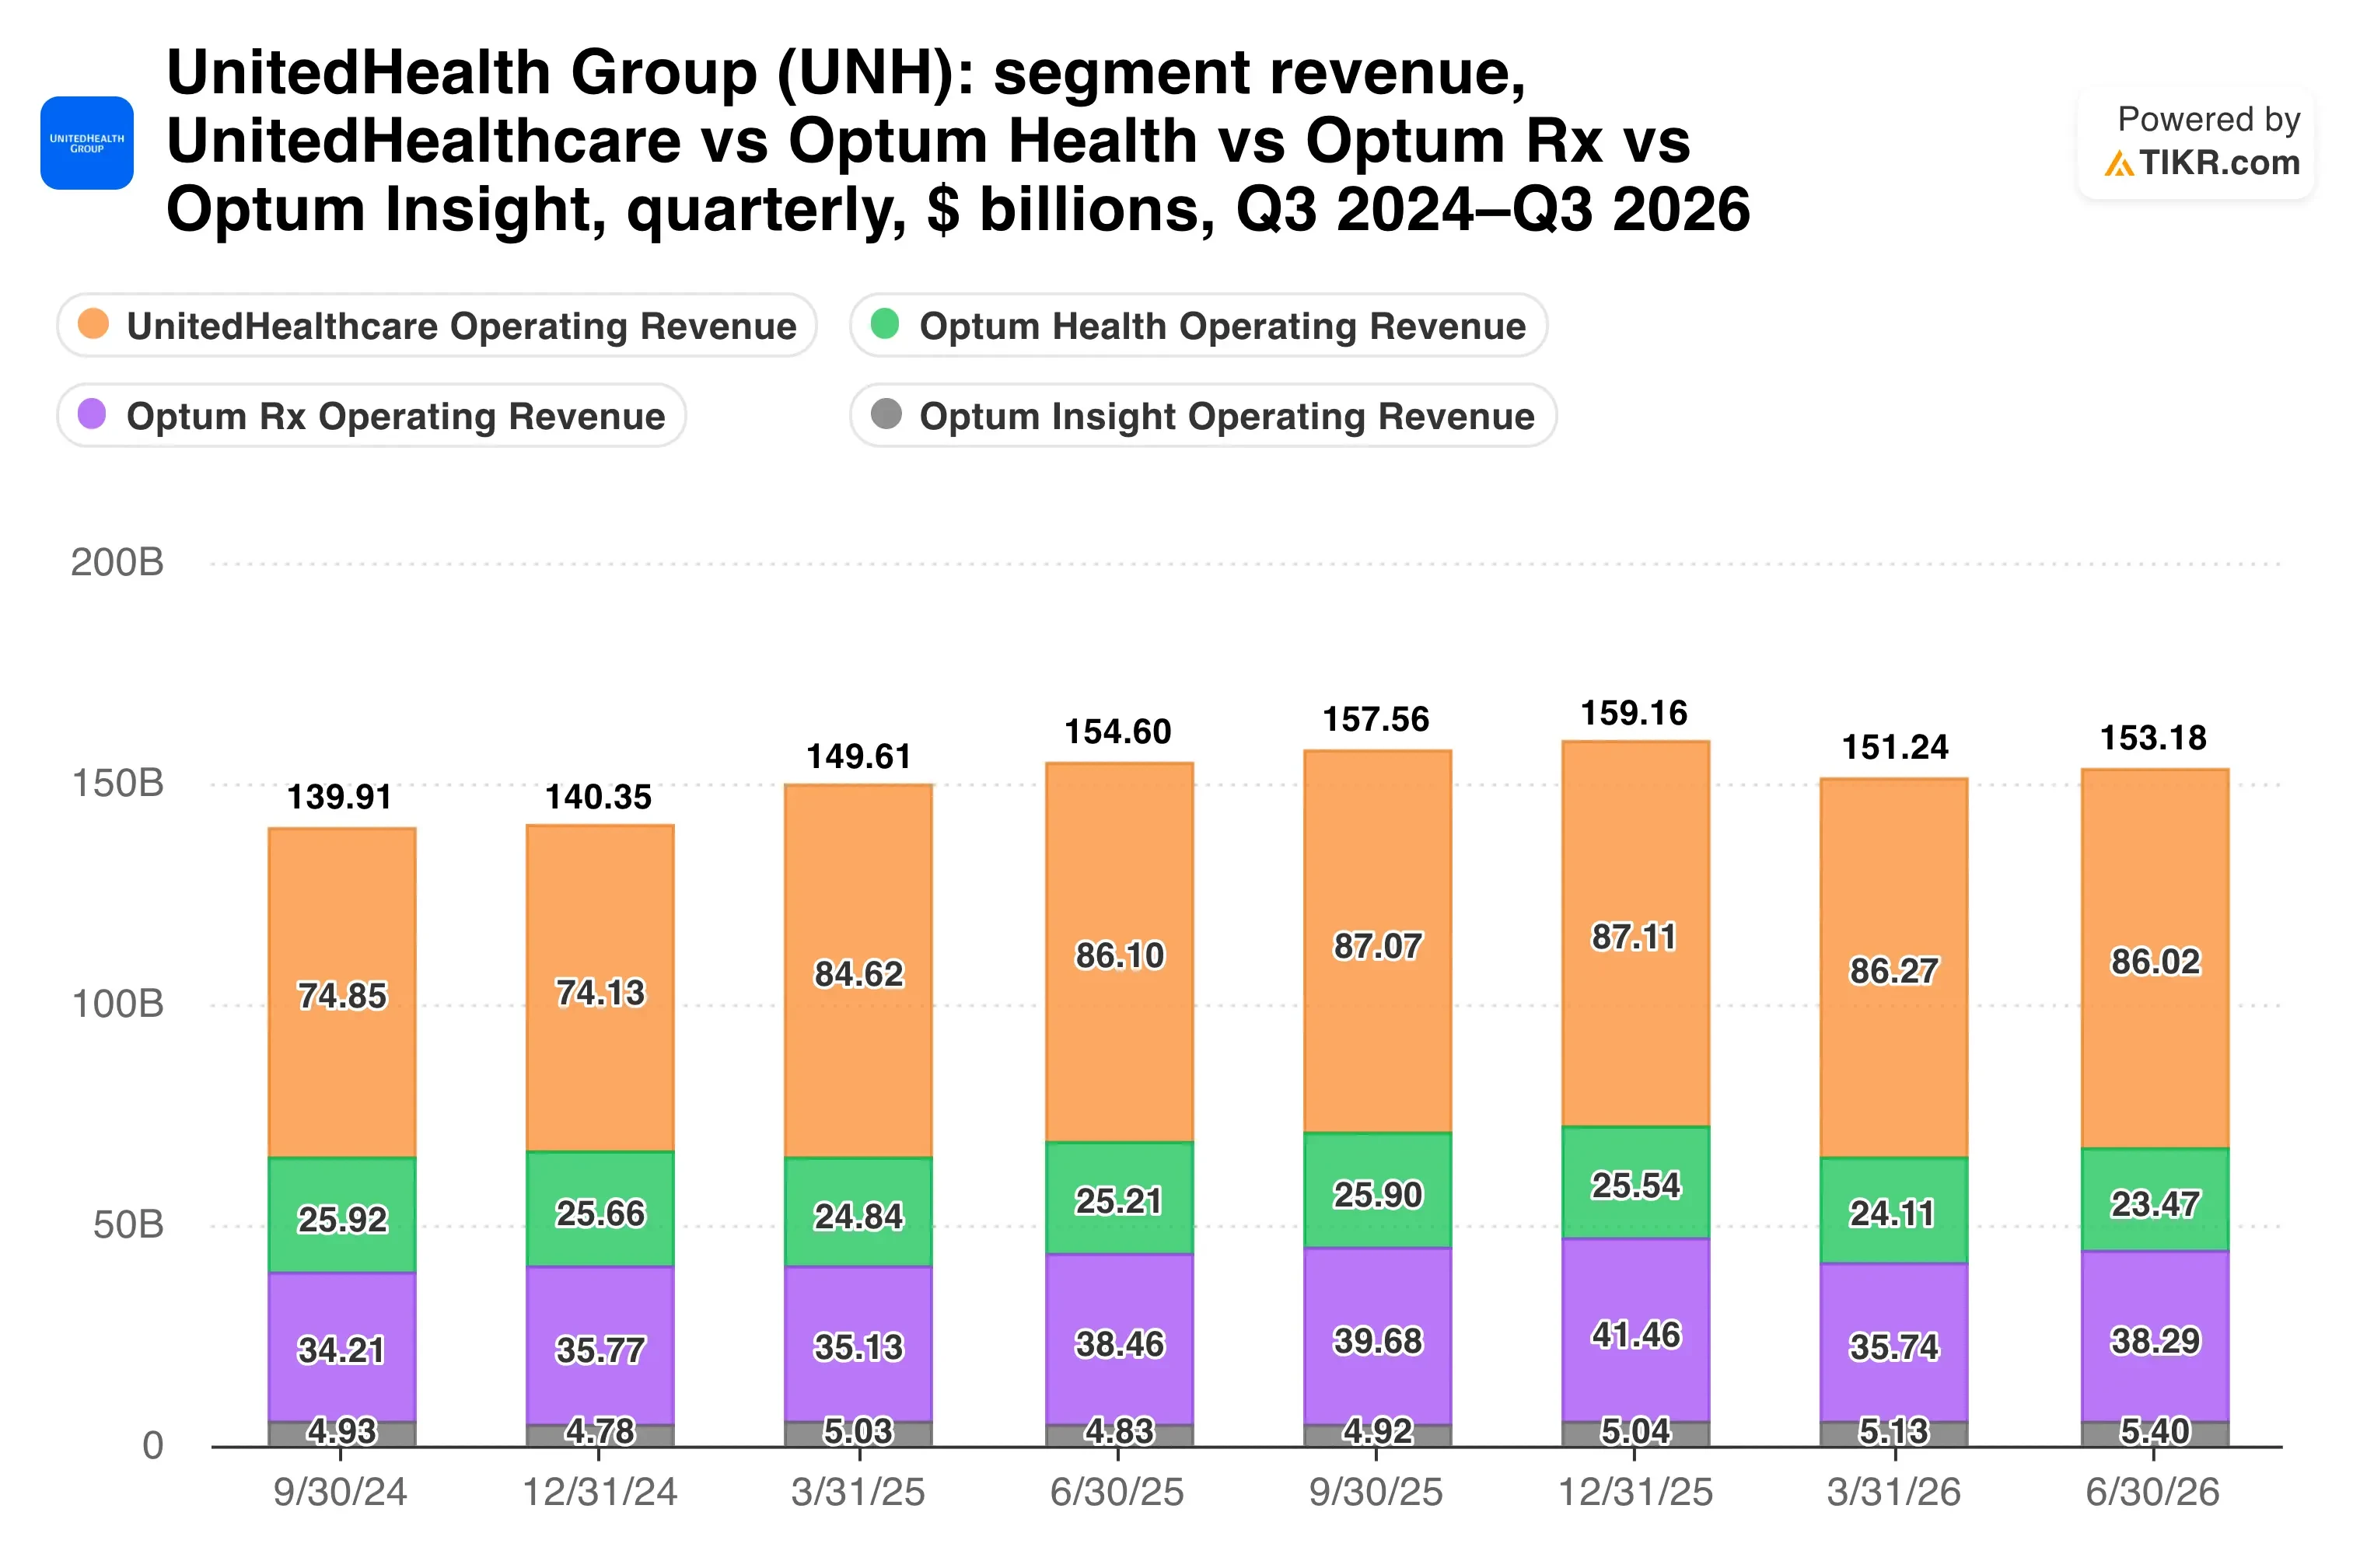
The segments show a company trading members and contracts for margin, and that trade has a limit.
TIKR tracks 26 analysts on UnitedHealth. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on UnitedHealth, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See UnitedHealth’s Analyst Ratings
Priced for a clean 2027
At $425, UnitedHealth trades at 18.4x forward earnings, and the average Street target of $478 implies about 12% upside. Consensus expects EPS to grow 19.3% a year over the next two years, after a 9.7% annual decline over the past three.
Management also said it still expects 2027 growth within its 13% to 16% long-term range. That leaves little room for another bad cost surprise.
Risks have not gone away. Individual market enrollment fell to 20.5 million as of June, and Medicare Advantage funding stays a political lever heading into the midterms.
Here is how far the earnings path still has to run…
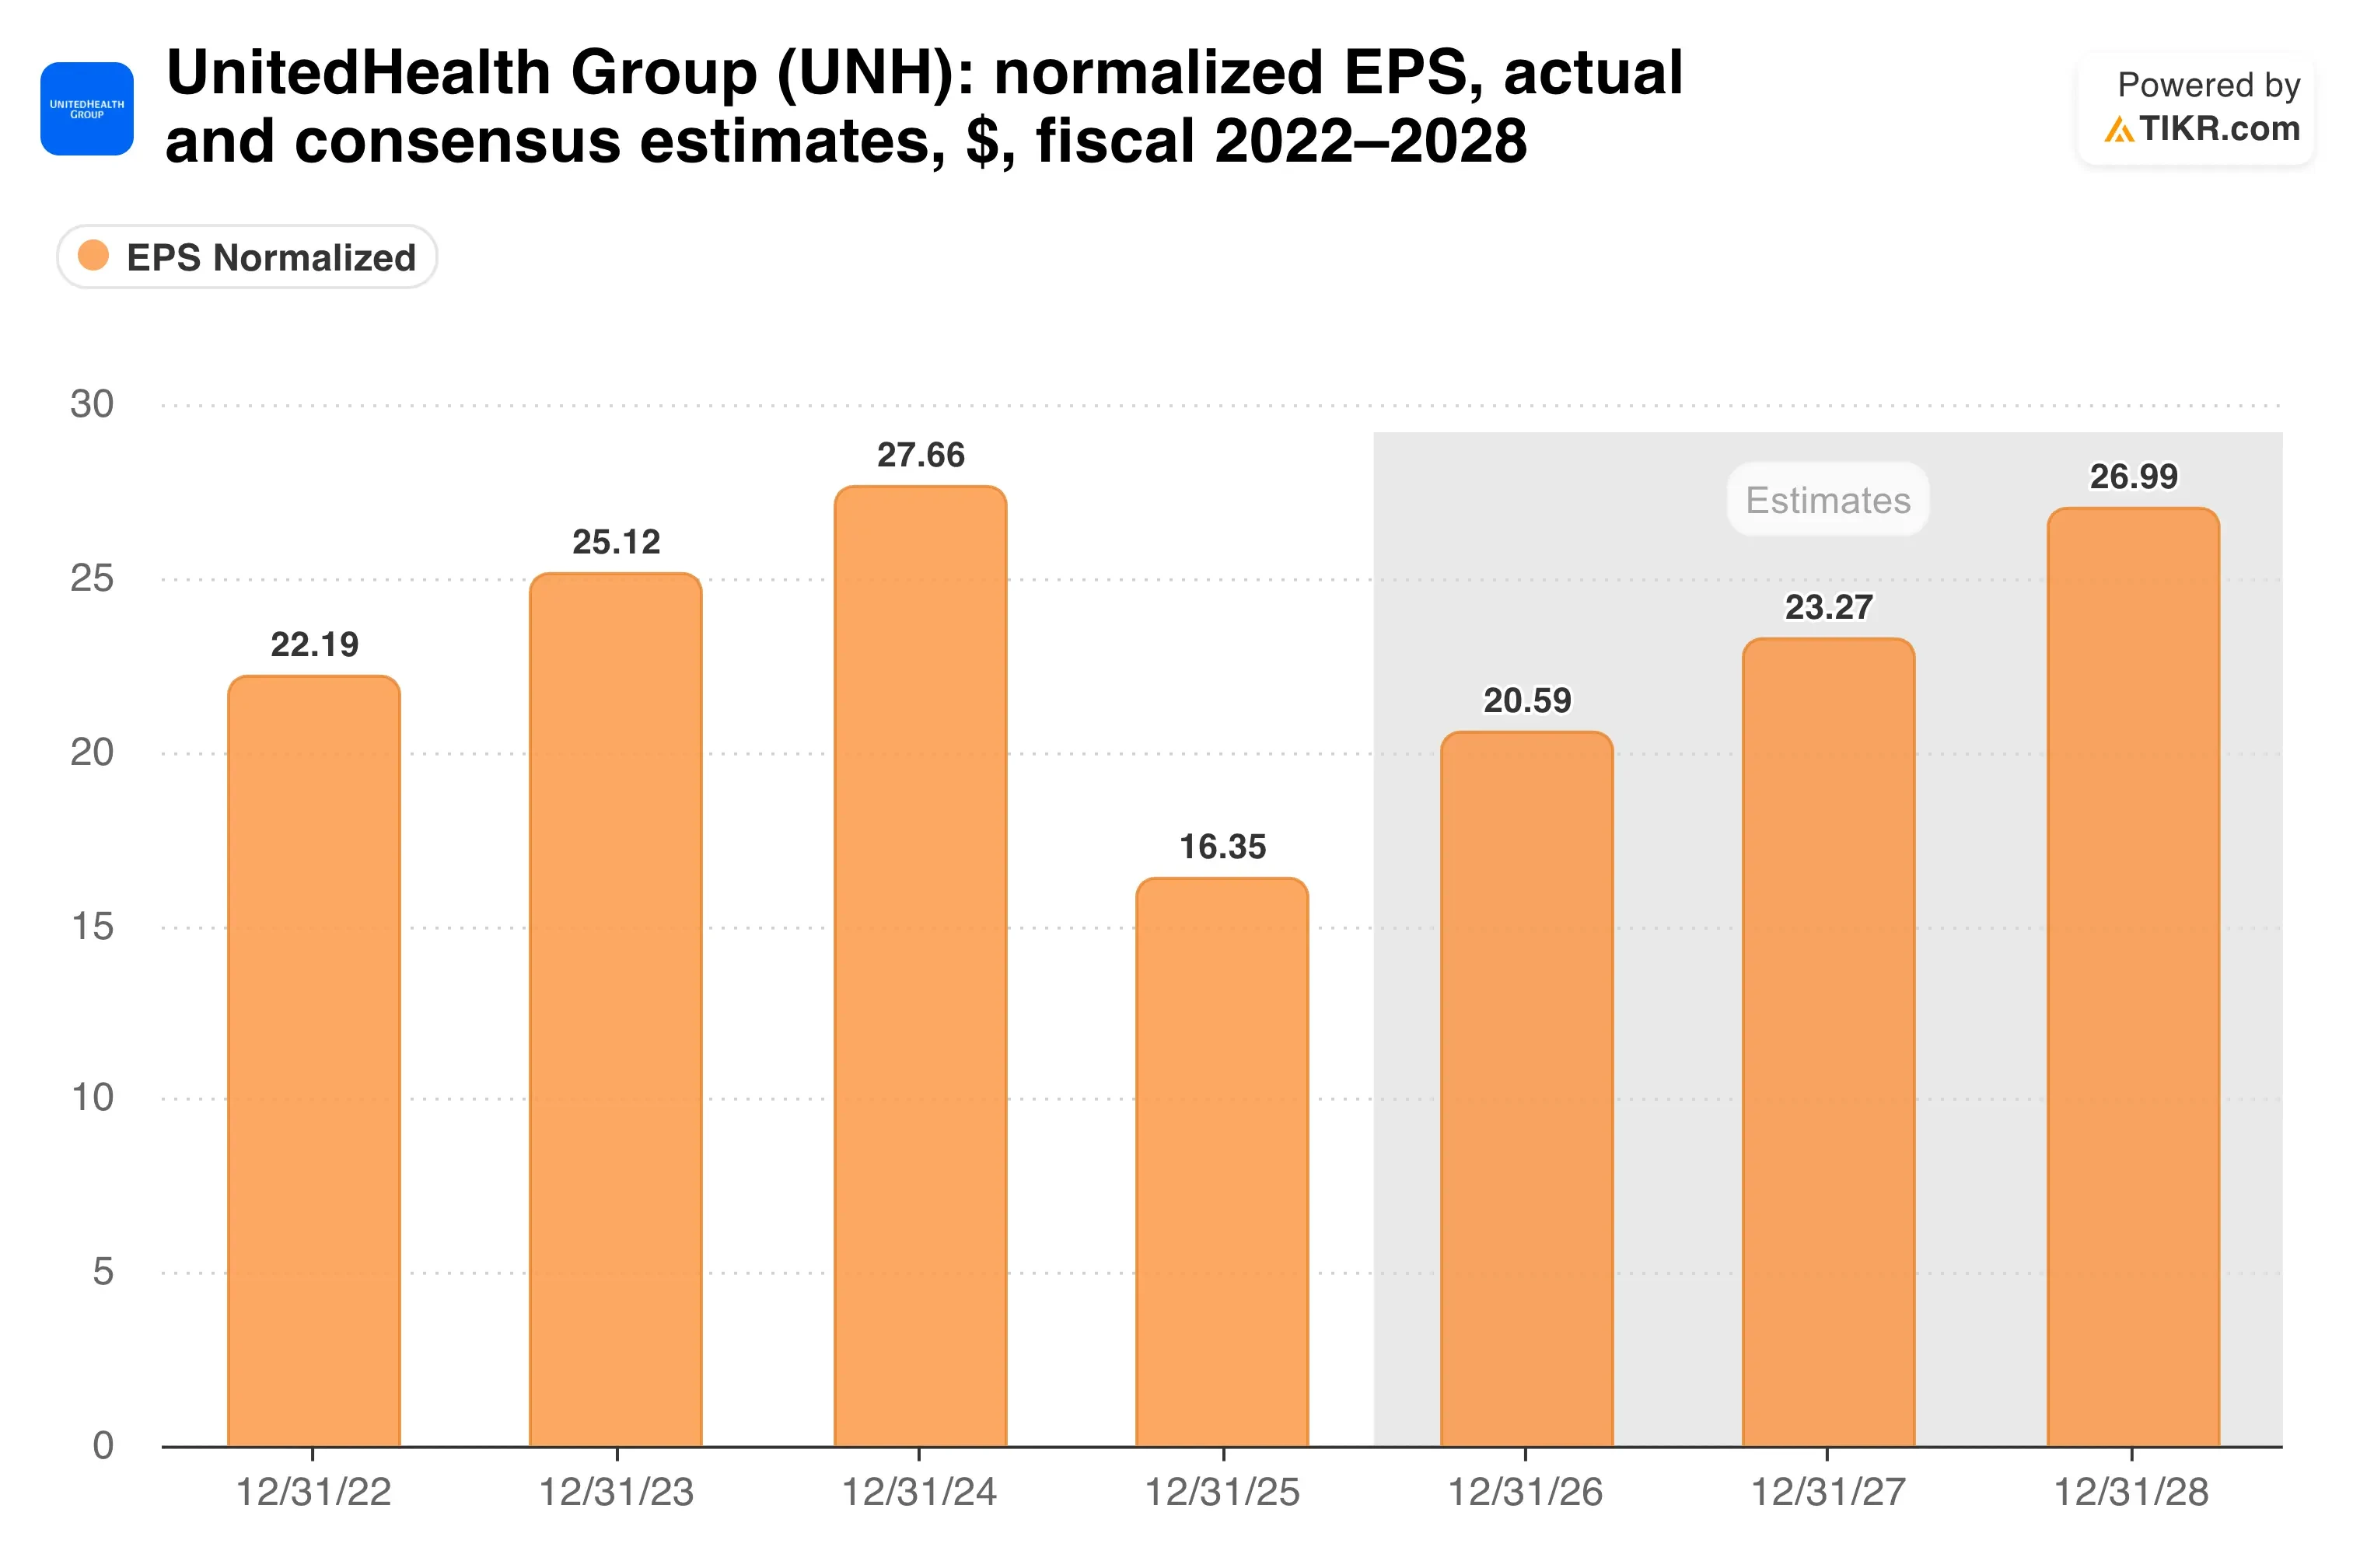
My take: This is a genuine turnaround, and Optum Health’s swing from $41 million to $735 million shows the fixes are working. Still, reserve releases and shrinking membership did part of the work, so I treat $20.50 as a floor management chose carefully.
Full-year results, expected around January 12, 2027, will bring the first 2027 guidance. That number will show whether the 13% to 16% target survives a full year of lower revenue.
So what is UnitedHealth stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what UnitedHealth could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!