Key Takeaways
- Chevron will hand its Hess Midstream stake and DJ Basin crude assets to Hess Midstream for $200 million plus contracts that cut Bakken unit midstream costs about 50%.
- The deal triggers a one-time after-tax loss of $3 billion to $4 billion at closing, which Chevron will treat as a special item.
- Shares trade near $227 after a 49.5% total return this year, with oil above $100 and consensus EPS growth of 46.8% annually.
- Q3 results on October 30 will show whether high prices offset 150,000 to 200,000 boe per day of turnarounds and downtime.
Chevron (CVX) is tidying its portfolio while oil prices do the heavy lifting.
Oil topped $100 last week on supply fears, and U.S. energy stocks climbed again this week on worries about attacks in Saudi Arabia. Chevron traded near $227 on Thursday, good for a 49.5% total return so far in 2026.
Meanwhile, management has been busy. In three weeks Chevron agreed to exit Hess Midstream (HESM), signed a fiscal deal with Egypt for the Aphrodite gas field, and moved to sell older U.S. Gulf assets.
None of that changes next week’s earnings much. All of it changes what Chevron looks like in 2028.
Swapping equity for cheaper pipes
The Hess Midstream deal trades ownership for lower costs:
- Chevron hands over its stake and general partner position in Hess Midstream, plus its DJ Basin crude midstream assets
- It gets $200 million in cash and extended Bakken contracts that cut unit midstream costs by about 50%
- Roughly $3.7 billion of Hess Midstream debt leaves Chevron’s balance sheet
There is a catch. Chevron will book a one-time after-tax loss of $3 billion to $4 billion at closing, since accounting rules will not let it record future Bakken savings as an asset. It plans to treat the hit as a special item, and the deal should close by year-end.
Andy Walz, who runs downstream, midstream and chemicals, said the deal “resets the commercial framework” between Chevron’s upstream and midstream assets.
The payoff shows up in returns, where Chevron expects a lift of 0.5 percentage points…

Half a point sounds small, but on a company earning about 9.4% on capital it is a real step.
Q2 set a high bar
Last quarter showed what Chevron can earn with Hess fully absorbed. Net income reached $12.1 billion, or $6.11 per share, and worldwide production rose 20% from a year earlier.
Cash was the standout. Operating cash flow excluding working capital hit $19.7 billion and free cash flow came in at $18.1 billion, while U.S. production set a record and U.S. refineries ran at 97% utilization.
Refining could matter even more in Q3. Exxon Mobil (XOM) has already signaled a $4.5 billion boost to refining earnings as margins soar, and Chevron’s high utilization should help it share in that tailwind.
Aphrodite is the longer bet. Chevron operates the Cyprus field with Shell (SHEL) and NewMed Energy (NWMD), and the Egypt agreement opens a path to send gas into Egyptian infrastructure for local use or LNG export. The project remains in front-end engineering, so it adds nothing to earnings yet.
Quarter by quarter, the cash swing looks like this.
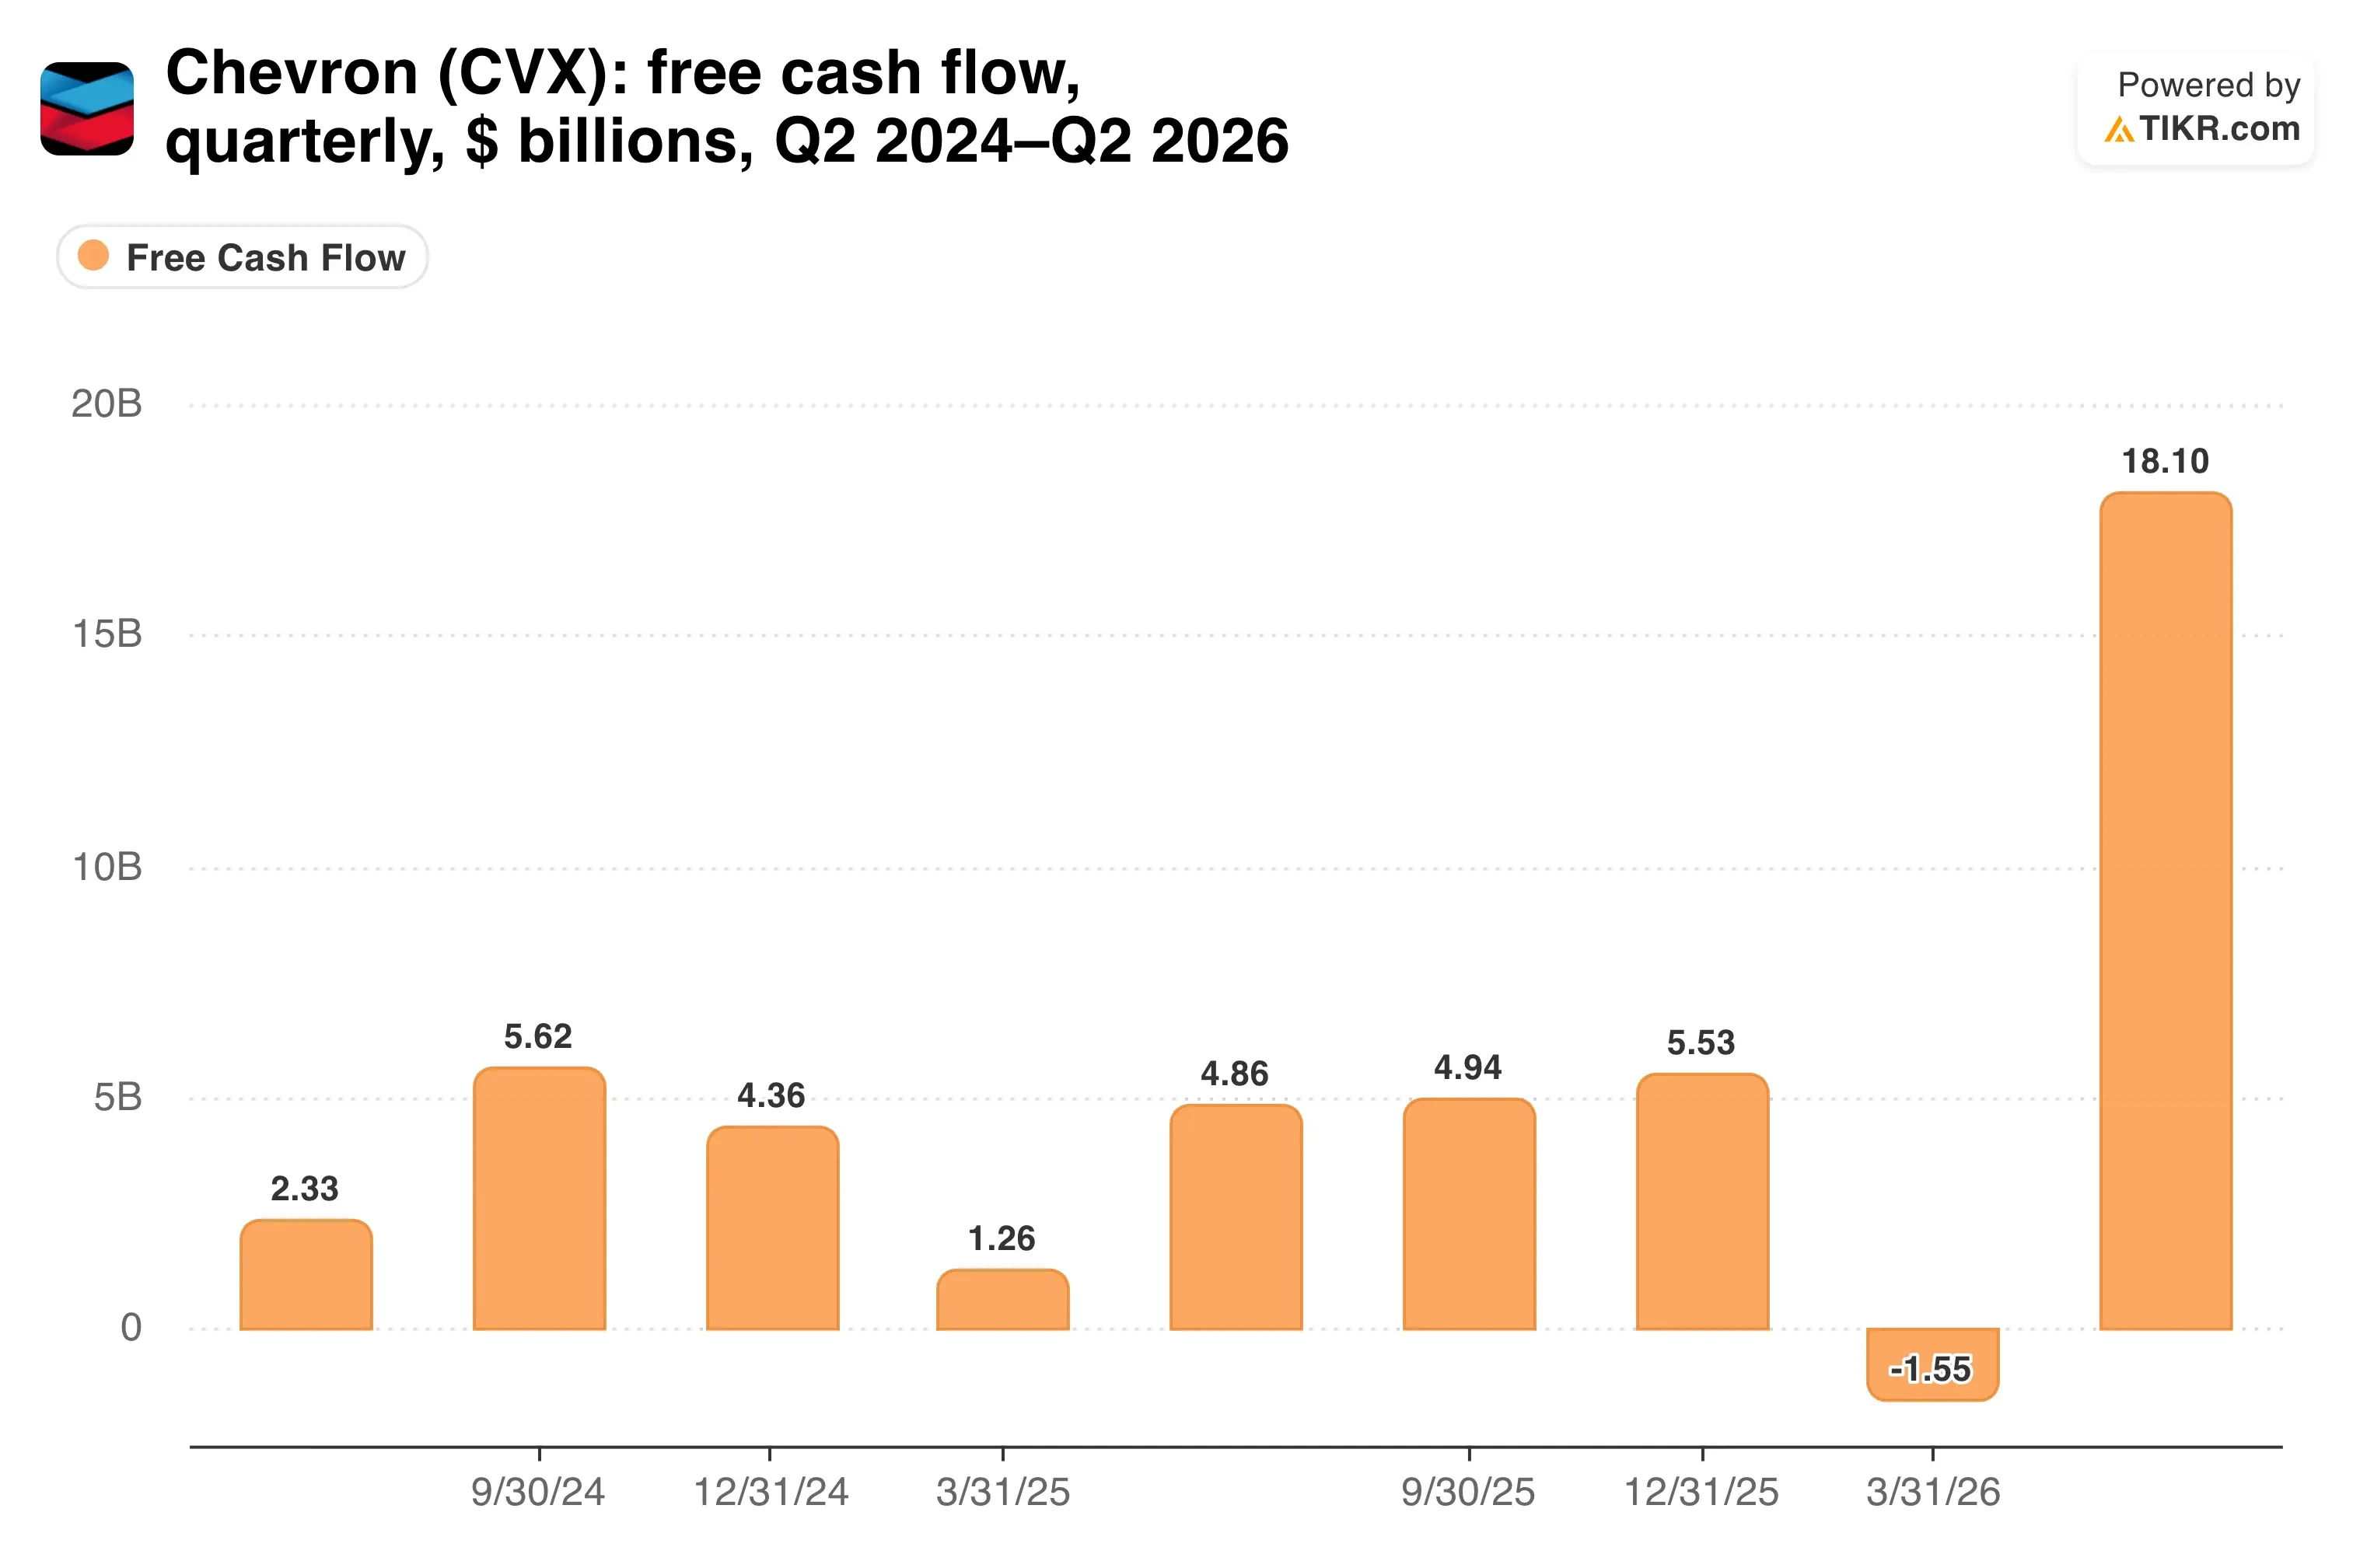
Q2’s $18.1 billion stands out because free cash flow briefly turned negative earlier in 2026.
TIKR tracks 25 analysts on Chevron. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Chevron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Chevron’s Analyst Ratings
Priced for $100 oil
The harder question is how much of 2026 lasts. Consensus expects EPS to grow 46.8% a year over the next two years, after a 27.1% annual decline over the past three. That swing is mostly the oil price, and the estimates assume it holds.
Q3 also carries real noise. Chevron guided to 150,000 to 200,000 boe per day of turnarounds and downtime for the quarter. Hurricane Isaias then shut in output at five Gulf facilities in early October, which will land in Q4.
The balance sheet gives Chevron room, with net debt at just 0.56x EBITDA and a 67.3% payout ratio. Still, Chief Legal Officer Hewitt Pate sold $9.77 million of stock this week.
How much of the earnings path is the cycle talking?

My take: The Hess Midstream reset is good business wearing an ugly accounting label, and Aphrodite adds a gas option for the next decade. At $227, though, investors are paying for oil staying near $100, so I want the buyback pace to back up that confidence.
Q3 results arrive on October 30. Watch the buyback guidance, the size of the turnaround hit and any early read on 2027 capex.
So what is Chevron stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Chevron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!