Key Takeaways
- Bill Ackman’s Pershing Square filed its 13F for the third quarter on Nov. 16, and analysts’ average targets put Uber, Netflix, Meta, Brookfield and Amazon 26% to 43% above their last close.
- Pershing added to Netflix in the quarter, held its Uber stake steady and trimmed Meta and Brookfield.
- Uber, Netflix and Meta trade below their usual forward earnings multiples, and each has a real risk behind the discount.
- Uber looks like the best buy of the group, with record free cash flow at about 17x forward earnings.
Bill Ackman doesn’t own many stocks, so the ones he keeps are worth a look. Pershing Square, which manages about $30.8 billion, held just 16 positions in its 13F for the quarter ended Sept. 30, filed Nov. 16.
Wall Street is also very bullish on several of them. Of the stocks that make up at least 2% of Pershing’s 13F, these are the five where analysts see the most upside, led by Uber (UBER) at 43%.
1. Uber: Ackman’s stake didn’t budge
Pershing owned 34.27 million Uber shares at Sept. 30, the same count as three months earlier. They were worth $2.35 billion, or 7.6% of its 13F stocks. The stock is up 0.4% since then, to $68.81. Meanwhile, the business is bringing in more cash than ever. Free cash flow hit a record $10.4 billion over the twelve months through September, and buybacks rose again to $750 million in the third quarter.
Analysts have still cut their consensus target over the past year, from about $111 to $98:
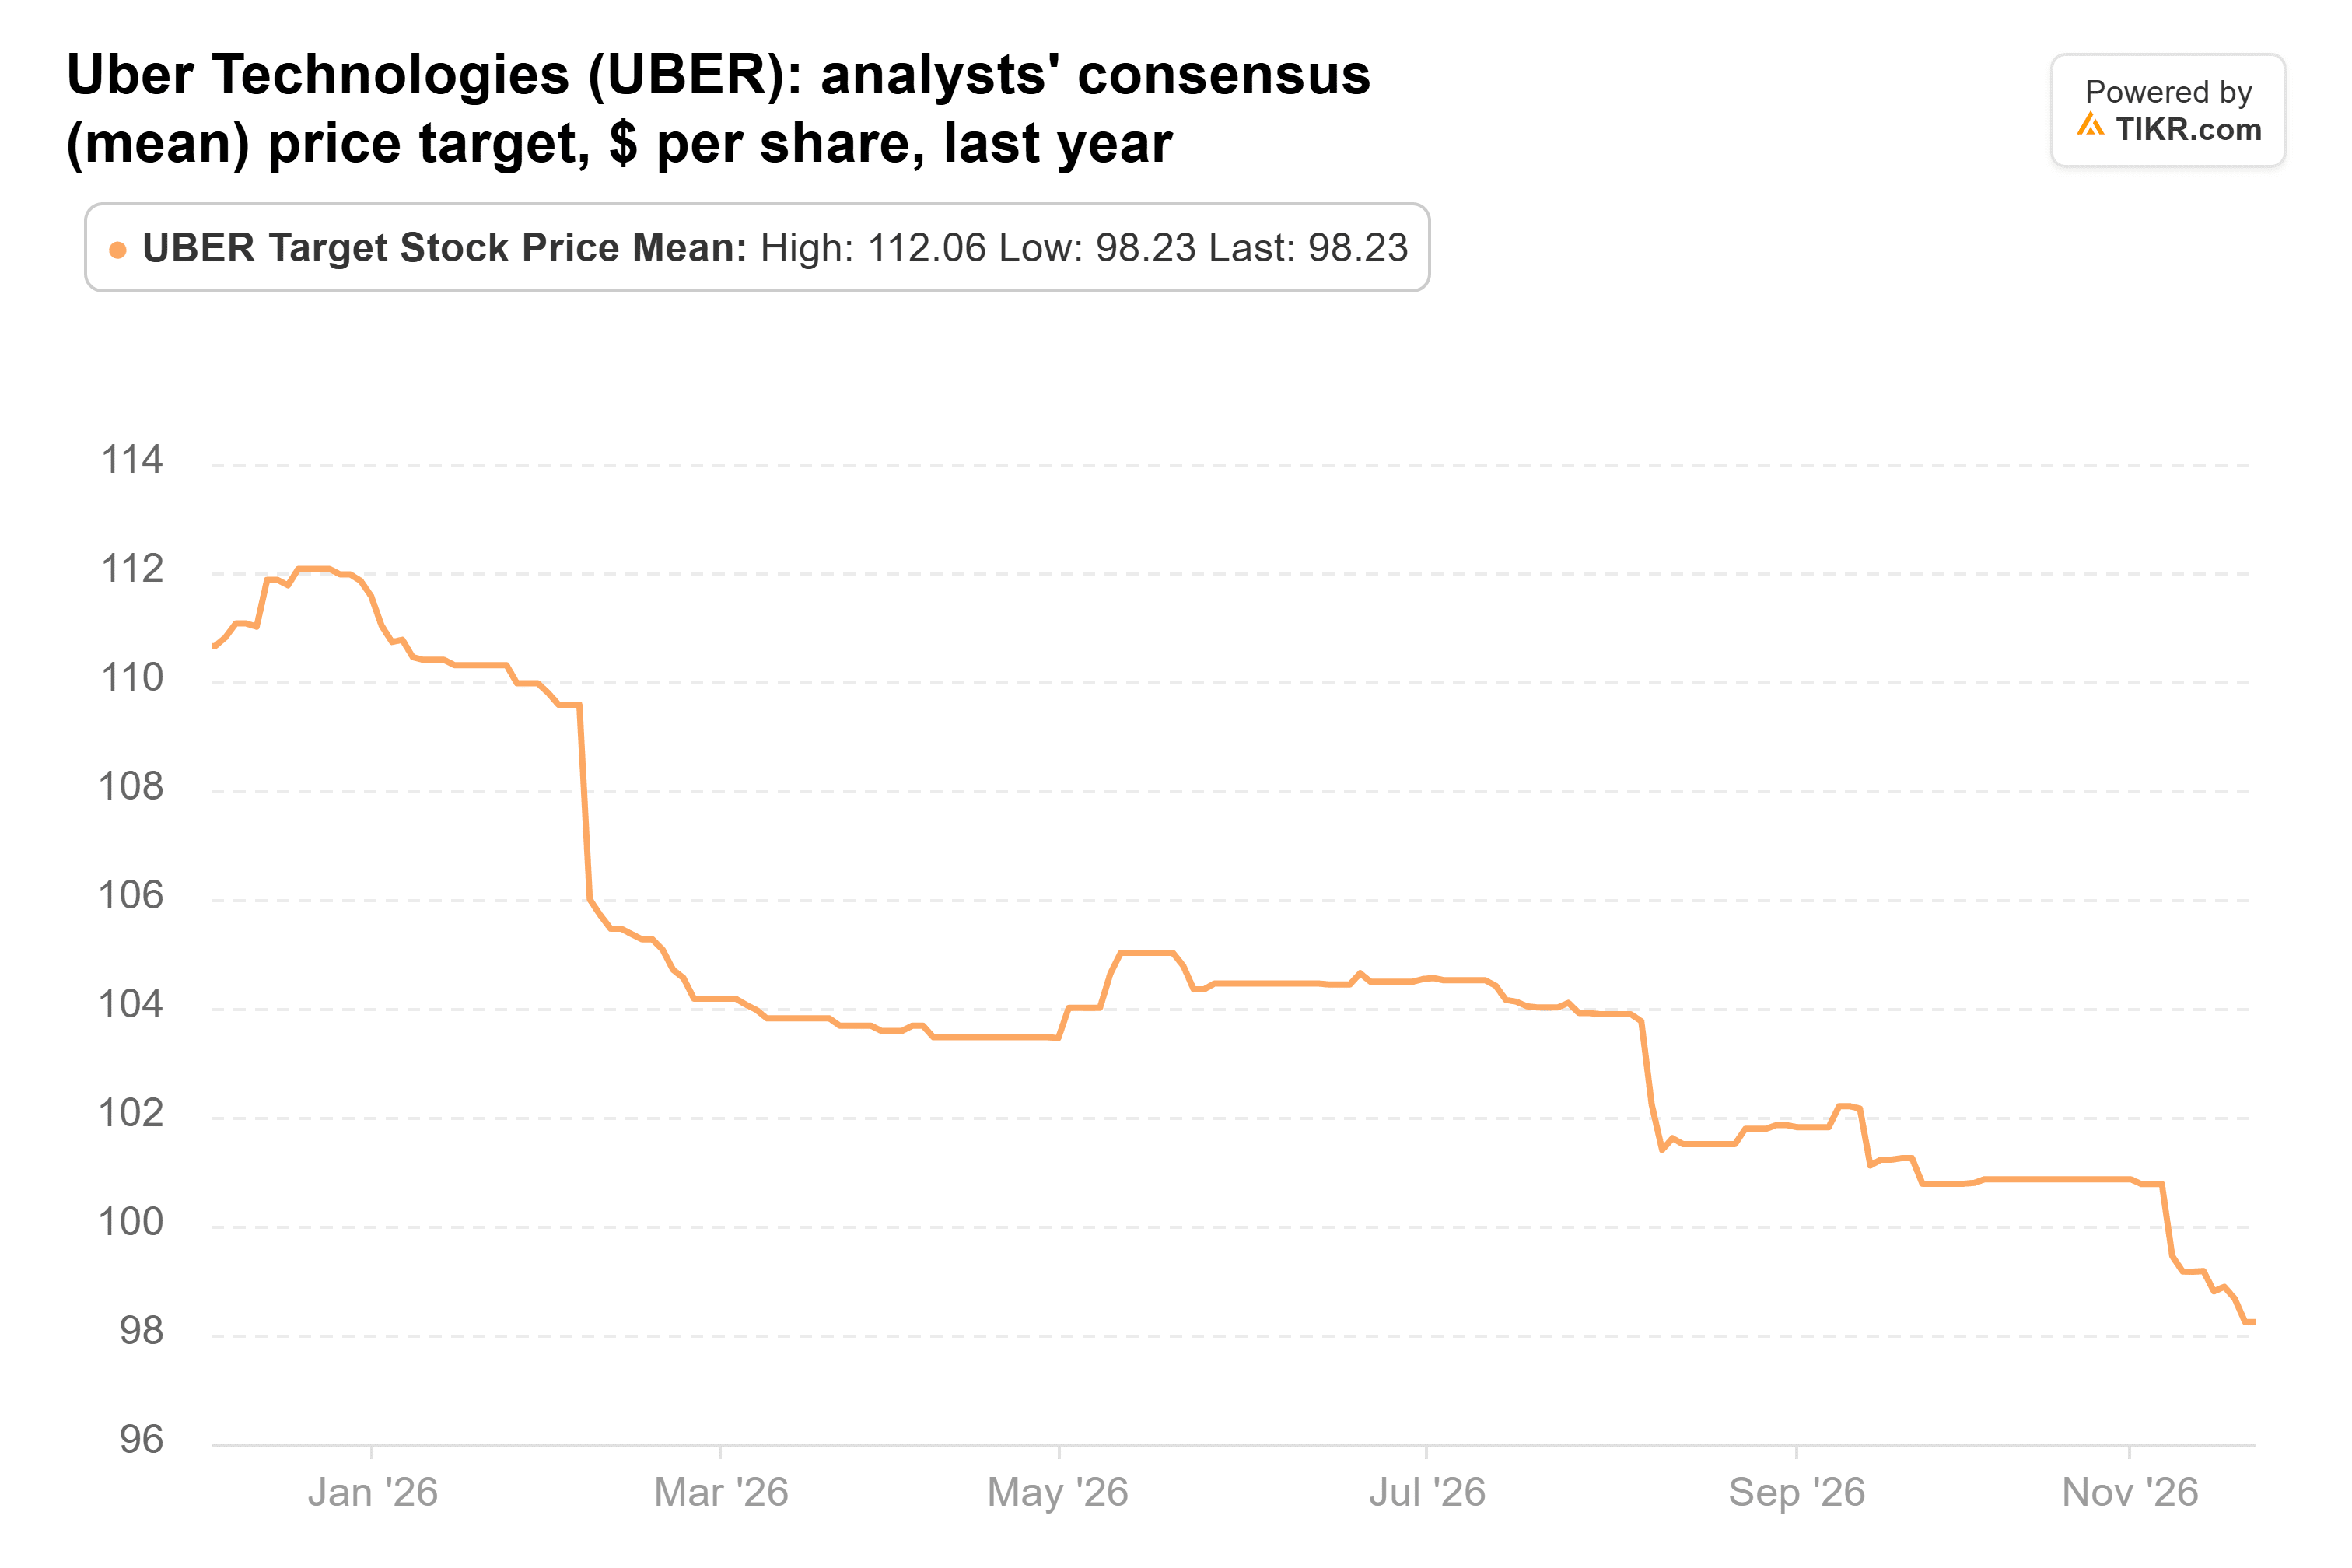
Even so, that $98 average from 49 analysts sits 43% above the last close.
TIKR tracks 49 analysts on Uber. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Uber, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Uber’s Analyst Ratings
2. Netflix: Ackman bought more
Pershing held its Uber stake flat but added to Netflix (NFLX). Its stake grew 18% in the third quarter to 15.41 million shares, worth $1.07 billion and 4% of its 13F stocks. The stock has fallen 14% since Sept. 30, to $59.68, and sits 48% below its 52-week high.
Ackman isn’t backing off. He called Netflix “an incredibly cheap stock” on CNBC’s Squawk Pod this month, arguing that viewing hours have fallen because “the mix of content is changing.” At about 17x forward earnings, against a five-year average near 33x on TIKR, he has a point.
The catch is engagement. Bloomberg reported in October that members are watching less per person. Netflix also guided to a 26.0% operating margin for the fourth quarter, below what analysts expected. Over the past year, analysts have cut their consensus target hard, from about $135 to $85:
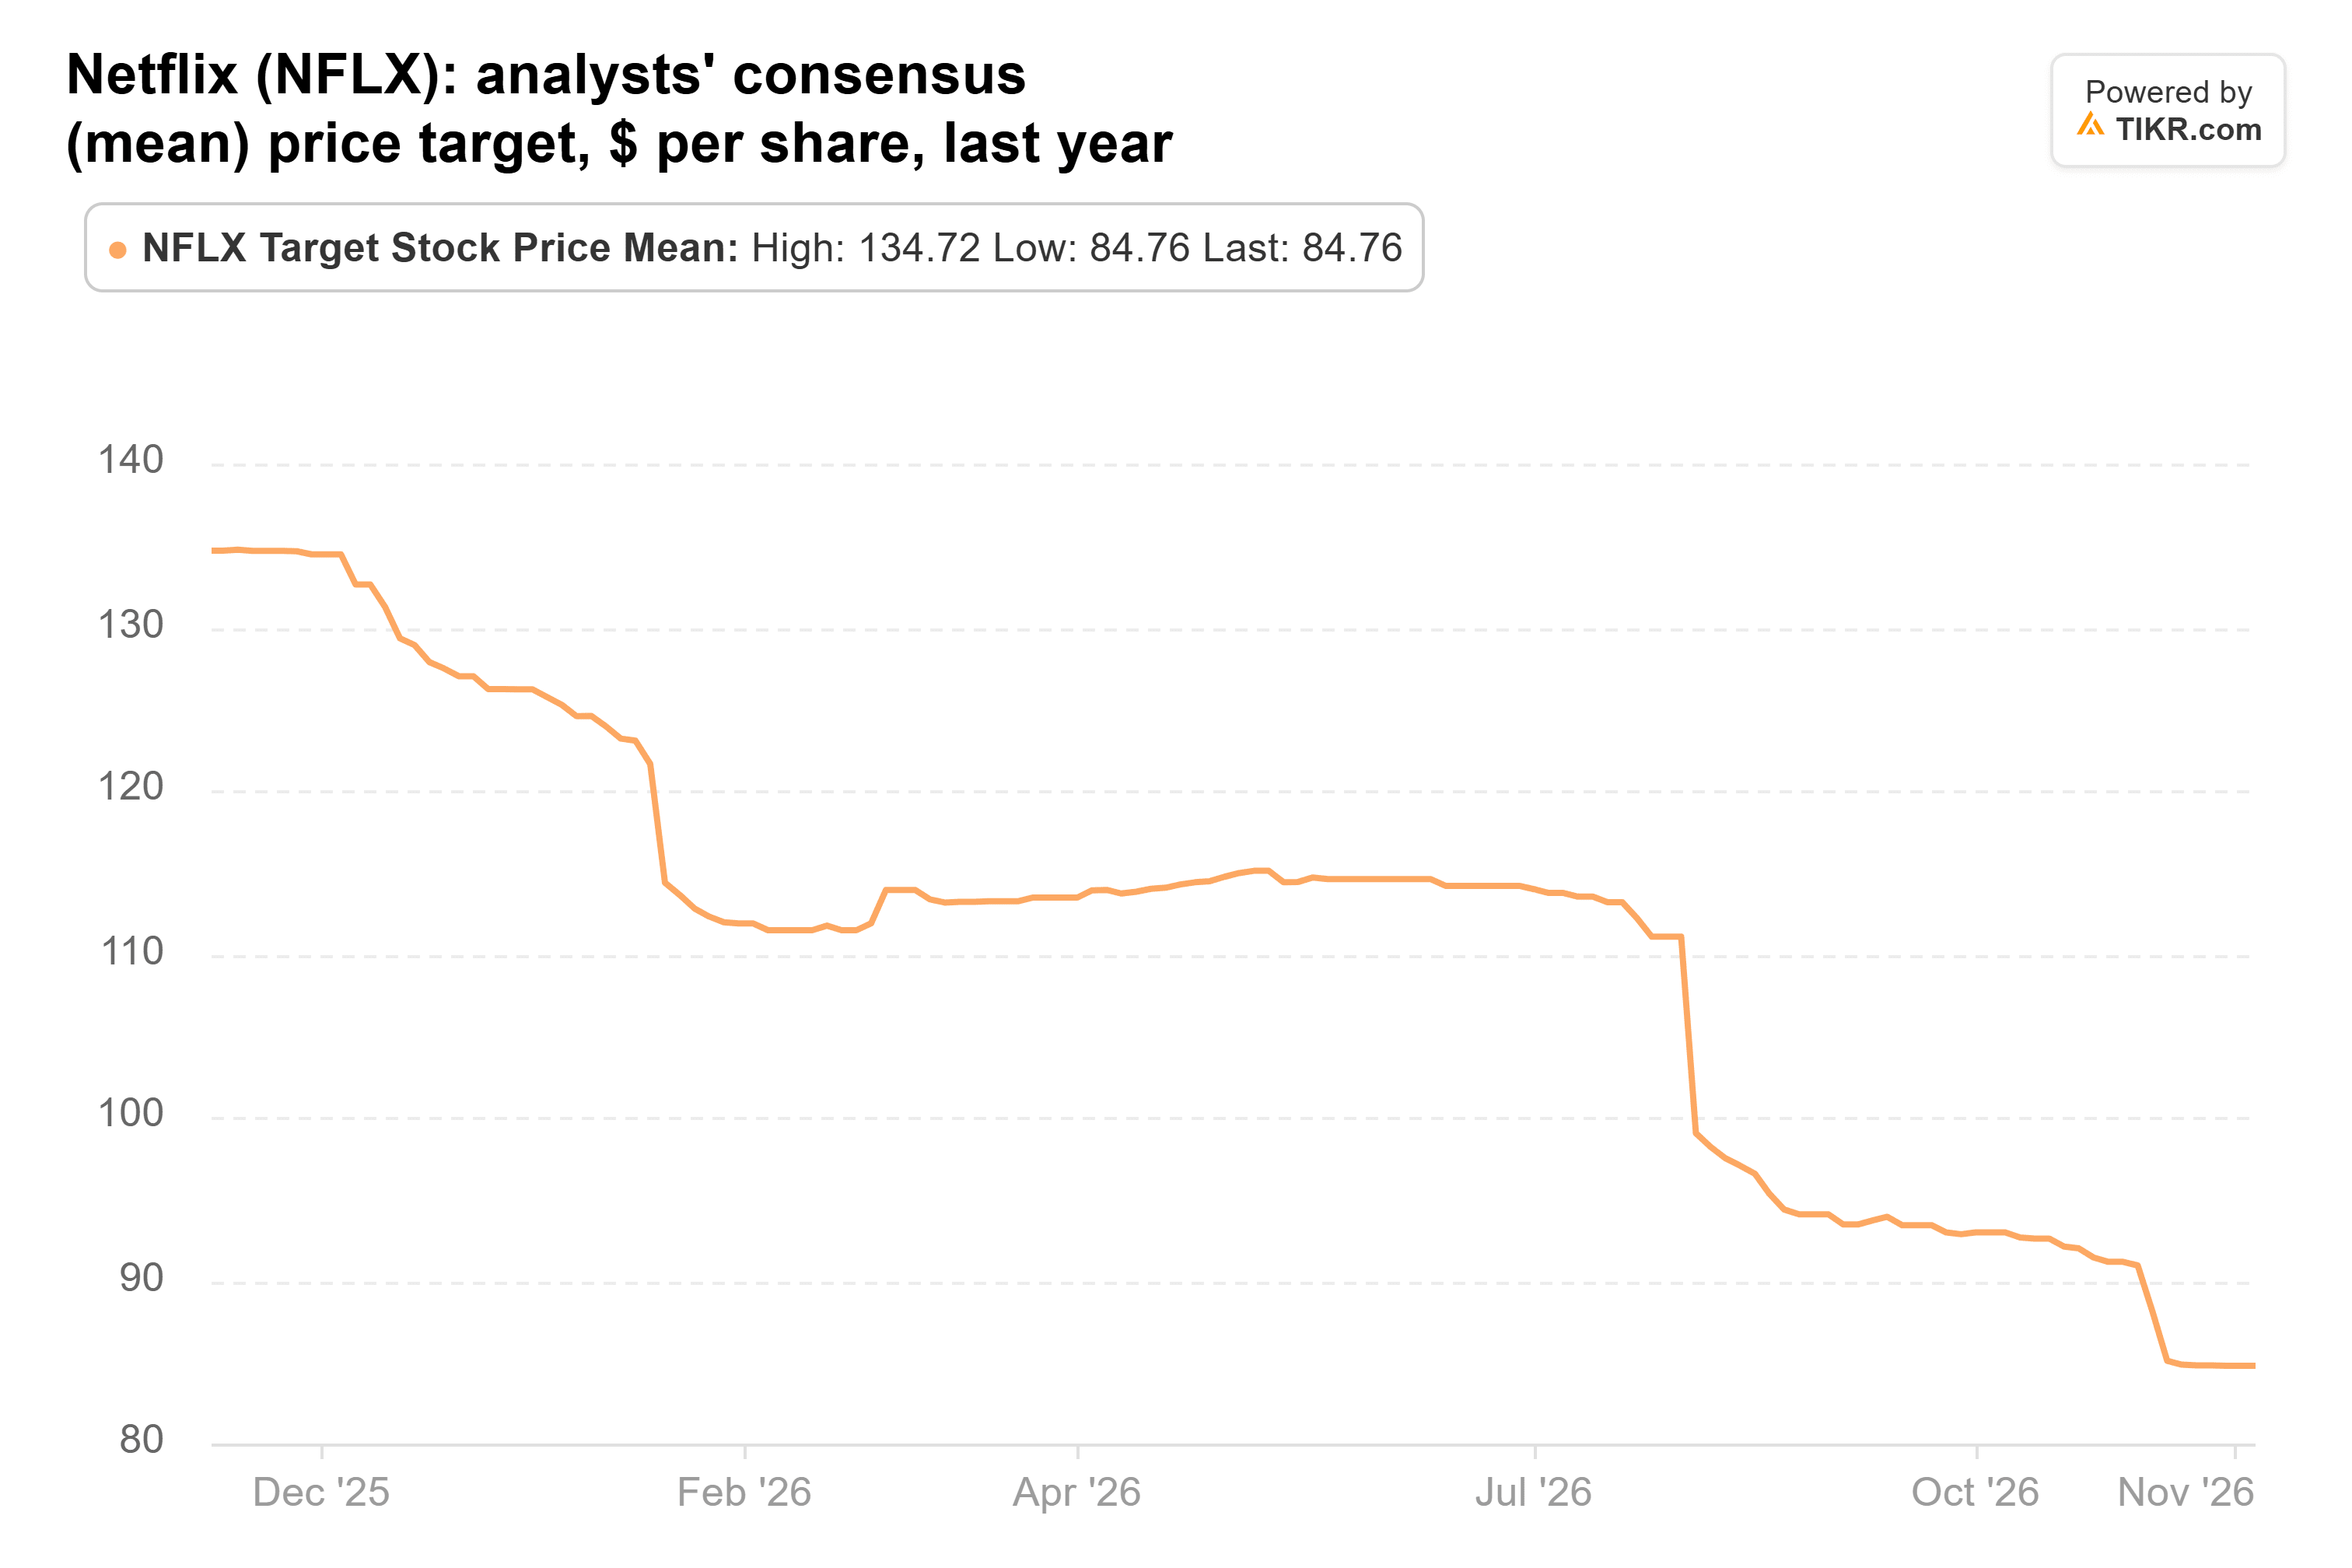
That $85 average from 51 analysts is still 42% above the last close.
3. Meta: a great ad business with a giant bill
Pershing cut its Meta Platforms (META) stake by 11% in the third quarter, to 2.83 million shares worth $2.05 billion, or 6.7% of its 13F stocks. The stock has dropped 15% since Sept. 30, to $618.87.
The ad business is still growing fast. Third-quarter revenue rose 26% to $64.6 billion as the price per ad climbed 14%. But Meta expects $135 billion to $145 billion of capex in 2026, and its third-quarter free cash flow was negative $2.1 billion. Consensus now has free cash flow bottoming at negative $48.0 billion in 2027. There’s also a $25 billion penalty that a New Mexico court ordered in October, which Meta plans to appeal.
At about 19x forward earnings, Meta trades a bit below its five-year average of 21x on TIKR. Analysts’ consensus target ended the past year about where it started, near $840, even as the stock swung:
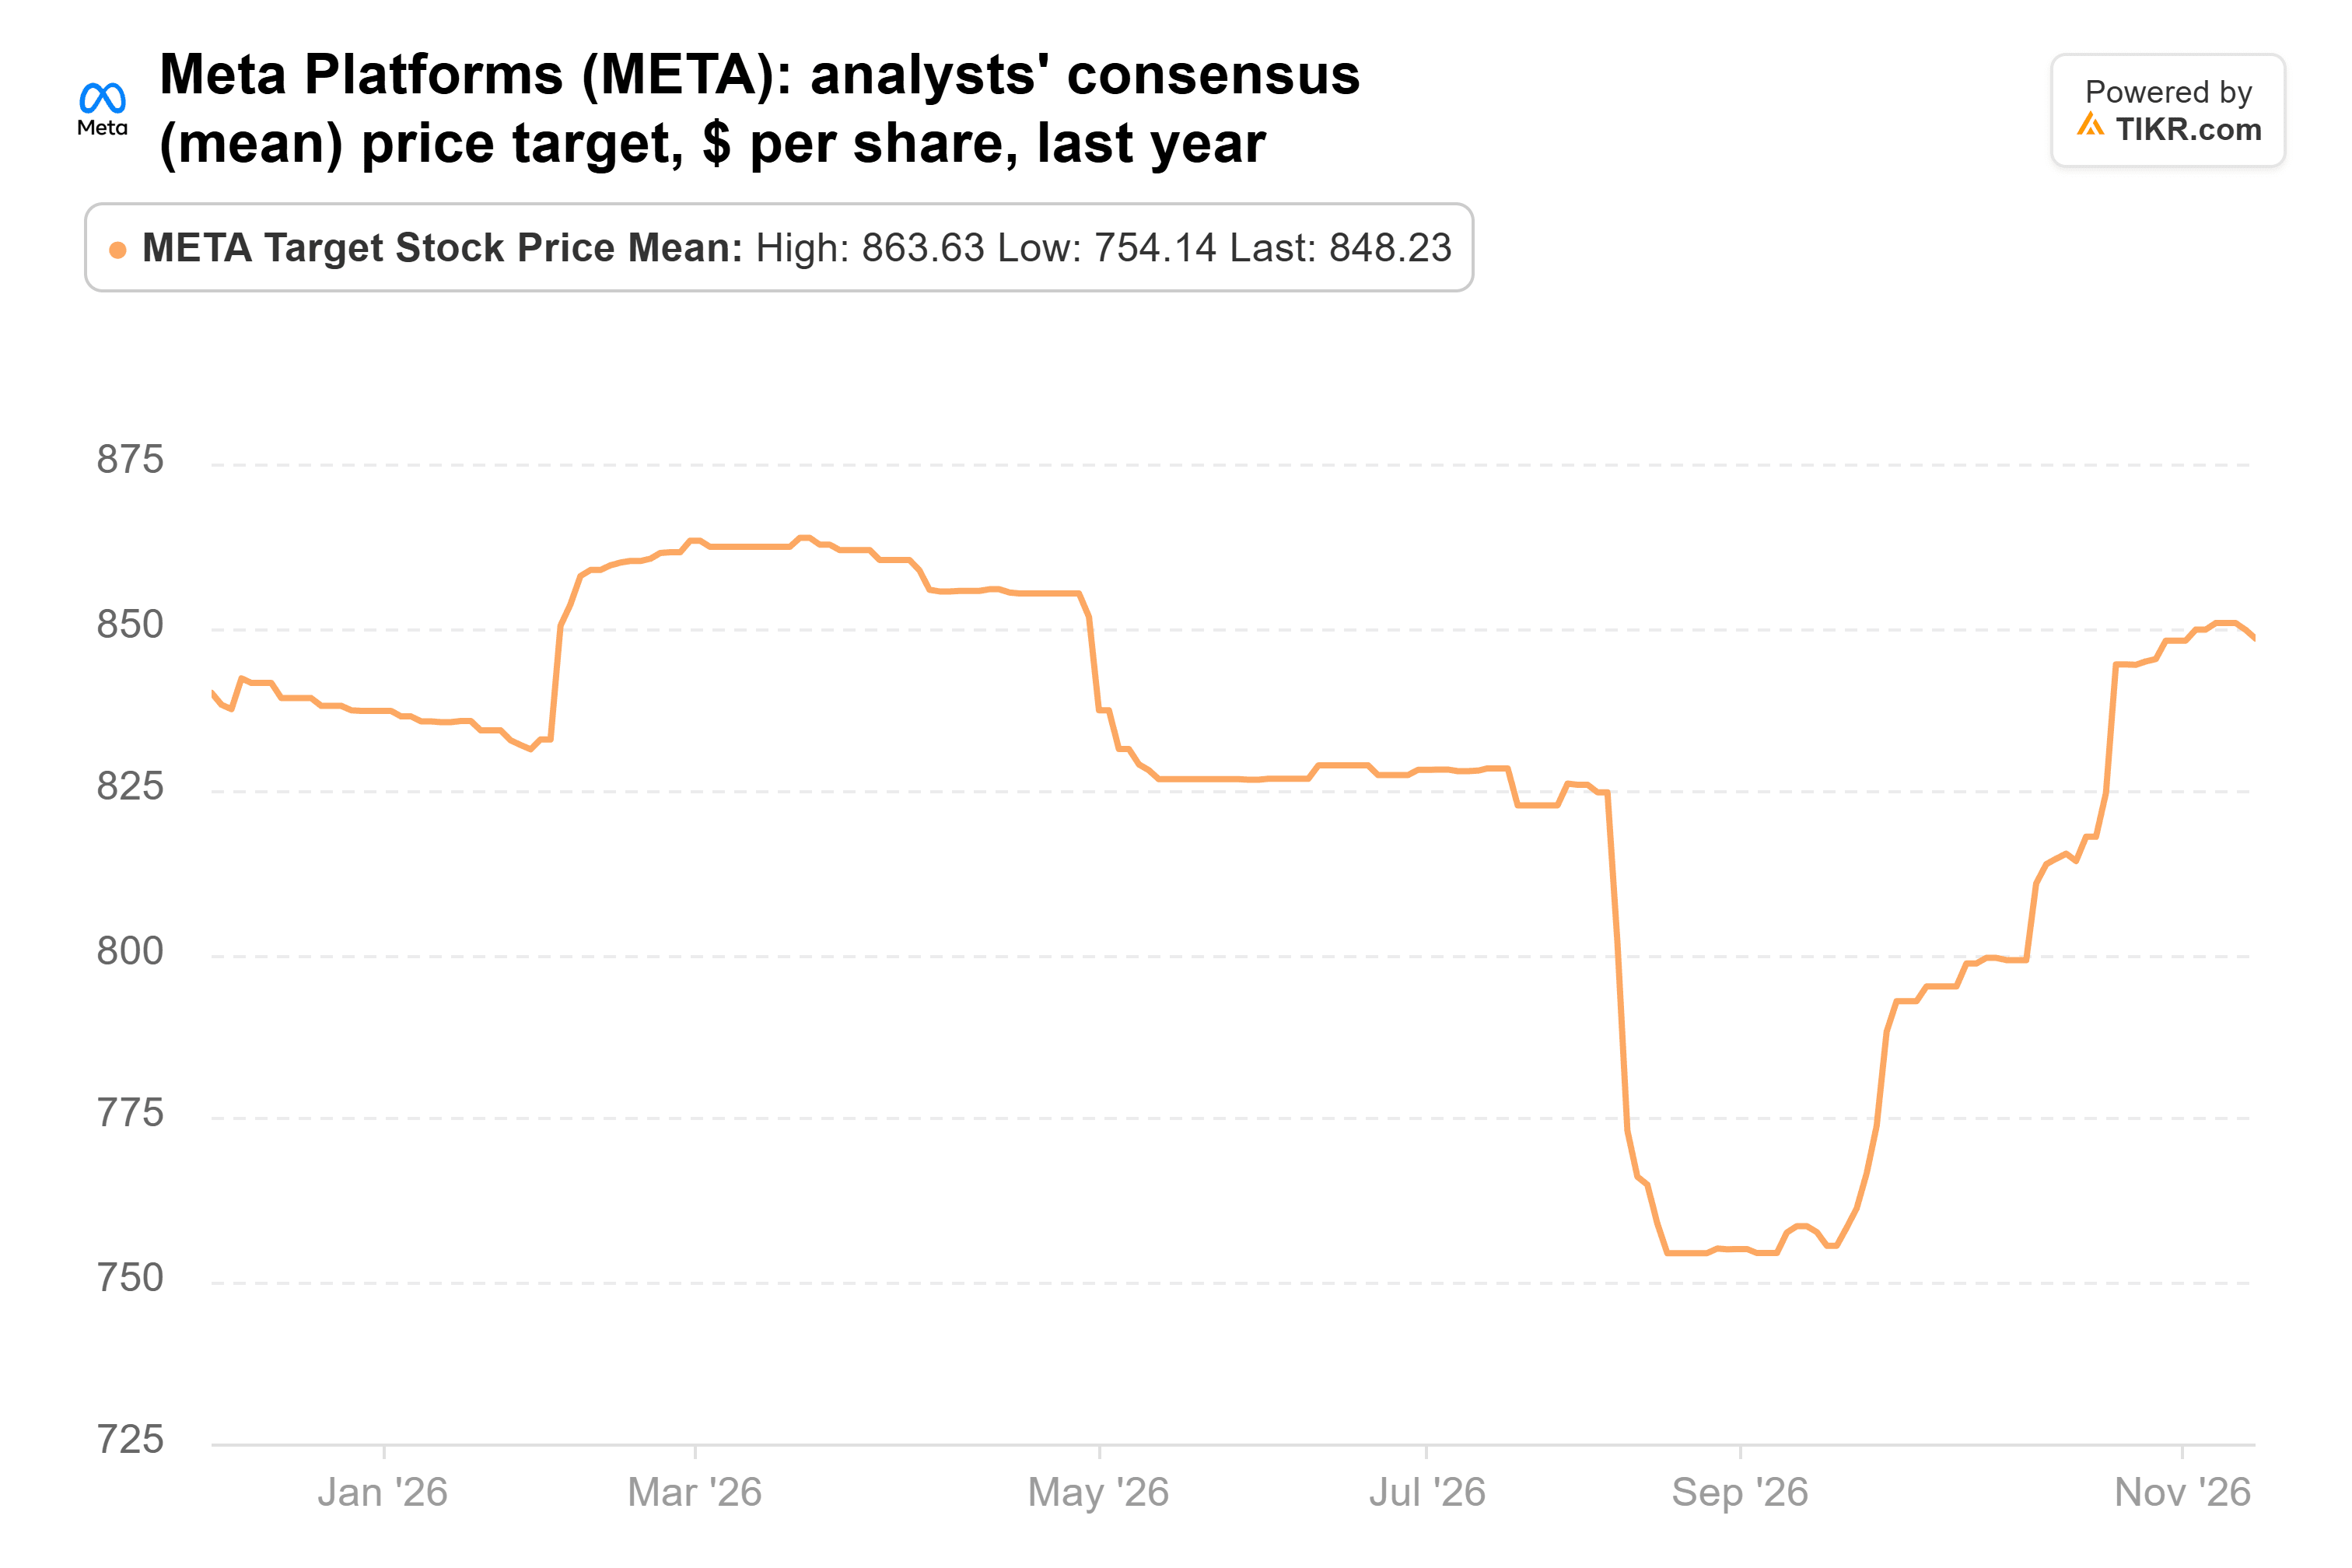
The $848 average from 62 analysts is 37% above the last close.
4. Brookfield: up since September, with room to run
Pershing also cut its Brookfield (BN) stake by 11%, to 51.33 million shares worth $1.87 billion, or 6.1% of its 13F stocks. Unlike the three above, it has gained since Sept. 30. It’s up 9% to $39.59, but still 20% below its 52-week high.
Analysts have plenty to like in the business. Brookfield’s distributable earnings rose 16% in the third quarter, to $1.72 billion from $1.49 billion. Its asset management arm raised $25 billion in the quarter and $123 billion so far this year. Brookfield also struck a $25 billion pact with Bloom Energy.
Over the past year, analysts have nudged their consensus target up from about $51, even as the stock slipped from $43:
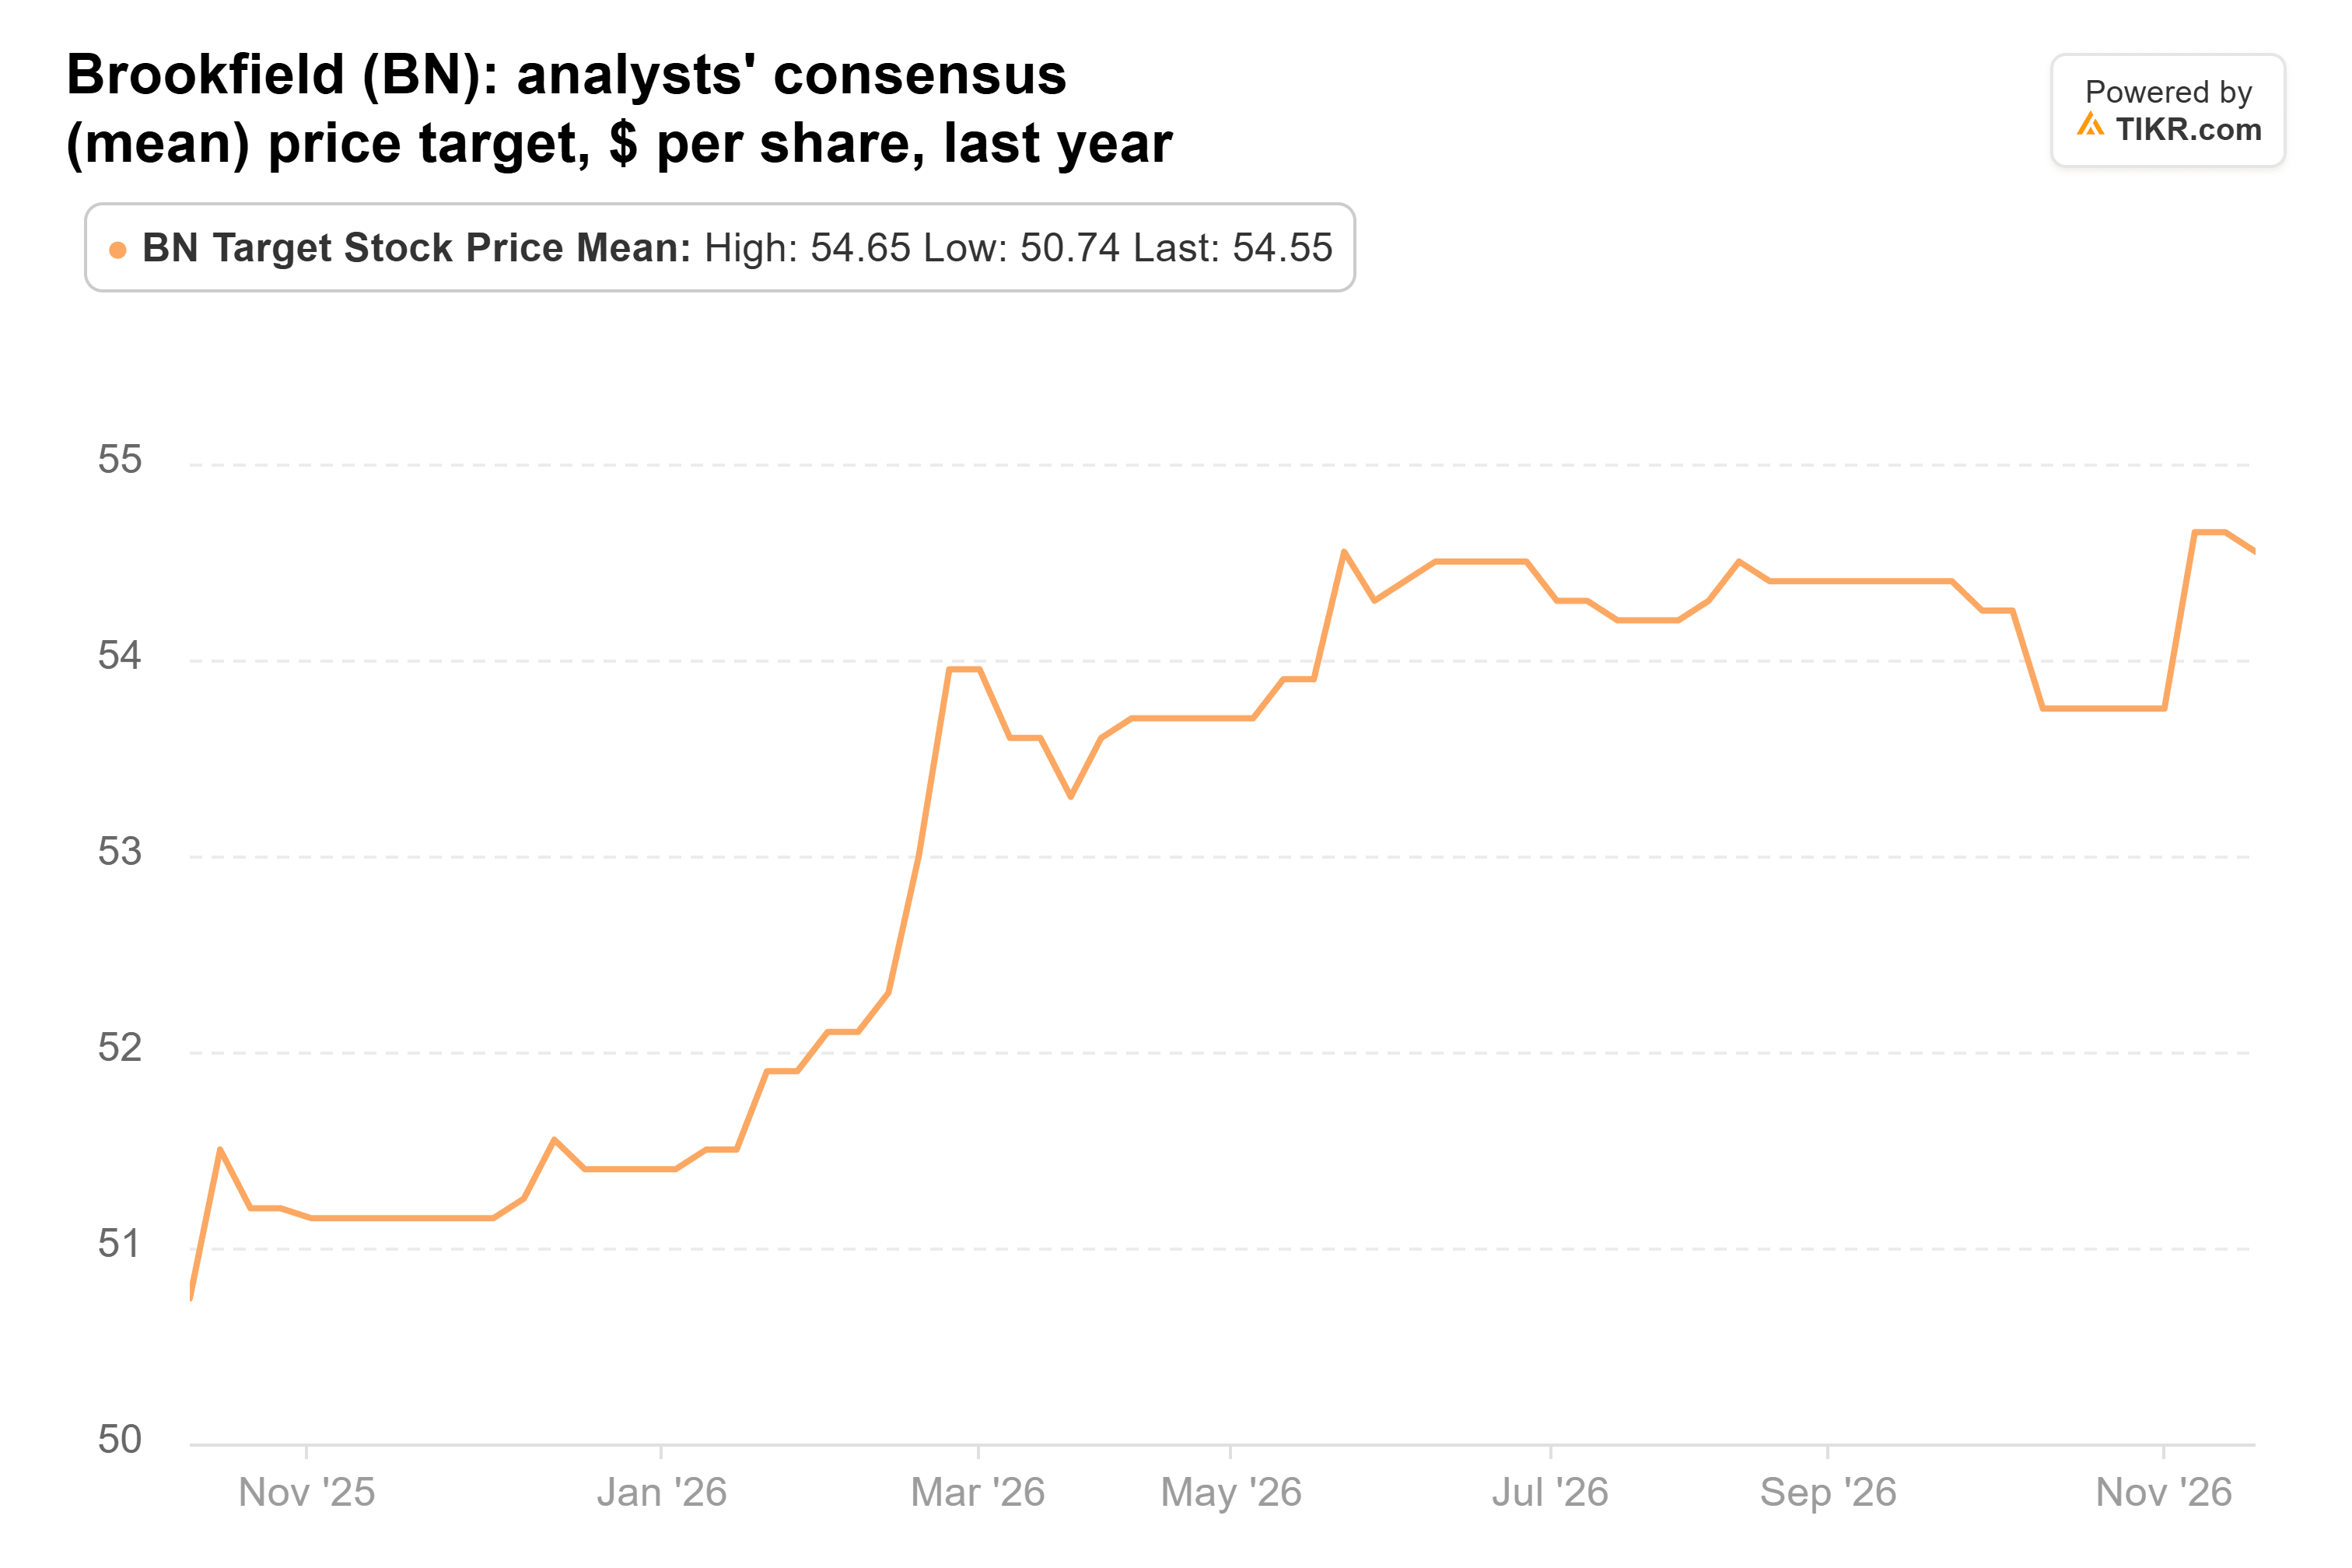
The $54 average sits 36% above the last close. But only 11 analysts cover the stock, and their targets run from $31 to $64, so they agree less on that number than on the others.
5. Amazon: the AI build has a price
Ackman’s Amazon and Uber stakes now overlap a little: Amazon gives Prime members free Uber Eats delivery. Pershing barely changed its Amazon (AMZN) position in the third quarter. It trimmed the stake 1%, to 8.51 million shares worth $2.12 billion, or 6.9% of its 13F stocks. The stock is up 4% since Sept. 30, to $257.89.
AWS grew 39% in the third quarter, its fastest in five years. AWS CEO Matt Garman said on Sources with Alex Heath that he expects AWS to be short of capacity for the next couple of years. Paying for all that capacity is the hard part. Amazon expects about $220 billion of capex this year, and consensus has free cash flow negative in 2026 and 2027 before it recovers to $37.8 billion in 2028.
The stock trades at about 26x forward earnings, well below its five-year average of about 48x on TIKR. Analysts have raised their consensus target over the past year from about $293:
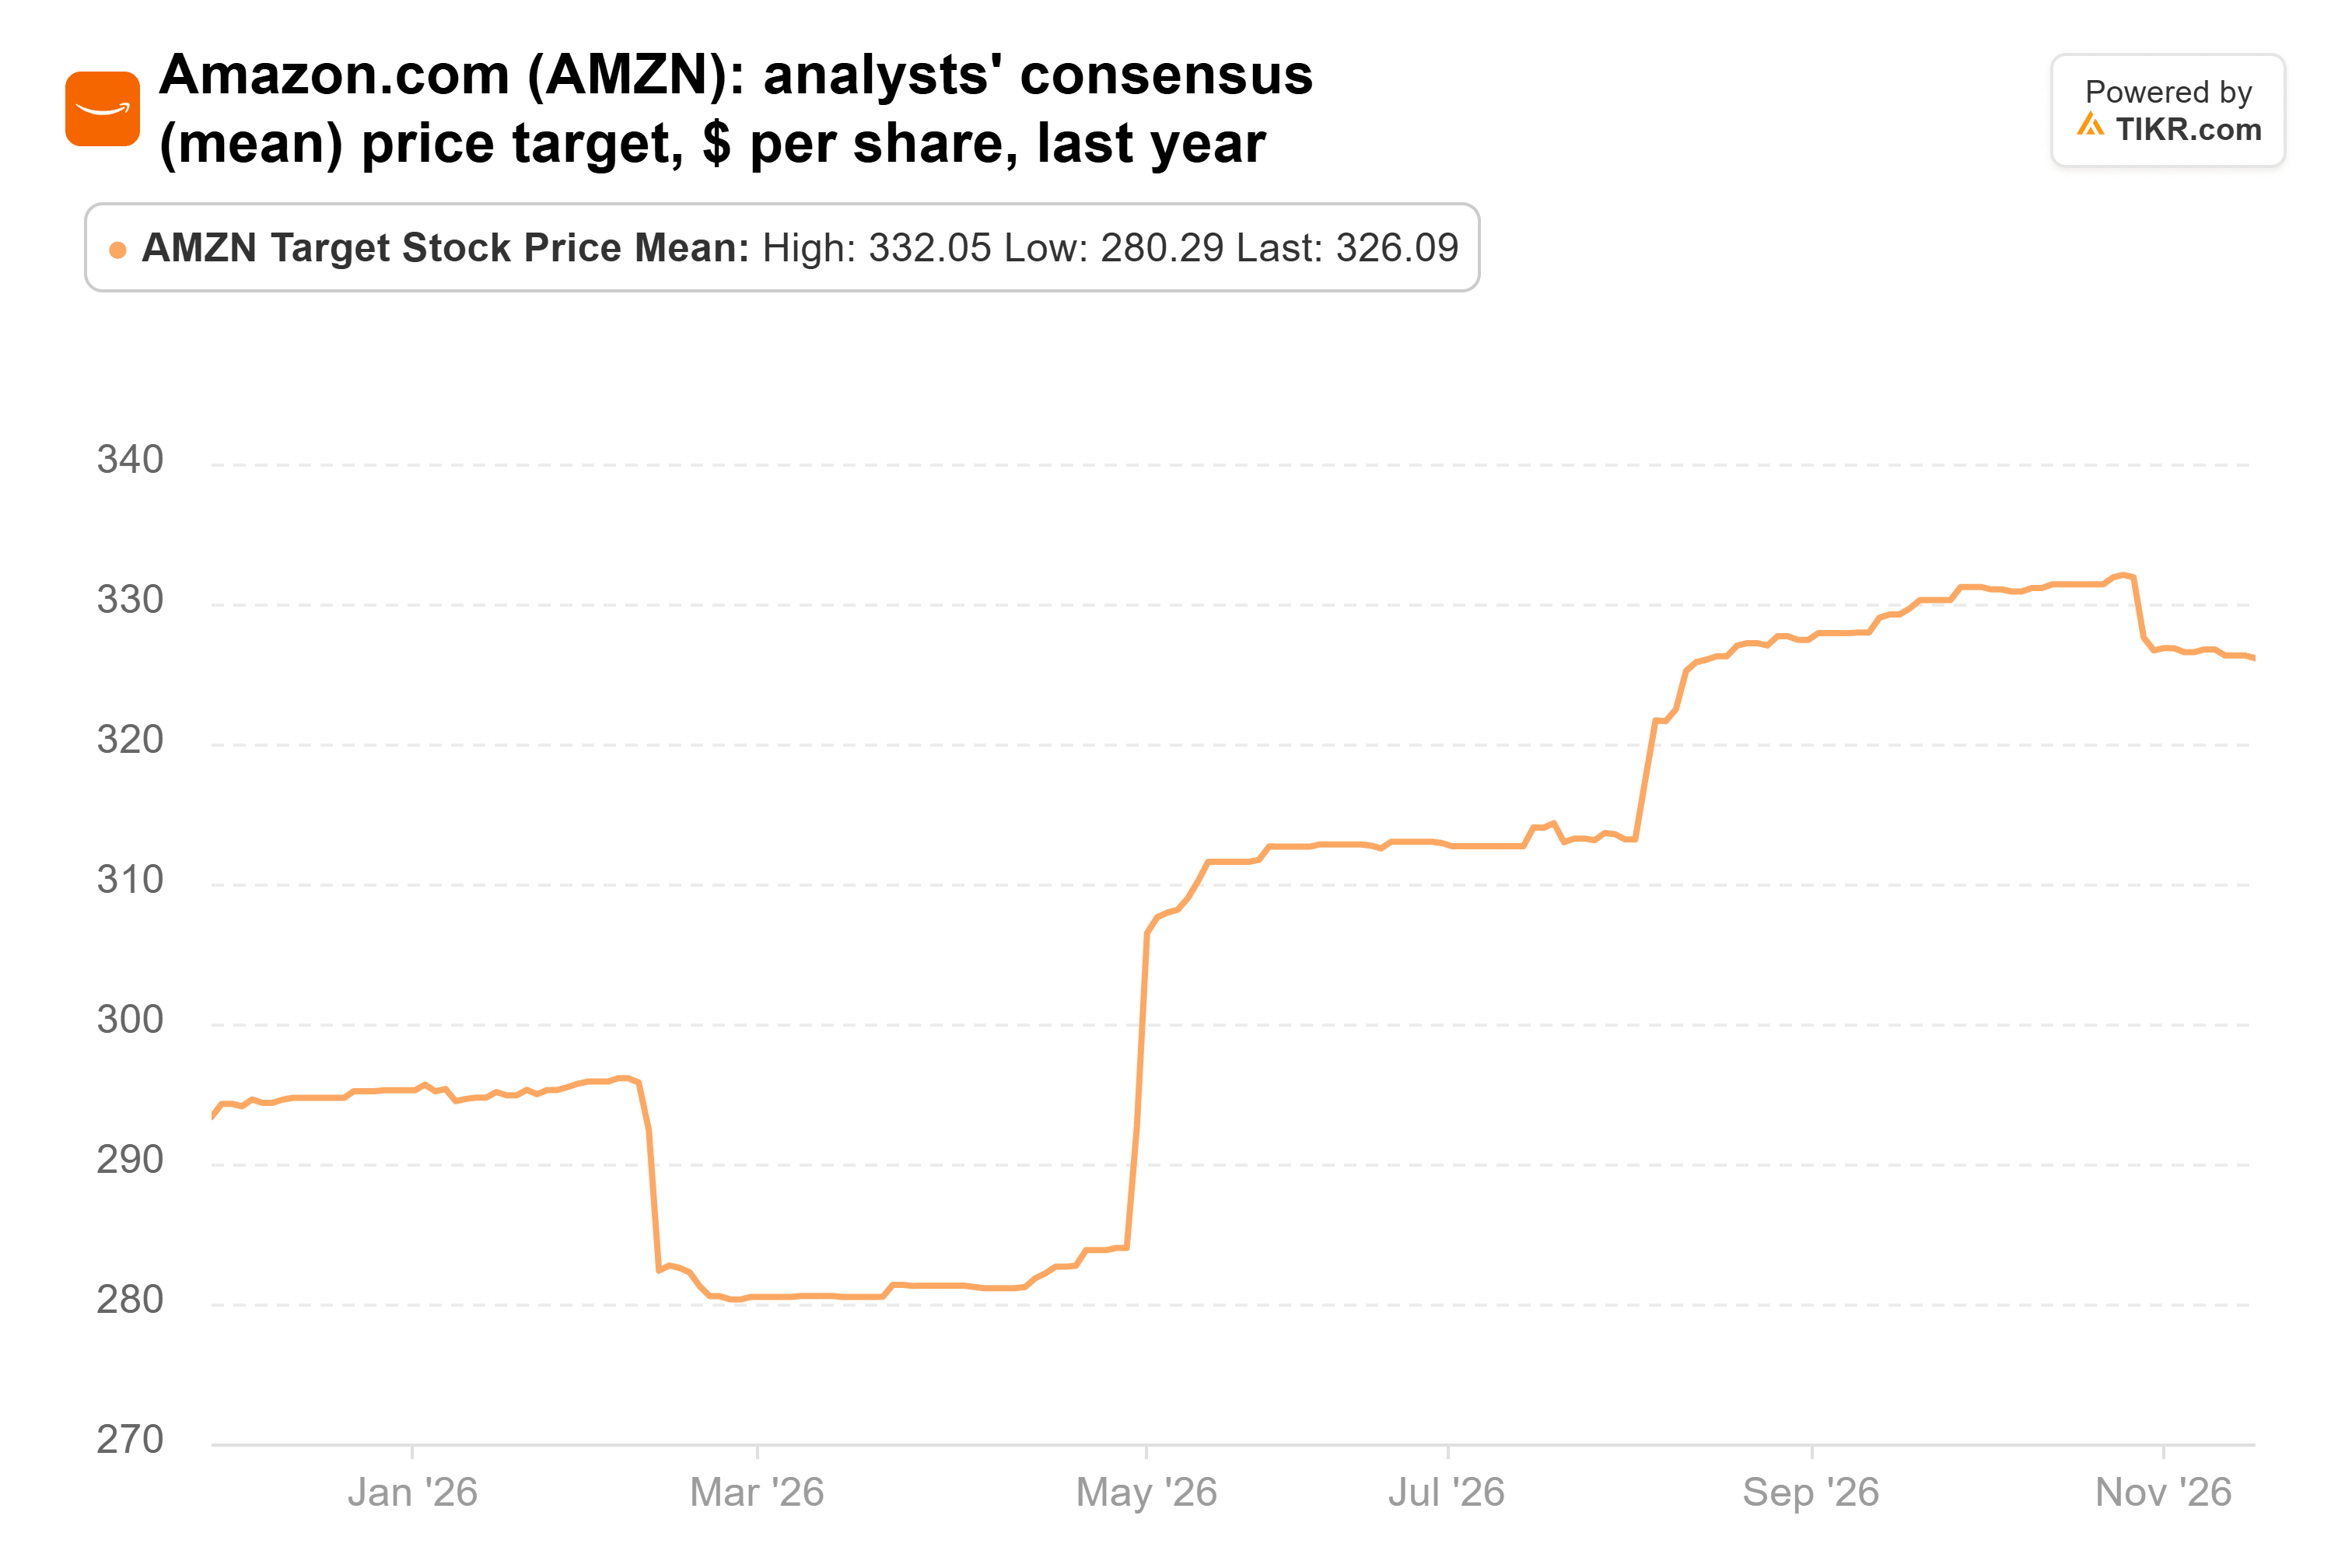
The $326 average from 62 analysts is 26% above the last close.
If I could only buy one, it’d be Uber
Wall Street sees real upside in all five of these stocks. But if I could only buy one right now, it’d be Uber. It trades at about 17x forward earnings, against a three-year average near 25x on TIKR. That price assumes its record cash flow won’t last, and I think it will.
The risk is robotaxis. If the strongest fleets sell rides through their own apps, Uber faces far more competition in its most profitable cities. Two of the executives behind its autonomous-vehicle partnerships also left on Nov. 16, Bloomberg reported. Uber aims to be live in 15 autonomous-vehicle cities by Dec. 31, and its fourth-quarter report early next year should show whether it got there. Pershing’s next 13F, due in mid-February, will show whether the fund still holds its stake.
So what is Uber stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Uber could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!