Key Takeaways
- The Gates Foundation Trust’s latest 13F shows it held Caterpillar, FedEx, Ecolab, Deere and Canadian National Railway without change last quarter, and together they make up more than half of its US stocks.
- They’re its five positions of 2% or more where analysts’ average price targets sit furthest above today’s prices, from 41% for Caterpillar to 6% for Canadian National.
- Caterpillar has the most upside after a steep fall, and its orders kept growing through it.
- If I could only buy one of the five, it’d be Caterpillar; the main risk is a slowdown in data-center spending.
Bill Gates’s foundation runs a concentrated book. The Gates Foundation Trust, which holds the Gates Foundation’s endowment, filed its 13F for the quarter ended Sept. 30 on Nov. 16. It shows $29.89 billion of US stocks in just 25 positions.
Five of them make up more than half of that: Caterpillar (CAT), FedEx (FDX), Ecolab (ECL), Deere (DE) and Canadian National Railway (CNI). The trust didn’t change a share of any of them in the quarter. They’re also the five of its positions of 2% or more where Wall Street sees the most upside.
1. Caterpillar’s selloff looks overdone
Caterpillar is the trust’s No. 3 holding: 6.35 million shares worth $5.15 billion at Sept. 30, or 17.2% of its US stocks. The stock is down 30% since then and sits 47% below its 52-week high, as investors have soured on stocks tied to AI power demand.
Yet Caterpillar’s orders keep growing. Its backlog hit a record $78 billion in the third quarter, up from $72 billion at June 30. And the Financial Times reported that Anthropic agreed to pay $3.4 billion to take over Caterpillar gas generator orders, including their engineering and installation. Another developer had placed those orders but needed financing to finish them.
Analysts have cut their targets along with the stock, but not nearly as far:
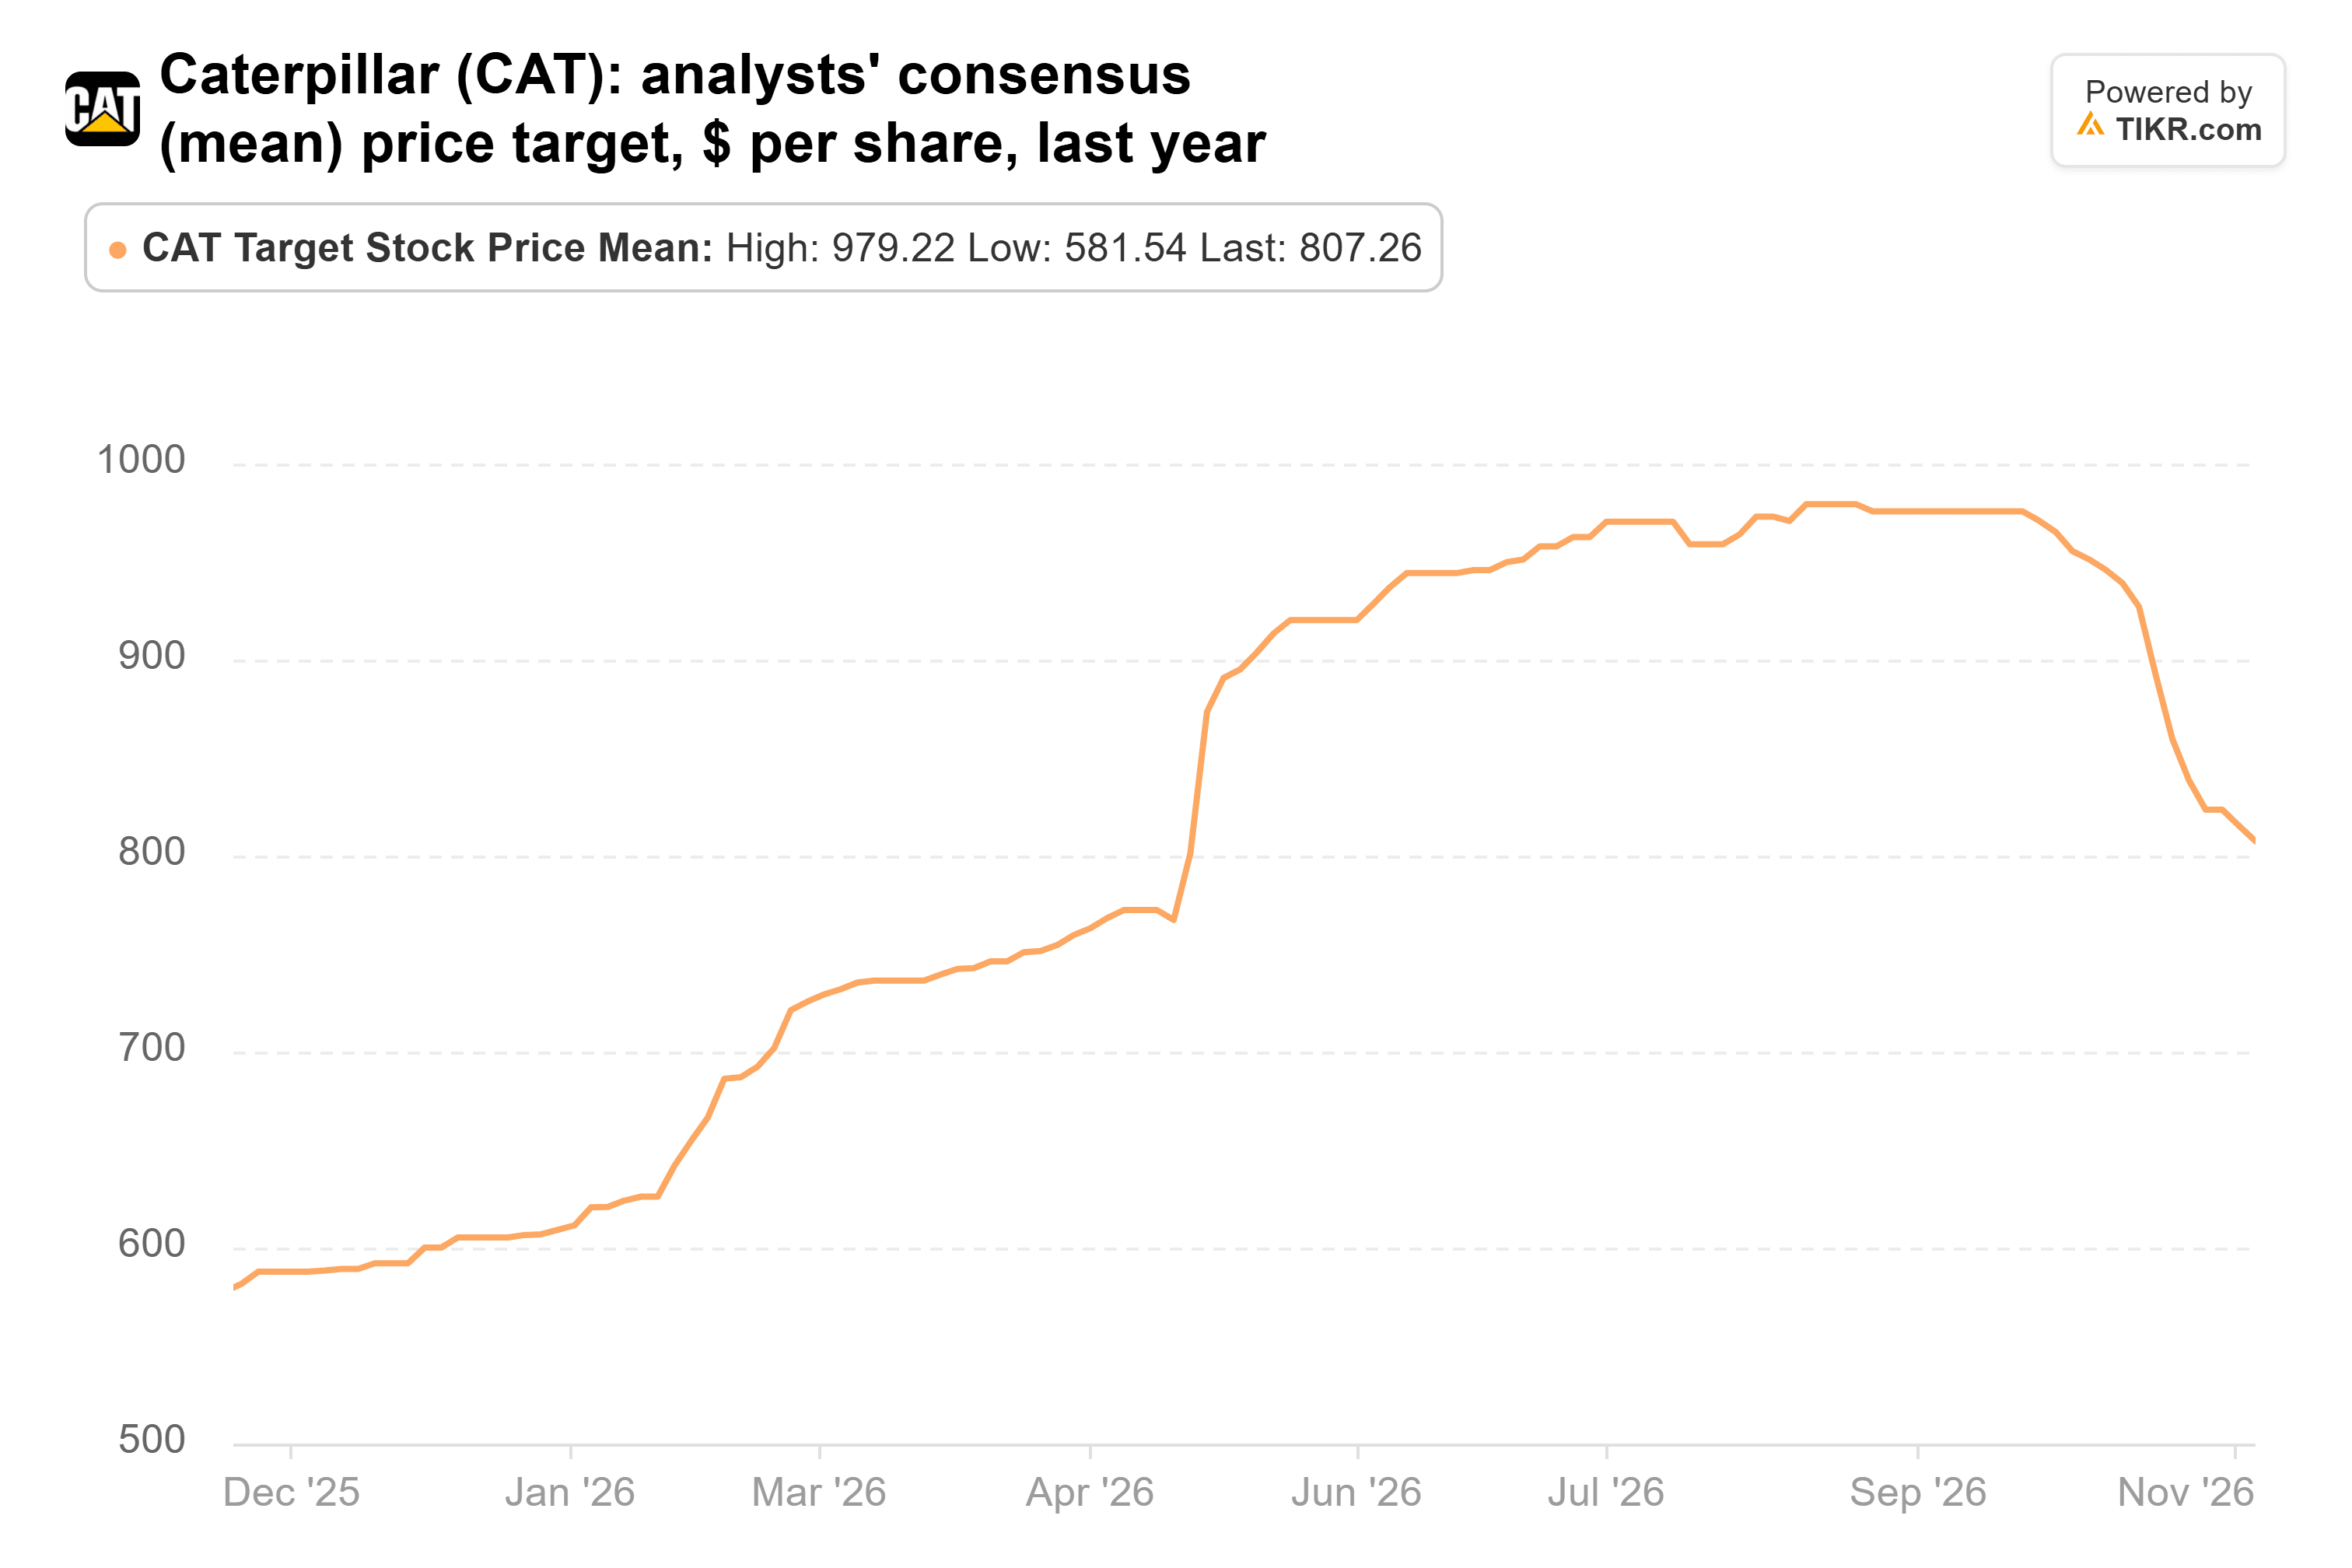
The average target of $807, from 29 analysts, is down from $979 in August. Even the lowest target, $575, is above today’s price.
TIKR tracks 30 analysts on Caterpillar. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Caterpillar, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Caterpillar’s Analyst Ratings
2. FedEx is charging more and shipping more
FedEx is a much smaller bet for the trust: 2.38 million shares worth $680 million at Sept. 30, or 2.3% of its US stocks. Unlike Caterpillar, it’s up since then, by 12%.
On Oct. 28, FedEx reported higher package yields, more package volume and lower costs for the quarter ended Sept. 30. It also raised its earnings outlook for calendar 2026. It’s a leaner company this year: it spun off FedEx Freight, moved to a calendar year, and bought back $2 billion of stock from June through September.
Analysts’ targets climbed with the stock into late May and have come down since:
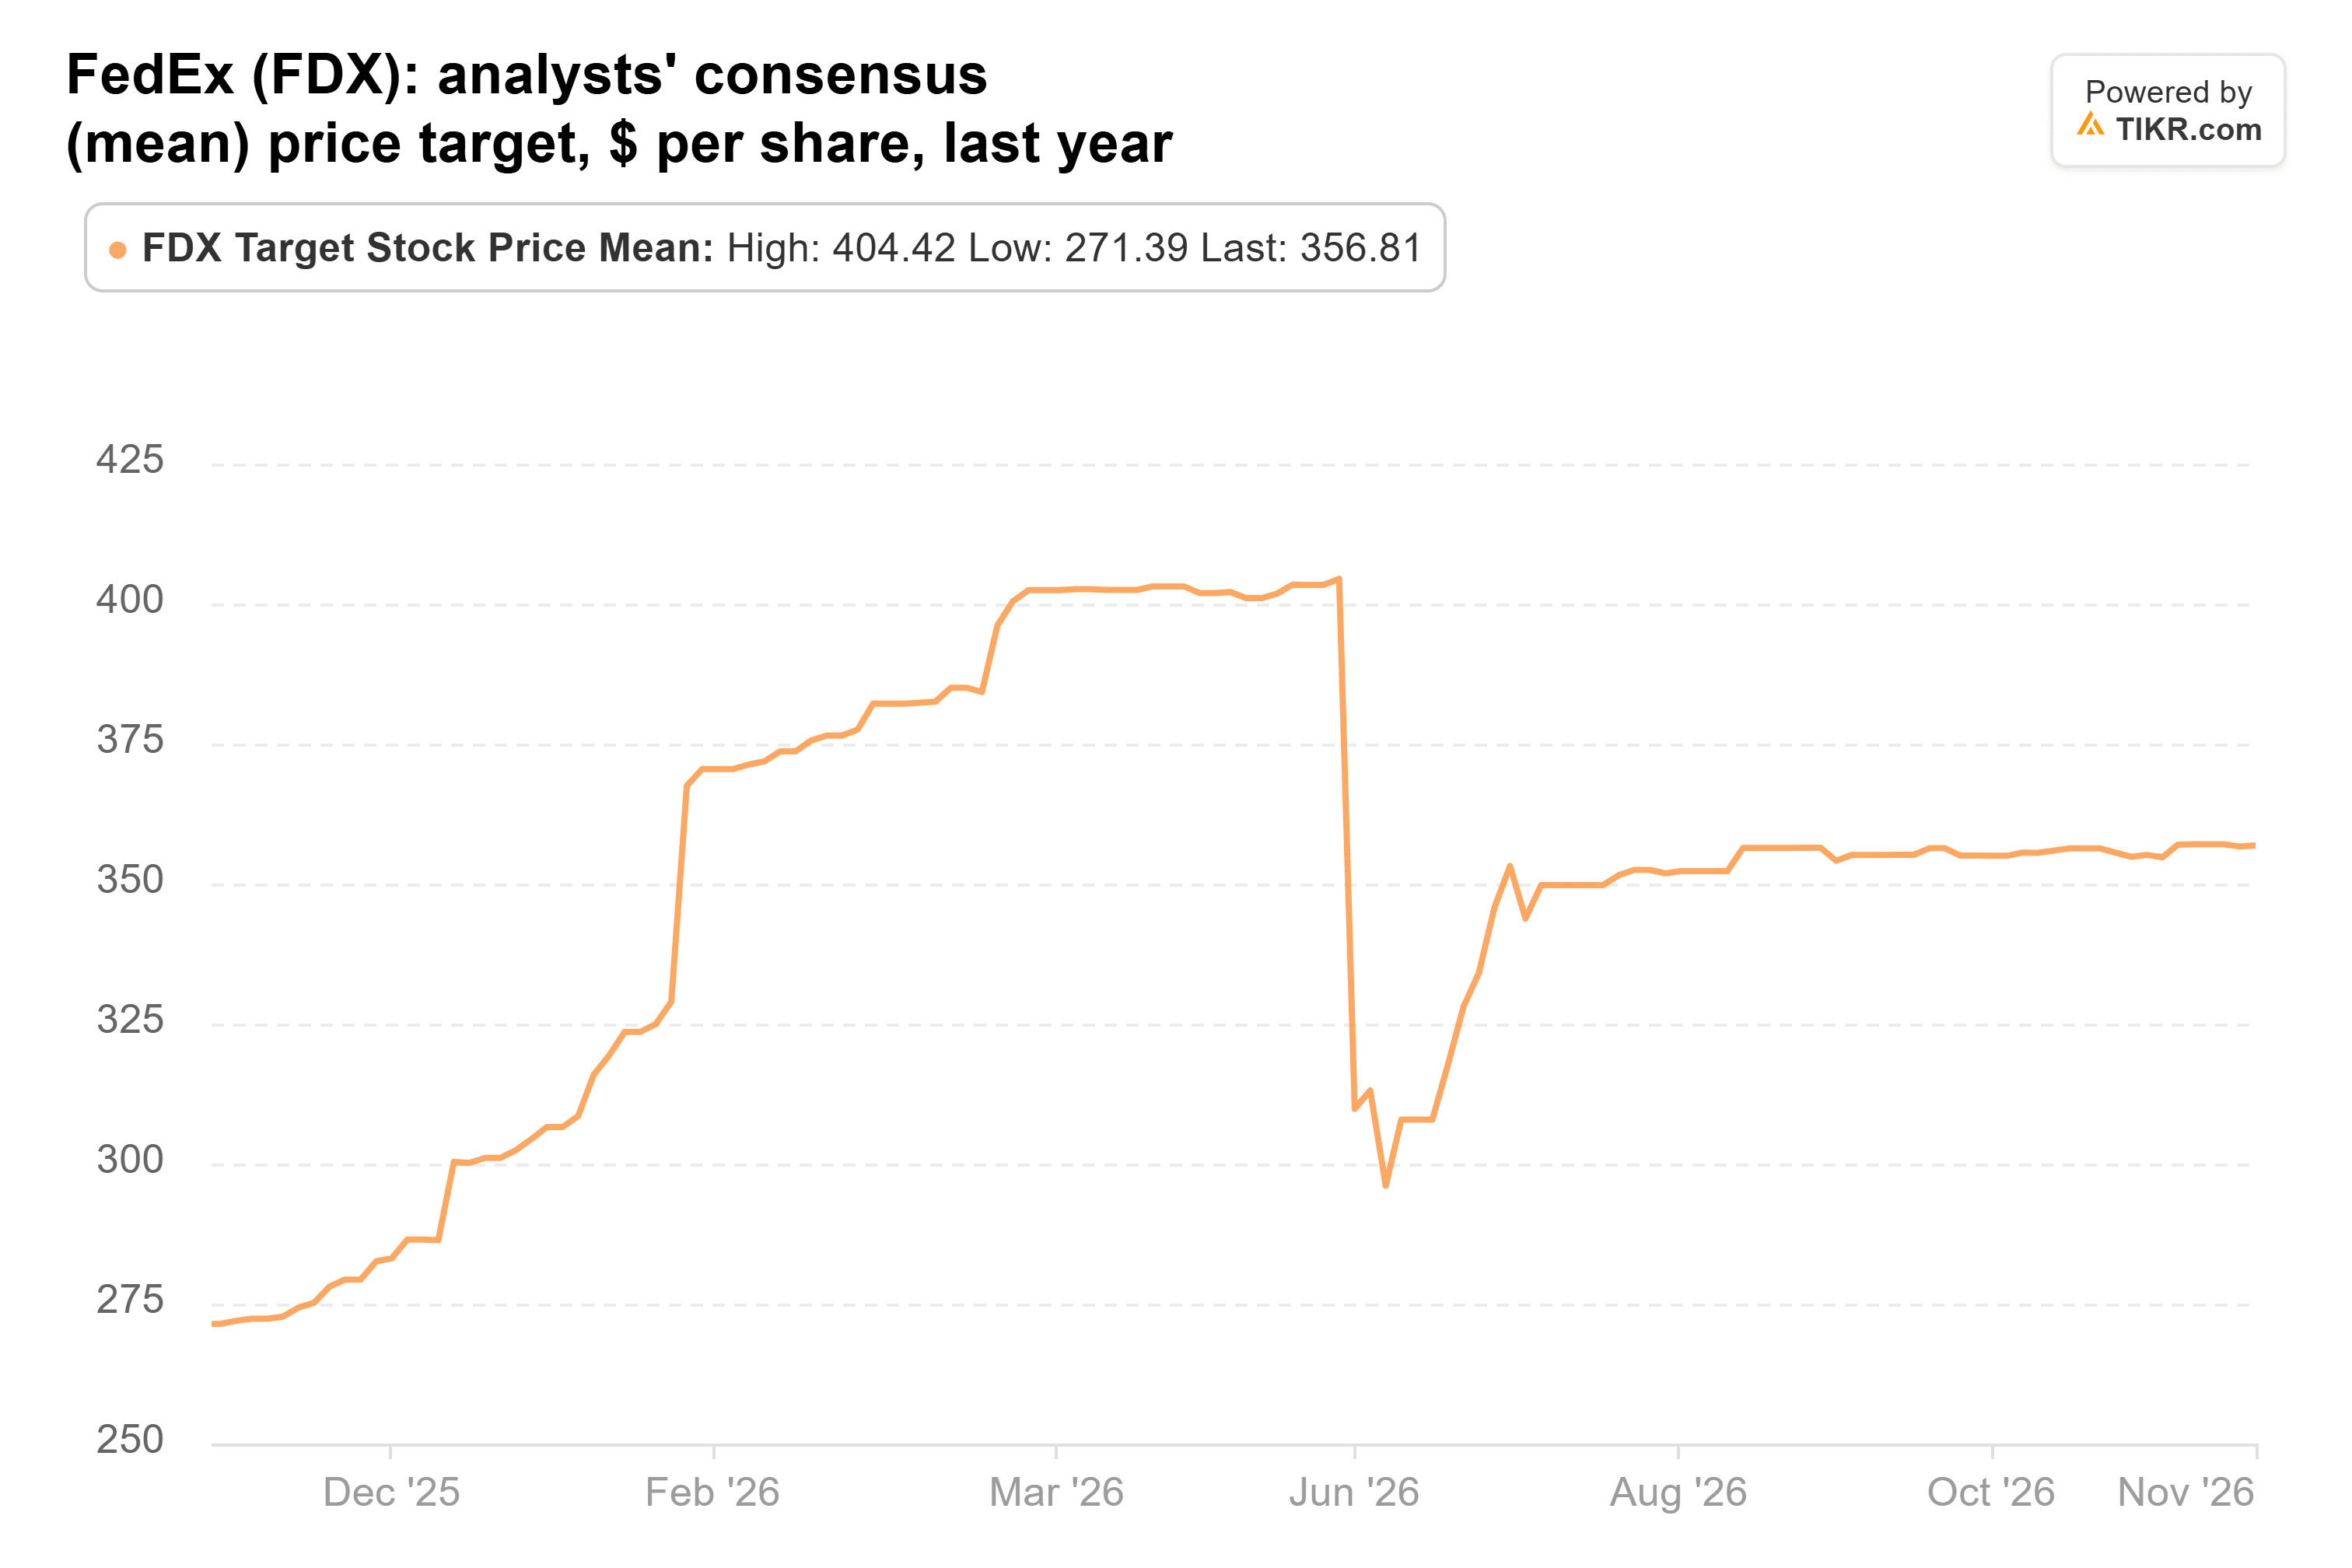
The average of $357 is 12% above today’s price, with the stock at about 16x forward earnings. But the targets range from $160 to $479, so analysts are far apart on what FedEx will earn from here. FedEx reports next in early February.
3. Analysts keep raising Ecolab’s targets
FedEx still trades 23% below its high, but Ecolab is close to its own. The trust holds 5.22 million shares worth $1.43 billion at Sept. 30, its No. 6 holding at 4.8% of its US stocks. The stock is up 10% since then and within 5% of its 52-week high.
Analysts have raised their targets all year:
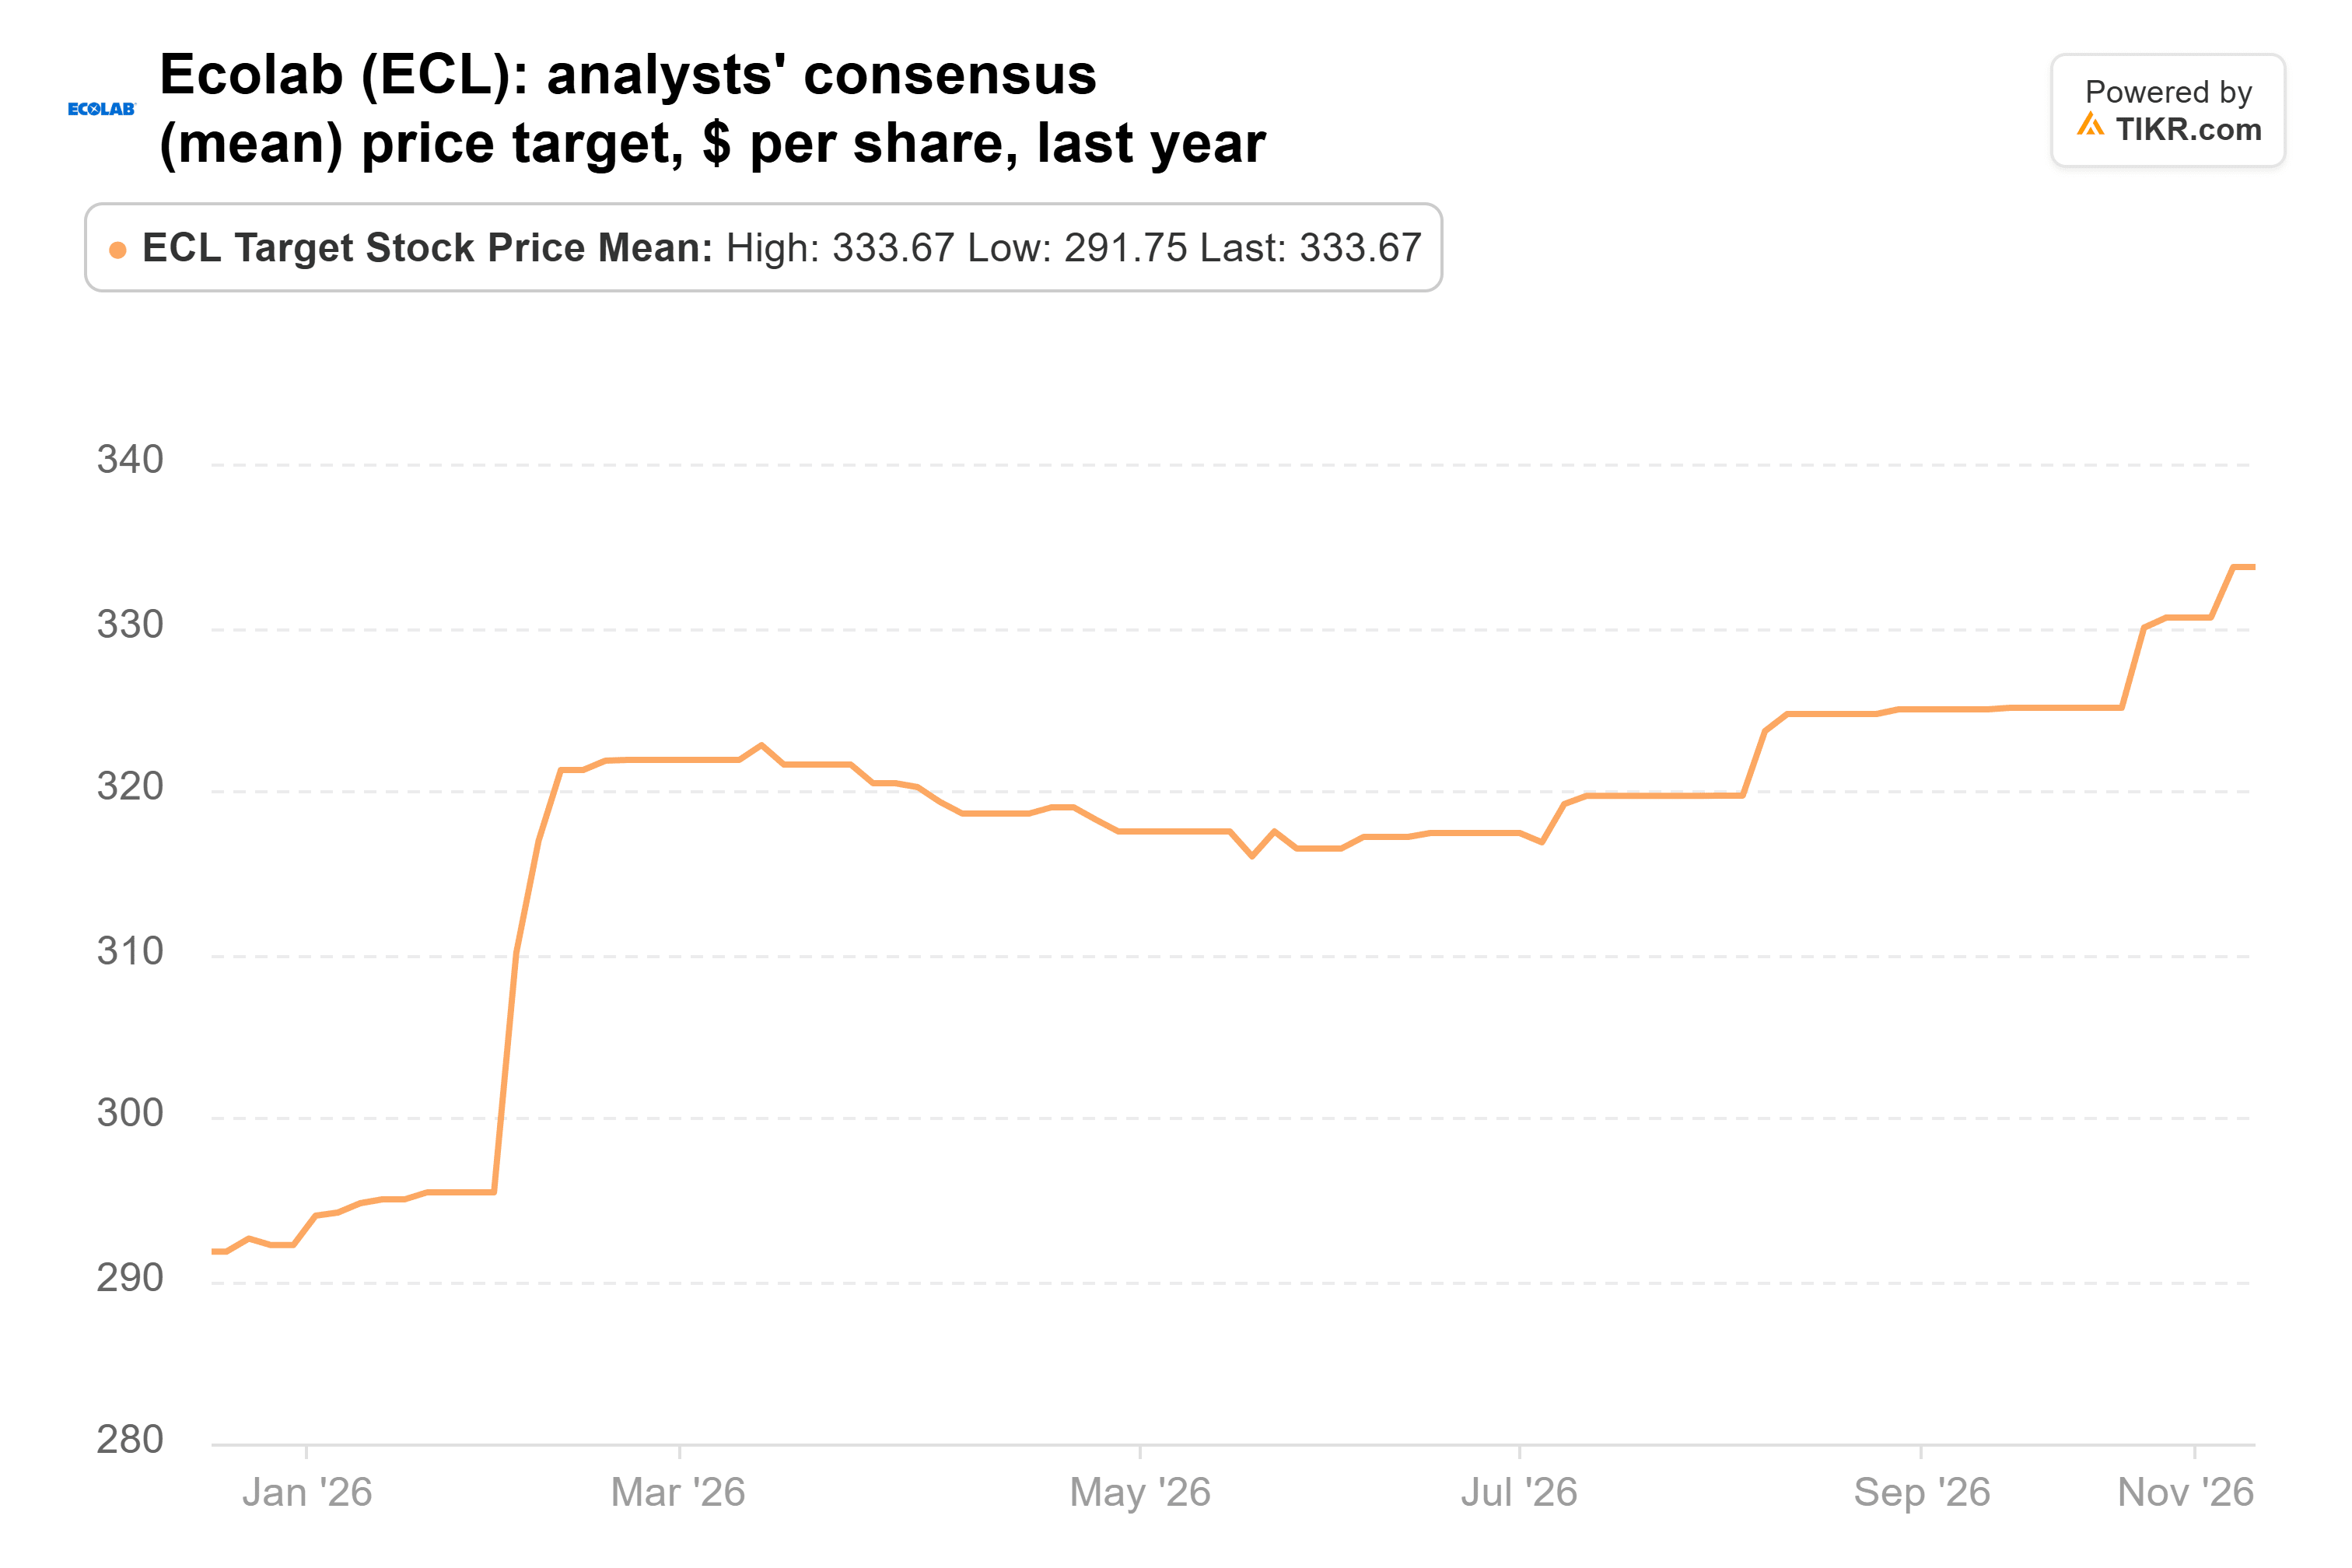
The average target, $334 from 24 analysts, is at its high for the year and 10% above today’s price. The lowest target rose to $300 in late October.
The problem is the price. At about 34x forward earnings, Ecolab already trades like a company investors count on to keep growing, so any upside has to come from estimates that keep rising.
4. Deere reports later this month
Deere, which went up against Caterpillar in a recent dividend duel, has held up far better than its rival. The trust owns 3.56 million shares worth $2.39 billion at Sept. 30, its No. 5 holding at 8.0% of its US stocks. The stock is down just 3% since then and 10% below its 52-week high.
Its average target climbed for most of the year and hasn’t moved since mid-October:
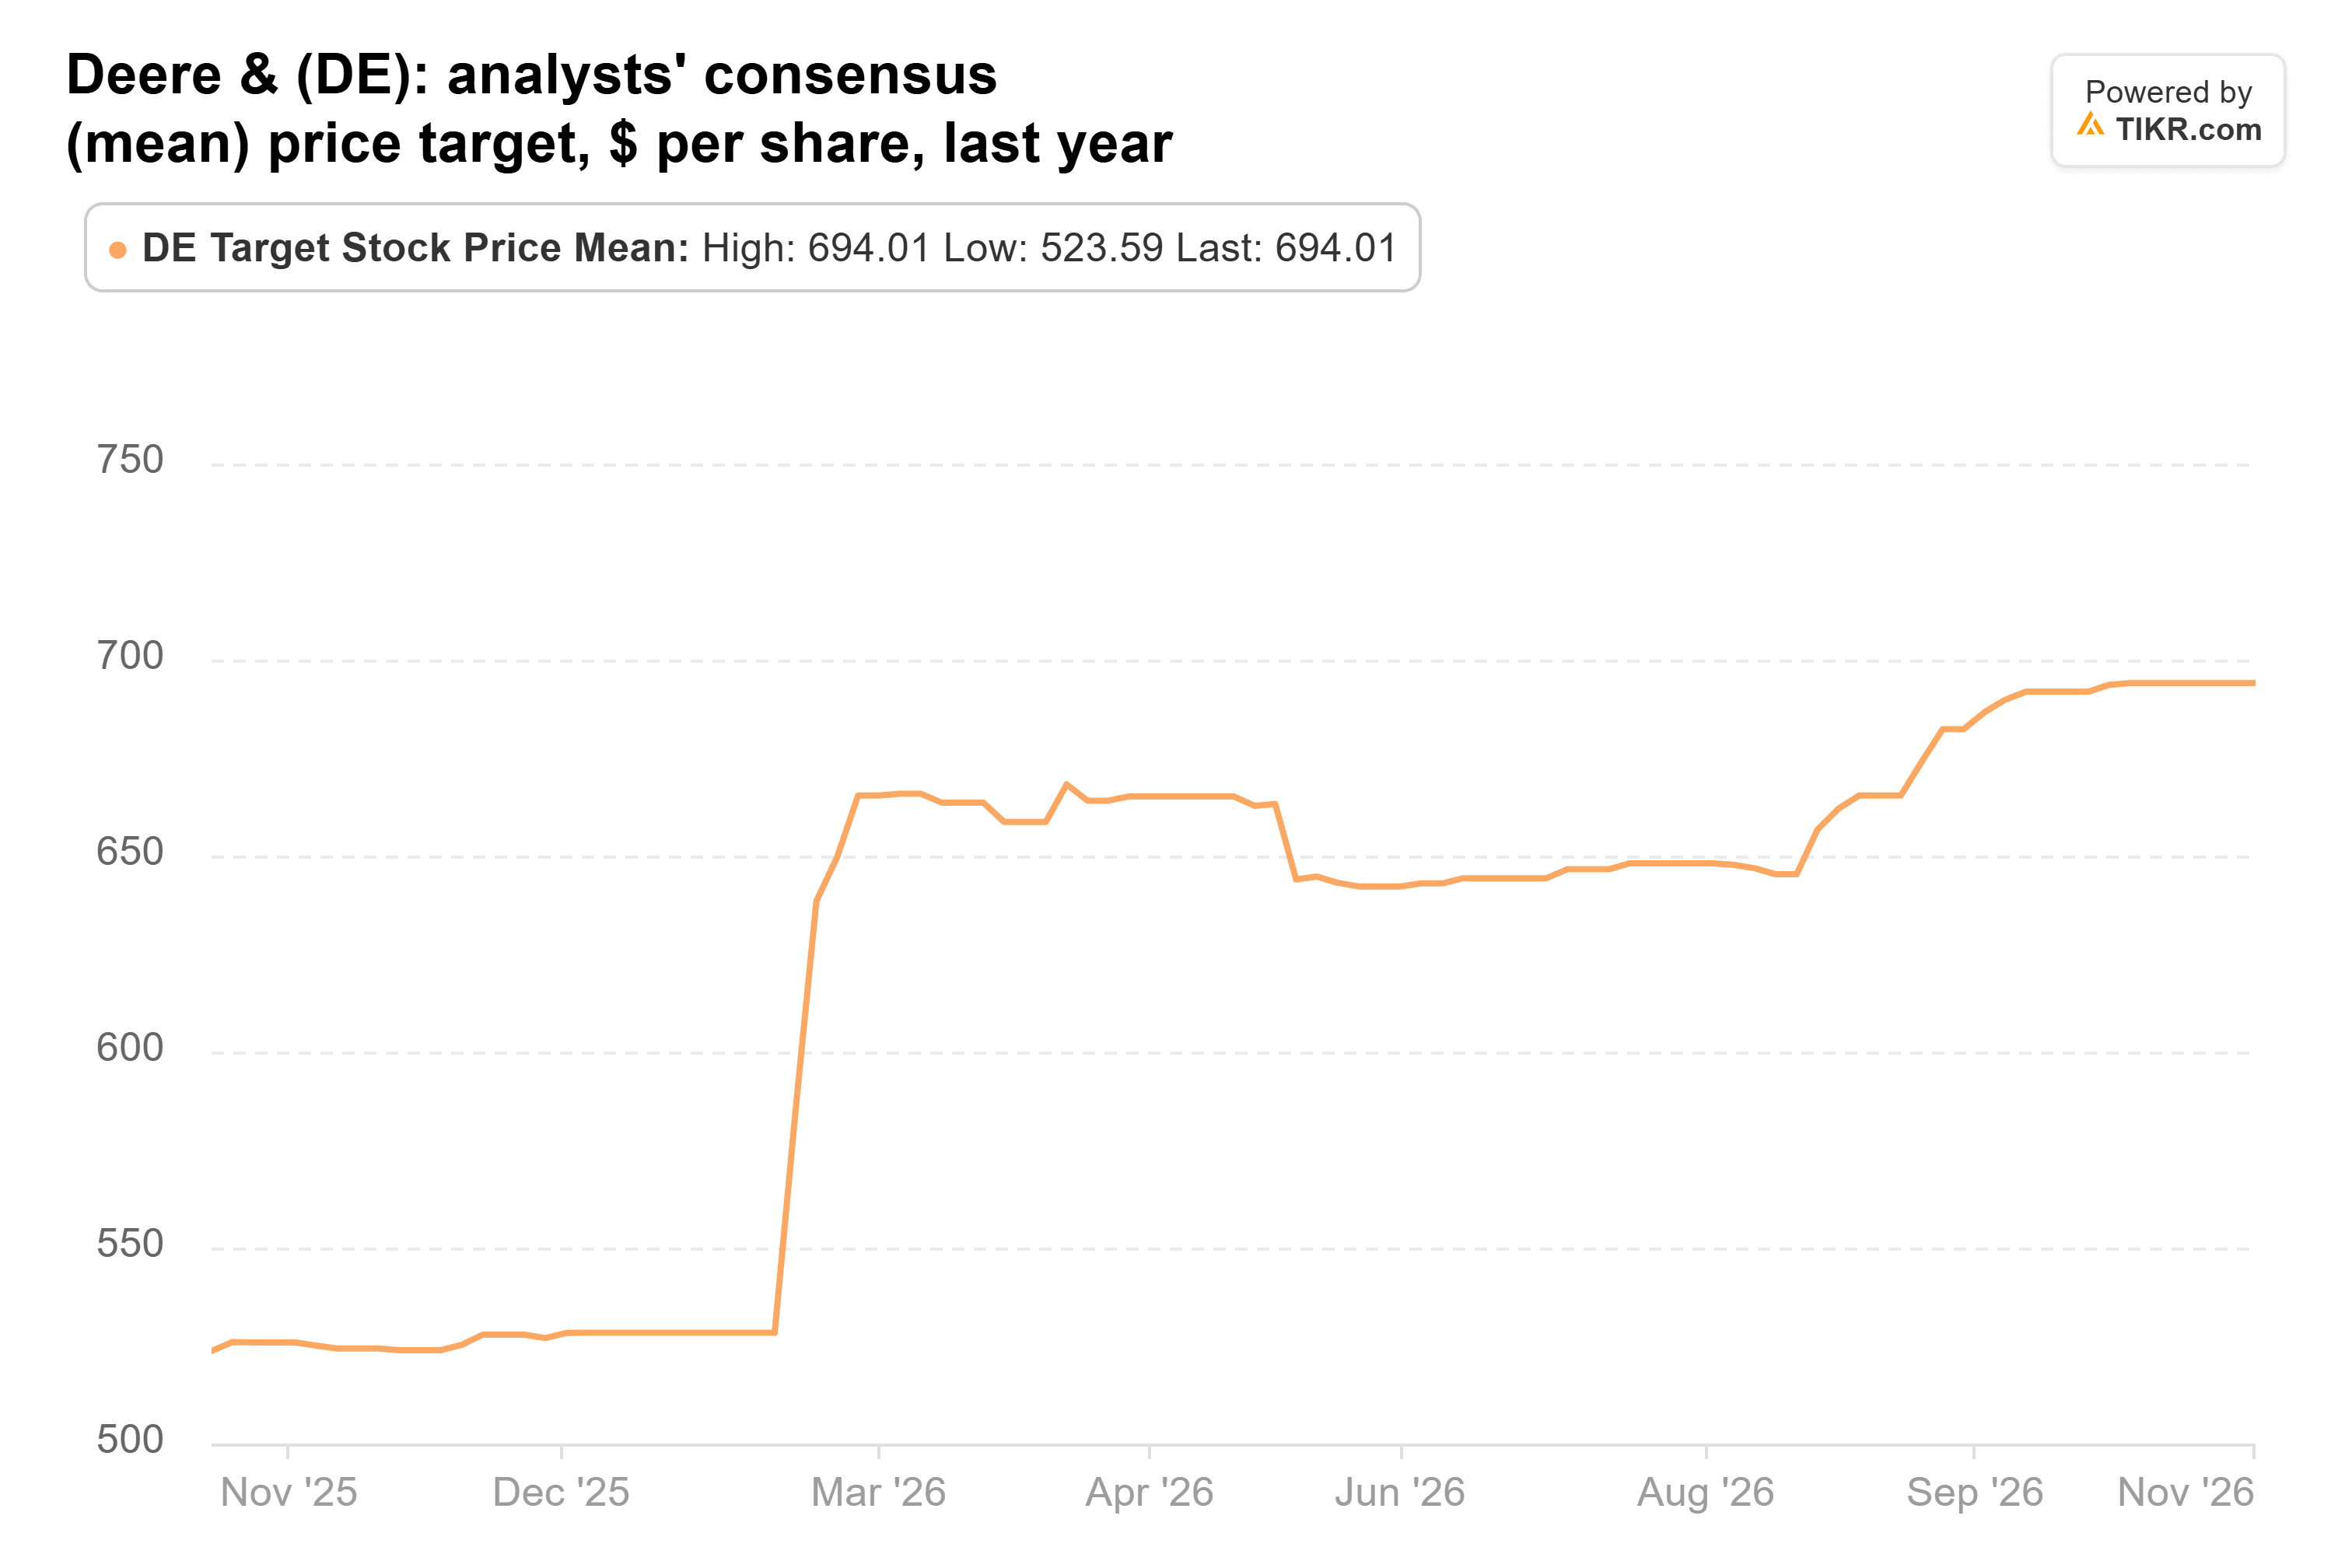
The average target is $694, from 25 analysts, 7% above today’s price. With the stock at about 31x forward earnings, that’s not much room. Deere’s next report, expected late this month, will show whether the estimates behind those targets hold up.
5. Canadian National trades close to Wall Street’s target
Like Ecolab and Deere, Canadian National is near its high. It’s the trust’s No. 2 holding: 51.83 million shares worth $6.16 billion at Sept. 30, or 20.6% of its US stocks. The stock is up 6% since then and sits 4% below its 52-week high. Wall Street’s average target of $134, from 30 analysts, is 6% above today’s price, with the stock at about 21x forward earnings. That’s modest upside for a fifth of the trust’s US stocks, and analysts don’t expect much more from here.
Caterpillar is the one I’d buy
If I could only buy one of the five right now, it’d be Caterpillar. Using 2028’s consensus EPS of $38.69, the $807 average target is about 21x by my math. That’s close to the 19x forward earnings Caterpillar has averaged since 2014. So it doesn’t need a higher multiple, just for the estimates to hold. The stock already trades at about 19x forward earnings, down from 42x at June 30.
Of course, investors have worried about tighter rules for data centers since the Nov. 3 elections. Management also still expects this year’s adjusted operating margin near the bottom of its target range.
The next test is Caterpillar’s fourth-quarter report in late January. Dealers are expected to cut about $1.6 billion of construction inventory, and sales to end users need to stay above last year’s level while they do. The trust’s next 13F, for the quarter ending Dec. 31, is due by mid-February.
So what is Caterpillar stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Caterpillar could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!