Key Takeaways
- Of the 460 big funds that have filed 13Fs for the third quarter, 26 bought Applied Materials, including David Tepper’s Appaloosa, and 27 sold, including Brad Gerstner’s Altimeter.
- The selling went beyond Applied: Altimeter also sold all of its KLA shares, and 11 of the sellers added Intel in the same quarter.
- Applied Materials is down 32% since Sept. 30, even though analysts have raised their fiscal 2027 earnings estimate to $19.29 a share from $16.40 at June 30.
- At 18x forward earnings, below its 21x five-year average, the buyers have the better case.
Applied Materials (AMAT) just split the big money almost down the middle. In their 13Fs for the quarter ended Sept. 30, David Tepper’s Appaloosa opened a new stake, while Brad Gerstner’s Altimeter Capital sold all of its Applied shares, and all of its KLA (KLAC) shares too.
And 11 of the sellers added Intel (INTC) in the same quarter.
From its Sept. 30 close to its latest close, Applied’s stock has fallen 32%. Score one for the sellers, for now.
Tepper’s in, Gerstner’s out
Of the 460 big funds that have filed 13Fs for the quarter so far (funds readers know, or with $1 billion or more of US stocks, leaving out quant and index funds), 26 bought Applied Materials, either opening a position or adding 20% or more. Another 27 sold out or cut 20% or more, and 66 of the 460 held it on Sept. 30.
Appaloosa’s 13F, filed Nov. 16, shows 225,000 new shares worth $115 million at quarter-end prices, 1.5% of its 13F stocks. Larry Robbins’ Glenview Capital added 74%, to 113,745 shares.
Altimeter’s filing came out the same day and shows none of the 261,950 shares it held on June 30. Chase Coleman’s Tiger Global cut its stake 26%, to 1.20 million shares.
TIKR tracks 40 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
The biggest checks went both ways
The biggest buyer by dollars was Sarasin & Partners, whose 13F holds $8.93 billion of US stocks. It opened a position of 428,405 shares, worth $219 million at quarter-end prices and 2.5% of its 13F stocks. Abrams Bison Investments, which manages $3.04 billion, went further: it added 36% to reach 752,000 shares, worth $385 million. That’s 19.4% of its 13F stocks and its second-largest position.
The sellers moved even more money. Lone Pine Capital, which manages $21.62 billion, cut its stake 92%, about $569 million of stock at quarter-end prices. Parnassus Investments cut 36%, about $467 million, and trimmed KLA by 20% as well. John Armitage’s Egerton Capital held 521,065 shares on June 30, which its filing valued at $377 million then, and none on Sept. 30.
KLA and Applied now both sit 53% below their 52-week highs. Whatever the sellers’ reasons, 11 of the 27 added Intel in the same quarter.
Analysts keep raising the bar
The slide since Sept. 30 ran through an October investor day that gave no forecast for the equipment market. Then on Nov. 12, Applied reported a record quarter anyway: fourth-quarter revenue of $10.41 billion, up 53%, and non-GAAP EPS of $4.16, above the $4.02 it had guided to. On the call, CFO Brice Hill said he expects cloud capex to rise more than 50% in 2027, to well over $1 trillion.
Analysts expect Applied’s earnings to keep climbing fast:
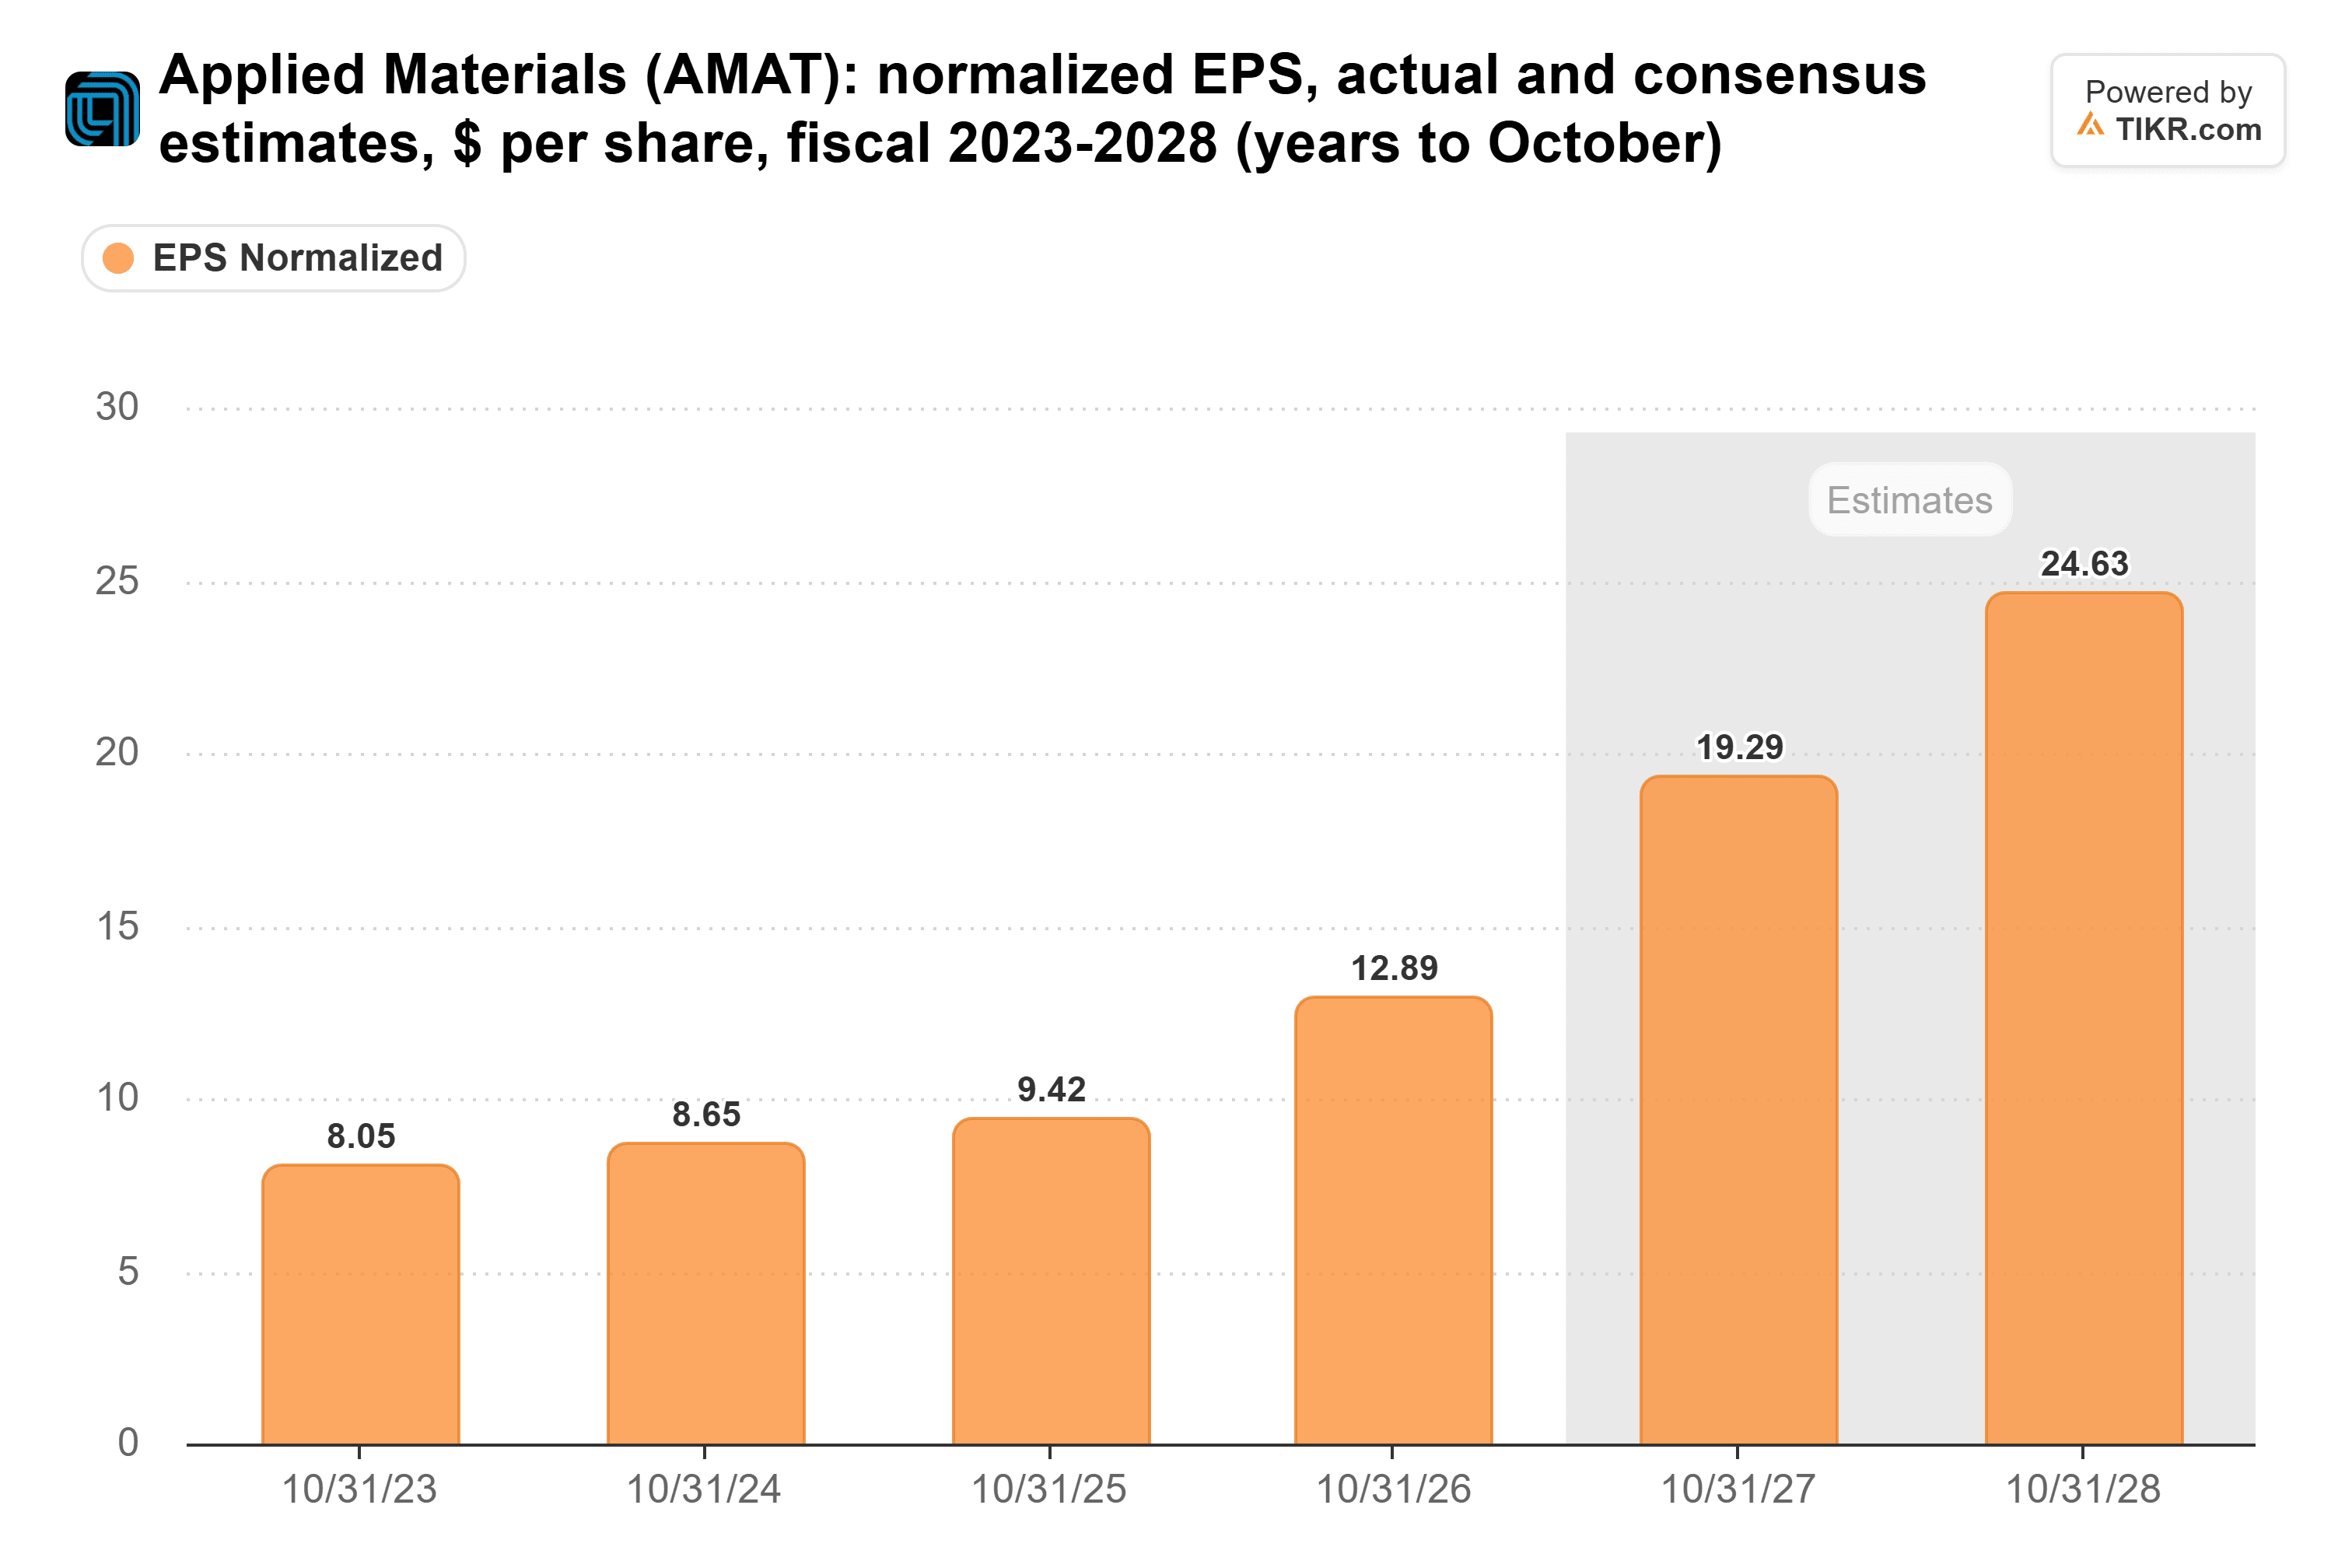
Consensus fiscal 2027 normalized EPS is $19.29, up from $16.40 at June 30. So the estimates went up while the stock went down. And the fiscal 2028 estimate of $24.63 is nearly double what Applied earned in fiscal 2026.
The buyers have the numbers
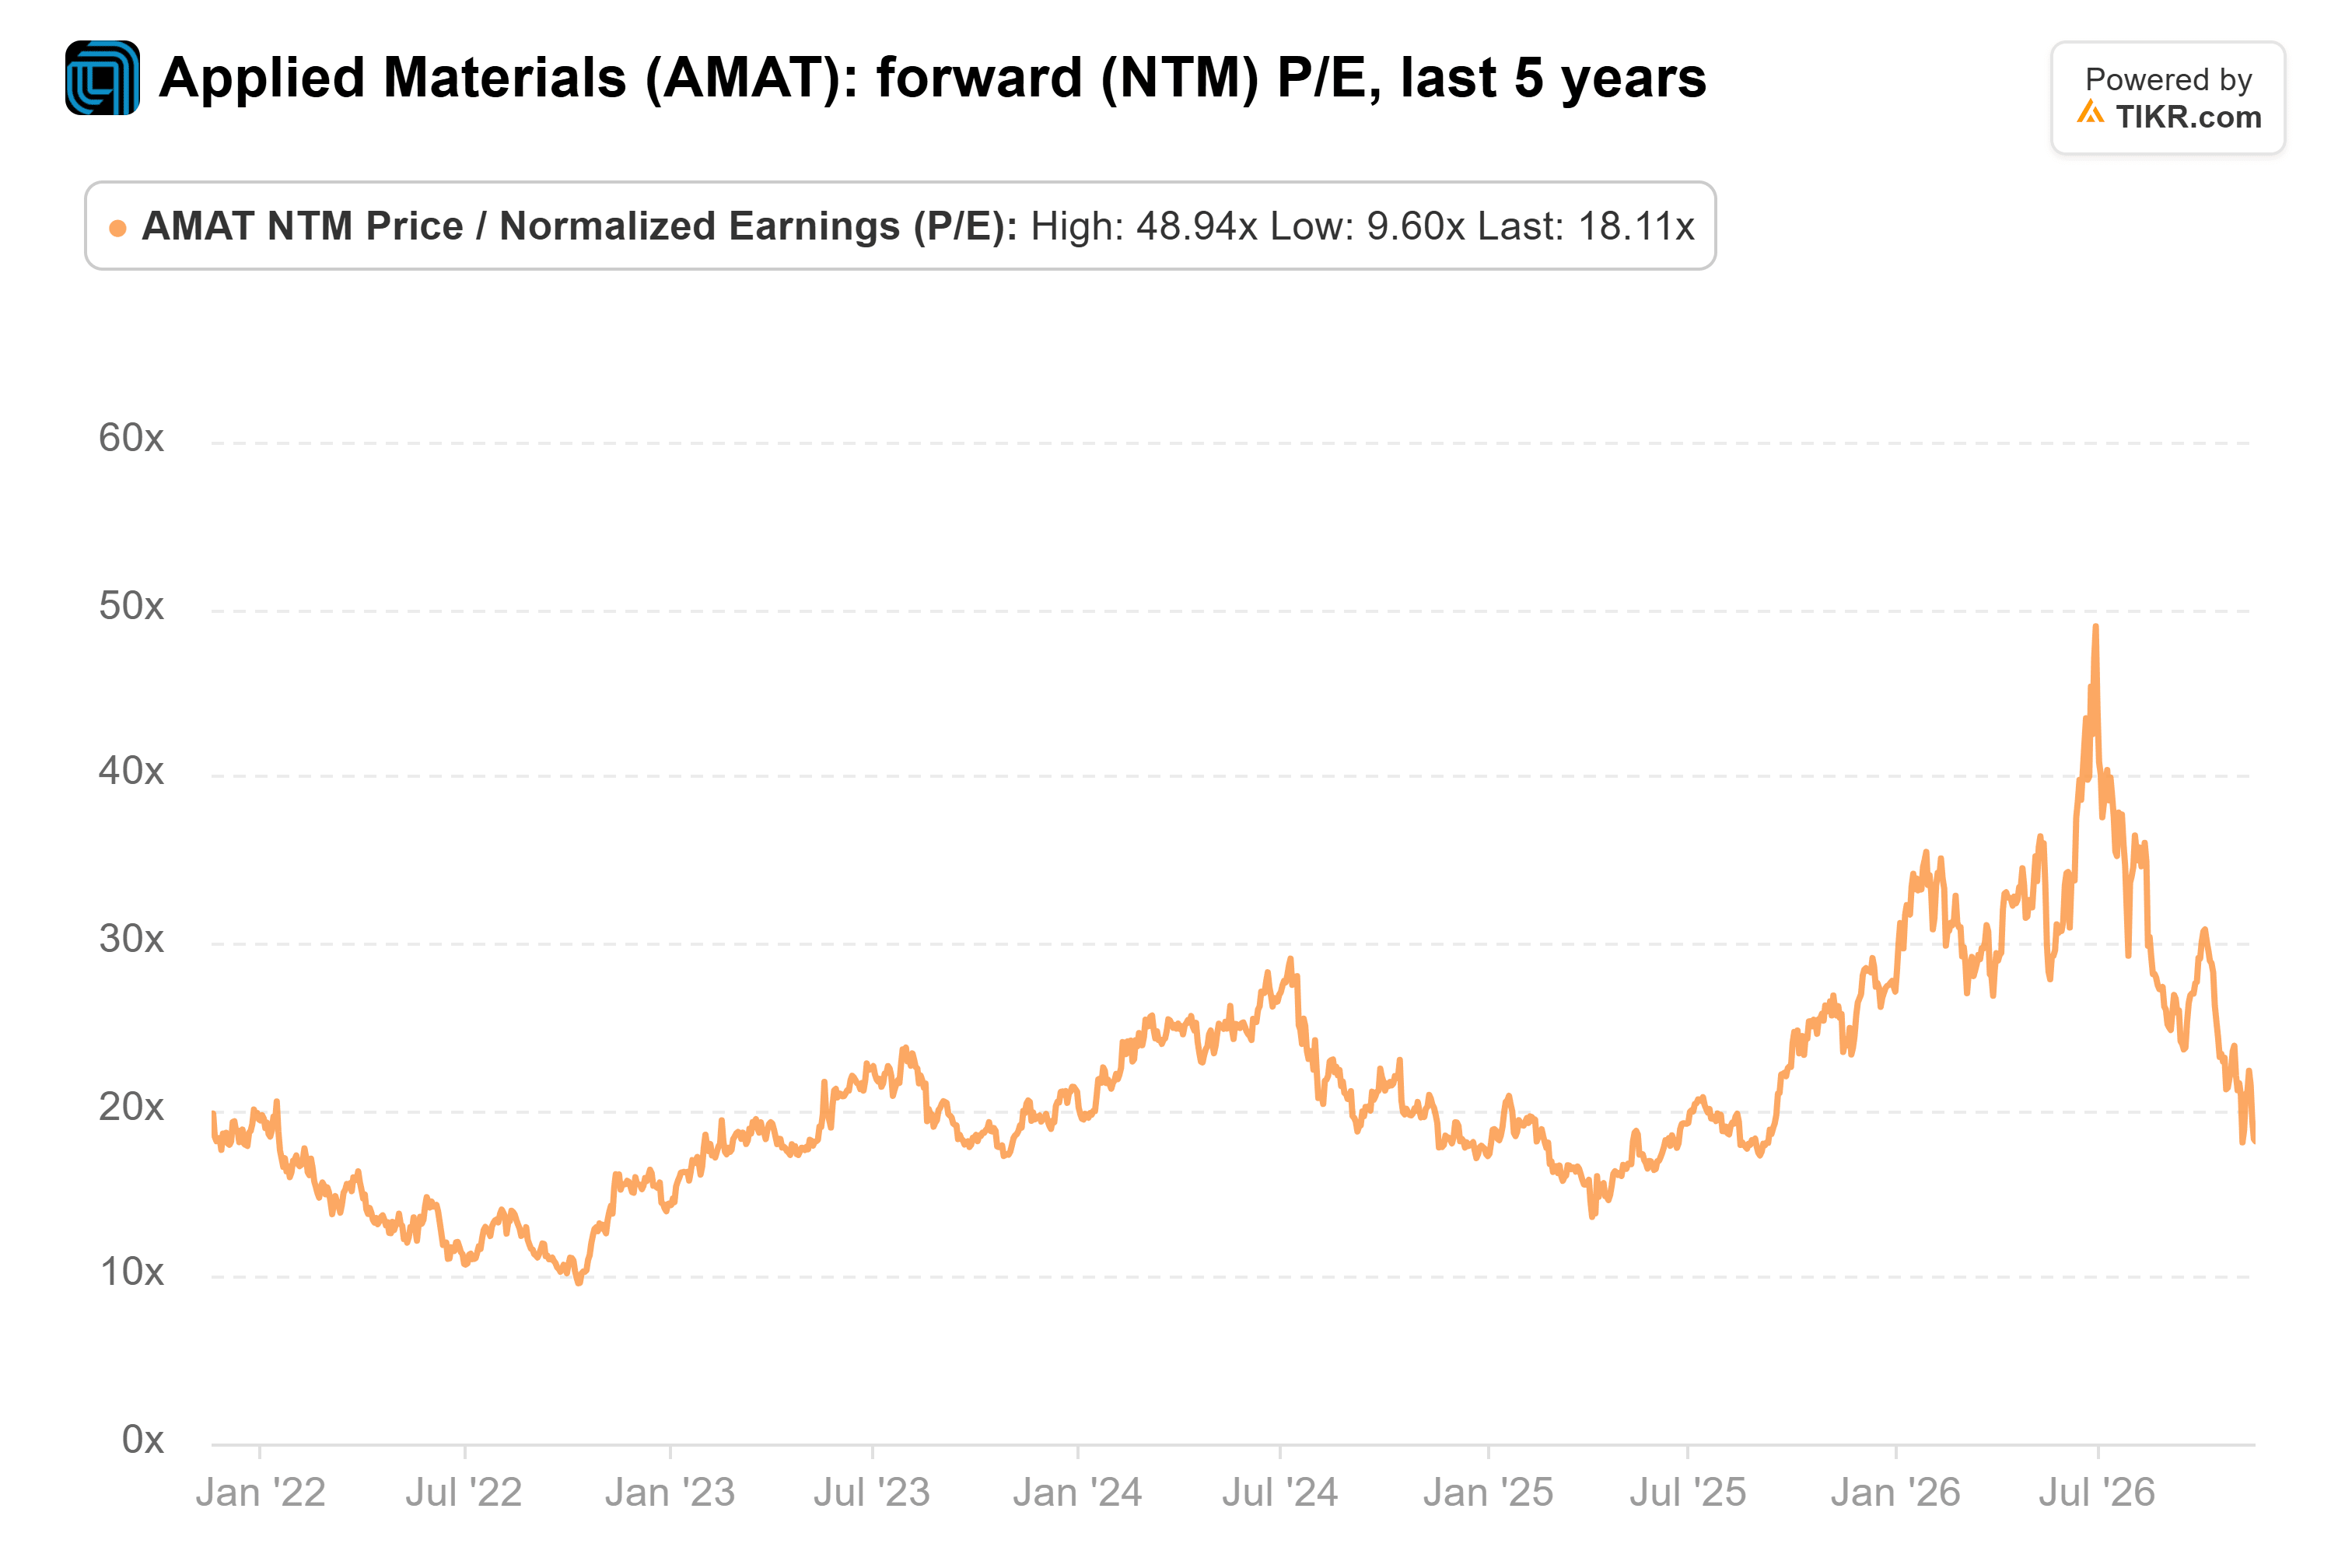
At 18x forward earnings, Applied trades below its five-year average of 21x, and far below the 49x it reached on June 30:
Analysts’ targets have come down from their September peak, but they’re still well above the stock price:
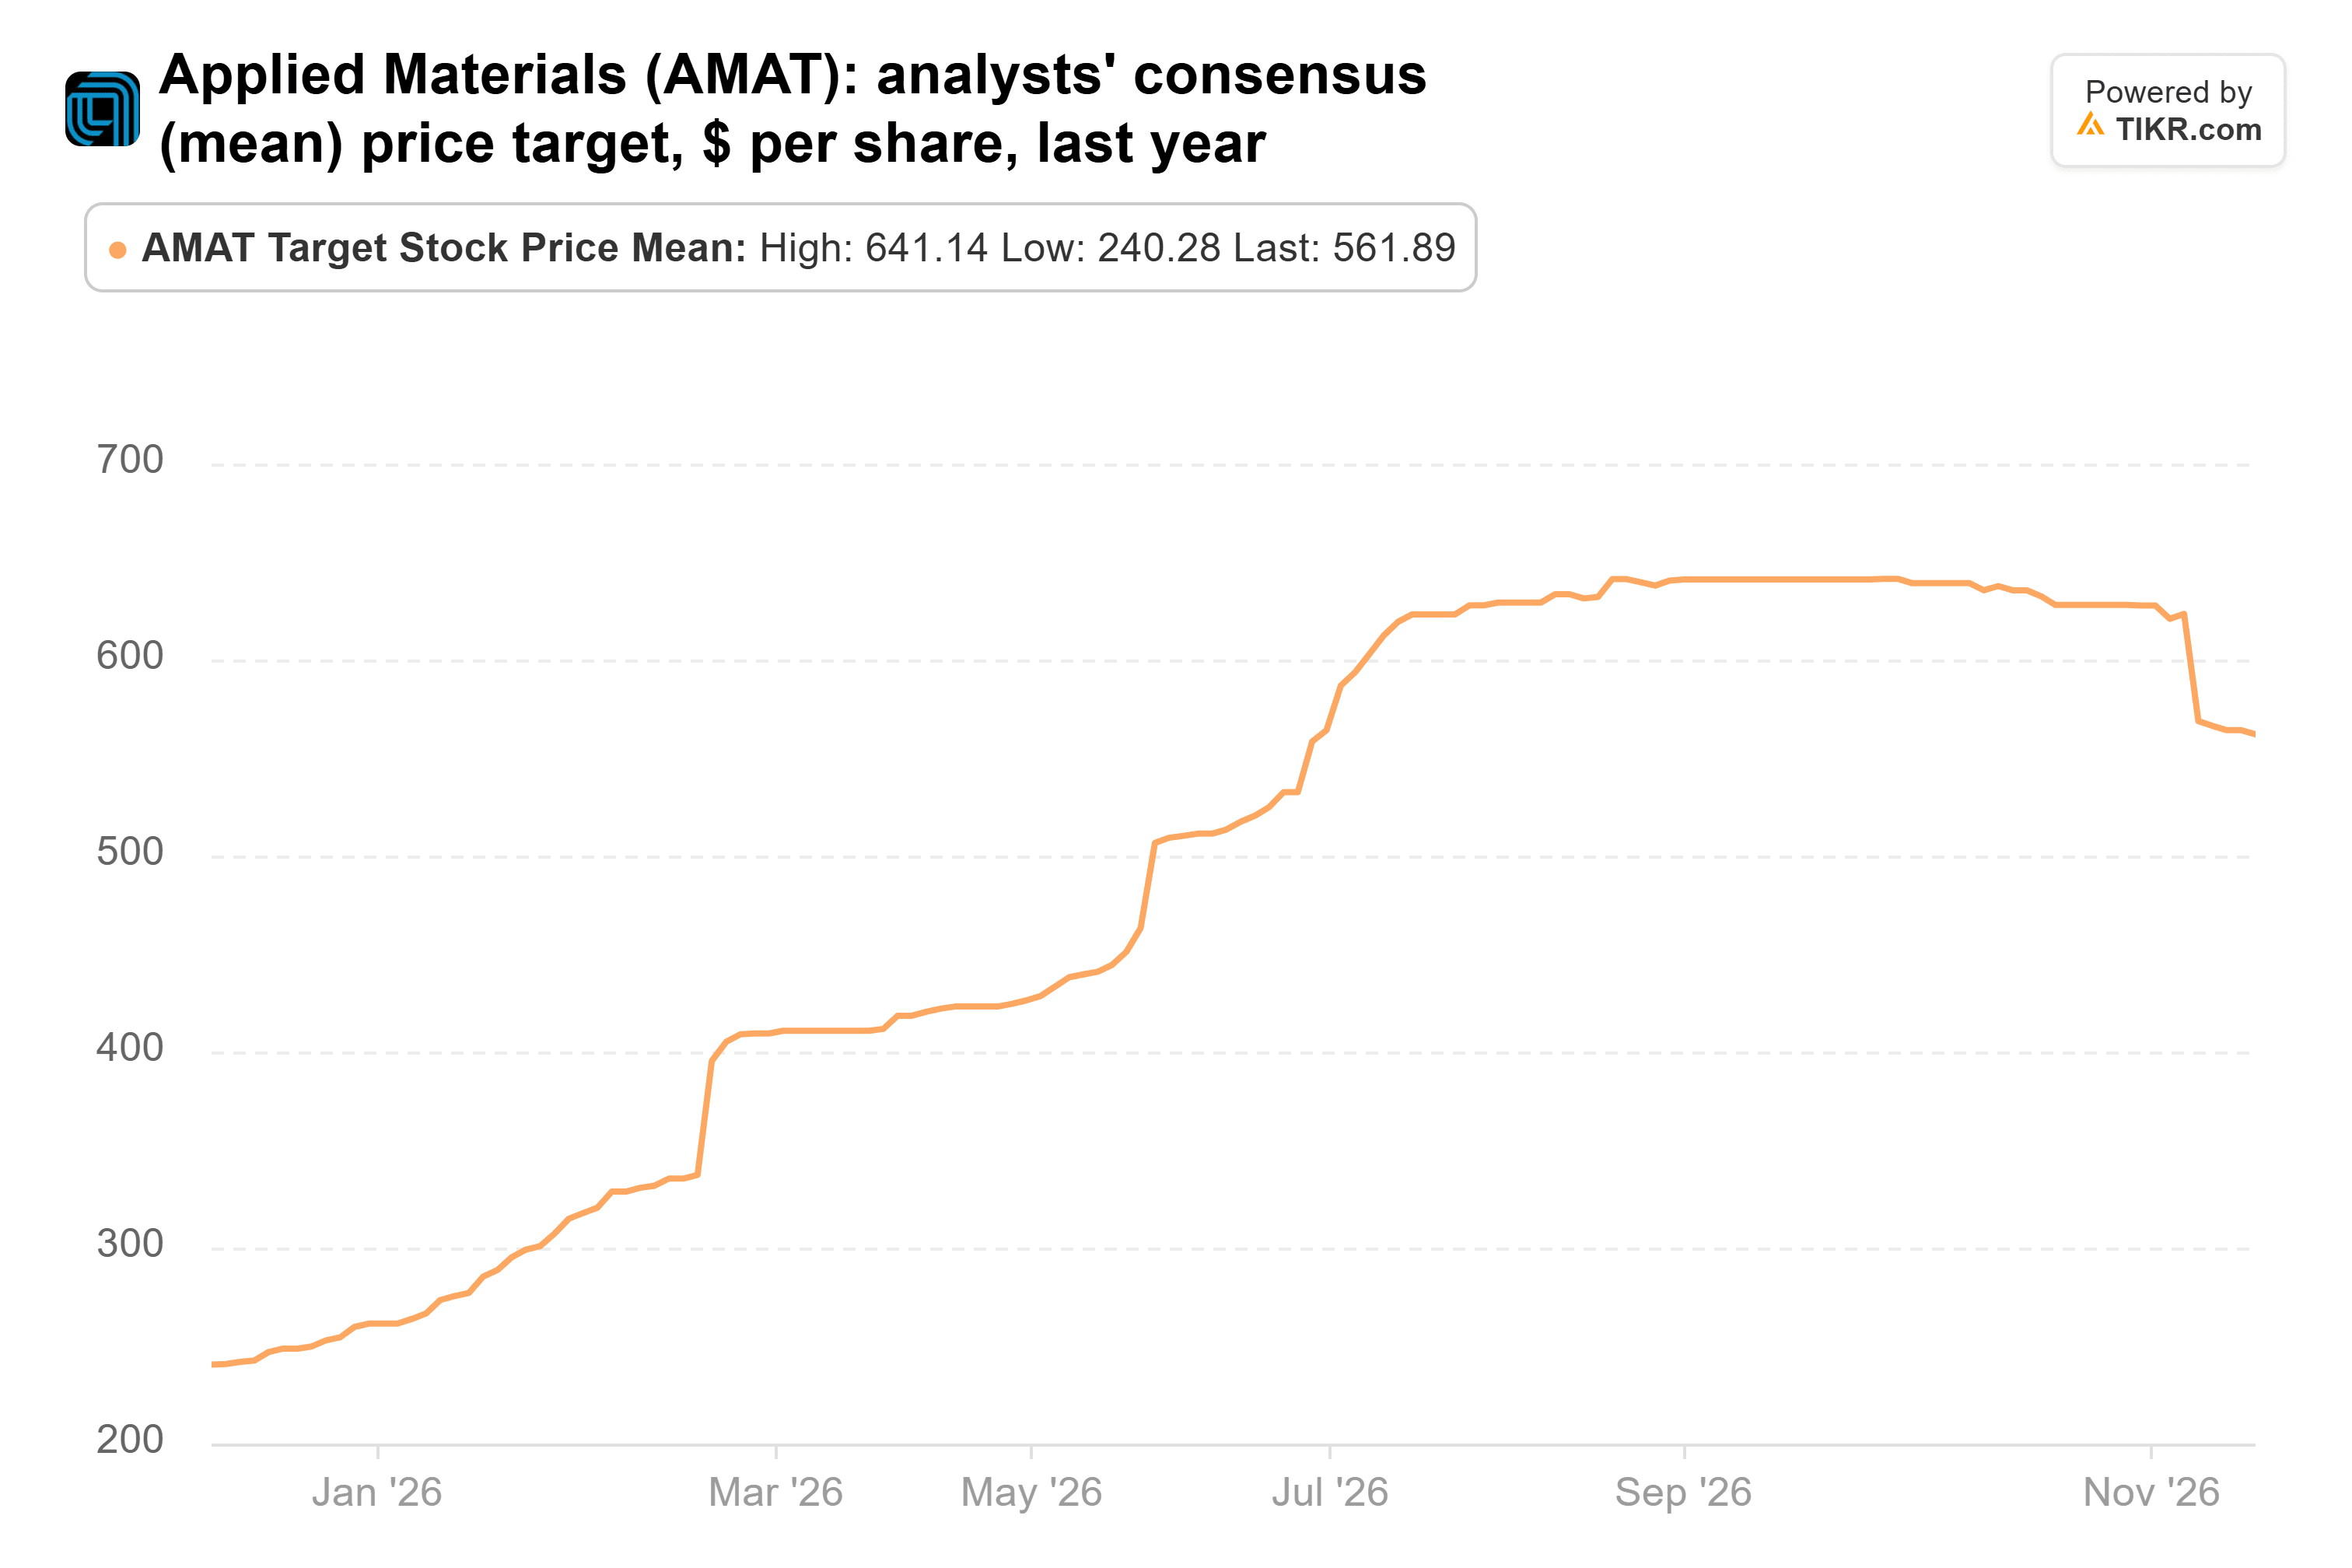
The consensus target from 40 analysts is $562. That’s down from $641 on Sept. 24 but up from $240 a year ago. It’s 61% above the latest close, and even the lowest target, $358, is above that close. On fiscal 2028 estimates, $562 works out to about 23x, a little above the stock’s average. So most of that upside would have to come from earnings growth.
The risk is a repeat of 2018. As that boom peaked, Applied’s forward P/E fell to 8.2x at the October quarter-end, and revenue fell 13% in fiscal 2019.
Still, I side with the buyers. The sellers have come out ahead since Sept. 30, but the buyers have rising estimates, a below-average multiple and a Street whose lowest target is above today’s price.
A 13F only shows where each fund stood on one day. The next round, for the quarter ending Dec. 31, comes in mid-February. Until then, watch the fiscal 2027 estimate. If it slips much below $19.29 a share, the sellers will have been right for the right reasons.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!