Key Takeaways
- Of 460 big funds that have filed 13Fs for the quarter ended Sept. 30, 12 bought Western Digital, Stanley Druckenmiller’s Duquesne Family Office among them, and 14 sold, Ken Fisher’s Fisher Investments among them.
- The sellers moved far more money, though Fisher’s own trim was tiny, and two sellers added Palo Alto Networks and Dell.
- Western Digital is down 43% since Sept. 30, while analysts expect its earnings per share to nearly quadruple from fiscal 2026 to fiscal 2028.
- At about 9x forward earnings, the numbers side with the buyers, as long as hard-drive pricing holds.
Western Digital (WDC) split the big funds almost down the middle last quarter, and the stock has fallen 43% since.
Of the 460 big funds that have filed 13Fs for the quarter ended Sept. 30 (funds readers know, or with $1 billion or more in US stocks, quant and index funds left out), 12 bought Western Digital, opening a position or adding 20% or more, and 14 sold out or cut 20% or more. Another 23 held it at the quarter’s end.
The same funds moved on other stocks, too: Stanley Druckenmiller cut his Palo Alto Networks (PANW) stake while Ken Fisher added to his, and the biggest Western Digital seller opened a position in Dell (DELL).
Druckenmiller brought the name, Brookfield the dollars
Druckenmiller’s Duquesne Family Office opened a position of 80,960 shares, worth $37 million on Sept. 30, according to its 13F filed Nov. 16. That’s 0.9% of the $4.15 billion of US stocks its 13F holds. Brookfield Corporation, whose 13F holds $80.45 billion of US stocks, was the biggest buyer by dollars, with a new 215,000-share position worth about $98 million. Blue Sparrow, whose 13F holds $8.31 billion, opened one worth about $71 million, and FengHe Fund Management, with $2.06 billion in its 13F, more than quintupled its stake to 138,361 shares, 3.0% of its 13F stocks.
TIKR tracks 26 analysts on Western Digital. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Western Digital, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Western Digital’s Analyst Ratings
The sellers moved far more money
The sellers’ three biggest moves each dwarf the biggest buy. WT Asset Management, whose 13F holds $6.18 billion of US stocks, sold all 784,212 shares, a stake worth $501 million on June 30 and 9.9% of its 13F stocks then. Jericho Capital, which manages $11.67 billion, sold out of a $412 million stake, and Whale Rock Capital, which manages $12.97 billion, sold one worth $256 million, both valued at the end of June.
Ken Fisher barely sold. Fisher Investments, which manages $386.67 billion, cut its stake 22%, about $859,000 of stock, according to its 13F filed Nov. 6. That’s about what Lee Ainslie’s Maverick Capital and Larry Robbins’ Glenview Capital each bought.
A 13F can’t say when anyone traded or at what price. But the shares the buyers held on Sept. 30 have lost 43% of their value since.
Two sellers added Palo Alto and Dell
Duquesne cut its Palo Alto stake 74%, to 30,000 shares worth $12 million, while Fisher added 41%, to 8.14 million shares worth $3.24 billion, making it one of 15 big funds that bought Palo Alto. Palo Alto raised its fiscal 2027 adjusted EPS guidance to $4.26-$4.30 from $4.16-$4.19 on Nov. 18, but its diluted share count was up 18% from a year earlier. It trades at about 79x forward earnings.
WT Asset Management opened a $78 million Dell position, and Blue Sparrow, a Western Digital buyer, kept Dell as its No. 5 holding. Dell has fallen 48% since Sept. 30 and trades at about 10x forward earnings. Its lower-grade customer financing receivables rose to $4.4 billion at the end of July from $1.8 billion in January.
Do the numbers back the buyers?
Western Digital’s fiscal first quarter was a blowout. Revenue rose 55% from a year earlier to $4.38 billion, non-GAAP gross margin jumped to 58.1% from 43.9%, and non-GAAP EPS rose 161% to $4.64. In the Oct. 22 release, CFO Kris Sennesael credited “robust exabyte growth and improved pricing,” and guided second-quarter non-GAAP EPS to $5.80 at the midpoint.
Analysts expect EPS to nearly quadruple, from $10.22 in fiscal 2026 to $40.40 in fiscal 2028:
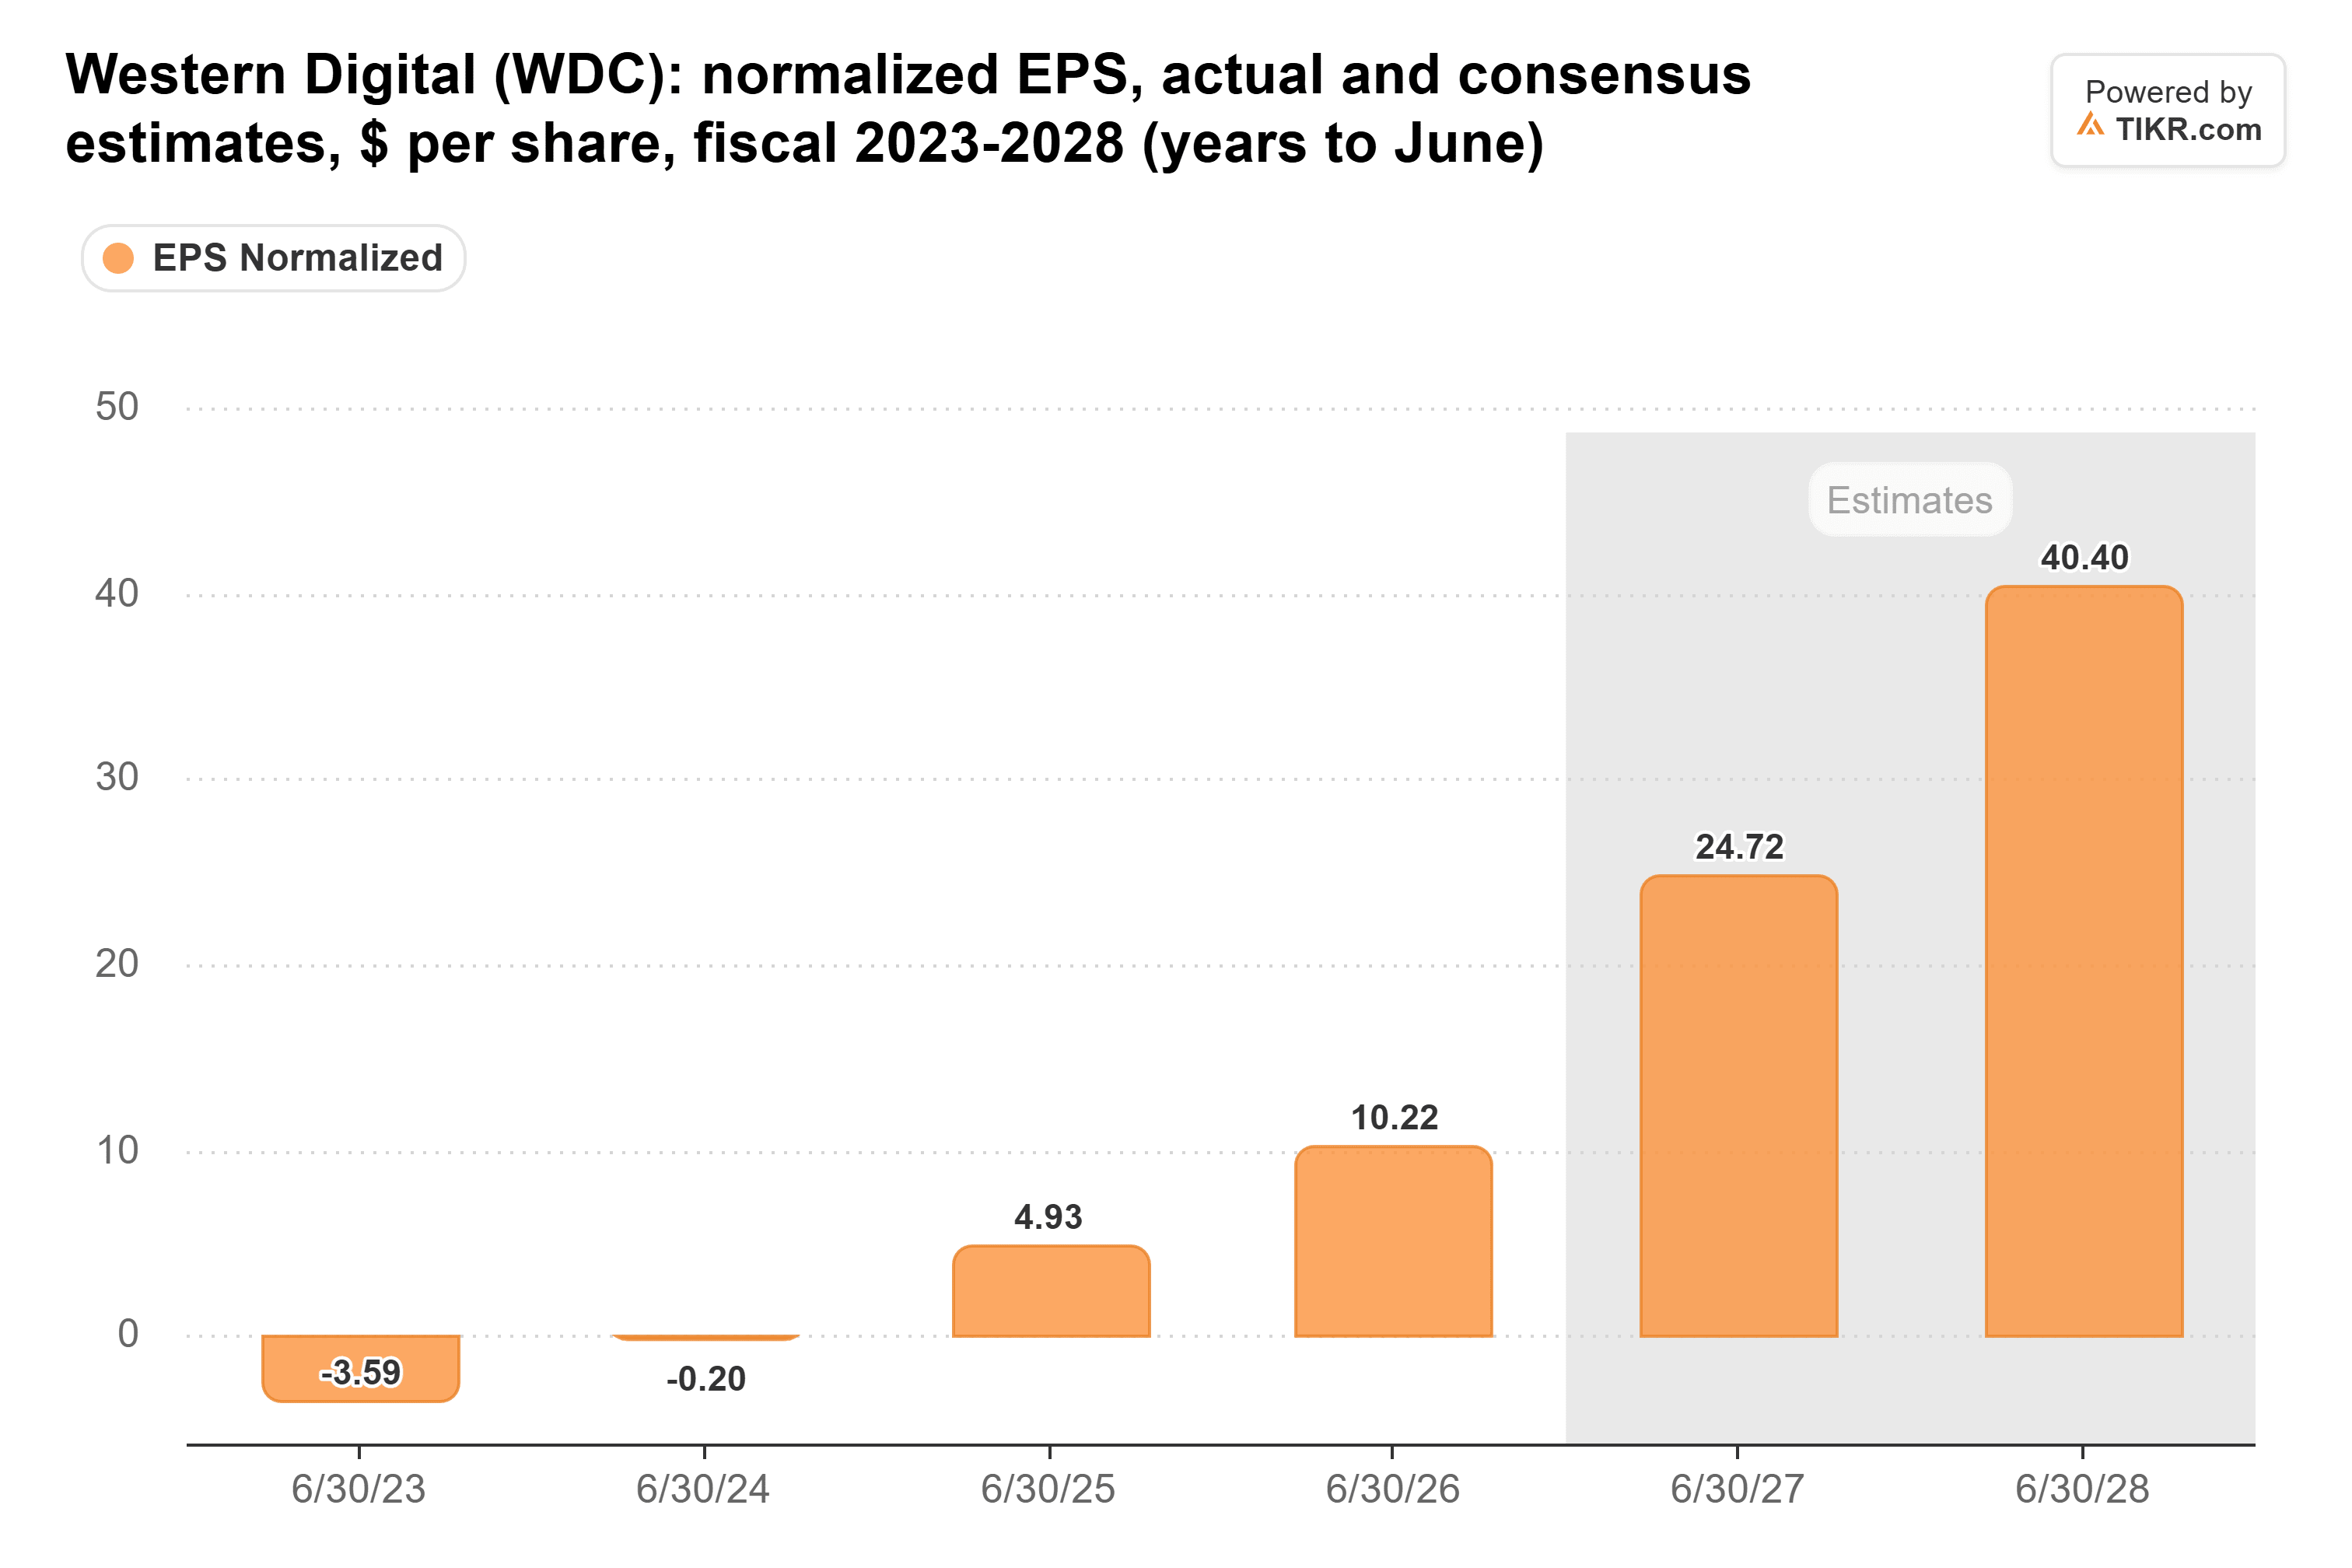
Take out the first quarter’s $4.64 and the second quarter’s guided $5.80, and fiscal 2027’s $24.72 needs about $14.28 from the second half, or roughly $7 a quarter.
Yet the stock trades at about 9x forward earnings, after sliding in early November on memory-price worries after the election and a flash maker’s cautious outlook. Analysts’ average target has come down only a little from its October high:
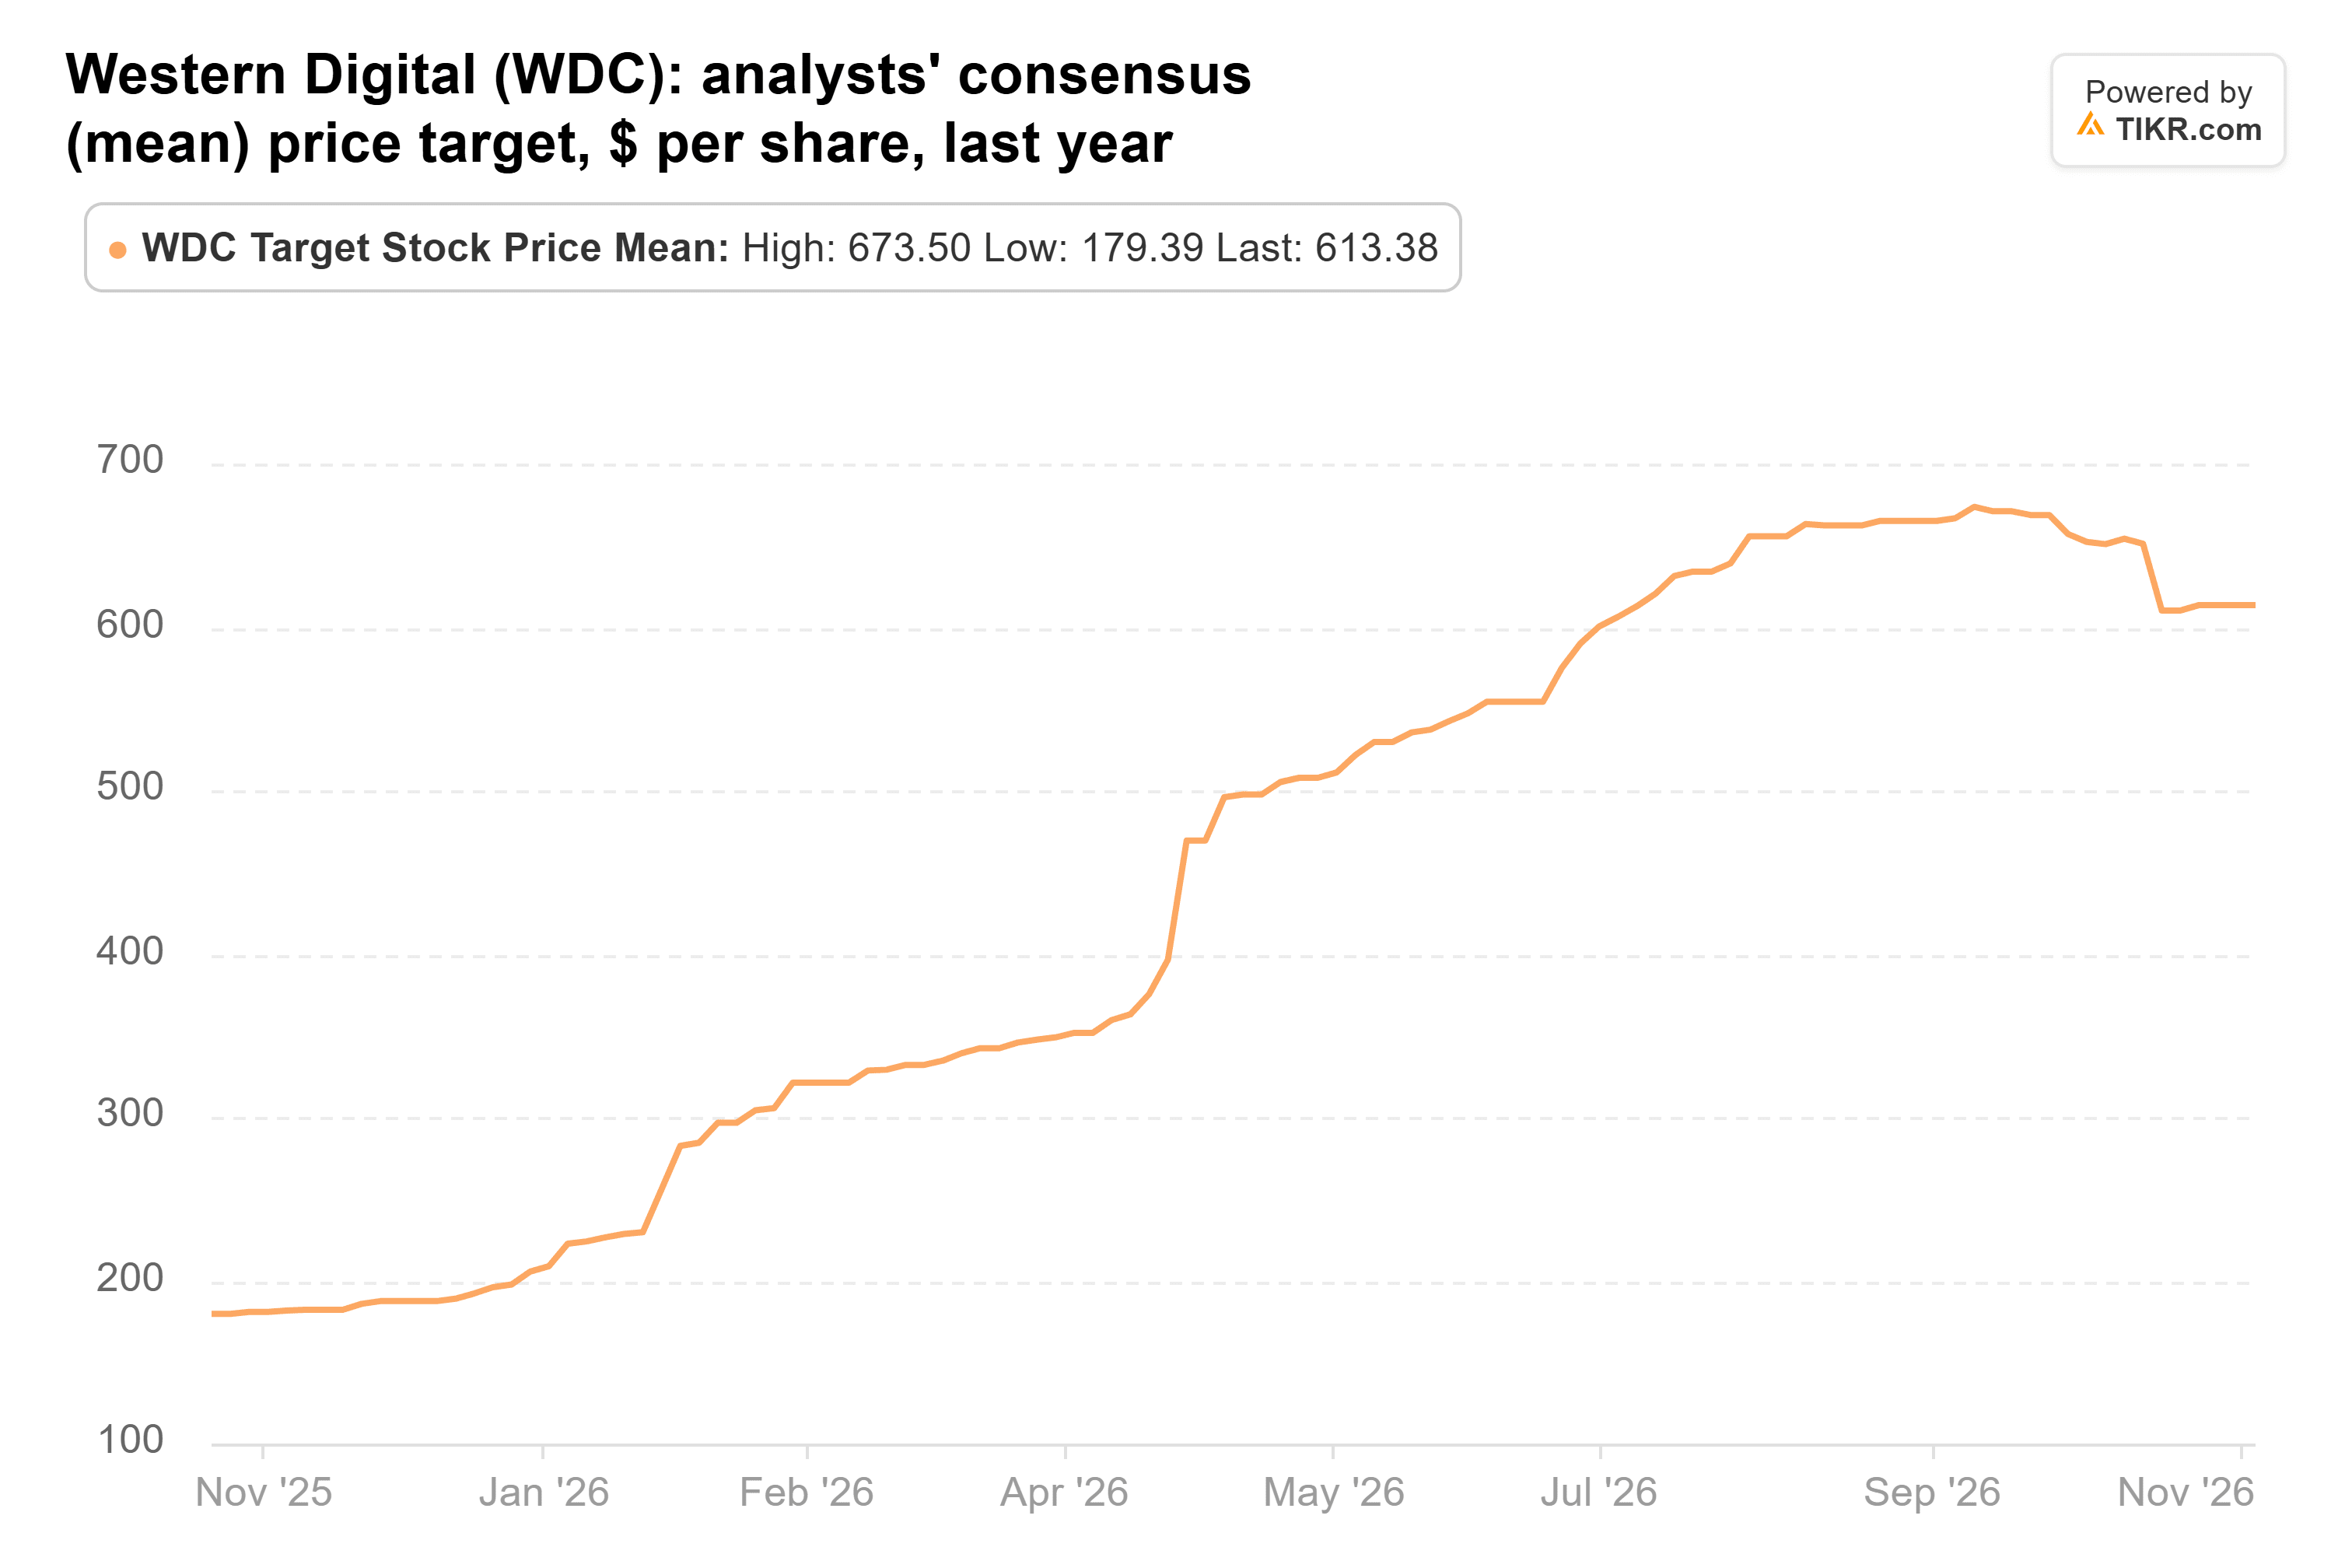
At $613, it sits 135% above the stock, and even the lowest, $405, is well above it.
The buyers have the better side
At 9x forward earnings, the market is pricing Western Digital as if its earnings have peaked. That’s the sellers’ best case: Western Digital’s margins rose on pricing, and pricing can turn faster than estimates do.
But at this price, I’d side with the buyers. Western Digital just topped expectations, turned out $1.38 billion of free cash flow in one quarter, and guided higher. Fiscal 2028 earnings could land well short of the $40.40 consensus and still leave the stock cheap.
The fiscal second-quarter report, likely in late January, is the next test: non-GAAP EPS near the $5.80 guide, with gross margin at or above the guided 60% to 61%, would keep the consensus path on track. And the next 13Fs, due in mid-February, will show whether Druckenmiller stayed.
So what is Western Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Western Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Western Digital for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!