Key Takeaways
- Dan Niles argues Meta’s ad business would keep producing cash even if the AI trade unwinds, which newly listed Anthropic can’t say.
- Meta’s ad revenue grew 26% in the third quarter, more than double Pinterest’s 12% revenue growth.
- The catch is that capex topped operating cash flow last quarter, and a pullback would hit suppliers like Arista Networks first.
- At about 19x forward earnings, Meta looks like a cheap way to own AI with a hedge built in.
Anthropic (ANT) closed its first day of trading on Nov. 19 at $97.17, 17% above its $83 IPO price, and Wall Street was lining it up against Meta Platforms (META) before the shares even opened.
On the Nov. 18 episode of Squawk Pod, the day Anthropic priced its offering, CNBC senior markets commentator Mike Santoli said Anthropic’s market cap “getting into the zone of a trillion and a half” makes for “a pretty clean comparison with Meta, which is at exactly that market cap.”
Dan Niles, founder and portfolio manager at Niles Investment Management, pointed to the bigger difference on CNBC’s Closing Bell the same day:
“If the AI trade blows up, Meta’s got this other business called social media that generates a ton of cash.”
Anthropic, he noted, doesn’t have one.
Meta’s ad business is still pulling away, too. Its ad revenue grew 26% in the third quarter, while revenue at Pinterest (PINS), which sells into the same social ad market without a giant AI bill, grew 12%. Meta’s suppliers, like Arista Networks (ANET), would feel an AI unwind first: Arista’s two largest customers, which it has identified as Microsoft and Meta, made up 42% of its 2025 revenue.
TIKR tracks 62 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
The ad engine is still compounding
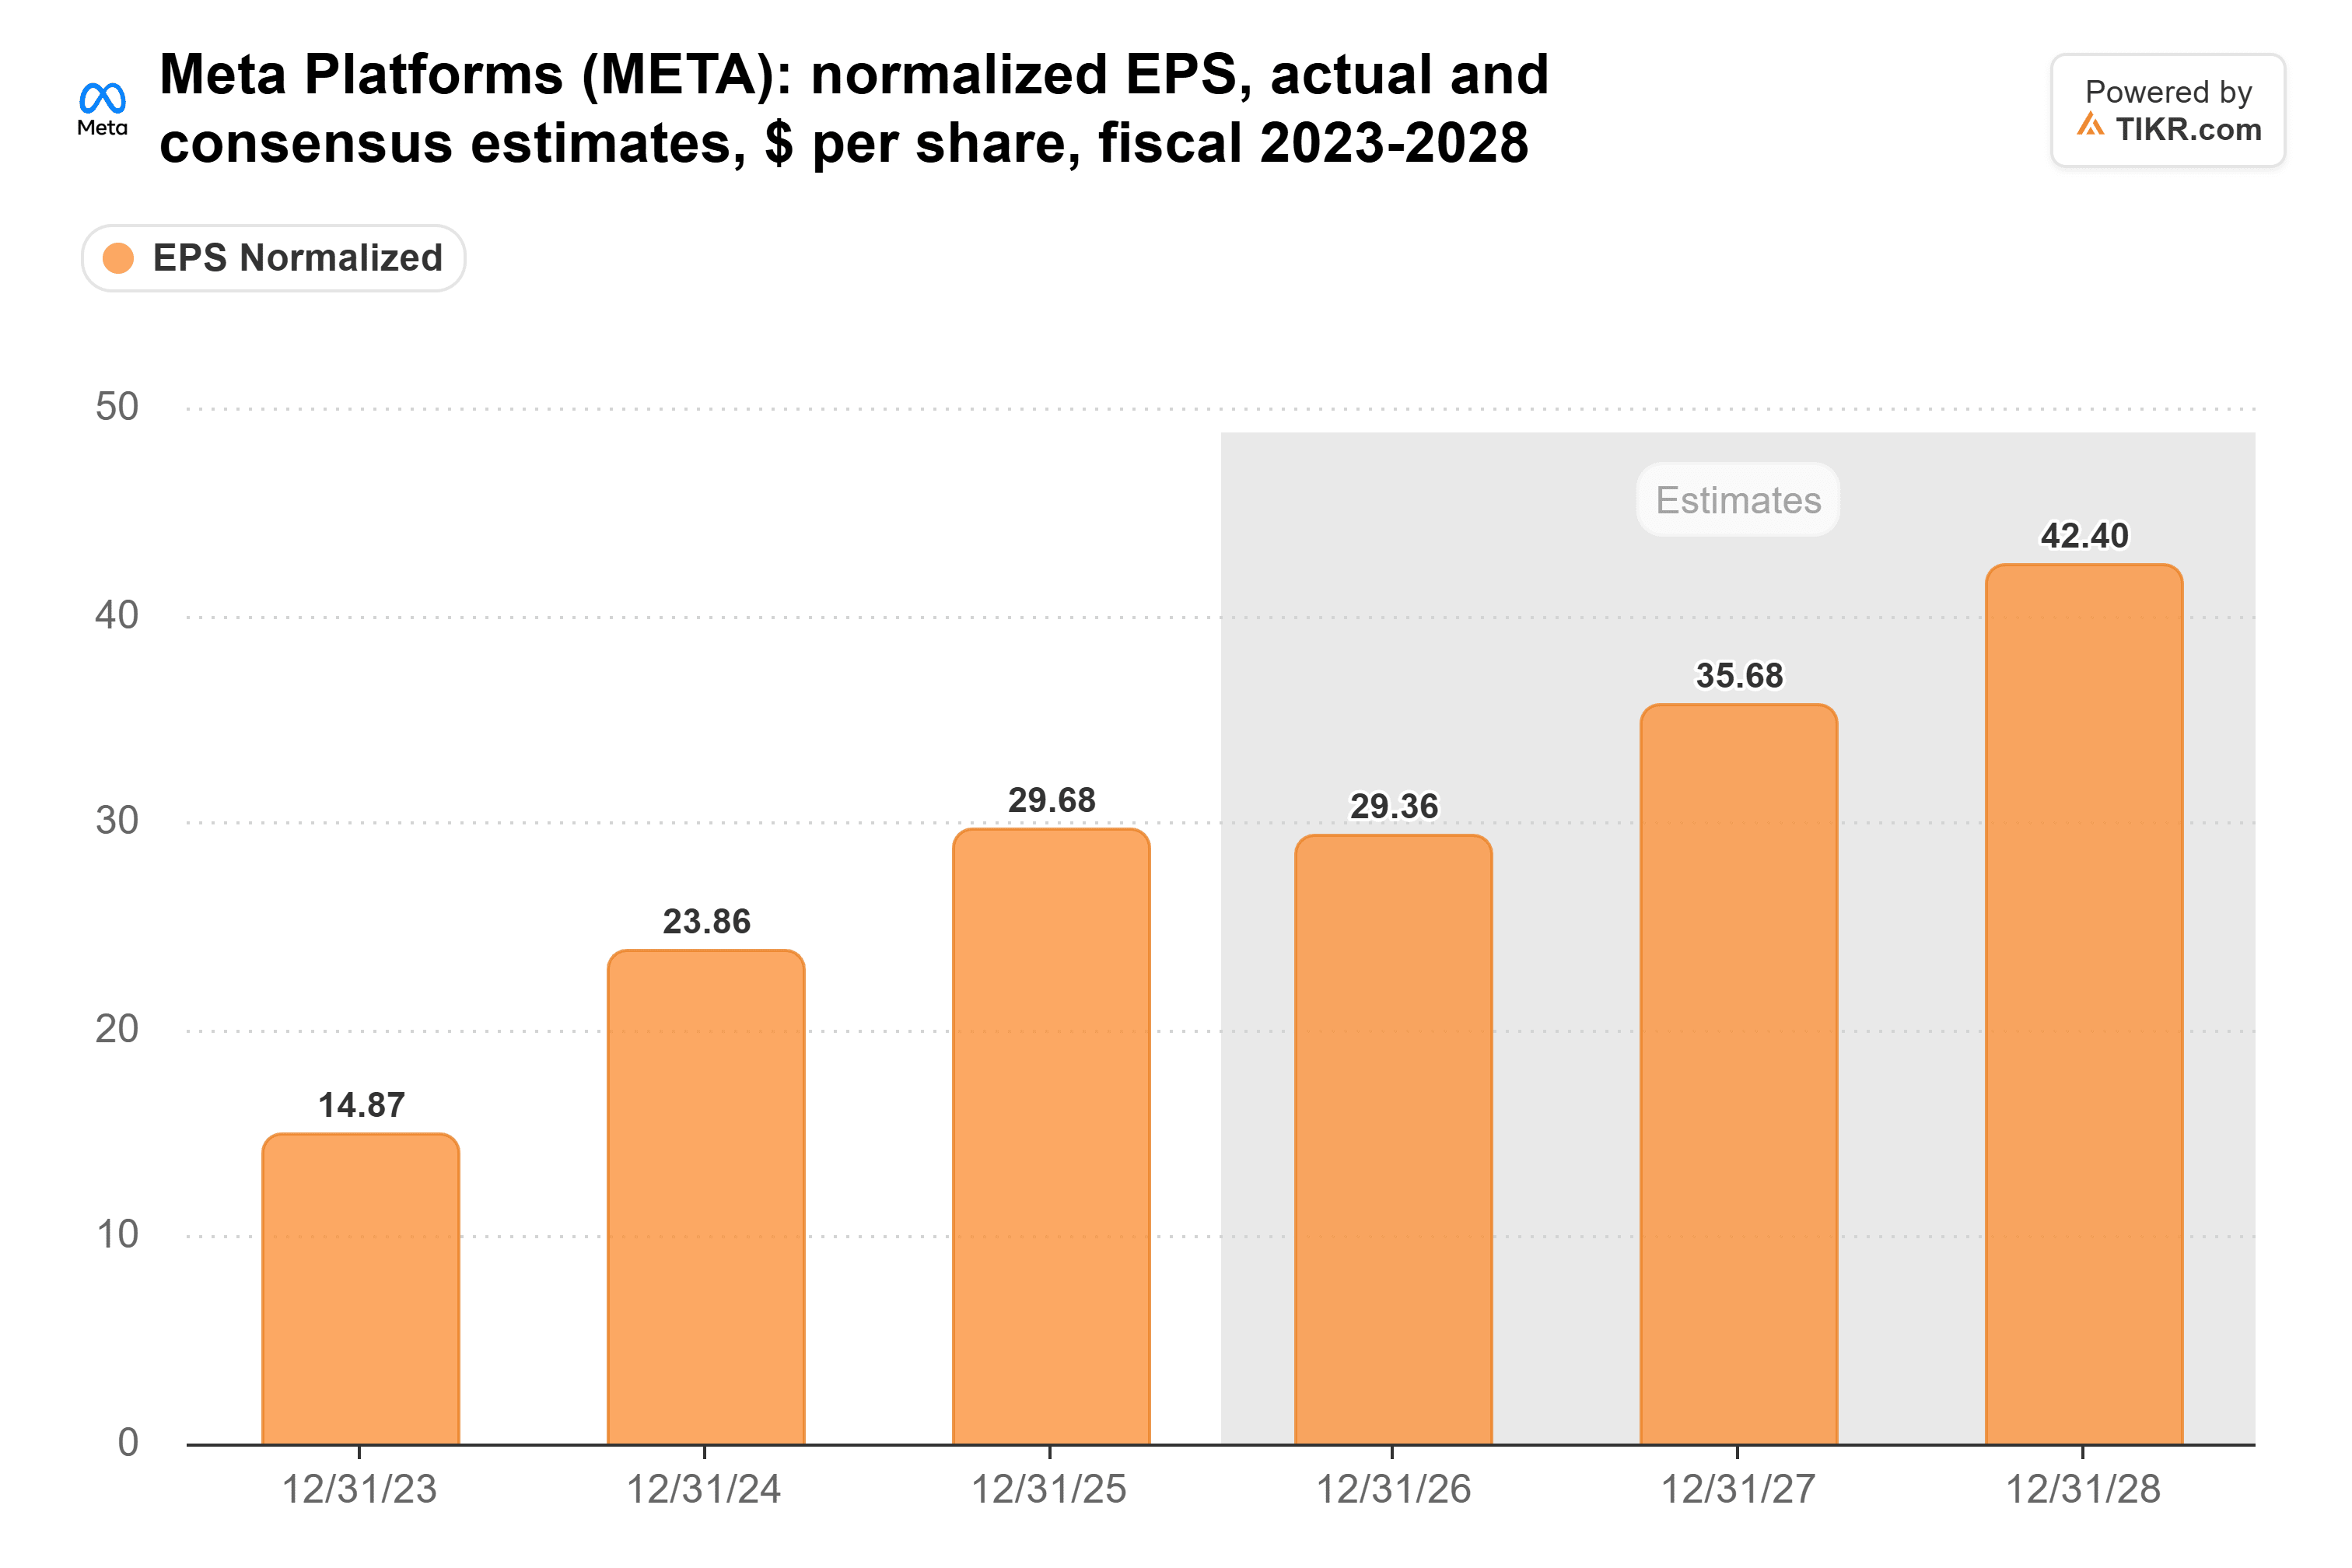
Consensus has Meta’s normalized EPS going from $29.68 in 2025 to $35.68 in 2027 and $42.40 in 2028, after a roughly flat 2026:
Prices did more of the lifting than volume last quarter: price per ad rose 14% while impressions rose 10%. Management says upgrades to its ad-ranking models are behind better conversions, and those models run on the same compute Meta is spending so heavily to build, so the AI build is already paying off inside the ad business. Meta guides fourth-quarter revenue to $73 billion to $76 billion, up 22% to 27%, while Pinterest guides to 8% to 12% growth for the same quarter.
The catch: the build now costs more than the cash
Operating cash flow doubled from $57.7 billion in 2021 to $116 billion in 2025, but capex grew faster, to $69.7 billion from $18.7 billion:
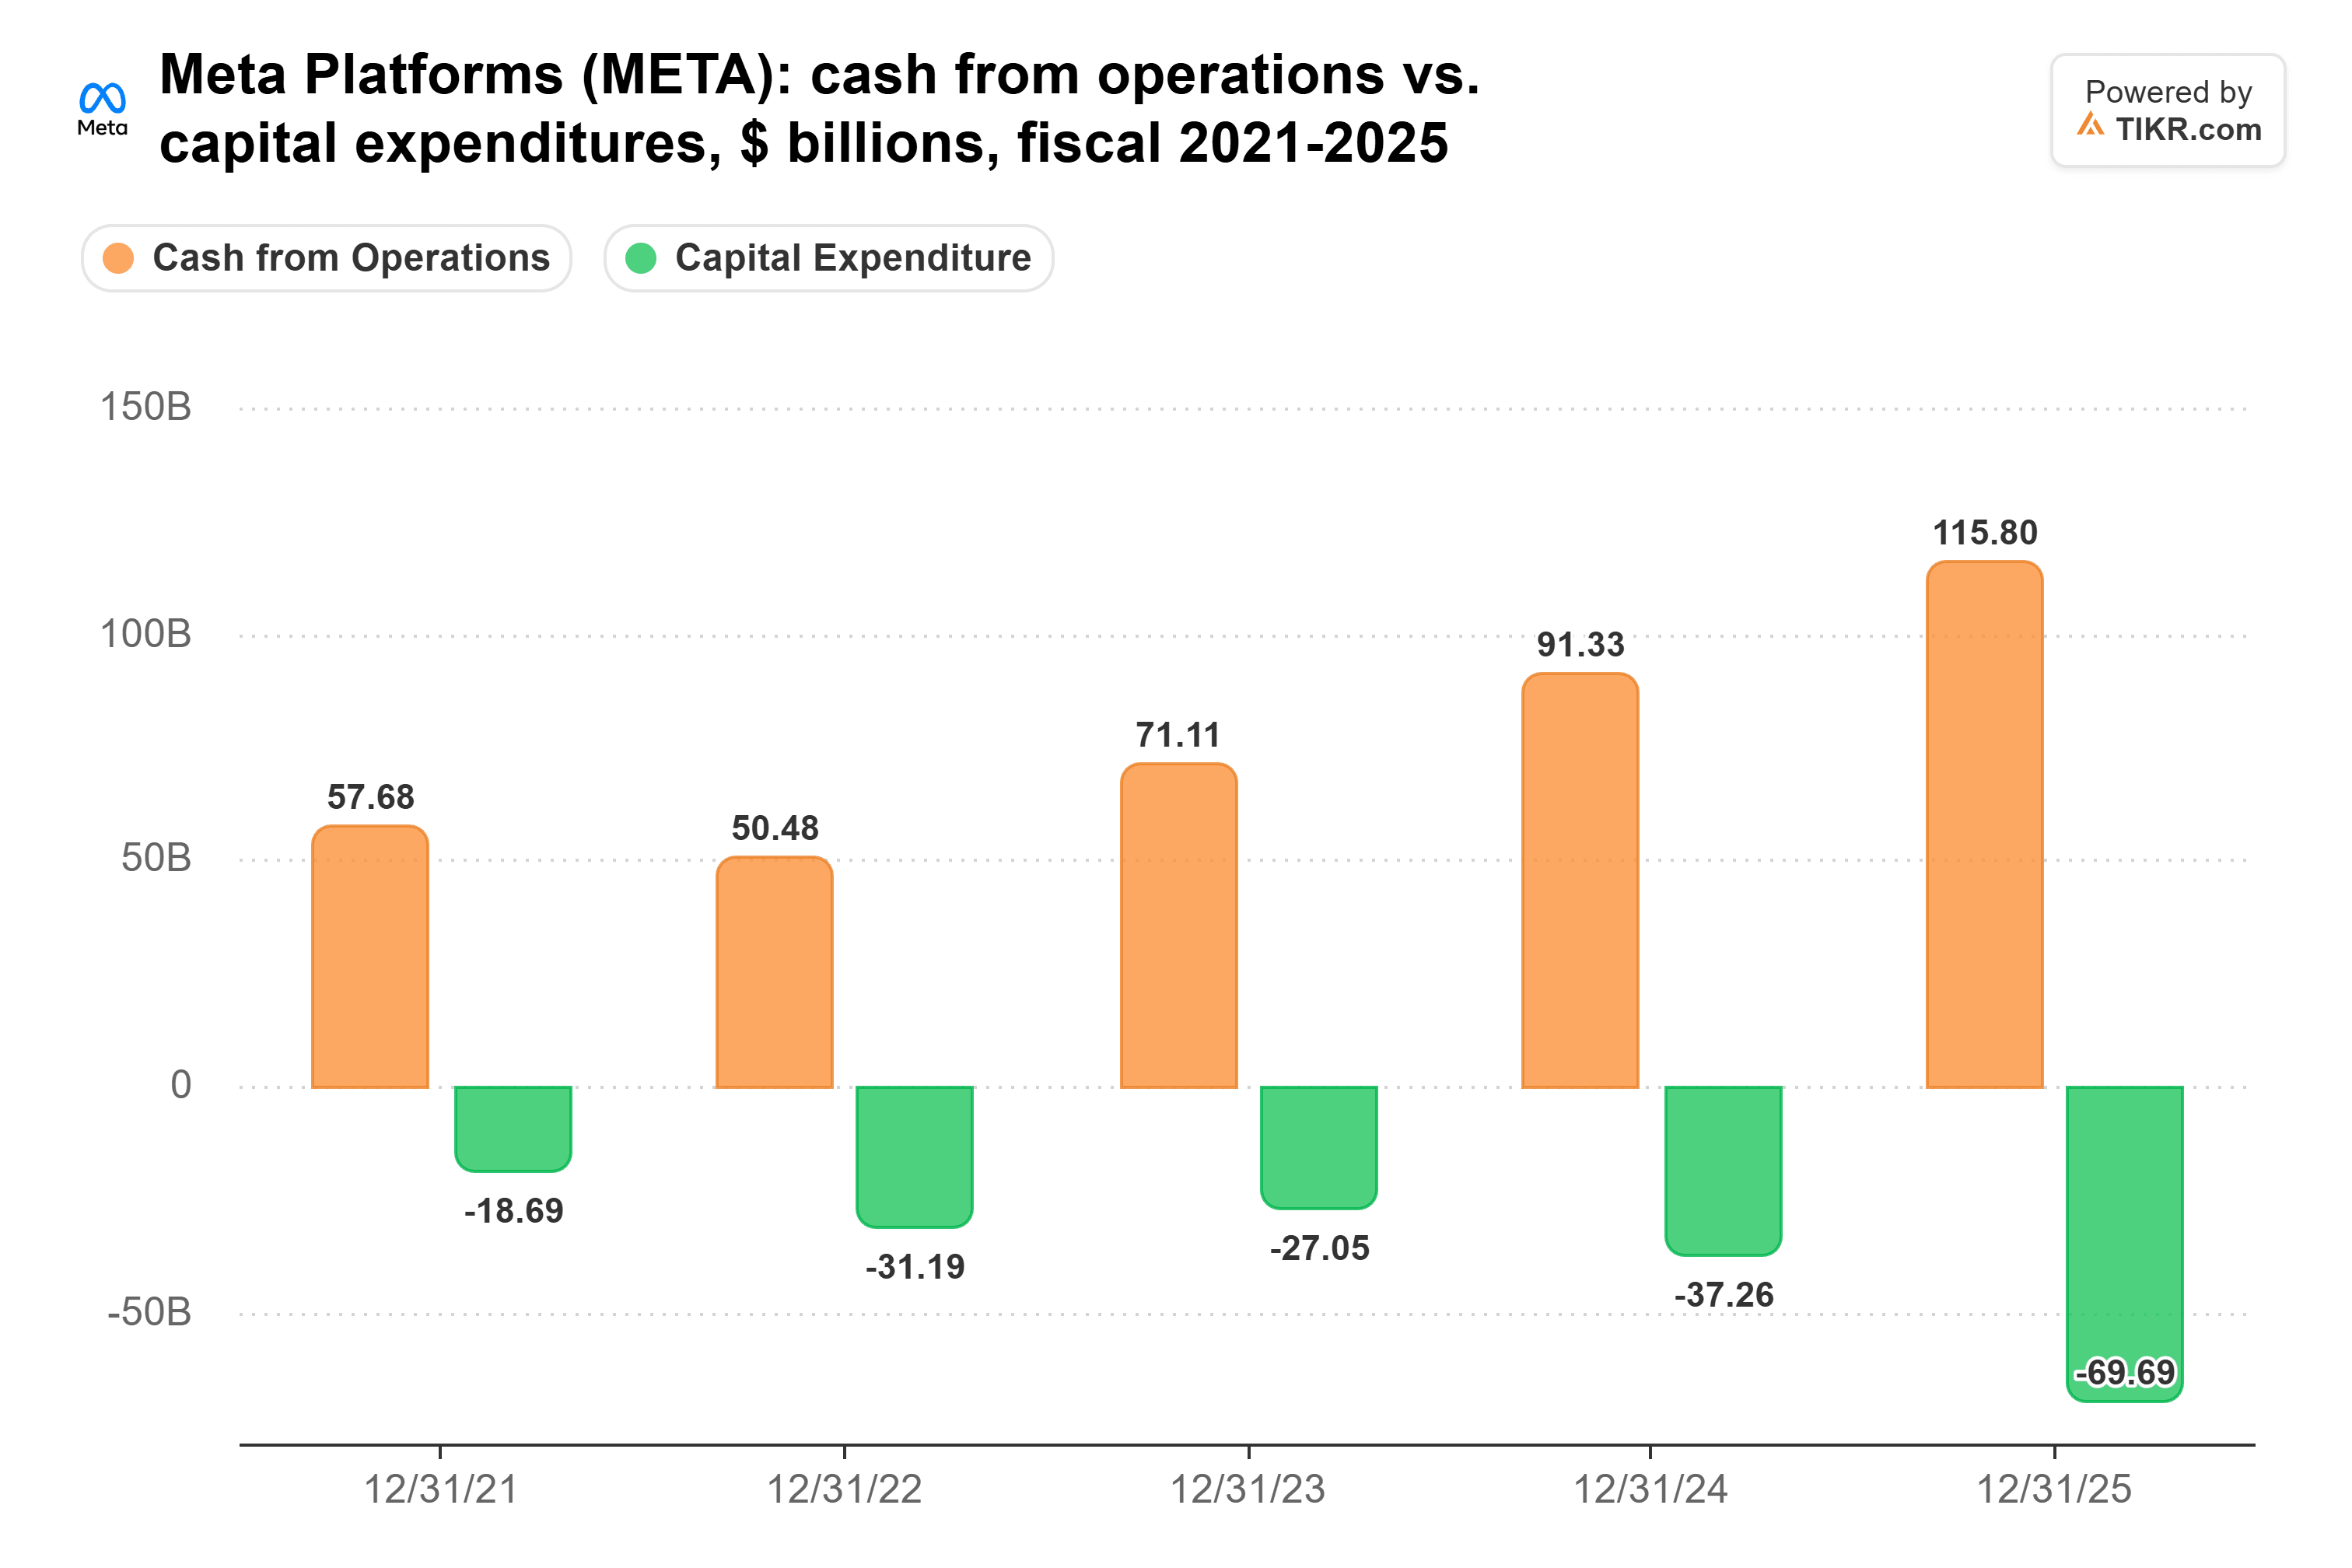
In the third quarter, capex of $34.9 billion, including finance-lease principal, topped operating cash flow of $32.8 billion, so free cash flow went negative. Management guides 2026 capex on the same basis to $135 billion to $145 billion. Analysts now see free cash flow bottoming at a $48 billion outflow in 2027.
Still, Meta has hit the brakes before. In 2023, it cut capex to $27.1 billion from $31.2 billion, and free cash flow more than doubled to $44.1 billion from $19.3 billion. This time, though, it has $454.5 billion of commitments it can’t cancel as of Sept. 30, per its latest 10-Q, so a cutback would take longer to show up in free cash flow.
Arista would feel it a lot sooner. Its third-quarter revenue jumped 58.5% to $3.66 billion, and investors pay about 34x forward earnings for that growth, so a Meta pullback would hit its stock much harder.
You’re not paying much for the hedge
As of the Nov. 18 close, Meta traded at about 19x forward earnings, below its five-year average of 21x and well off its 29x peak in February 2025:
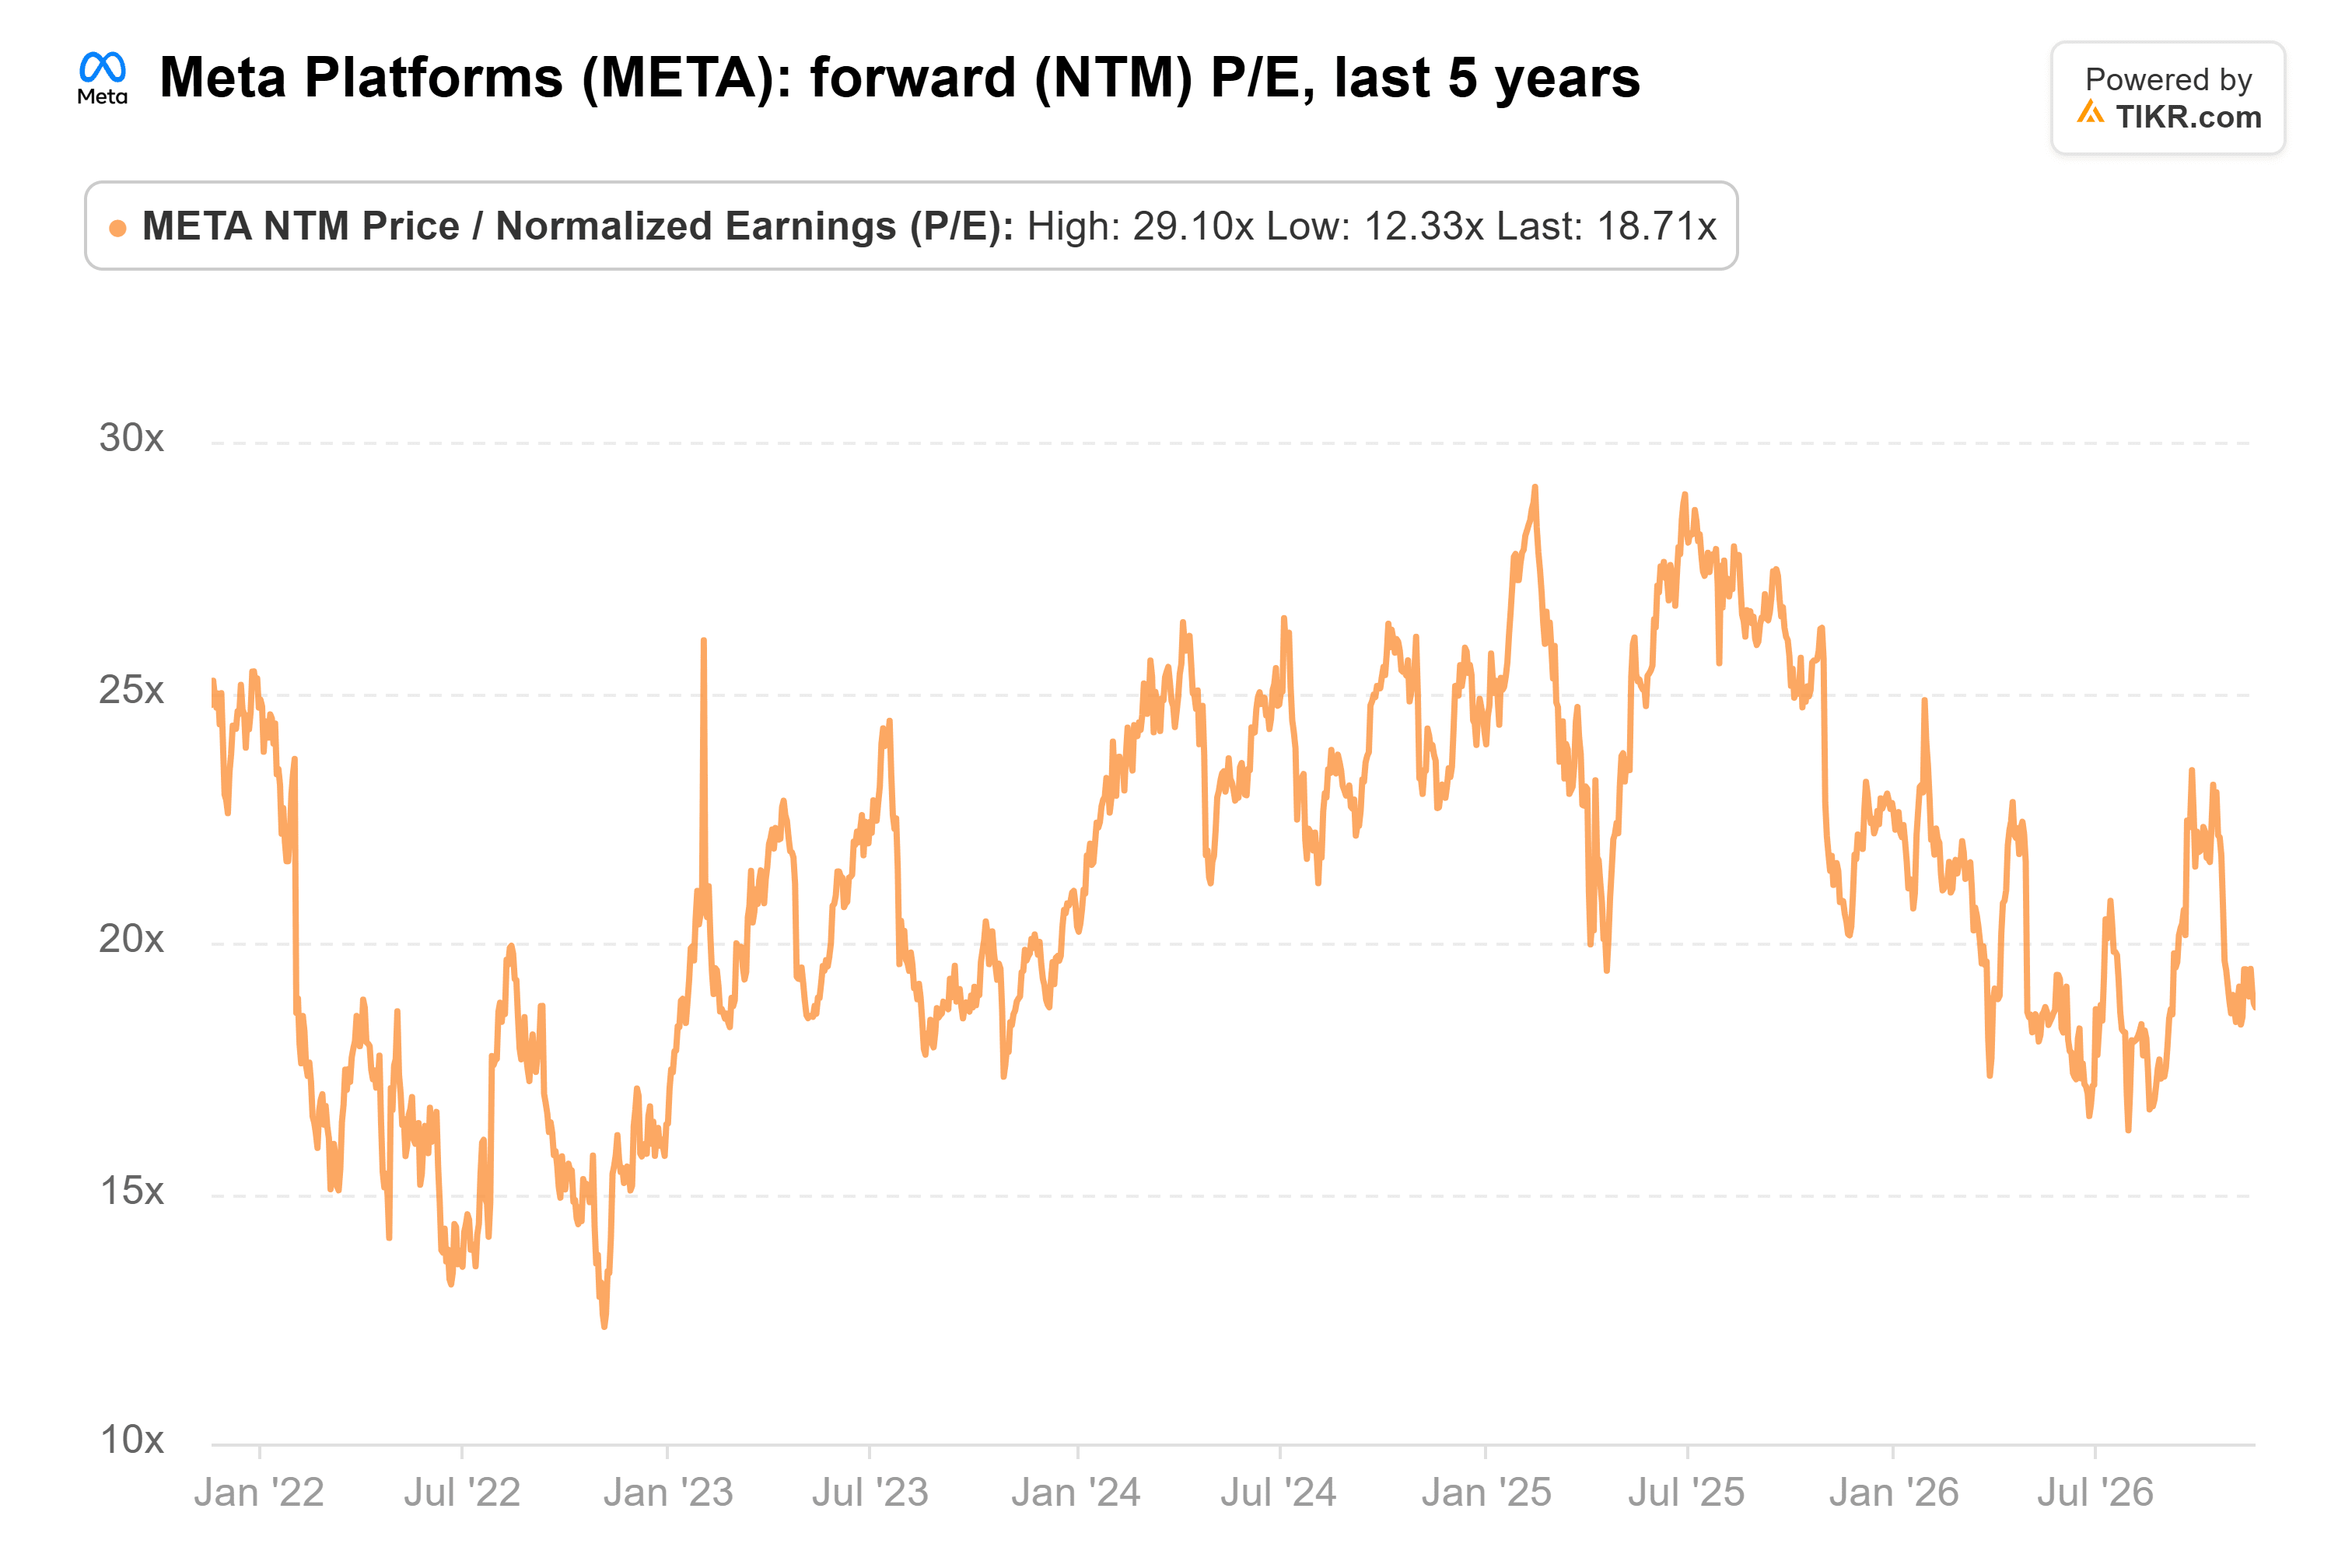
That’s a modest multiple for an ad business growing 26% with an AI bet on top, and a little over half what investors pay for Arista. Niles has it right: if the AI trade cracks, Meta can slow the build and lean on its ad business, which is more than Anthropic or Meta’s suppliers can do.
The test comes on the fourth-quarter call in late January. If revenue lands in the upper half of its guide, the ad engine is holding up. If the 2027 capex plan comes in well above the roughly $210 billion analysts expect, the cushion gets thinner.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!