Key Takeaways
- Pinterest stock is up 20% in the past month through Monday’s close, while the S&P 500 rose less than 1% and Snap gained 13%.
- The stock bounced off a September low near the price Pinterest paid to buy back its own shares, and two social-media rallies carried it higher in October.
- Even after the run, Pinterest trades at 10x forward earnings, against a five-year average of 24x.
- Third-quarter results in early November will be the first with Amazon veteran James Dibbo as CFO, and they need to show US and Canada growth holding near Q2’s 18%.
Pinterest (PINS) stock is up 20% in the past month (through Monday’s close), while the S&P 500 rose 0.6% and the Nasdaq 100 slipped 0.4%. Snap (SNAP) gained 13% over the same stretch.
The strange part? Pinterest hasn’t put out a new quarterly number since early August.
A September low, then an October run
The month started from a rough spot. Pinterest dropped 9% on Sept. 9 after CEO Bill Ready warned at a Goldman Sachs conference that the international business was under pressure, from new EU limits on Asia-based cross-border sellers and from a reshuffle of how it sells overseas. The slide went on through a 5% drop on Sept. 22, with no news behind it.
But it ran out of steam at an interesting level. Pinterest spent more than $2 billion buying back its own stock this year through early August, at an average price of $18.17, and the shares bottomed in September just above that.
Then October did all the work: the stock climbed 20% from Sept. 30 to Oct. 15. Snap jumped 7% on Oct. 9 as social-media stocks rallied together, and Pinterest rose 4.2%. The group rallied again on Oct. 13, and Pinterest added 4.4%. Two days later it gained another 4.4% as UBS kept its Buy rating and $33 target.
TIKR tracks 39 analysts on Pinterest. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Pinterest, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Pinterest’s Analyst Ratings
Amazon’s ad money man takes over
The only real company news came on Oct. 5, after the close, when Pinterest named James Dibbo CFO, starting Oct. 26. At Amazon (AMZN), Dibbo ran finance for Amazon Ads and Prime Video, among other businesses. The stock barely reacted, rising about 1% after hours.
I think the hire matters more than that. Ready has been blunt about where Pinterest falls short: “We 5x the number of clicks to advertisers over that last 3-year period, but we certainly didn’t 5x the revenue,” he said on the second-quarter call.
A finance chief who helped run Amazon’s ad business is a sensible pick to help close that gap.
Still cheap after the bounce
A 20% month sounds like a lot, until you see the starting point. Pinterest’s forward P/E is 10.3x today. That’s up from a five-year low of 8.4x on Sept. 17, but far below its five-year average of 24x.

Wall Street hasn’t chased the move, either. Holds now lead the ratings, 19 against 17 Buys and 2 Outperforms, after 29 Buys and 6 Holds a year ago. And the consensus target has stayed at about $29 the whole time.

That’s still about 30% above Monday’s close, though it’s down from $44 a year ago. Plus: the stock now sits just under the roughly $22.72 conversion price on Elliott’s $1 billion of convertible notes.
November has to earn it
Third-quarter results are due in early November, the first report with Dibbo as CFO. Pinterest guided to revenue of $1.19 billion to $1.21 billion, or 13% to 15% growth. That follows 18% in Q2, when US and Canada growth sped up five points to 18%.
Analysts still expect revenue to grow 16% this year, to $4.91 billion, and another 13% in 2027.
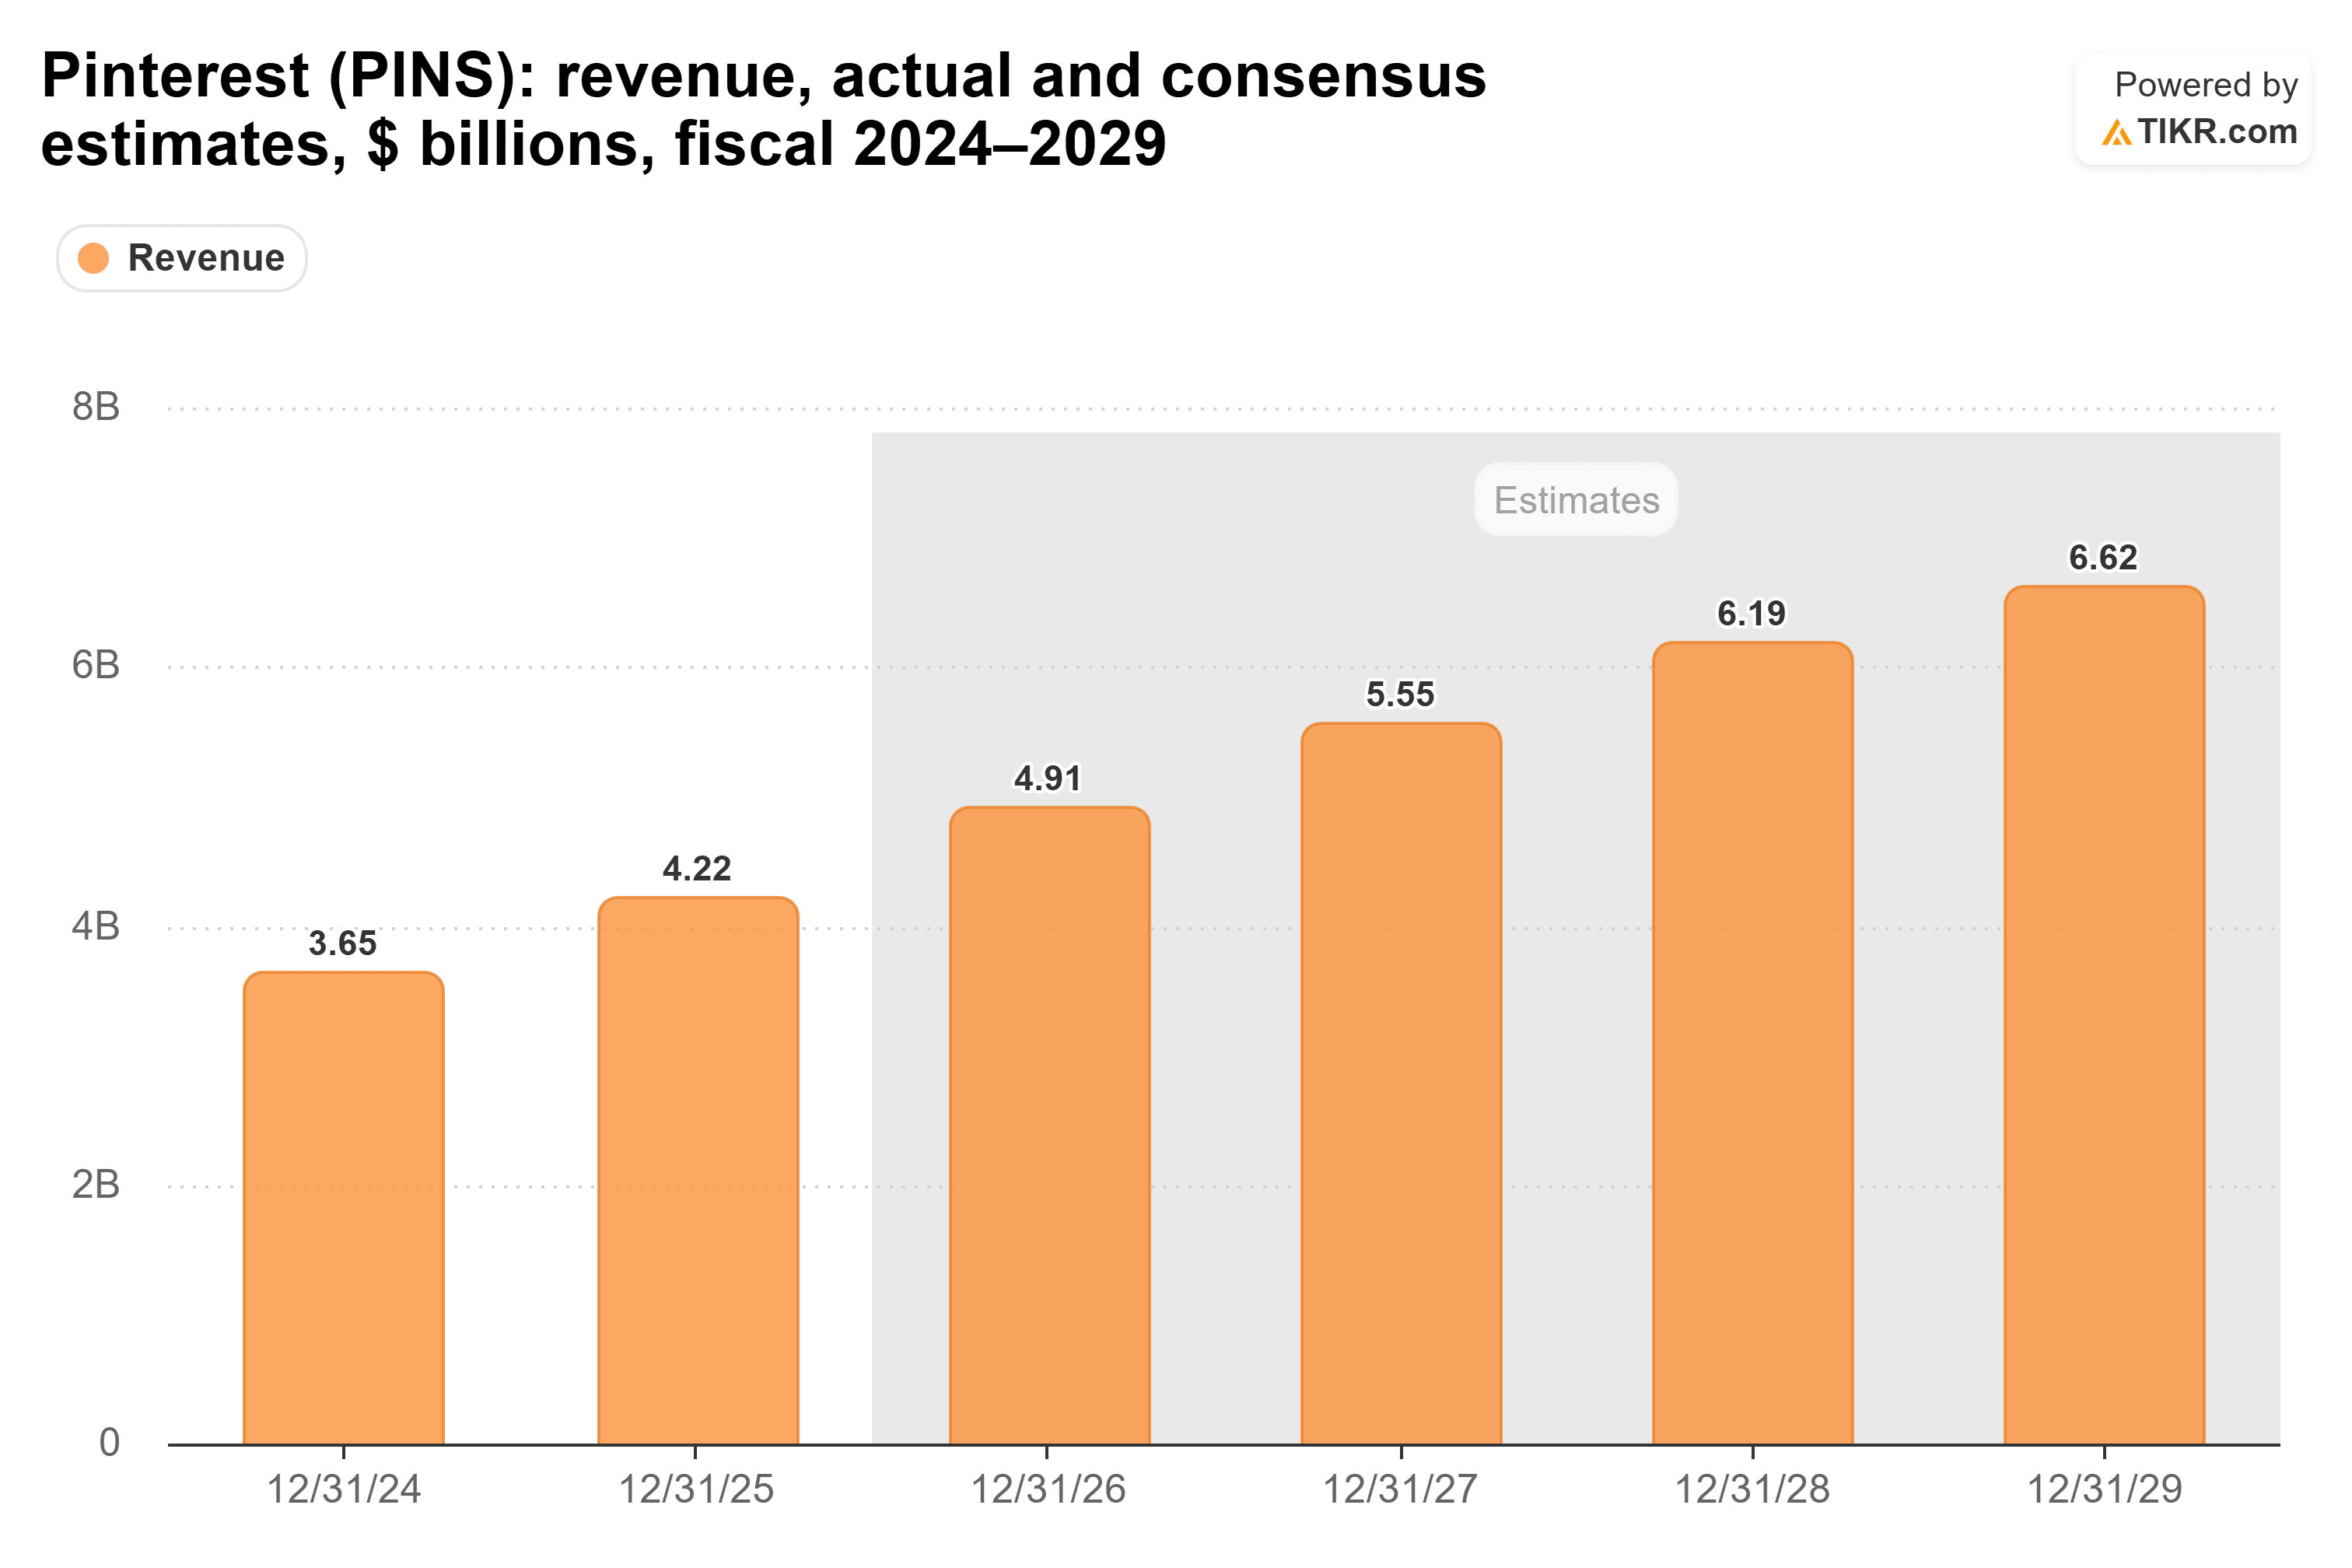
Nothing in October’s news should move those estimates, so it’s up to the November report.
The risk is overseas. The international business has more than 80% of Pinterest’s users but brings in only about a fifth of its revenue, and the reset there could drag on.
My take: Pinterest is still a buy at 10x forward earnings. If US and Canada growth holds near 18%, this multiple has a lot of room to rise. Of course, a miss on the guide would send the stock right back toward that $18 buyback price.
So what is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!