Key Takeaways
- Cloudflare stock fell 15% in the past week (through Monday’s close), while the Nasdaq 100 fell 3.7%.
- The company put out no bad news, and the drop looks like a better entry point into a business that’s still growing fast.
- A sell-off in AI and richly valued software stocks hit Cloudflare, Palo Alto Networks and CrowdStrike, and at about 200x forward earnings Cloudflare is still expensive.
- Third-quarter results come after the close on Nov. 5, and the consensus price target sits about 15% above Monday’s close.
Cloudflare (NET) stock is down 15% in the past week (through Monday’s close). That leaves it nearly 20% below the record high it hit on Oct. 6. The Nasdaq 100 lost 3.7% over the same stretch.
Even so, Cloudflare is still up 51% in 2026.
A bad week for anything priced for AI
Three sessions did almost all the damage: Cloudflare fell 6.7% on Oct. 14, 2.5% on Oct. 15 and 6.3% on Oct. 16, as inflation worries and rising bond yields sent investors out of AI names and richly valued software.
Palo Alto Networks (PANW) fell 14.1% and CrowdStrike (CRWD) 13.3% over the same week. Cloudflare fell more than either Palo Alto or CrowdStrike, and it had the most to lose. At about 200x forward earnings, most of what buyers pay for sits years out, and higher yields make those years worth less today.
The company gave nobody a reason to sell
Cloudflare agreed to buy Deno to improve its Workers programming model. On Monday it also expanded the partner lineup for Cloudflare OS, its AI workspace.
Analysts kept raising their targets, too: BTIG, Oppenheimer, Barclays and TD Cowen lifted theirs between Oct. 6 and Oct. 13, to between $375 and $430.
As SaaStr founder Jason Lemkin put it on the 20VC podcast on Oct. 15: “They beat the quarter. They’ve accelerated growth even more.” Second-quarter revenue rose 36% to $696.1 million.
Nov. 5 is the next test
Cloudflare reports third-quarter results after the close on Thursday, Nov. 5. Management guided for $736.0 million to $737.0 million of revenue, and Oppenheimer expects Cloudflare to beat that as more customers adopt its security products.
Analysts expect revenue to grow 32% this year, to $2.87 billion, and another 29% in 2027.
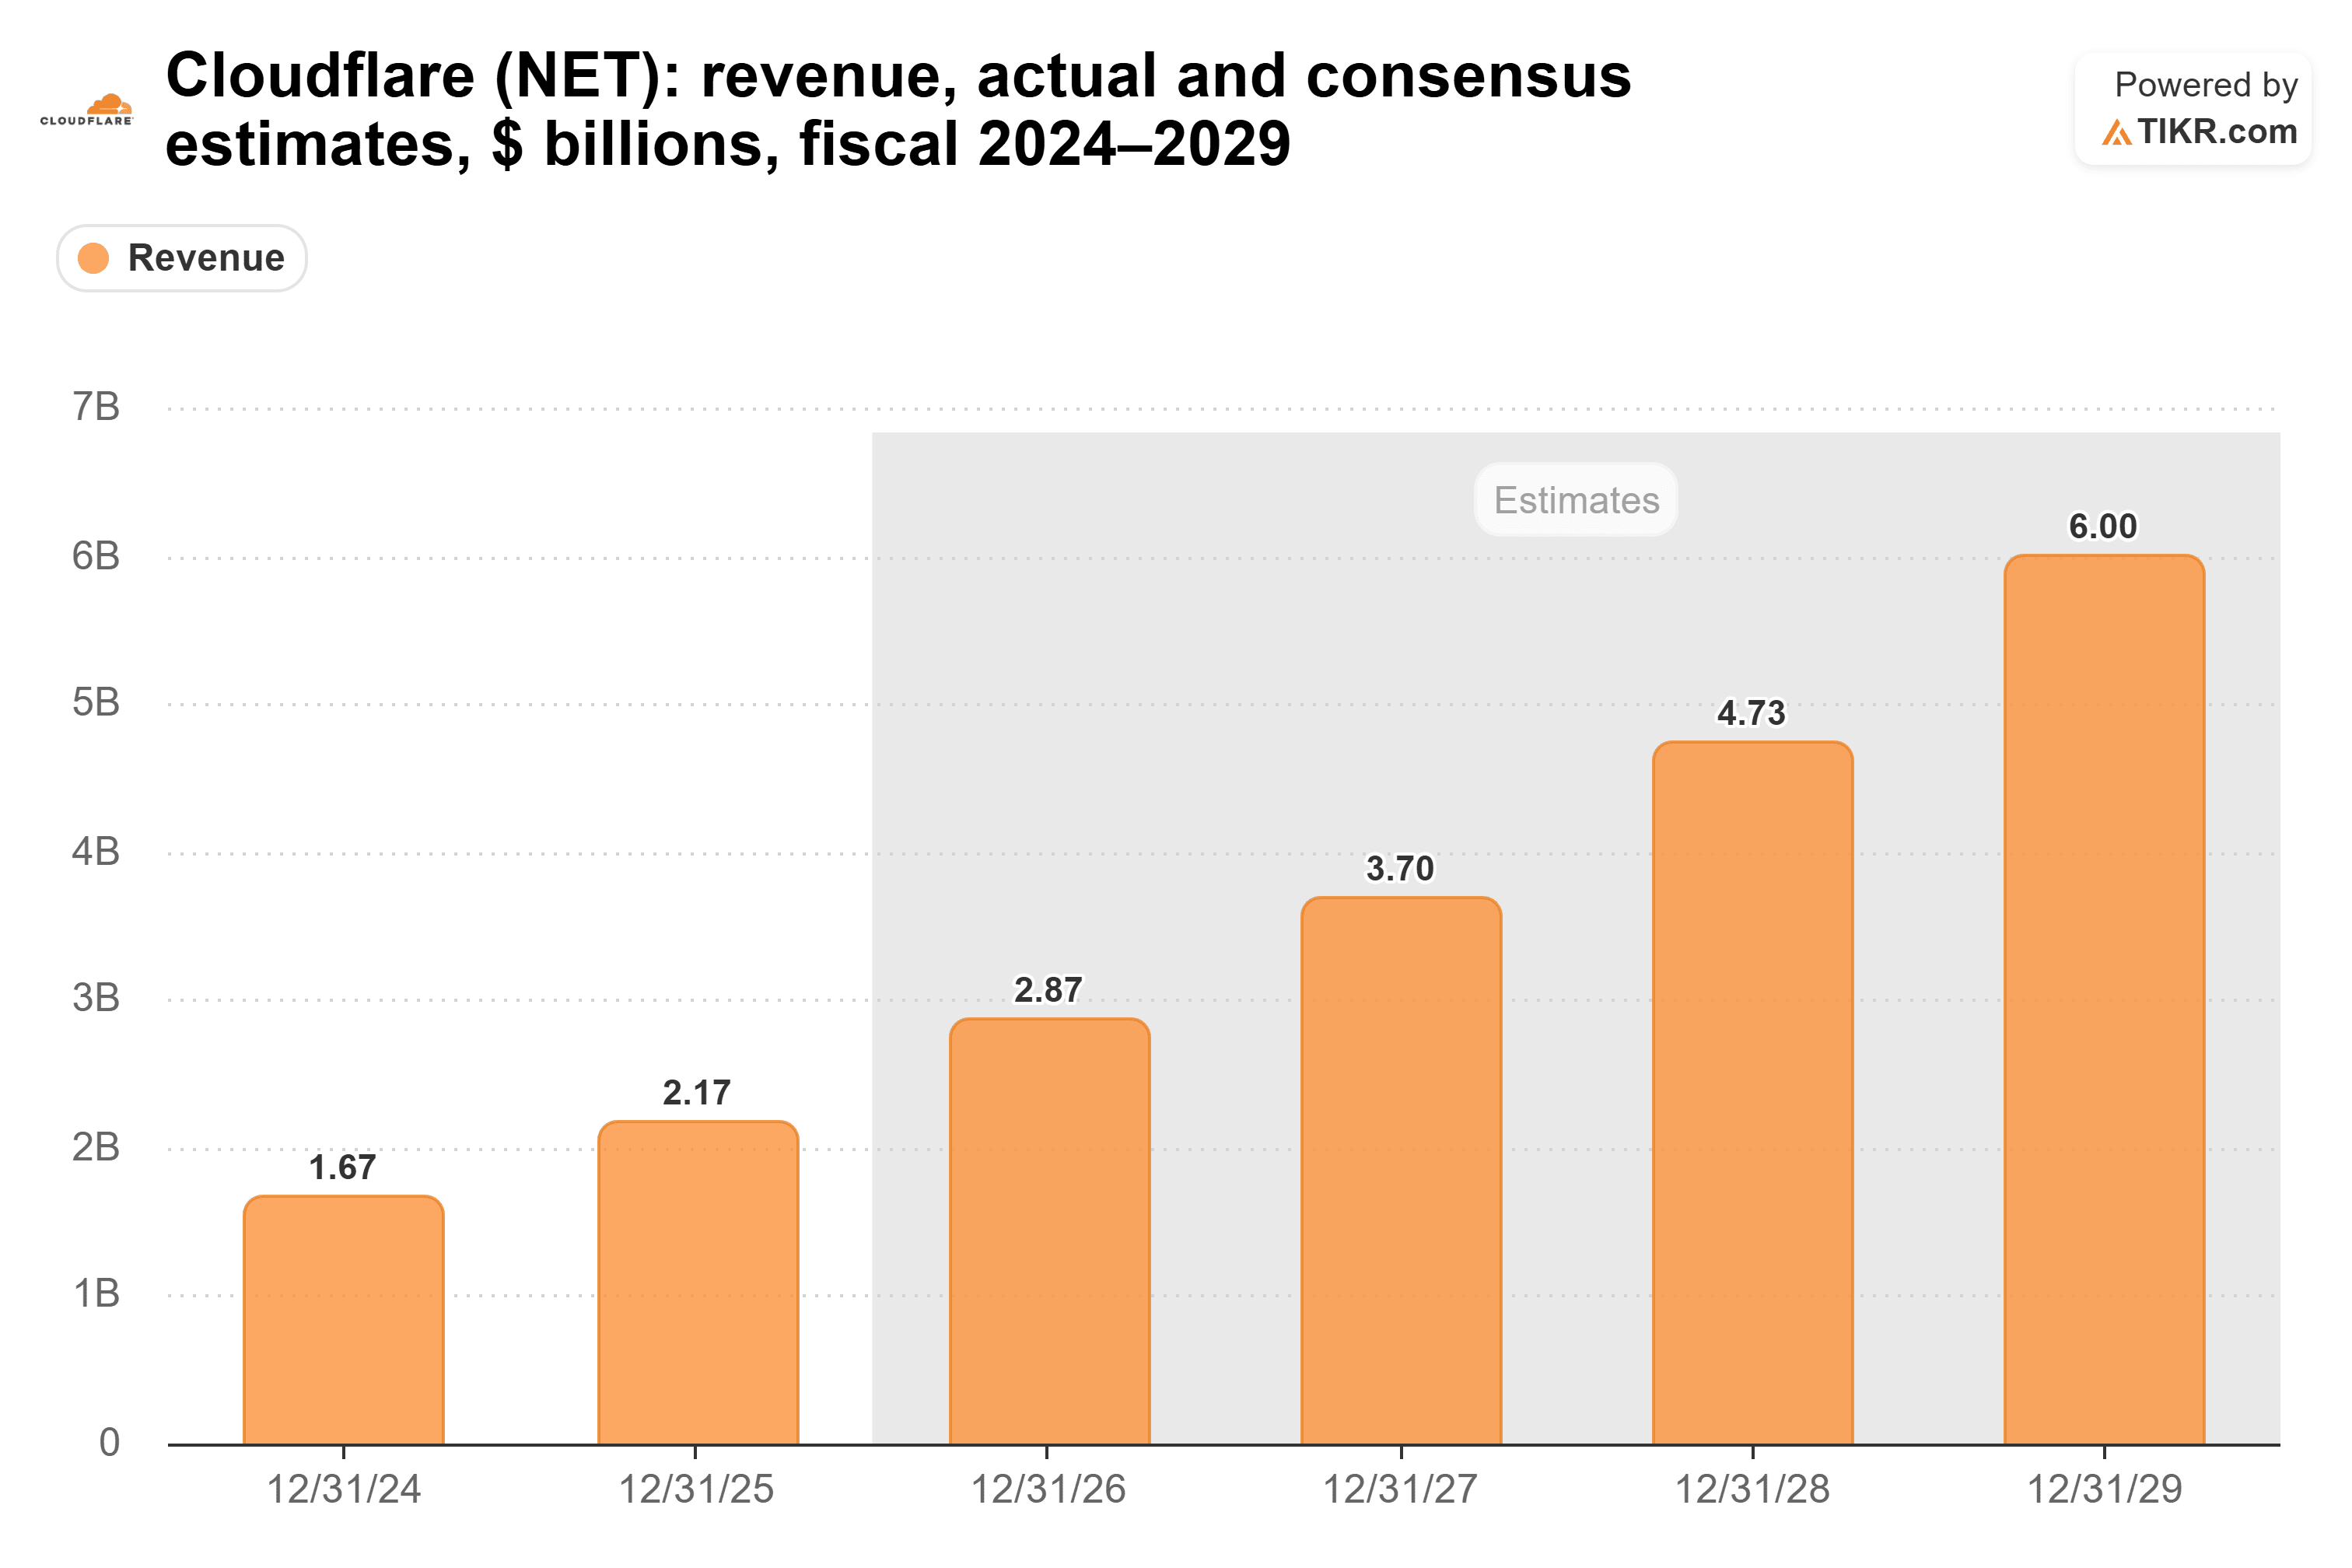
That 2026 estimate is already at the top of management’s full-year range, so Cloudflare needs a beat on Nov. 5.
Cheaper, but still not cheap
At about 200x forward earnings, Cloudflare is still expensive. But the Street’s consensus target kept climbing into the drop.

At $343, the target sits about 15% above Monday’s close.
My take: nothing about the business got worse this week, and buyers can now get it nearly 20% below its high. I’d start a position ahead of Nov. 5.
The risk is another leg of the AI sell-off, or a third quarter that only matches guidance. At this multiple, that could send the stock lower still.
So what is Cloudflare stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cloudflare could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!