Key Takeaways
- Palestra Capital Management, a firm that manages $5.44 billion, bought Amazon (AMZN), Lam Research (LRCX) and Advanced Micro Devices (AMD) in the Q2, according to its 13F for the quarter ended June 30.
- Since June 30, Amazon is up 9%, while AMD is down 23% and Lam Research is down 54% as chip stocks sold off.
- Analysts still see big upside in all three, from 26% for Amazon to 82% for Lam Research.
- Amazon looks like the best buy of the three: it trades below its usual forward P/E while analysts keep raising its earnings estimates.
Funds have until Nov. 16 to file what they owned at the end of September. Until then, the latest look at Palestra Capital Management is its 13F for the quarter ended June 30, filed Aug. 14.
Its three biggest buys of that quarter have gone very different ways since.
The firm manages $5.44 billion in all, and its 13F held $2.95 billion of US stocks in 21 positions. It built Amazon into one of its biggest holdings and opened new positions in Lam Research and Advanced Micro Devices.
(A 13F shows only what a fund held on the last day of the quarter, so each move below runs from the June 30 price.)
Amazon is the one paying off
Palestra held 942,732 Amazon shares worth $225 million on June 30. That was 7.6% of its 13F holdings and its fourth-biggest position, after it raised its share count 465% in the quarter. The stock is up 9% since.
Investors have had reason to stay. Amazon Web Services (AWS) grew 39% in Q3, and its backlog reached $578 billion.
Analysts have raised their targets all year:
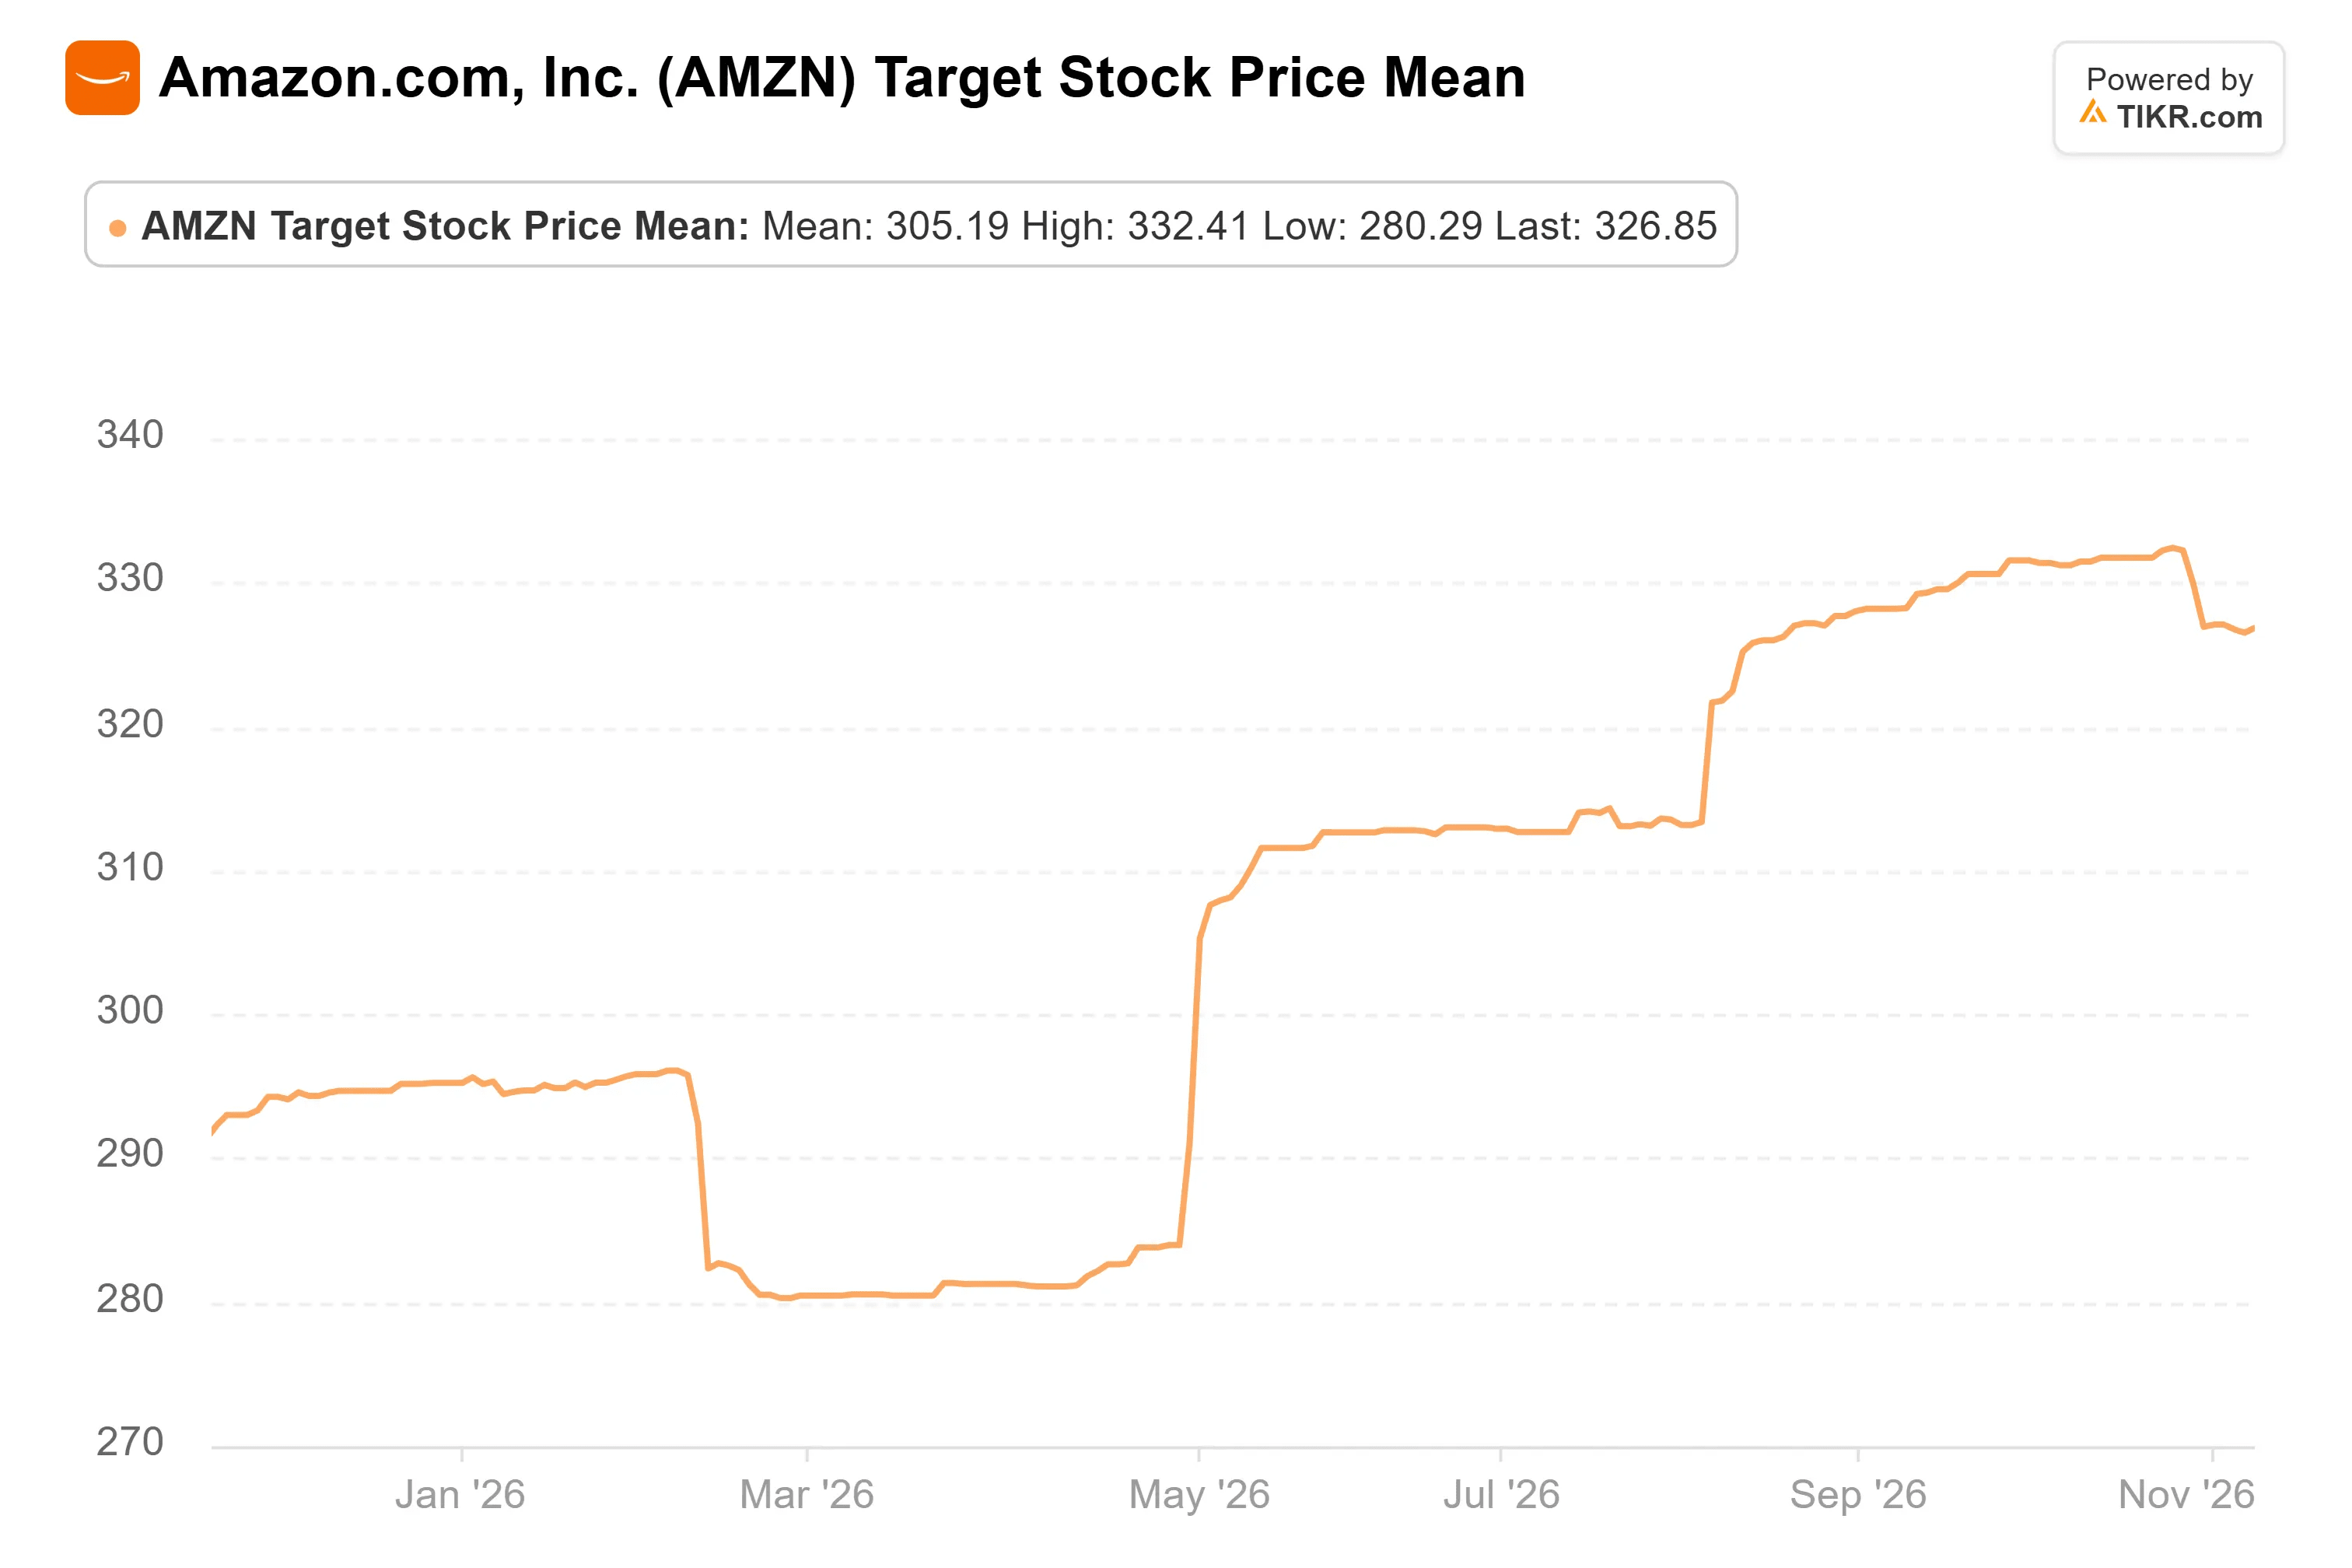
The consensus target has climbed from $292 a year ago to $327, 26% above Friday’s close.
TIKR tracks 63 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Lam Research has lost more than half its value since June
Lam was a new position: 388,886 shares worth $169 million on June 30, or 5.7% of Palestra’s 13F holdings. It’s down 54% since.
On Oct. 21, Lam reported record September-quarter revenue of $8.22 billion. But its December-quarter guide of $8.6 billion, plus or minus $400 million, was only about what analysts expected.
On the call, CFO Doug Bettinger said the guide “would have been a bit higher if not for some near-term supply chain constraints that we are actively managing.”
China made up 35% of Lam’s September-quarter revenue, and sales there are also expected to drop sharply in December. Then chip stocks sold off again after the midterms.
Analysts haven’t followed the stock’s trajectory.
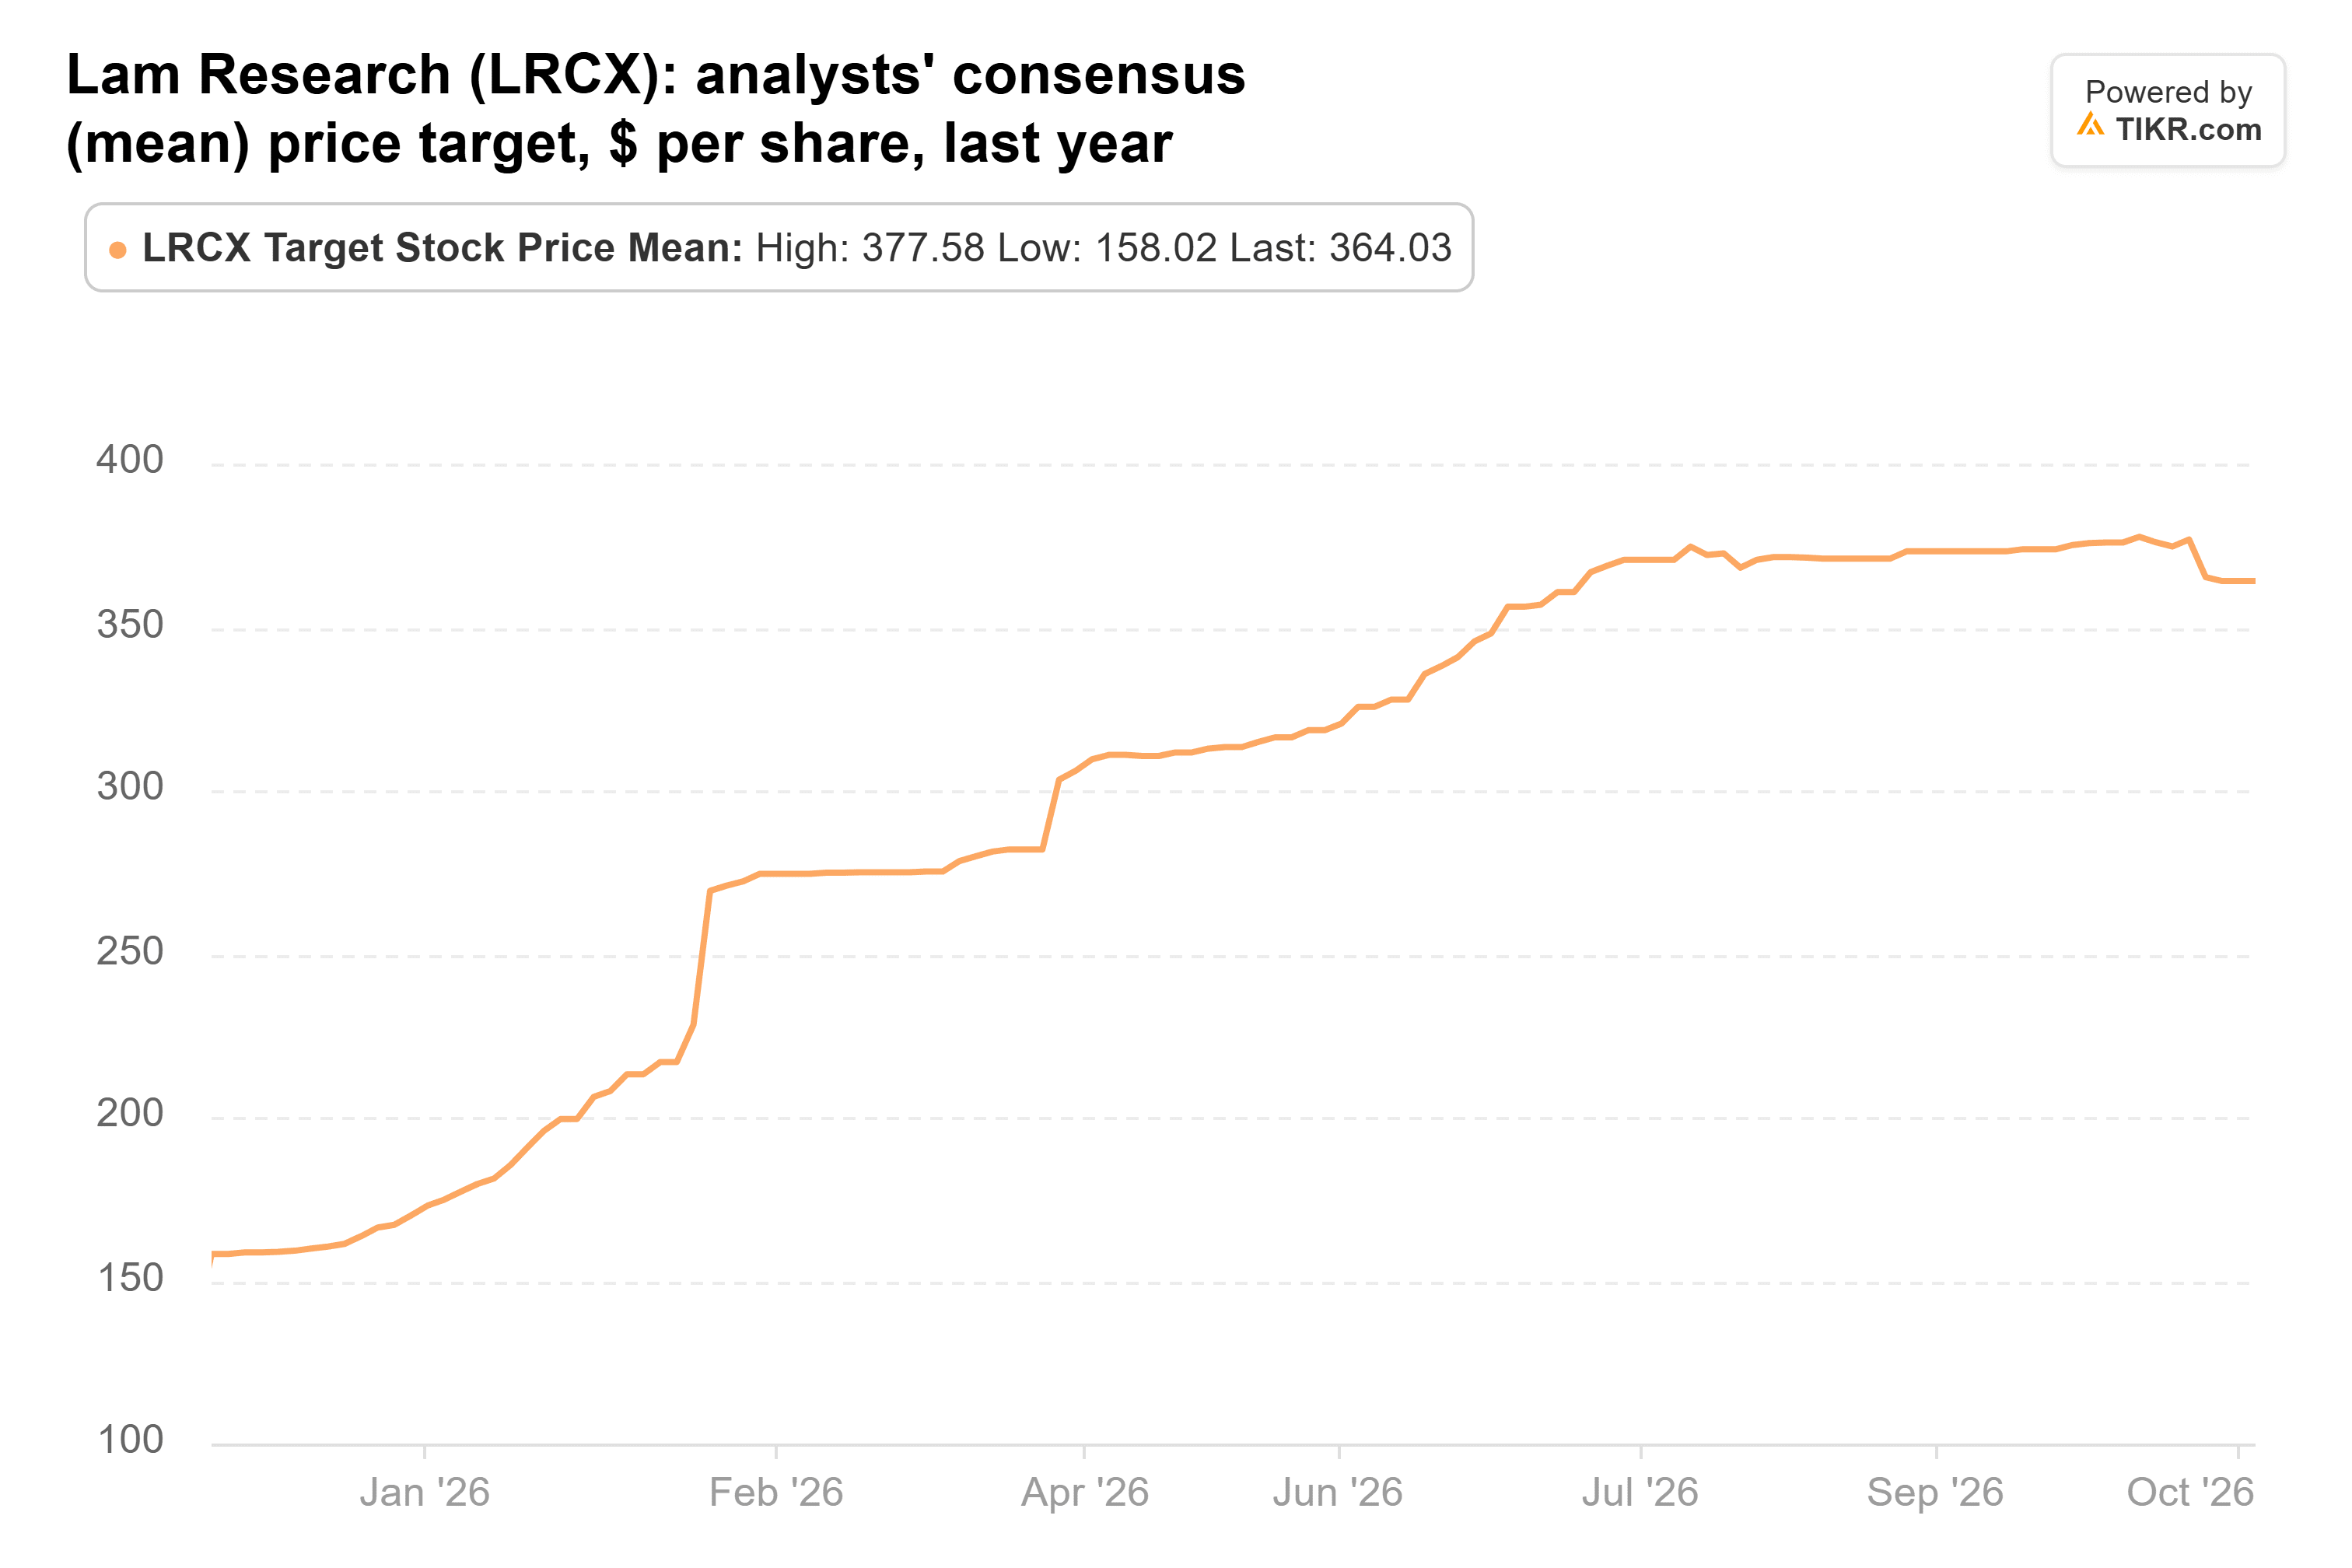
The consensus target more than doubled over the year, from $158 to $364, and has barely moved from its Oct. 18 peak of $378.
Even the lowest target, $255, sits well above Friday’s $200.44 close, and the average is 82% above it.
At about 20x forward earnings, Lam looks cheap. But I’d want to see December’s supply problems ease before trusting a target that hasn’t come down with the stock.
AMD is down 30% despite a strong quarter
AMD was a new position too: 237,958 shares worth $138 million on June 30, or 4.7% of Palestra’s 13F holdings.
It’s down 23% since then, even after a strong Nov. 3 report. Revenue was $13.38 billion, Data Center revenue rose 97% to $8.5 billion, and the Q4 guide was about $17 billion.
CEO Lisa Su said AMD now expects 2027 revenue to grow more than 80%.
Free cash flow fell to $554 million in the quarter, about 4% of revenue. AMD also took its first charge for the warrants it gave OpenAI and Meta, $1.1 billion, and CFO Jean Hu expects that charge to grow as the deals progress.
Analysts kept raising their targets.

The consensus target has climbed from $247 a year ago to $650, 45% above Friday’s close. At about 31x forward earnings, AMD trades below its 5-year average of 35x on TIKR.
Amazon is the one I’d buy
What sets Amazon apart is the price. It trades at about 25x forward earnings, under its 1-year average of 30x on TIKR and well below its 5-year average of 48x. Meanwhile, analysts raised their 2028 EPS estimate 24% over the year to Oct. 23.
Amazon guided to about $220 billion of capex this year, and analysts don’t expect its free cash flow to turn positive again until 2028. The cost of insuring its debt against default has risen about 50% since early August, per Bloomberg data.
Lam has the most upside on paper, and AMD just had the strongest quarter. But if I could only buy one of Palestra’s three right now, it’d be Amazon: AWS keeps growing faster, and the stock costs less than investors have usually paid for it.
Palestra’s 13F for the September quarter is due by Nov. 16. It will show whether the fund kept, added to, or sold all three positions by Sept. 30.
For Amazon, the bigger test is its 2027 capex outlook, due with Q4 results in early February.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!