Key Takeaways
- A fund with $4.51 billion in US stocks opened new stakes in CSX (CSX) and Entergy (ETR) in Q3 and grew its Mastercard stake by 1,884%.
- Analysts’ average price targets sit 9% to 10% above each stock’s last close.
- Mastercard (MA) is already up 20% since Sept. 30, and its forward multiple has climbed back toward its long-run average.
- CSX looks like the best buy of the three, with record revenue, rising price targets and the lowest forward multiple.
Alphinity Investment Management, a fund with $4.51 billion in US stocks, made three big moves in Q3, according to its 13F for the quarter ended Sept. 30, filed on Nov. 2.
It opened new stakes in CSX and Entergy, and it held a much bigger stake in Mastercard than three months earlier.
All three stocks have climbed since the quarter ended, and Wall Street still sees about 9% to 10% upside in each.
CSX just had a record quarter
CSX was the fund’s biggest new position, at 3.72 million shares worth $173 million on Sept. 30, or 3.8% of its US stocks.
The stock is up 6% since the quarter ended, helped by a 7% jump on its Q3 report in October.
Revenue hit a record $4.02 billion, up 12% on higher fuel surcharges, volume, and pricing, and EPS rose 30% to $0.57 from last year’s adjusted $0.44. The operating margin came in at 39.1%.
Analysts have raised their sights all year, and the consensus target climbed from $39.29 a year ago to $53.81 at the end of October:
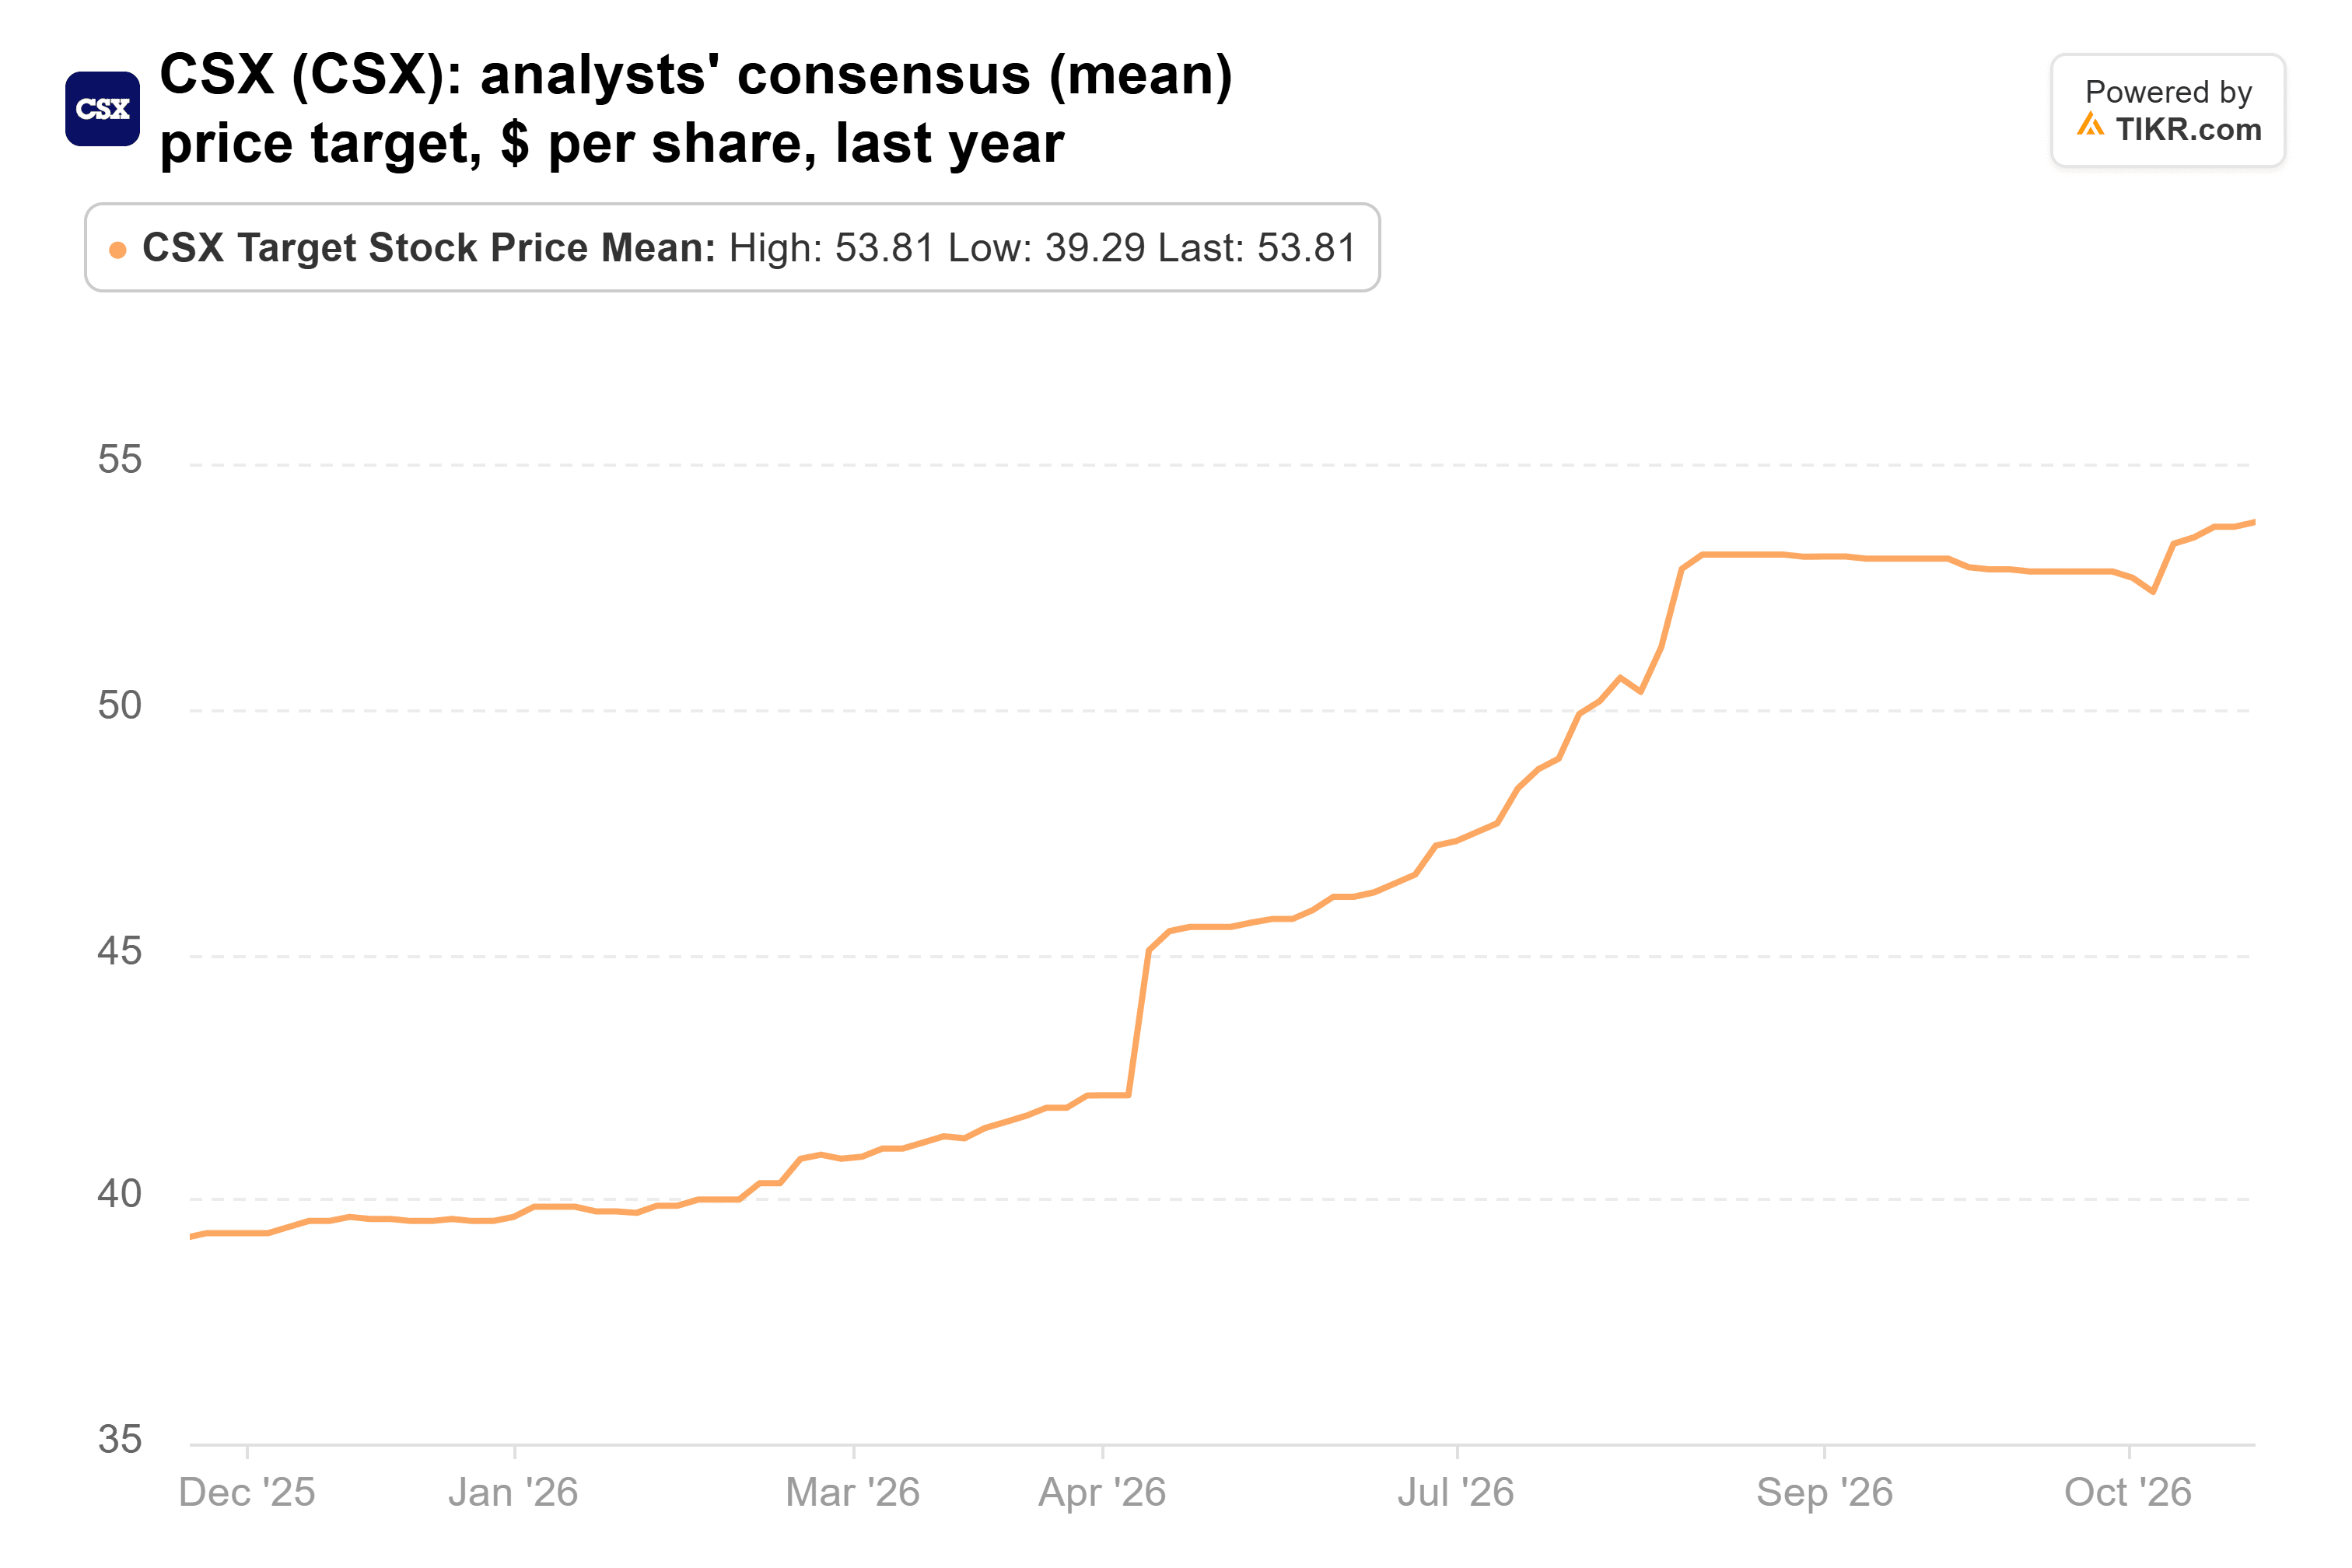
That’s 10% above Friday’s $49.12 close, with targets from 26 analysts running from $32 to $60. The stock trades at about 21x forward earnings, still 8% below its July high.
TIKR tracks 26 analysts on CSX. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CSX, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CSX’s Analyst Ratings
Entergy’s targets have cooled since July
Entergy was the second-biggest new stake, at 1.36 million shares worth $135 million on Sept. 30, or 3.0% of the fund’s US stocks. It’s up 11% since the quarter ended.
On Nov. 2, Entergy reported Q3 adjusted EPS of $1.98, up from $1.53 a year earlier. It also narrowed its 2026 adjusted EPS guidance to $4.35-$4.45 and raised its quarterly dividend 6% to $0.68. Higher interest expense and more shares outstanding held back the per-share gains.
Analysts were most bullish in the summer. The consensus target rose from $103.11 a year ago to $124.31 in late July, then slipped to $120.38:
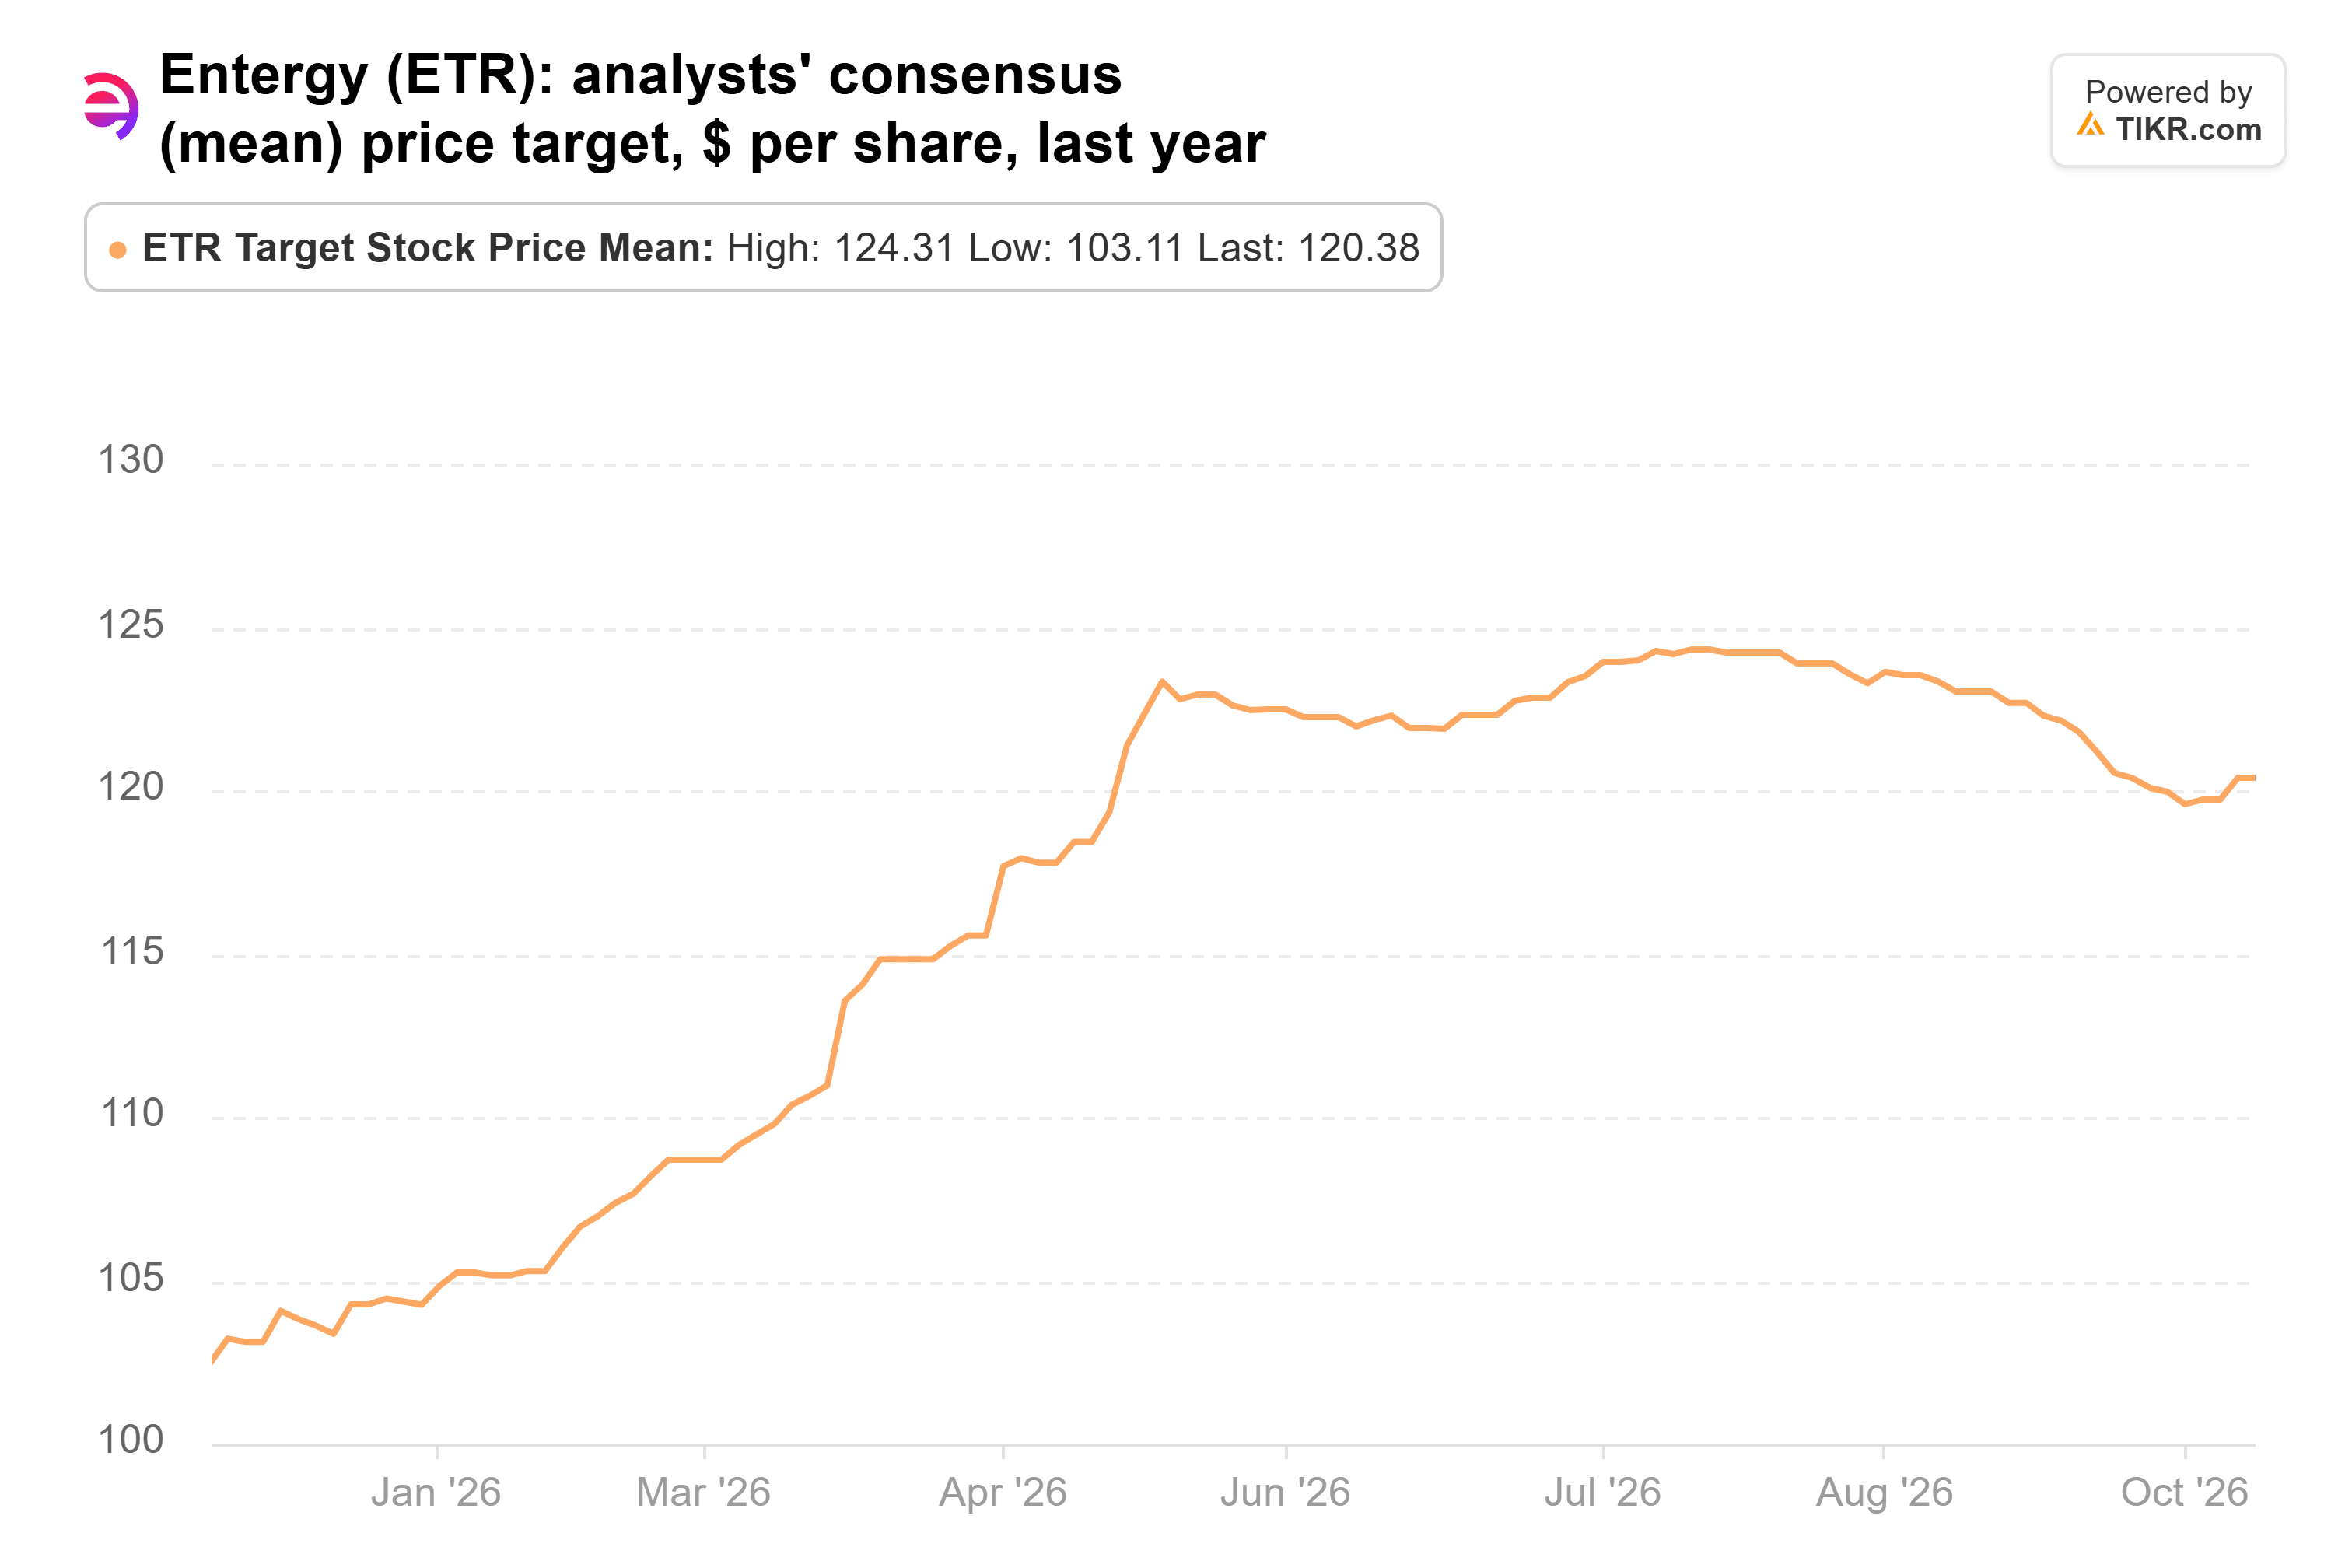
That’s still 9% above Friday’s $110.55 close, from 24 analysts, and the stock trades at about 23x forward earnings.
Mastercard has already run
The fund grew its Mastercard stake 1,884% in the quarter, to 233,018 shares worth $129 million on Sept. 30, or 2.9% of its US stocks. The stock is up 20% since then.
Mastercard beat expectations in its Q3 report on Oct. 29: net revenue rose 14% to $9.81 billion, services grew 19% on a currency-neutral basis, and adjusted EPS rose 21% to $5.31.
But new CFO Ling Hai said part of the beat was pulled forward from Q4, and that “you will see a similar offset in Q4.”
The bigger change is the multiple. Mastercard’s forward P/E sat between 25x and 26x at each of 2026’s first three quarter-ends, the low end of its range since 2016. It’s now about 29x, close to its 12-year quarter-end average of 31x, and analysts have followed the stock up:
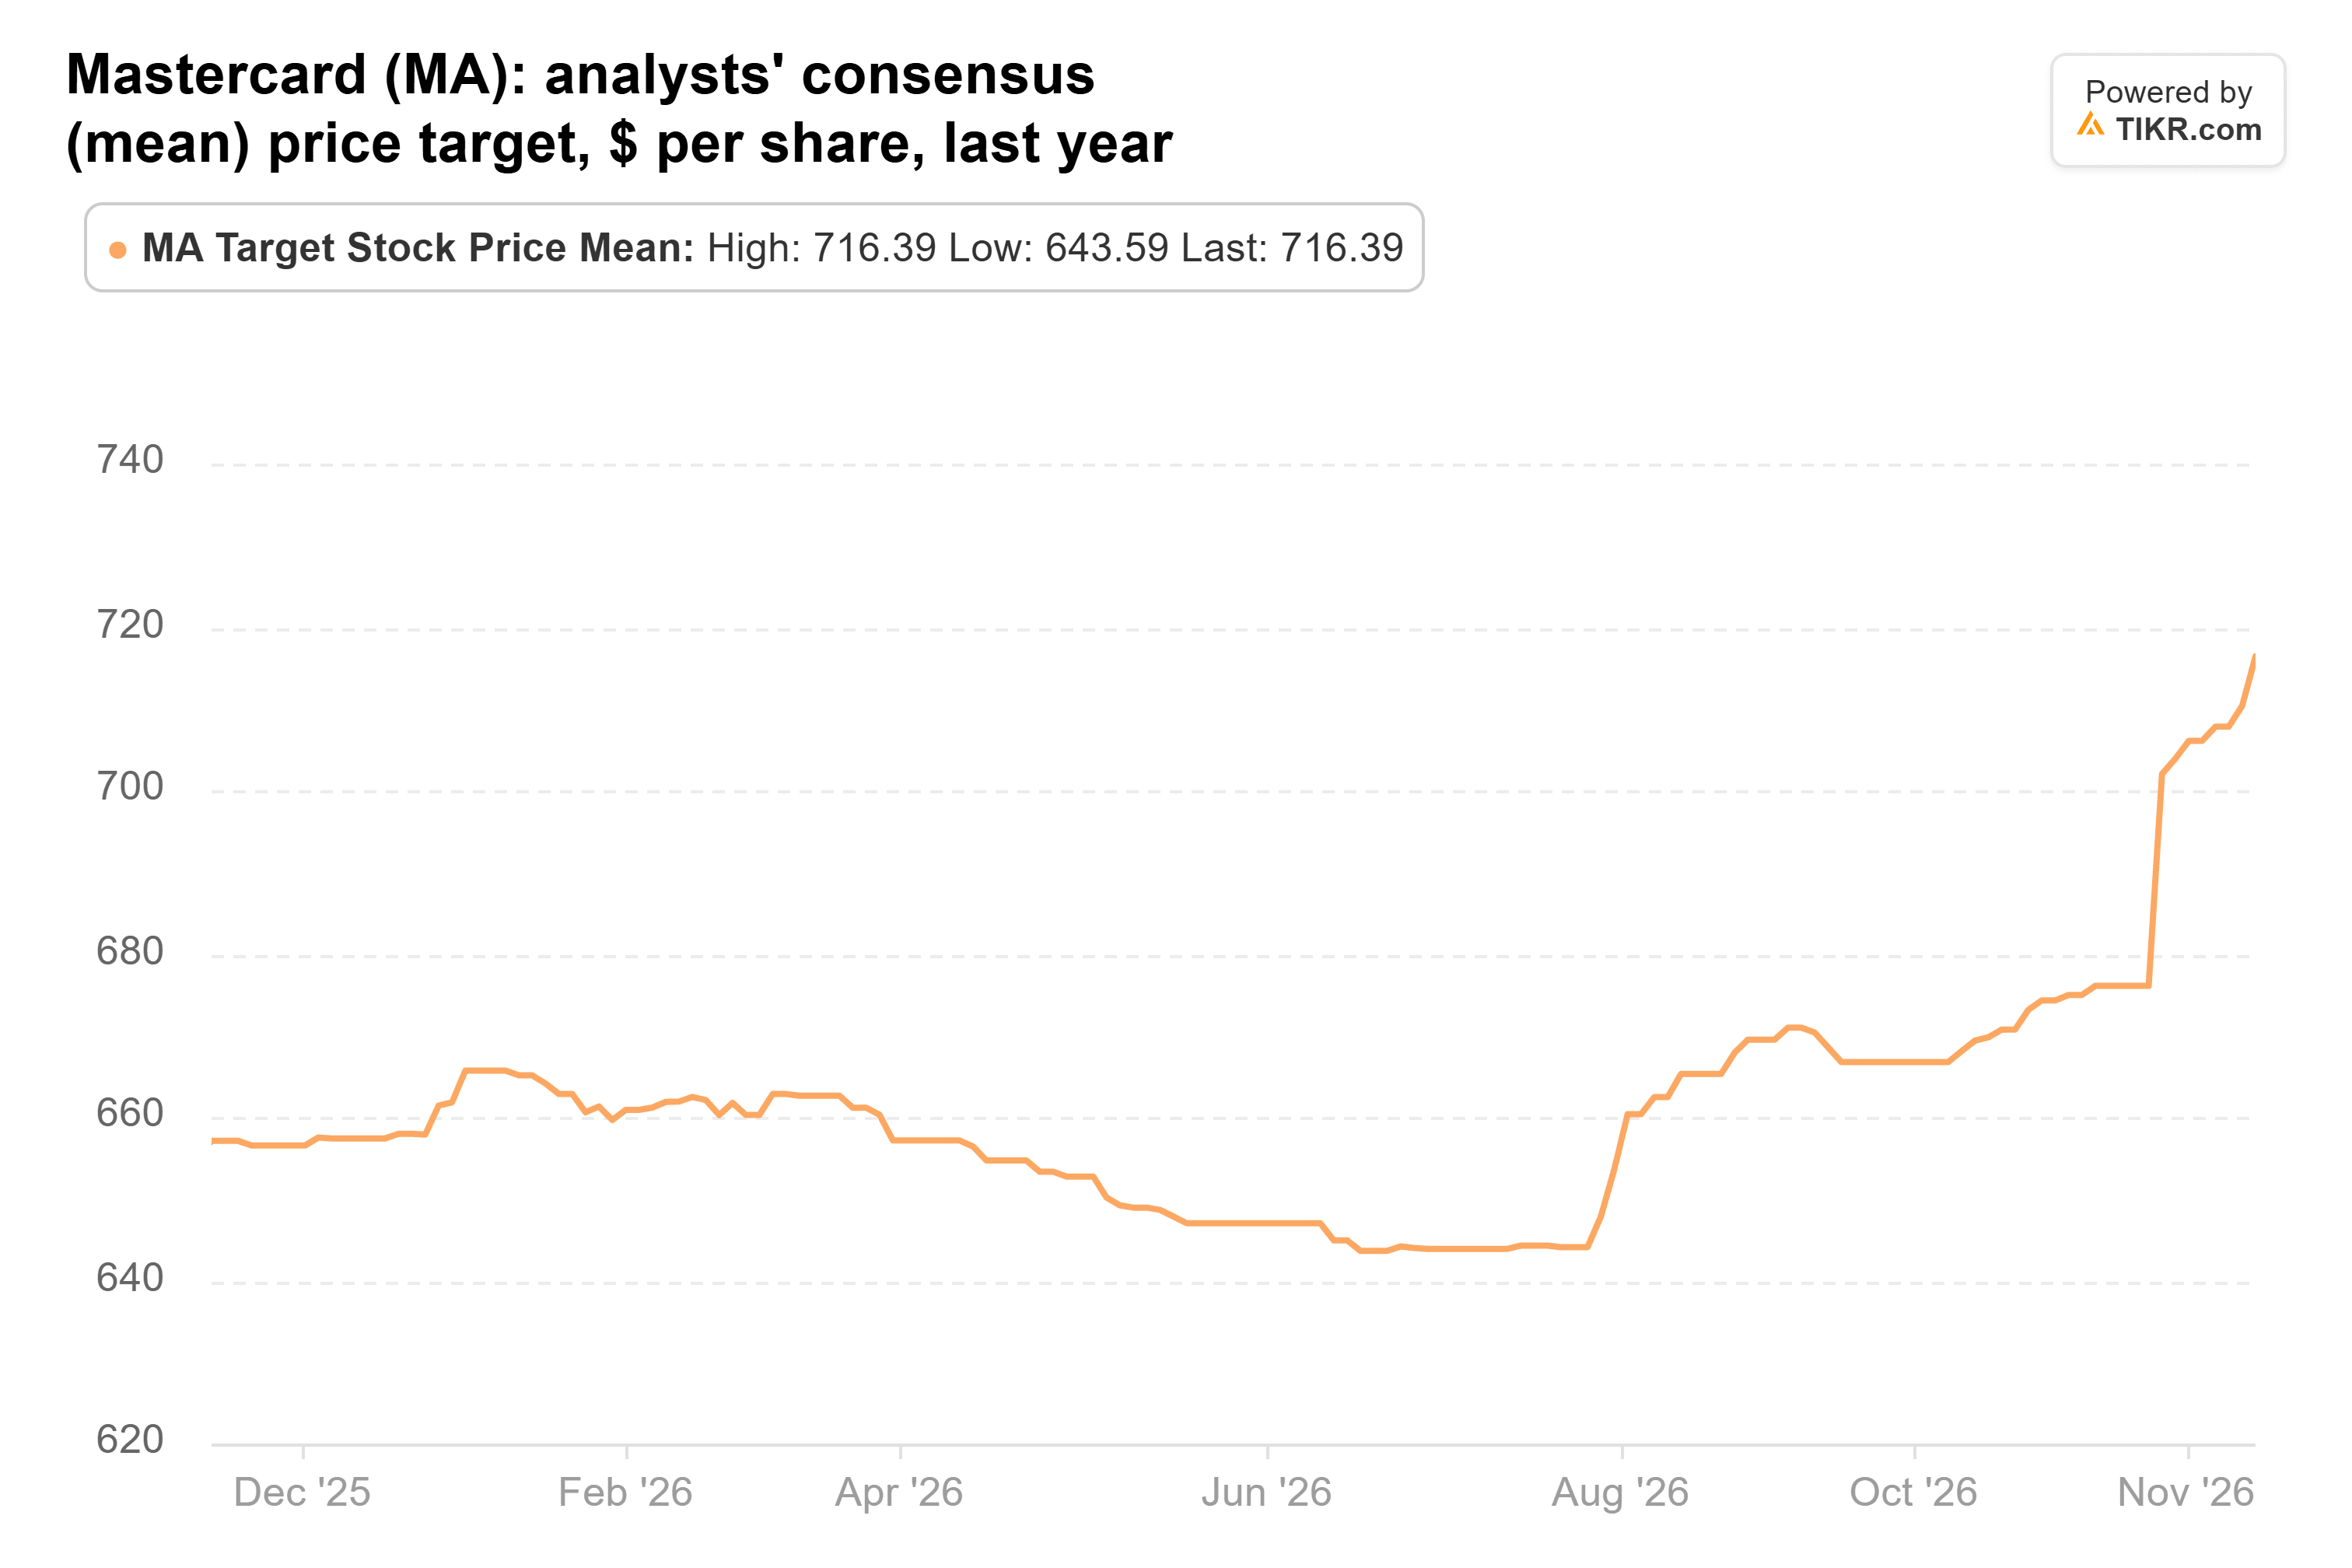
The $716.39 consensus target, its high for the year, is 10% above Friday’s $652.70 close, from 41 analysts.
CSX gets my vote
If I could only buy one of the three right now, it’d be CSX.
It’s the cheapest of the three on forward earnings, and analysts kept raising their targets right through its latest report. Mastercard is the best business here, but at about 29x, much of its rebound is already in the price. And Entergy’s targets have been heading the wrong way since July.
Part of CSX’s revenue growth came from fuel surcharges, which move with fuel prices, so I’d want volume and pricing to do more of the work from here.
Its Q4 report early next year is the next check, and Alphinity’s next 13F, due by mid-February, will show whether the fund held on.
So what is CSX stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CSX could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!