Key Takeaways
- Lam Research stock is down 34% in the past month. A record September quarter came with a December-quarter guide only in line with estimates, and fears about AI spending hit Applied Materials and the rest of the chip-equipment group too.
- Management said shortages of certain components held the guide back, and SK hynix expects memory demand to outrun supply through 2030.
- Analysts expect Lam’s EPS to rise about 66% this fiscal year, yet the stock trades at 22x forward earnings, below its five-year average of 24x.
- Bernstein kept its Buy rating and $350 target on Nov. 2, and Lam looks like a buy at this price, with its December-quarter report in late January the next test.
Lam Research (LRCX) stock is down 34% in the past month, right after the best quarter in the company’s history.
Most of that came from a selloff in anything tied to AI spending. Applied Materials (AMAT) fell 30% over the same month, against 9% for the Nasdaq 100. Even SK hynix (SKHY), a big buyer of Lam’s tools that says it can’t make memory fast enough, is down 23%.
Supply held back the guide
Lam reported after the close on Oct. 21. September-quarter revenue hit a record $8.22 billion, up 54% from a year earlier, and adjusted EPS of $2.20 beat estimates. Its adjusted operating margin was a record 40.2%.
The trouble was December. Lam guided to revenue of $8.6 billion, plus or minus $400 million, and adjusted EPS of $2.33, roughly what analysts already expected. Management said on the call that shortages of certain components kept the guide from being higher, and that the delayed shipments should go out in the March quarter. China, 35% of September-quarter revenue, is also expected to drop sharply in December.
With investors already nervous about AI spending, that was enough. The stock fell 12% the next day, and analysts cut their targets across the board. Bernstein’s Stacy Rasgon was one of them, cutting his to $350 from $385.
TIKR tracks 34 analysts on Lam Research. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Lam Research, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Lam Research’s Analyst Ratings
Chip equipment sold off as a group
The slide had started before Lam reported. Chip-equipment stocks were headed for historic losing streaks on Oct. 16 on worries about how fast AI spending was running. Then on Oct. 30, Intel’s weak fourth-quarter guidance and Amazon’s growing AI spending revived doubts that all that spending will pay off, and chip stocks fell again.
With Applied Materials down nearly as much as Lam, I read this as investors selling the whole AI-spending trade, with Lam’s guide giving them one more reason.
The shortage is still there
SK hynix made the bull case on Oct. 28, posting a record quarter and saying memory demand will outrun supply through 2030, since new fabs take years to build. Lam rose 5% that day. And on its own call, Lam’s management put preliminary 2027 wafer fab equipment spending above $200 billion, led by DRAM.
Analysts expect that to show up in Lam’s earnings, with EPS climbing from $5.82 in the year to June 2026 to $9.65 this fiscal year and $12.24 the next:
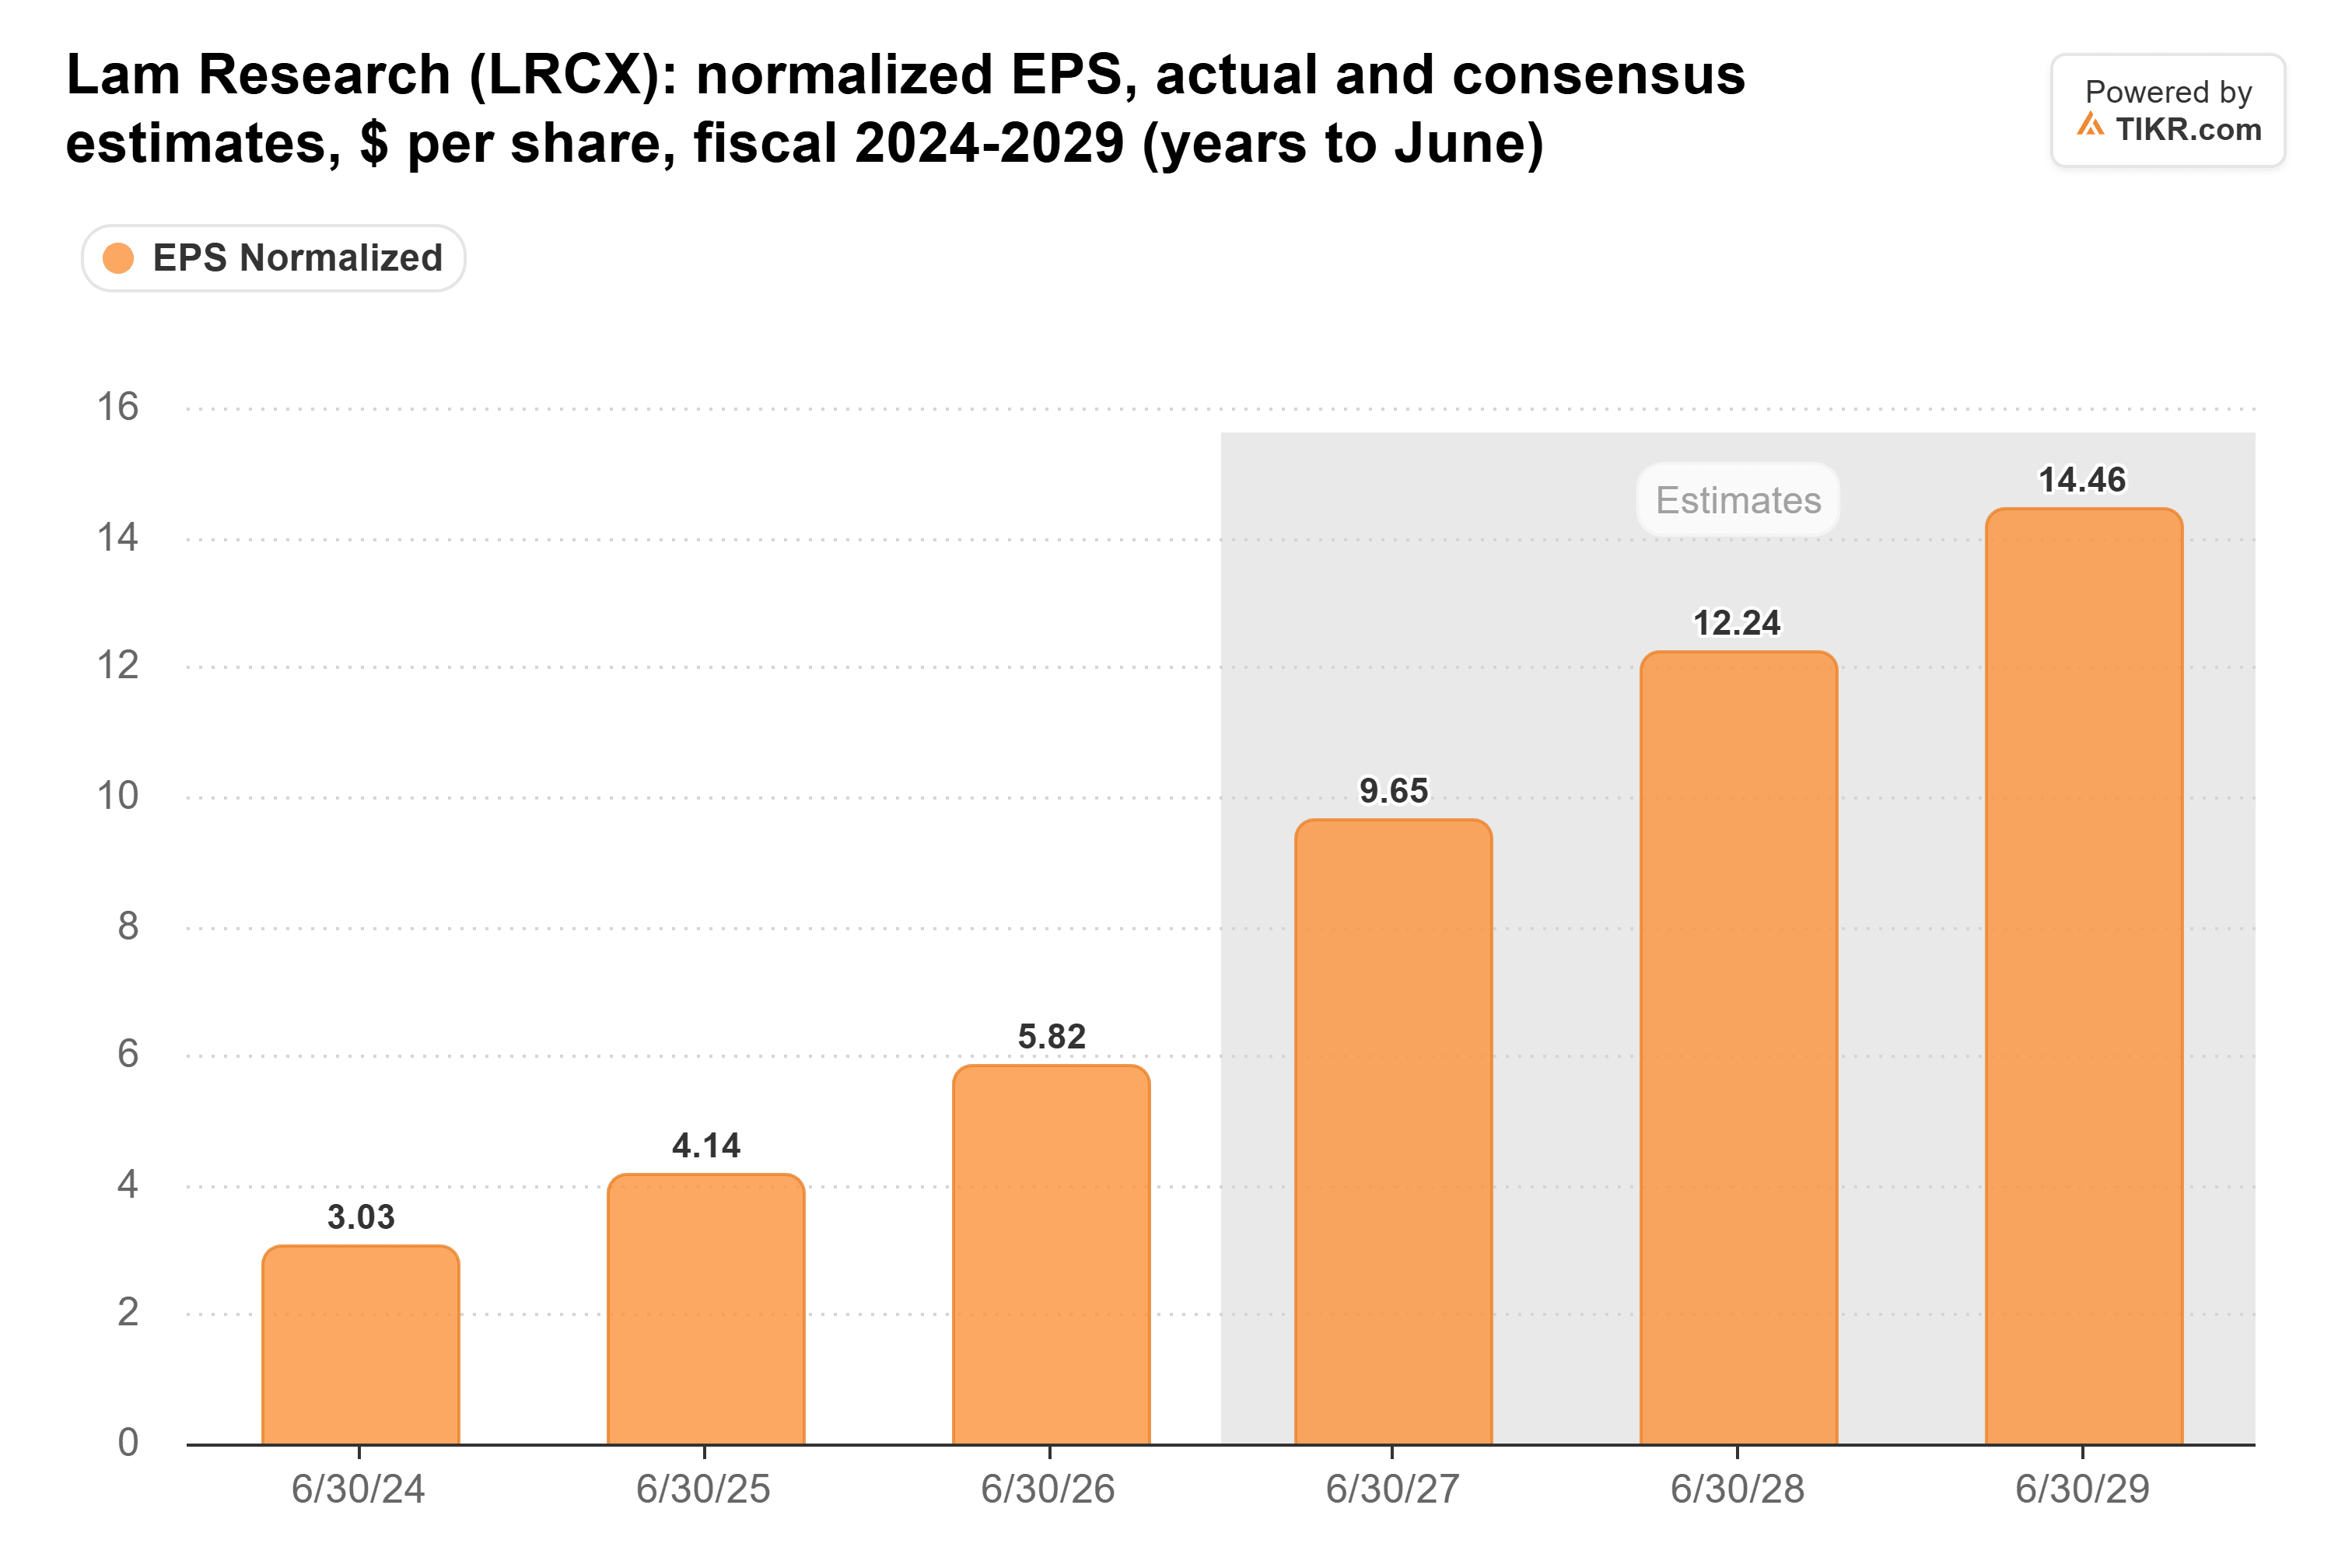
A delay in shipping, with demand intact, shouldn’t move those estimates much.
$350 needs only a modest premium
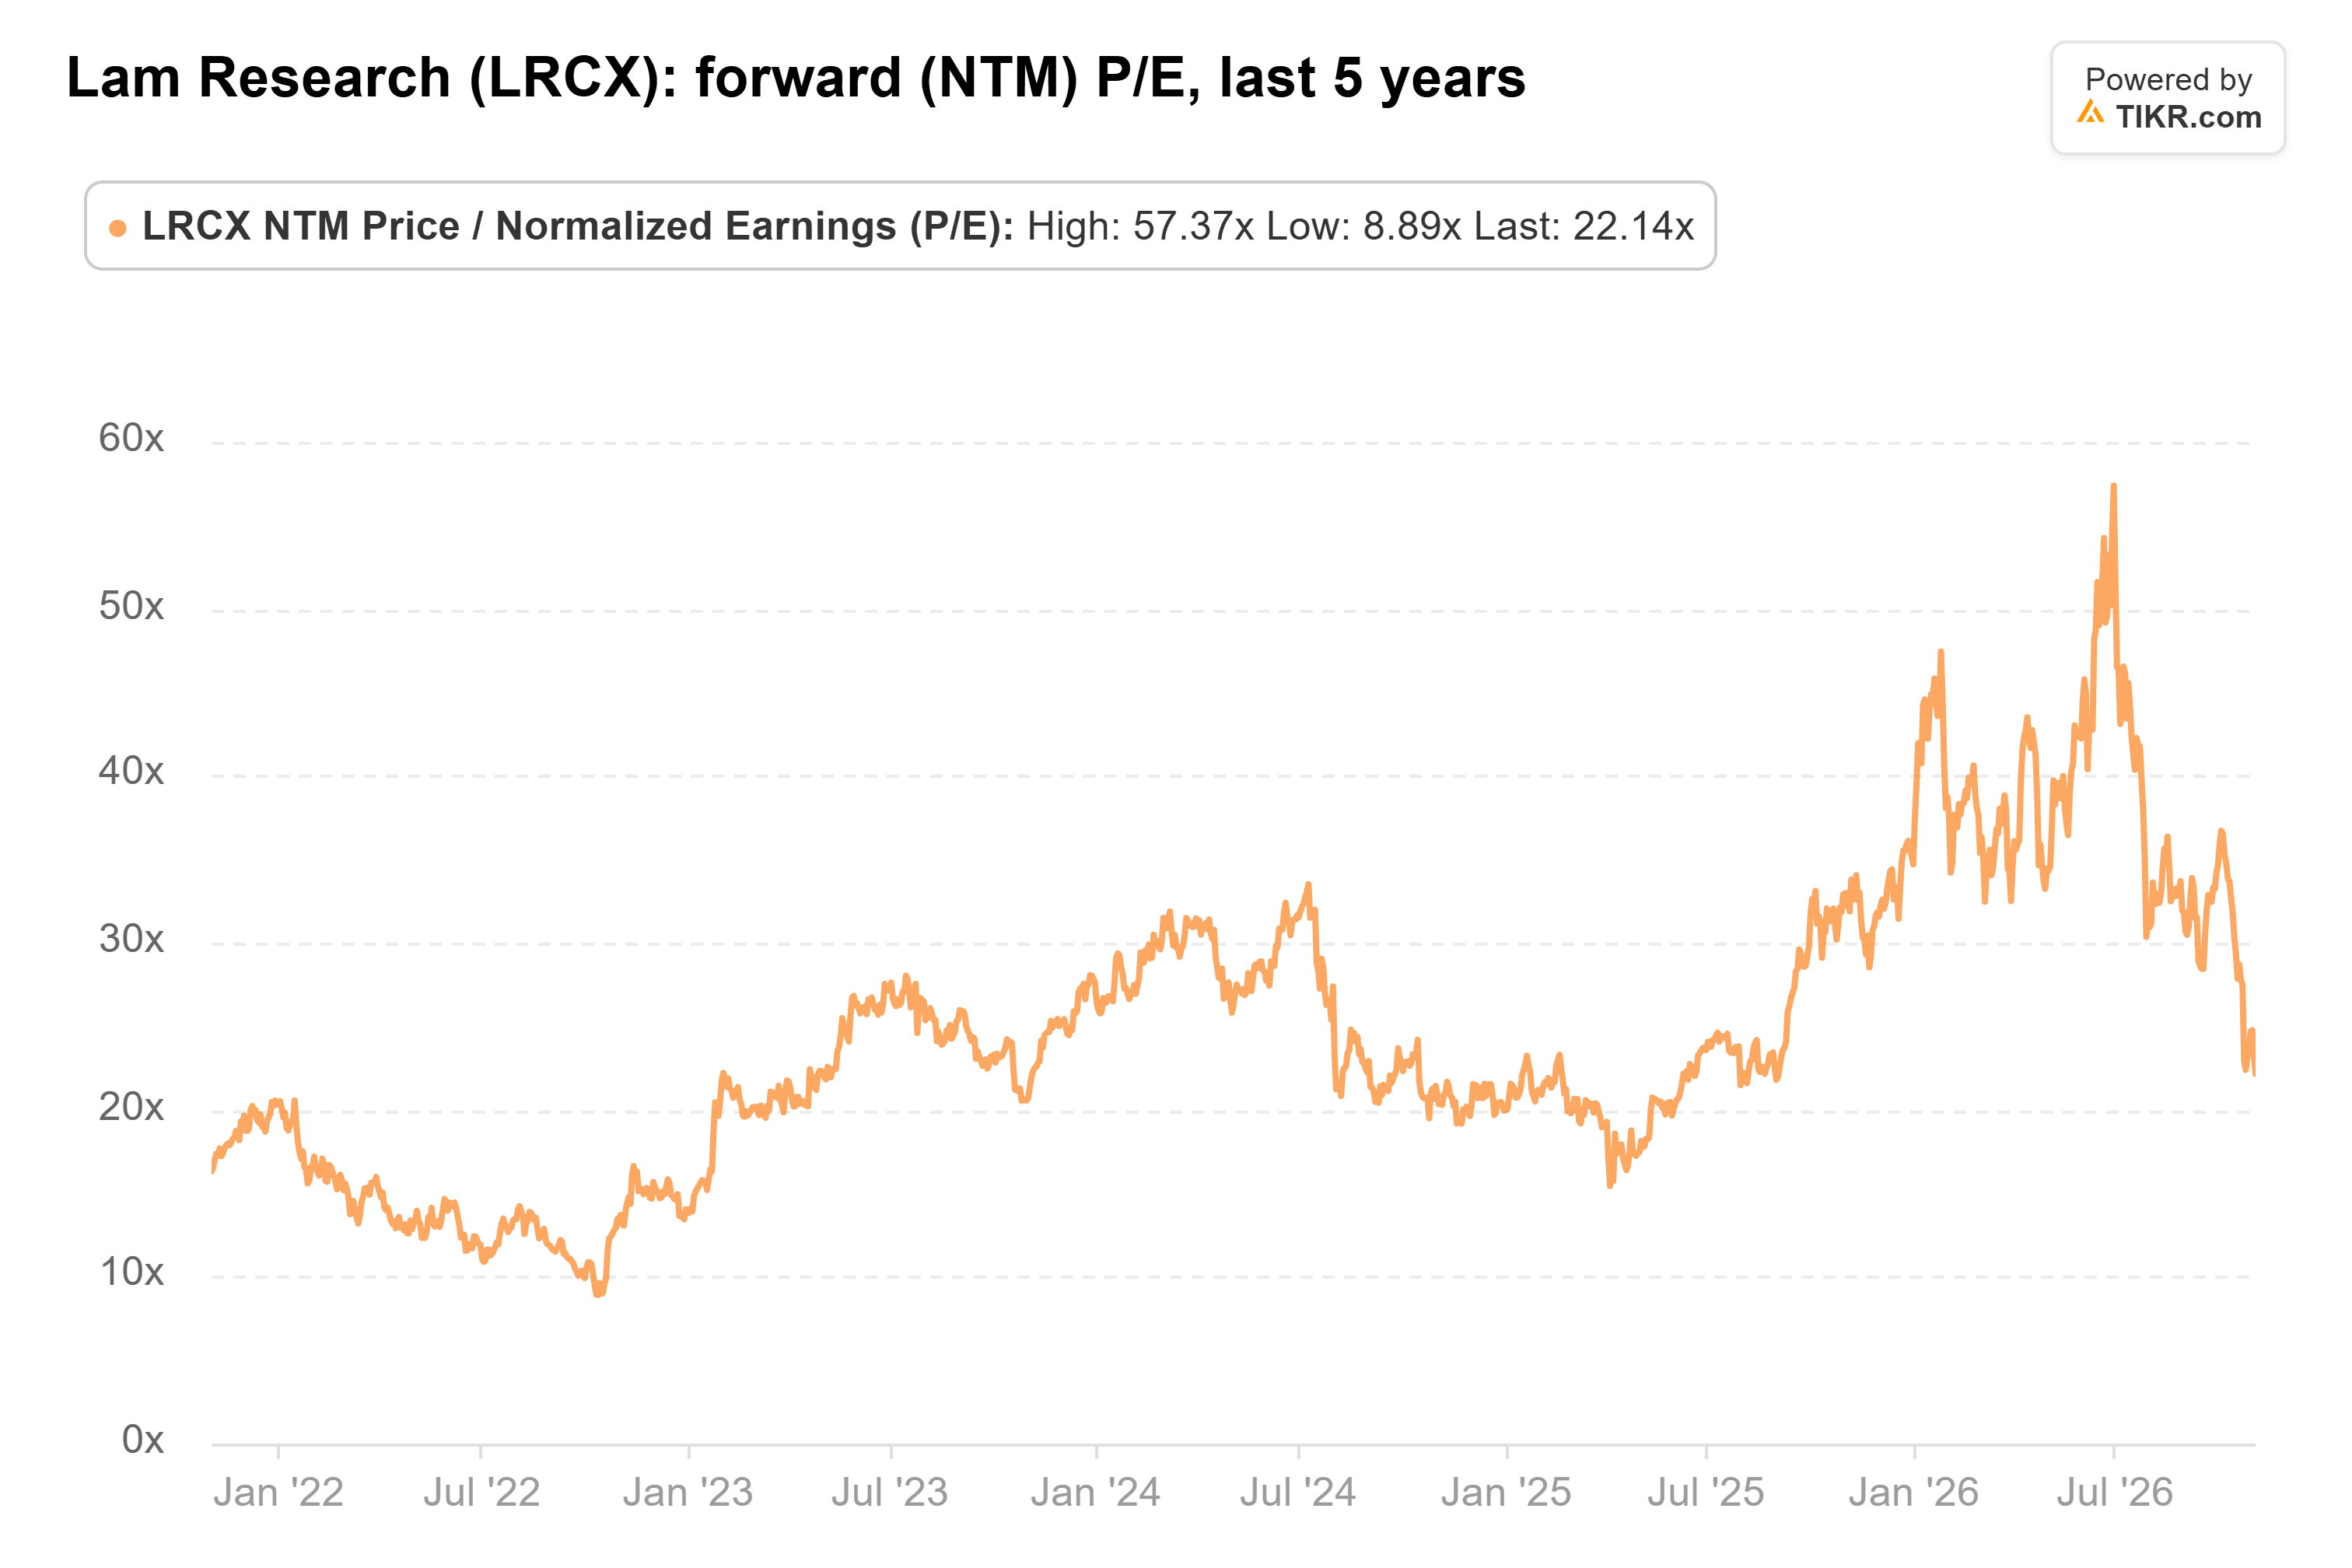
Lam now trades at 22x forward earnings, below its five-year average of 24x and far from its 57x peak on June 30:
On Monday, Rasgon kept his Buy rating and his $350 target, 53% above the stock’s current price. The Street’s consensus target of $364 is higher still, though it slipped from its Oct. 18 high after the cuts:

Rasgon’s $350 is about 29x what analysts expect Lam to earn in the year to June 2028. At the stock’s usual 24x, those same earnings would put it near $300.
The way I see it, the market is pricing in AI-spending fears that Lam’s own numbers don’t show yet. Getting to $300 takes nothing more than the multiple Lam has averaged for five years. And $350 needs only a modest premium for a company whose earnings are expected to double in two years. At this price, I think Lam is a buy.
The risk is that those fears prove right: if chipmakers cut their spending, the estimates behind every target come down too. Lam’s December-quarter report, due in late January, is the next test.
So what is Lam Research stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Lam Research could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!