Key Takeaways
- Fortinet stock fell 12% in the past week, adding to its post-earnings slide as Palo Alto Networks, CrowdStrike and Zscaler sold off alongside it.
- Service revenue grew just 13% in the third quarter while billings grew 29%, and management says big deals are taking longer to activate.
- Analysts still expect Fortinet’s normalized EPS to climb from $3.56 this year to $4.42 in 2028, and the stock trades well below its 5-year average forward P/E.
- Patient investors can start buying here, and service revenue in the fourth-quarter report in early February is the number to watch.
Fortinet (FTNT) stock fell 12% in the past week. That adds to a slide that began when shares sank more than 20% the morning after its Oct. 28 earnings report.
And this time it had company. Investors sold cybersecurity stocks as a group, and Palo Alto Networks (PANW), CrowdStrike (CRWD) and Zscaler (ZS) all fell even harder than Fortinet did.
Customers are buying, but the revenue is running late
The quarter itself looked strong. In the three months ended Sept. 30, Fortinet reported:
- Revenue up 20% to $2.08 billion
- Product revenue up 37% to $765 million
- Billings up 29% to $2.34 billion
- Service revenue up just 13% to $1.31 billion
Management also raised its full-year revenue guidance to $8.125 billion to $8.215 billion. It added $1.2 billion to its buyback, which leaves $2 billion authorized. But service revenue is the recurring piece investors pay up for, and it grew much more slowly than billings.
CFO Christiane Ohlgart said on the third-quarter call that the lag comes from big enterprise deals where the services switch on gradually. She pointed to service billings and deferred revenue as proof that customers are still buying services. It’s “just a little bit of a delay from when it gets recognized.”
The risk is that service growth has simply peaked. Wells Fargo kept its Sell rating and cut its target to $115 from $160 just before the week began.
TIKR tracks 43 analysts on Fortinet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Fortinet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Fortinet’s Analyst Ratings
Palo Alto, CrowdStrike and Zscaler are paying for it too
Fortinet’s report hit the whole group, and the selling picked up again this week. Zscaler fell 17%, while Palo Alto and CrowdStrike each fell 14%, against a 5.5% drop for the Nasdaq 100. CrowdStrike fell even after Deutsche Bank upgraded it to Buy with a $300 target on Nov. 2.
Spending doesn’t look like the issue. Wedbush analyst Dan Ives said on the RiskReversal Pod that “budgets are going to potentially double in cybersecurity for IT over the next two, three years.” All three companies report their October quarters in the coming weeks. Their subscription growth will show us whether Fortinet’s service problem is its own or a sign of something bigger.
Earnings are still headed higher
Analysts expect Fortinet’s normalized EPS to rise to $3.56 this year, inside management’s guided $3.54 to $3.58. They see it reaching $3.90 in 2027 and $4.42 in 2028:
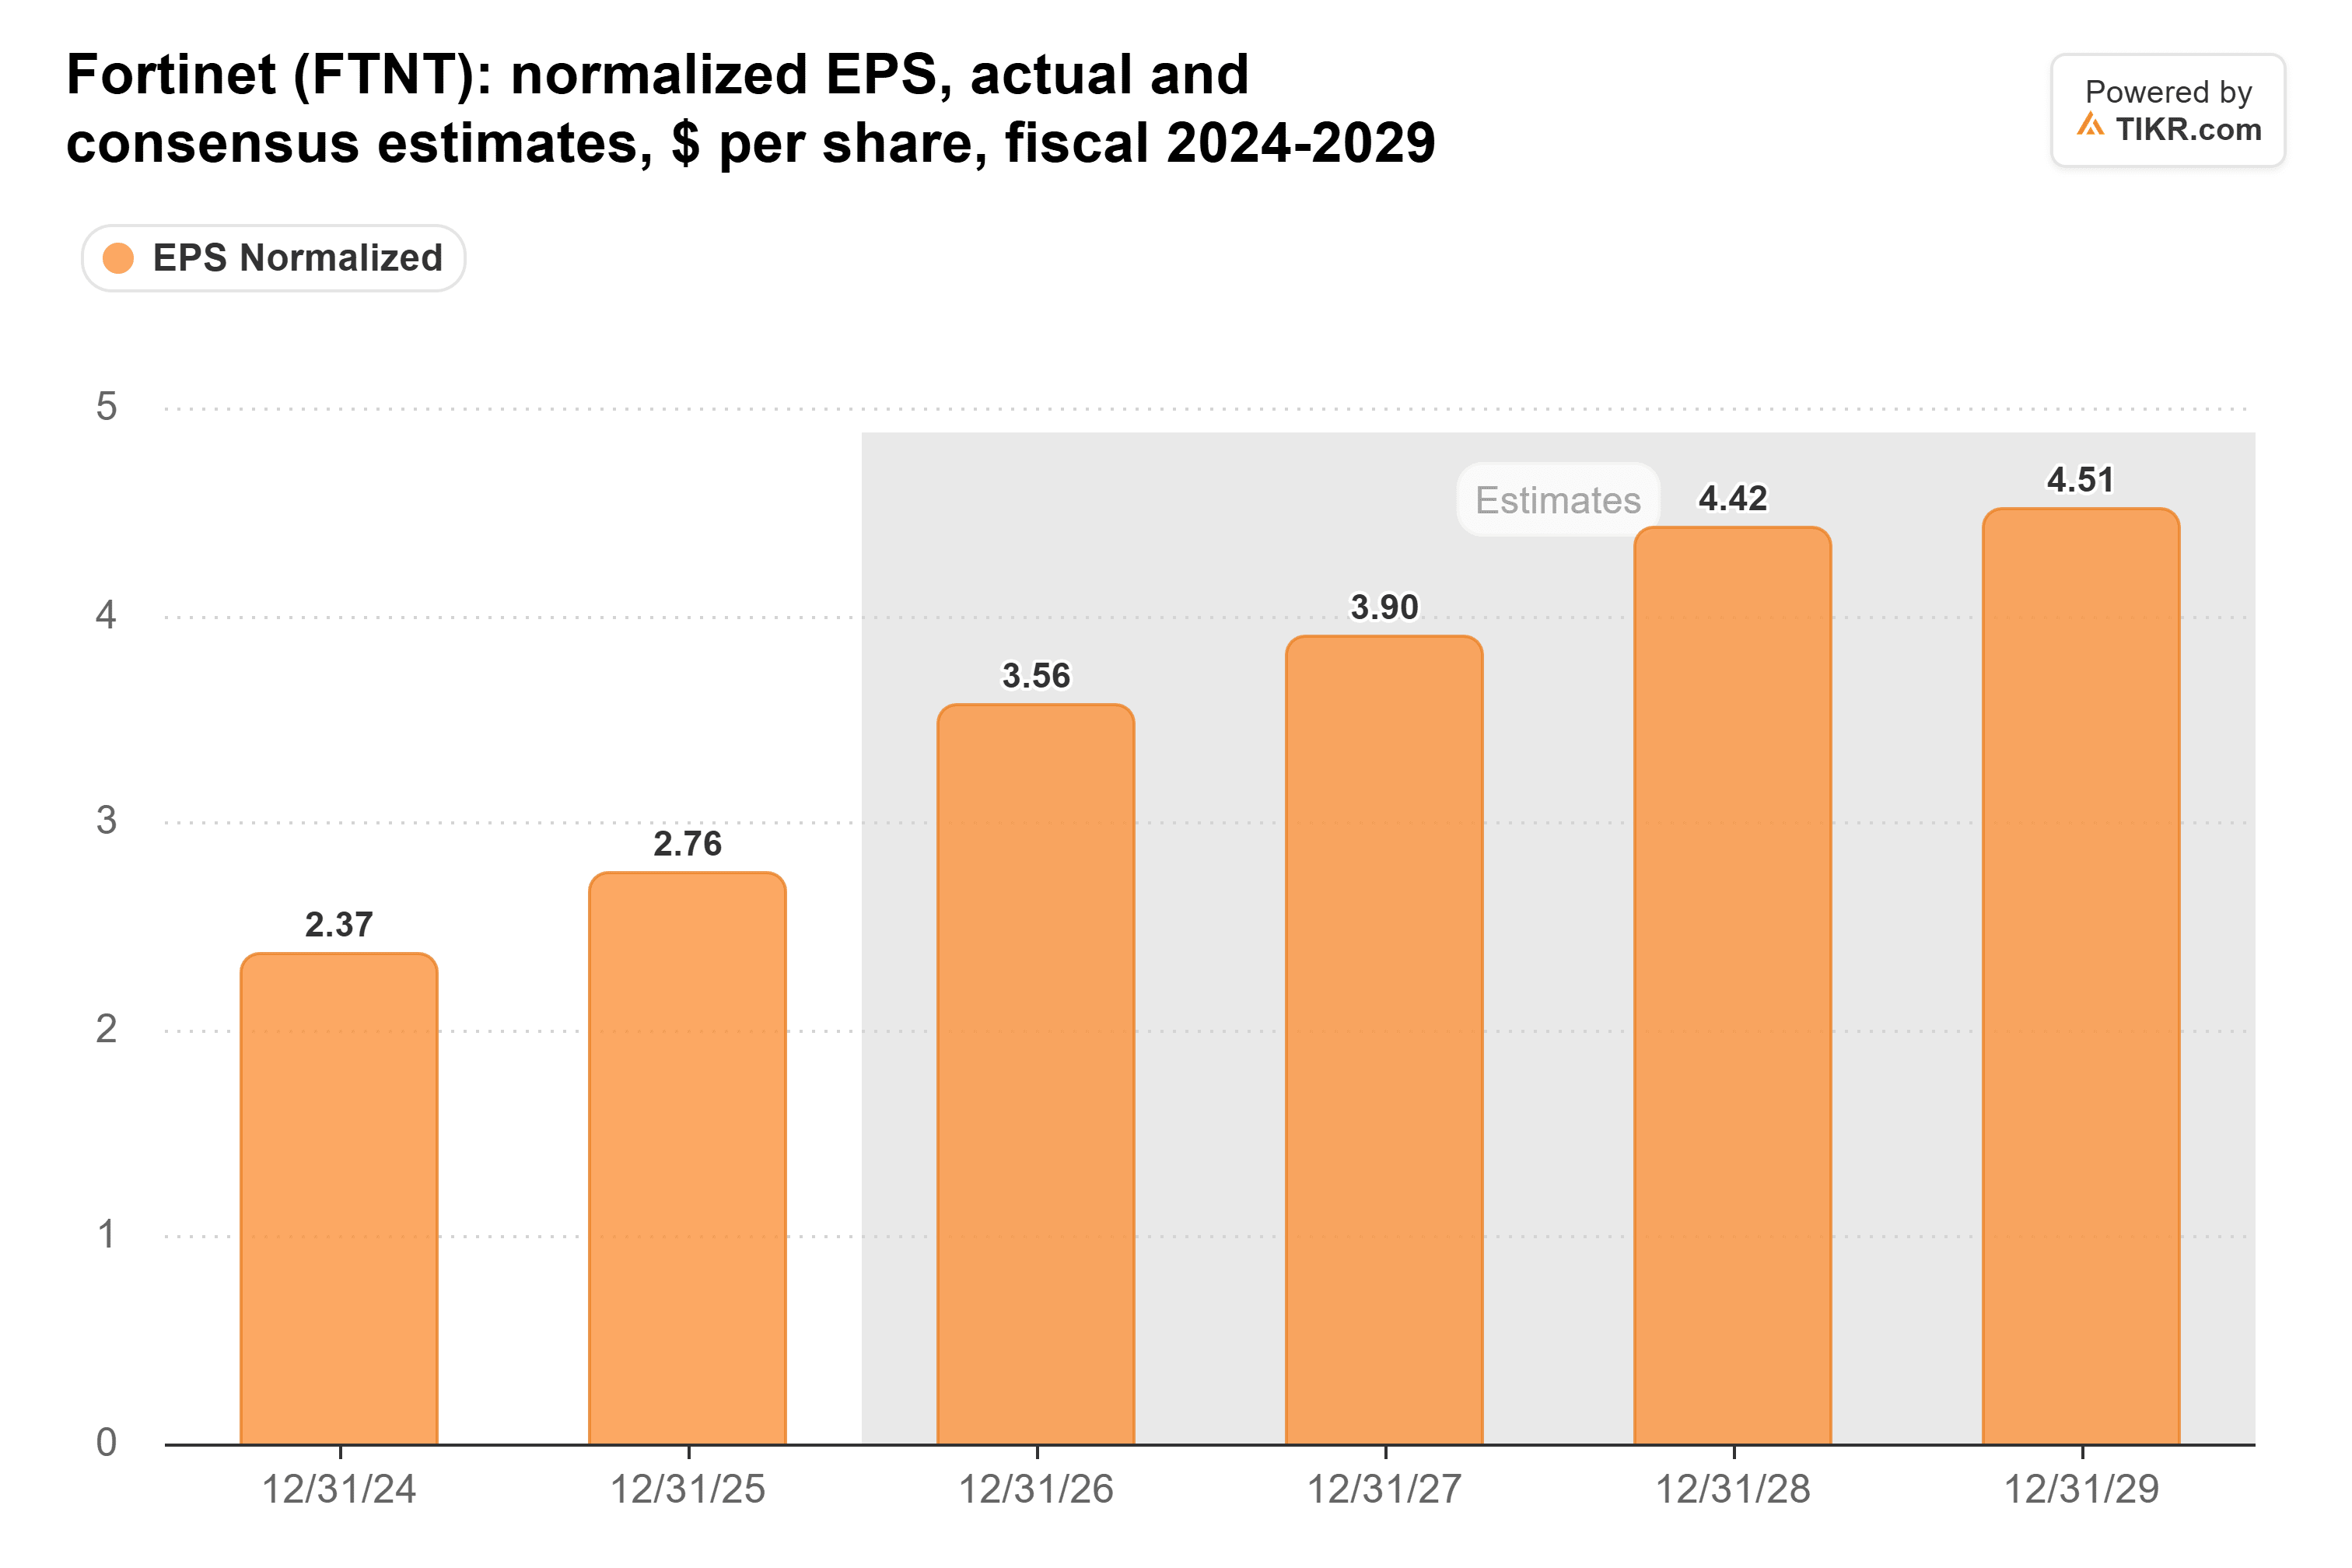
And I don’t see anything in this quarter’s results or guidance that should push those numbers down.
Investors are paying a lot less for those earnings, though. Fortinet traded at 33x forward earnings at the Nov. 5 close, well below its 5-year average of 43x, and Friday’s slip took it a little lower:
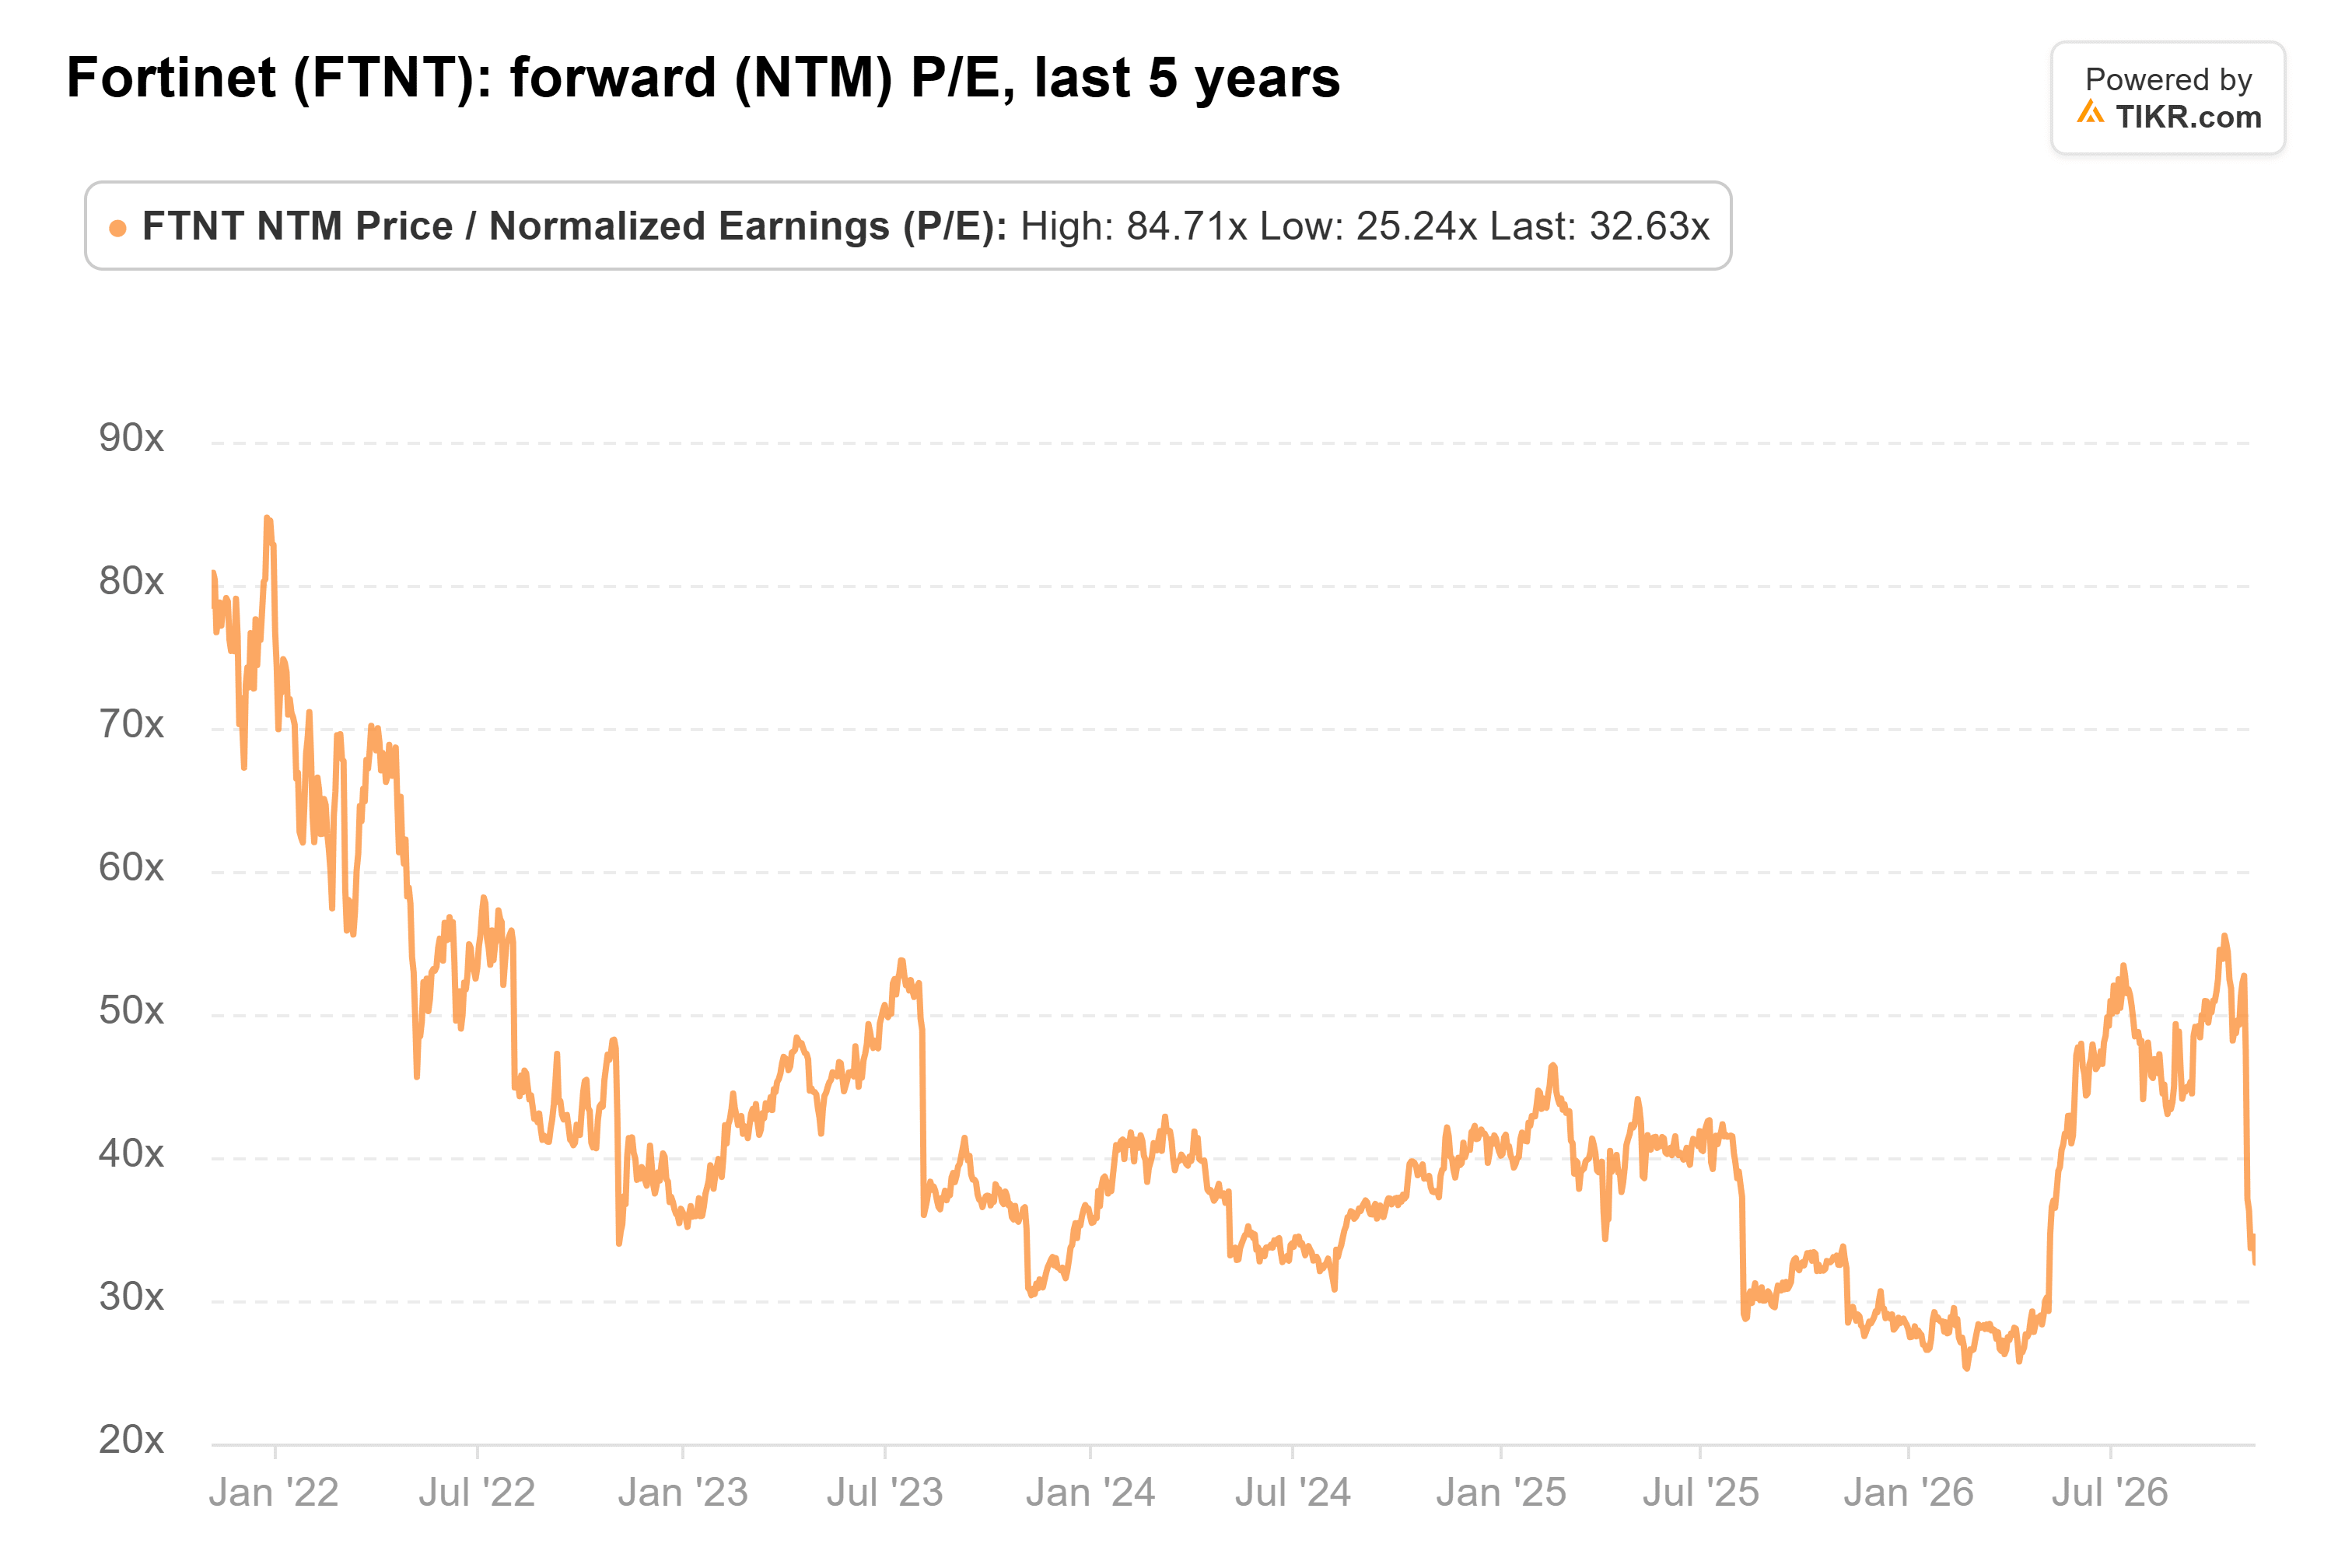
(It was even cheaper in February, at 25x, before the stock’s big run this year.)
Time to start buying
Analysts have cut their targets along with the stock, but the average still sits well above it. The consensus target was $146 as of Nov. 3, down from $169 just before the report and about 22% above Friday’s close:
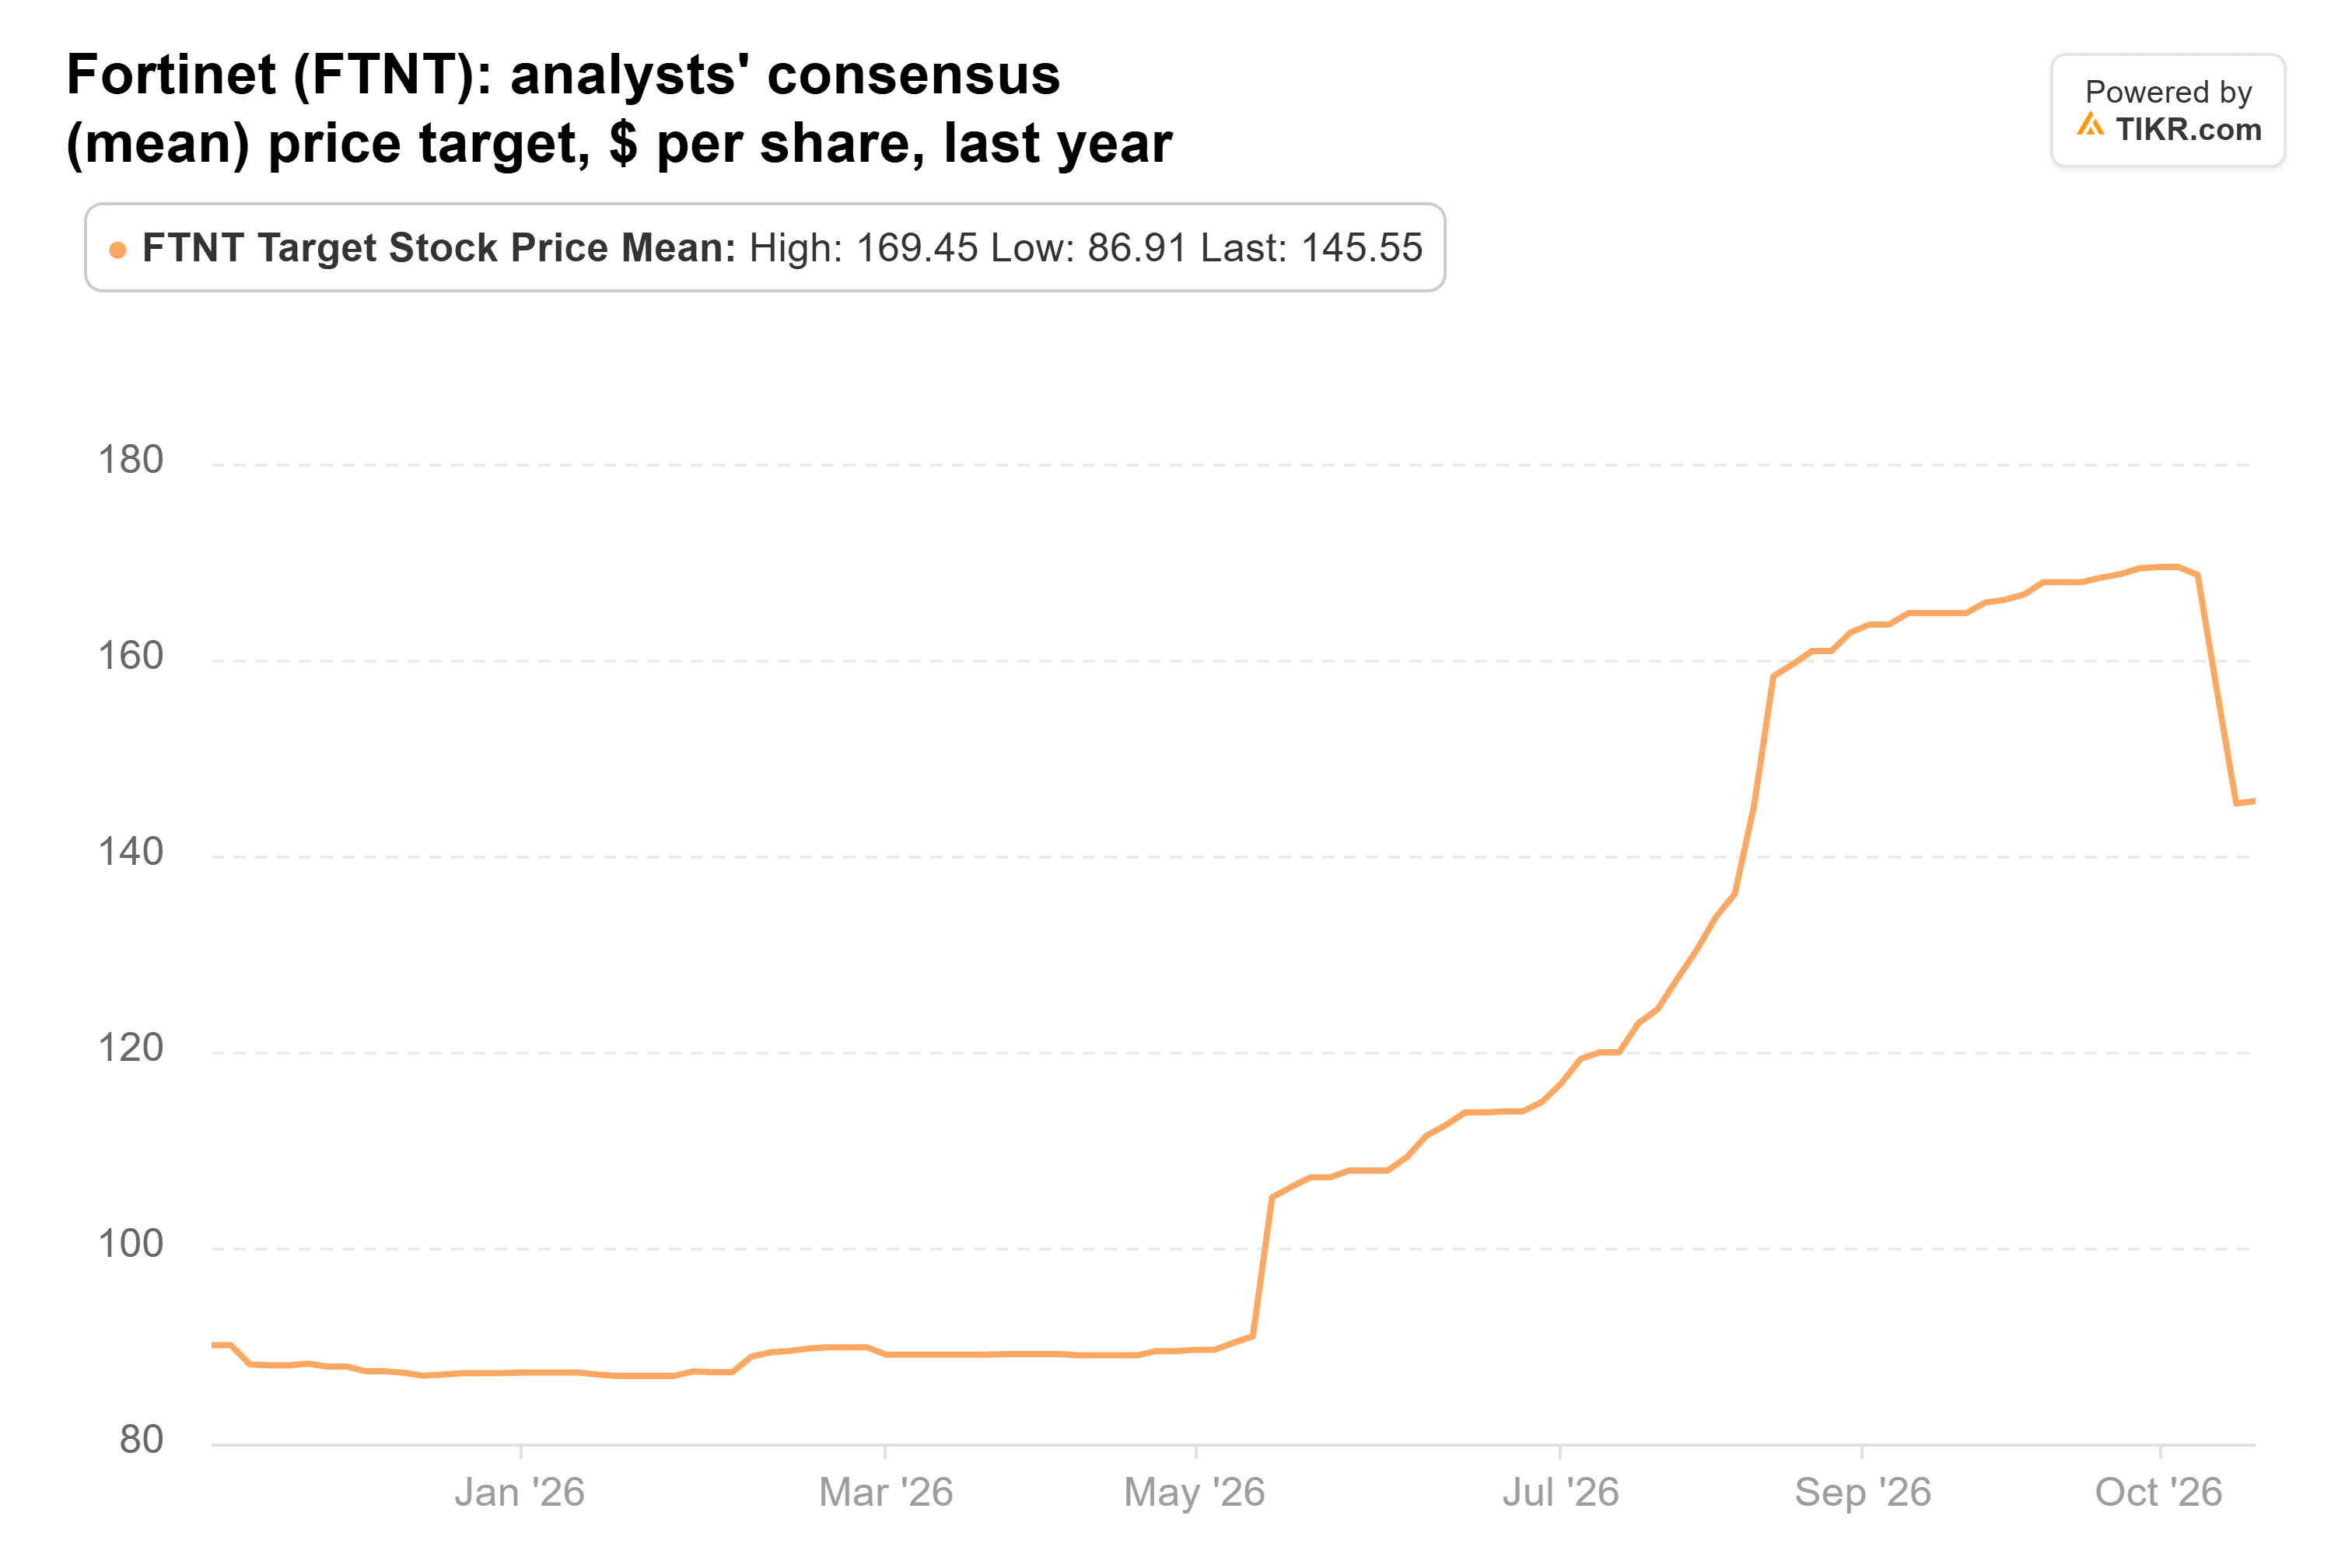
Daiwa upgraded the stock to Outperform with a $150 target on Nov. 3, and the selling went on anyway. With the stock now 40% below its 52-week high, I think the market has overreacted. Patient investors can start a position here and add to it as the service revenue comes in.
Management presents at BMO’s technology conference on Nov. 12. But the real test is the fourth-quarter report in early February, against guidance for $2.775 billion to $2.925 billion of billings. If service growth hasn’t picked up by then, I’d have a much harder time believing it’s just timing.
So what is Fortinet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Fortinet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!