Key Takeaways
- Nebius stock is up 71% in 2026 even after a 35% slide since the end of September, helped by an August report in which second-quarter revenue rose 454% to $582.3 million.
- Its October slide came from debt fears that started at CoreWeave and spread to every AI cloud, capped by Elon Musk’s warning, more than from bad news at Nebius.
- Contracts with Microsoft and Meta back Nebius’s borrowing and Palantir added a new sales channel, but analysts expect its capex to reach $29.1 billion in 2027.
- Below 7x forward sales, the stock is worth buying, as long as November’s report shows customers still paying up front.
Nebius Group (NBIS) is up 71% in 2026, even after losing about 35% since the end of September as investors soured on AI cloud companies that run on borrowed money.
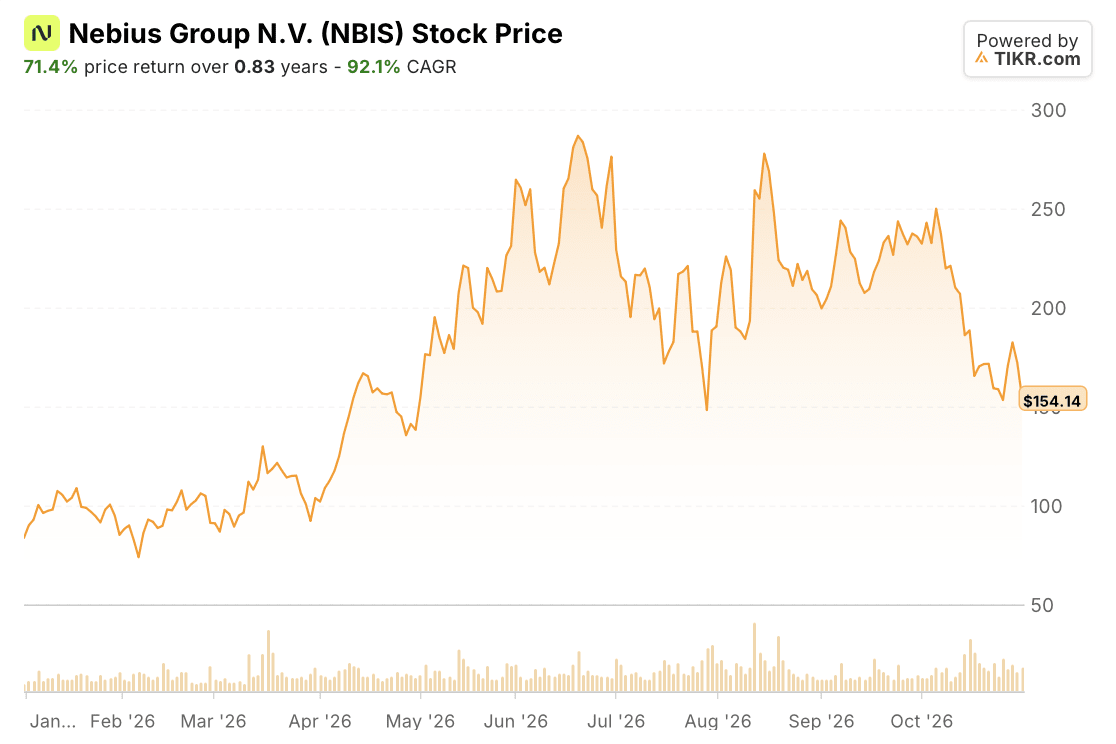
The scare started at CoreWeave (CRWV), and on Oct. 25 SpaceX and Tesla CEO Elon Musk posted on X that more than 200 neoclouds are “going to see guppy-level death and consolidation.” But Nebius has more than $40 billion in long-term contracts from investment-grade customers, including Microsoft (MSFT) and Meta Platforms (META), and in September Palantir Technologies (PLTR) named it its preferred sovereign AI infrastructure partner.
The August Report Did the Heavy Lifting
Before the open on Aug. 12, Nebius reported its second quarter:
- Revenue up 454% to $582.3 million
- Adjusted EBITDA of $236.2 million, a 41% margin, against a $21.0 million loss a year earlier
- Four new AI cloud deals averaging more than $1 billion each
The stock jumped 34% that day.
A month later, Palantir added a channel: it will offer Nebius’s compute to commercial customers running their own models.
TIKR Tracks 23 Analysts on Nebius. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nebius, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nebius’s Analyst Ratings
October’s Selloff Started at CoreWeave
Worries about CoreWeave’s roughly $50 billion of debt hit Nebius hard on Oct. 16, though the two balance sheets looked nothing alike. At June 30, Nebius had about $0.5 billion of borrowings net of cash, leaving out leases, against roughly $29.5 billion for CoreWeave.
On Oct. 22, Nebius announced a $3.5 billion, 364-day bridge loan from Citi whose rate steps up every 90 days.
Nebius got its money, but Musk says that window is closing: debt markets, he wrote, have “almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers.”
The Bill Comes Due in 2027
Nebius’s net debt won’t stay small, though. Analysts see capex of $23.2 billion this year and $29.1 billion in 2027, and net debt of about $34 billion by the end of 2027.
Customers cover a big piece, with more than $9 billion of prepayments expected this year, and Nebius can borrow against its contracts: Microsoft’s is worth $17.4 billion to $19.4 billion, and Meta’s up to $27 billion, including $15 billion that Meta pays only for capacity Nebius doesn’t sell to others first.
The bet is that prices hold. CEO Arkady Volozh said at a Citi conference in September that the shortage of AI computing power should balance in a year or two, while deals at today’s prices pay back in under two years.
What Nebius’s November Report Has to Show
Nebius reports third-quarter results in mid-November. Analysts expect about $906 million of revenue, and management is aiming for $7 billion to $9 billion of annualized revenue by December, from $3.0 billion at June 30.
Analysts still expect revenue to multiply in 2026 and 2027:

They’ve trimmed their 2027-2030 estimates by less than 2% since Sept. 30, and nothing in October’s news touched Nebius’s demand.
I’d watch deferred revenue most, $6.0 billion at June 30: it shows whether customers still pay up front for 2027.
I’d Buy More Nebius Below 7x Sales
Nebius traded at 6.5x forward sales on Oct. 27, about half its 13x at the end of June and below its 32x peak in October 2025:

The 20 analysts with price targets average $281, 82% above the Oct. 30 close.
Take profits? I wouldn’t. Estimates are holding and the multiple has been cut in half, so Nebius is a buy if you can sit through drops like October’s.
Of course, risks come with it. Profits aren’t there yet: second-quarter depreciation of $259.7 million topped adjusted EBITDA. And dilution comes with growth: a share sold at the Oct. 30 close raises about 31% less than the $224 average Nebius got in the second quarter. If prepayments slow, expect more stock or debt in the year the Citi loan comes due.
So What Is Nebius Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nebius could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!