Key Takeaways
- Anthropic’s S-1, made public Oct. 26, says it now leases its own data centers and the AI chips inside them, alongside renting computing power from Amazon and Alphabet’s Google.
- That makes one of AWS’s two biggest AI customers a partial rival, and it limits how much of Anthropic’s growing compute bill AWS can win beyond its current contract.
- Anthropic’s $110 billion AWS commitment runs through 2036, while Amazon spent $132 billion on capex in 2025 and expects about $220 billion in 2026.
- Amazon’s Oct. 29 results showed AWS growth speeding up to 39% and its backlog rising to $578 billion, and CEO Andy Jassy projects AWS growth above 40% in both 2027 and 2028.
Amazon (AMZN) has a new competitor in the cloud, and it’s one of its biggest customers.
Anthropic’s S-1, made public Oct. 26, says the Claude maker now leases AI chips directly and runs them in data centers leased and operated for it, built to its own spec. That comes on top of renting computing power from Amazon and Alphabet (GOOG). Anthropic calls the effort Anthropic Direct. The S-1 names Fluidstack, the company behind the $50 billion Texas and New York data center deal Anthropic announced in November 2025, as a partner that develops and runs data centers for it, and Anthropic plans to sign more leases.
On the Oct. 27 episode of Prof G Markets, investor Paul Kedrosky summed up what that means:
“They’re essentially reduplicating AWS, Amazon Web Services, in both directions.”
He means Anthropic is building up both the products customers use and the cloud underneath them. In his view, Anthropic has little choice. Leaning on its largest competitors leaves it exposed, so it has to make duplicate investments to stop depending on them, both strategically and for the cut they take on sales through their cloud marketplaces. He expects the spending to speed up from here.
For AWS, that’s a big customer planning a partial exit.
Amazon Built for This Demand
Anthropic has committed $110 billion to AWS through 2036, tied to Amazon’s Trainium chips, and $114.5 billion to Alphabet’s Google through 2033, according to CNBC’s read of the S-1. Amazon has spent heavily to be ready for bills that size. Its capital spending more than doubled from $52.7 billion in 2023 to $132 billion in 2025…

And management expects about $220 billion of cash capex in 2026, a figure it reaffirmed on Oct. 29.
TIKR Tracks 60 Analysts on Amazon. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
That build has swallowed most of Amazon’s free cash flow, which fell from $32.9 billion in 2024 to a thin $7.7 billion in 2025…
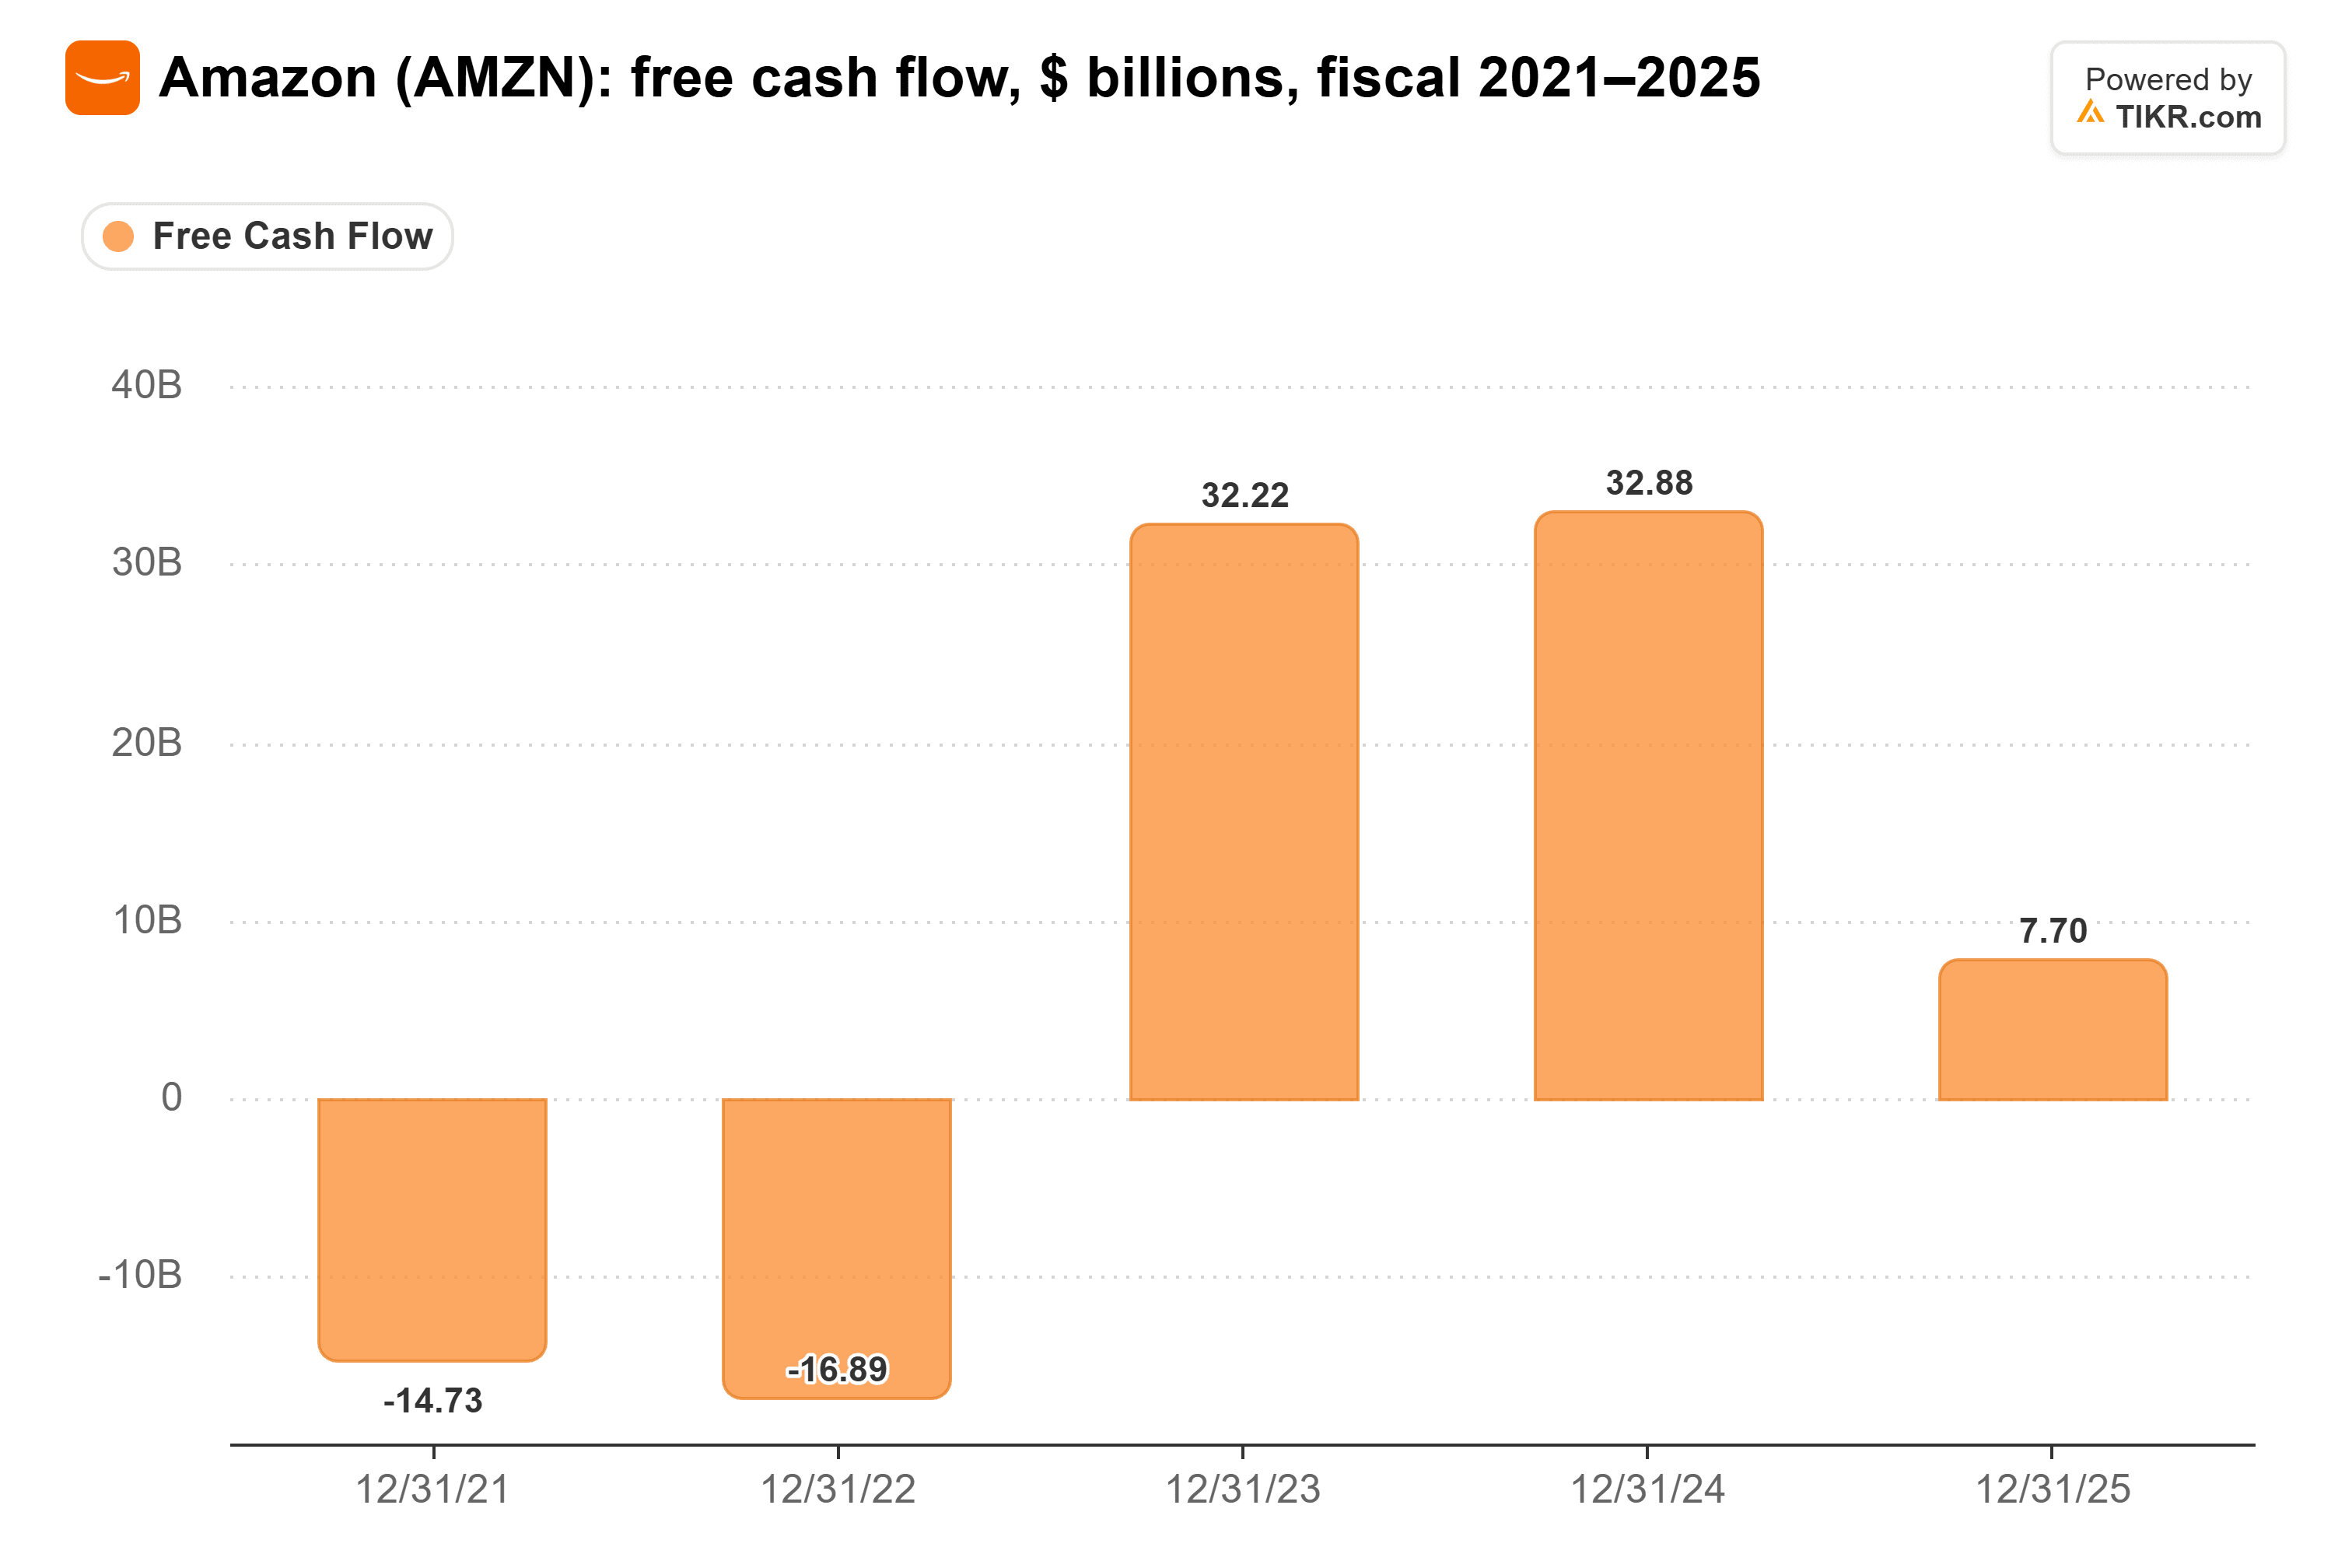
By Amazon’s own measure, free cash flow over the 12 months to Sept. 30 was a $42.4 billion outflow, against $7.6 billion three months earlier.
So every dollar of AI demand AWS keeps matters for when that spending pays back. Anthropic Direct won’t show up much in Anthropic’s own capex, though. The S-1 says it gets the chips through equipment leases and the buildings through leases too, so the build lands as long-term lease commitments rather than upfront spending.
The Contracts Are a Floor
AWS keeps that $110 billion either way. Anthropic’s S-1 says its long-term compute agreements oblige it to pay for capacity regardless of how much it actually uses, so for now Anthropic Direct adds data centers on top of what Anthropic already owes Amazon.
AWS isn’t short of buyers either. Jassy said on Oct. 23 that AWS capacity is largely sold out through 2027, with a good chunk of 2028 already spoken for.
The upside is what shrinks. AWS’s backlog more than doubled from $244 billion at the end of 2025 to $496 billion at June 30, 2026, as Anthropic and OpenAI each added $100 billion or more in commitments. That kind of jump from Anthropic gets harder to repeat once it fills its own buildings first.
Plus: Amazon owns a big piece of Anthropic, a stake it carried at $190.4 billion on June 30. Anthropic says running its own data centers could bring long-term cost advantages. Kedrosky says its margins only hold up if the computing cost of each token keeps falling. If owning its own data centers helps with that, Amazon gets some of the benefit back as a shareholder.
What Amazon’s Q3 Says About the Anthropic Risk
Amazon’s Oct. 29 results answered part of the question. AWS revenue grew 39% to $46.0 billion, its sixth straight quarter of faster growth, at a 38.7% operating margin. The backlog jumped to $578 billion from $496 billion in three months, and Jassy called it “well diversified.” He also projected AWS growth above 40% in both 2027 and 2028. Amazon didn’t say how much of that $82 billion came from the two labs.
Anthropic’s own data centers won’t hurt AWS this year or next, and the contract protects Amazon through 2036. They do cap what Amazon can expect from one of its two biggest AI customers. But a $578 billion backlog and a 40%-plus growth target for two more years say the bull case for AWS never rested on Anthropic alone. The cost is the cash: a $42.4 billion trailing outflow while that capacity gets built.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!