Key Takeaways
- Micron shares rose 5.2% to $977 after SK Hynix’s profit surge and its forecast that memory demand will outrun supply through 2030.
- Fiscal fourth-quarter revenue jumped 379% to $54.2 billion at an 86.8% gross margin, and Micron guided next quarter to $61.5 billion.
- The stock trades at 5.3x forward earnings because investors still price memory as a cycle that eventually turns.
- The December 16 report will show whether gross margin holds near 86% as capex and labor costs rise.
Micron Technology (MU) shares jumped 5.2% to $977 on Wednesday, and the push came from Seoul.
SK Hynix (A000660) posted a profit surge and forecast that memory demand will keep outrunning supply through 2030. When your biggest rival says the shortage has four more years to run, your stock tends to catch a bid.
Micron didn’t need the reminder. Its own numbers from late September were already extraordinary by memory standards.
Yet the stock still sits about 22% below its 52-week high of $1,255. Investors keep treating each record quarter as a possible peak.
Seoul backs up Micron’s numbers
Micron’s fiscal fourth quarter, which ended September 3, rewrote the record book:
- Revenue rose 379% to $54.2 billion, ahead of the $51 billion consensus.
- Adjusted EPS of $33.42 beat the $31.60 estimate.
- Gross margin reached 86.8%, up from 44.7% a year earlier.
Full-year revenue hit $133.2 billion, up 256%. And the guide went higher still: $61.5 billion of revenue next quarter, plus or minus $1.5 billion, against a $57 billion consensus.
“Micron delivered record fiscal 2026 results, and we expect an even stronger fiscal 2027,” CEO Sanjay Mehrotra said in the release.
Here’s how quickly the margin expanded…
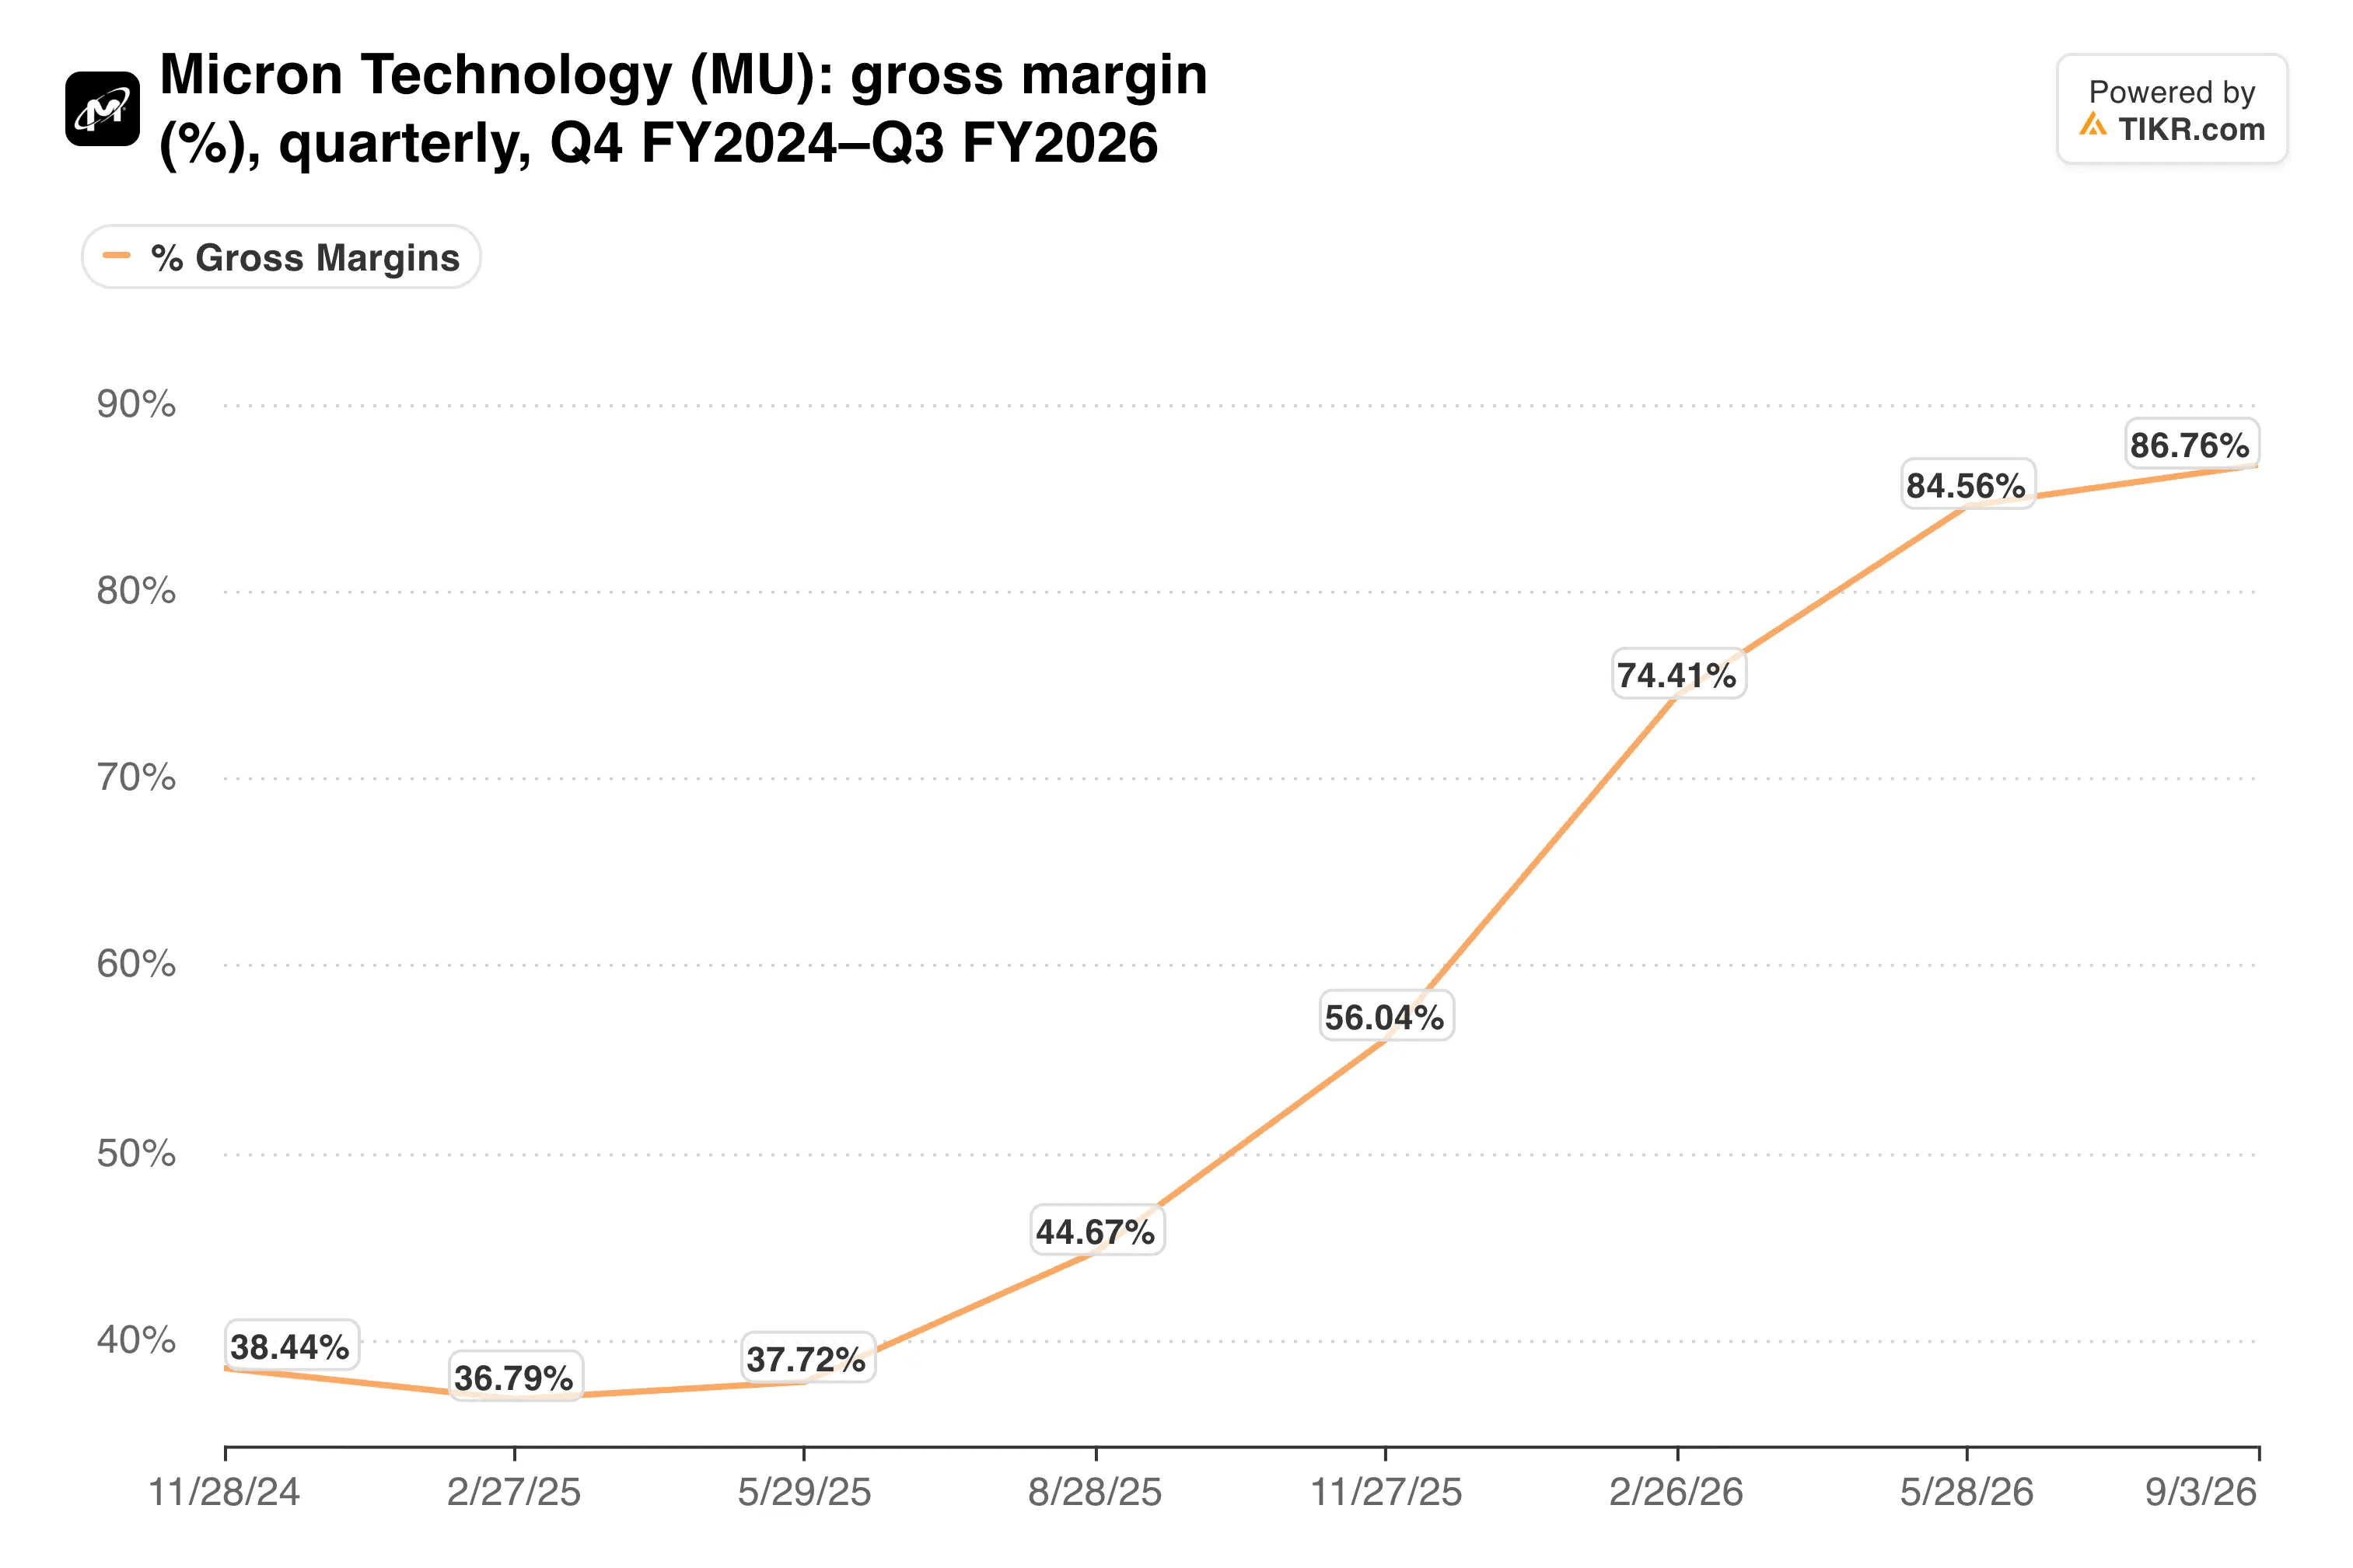
Gross margin nearly doubled in four quarters, and Micron guided it to about 86.25% next quarter.
Sold out before the year starts
More than 75% of Micron’s 2027 output is already committed. Long-term customer commitments climbed to $32 billion, from $22 billion in June.
Management expects supply and demand to be “much tighter” in fiscal 2027 and 2028 than in 2026. It also says it can’t yet see when the market rebalances.
Pricing explains the profits. DRAM prices rose about 180% in fiscal 2026 and NAND about 200%, so a memory maker now earns a fatter gross margin than Taiwan Semiconductor Manufacturing (TSM), which posted 66.4% last quarter.
So what does the Street expect from here?

If SK Hynix is right about 2030, the outer years of those estimates look too low.
TIKR tracks 49 analysts on Micron. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
The cycle still sets the multiple
At $977, Micron trades at 5.3x forward earnings and 4.0x forward EV/EBITDA. That’s the price of earnings the market expects to shrink.
Korea’s memory makers get the same treatment:

Memory stocks have stayed at single-digit multiples through this whole boom, so the discount reflects the industry’s history.
Costs are rising, too. Micron plans about $11.5 billion of capex in the first quarter and $25 billion in the first half, while operating expenses climb about $2.5 billion for the year.
Labor is the newest line item. After pressure from Taiwan unions, Micron launched a global quarterly bonus tied to profits, paid half in cash and half in shares. The Taichung union accepted the framework, but the Taoyuan union staged a one-day strike and wants a transparent 15% of operating profit.
My take: Micron is the cleanest way to own the memory shortage, and 5.3x earnings leaves plenty of room for error. Still, a 15% profit-share demand shows that record margins attract claims from employees, customers and rivals adding capacity. I’d keep owning it while contracts cover 2027.
Micron reports fiscal first-quarter results on December 16. Watch whether gross margin lands near the 86.25% guide and whether long-term commitments grow beyond $32 billion.
So what is Micron stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!