Key Takeaways
- Cipher Digital shares have fallen 77% from their June high, and J.P. Morgan cut its target to $18 from $22 on Tuesday while keeping its Overweight rating.
- The $18 target is 162% above the last close, and analysts expect revenue to nearly quadruple in 2027 as data center rent starts.
- Analysts have cut their 2027 earnings estimate by more than half in three months, while Cipher’s long-term borrowings doubled this year and its share count kept rising.
- A rebound looks reasonable, but $18 looks too high for the next year, and Wells Fargo’s $15 is the better one-year bet.
Cipher Digital (CIFR) has lost 77% of its value since its June high. J.P. Morgan just cut its target, but its new $18 is still 162% above the last close of $6.86.
Three blows since late September
On Sept. 25, Cipher doubled its Barber Lake lease to 20 years, lifting the site’s contracted revenue to about $9.1 billion. But Cipher agreed to pay the first $359.3 million of any cost overruns there and to front everything above that, with the tenant paying back half as rent over 20 years. And Wells Fargo estimates the site will cost nearly $3 billion, up from an original budget of about $2.16 billion.
Then, on Oct. 14, Cipher priced $850 million of 0% convertible notes due 2032. It also swapped $165.9 million of older notes for about 40.7 million new shares.
Monday’s third-quarter report showed the gap before the rent arrives. Revenue fell to $26.7 million from $71.7 million a year earlier as bitcoin mining shrank. Just $5.9 million came from Cipher’s first data center lease, and adjusted EBITDA was a $10 million loss.
J.P. Morgan trims, but stays bullish
J.P. Morgan analyst Richard Choe kept his Overweight rating on Tuesday and cut his target to $18 from $22 after the report. Wells Fargo cut harder, to $15 from $25, and KBW’s target is down to $11, from $28 in August.
CEO Tyler Page made the bull case on Monday’s call: “we are building expressways for AI to come to market, and we are charging a long-term toll.”
TIKR Tracks 22 Analysts on Cipher Digital. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cipher Digital, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cipher Digital’s Analyst Ratings
Can the rent carry $18?
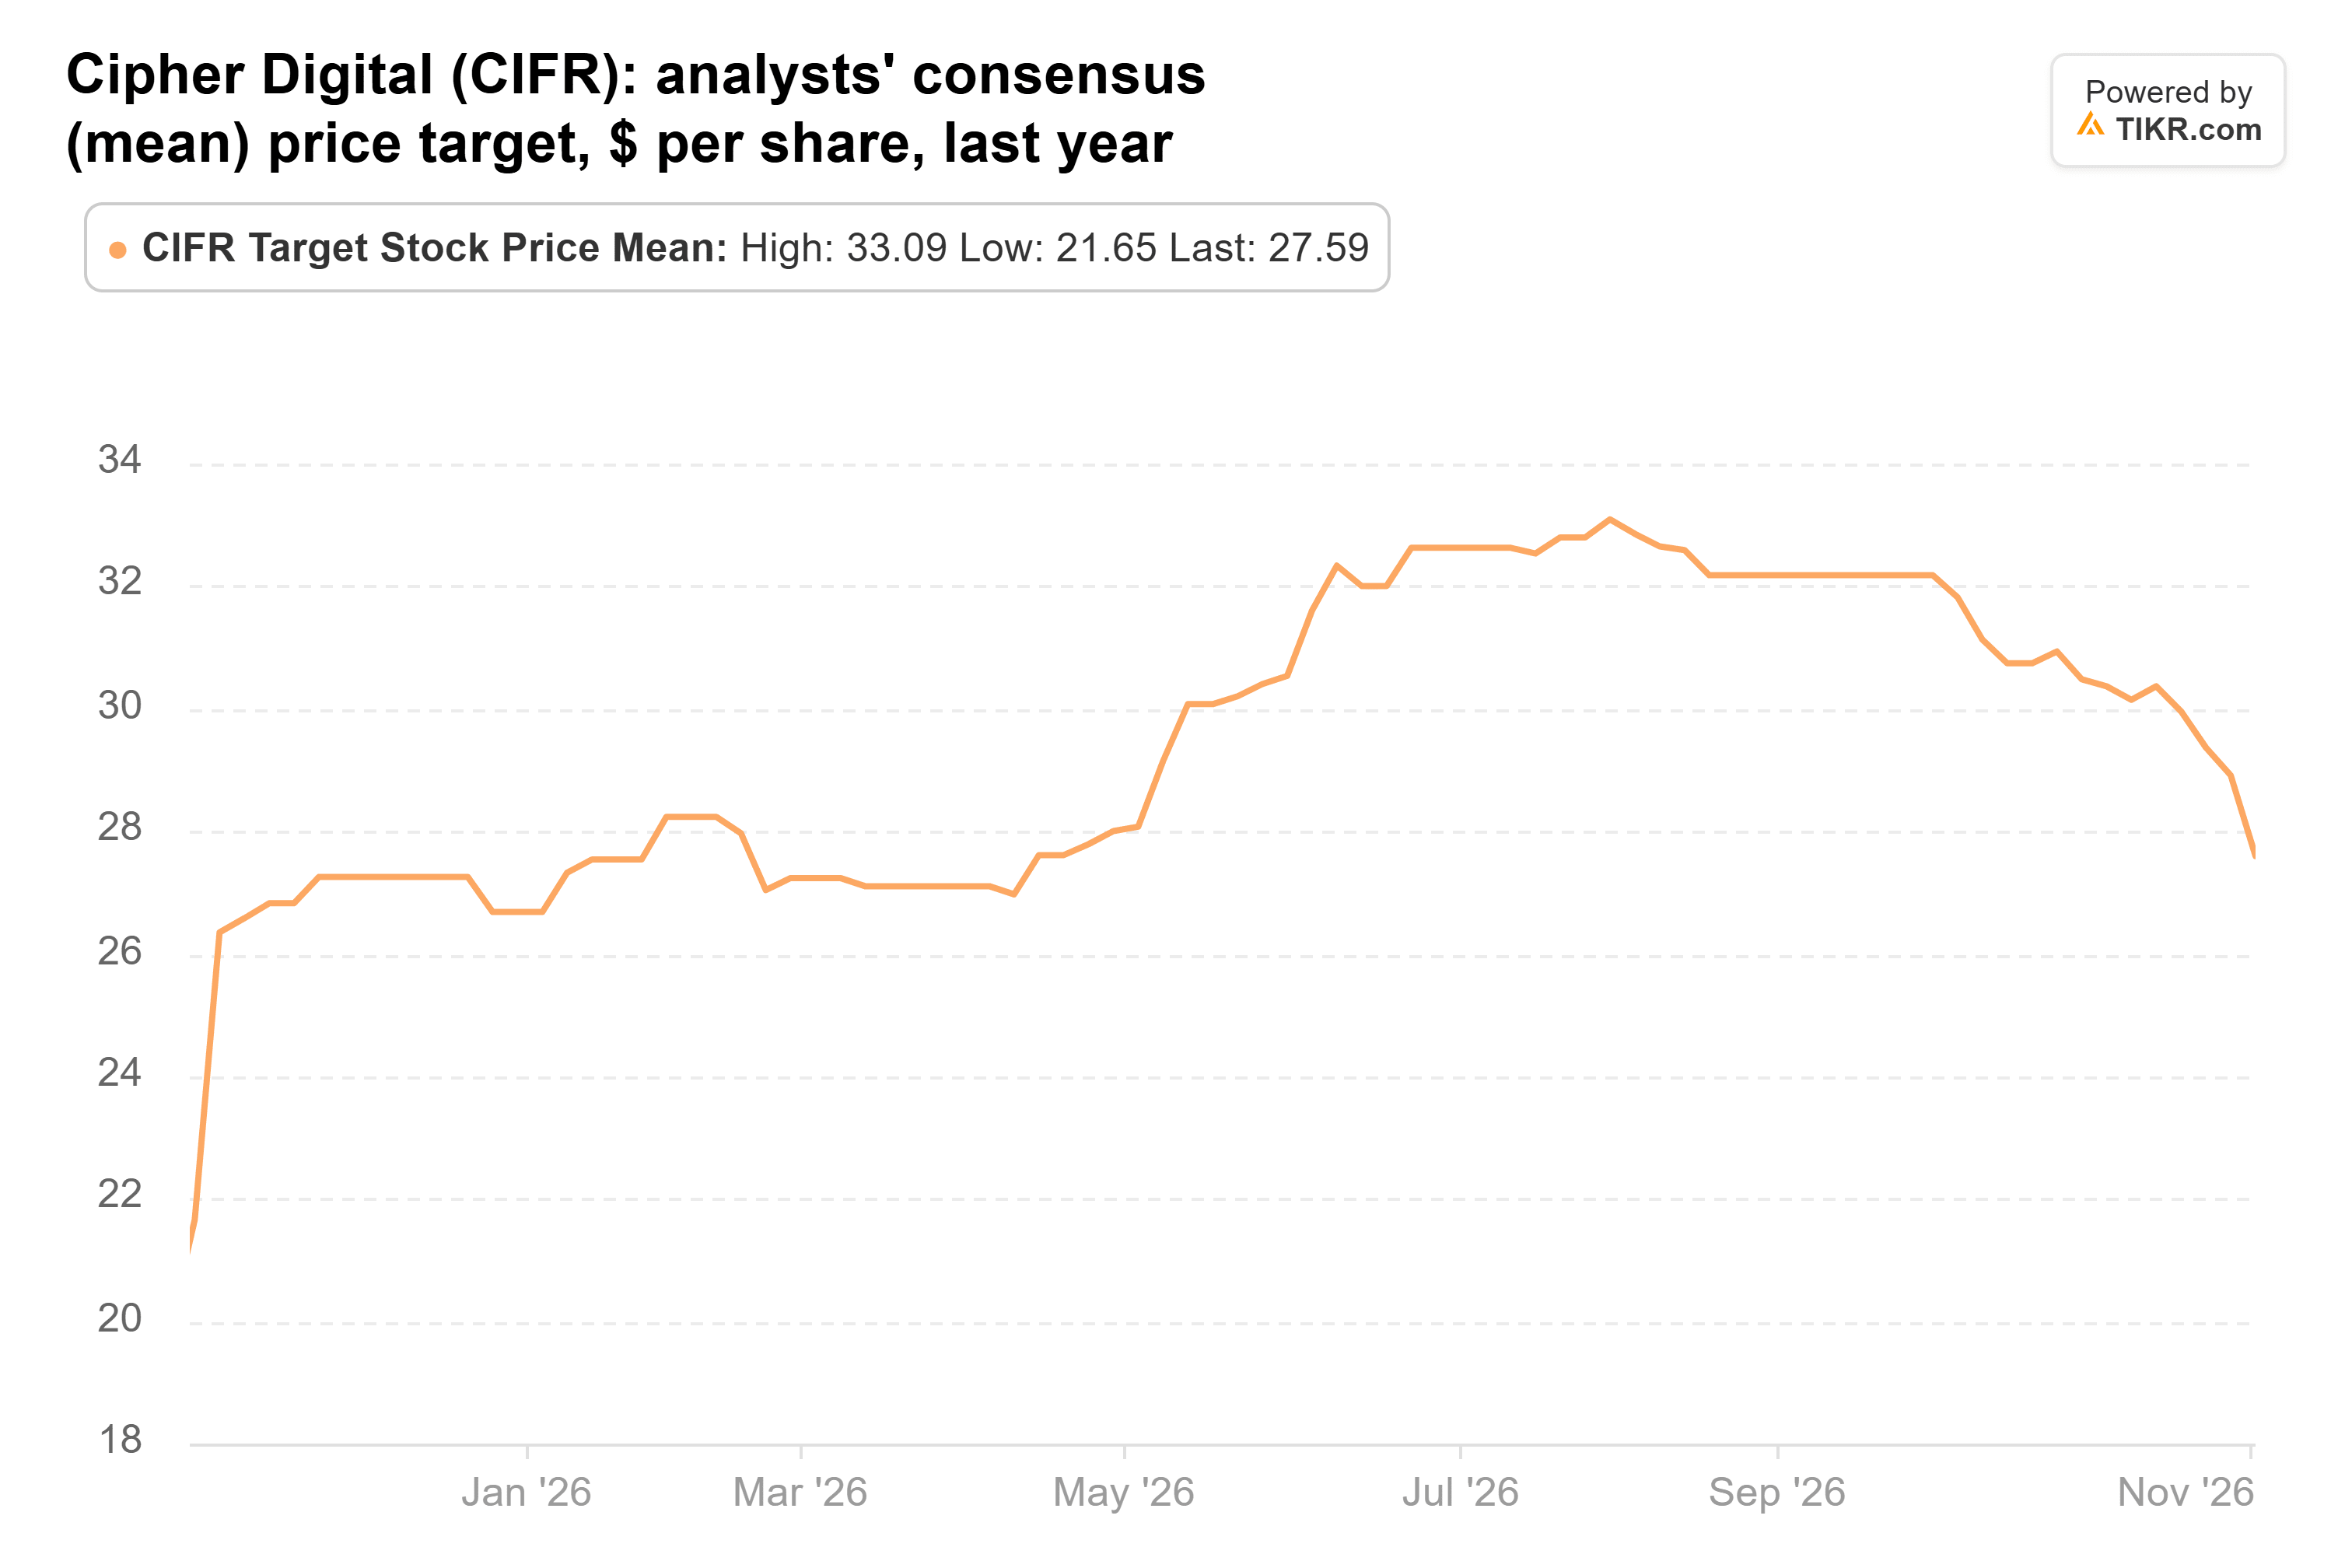
The Street’s average target has hardly moved while the stock collapsed. It’s $28 today, against $22 a year ago and a peak of $33 in early August.
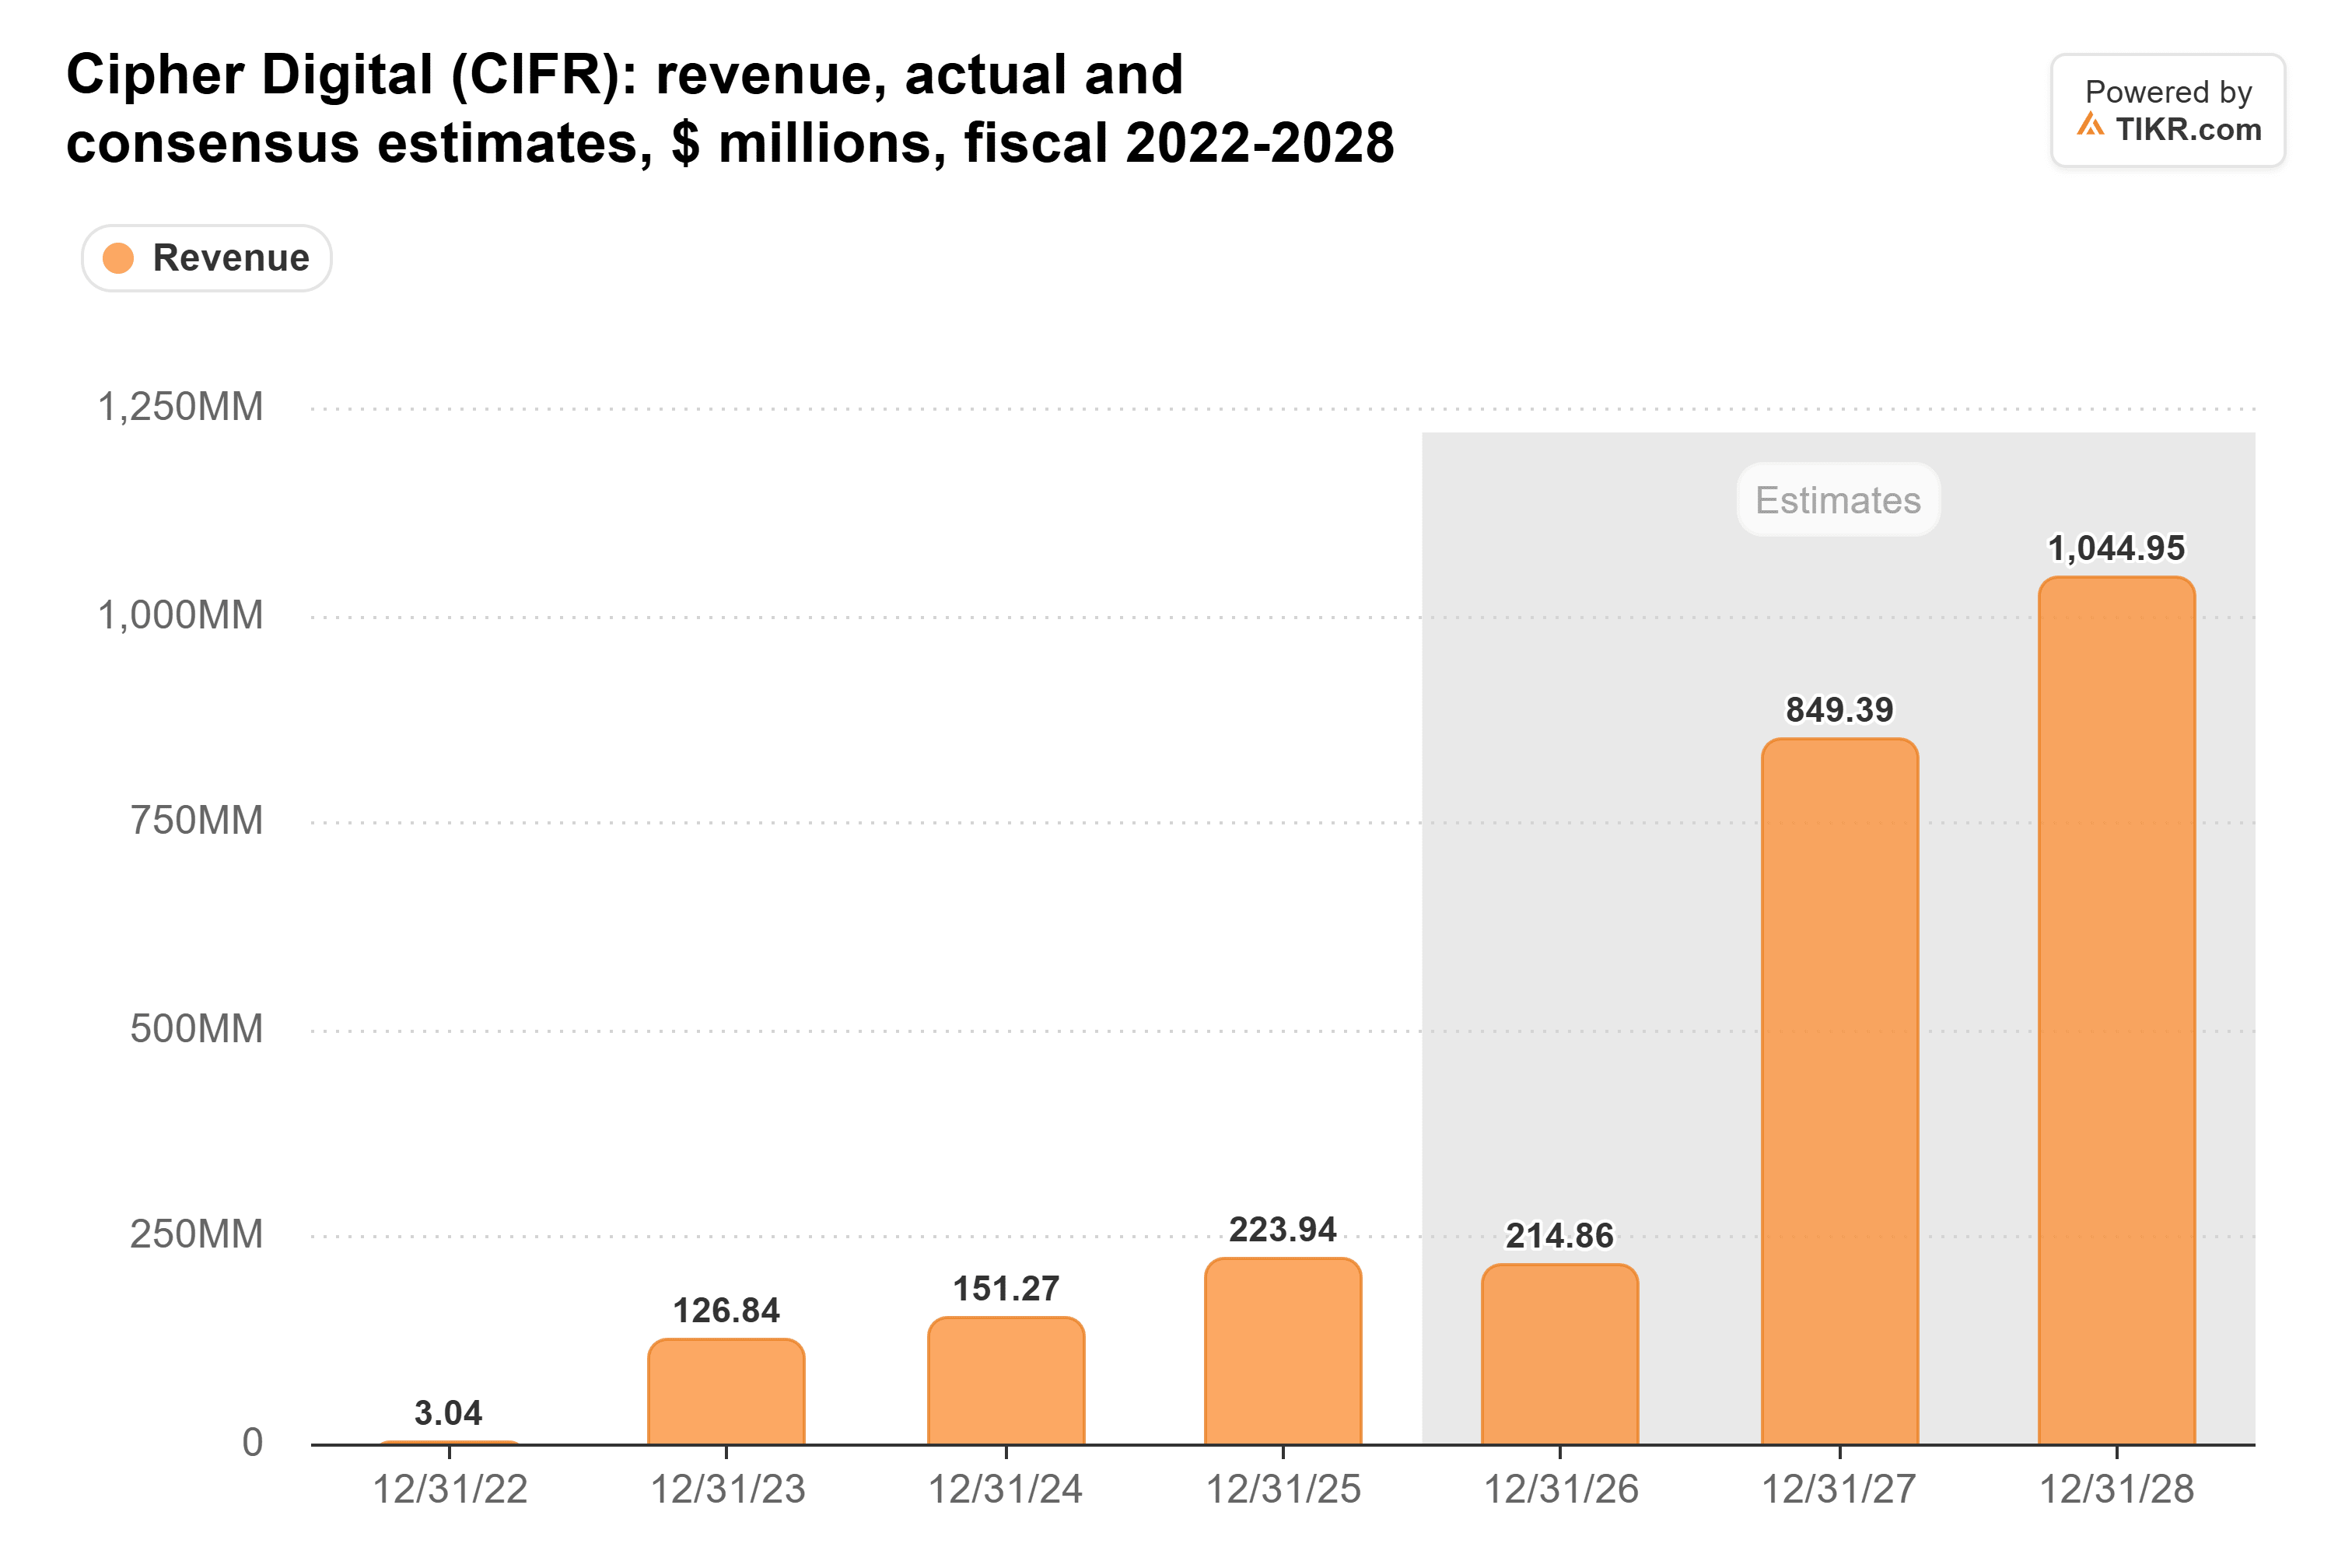
Analysts expect sales to nearly quadruple, from $215 million this year to $849 million in 2027, as rent starts at Black Pearl, Barber Lake and Stingray.
But the 2027 EPS estimate has fallen to $0.22, from $0.52 three months ago. And Cipher’s long-term borrowings doubled this year, to $5.4 billion at Sept. 30.
J.P. Morgan’s $18 works out to 480x the roughly $0.04 a share analysts expect over the next twelve months, against 183x at the last close.
Barber Lake’s tenant backstop also came with warrants guaranteeing $435.0 million of value on about 26.2 million shares. If those shares are worth less than that when the lease commences, Cipher owes the difference in more shares or cash. At $6.86, that’s about $255 million, or roughly 37 million new shares if Cipher pays in stock. The break-even is about $16.60 a share, and J.P. Morgan’s $18 sits just above it.
The rent is real, and some rebound from here looks reasonable. But $18 needs earnings estimates to stop falling and the share count to stop climbing, and I don’t see either happening within a year. Wells Fargo’s $15 looks like the better one-year bet.
What would change my mind: a fourth lease at Reveille, Ulysses or Odessa, with project bonds paying for most of the build.
So what is Cipher Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cipher Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!