Key Takeaways
- Palantir shares fell 4% today after third-quarter revenue rose 96% but total contract value grew just 6%.
- The bookings slowdown looks more like shorter deals than fading demand.
- ServiceNow’s latest results show big buyers still signing, while Snowflake’s backlog is growing slower than its revenue.
- U.S. commercial remaining deal value, up just 4% from June, is the figure to watch in Palantir’s next report.
Palantir Technologies (PLTR) is down 4% today, even after revenue nearly doubled in the third quarter. The catch: new contracts grew just 6%.
If big U.S. companies are getting cautious about long AI contracts, ServiceNow (NOW) and Snowflake (SNOW), which sign the same buyers to multi-year deals, should feel it too.
A blowout with one soft spot
Revenue rose 96% to $2.31 billion, well ahead of the $2.18 billion analysts expected. And Palantir raised its 2026 revenue guidance to $8.53 billion, against a consensus of $8.22 billion.
But total contract value, the lifetime value of deals signed in the quarter, rose just 6% to $2.92 billion. U.S. commercial TCV grew 11%, and U.S. commercial remaining deal value, what’s left on signed contracts, rose only 4% from June, to $6.52 billion.
CEO Alex Karp said on Palantir’s third-quarter call that the market for its AI software is “much larger than we can service.”
Shorter deals, most likely
Piper Sandler wrote Monday that it believes the 11% is “a fluke of duration”: customers signed shorter contracts, which shrinks TCV without shrinking what they spend each year.
I agree. U.S. commercial remaining deal value is still up 79% from a year earlier, and analysts expected revenue to keep climbing fast going in:
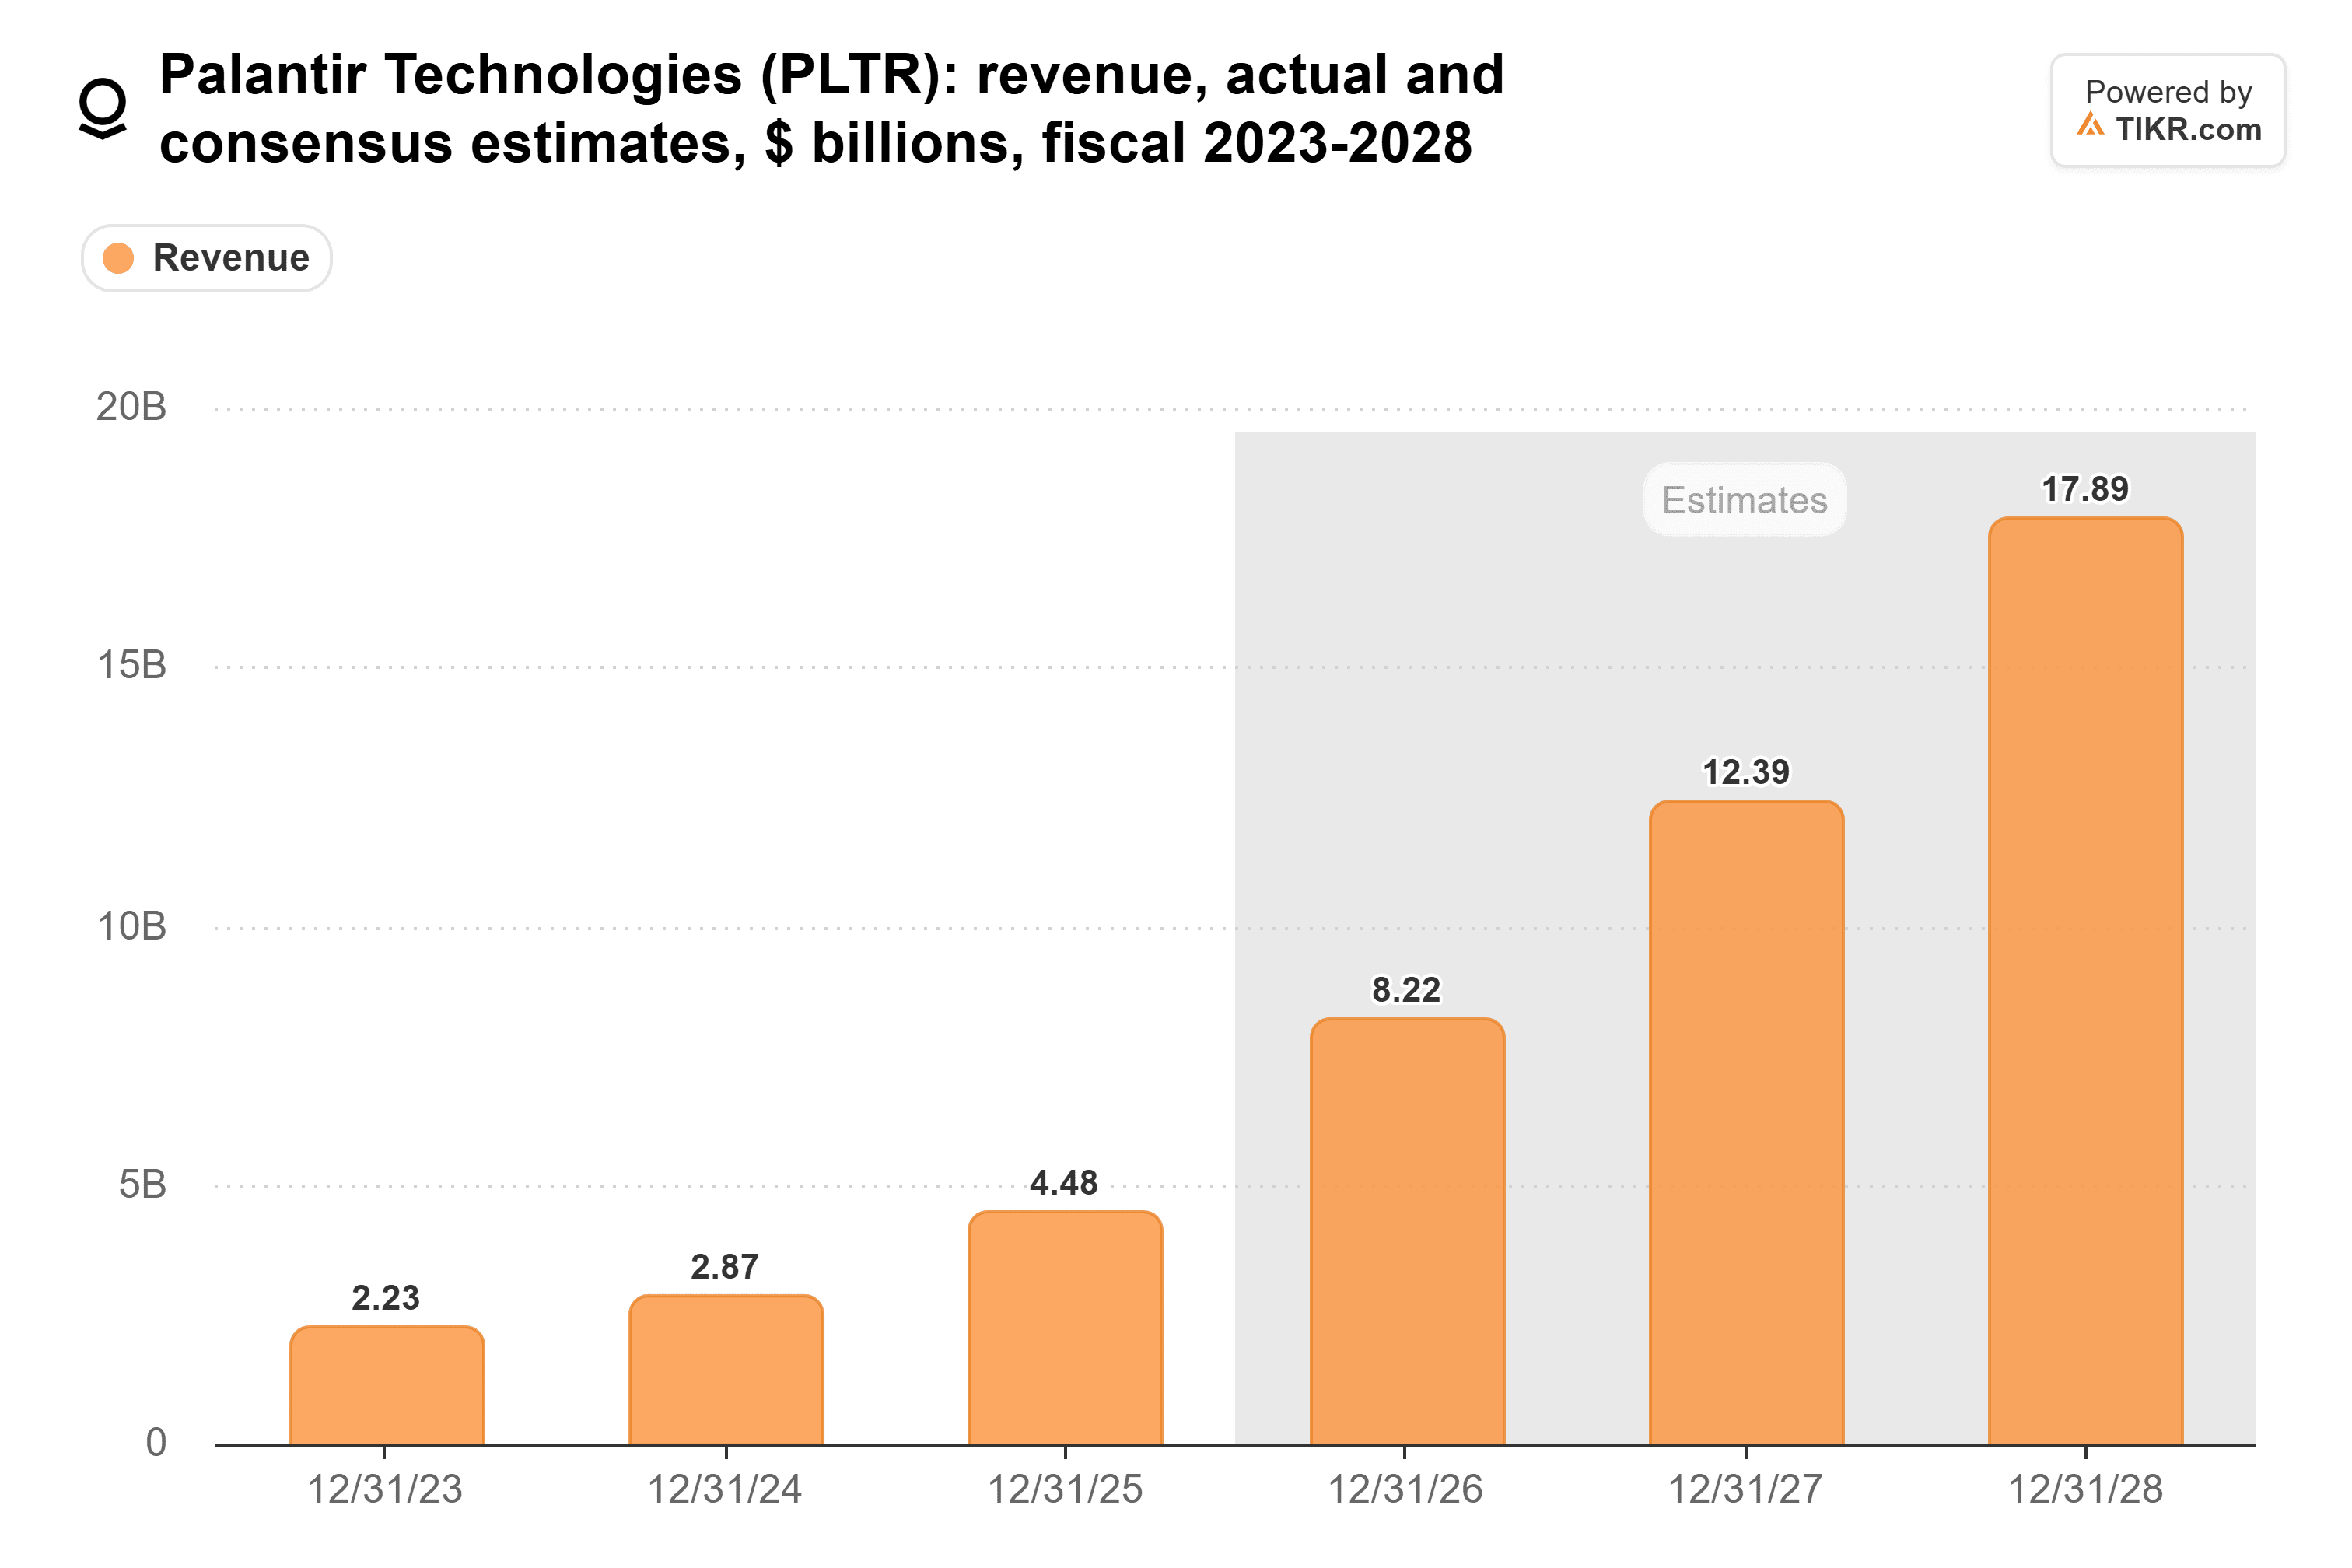
The new guide already tops their 2026 number, and nothing in this report makes me expect cuts to the $12.4 billion they see for 2027.
Nor is Palantir priced for perfection by its own standards. It traded at 94x forward earnings at Monday’s close, below its five-year average of 102x:

At today’s price, it’s even lower.
TIKR tracks 32 analysts on Palantir. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palantir, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palantir’s Analyst Ratings
ServiceNow’s buyers are still signing
Last week, ServiceNow reported current remaining performance obligations up 20.5% to $13.65 billion for the quarter to Sept. 30. It also closed 19 deals worth more than $5 million in net new annual contract value, more than double a year earlier. Big buyers there don’t look cautious.
Snowflake looks more like Palantir. Its remaining performance obligations grew 30% in the quarter to July 31, slower than its 37% product revenue growth. If that gap widens when Snowflake reports on Dec. 2, Palantir’s slowdown starts to look less like a one-off.
An overreaction, for now
Today’s drop looks like an overreaction to me. Of course, if U.S. commercial remaining deal value barely grows again in early February, when Palantir also guides for 2027, I’d have a much harder time calling it timing.
So what is Palantir stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palantir could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!