Key Takeaways
- Barclays upgraded Bloom Energy to Overweight on Nov. 3, even though it cut its price target to $289, which is 35% above the stock price.
- Bloom’s third quarter brought record revenue and a third guidance raise, but cash flow turned negative as unbilled revenue piled up.
- Barclays’ case rests on customer deposits, which rose to $661 million at Sept. 30 from $78 million at the end of 2025.
- Barclays’ target works out to 59x forward earnings, below Bloom’s three-year average of 76x, so the call looks right if the cash catches up with the profits.
Bloom Energy (BE) has fallen 38% from its June 22 closing high, even after the best quarter in its history. On Nov. 3, Barclays upgraded the stock to Overweight from Equal Weight, though it cut its price target to $289 from $316. That’s still 35% above today’s $213.36 share price.
The cash went the other way
The trouble started in July, when a short seller alleged that Bloom’s scandium comes from China, which Bloom disputes. A securities class action followed.
Then came the third-quarter report on Oct. 22. Revenue rose 138% to $1.24 billion, and Bloom raised its 2026 revenue guidance for the third time this year, to between $4.4 billion and $4.6 billion.
But operating cash flow was a use of $27 million, and free cash flow a use of $181 million, as contract assets (revenue Bloom has booked but not yet billed) jumped $430 million in the quarter. CFO Simon Edwards said on the call that the cash use is “not the beginning of a trend.”
Investors didn’t wait to find out. The stock sank the day after the report, and Jefferies cut its target to $242 from $289, keeping a Hold rating.
TIKR tracks 29 analysts on Bloom Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
Barclays is watching the deposits
Barclays analyst Christine Cho, who had raised her target to $316 a week earlier, now argues Bloom’s backlog is growing faster than she assumed. She points to its faster capacity build, new supply commitments and rising customer deposits.
The deposits stand out. They rose to $661 million at Sept. 30, from $78 million at the end of 2025, and Cho called that “potentially one of the clearest indications yet” of a pickup in customer commitments.
That’s nearly as much as contract assets grew over the same nine months, to $859 million from $241 million.
Does $289 add up?
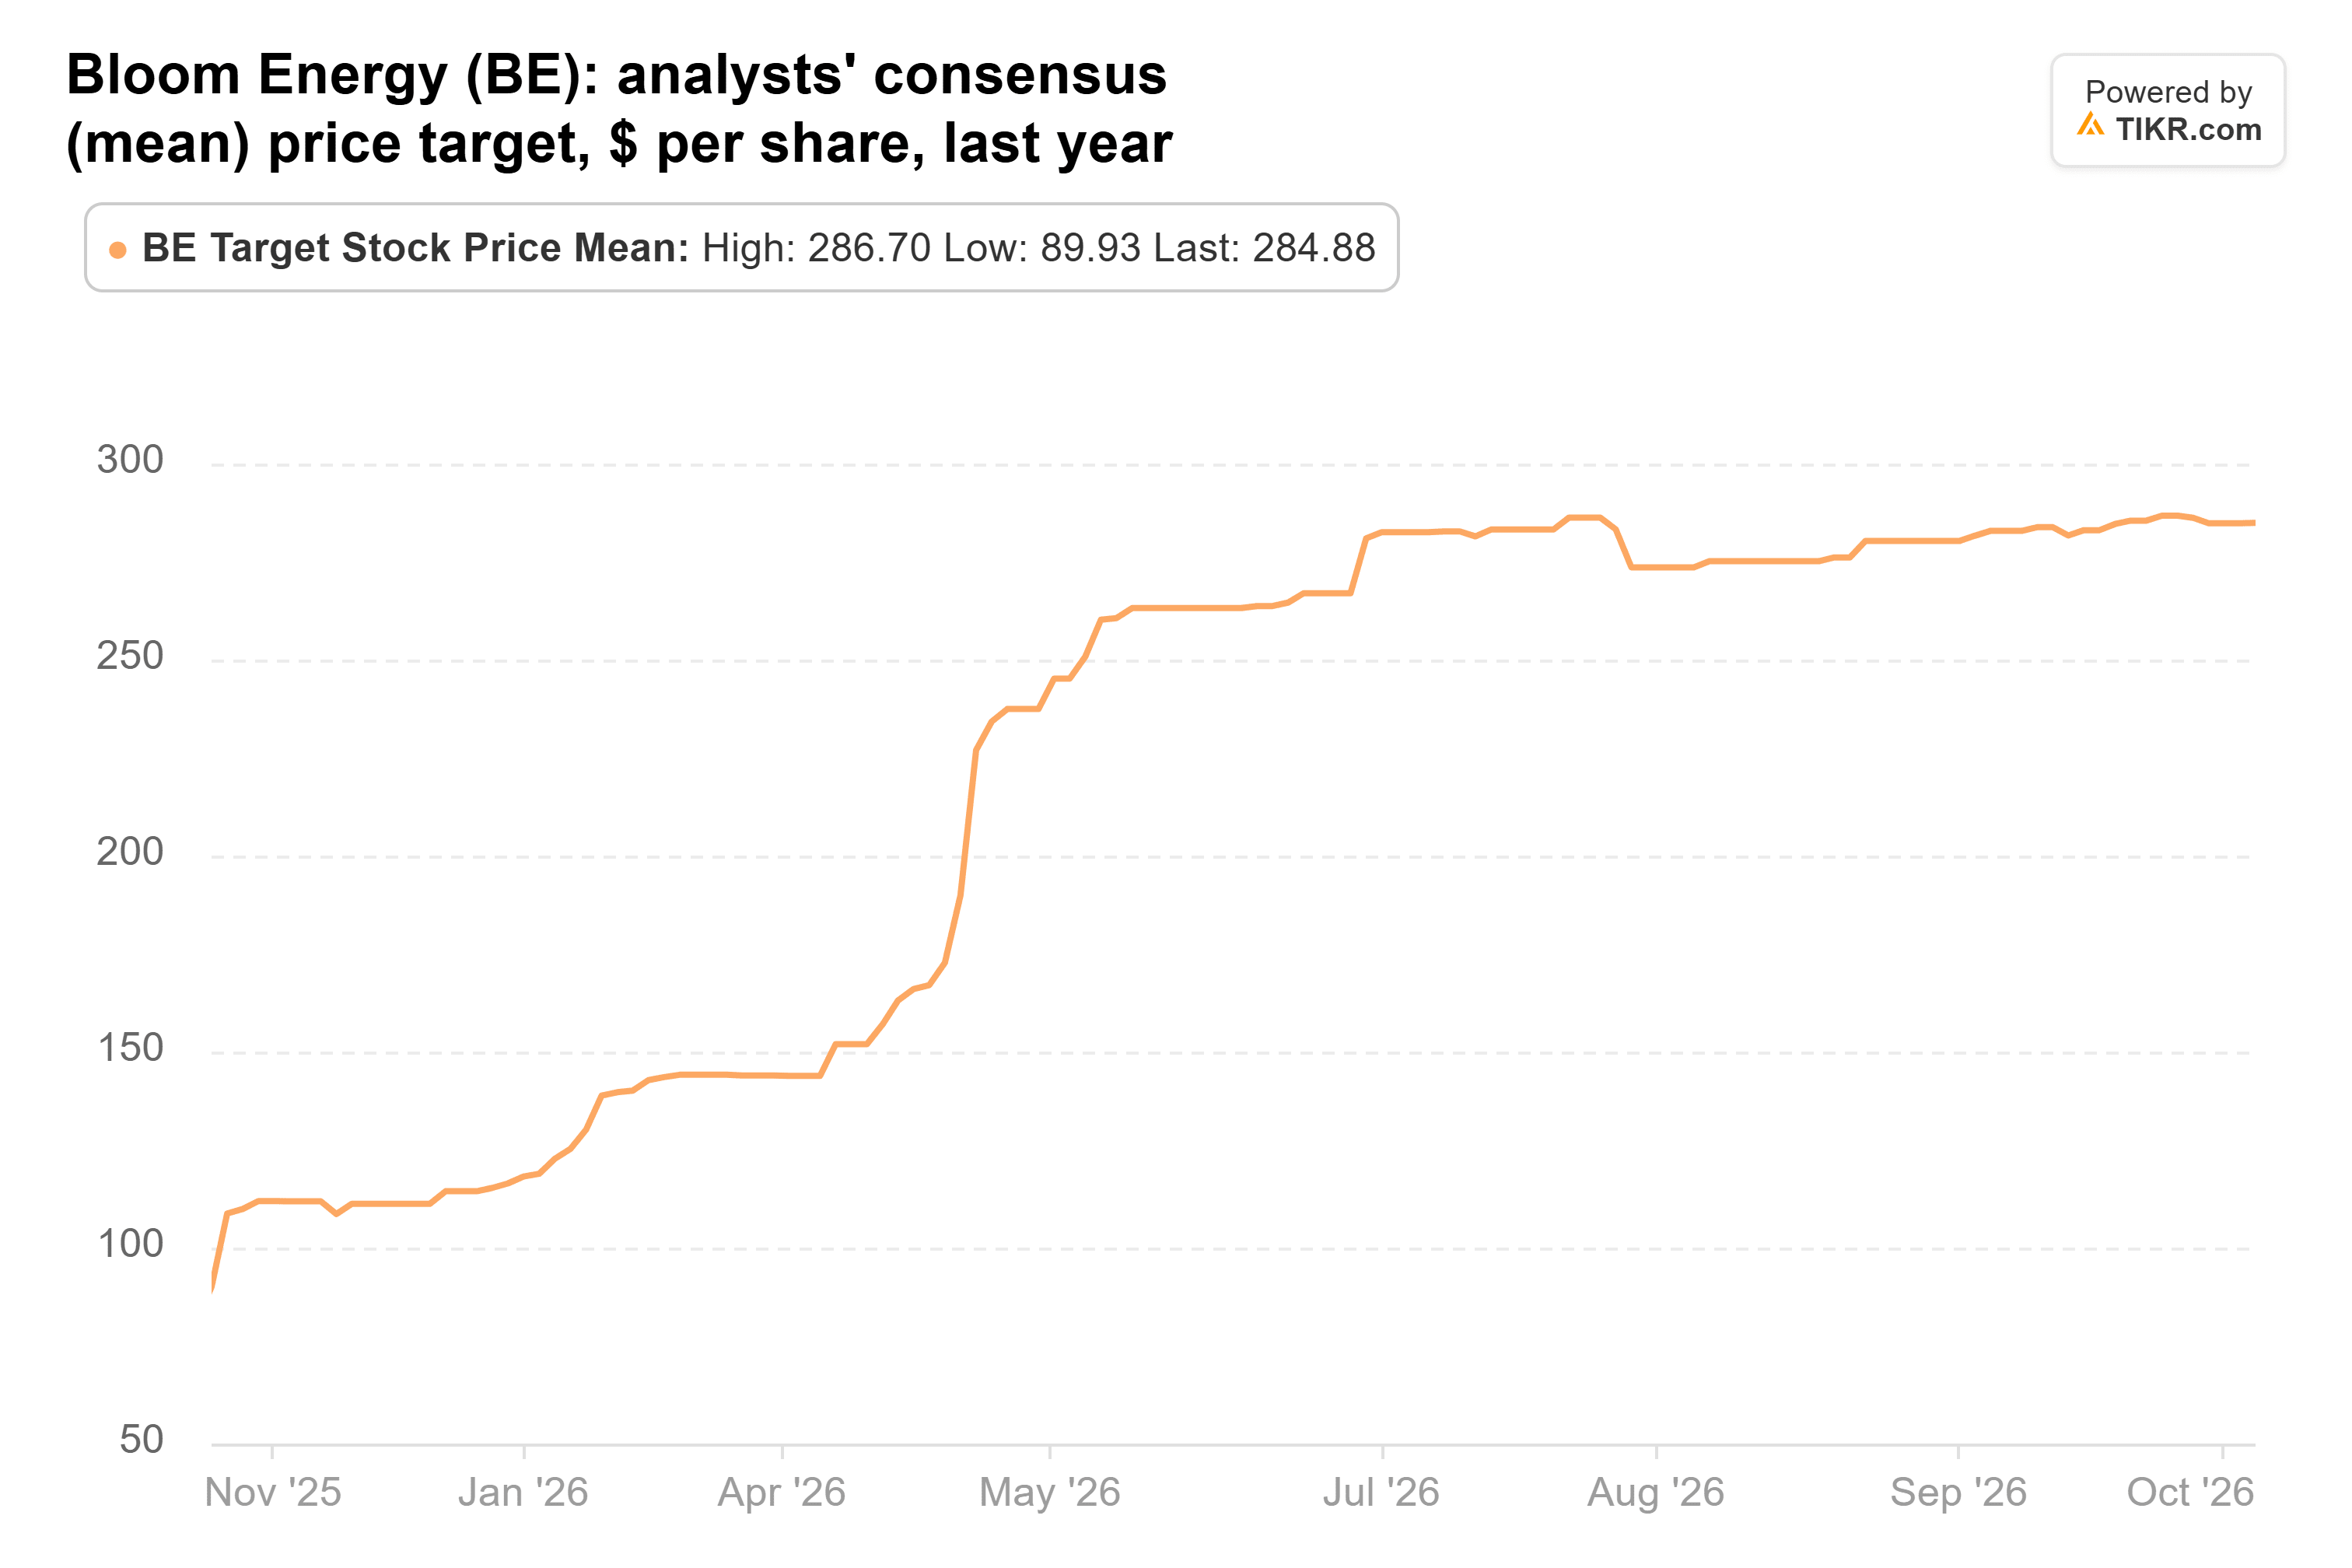
Barclays’ target is almost exactly the Street’s: the consensus target is $285, up from $90 a year ago, and 29 analysts cover the stock, with targets from $102 to $380:
Analysts expect normalized EPS to climb from $0.76 in 2025 to $3.27 this year and $8.24 in 2028:

The 2026 figure was $2.69 a month ago, before the guidance raise. If Cho is reading the deposits right, I’d expect the later years to keep rising too.
At $213.36, Bloom trades at about 43x forward earnings. Barclays’ $289 works out to 59x the same earnings, below the 76x Bloom has averaged over the past three years.
The cash still has to show up
Two customers took 69% of Bloom’s third-quarter revenue, so a delay at either one would hit its collections hard.
Even so, I think Barclays has this one right. At $289, Bloom would still trade below its three-year average multiple, on estimates that keep rising.
The fourth-quarter report, due early next year, should show us whether contract assets are turning into cash. Bloom had $42 million of free cash flow through September, and another negative quarter would likely make investors wait longer.
So what is Bloom Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bloom Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!