Key Takeaways
- Qualcomm reports its fiscal fourth quarter after the close on Wednesday, Nov. 4, after a week of headlines about Anduril’s U.S.-made laptop and renewed attention on its stake in AI startup Hark.
- Those deals are too small to show up in next year’s numbers, so data center chips have to carry Qualcomm’s growth in fiscal 2027.
- Analysts expect fiscal 2027 revenue of $44.9 billion, only $2 billion more than this year. Operating margin fell to 18.5% in the June quarter.
- The stock trades at 18x forward earnings against a five-year average of 14x, so the December-quarter guide needs to show data center revenue arriving on schedule.
Qualcomm (QCOM) has spent the past week in headlines that have little to do with phones.
Last week, on Bloomberg Tech, Anduril founder Palmer Luckey talked up BlueChip, a rugged laptop Anduril aims to eventually build entirely from U.S.-made parts. Qualcomm is supplying its CPU, GPU and NPU. Luckey’s pitch went past the laptop: “Qualcomm has announced that they’re going to be making the chips in Arizona.” Qualcomm CEO Cristiano Amon confirmed it, saying TSMC (TSM) will make the Snapdragon X chips at its Arizona plants.
Qualcomm is also among the backers of AI-assistant startup Hark. Its venture arm joined Nvidia (NVDA), AMD (AMD) and Intel (INTC) in Hark’s $700 million Series A in May, at a $6 billion valuation.
These are good headlines, but there are no numbers behind them yet. No revenue figure came with the Anduril deal. And whatever Qualcomm put into a $700 million round is tiny next to more than $40 billion of yearly sales.
Analysts aren’t counting on a big fiscal 2027
Analysts expect fiscal 2027 revenue of $44.9 billion. That’s about $2 billion more than the $42.9 billion they expect for fiscal 2026, the year Wednesday’s report closes out, and barely above fiscal 2025’s $44.1 billion:

That’s a small step for a company that told investors at its June Investor Day to expect $5 billion of data center revenue in fiscal 2027. Custom chips for two hyperscalers are due to start shipping in the December quarter.
The gap comes from phones. On its July call, management said Apple revenue would fall by about half from the September quarter to December. It also said the memory crunch would cut its Android chip revenue by about 20% from a year earlier, a hit of more than $1.50 to EPS.. So analysts expect the new businesses to do little more than fill the hole phones are leaving.
TIKR Tracks 37 Analysts on Qualcomm. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Margins have to stop sliding
Qualcomm’s operating margin fell from 27.5% in the quarter to June 2025 to 18.5% a year later:
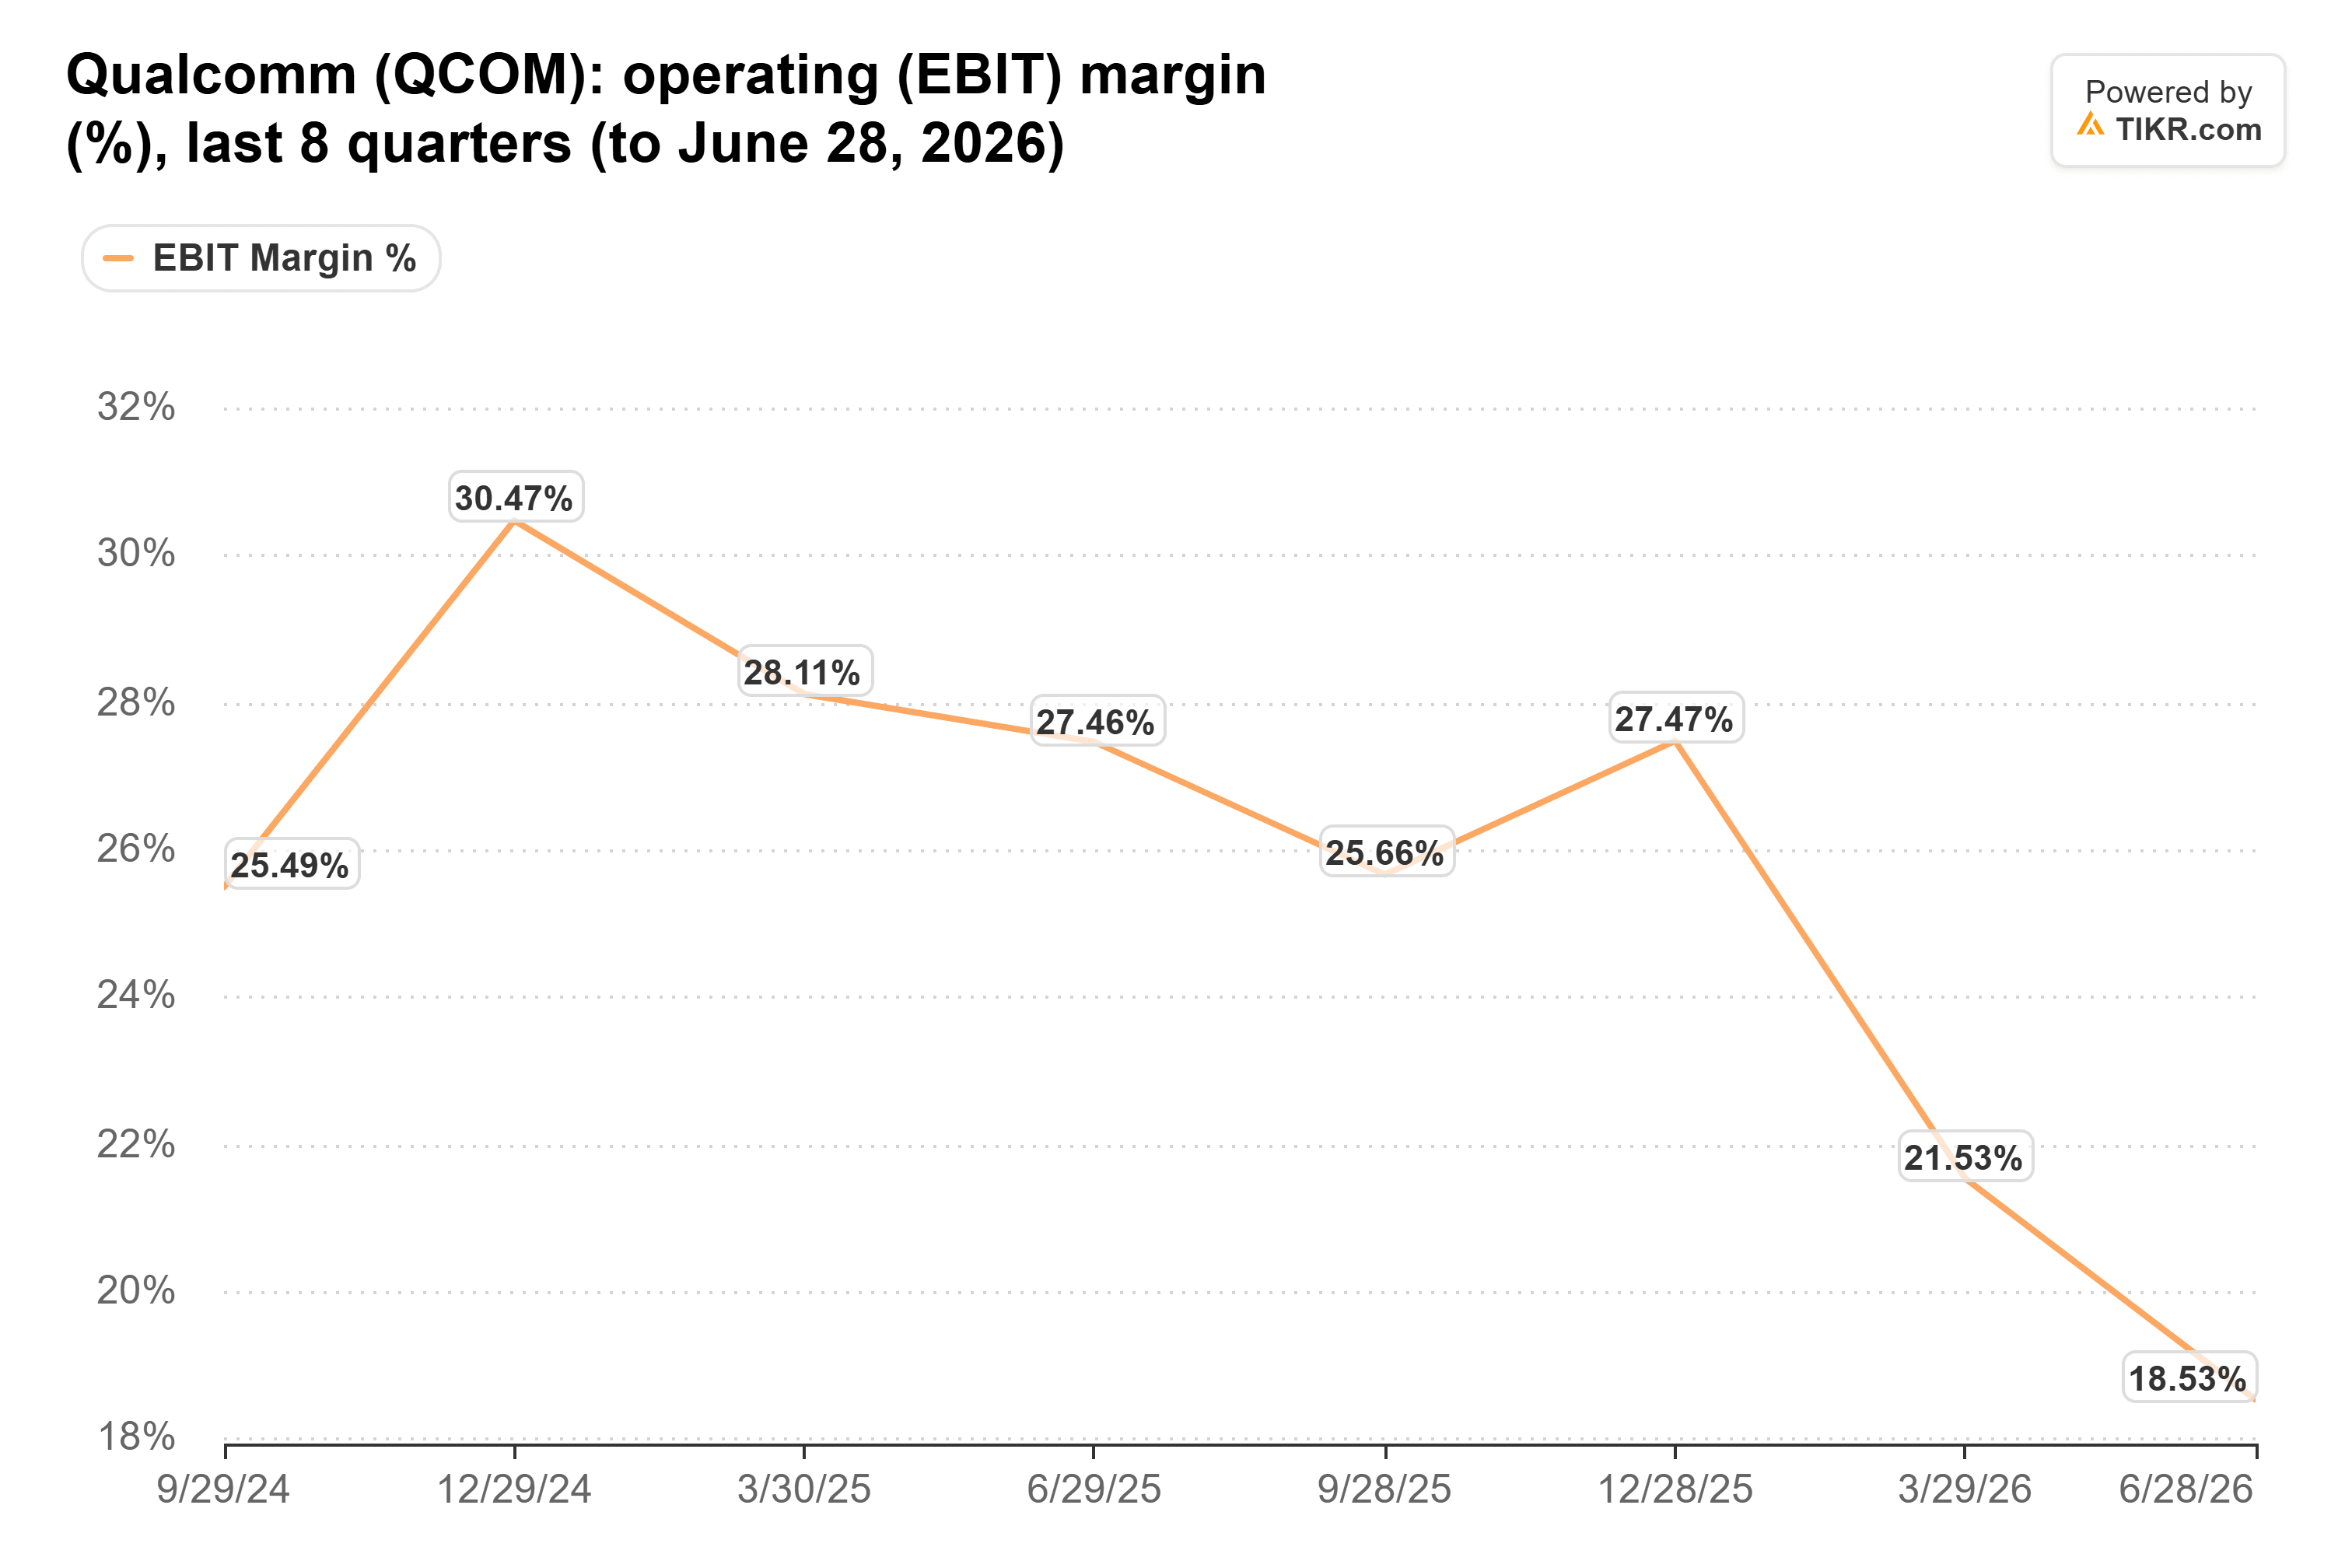
Management guided to about $2.7 billion of operating expenses for the September quarter. That’s 26% to 28% of guided revenue, against a long-term target of 19% to 20%. The global layoffs CEO Cristiano Amon outlined in an Oct. 19 memo are the first step toward closing that gap, with employee notifications starting in November.
18x already pays for the new businesses
Qualcomm trades at 18x forward earnings, well above its five-year average of 14x:
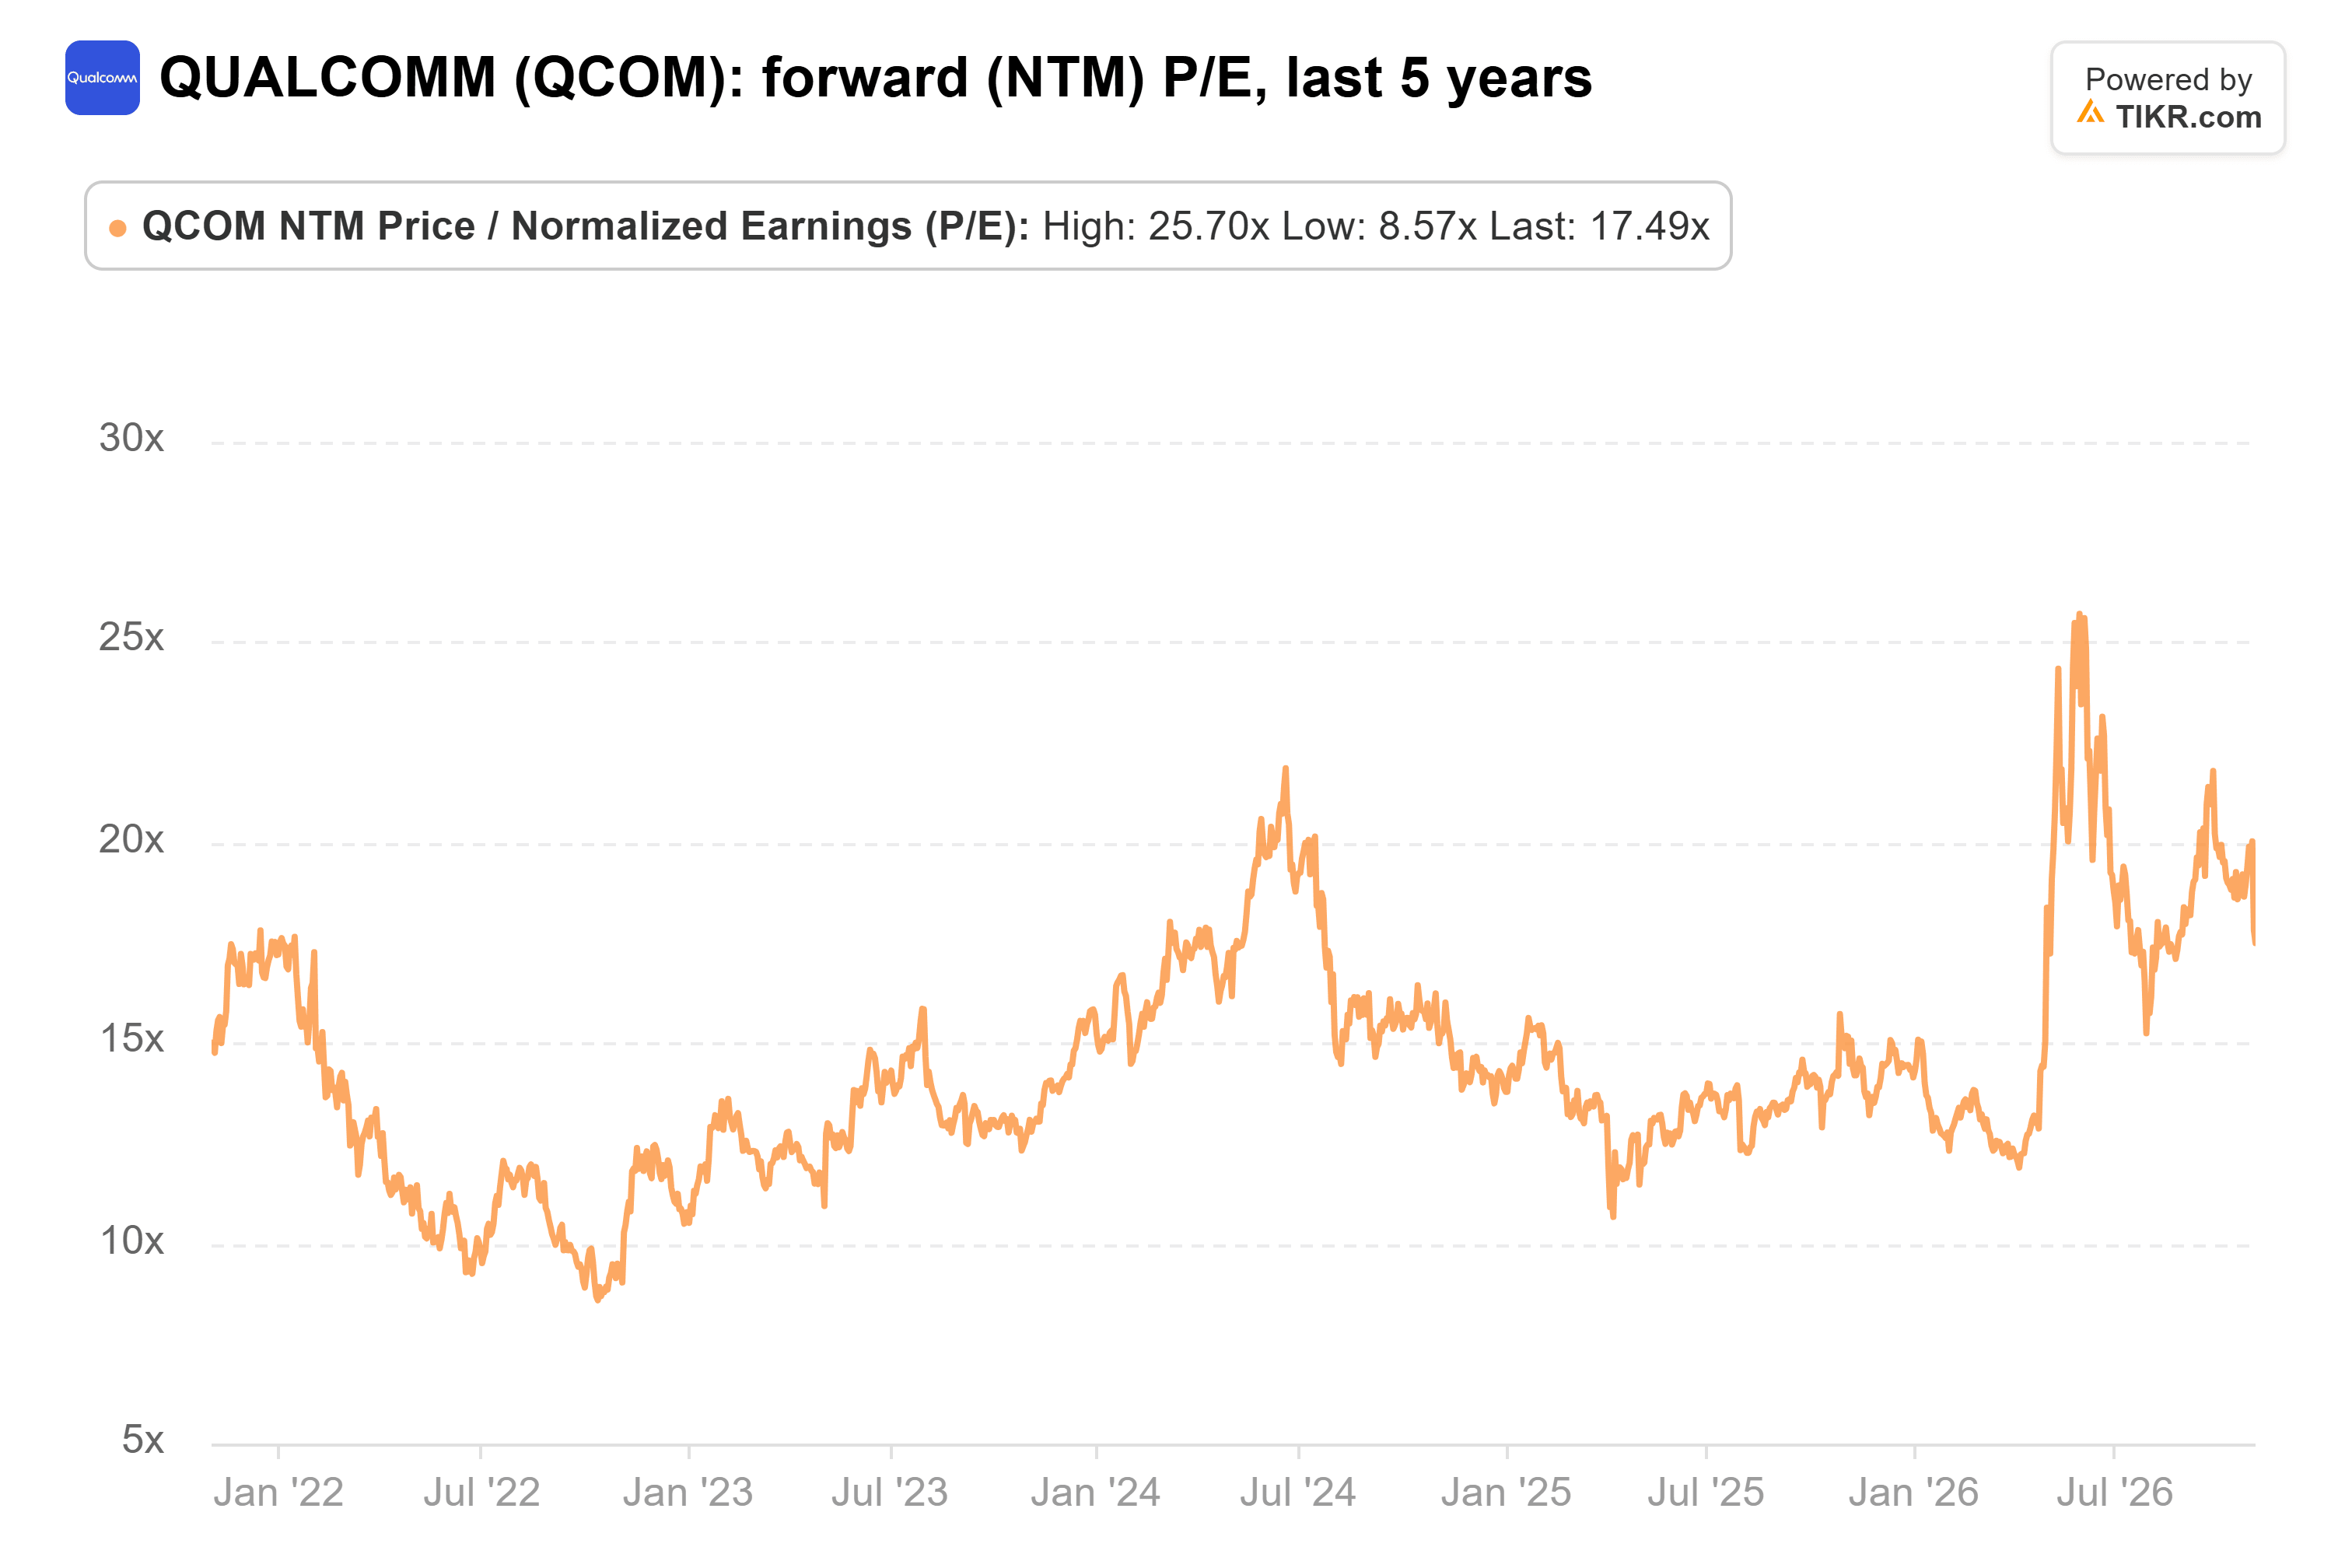
And analysts expect those earnings to shrink. Consensus normalized EPS for fiscal 2027 is $10.19, below the $12.03 Qualcomm earned in fiscal 2025. Investors are paying an above-average multiple for trough earnings, which only makes sense if the data center plan lands on time.
What Wednesday has to show
Here’s what I’ll be watching:
- A December-quarter revenue guide above the September quarter’s actual. Management said in July that chip revenue would rise slightly in December even with Apple revenue down about half, because Android picks up and data center sales begin. Analysts expect about $10.6 billion.
- Data center revenue with a number on it. I want a dollar figure for the hyperscaler ramp toward $5 billion.
- A margin floor. Management guided the chip unit’s pre-tax margin to 23% to 25% for September, down from 29% a year earlier. A December guide that stops that slide would show the price increases and job cuts are working.
Any comment on Anduril or Hark is a bonus.
The way I see it, the risk into Wednesday is on the downside. At 18x shrinking earnings, a December guide that just meets expectations doesn’t leave much room for a pop. A softer handset outlook could send the stock back toward its average multiple, the same way it fell 11% in a day on Intel’s PC warning.
Of course, the custom chips only start shipping in the December quarter. Wednesday gives us the guide, and we won’t see the revenue itself until Qualcomm reports that quarter in early 2027.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!