Key Takeaways
- Dan Loeb’s Third Point made Meta, Unum and NVIDIA its three largest positions in the third quarter, all of them new, and sold all of its Amazon and Norfolk Southern shares.
- All three new positions are down since Sept. 30, NVIDIA by 34%, while Amazon and Norfolk Southern are both up.
- After that drop, NVIDIA trades at about 10x forward earnings, and analysts’ average target is 63% above the price.
- NVIDIA is the move to follow from here. The main risk is that an interim CEO is running the company.
Dan Loeb’s Third Point replaced the top of its portfolio in the third quarter. Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows three new positions at the top, Meta Platforms (META), Unum (UNM) and NVIDIA (NVDA), and no shares left of Amazon (AMZN) or Norfolk Southern (NSC).
A new top three in one quarter
Third Point manages $28.73 billion in all. Its 13F held $4.54 billion of US stocks in 36 positions on Sept. 30. During the quarter, it opened or added to 13 positions and sold out of eight. Meta is now its largest at 10.5% of its 13F stocks, followed by Unum at 9.7% and NVIDIA at 7.5%. Further down the list, it bought Microsoft, Casey’s General and Bank of America, worth $230 million, $112 million and $108.9 million at the quarter’s end. Its SpaceX position was worth $147.9 million, 443% more than on June 30. Three stocks were sold out completely: Amazon, which was 9.0% of its 13F stocks at June 30, Norfolk Southern at 4.1%, and Danaher.
TIKR tracks 62 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
Meta tops the list, cash burn and all
Third Point held 655,000 Meta shares worth $475 million on Sept. 30. The stock is down 15% since then. Meta’s third quarter gave each side something to point to. Revenue grew 26% to $64.6 billion. But capital spending of $34.9 billion was more than the $32.8 billion of cash the business brought in from operations. Analysts now see Meta’s free cash flow bottoming at negative $48.0 billion in 2027, so the AI build is the whole debate.
Even so, analysts’ average target has recovered to $848 from its Aug. 10 low of $754, and it’s now above where it was a year ago:
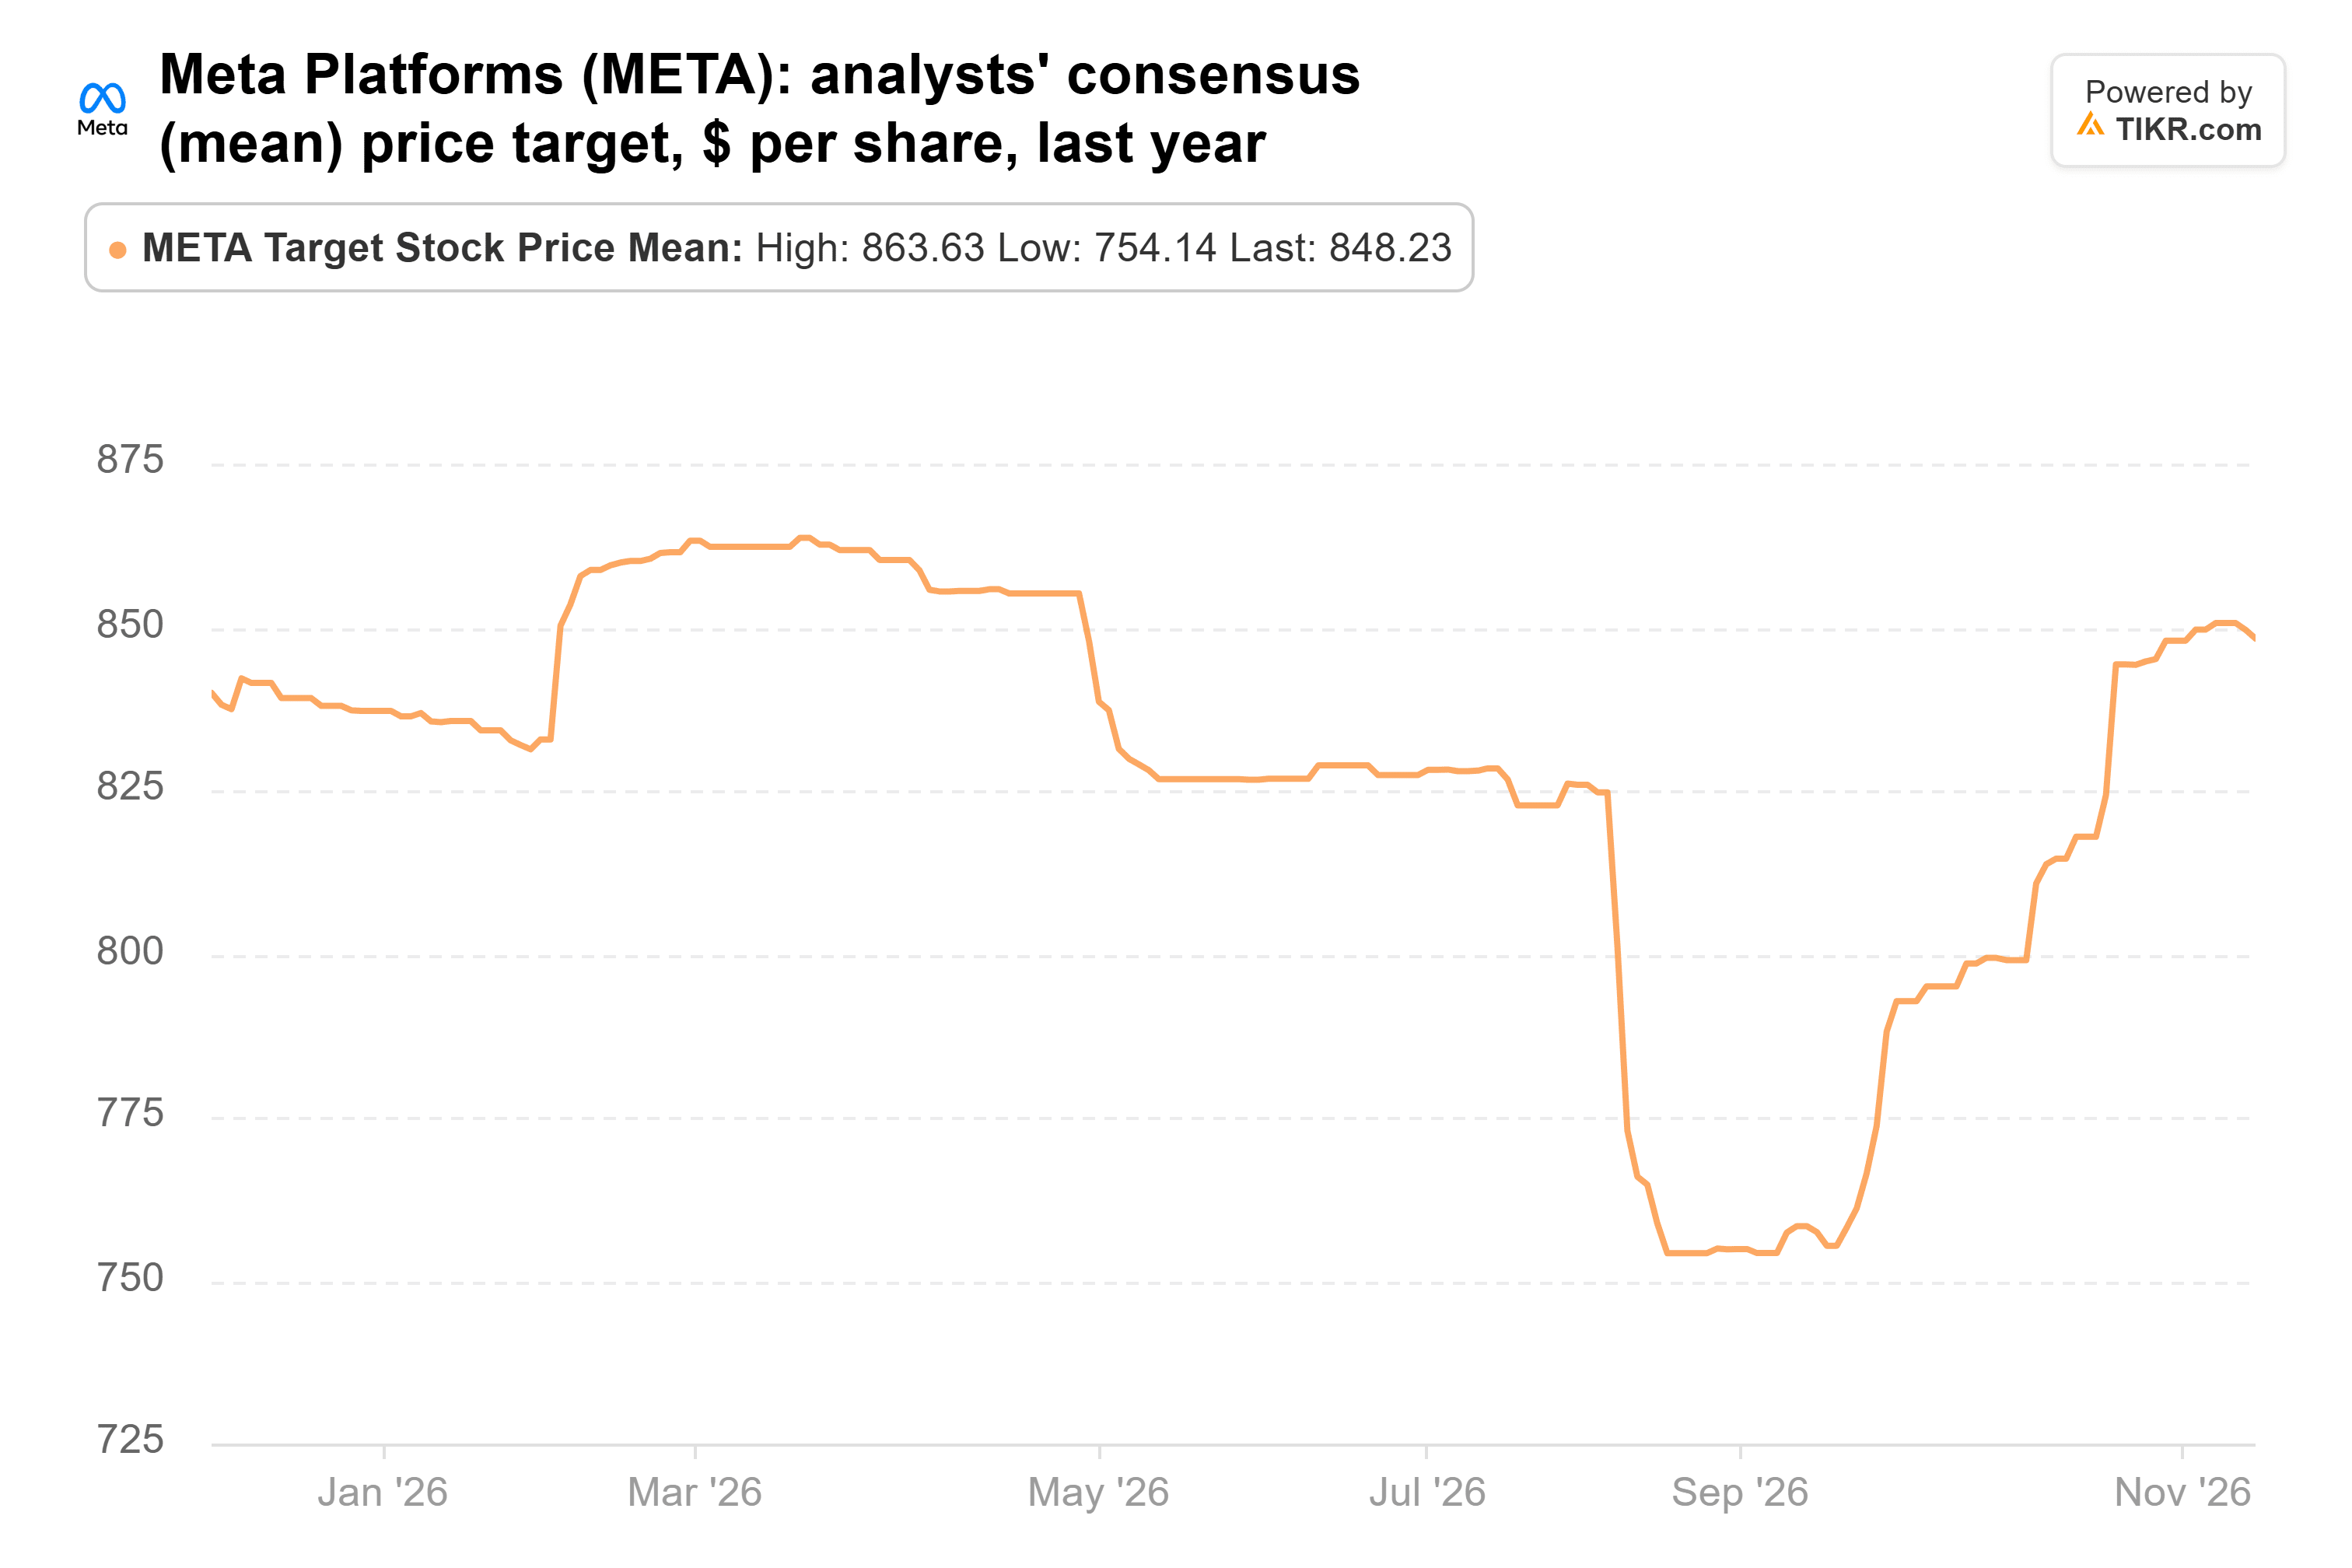
That target is 38% above today’s price. Individual targets run from $650 to $1,050. At about 19x forward earnings, Meta also trades below its five-year average of about 21x.
Unum’s quarter was rough
The No. 2 position is the one most readers won’t expect. Third Point held 5.00 million Unum shares worth $439 million on Sept. 30, and the stock is down 13% since. On Nov. 3, Unum reported a GAAP net loss of $419.7 million for the third quarter. Most of that came from an $853.0 million before-tax investment loss, largely impairments. After-tax adjusted operating income was $349.0 million, or $2.20 a share.
The core business had a weak quarter too. Unum US paid out 62.0% of its premiums in benefits, up from 51.1% a year earlier. Adjusted operating income at Unum International fell to $0.2 million from $44.2 million. Management still bought back 2.1 million shares for $202.0 million during the quarter.
Unum trades at about 9x forward earnings. Analysts’ average target of $95, from 13 analysts, is 25% above the price. Following Loeb here is a bet that claims fall back toward last year’s levels.
NVIDIA has fallen the hardest
Third Point held 1.50 million NVIDIA shares worth $343 million on Sept. 30. The stock is down 34% since then, a stretch that included Jensen Huang’s resignation as CEO.
The Nov. 17 report showed demand still holding up. NVIDIA guided its January quarter to about $130 billion of revenue, roughly what the Street wanted. Interim CEO Colette Kress raised fiscal 2028 growth to about 75% from about 70%. The weak spot was days sales outstanding, which rose to 64 from 60. NVIDIA blamed the timing of Rubin shipments and longer payment terms for some investment-grade customers.
The stock now trades at about 10x forward earnings, compared with a five-year average of about 36x on TIKR. Analysts’ average target is $247, from 62 analysts, 63% above the price.
Amazon and Norfolk Southern kept climbing without him
The sales tell the opposite story. Third Point sold all 1.75 million of its Amazon shares, which were worth $417 million at June 30. Amazon is up 12% since Sept. 30, and AWS grew 39% in the third quarter, its fastest in five years. Analysts’ average target has risen to $326 from $293 a year ago:
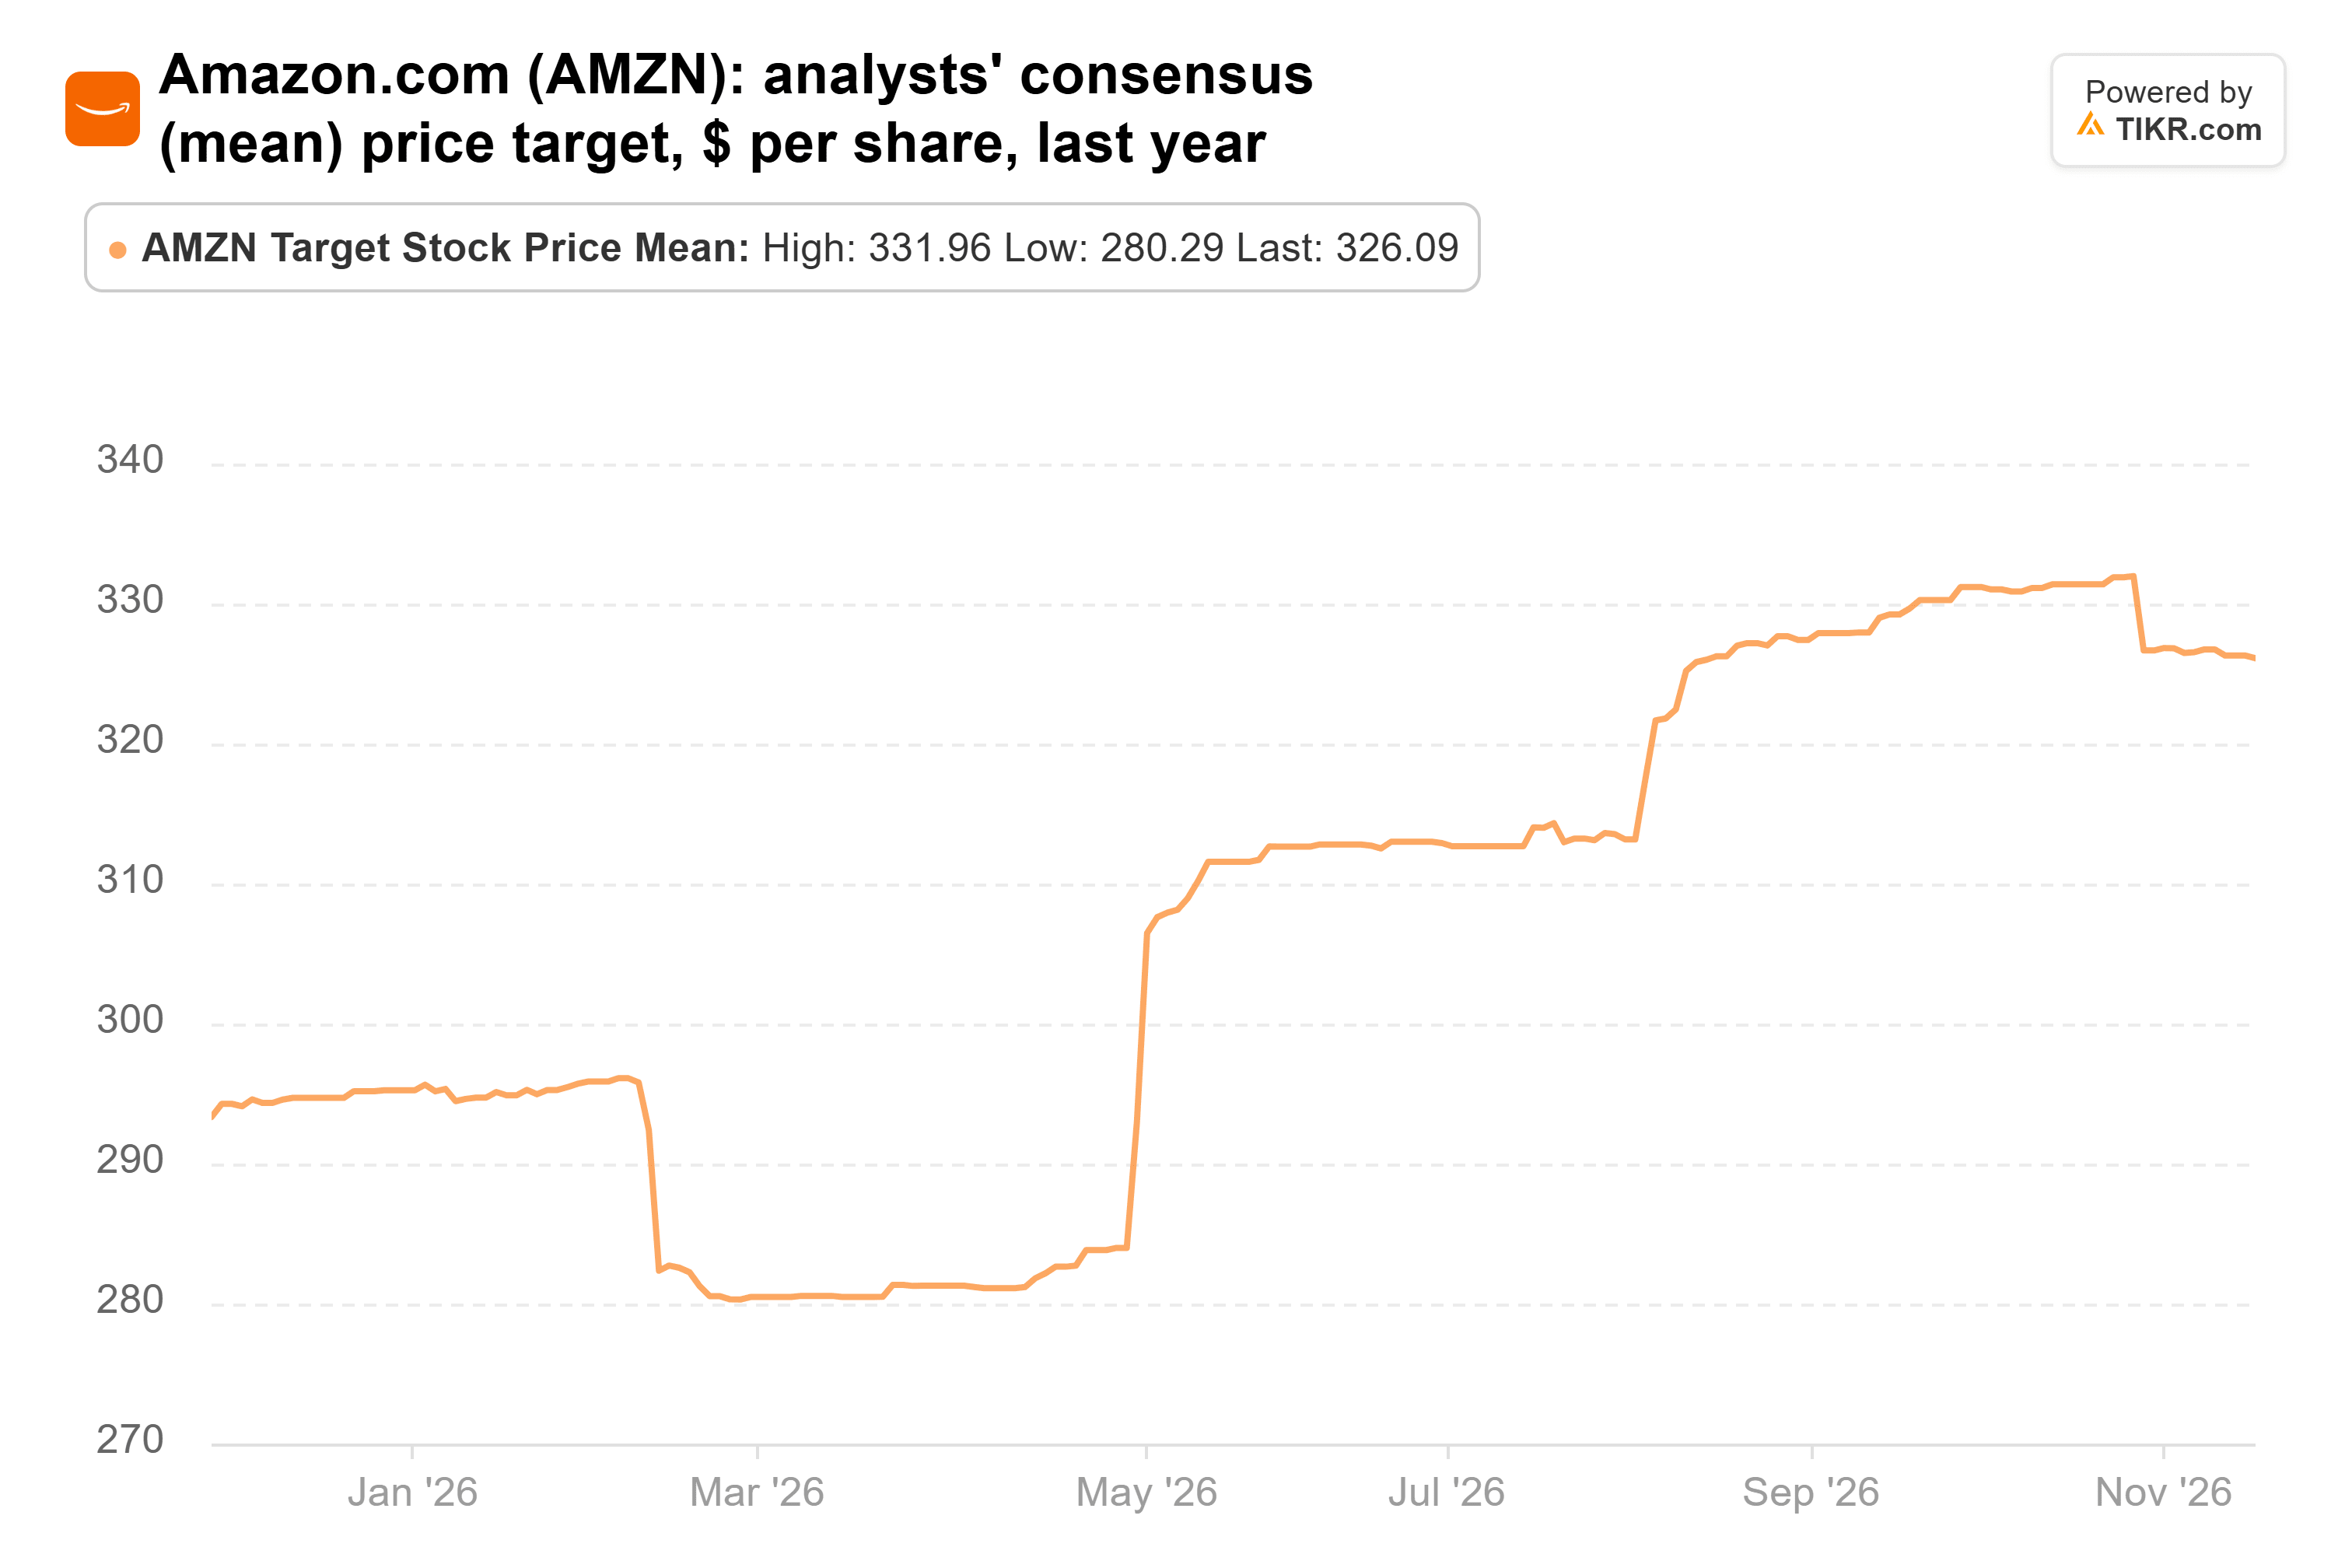
It peaked at $332 on Oct. 29 and is now 22% above the price. The stock trades at about 27x forward earnings. Amazon is paying for its own buildout too, and it has sold more than $92 billion of bonds this year.
Norfolk Southern was the smaller sale: 600,000 shares, worth $189 million at June 30. The stock is up 3% since Sept. 30, and analysts’ average target has risen to $357 from $312 a year ago:
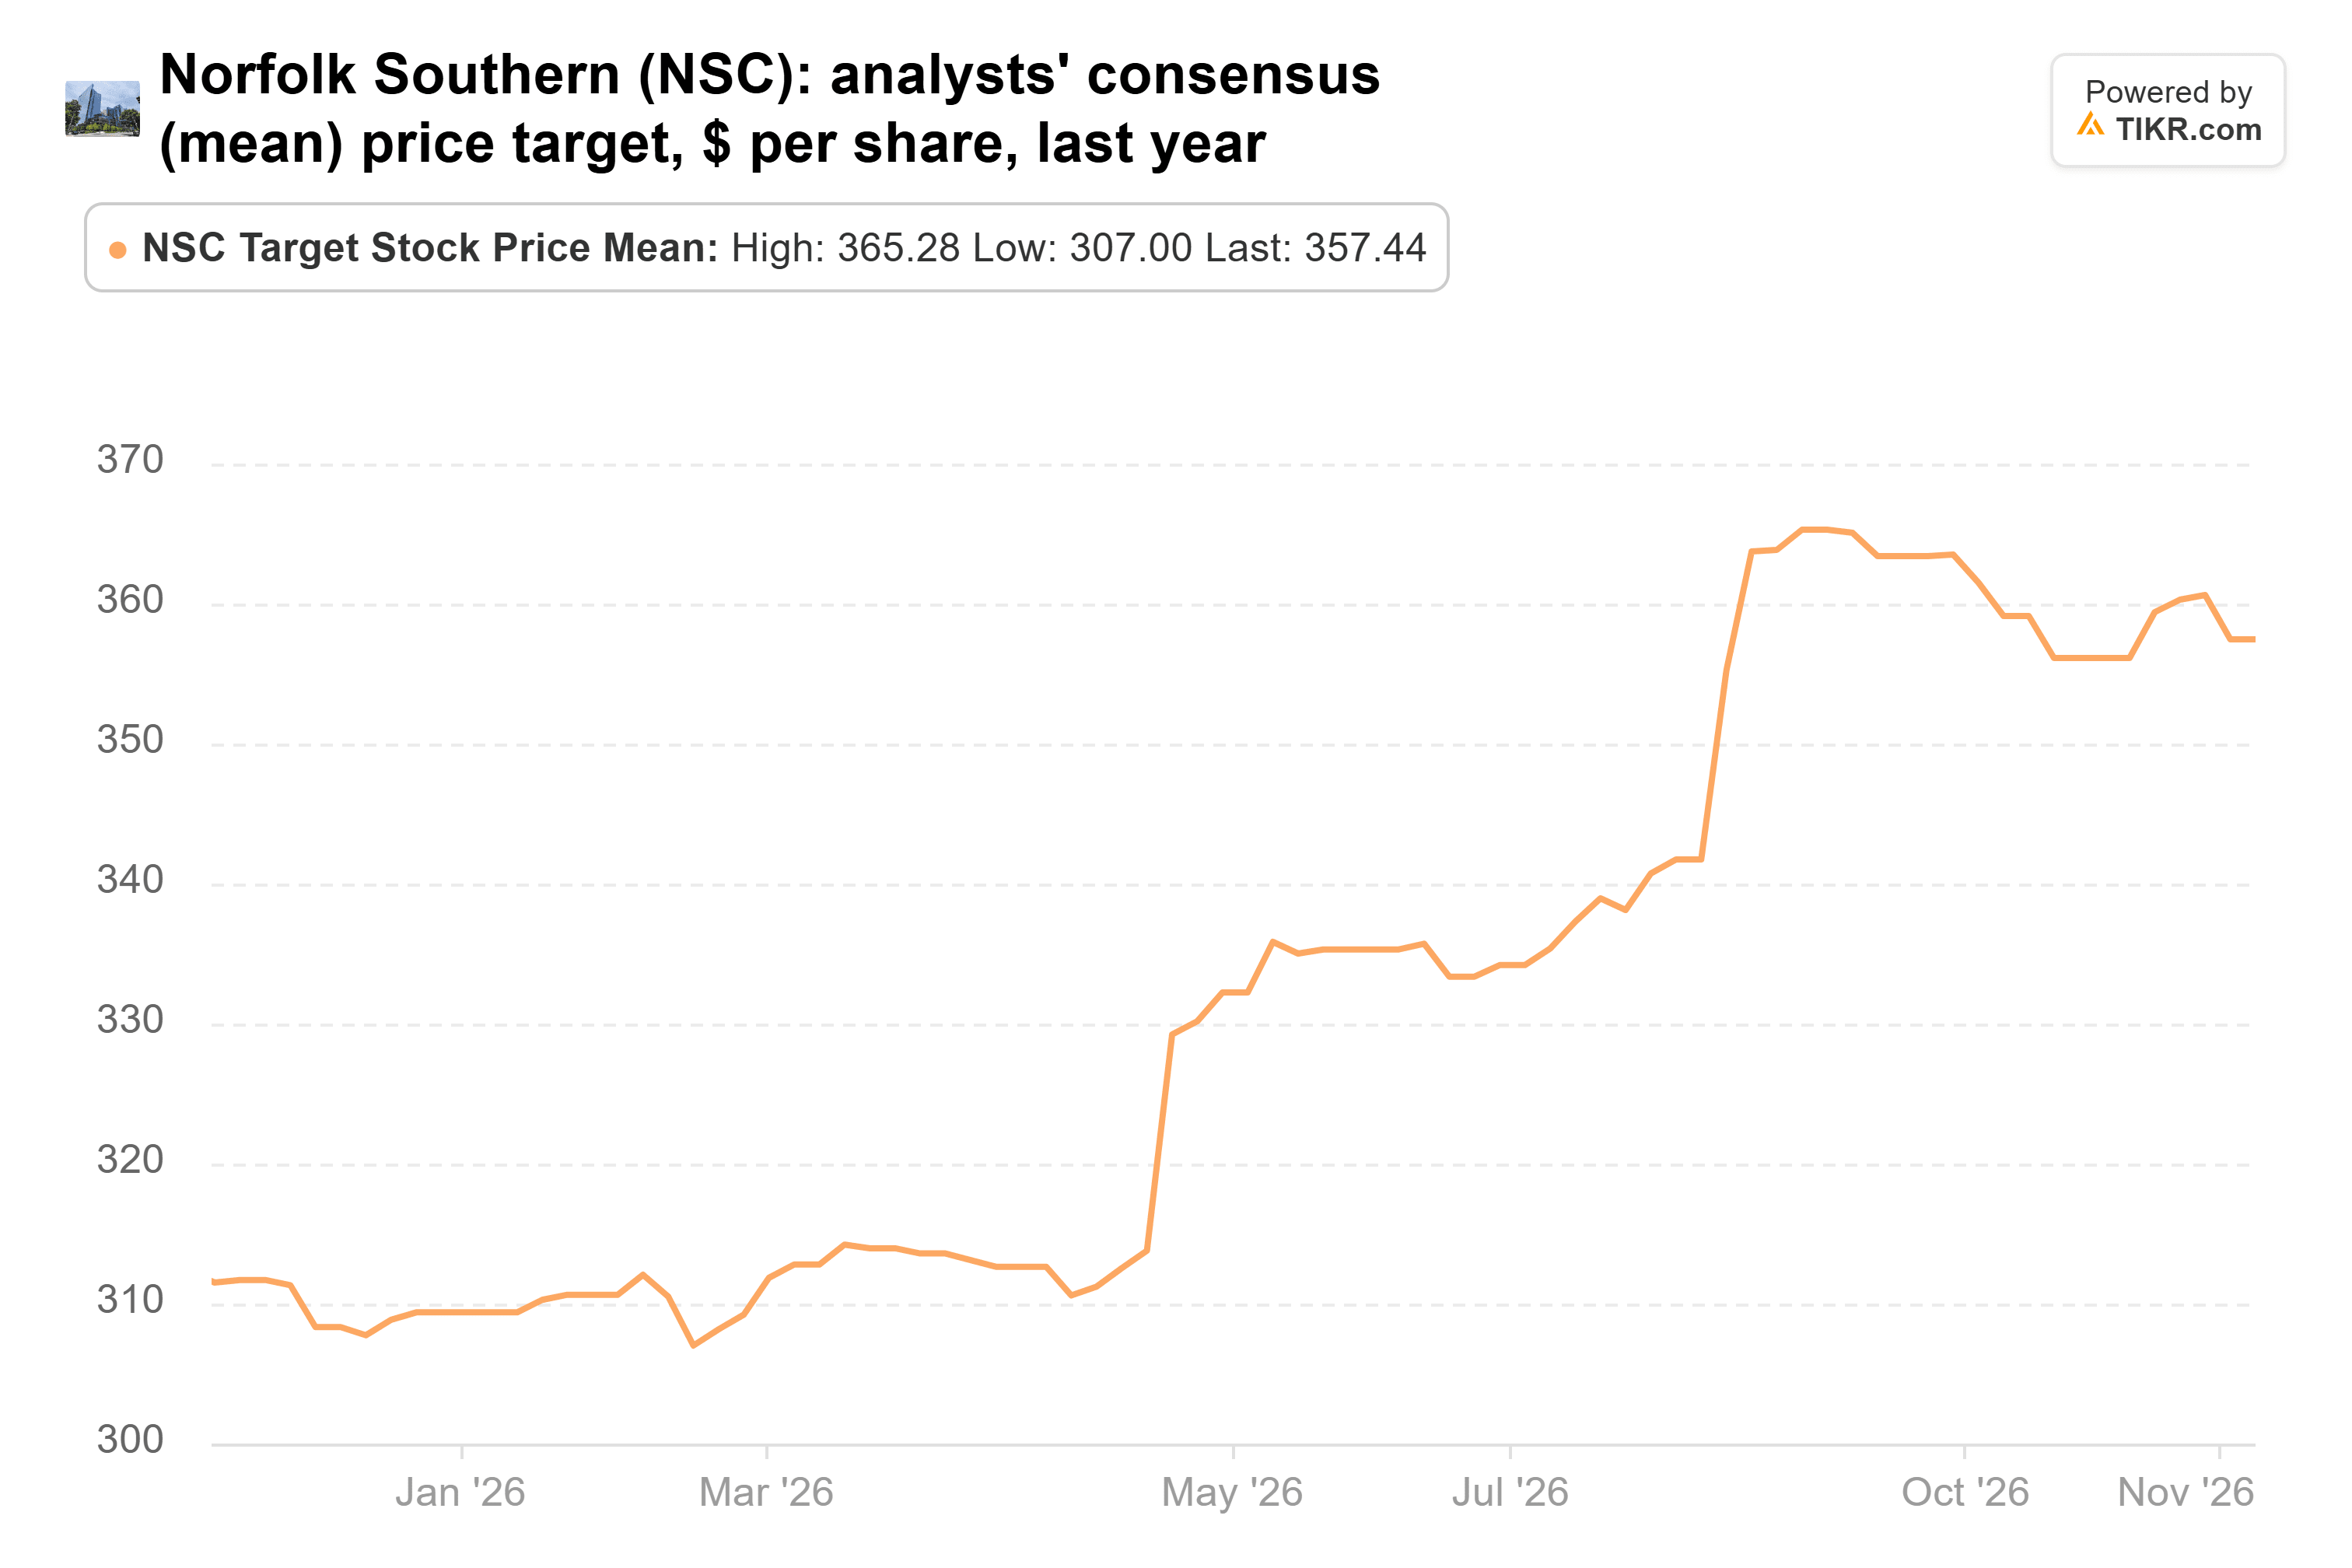
That’s 10% above the price, with targets running from $297 to $400.
NVIDIA is the bet I’d copy
On price alone, Loeb hasn’t been rewarded yet. All three of his biggest buys are down since Sept. 30, and both of his big sales are up. That only measures from quarter-end prices, though. The 13F doesn’t show what he paid or when he traded.
If I could only follow one of his moves right now, it’d be NVIDIA. At about 10x forward earnings, the stock is priced as if the AI build is close to its peak, yet management just raised its growth outlook for fiscal 2028. The main risk is leadership: an interim CEO is running NVIDIA, and longer payment terms put more of its customers’ risk on its balance sheet.
Third Point’s next 13F, for the quarter ending Dec. 31, is due by mid-February. NVIDIA reports its January quarter around late February. Revenue near the $130 billion guide, with days sales outstanding back below 64, would go a long way toward proving Loeb early.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!