Key Takeaways
- Anthropic now brings in $1.72 per compute dollar, up from 40 cents in early 2025, per its S-1.
- The ratio dipped from $2.08 in the June quarter and counts compute costs only.
- Treated as capital invested up front, Anthropic’s $900.9 billion of commitments would need roughly twice 2028’s expected revenue for a 20% return.
Anthropic (ANT) began trading on Nov. 19 after pricing its IPO at $83 a share.
That’s a big day for Amazon (AMZN) and Alphabet (GOOG), which will own 14.6% and 13.4% of Anthropic, per its final prospectus, and for Broadcom (AVGO), which expects Anthropic to become its largest custom-chip customer in 2027.
On the Nov. 19 Big Technology Podcast, host Alex Kantrowitz and Box CEO Aaron Levie discussed a chart from Anthropic’s S-1. It showed that Anthropic generated $1.72 of revenue per dollar of compute and infrastructure expense in the September 2026 quarter, up from $0.40 in the March 2025 quarter.
What Anthropic’s $1.72 Leaves Out
The math holds: third-quarter revenue of $17.0 billion against $9.9 billion of compute and infrastructure expense is $1.72, more than 4x the early-2025 level. But it peaked at $2.08 in the June quarter. Anthropic said $5 billion of pricier short-term compute pulled it down. The ratio also leaves out staff and every other cost, and Anthropic still posted a $567 million third-quarter operating loss.
Levie says the commitments come down to growth: “If you believe that the thing is going to generate hundreds of billions of dollars a year in revenue, then those commitments are fine.”
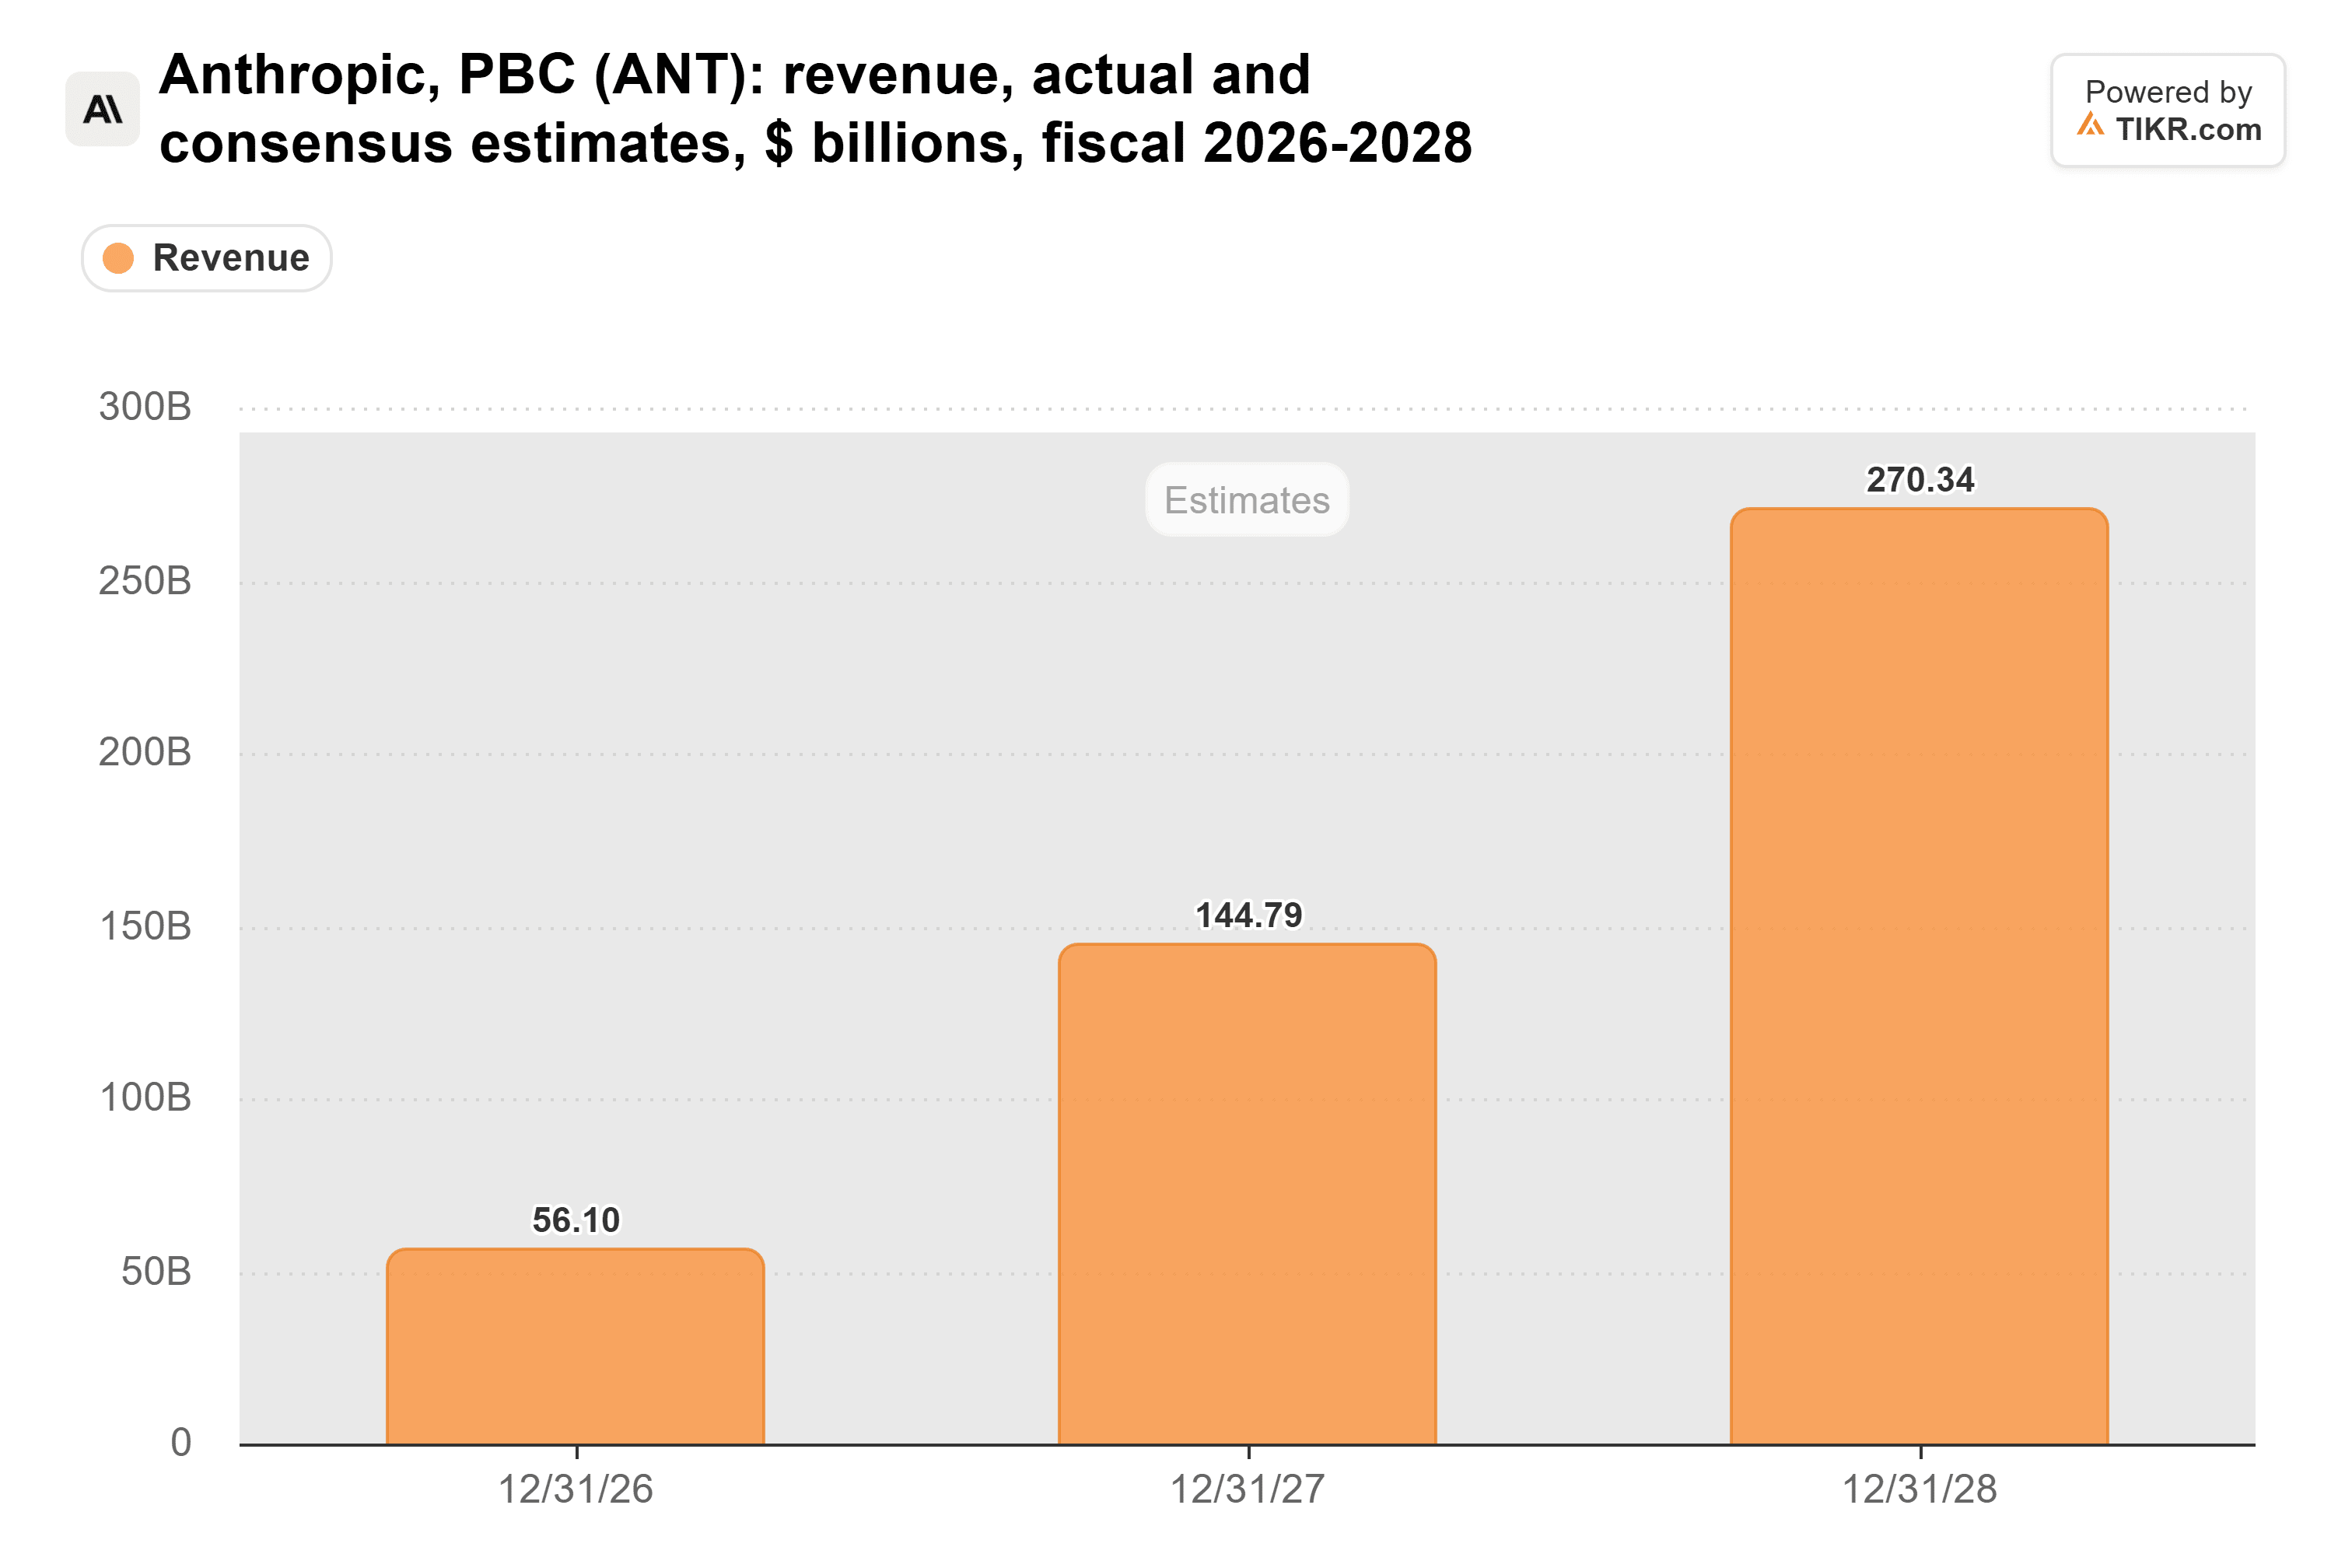
The two analysts with estimates expect $56.1 billion of revenue this year, $145 billion in 2027 and $270 billion in 2028:
See analyst ratings on Anthropic (it’s free):
See the full breakdown of Buy, Hold, and Sell ratings on Anthropic, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Anthropic’s Analyst Ratings
The Bar Is Still Very High
Third-quarter revenue was about 12x a year earlier, but Levie cautioned, “I don’t think anybody should think that there’s another 12x in the next 12 months.”
Anthropic’s prospectus lists about $900.9 billion of compute and infrastructure commitments. If you treat the full $900.9 billion as invested capital, the Financial Times’ assumptions of a 40% operating margin and a 17% tax rate imply about $543 billion in annual revenue for a 20% after-tax return, roughly twice the 2028 estimate.
Amazon and Alphabet Are Already Cashing In, on Paper
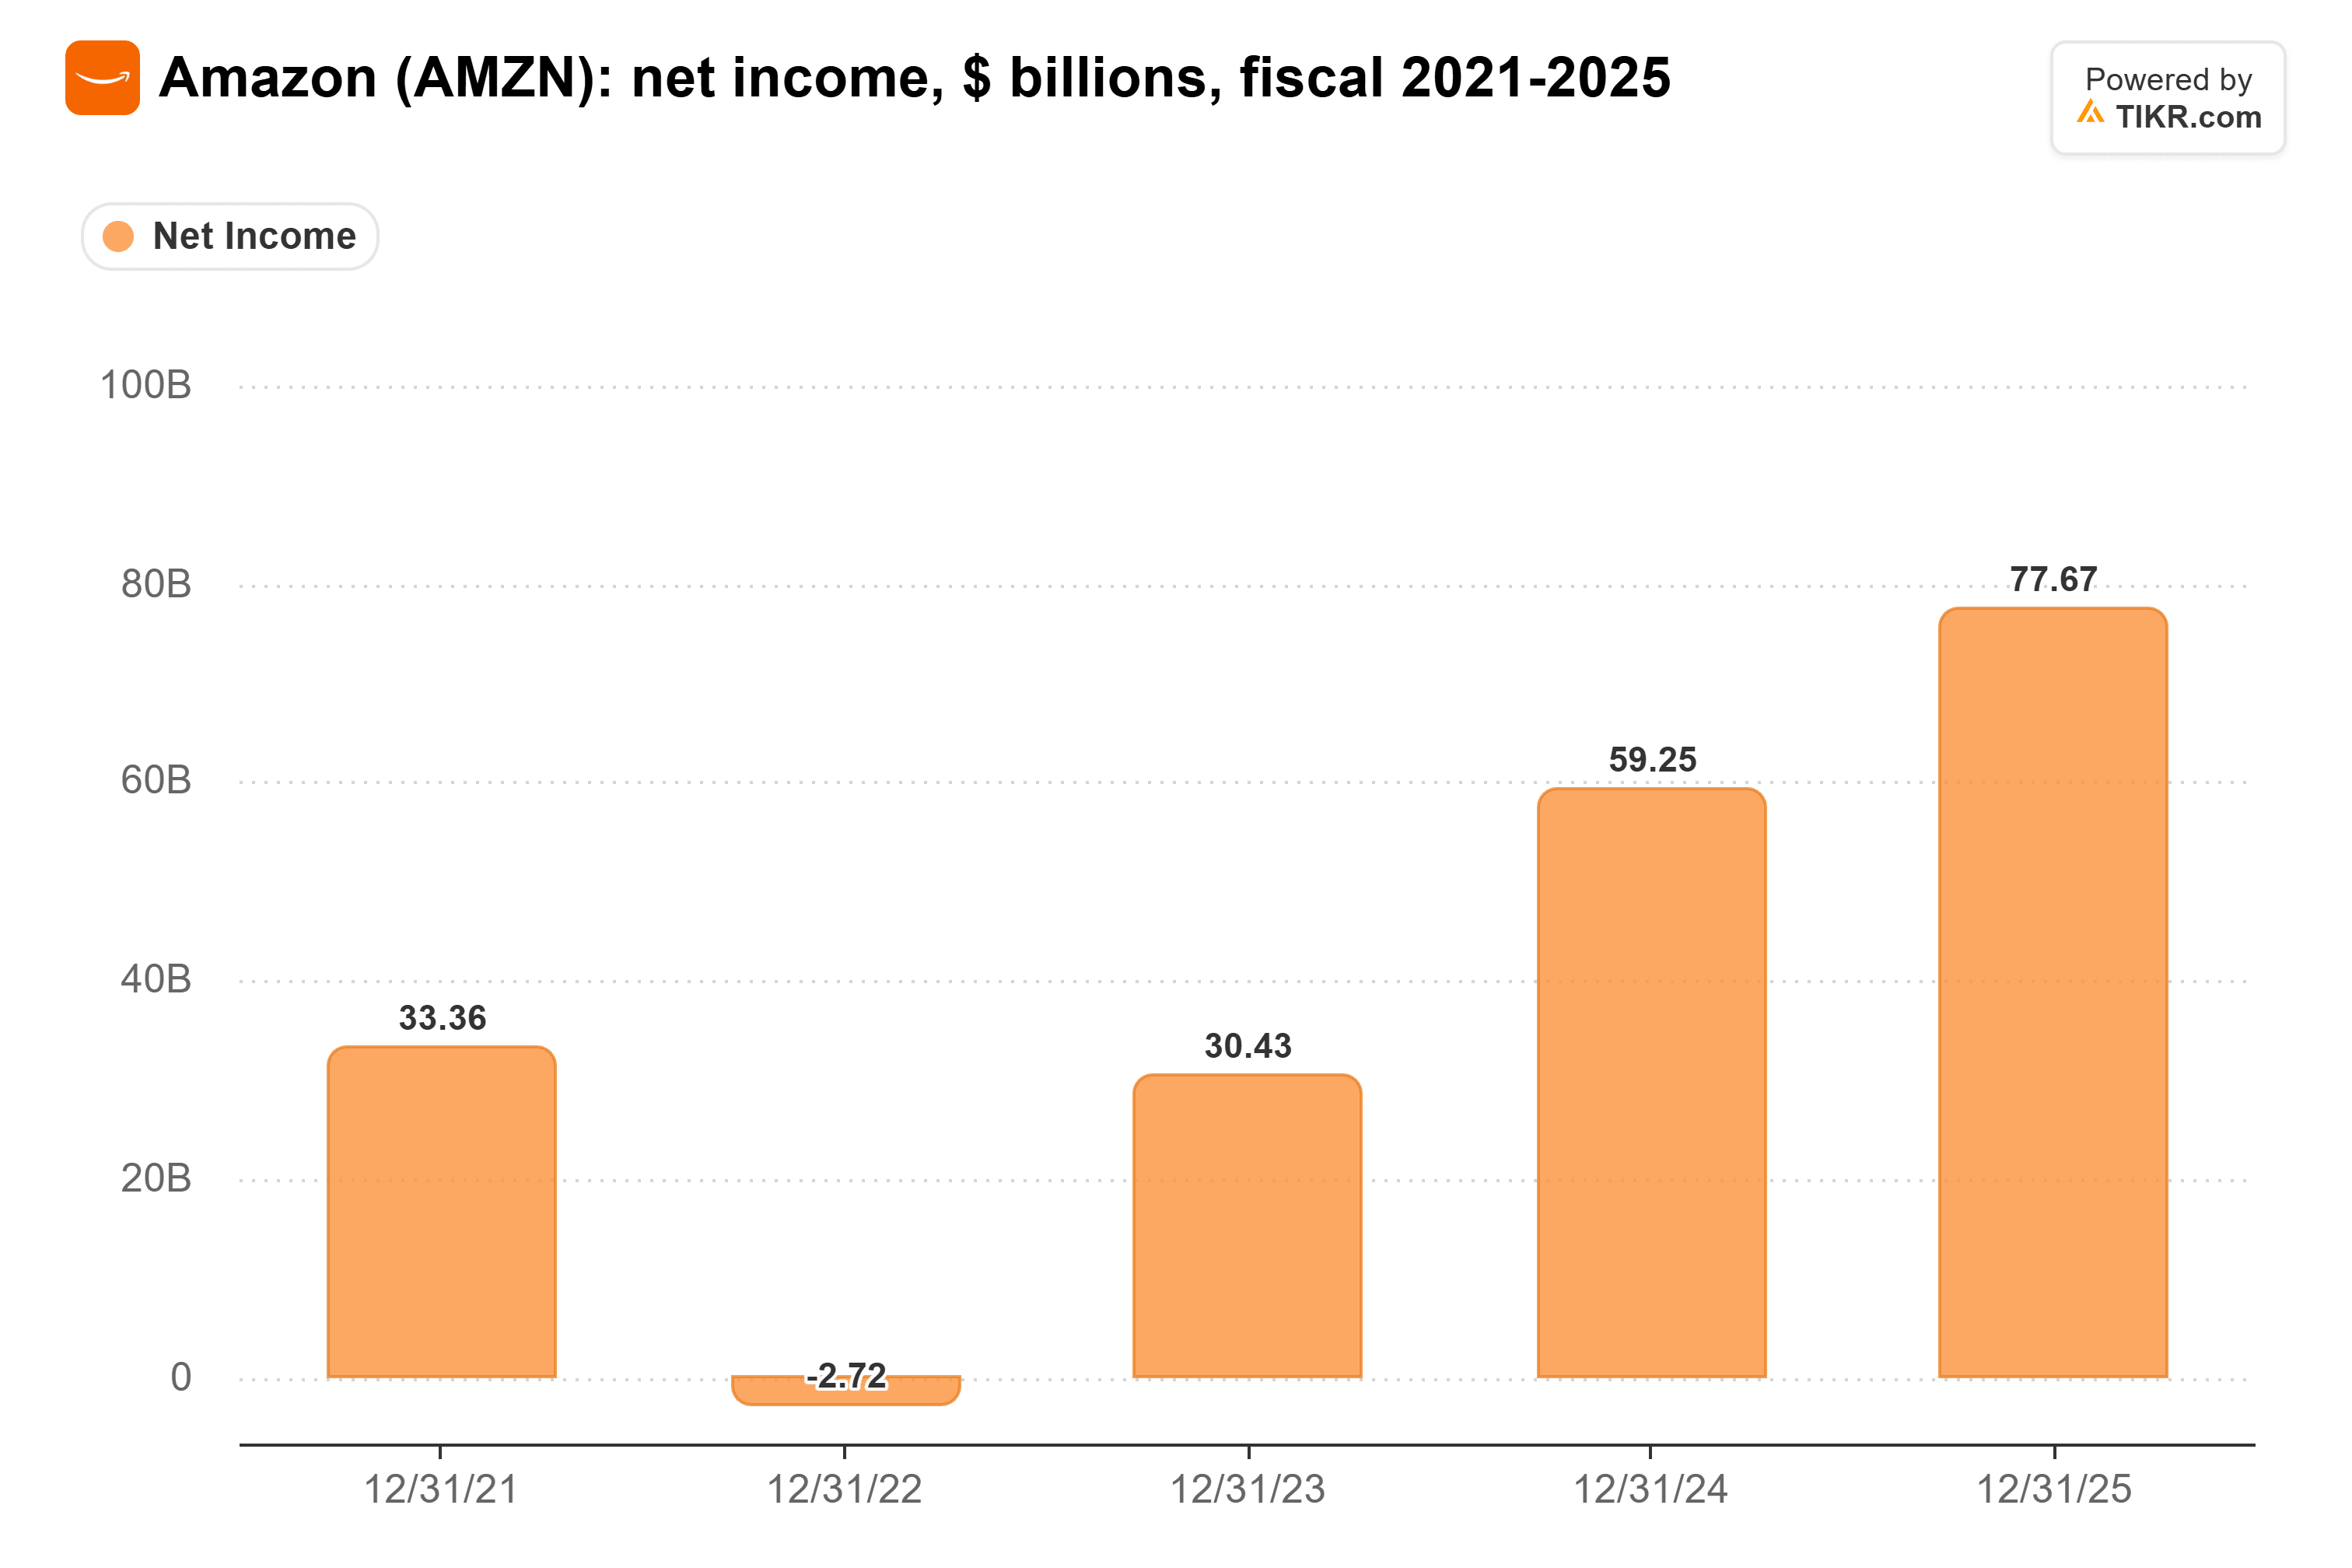
Anthropic expanded its AWS commitment by more than $100 billion over 10 years in the second quarter, so a good chunk of those bills is Amazon’s own revenue. Amazon’s net income reached $77.7 billion in 2025:
In the second quarter of 2026, Amazon booked $50.5 billion of upward adjustments, mostly on Anthropic preferred stock, against $27.5 billion of operating income.
Alphabet’s net income climbed to $132.2 billion in 2025, helped by equity gains that Bloomberg reported included Anthropic:
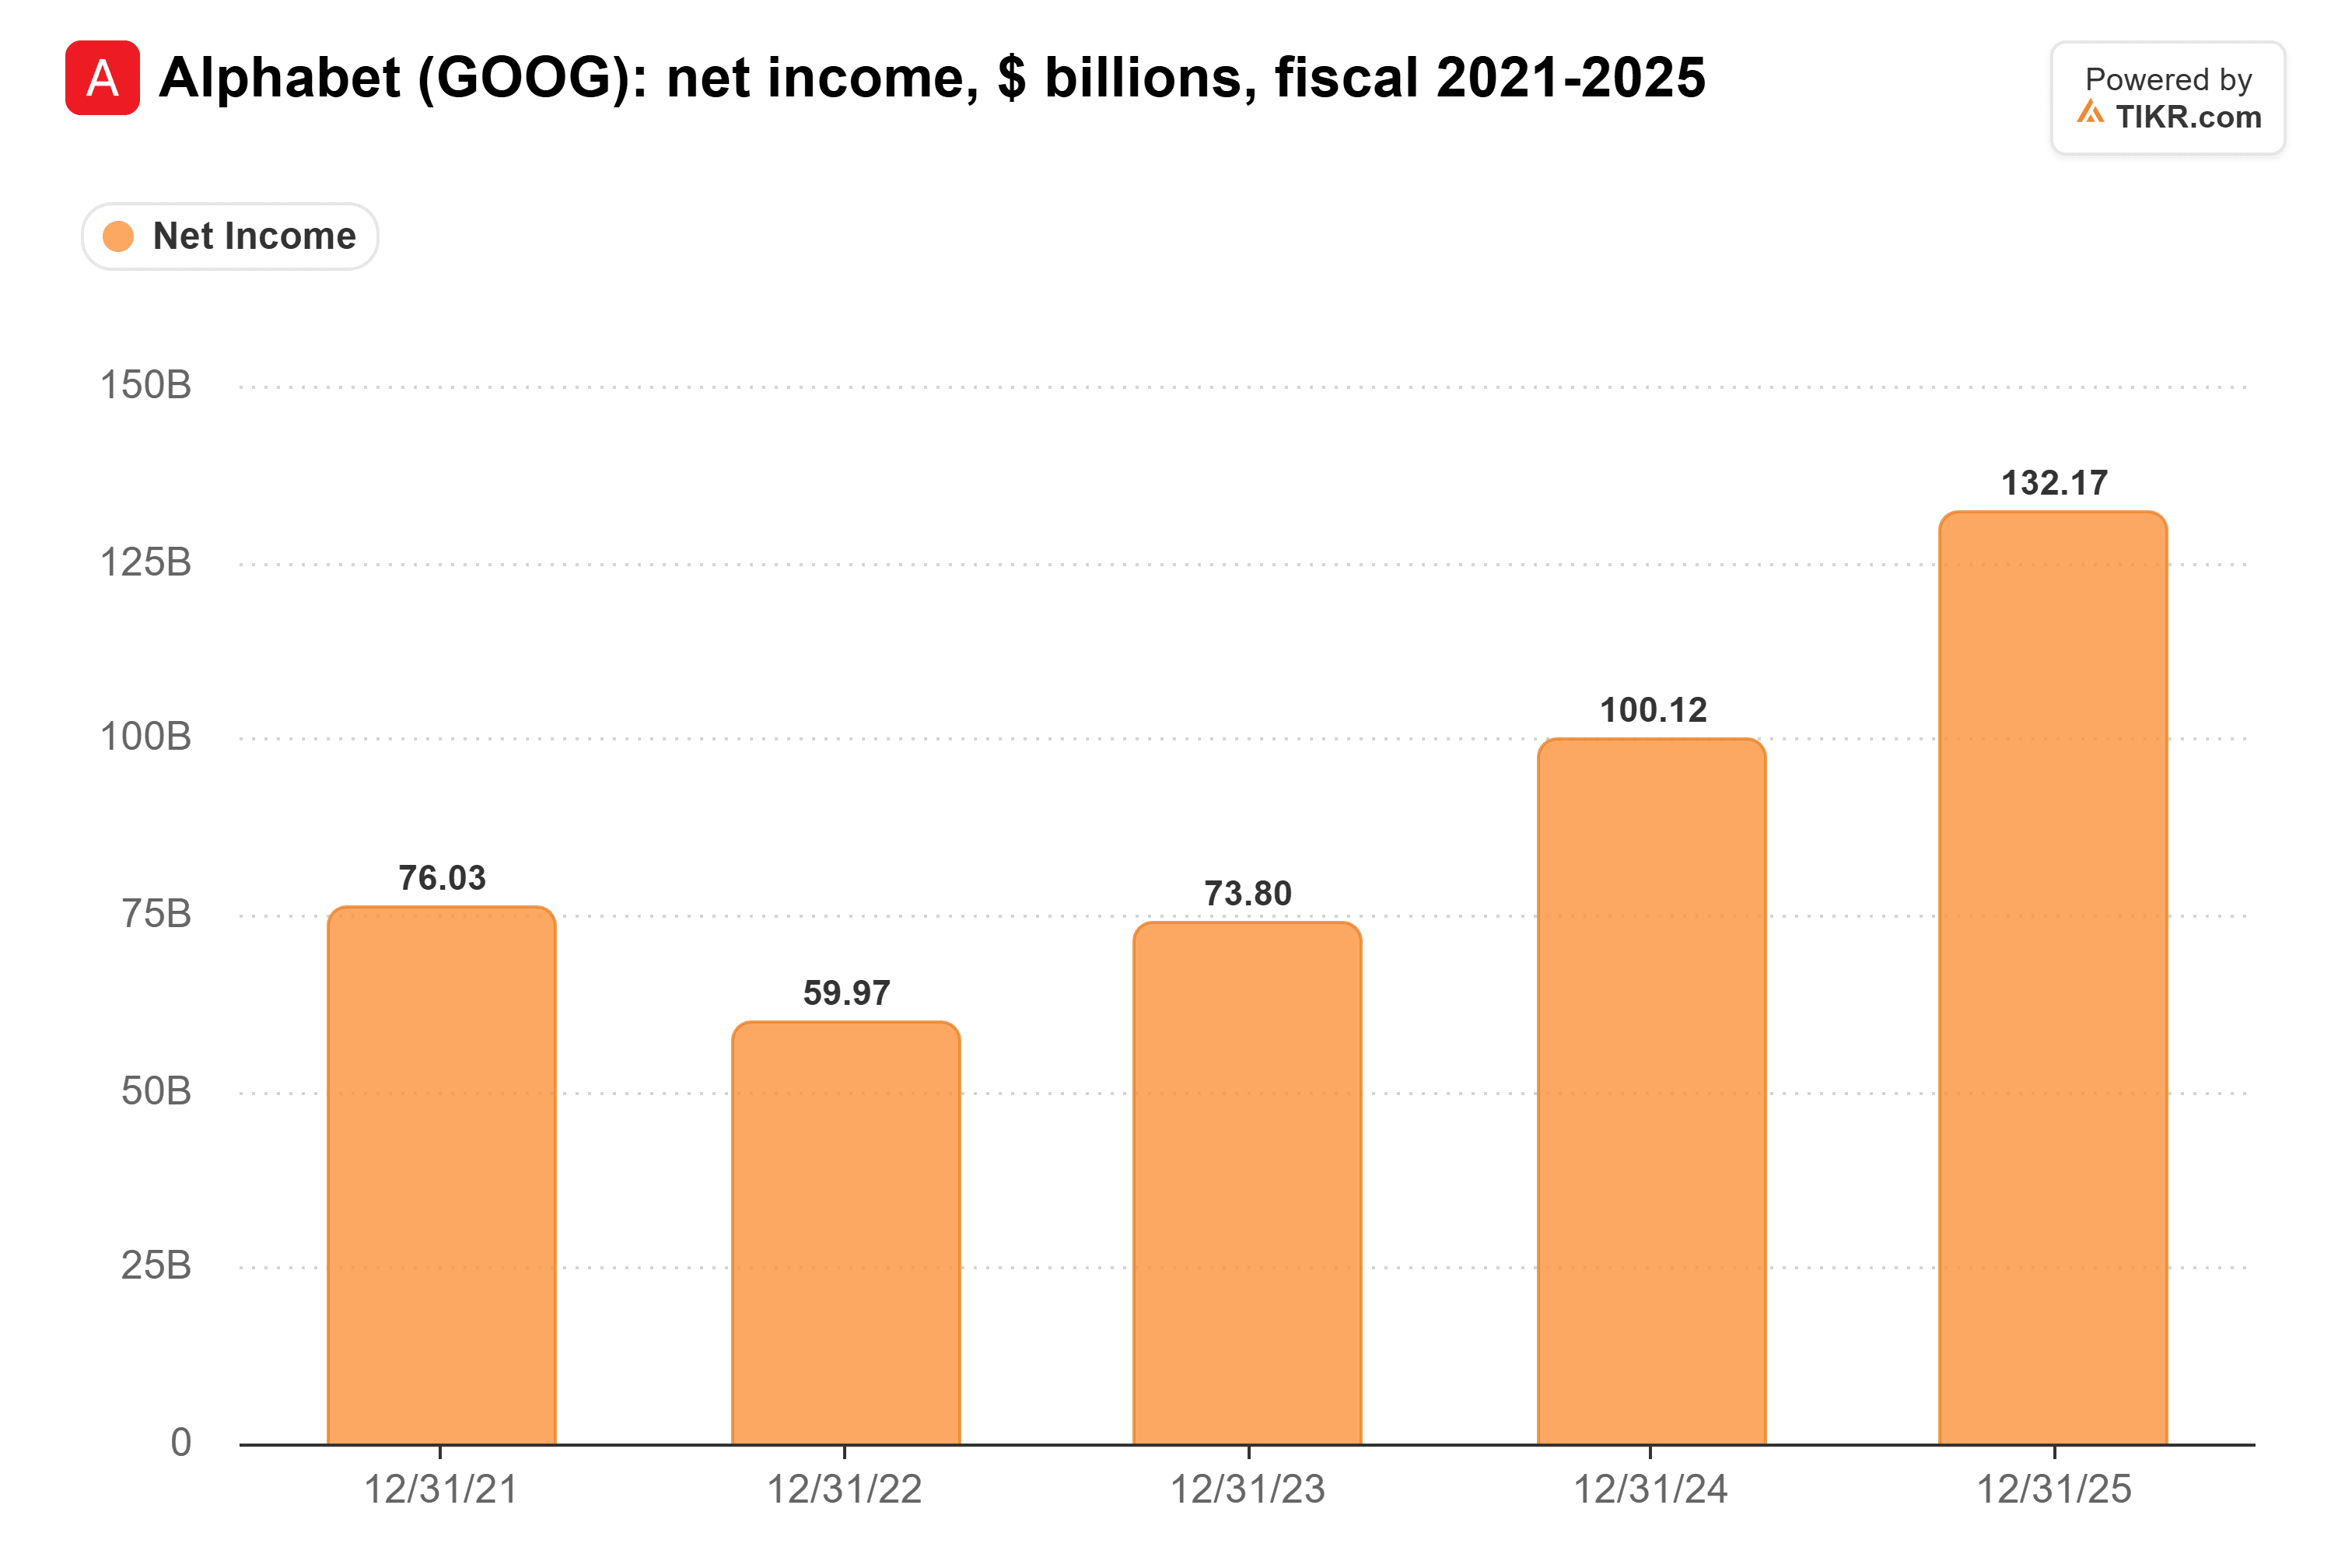
In the second quarter of 2026, it booked a $99.0 billion gain on equity securities, mostly from Anthropic and SpaceX per Fortune, against $40.8 billion of operating income.
What Anthropic’s Ratio Means for Amazon and Alphabet
Anthropic’s $1.72 is good news for both: it shows Anthropic’s revenue already covers its compute bill, which supports the stakes and the cloud contracts behind them. Changes in the value of the Anthropic shares will affect both companies’ reported earnings. Amazon records unrealized gains on its remaining convertible notes in other comprehensive income and has recognized gains in earnings when notes converted.
Broadcom reports Dec. 9. Its $21.7 billion AI semiconductor revenue guide, up from $16.7 billion, measures demand across customers. For Anthropic, the milestone to watch is whether planned compute deliveries begin in 2027.
So What Is Amazon Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!