


Key Takeaways
- A fund that manages $467 billion made Amazon, GE HealthCare and a third stock its three biggest new or added positions in the third quarter, per its 13F filed Nov. 13.
- Amazon got the biggest stake of the three, and Wall Street’s average target is 22% above the stock’s price.
- GE HealthCare is up 28% since Sept. 30, so it now trades only 5% below the Street’s average target.
- Amazon is the one to own of the three. The main risk is free cash flow, which analysts don’t expect to turn positive until 2028.
When a firm that manages $467 billion puts fresh money to work, it’s worth knowing where it went. Dodge & Cox’s 13F for the quarter ended Sept. 30, filed Nov. 13, shows its three biggest new or added positions were Amazon (AMZN), GE HealthCare (GEHC) and a third stock.
Amazon got the biggest check
The fund ended the quarter with 22.70 million Amazon shares, 36% more than three months earlier. At quarter-end prices, the stake was worth $5.66 billion. That’s 3.0% of its 13F stocks and its fifth-largest position. Not everyone agreed: Dan Loeb’s Third Point sold its entire Amazon stake in the same quarter.
Amazon’s third-quarter report on Oct. 29 showed AWS growing 39%, its fastest in five years. Analysts’ consensus target has risen over the past year:
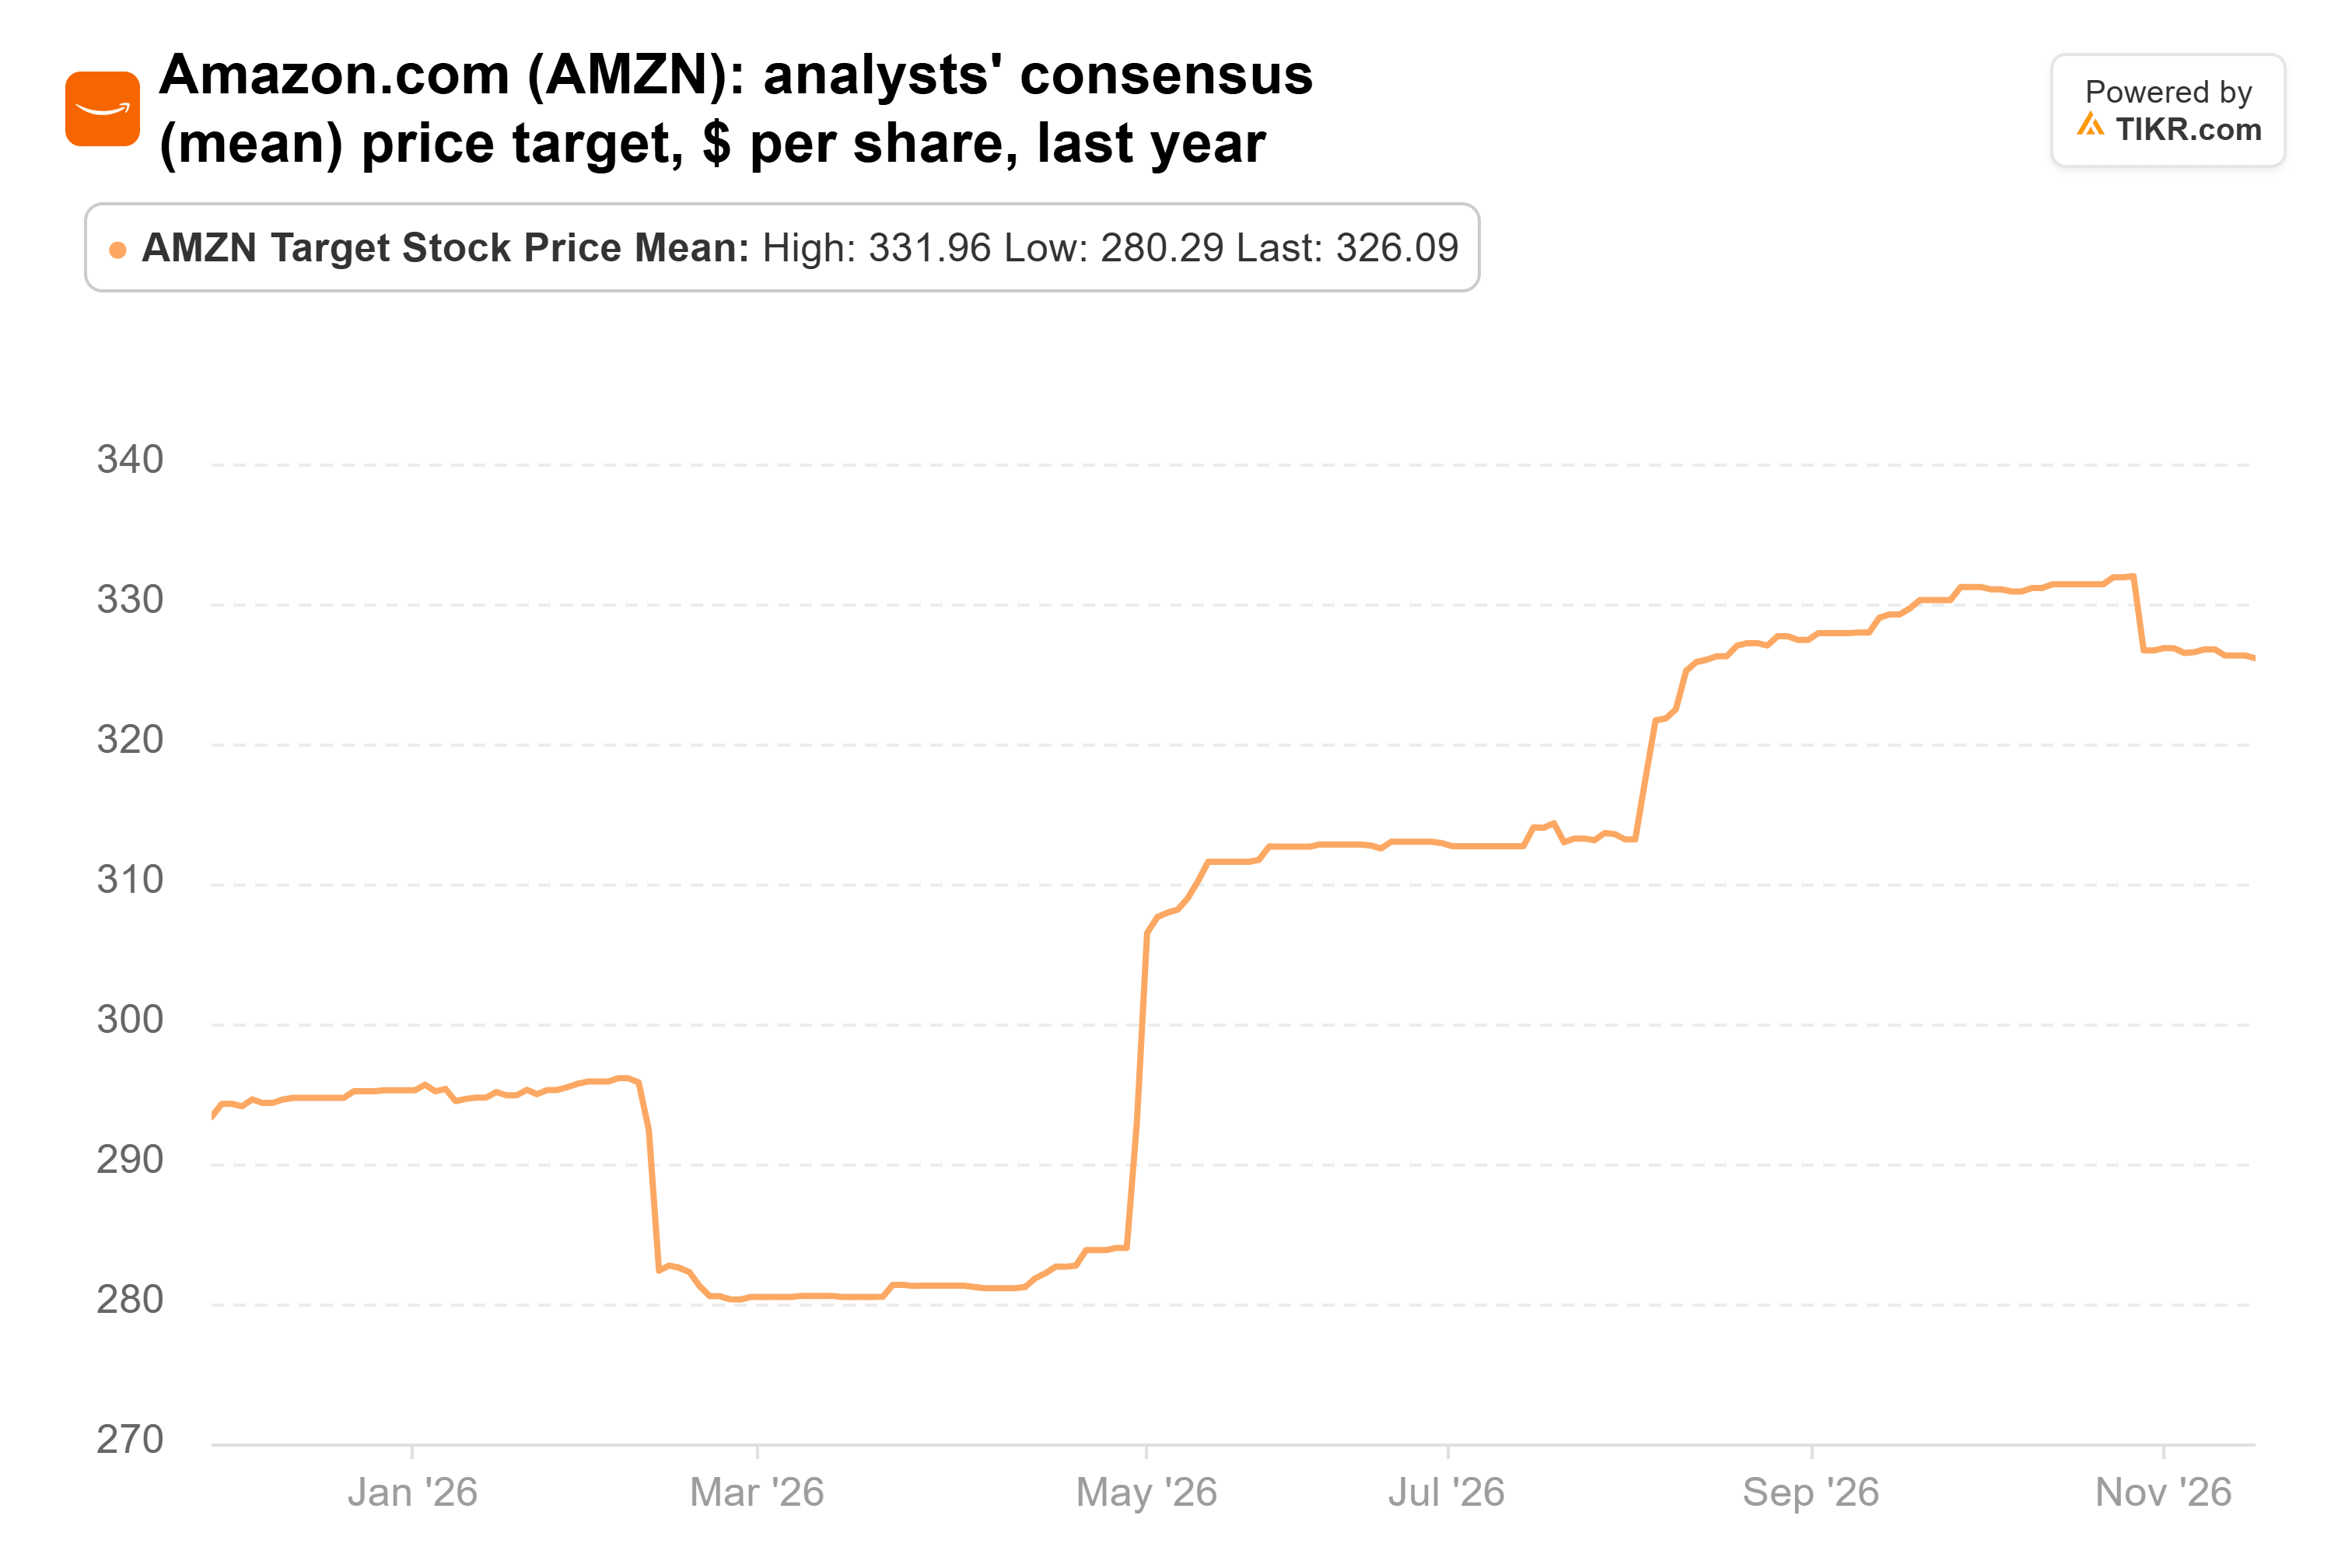
The target is now $326.09 from 61 analysts. That’s up from $293.33 a year ago and 22% above the last close. The stock is up 7% from its Sept. 30 price.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
GE HealthCare has already had its run
The fund added 28% to its GE HealthCare shares in the quarter. It ended with 48.30 million shares worth $3.16 billion, 1.7% of its 13F stocks. The stock is up 28% from its Sept. 30 price. In between, GE HealthCare reported a third quarter that came in ahead of its own expectations on Oct. 28: revenue rose 7.2% to $5.5 billion, adjusted EPS climbed 25.1% to $1.34, and the company raised its full-year guidance.
Analysts haven’t followed the stock up, though. Their consensus target has barely moved in a year:
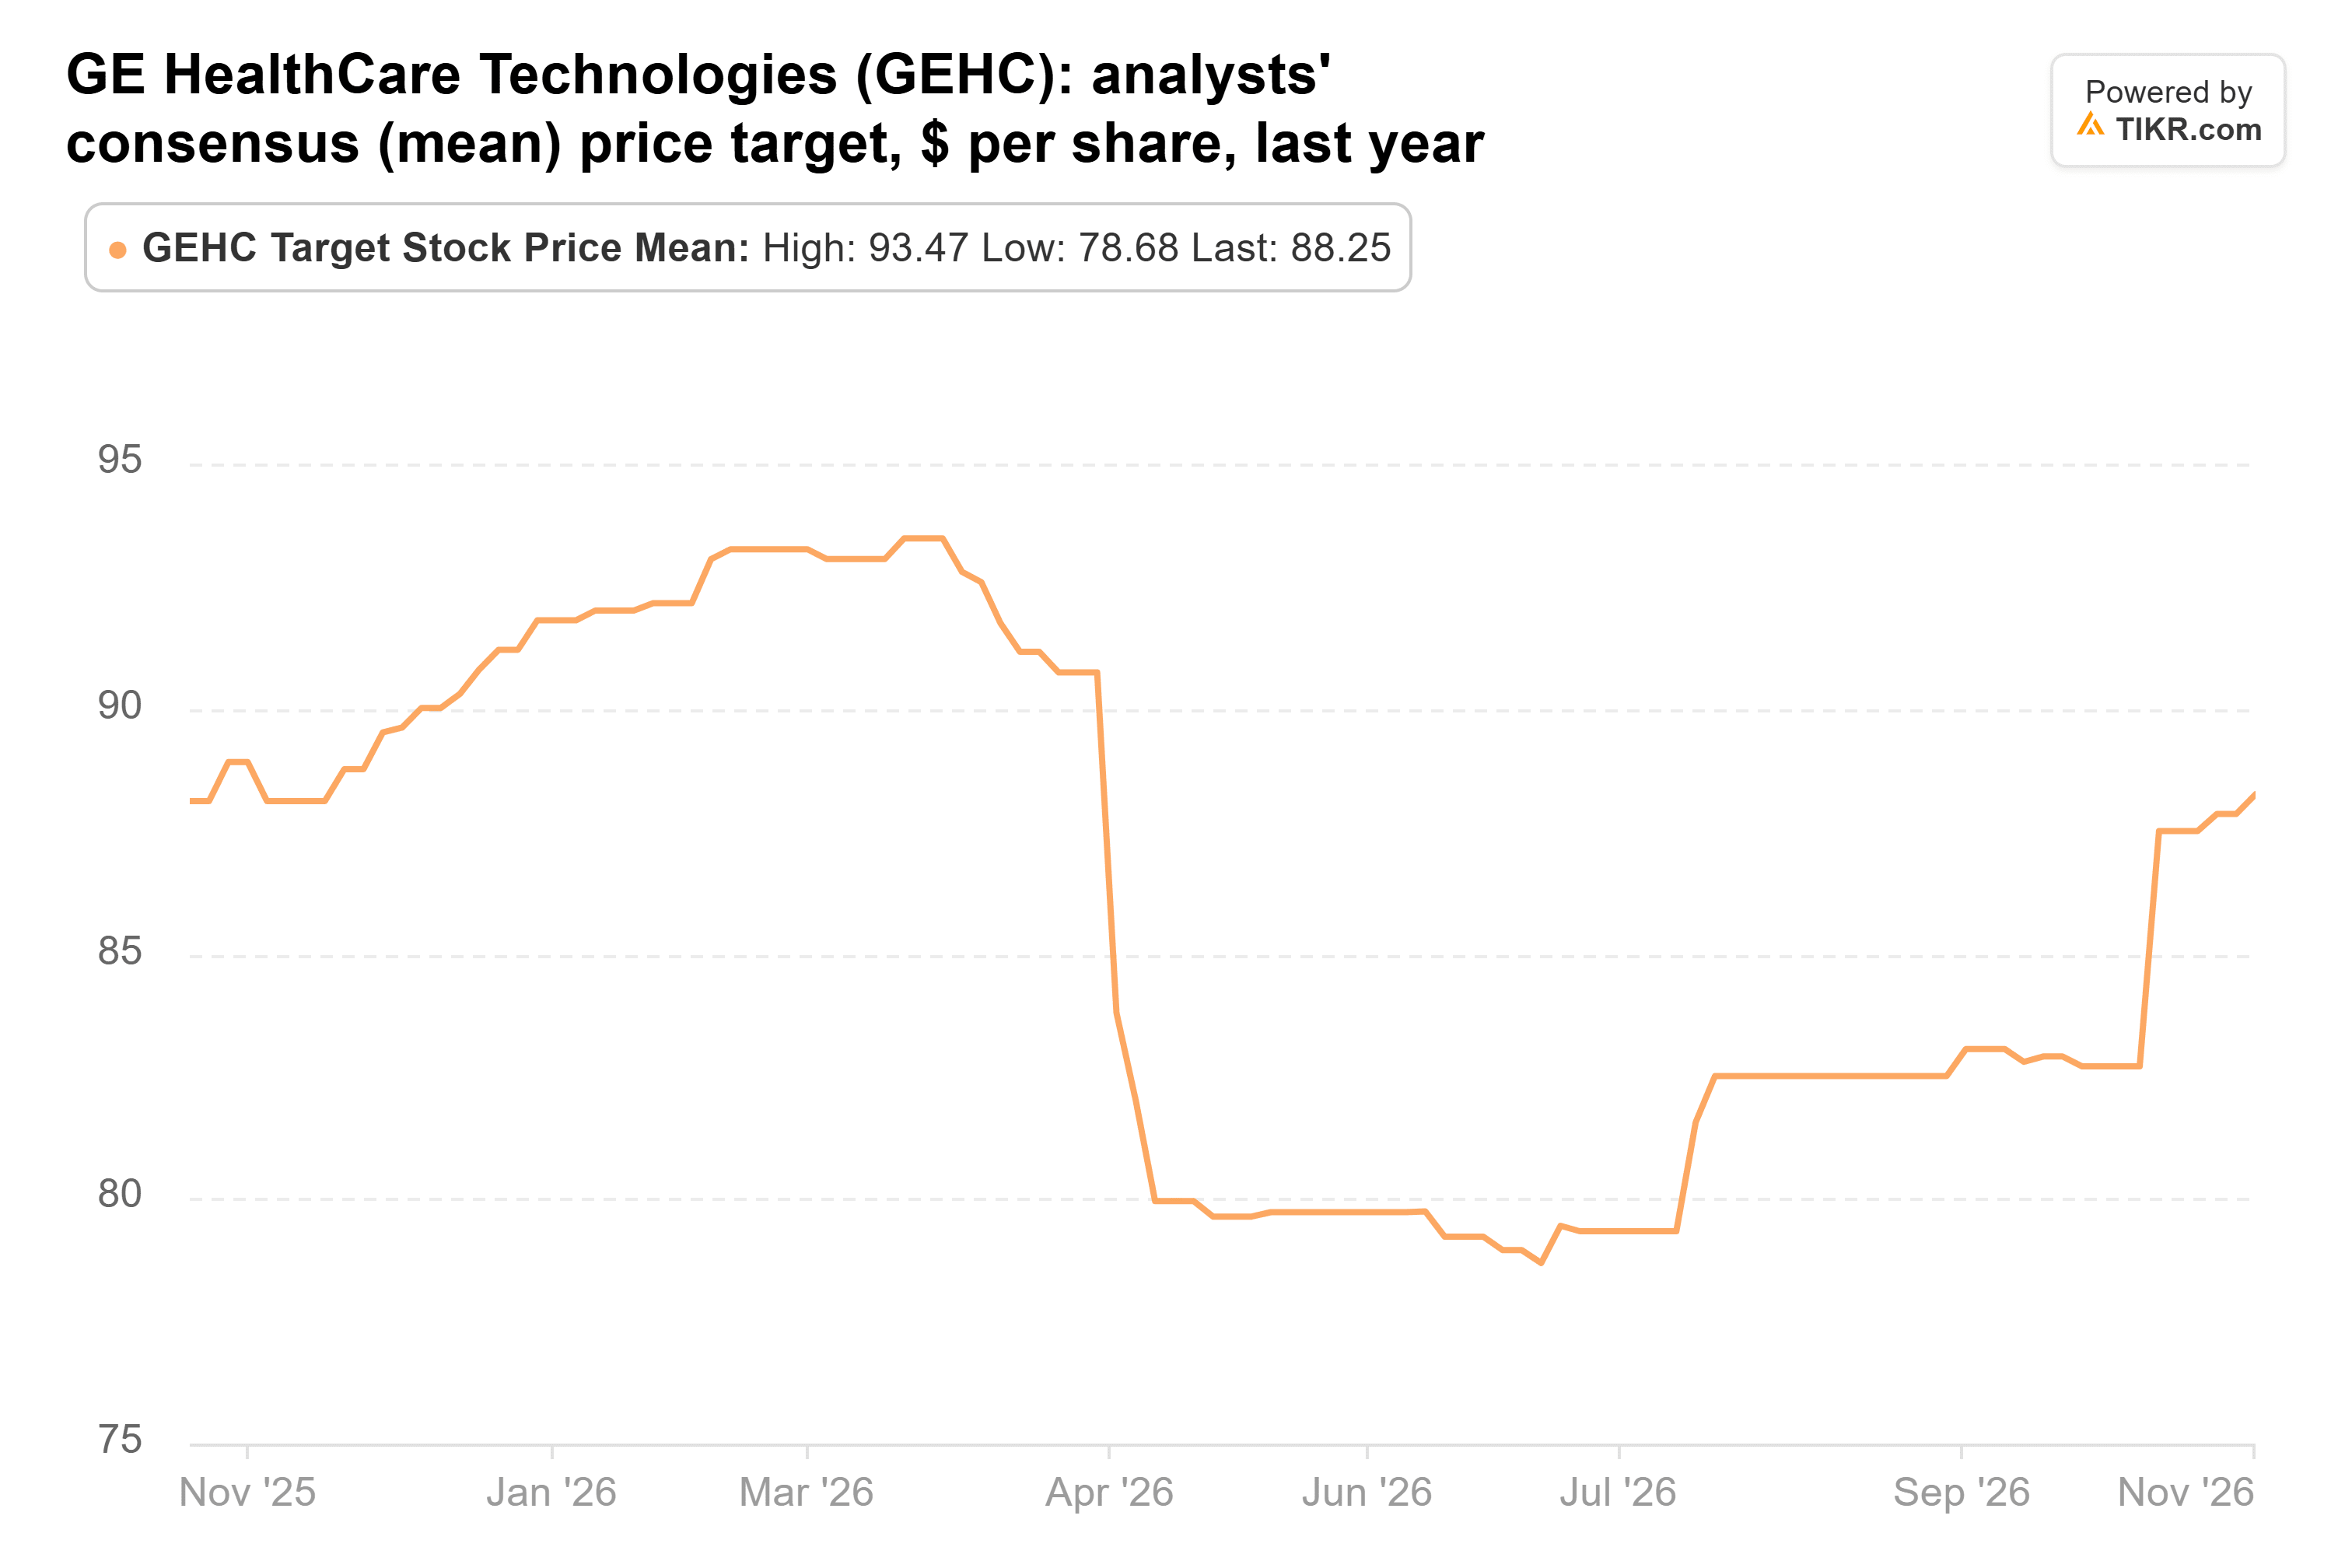
At $88.25 from 22 analysts, the target is only slightly above the $88.11 of a year ago, and just 5% above the last close. The stock trades at about 16x forward earnings, so it isn’t expensive. But most of the upside Wall Street sees is already in the price.
Danaher is the newest bet
Danaher (DHR) was a tiny holding at June 30. By Sept. 30, the fund had grown that stake by more than 3,800%, to 10.08 million shares worth $2.23 billion, 1.2% of its 13F stocks. The stock is up 3% from its Sept. 30 price.
Three weeks after the quarter ended, Danaher beat on its third-quarter results, with trends improving across its end markets. Analysts had already started coming back around:
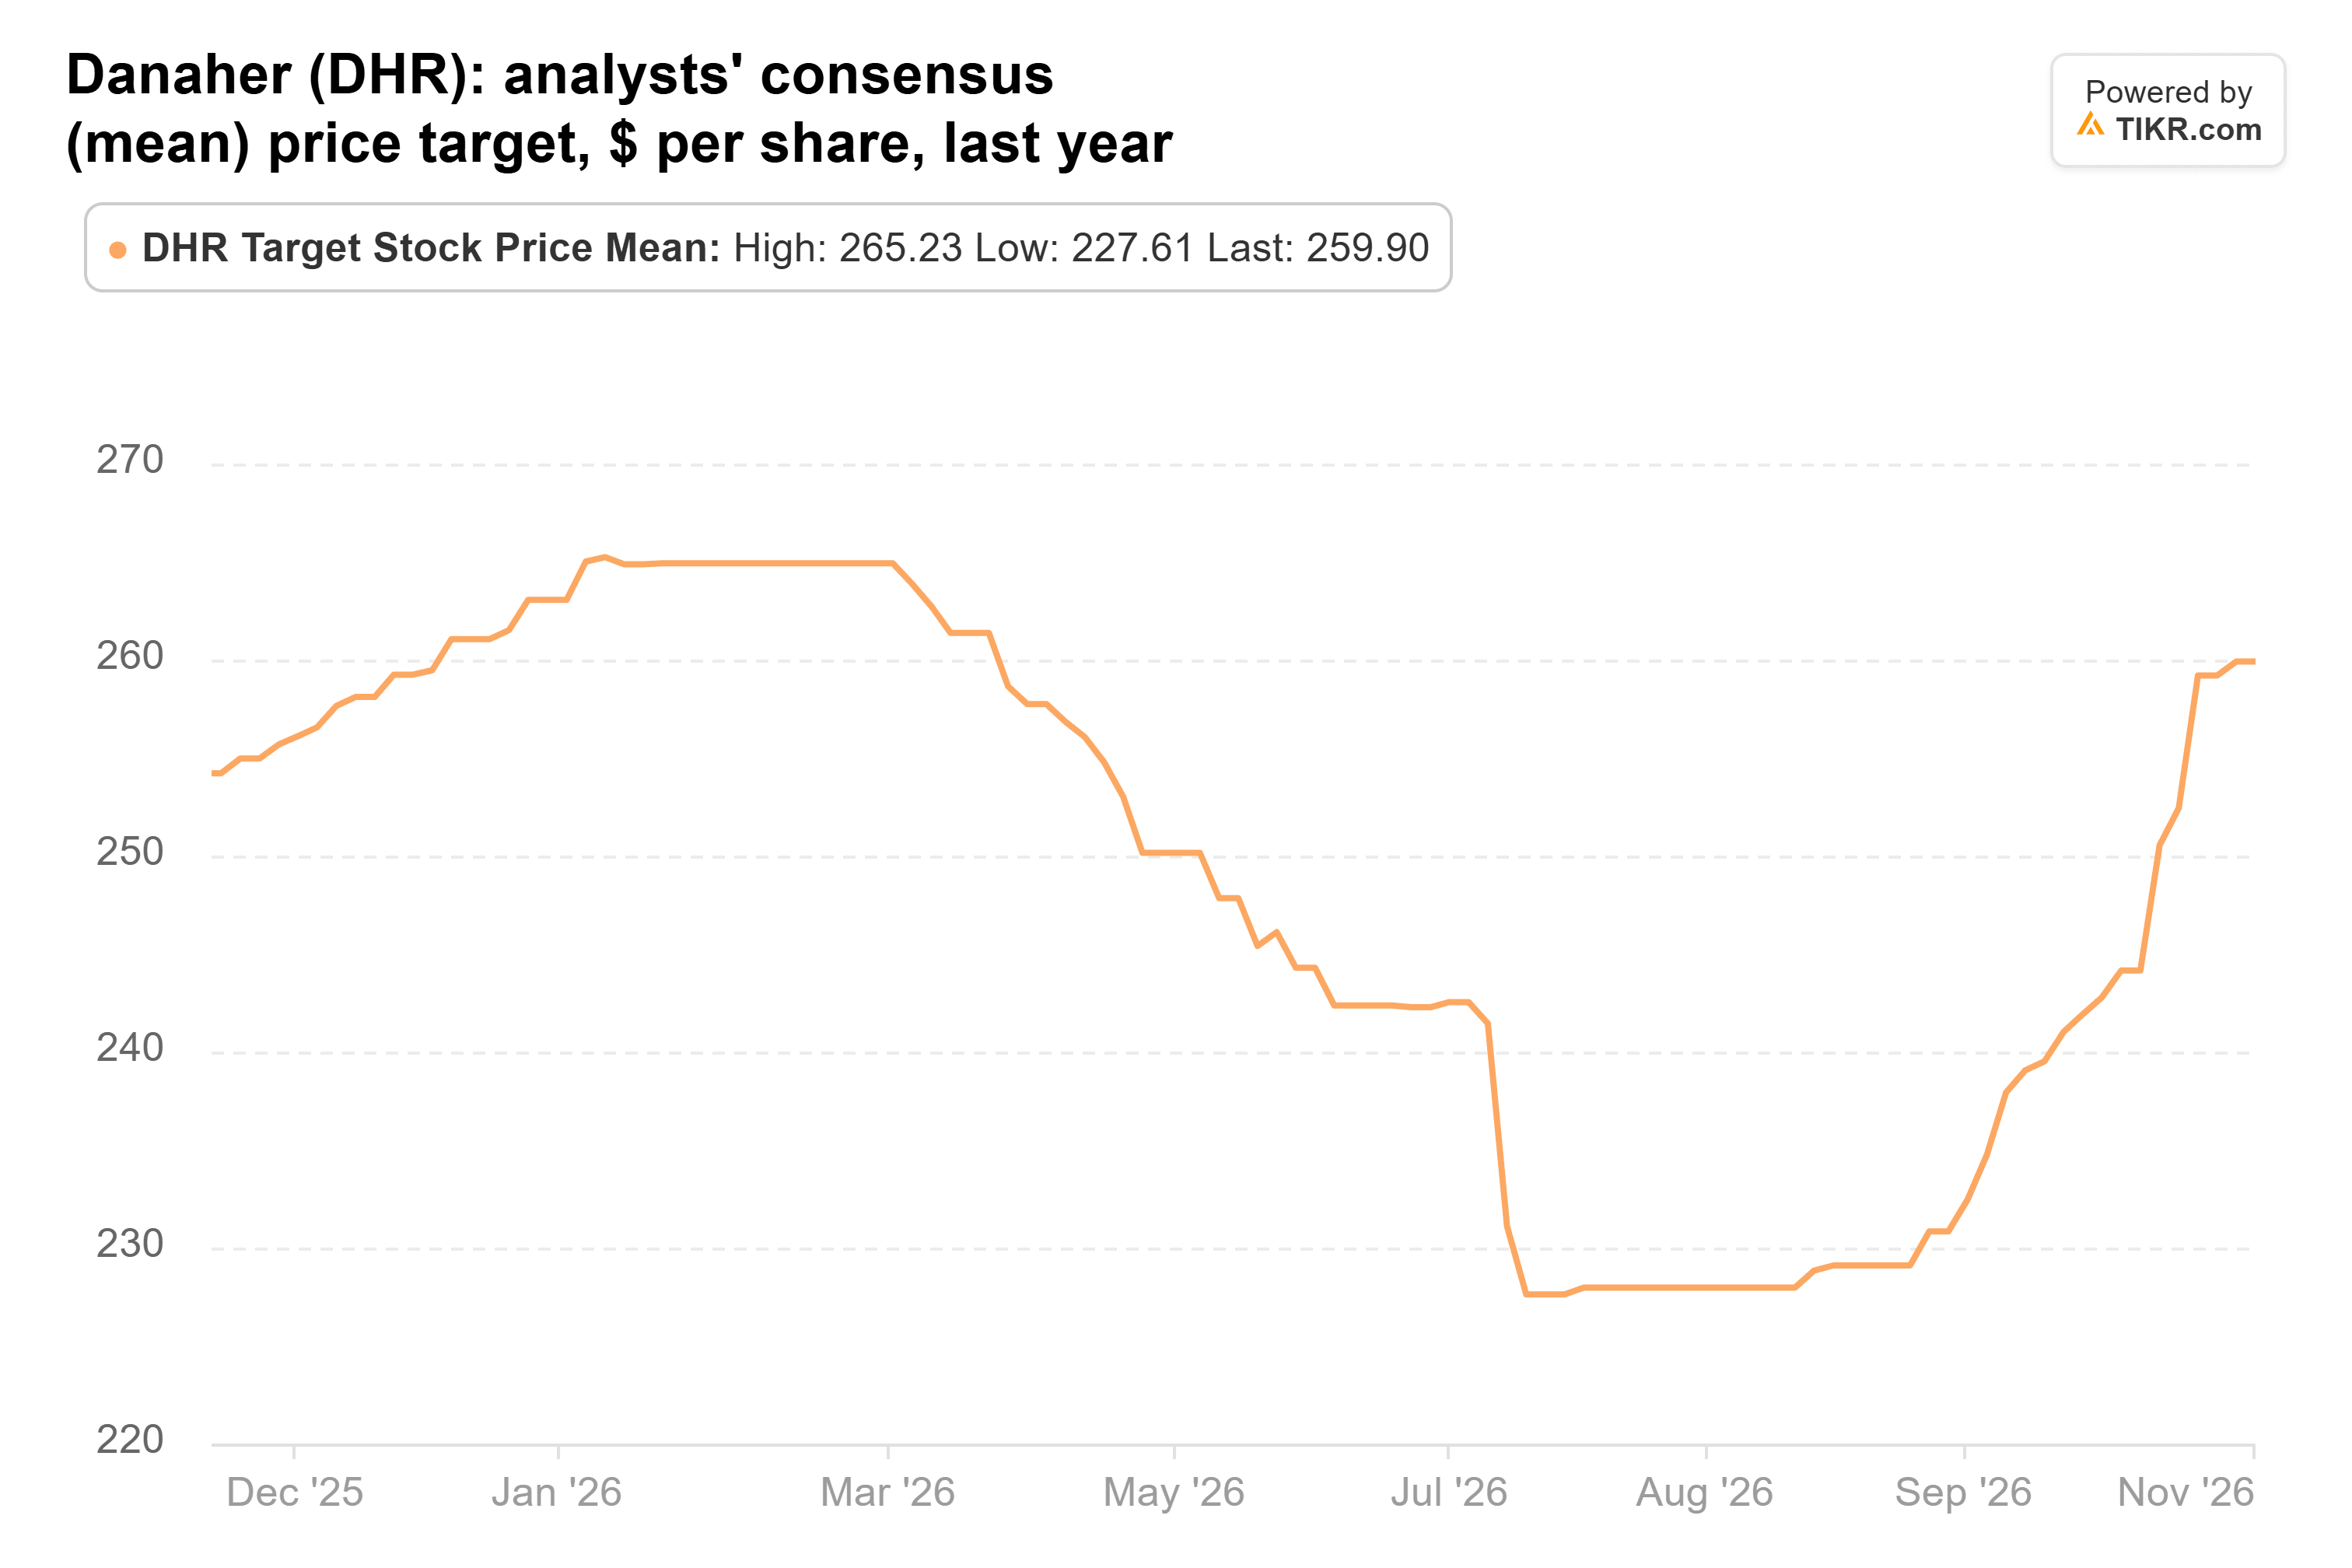
The consensus target fell to $227.61 in July and has since climbed to $259.90 from 24 analysts. That’s above the $254.20 of a year ago and 14% above the last close. At about 25x forward earnings, Danaher isn’t cheap, so analysts are counting on that recovery to keep going.
Amazon is the one to own
Amazon trades at about 27x forward earnings, close to the cheapest it’s been in more than a decade. Over the year to October, analysts raised their 2028 earnings estimates 24%. That’s a lot of expected growth at a multiple this low.
The risk is cash. Amazon has guided to about $220 billion of capex this year. Consensus has its free cash flow negative this year and next, before it turns into a $37.8 billion inflow in 2028.
Still, if I could only buy one of the three right now, it’d be Amazon: AWS is speeding up, and Wall Street sees the most upside in it. GE HealthCare’s run has taken most of its upside, and Danaher needs its recovery to hold.
The next test is Amazon’s fourth-quarter report in early February, which brings its 2027 capex outlook. Consensus has 2027 capex at $278.2 billion. A guide below that, with AWS growth intact, would pull the turn to positive cash flow closer. The fund’s next 13F, due in mid-February, will show whether it kept buying.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


