


Key Takeaways
- Walmart fell about 2% in morning trading despite a beat and a raised adjusted EPS outlook of $2.84 to $2.89.
- The top of that range only matches the $2.89 analysts already expected, not much for a stock at 43x forward earnings.
- Target and Dollar General trade at about 17x and grew comparable sales faster than Walmart U.S.
- The next test comes in February, when Walmart guides next year against $3.23 of consensus EPS.
Walmart (WMT) beat on sales and earnings on Nov. 19 and raised its full-year outlook for the second time this fiscal year. The stock fell about 2% in morning trading anyway.
The price is the problem. Walmart came into the report trading at more than twice Target’s forward multiple, and the new guidance does little to close that gap. Meanwhile, Target (TGT) and Dollar General (DG) are growing comparable sales faster for far less.
The Raise Only Caught Up to the Street
Third-quarter revenue rose 5.2% to $188.8 billion, and adjusted EPS of $0.65 beat expectations by a cent. Adjusted operating income grew 5.5% in constant currency, ahead of the 2% to 4% Walmart had guided.
For the fiscal year ending in January, Walmart now expects adjusted EPS of $2.84 to $2.89, up from $2.80 to $2.87. The midpoint rose 3 cents, or about 1%.
Going into the report, the consensus for this year was already $2.89, with about 12% growth expected the year after:
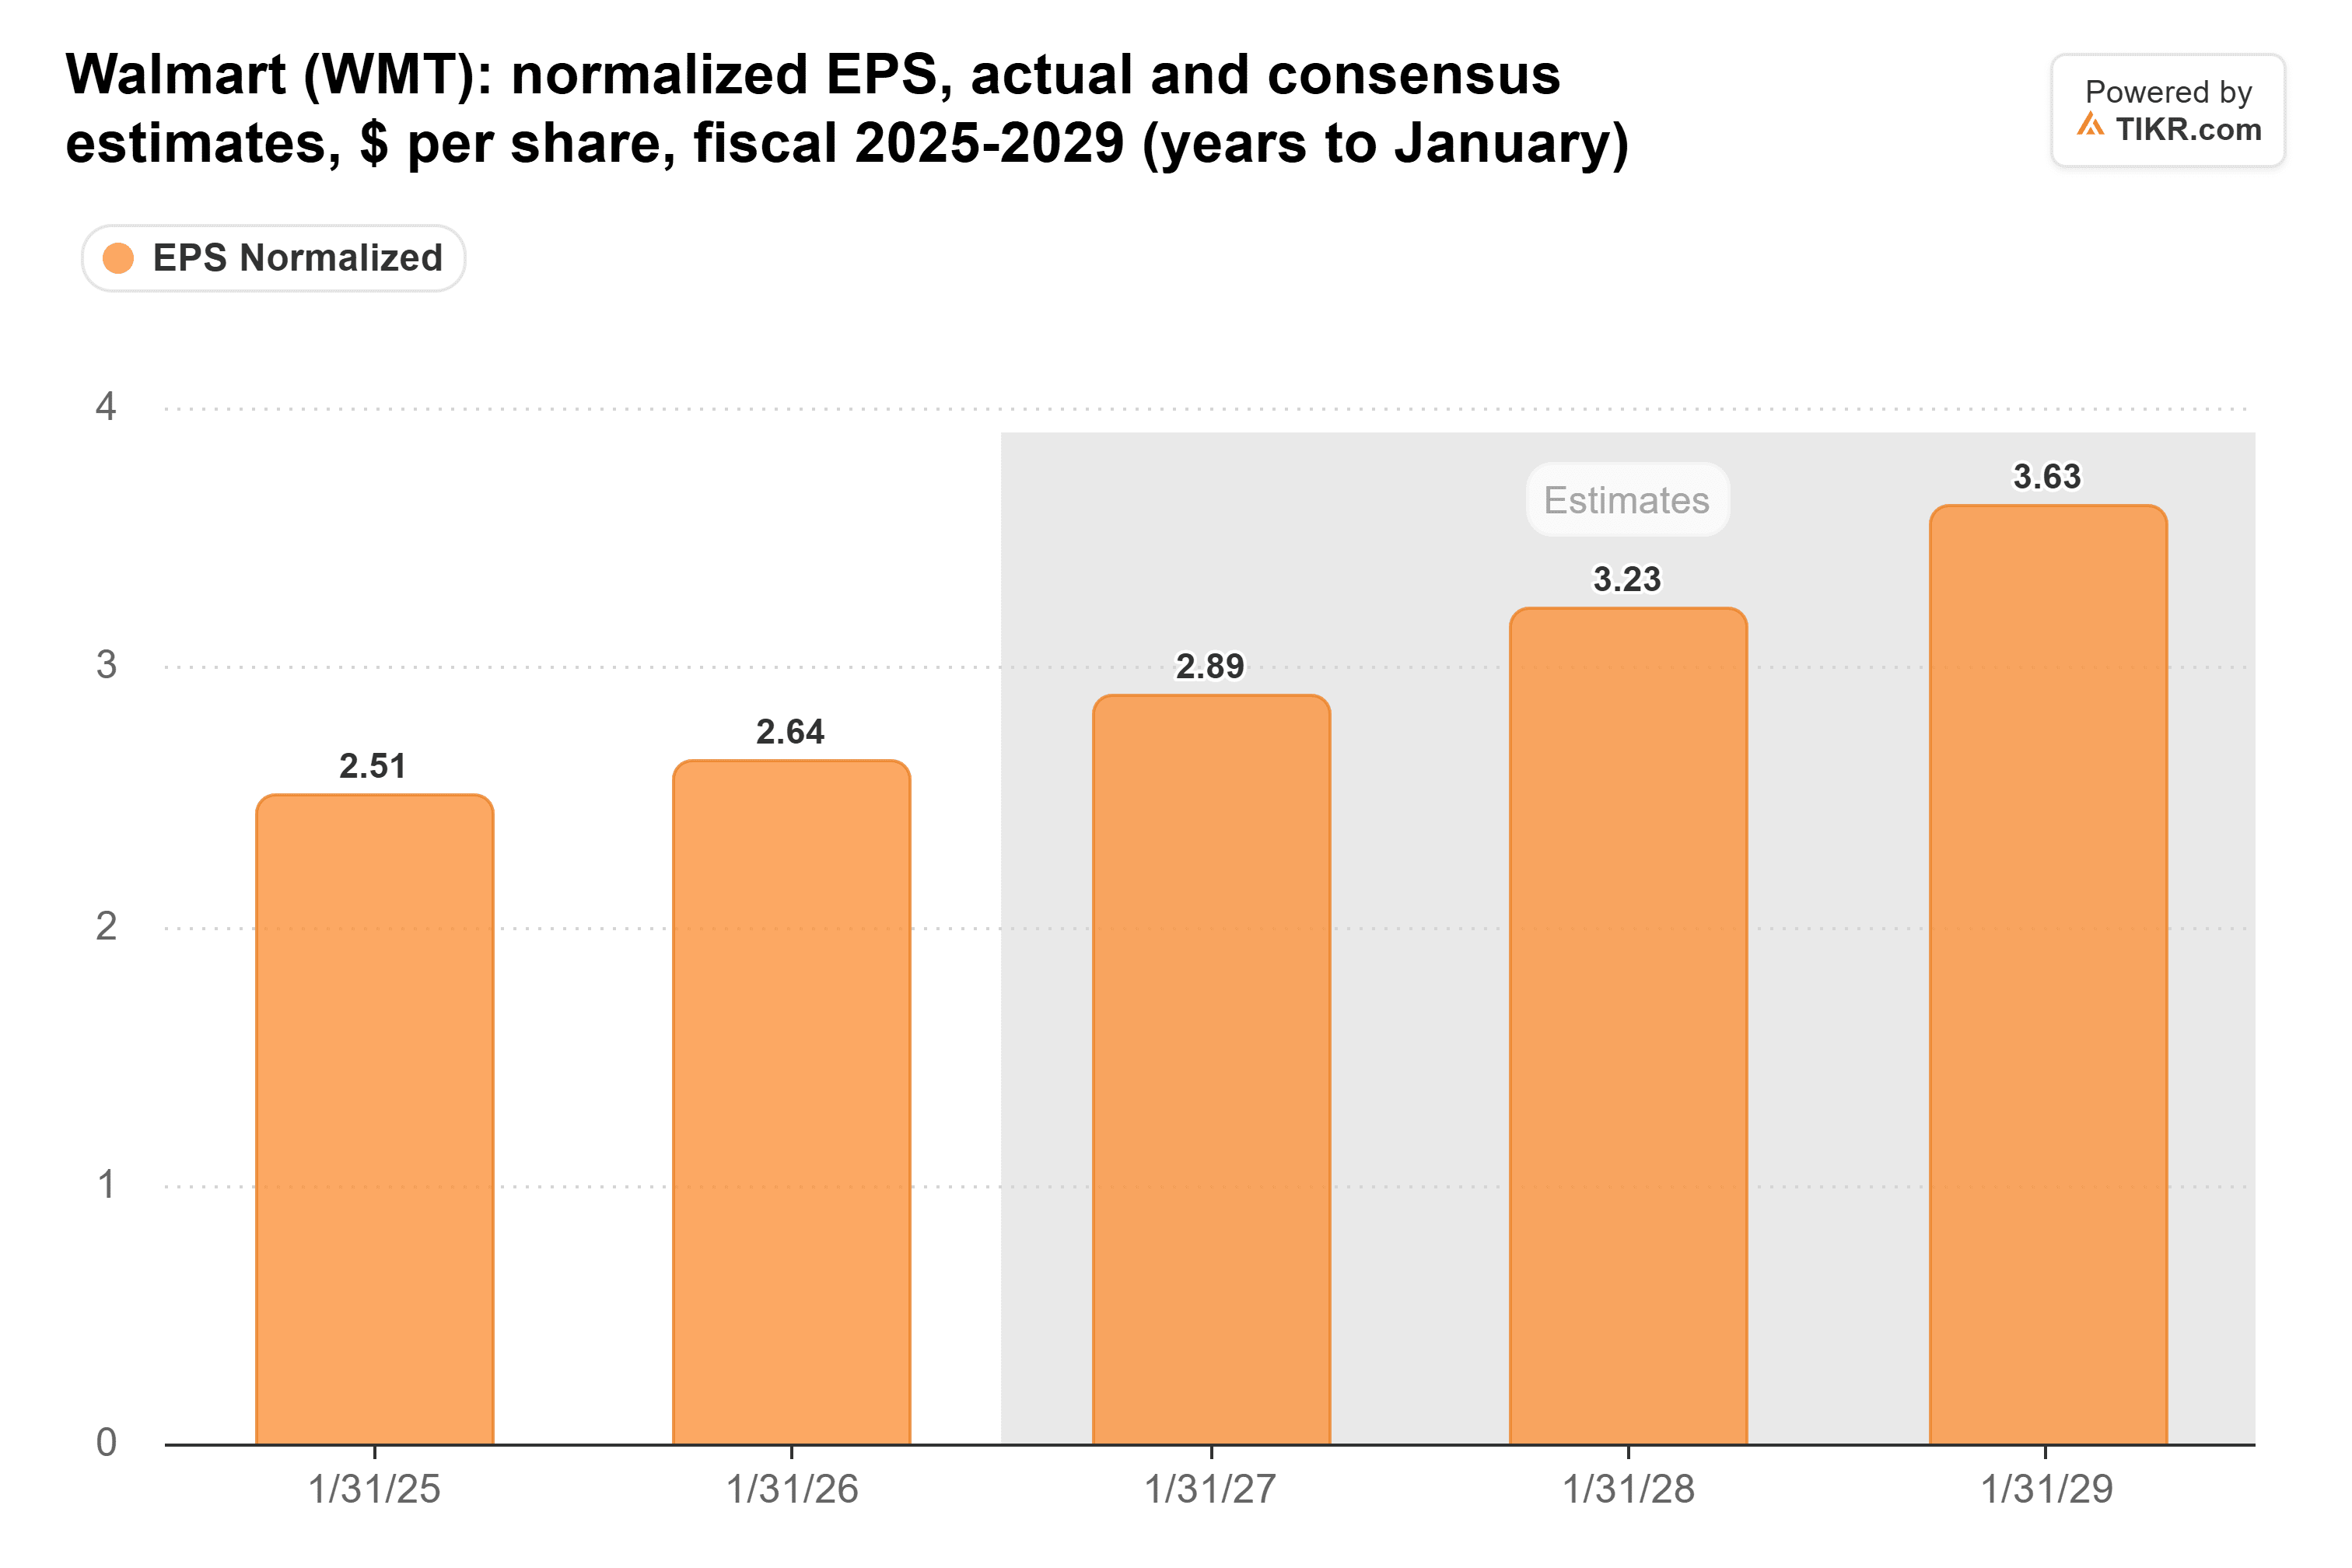
The raise brought Walmart’s guidance up to where the Street already was.
At 43x, a Few Cents Don’t Go Far
As of the last close, Walmart traded at 43x forward earnings, far above its five-year average of 30x and close to the 47x it hit in February:
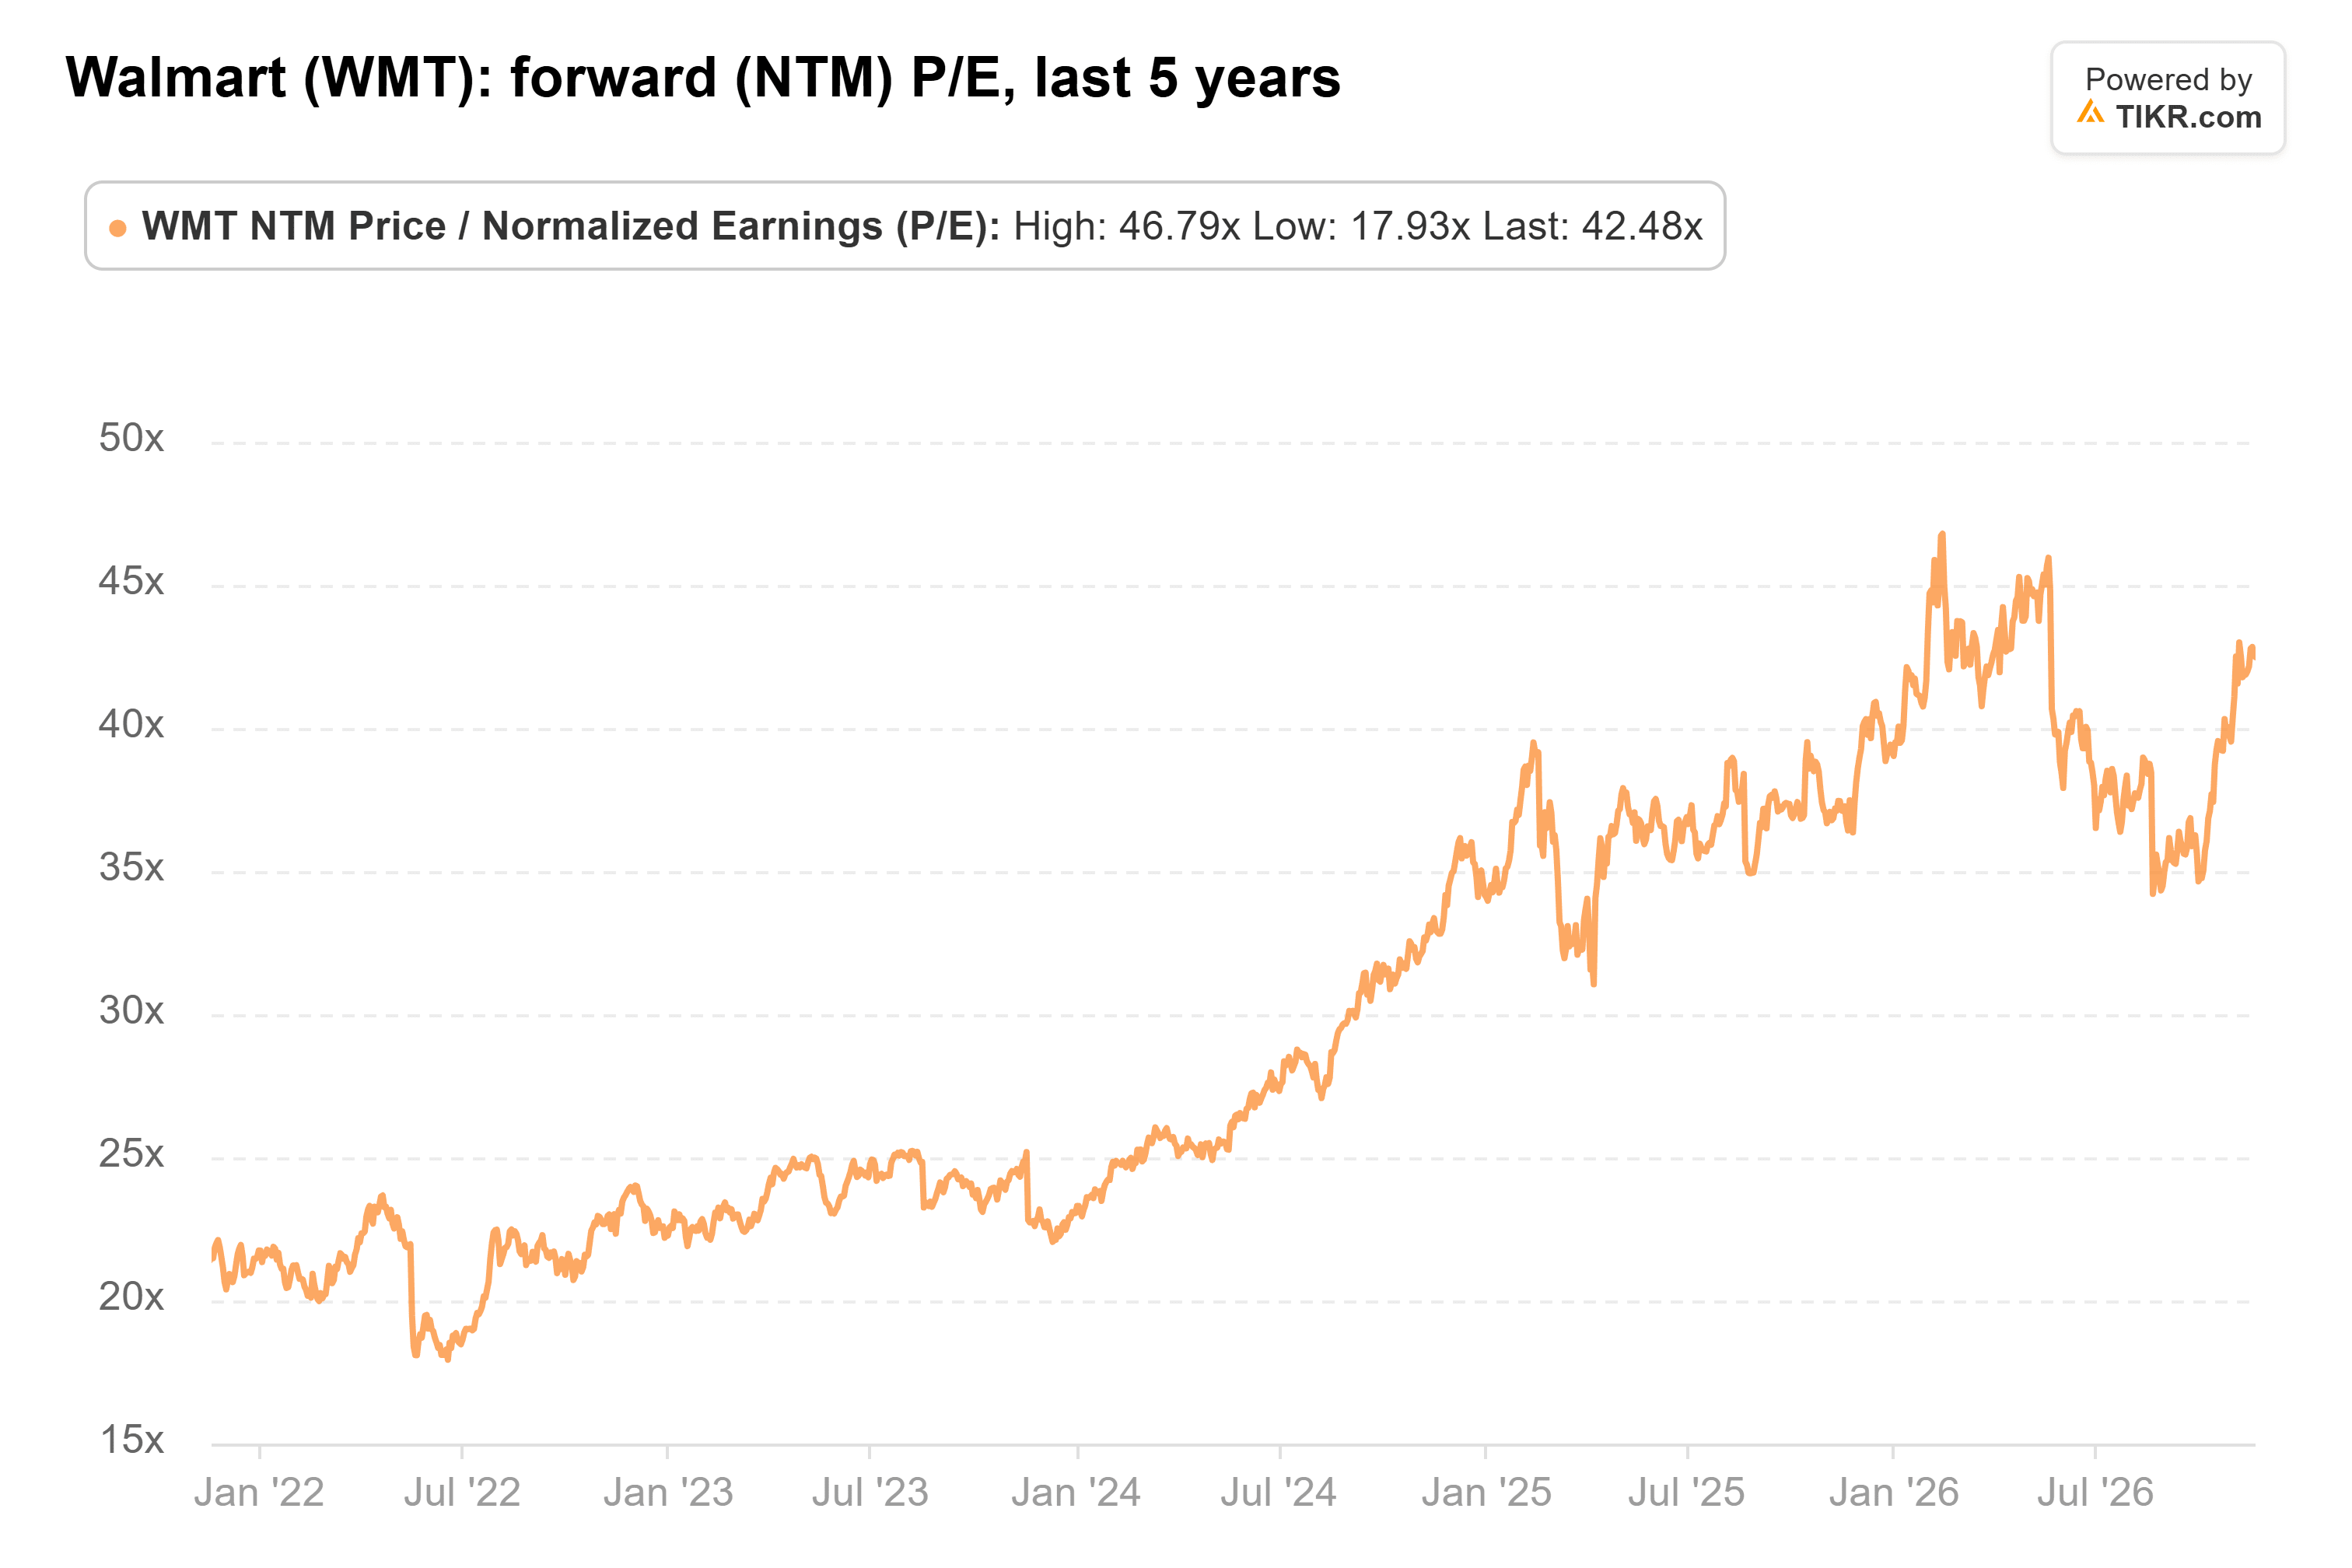
At that multiple, adding 1% to this year’s earnings doesn’t count for much. The Nov. 19 drop took more than that off the stock.
Underneath, the business is growing at its usual pace. Revenue grew a little under 6% a year from fiscal 2022 to fiscal 2026 (years ending in January):
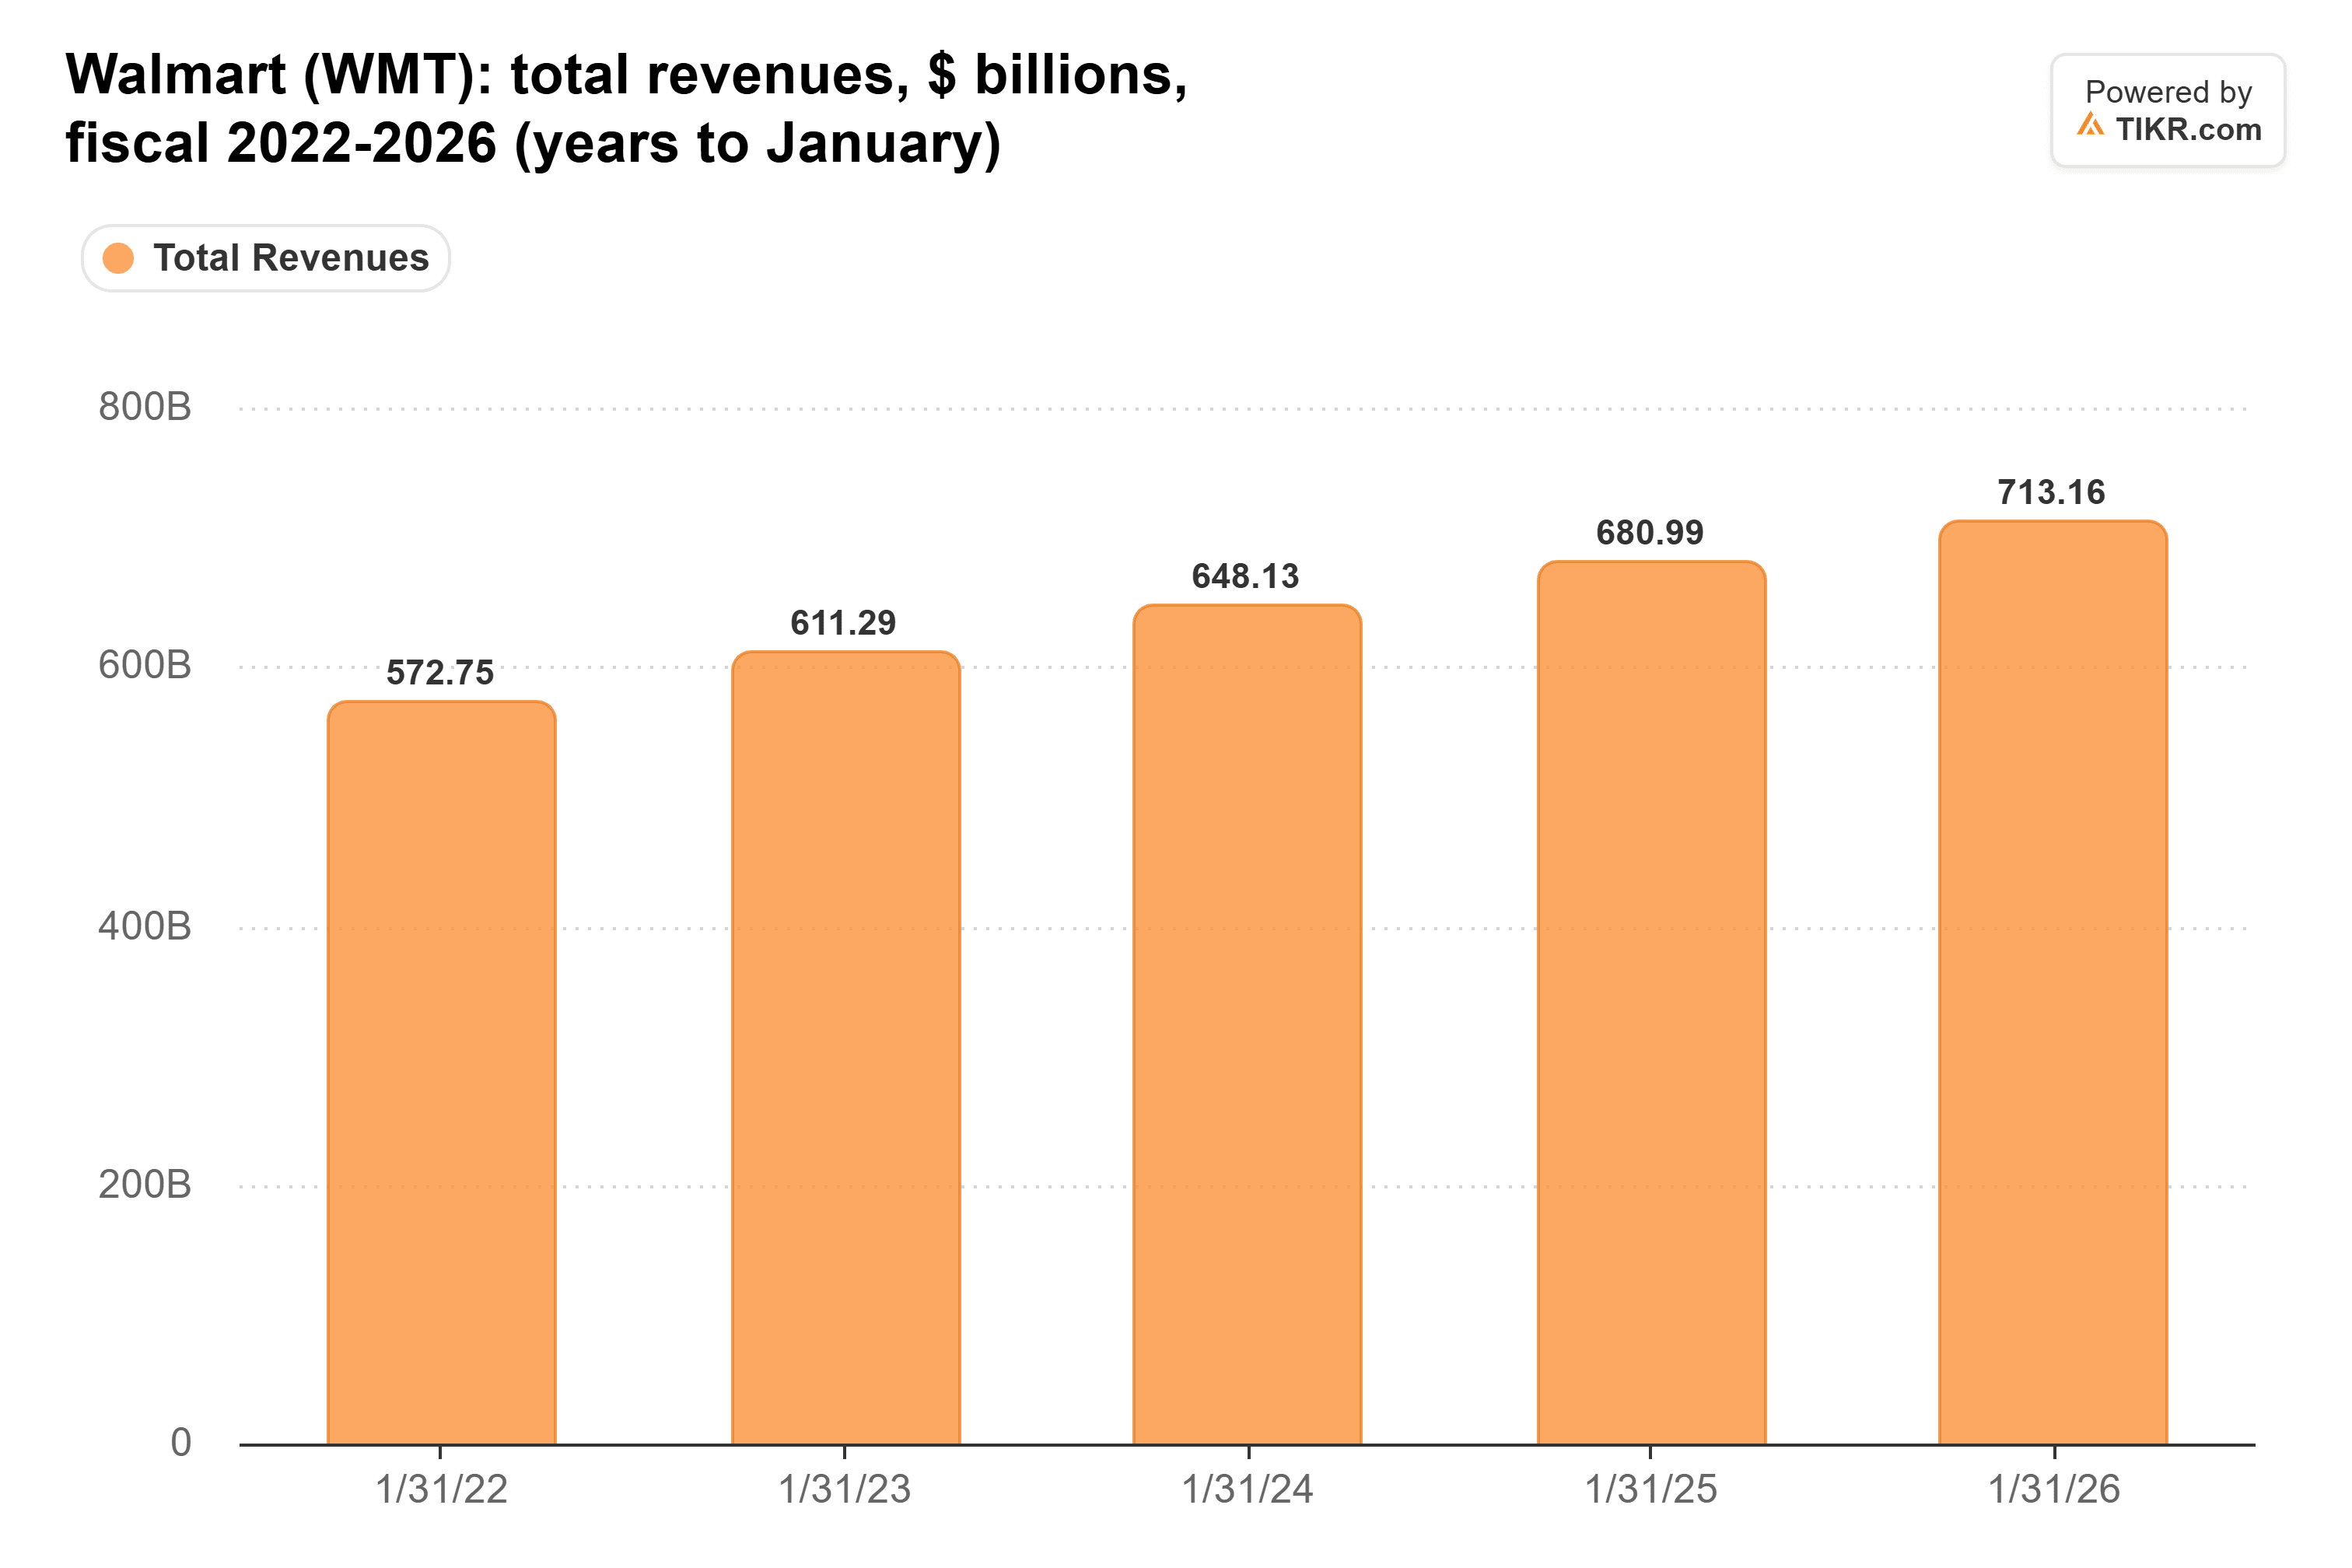
The bull case rests on advertising and membership lifting profit faster than sales, and Walmart’s U.S. advertising business grew 37% in the quarter. But adjusted operating income grew 5.5% in constant currency, only a point faster than revenue’s 4.5%, as Walmart kept cutting prices and absorbed higher fuel costs.
TIKR Tracks 44 Analysts on Walmart. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Walmart, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Walmart’s Analyst Ratings
Target and Dollar General Are Growing Faster at 17x
Walmart U.S. comparable sales grew 2.9% excluding fuel. Target’s grew 5.6% in the same quarter. Target said a 5.0% increase in traffic drove that growth. Its $10.65 to $11.40 EPS guidance includes about $2.14 in tariff refund benefits, but it still trades at 17x forward earnings.
Dollar General’s same-store sales grew 3.5% in the quarter to July 31, against 2.6% at Walmart U.S. over the same three months. It reports in early December, and that report will show whether its shoppers are leaning on essentials the way Walmart’s grocery customers are.
What Walmart’s February Guide Has to Show
Walmart is running the business well. But at 43x, the stock needs profit to grow clearly faster than sales, and this guidance asks investors to keep paying up for margin gains that haven’t fully arrived. I’d wait for a lower price.
The real test comes in February, when Walmart guides the fiscal year ending January 2028. Analysts expect $3.23 of EPS for that year. An outlook above that, with operating income guided well ahead of sales, would go a long way toward justifying the multiple.
So What Is Walmart Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Walmart could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


