Key Takeaways
- Nvidia’s receivables rose about $18 billion in its record October quarter, to $81.0 billion.
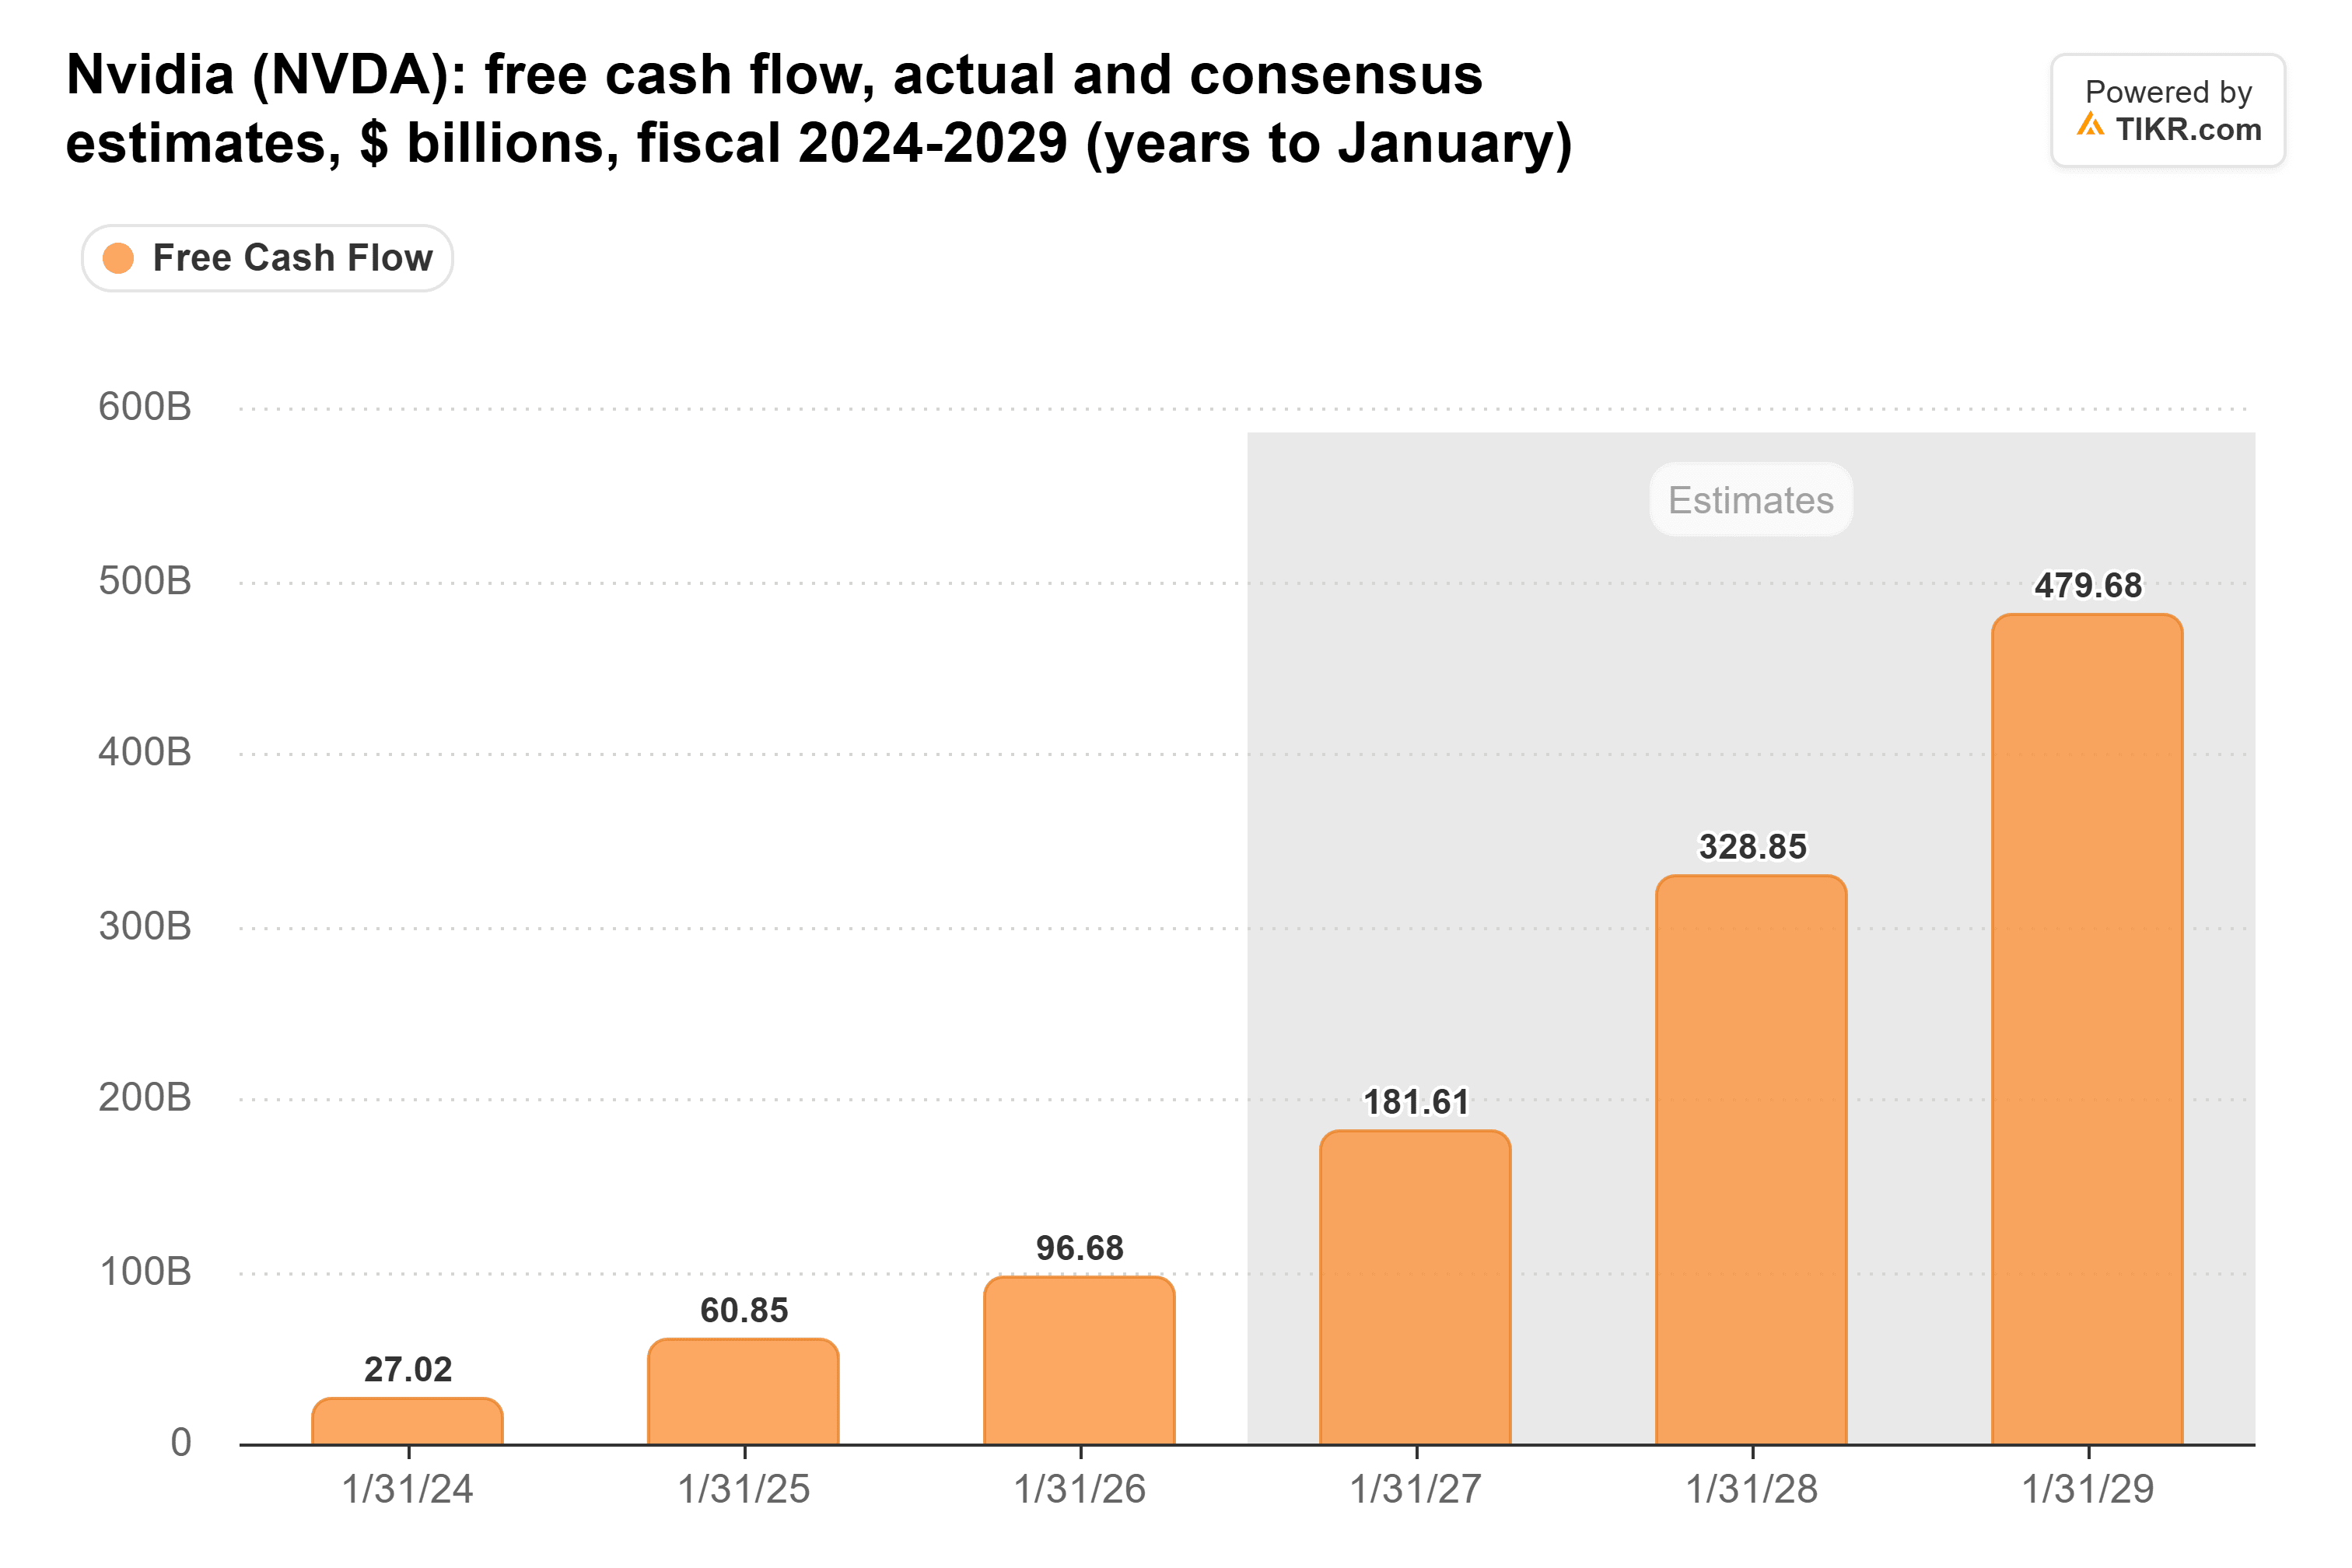
- Nvidia generated $43.8 billion of free cash flow last quarter and needs about $68 billion in the fourth to meet the full-year estimate.
- Nvidia plans to be more selective in backing customers, and Moody’s cut its outlook over governance.
- Arista Networks’ collection days fell to 59, and Broadcom reports Dec. 9.
Nvidia (NVDA) just reported a record $115.8 billion quarter, and its customers are taking longer to pay for it. Accounts receivable rose about $18 billion in the quarter ended Oct. 25, to $81.0 billion, nearly matching revenue’s $19.6 billion rise. Nvidia puts that at 64 days of sales, up from 60 in July, and Yahoo Finance notes that’s the most since the 2022 chip slump.
Broadcom (AVGO) and Arista Networks (ANET) sell into the same AI data center builds. Broadcom turned 46% of its $29.6 billion of revenue into free cash flow in the quarter ended Aug. 2, and Arista grew revenue 58.5% in its September quarter. If AI buyers were stretching payments everywhere, their books would show it.
As of Nov. 18, analysts expected about $182 billion of free cash flow in the fiscal year ending January 2027:
Nvidia’s Receivables Have Doubled This Year
Receivables are up from $38.5 billion in January:
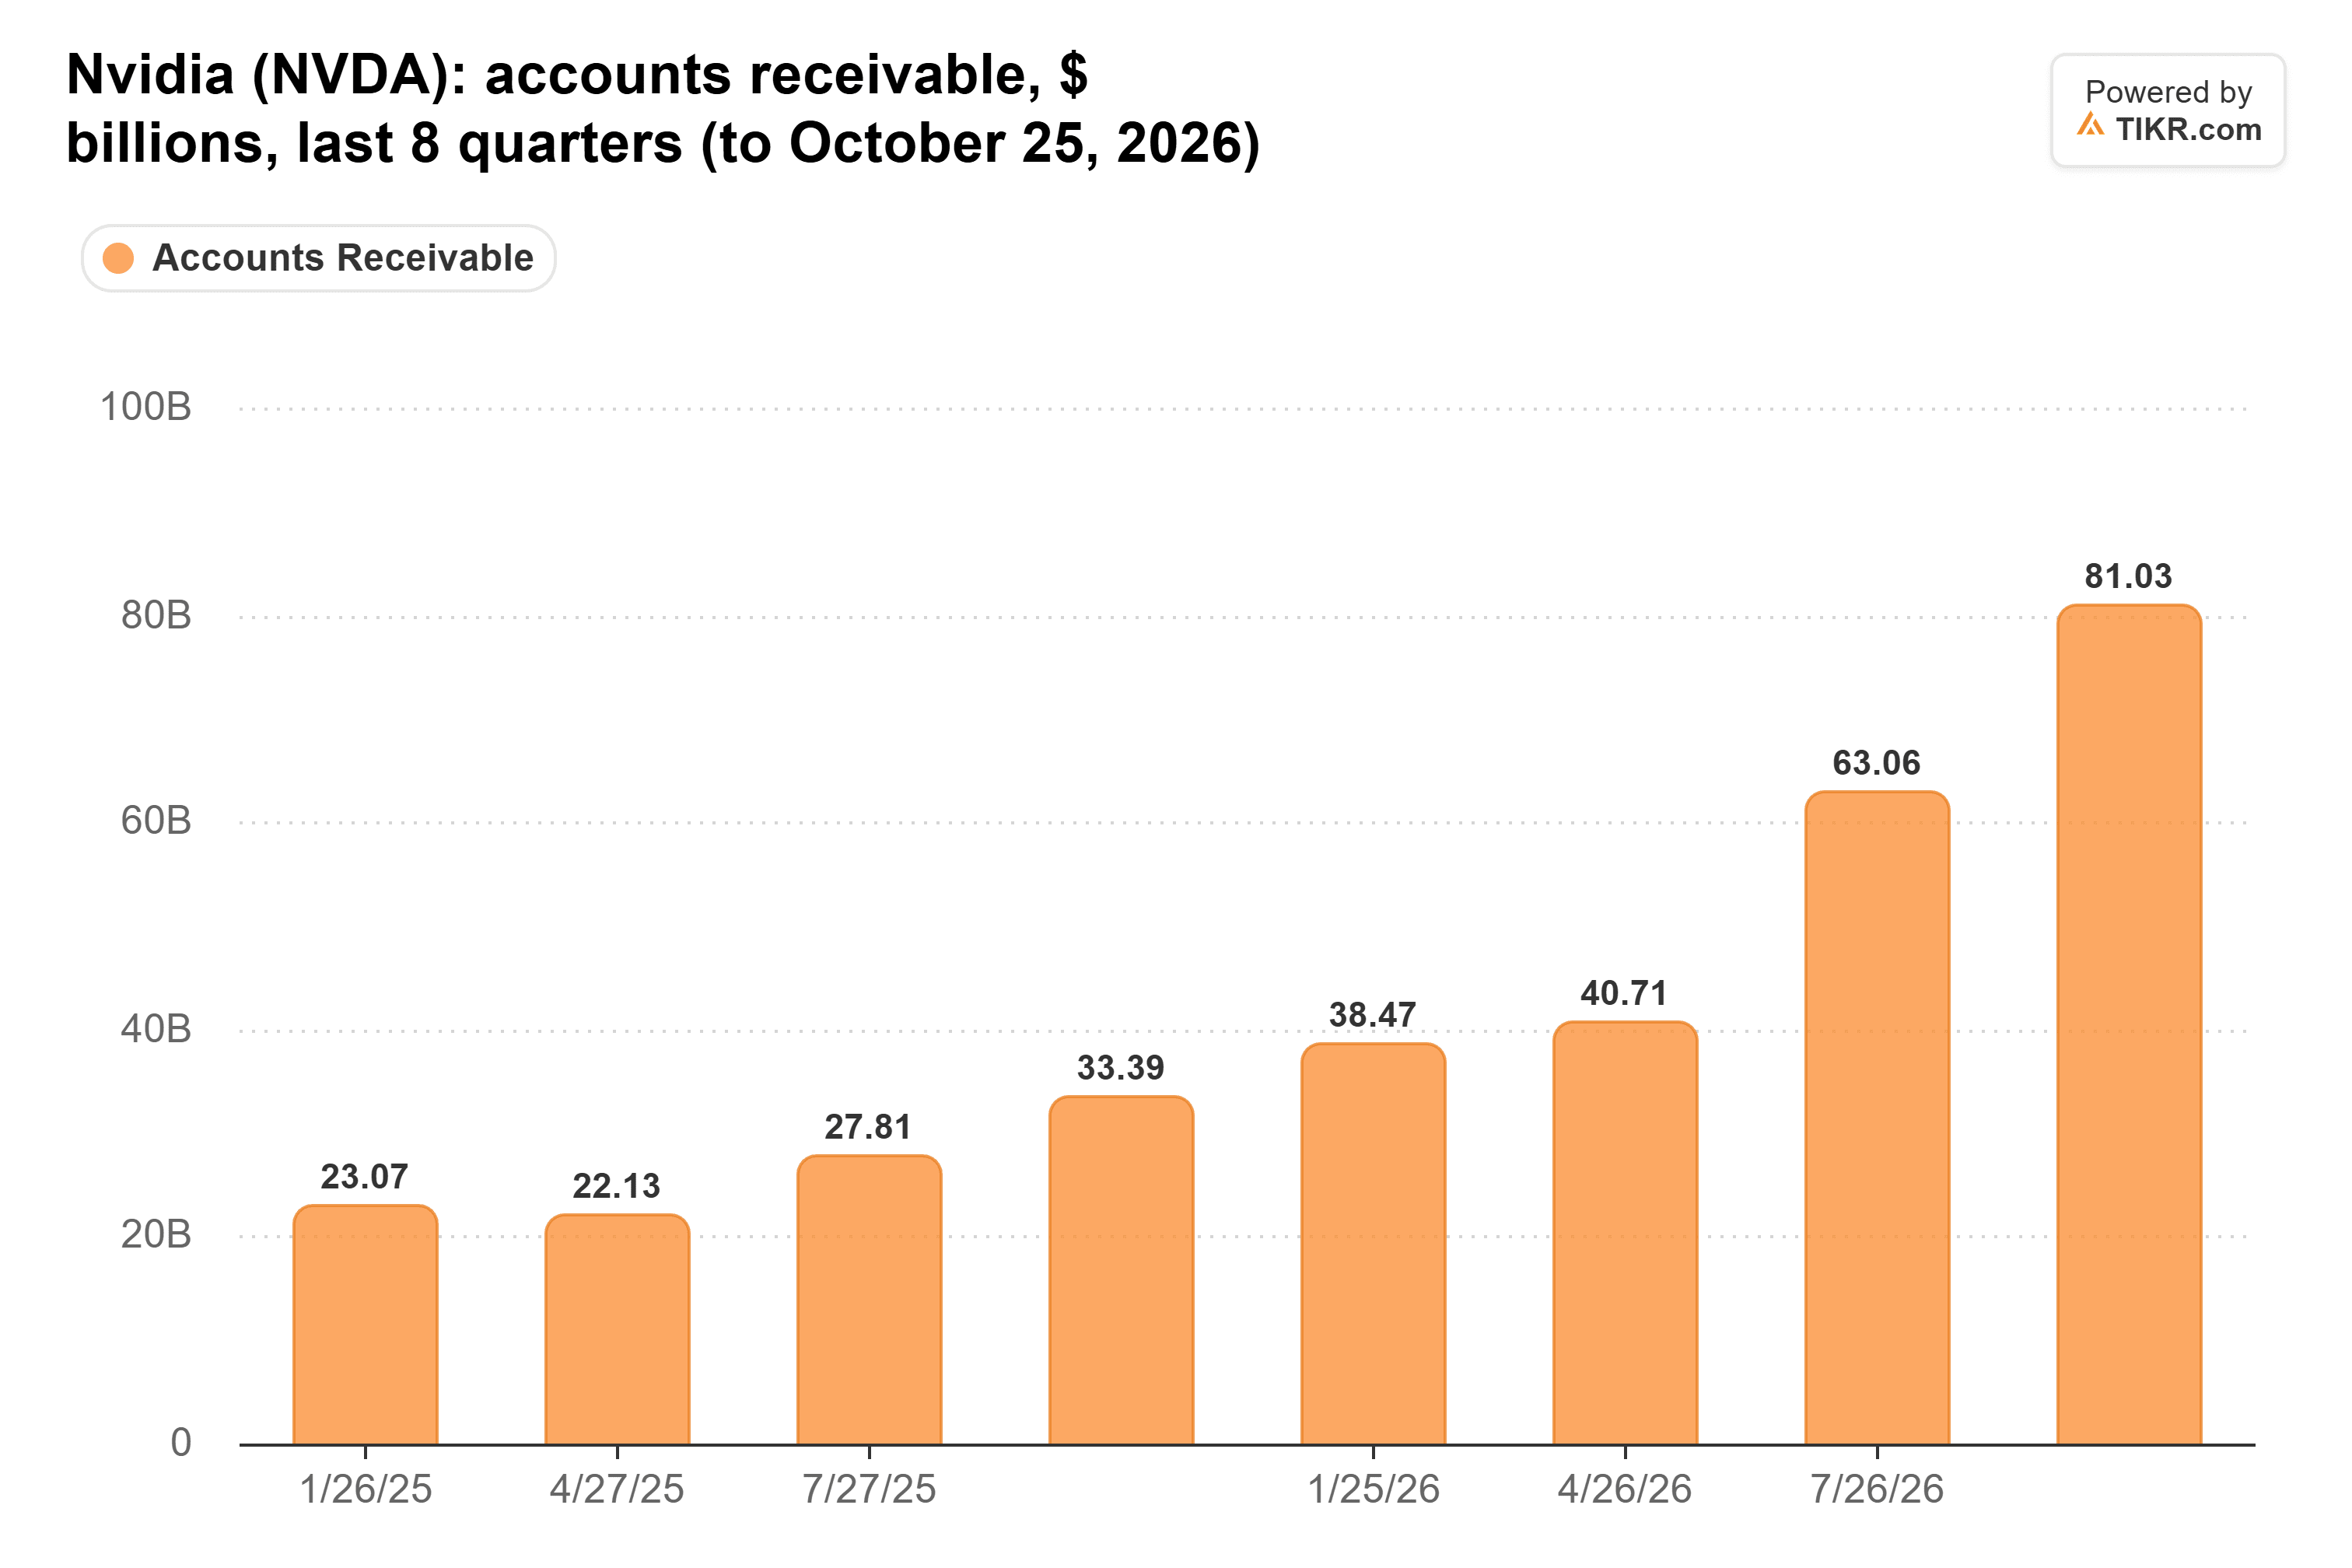
Nvidia ties the latest jump to Rubin shipment timing and “extended payment terms on large, multi-quarter agreements with certain investment-grade customers.” Its July 10-Q already showed terms of 90 days to a year for those buyers, so much of the wait is Nvidia’s choice. The catch is concentration: on July 26, five direct customers held 70% of its receivables.
TIKR Tracks 62 Analysts on Nvidia. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
The Cash Still Showed Up
Nvidia generated $43.8 billion of free cash flow in the October quarter, double July’s $21.3 billion:
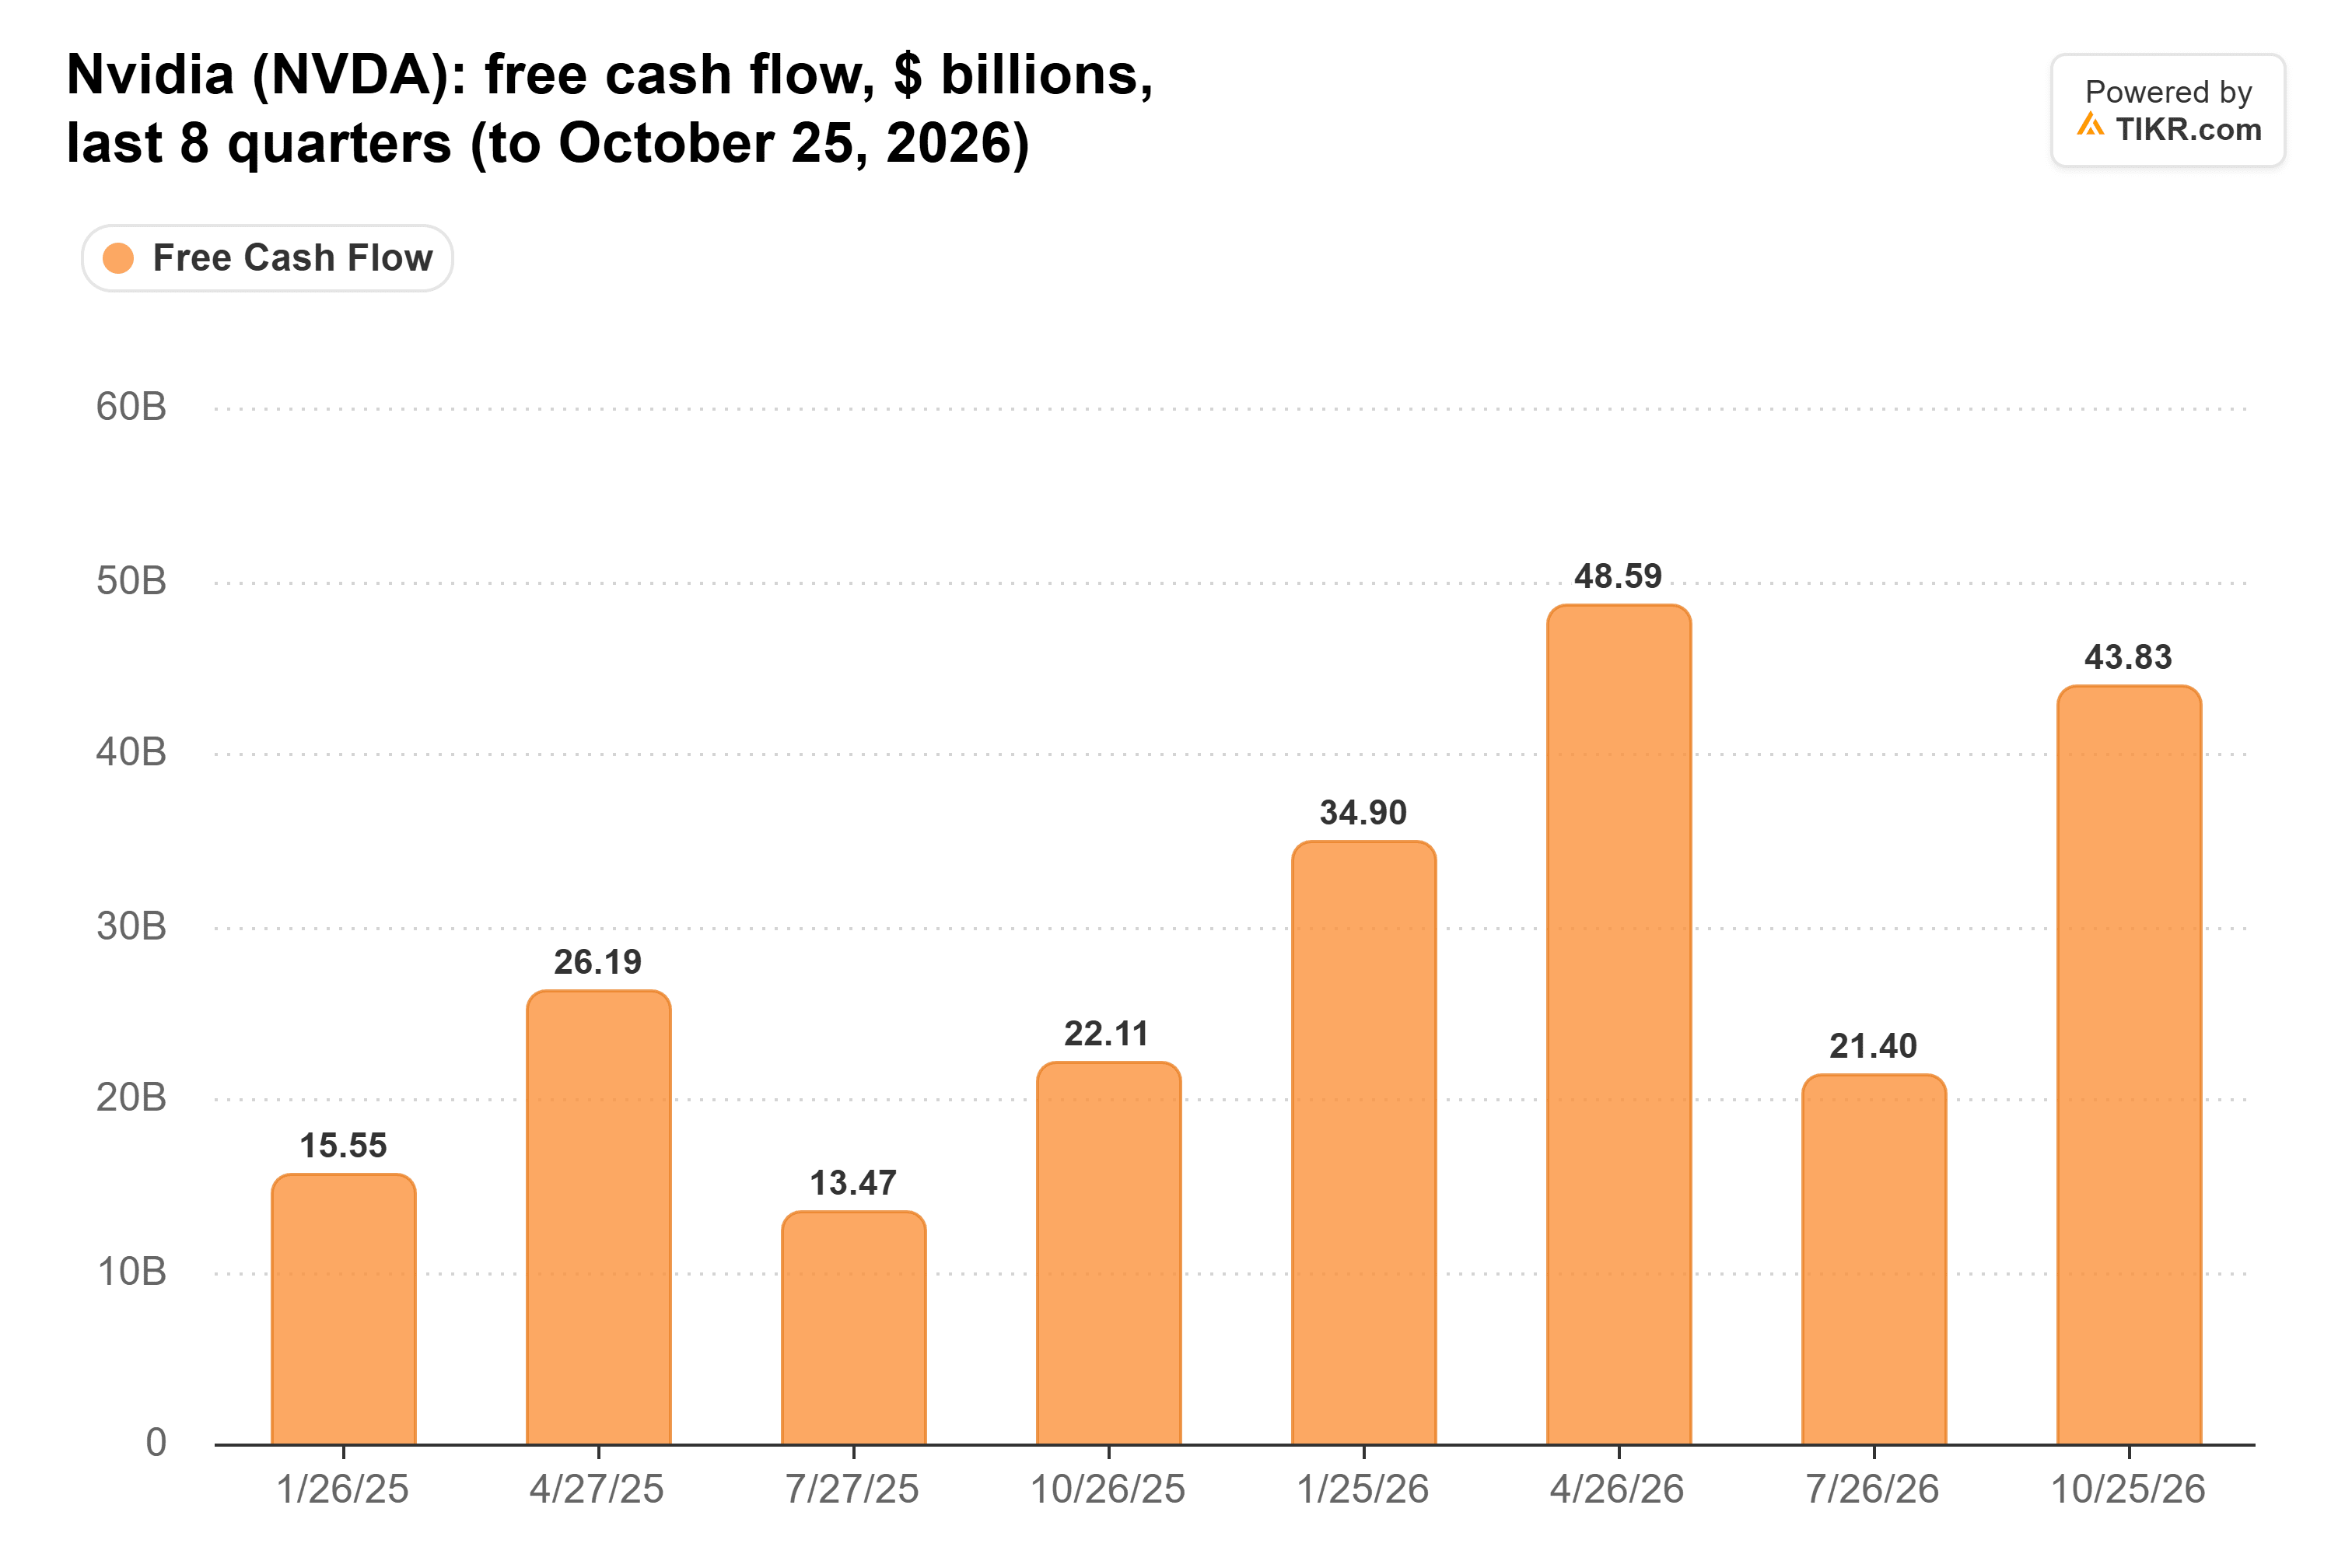
That’s about 38% of revenue, below the 45% Nvidia converted in the year ended January 2026 but well above July’s 22%. Part of that jump is federal cash tax timing, Nvidia said.
Nvidia Is Getting Choosier
Nvidia says it will be more selective about backing customers. “As the market matures and additional sources of capital become available, we are rigorously evaluating future investments, commitments, and guarantees,” interim CEO and CFO Colette Kress said on the Nov. 17 call.
Moody’s cut its outlook on Nvidia to stable from positive on Nov. 18 and kept its Aa1 rating. The reason was governance after Jensen Huang’s resignation, not the receivables.
Arista’s Collection Days Fell
Arista’s days sales outstanding moved the other way, falling to 59 from 68 in the September quarter, which its CFO attributed to the timing of customer shipments.
Broadcom, which sells custom chips to many of the same labs, is the closer test. Its Dec. 9 report will show companywide receivables against total revenue; Hock Tan separately guided AI chip revenue to $21.7 billion for the quarter ended Nov. 1.
Nvidia’s Fourth Quarter Is the Test
Nvidia generated $113.7 billion of free cash flow through three quarters. The $182 billion consensus needs about $68 billion in its 14-week fourth quarter, roughly 1.4 times its previous quarterly high.
With the longer terms limited to investment-grade buyers and cash still coming in, the slower payments look worse than they are. Concentration is the real risk.
Two direct customers held 18% and 17% of the $81 billion on Oct. 25. If fourth-quarter free cash flow reaches about $68 billion and days sales outstanding drops below 60, Nvidia meets consensus and the collection slowdown reverses.
So What Is Nvidia Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nvidia could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!