Key Takeaways
- CoreWeave fell 4% today after Nvidia said it would be more selective about which neoclouds it helps finance.
- CoreWeave’s Polaris Forge 1 lease is 30.4% of Applied Digital’s $36.2 billion of contracted revenue, so Applied Digital has more riding on it.
- Applied Digital’s financing costs ran at 2.6x its base rent in the quarter to Aug. 31.
- The next tests are CoreWeave’s next loan and whether Applied Digital can refinance the debt behind that lease more cheaply.
Nvidia (NVDA) beat estimates and raised its outlook after Tuesday’s close, and the neoclouds that rent out its chips rallied with it.
Then interim CEO Colette Kress said on the earnings call that Nvidia is “taking a very strong look in terms of the types of companies that we would want to help in terms of the financing.”
CoreWeave (CRWV) gave back its early gain and fell 4% today.
D.A. Davidson’s Gil Luria described the shift on today’s episode of Prof G Markets: “That bank of NVIDIA aspect of this is unlikely to continue.”
But the stock I’d worry about more is CoreWeave’s landlord, Applied Digital (APLD).
CoreWeave pays almost a third of the rent
Applied Digital leased all 400 MW of its Polaris Forge 1 campus in North Dakota to CoreWeave on a 15-year take-or-pay lease worth about $11.0 billion over its base term. That’s 30.4% of the $36.2 billion of contracted revenue Applied Digital had signed as of May 31.
Analysts expect Applied Digital’s revenue to more than triple from fiscal 2026 to fiscal 2028.
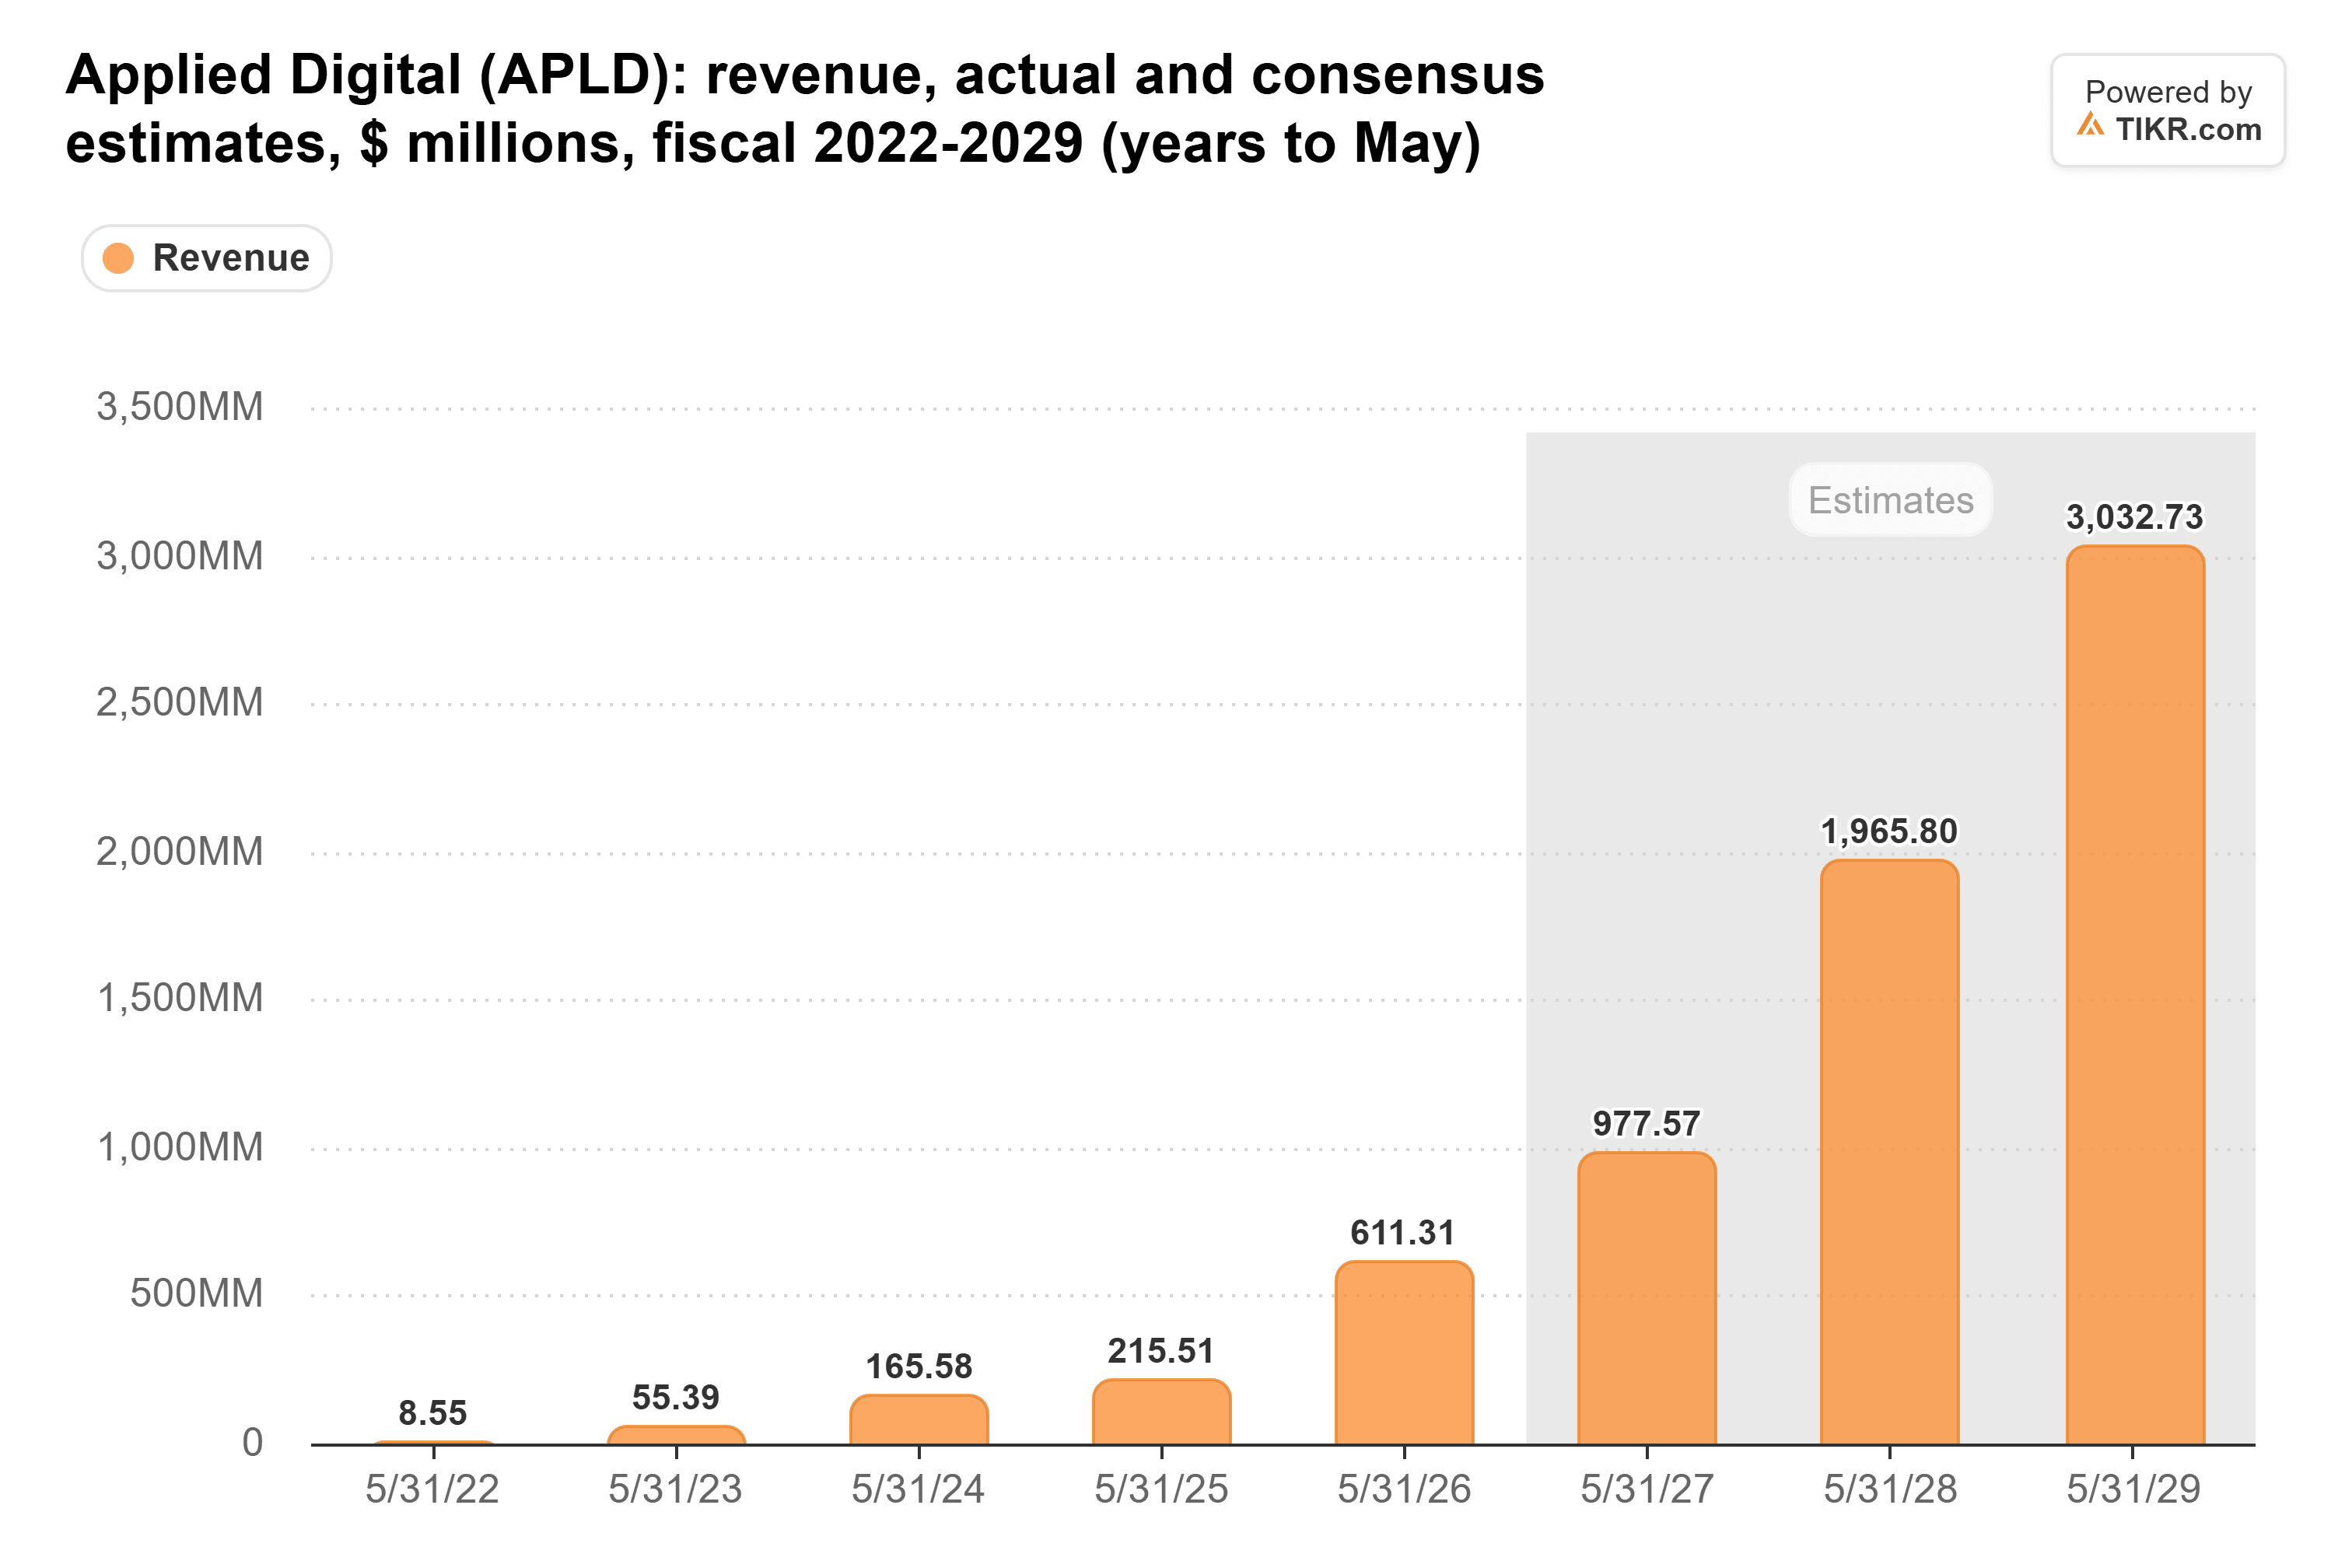
Once all 400 MW are live, CoreWeave’s rent alone comes to about $730 million a year. That’s more than a third of the $1.97 billion analysts expect for fiscal 2028.
TIKR tracks 41 analysts on CoreWeave. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoreWeave, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoreWeave’s Analyst Ratings
That lease backs nearly $4 billion of notes
CoreWeave’s leases help back two of Applied Digital’s note issues: $2.35 billion of 9.25% notes sold in November 2025 and $1.59 billion of 7.00% notes sold in June 2026. That borrowing now shows up in GAAP interest expense, which rose to about $79 million in the quarter to Aug. 31 from about $10 million a year earlier.
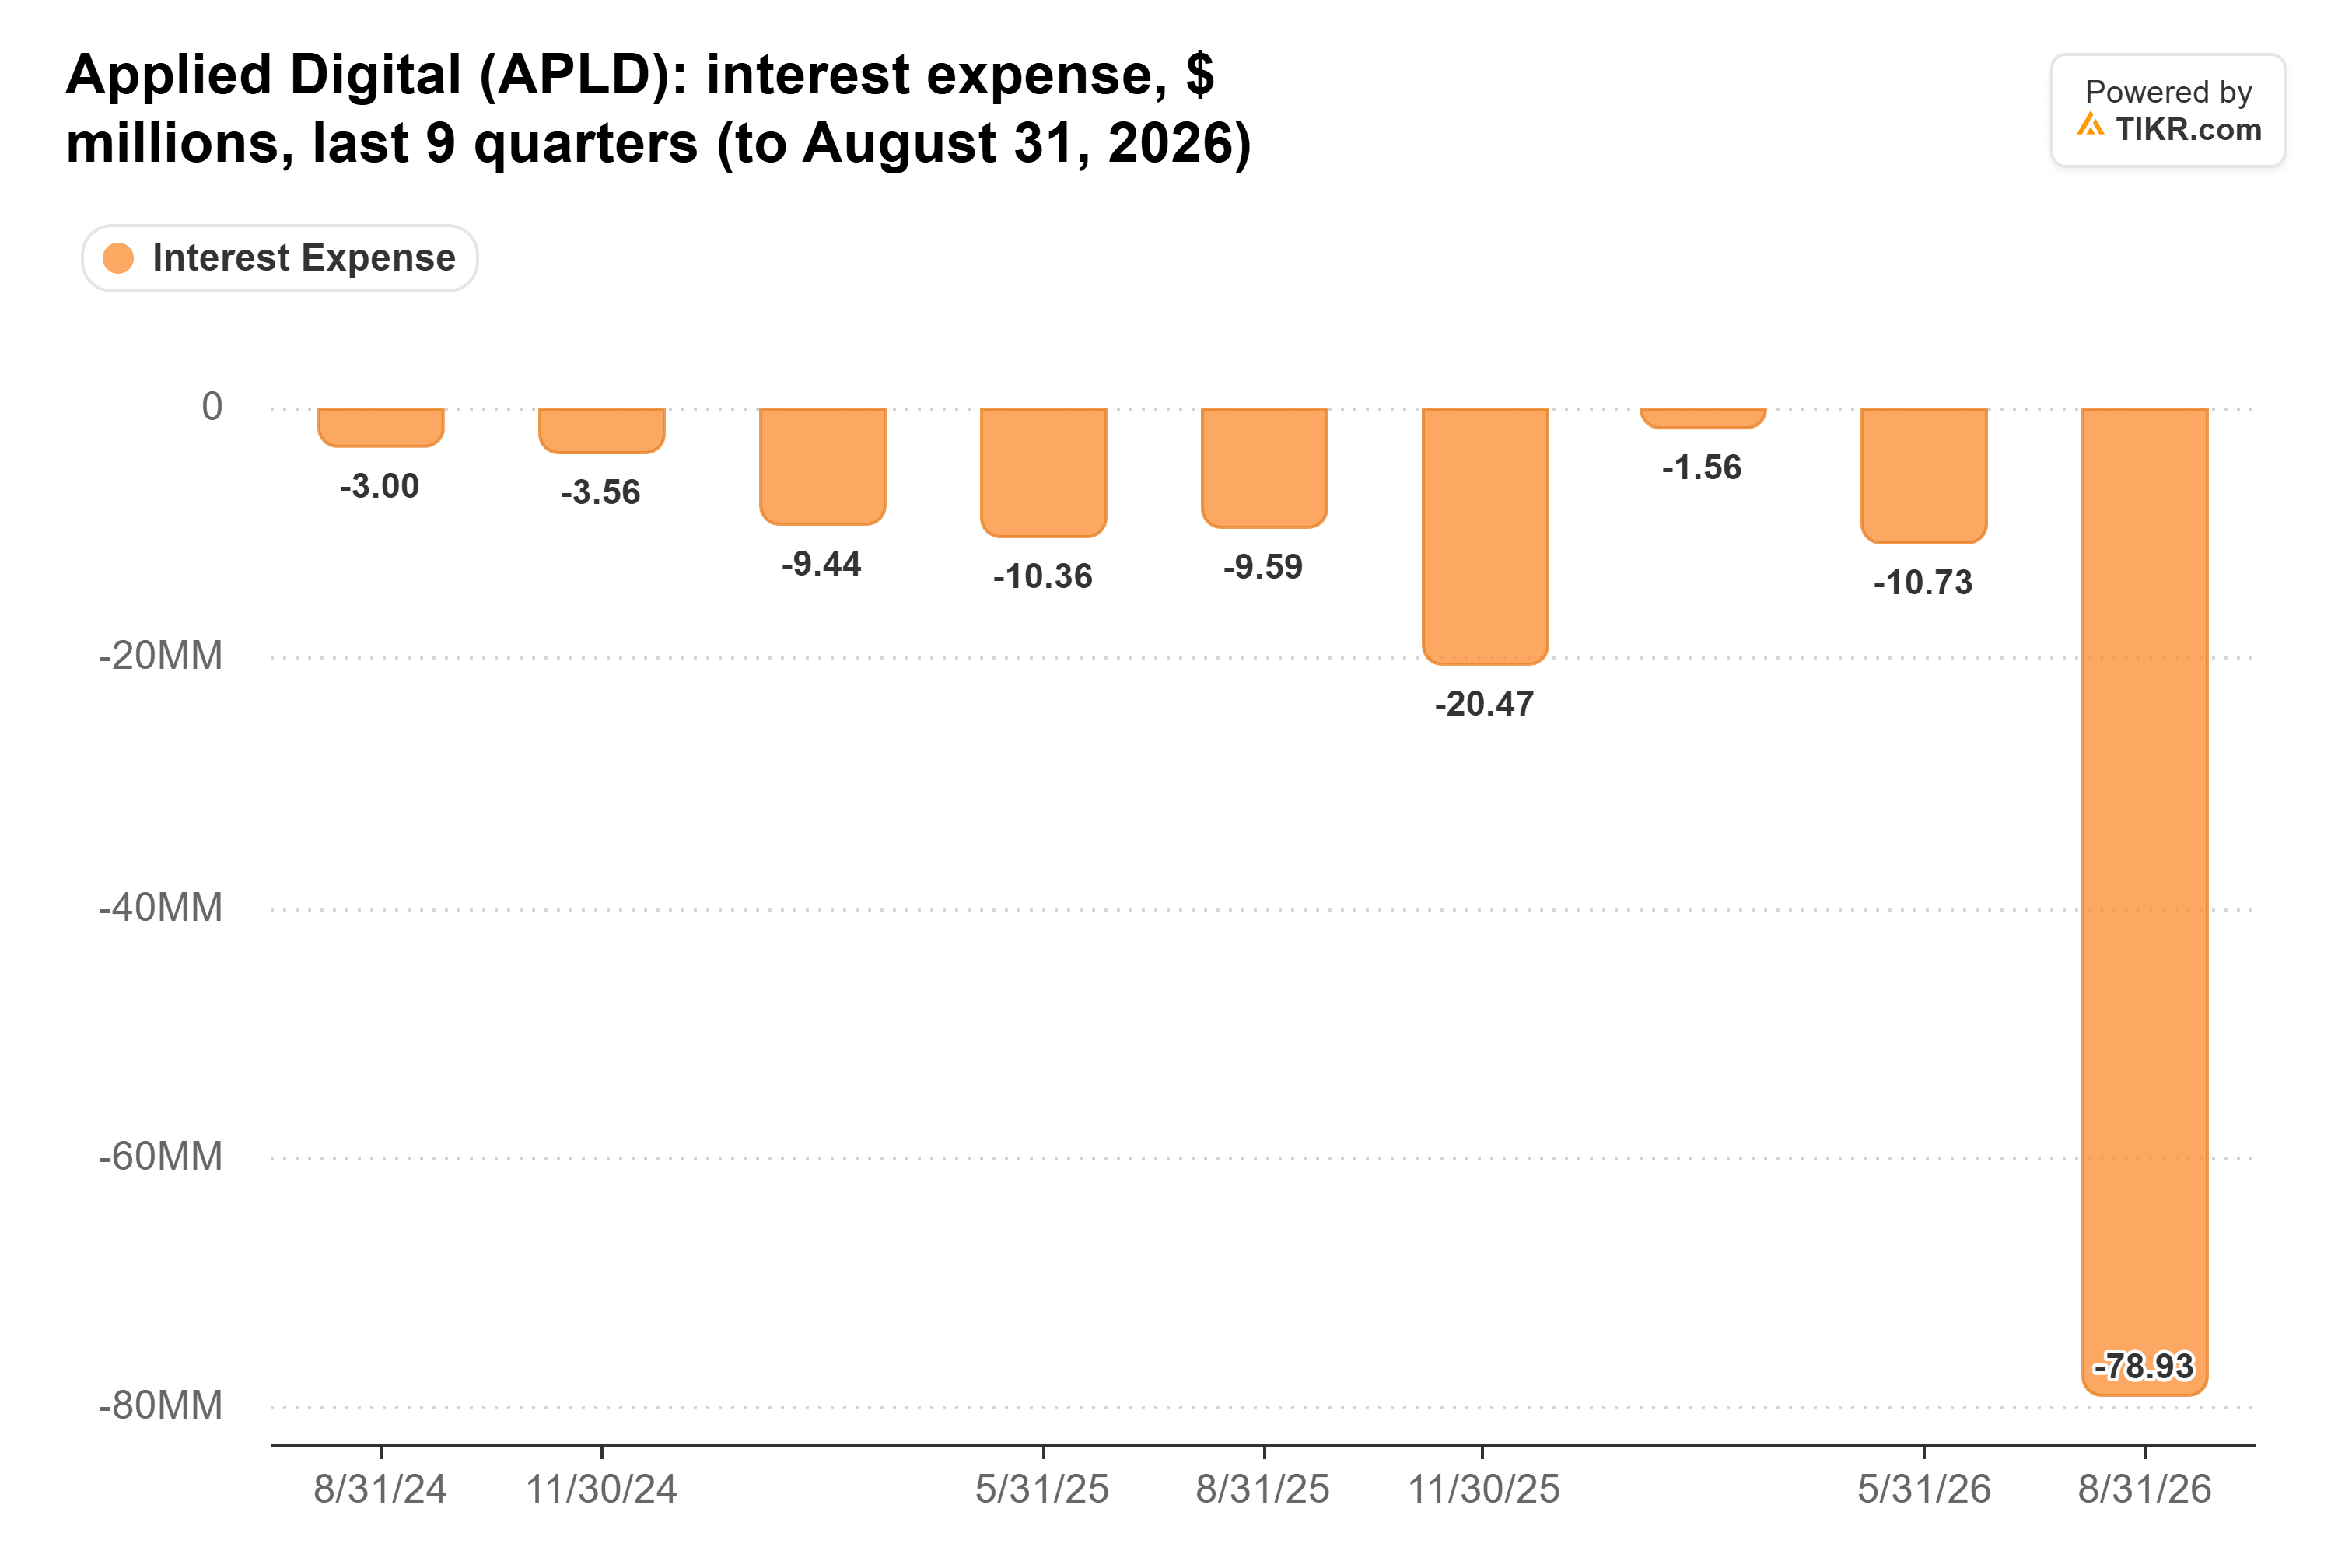
The company also capitalized $35.7 million of interest into construction, and Macquarie collected a $60.1 million preferred dividend in kind. Add those in, and financing costs ran at 2.6x the $65.8 million of base rent Applied Digital collected in the quarter. None of these costs come down if CoreWeave has a harder time raising money.
CoreWeave’s debt has more than tripled in a year
CoreWeave’s own funding is the weak spot. Its total debt reached $66.2 billion at the end of September, up from $18.8 billion a year earlier.
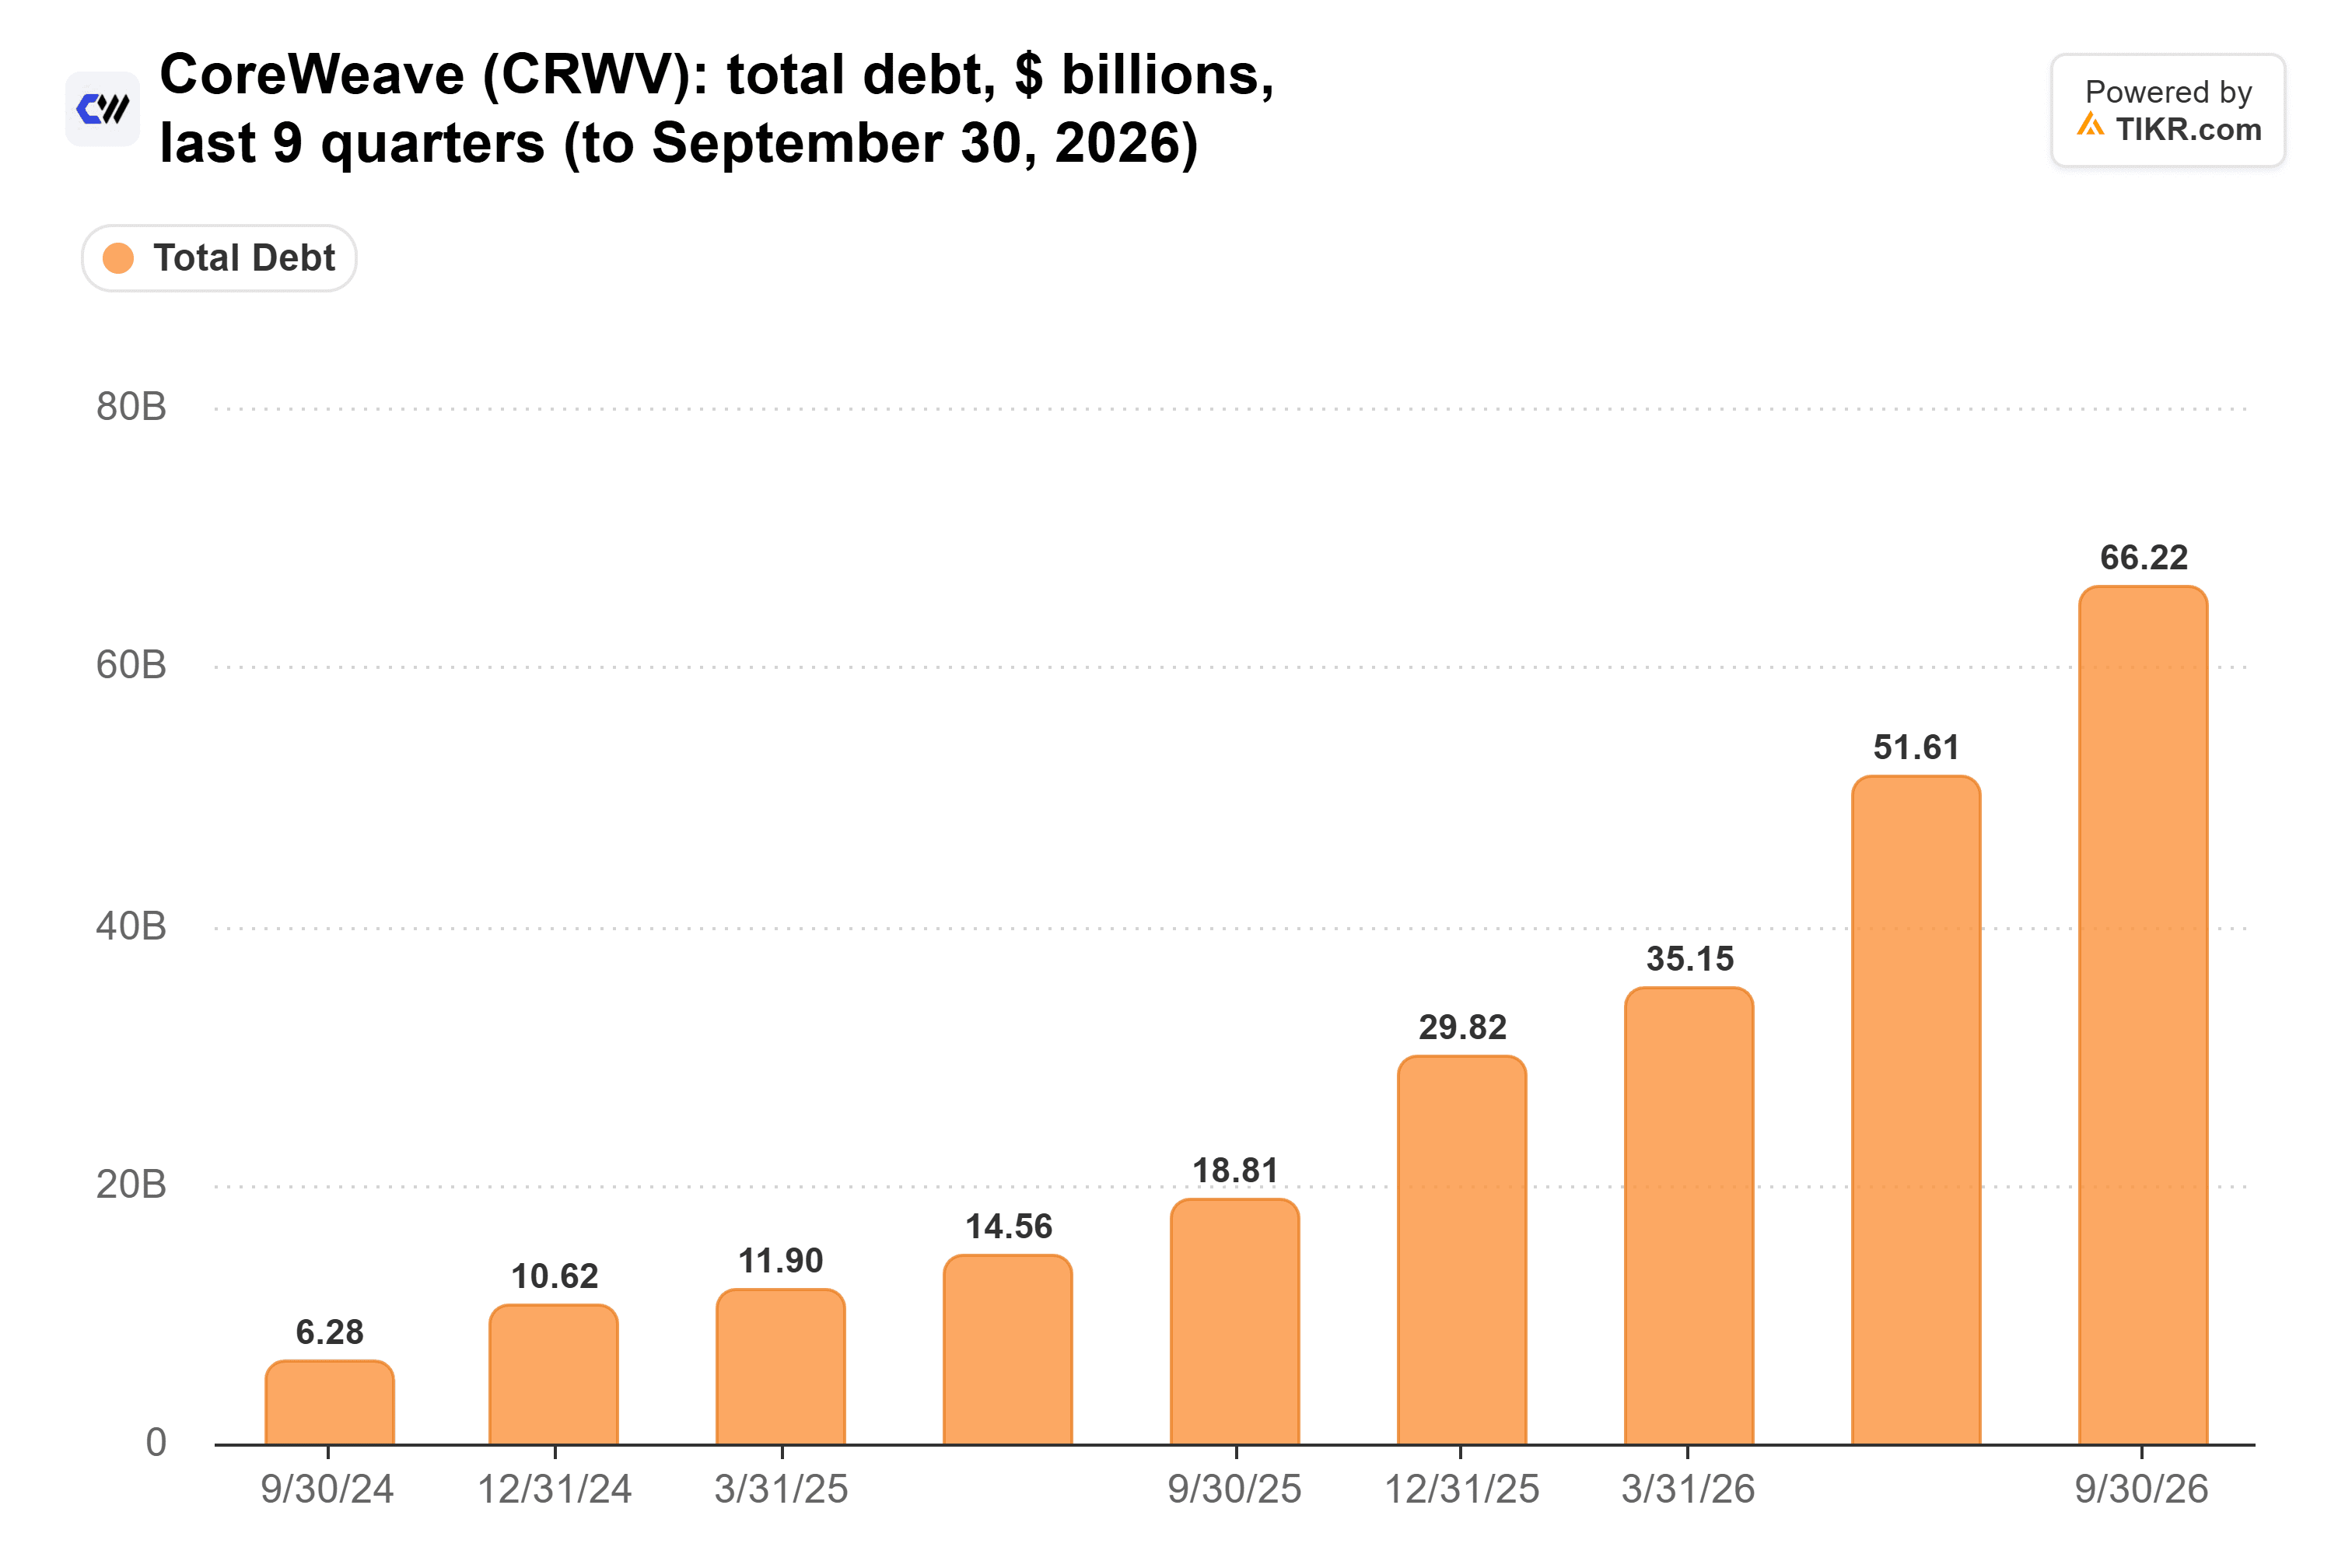
Its bonds were yielding over 17% earlier this month. And Kress’s commentary says Nvidia’s commitments to neoclouds only apply once those customers line up their own financing, and that Nvidia can reduce or cancel them if they don’t.
Applied Digital still has to refinance
Applied Digital does have real protection. The leases can’t be cancelled; a tenant that walks away for convenience owes the full remaining contract value.
But the lease only protects the rent. Applied Digital plans to refinance its campuses into asset-backed or investment-grade debt once they’re built. I’d expect lenders to price the Polaris Forge 1 debt off CoreWeave’s credit, and a tenant whose bonds yield over 17% won’t win its landlord a cheap refinancing.
CoreWeave has more to fall back on, including a revenue backlog of about $132.5 billion. Applied Digital has two tenants holding 86.2% of its contracted revenue, and its financing costs already run well ahead of its rent. That makes Applied Digital the bigger loser in my book.
The first test is CoreWeave’s planned delayed-draw term loan. If it prices near the 7% to 7.5% management has pointed to, the pressure eases on both companies. Then comes Applied Digital’s fiscal second-quarter report in January, where base rent needs to start closing that 2.6x gap.
So what is Applied Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Digital for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!