

Key Takeaways
- Bernstein downgraded PepsiCo to Underperform on Nov. 17 with a $128 target, 13% below the Nov. 16 close.
- The firm expects PepsiCo to miss earnings estimates as North American snack volumes fall in 2027 and the turnaround needs more investment.
- PepsiCo’s North American business faces rising costs, fading tariff refunds and KFC’s U.S. move to Coca-Cola, starting in January.
- The rebound since October came from a higher multiple while estimates fell, so the downgrade looks well founded.
PepsiCo (PEP) has bounced back since early October, and Bernstein thinks it has further to fall. On Nov. 17, the firm downgraded the stock to Underperform from Market Perform and cut its target to $128 from $131. That was 13% below the $146.43 close on Nov. 16. The stock fell 3% on the day to $142.02, leaving about 10% to go.
And KFC’s roughly 3,700 U.S. restaurants start moving to Coca-Cola (KO) in January, an account Bank of America puts at about $500 million a year in sales, according to Reuters.
North America Is Still the Problem
PepsiCo cut its 2026 outlook on Oct. 8 and now expects core EPS to grow 2.5% to 3.5%, down from the low end of 5% to 7%. Core constant-currency operating profit at PepsiCo Foods North America fell 12% in the third quarter. Tariff refunds that are now going away supplied 4 percentage points of the company’s 3% core operating profit growth. North American beverage volume fell 2% in the quarter. “We’re not competing well in soft drinks,” CEO Ramon Laguarta said on the third-quarter call.
The Fix Will Cost More Than Investors Expect
Bernstein analyst Cristian Rios wrote that he forecasts “a miss on EPS expectations over the next 12 months, driven by underperformance in North America.” He sees North American snack volumes falling in 2027 as PepsiCo laps this year’s price cuts and chip consumption keeps shrinking, while costs and marketing spend squeeze margins. He also expects the multiple to shrink as the market prices in “the new reality of an algorithm that requires significant catch-up investment to be sustained.” Management isn’t arguing with the spending part: it said advertising and marketing rose by double digits in both U.S. businesses last quarter.
TIKR Tracks 24 Analysts on PepsiCo. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on PepsiCo, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See PepsiCo’s Analyst Ratings
Does $128 Add Up?
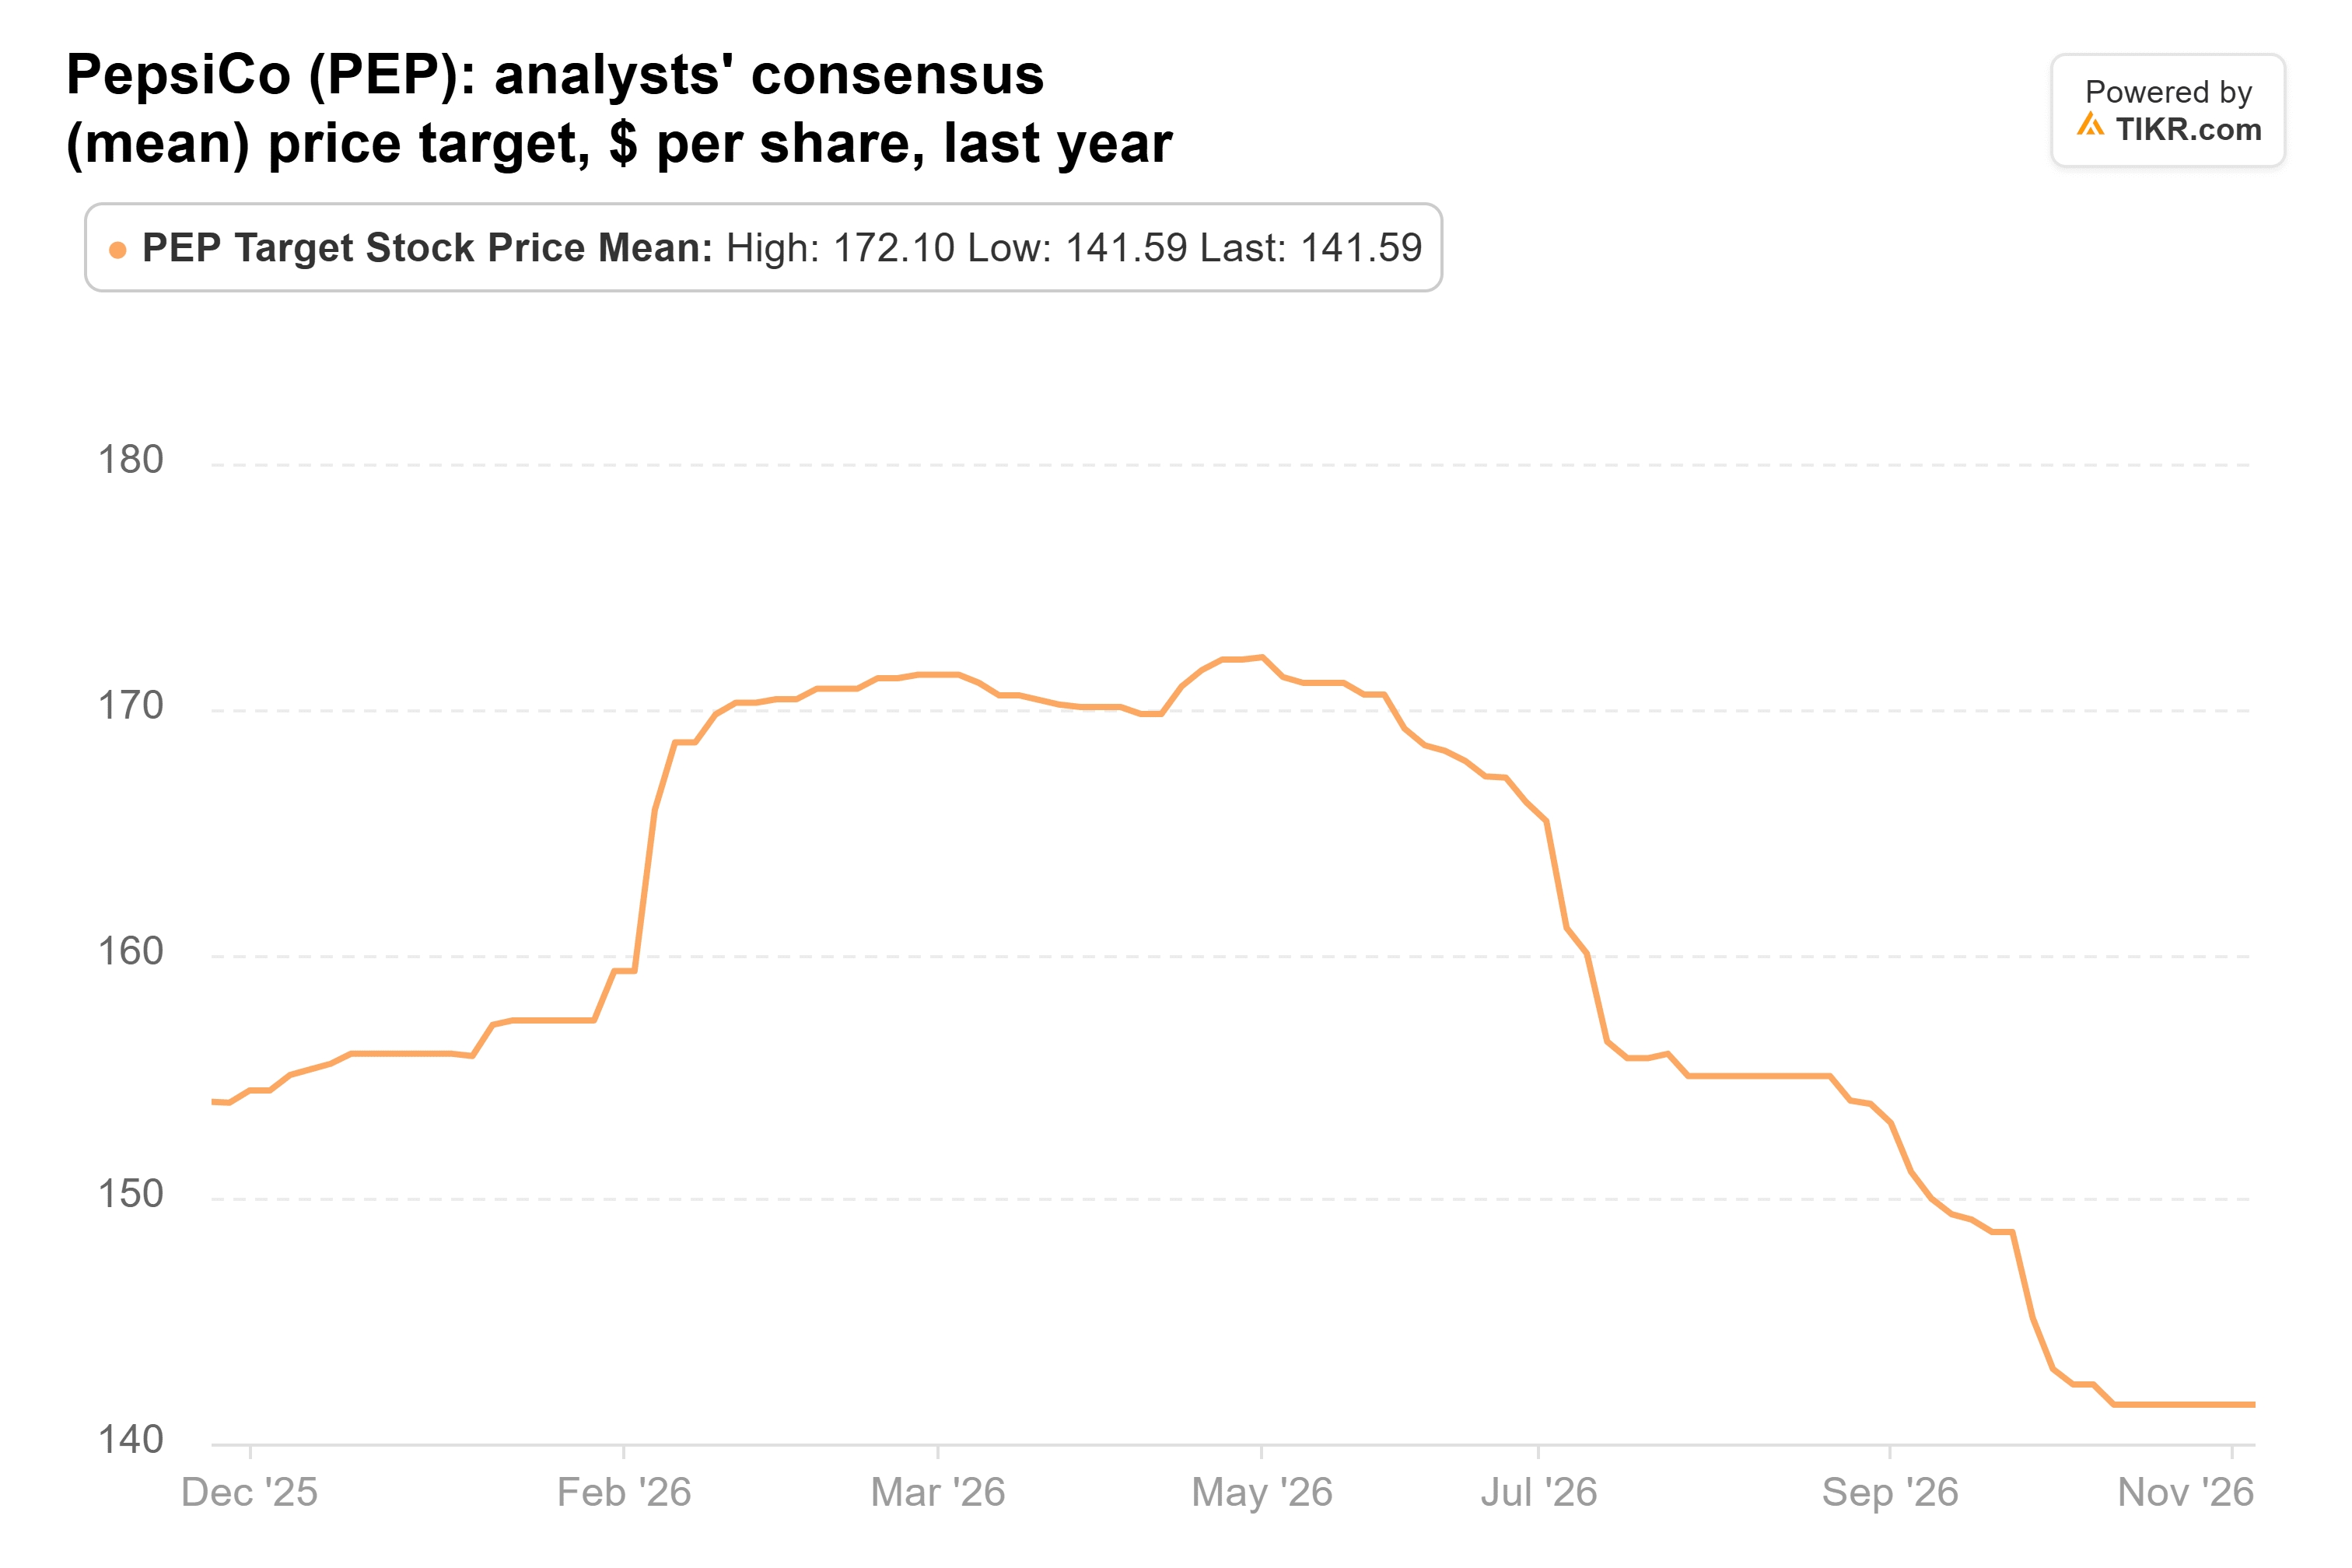
Wall Street’s average target is $142, right at the share price. That average peaked at $172 in May and has fallen to a one-year low since:
Analysts expect normalized EPS to rise from $8.14 in 2025 to $8.42 this year and $8.61 in 2027:
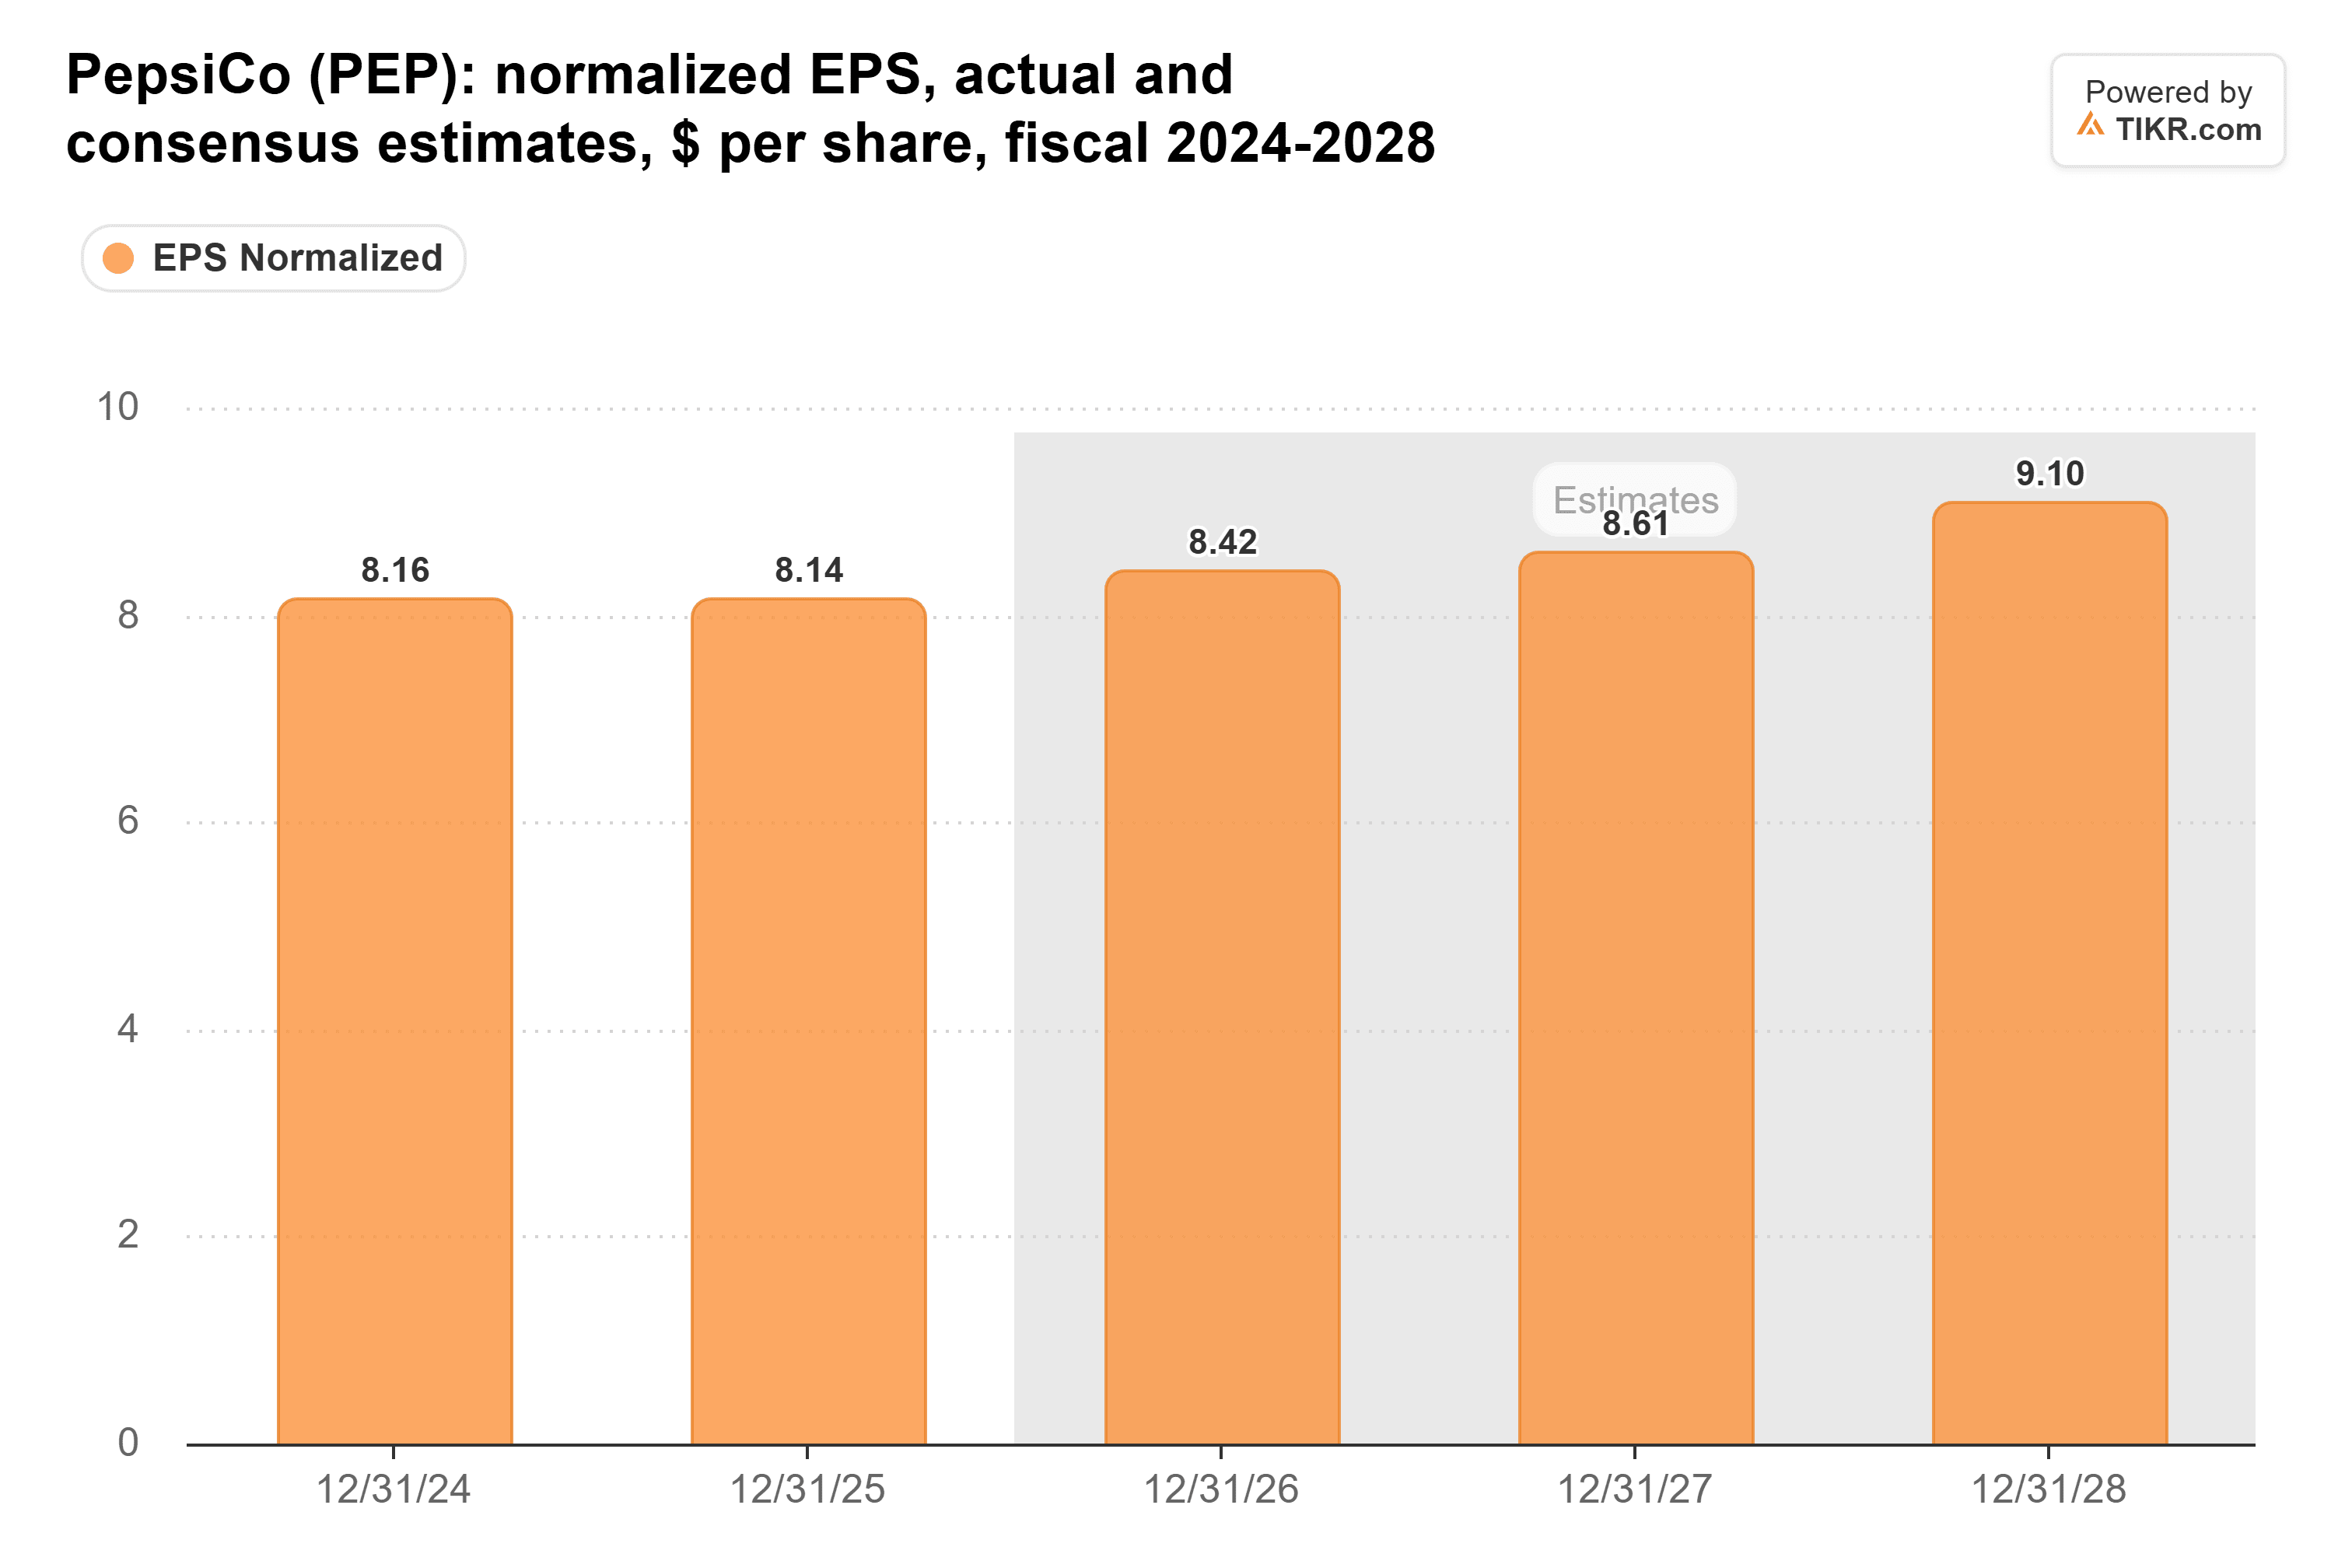
The 2027 estimate has fallen about 4% in three months. This year’s estimate already sits at the top of what management’s guidance implies, which leaves no cushion for a miss.
PepsiCo trades at 16.8x forward earnings. That’s below its five-year average of 21x but above the 14.3x low it hit on Oct. 7:
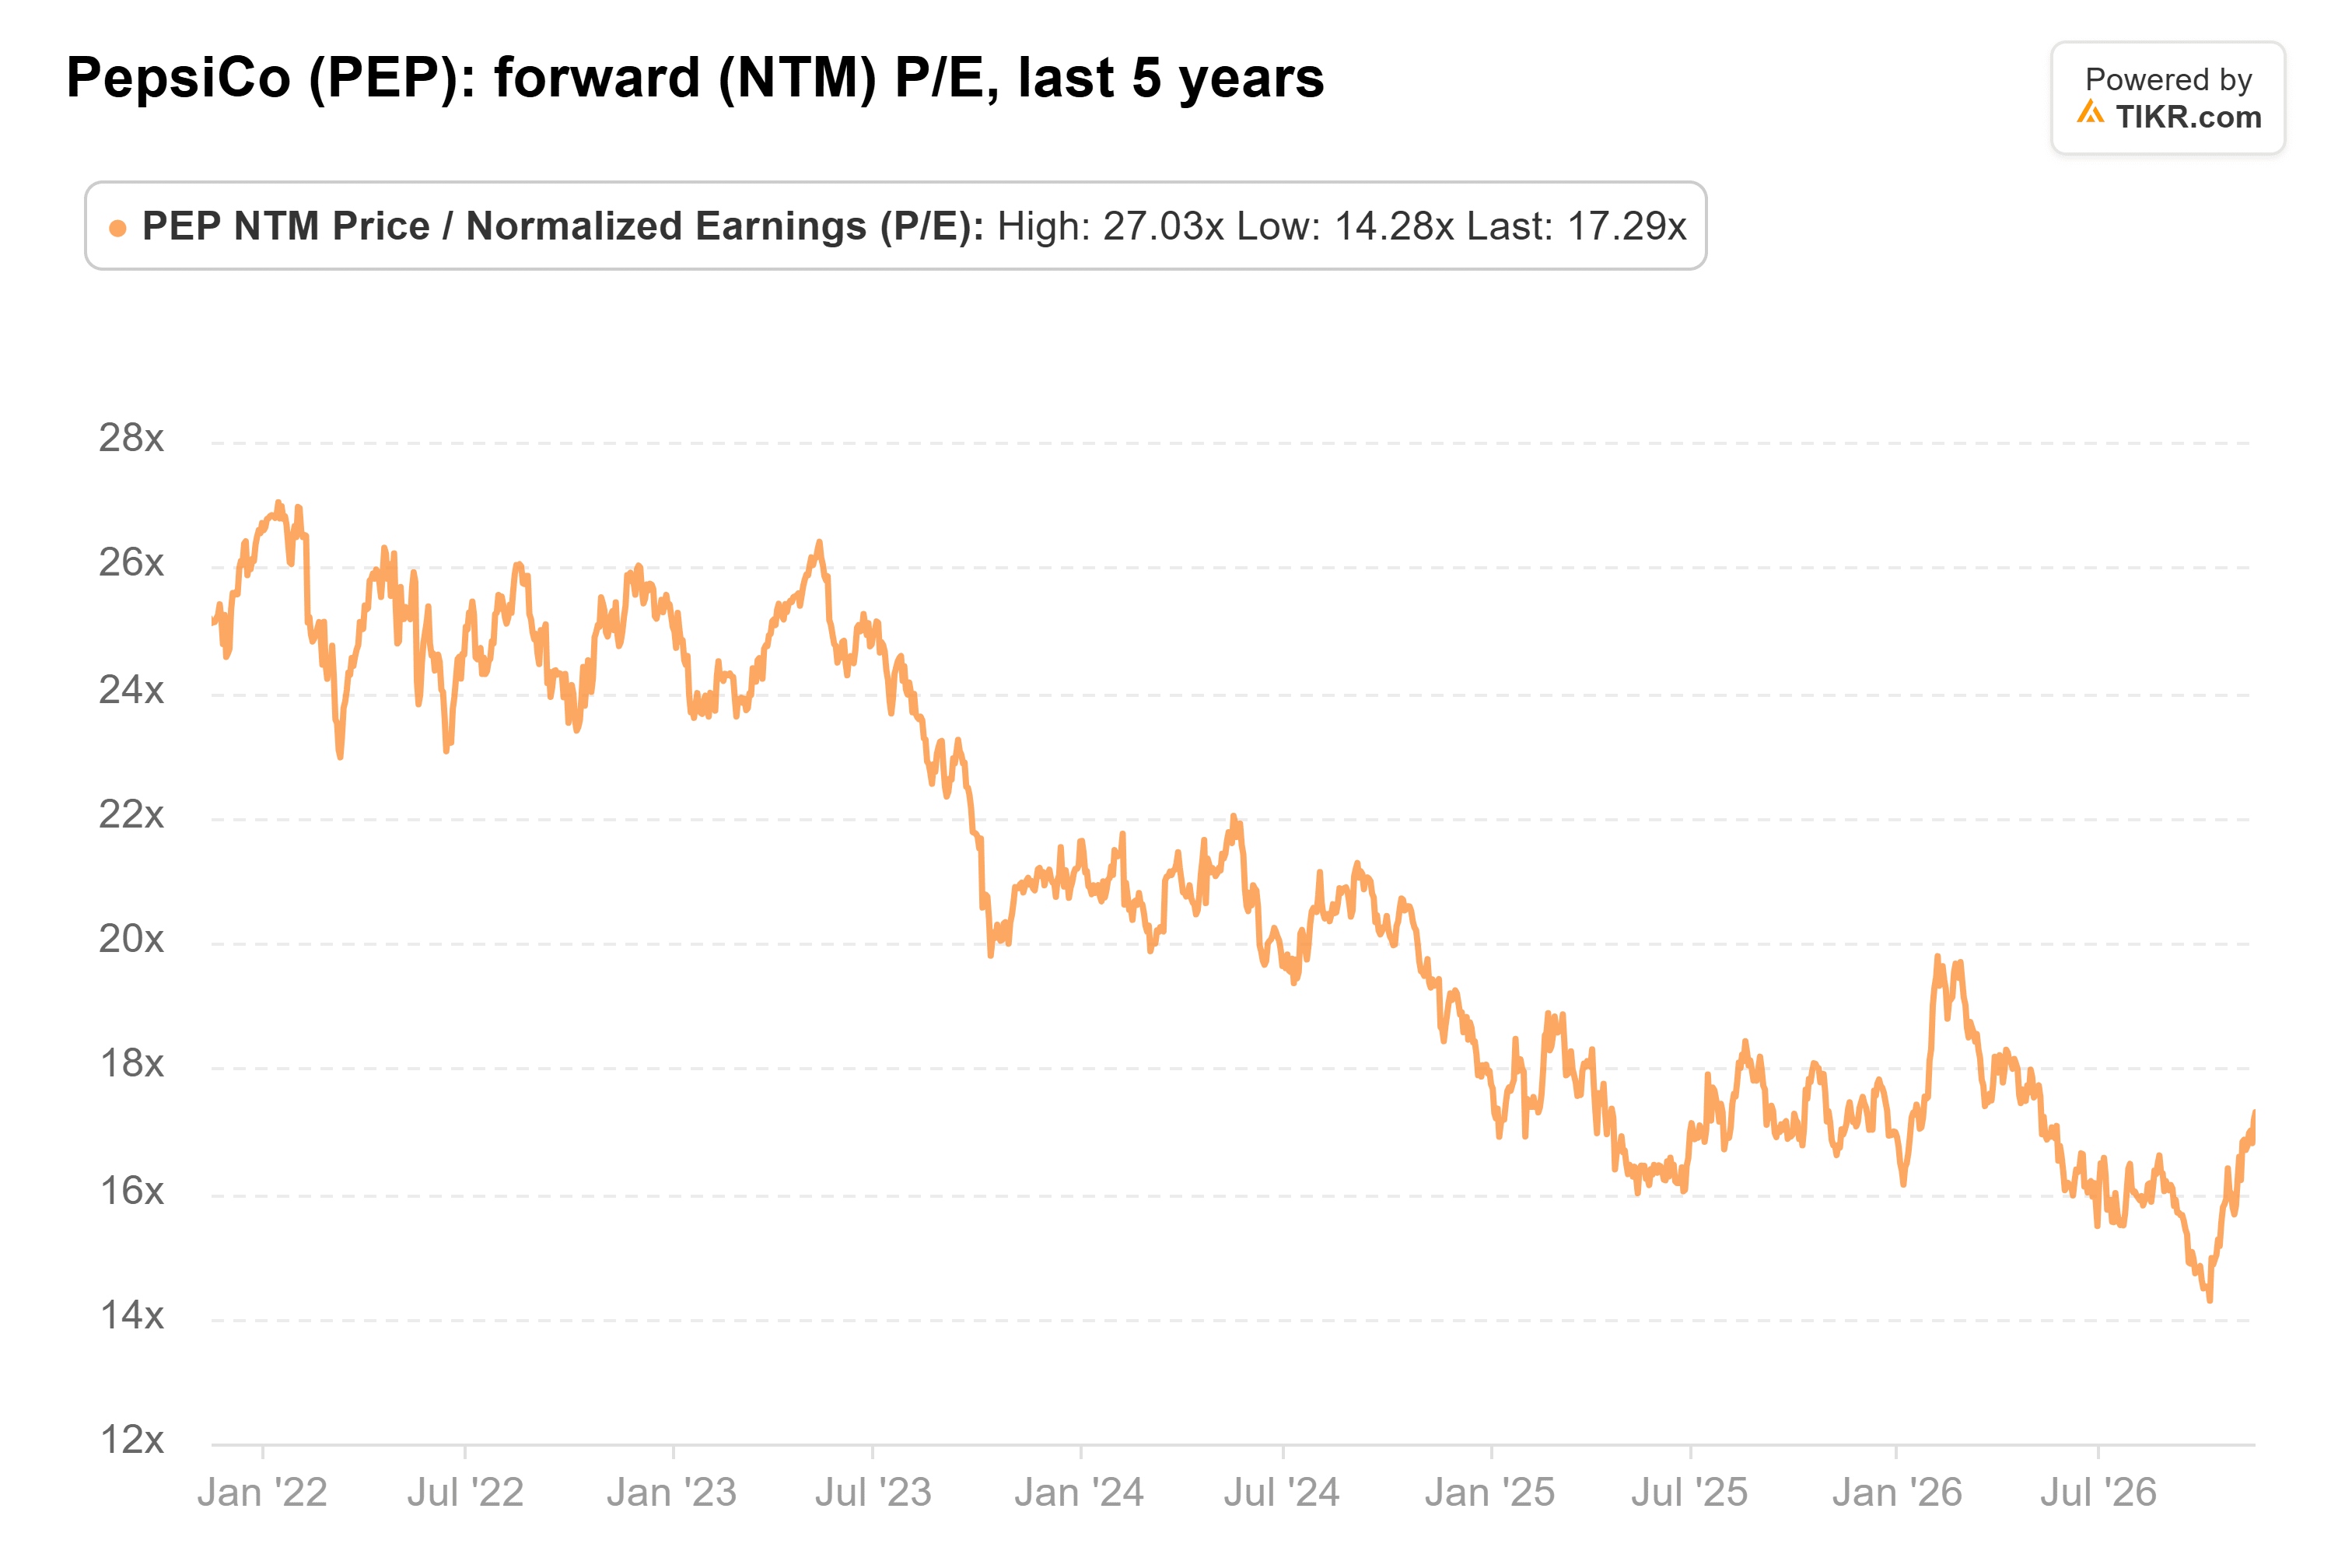
On today’s estimates, Bernstein’s $128 is 15.1x forward earnings, just above that October low.
Bernstein Has the Better Argument on PepsiCo
International is the bulls’ best card: organic revenue there grew 8% last quarter. But estimates have kept falling since early October, so the whole rebound has come from a higher multiple. I’d side with Bernstein here, since getting to $128 would only take a multiple a little above the one PepsiCo had in early October.
The next test comes in February, with fourth-quarter results and the 2027 outlook. A guide that supports the $8.61 consensus, with PepsiCo Foods North America’s margin holding up, would make this downgrade look early.
So What Is PepsiCo Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PepsiCo could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


