


Key Takeaways
- Anthropic is set to price its IPO at up to $1.4 trillion, which would make Amazon’s 15% and Alphabet’s 14% stakes worth about $406 billion.
- Gary Marcus calls that valuation “lunacy” and expects Anthropic to end up selling itself for about $400 billion.
- Anthropic’s revenue reached $33.2 billion in the first nine months of 2026, and the IPO adds about $84.6 billion of cash.
- Even at Marcus’s $400 billion, Amazon’s stake would be worth more than 3x what it invested, and its stock trades at 25x forward earnings, near a five-year low.
Anthropic is set to price its IPO tonight, and it’s guiding investors to the top of its $70-$78 range or above, Bloomberg reported. That would value it at up to $1.4 trillion.
On this week’s Big Technology Podcast, Gary Marcus, a professor emeritus at New York University and a longtime AI critic, pointed to a company that has barely turned a profit and has “nearly $900 billion in future liabilities”:
“To value a company like that at $1.4 trillion is lunacy because it’s a bad business.”
That’s a big claim for Amazon (AMZN) and Alphabet (GOOG) shareholders. After the IPO and a private placement alongside it, they’re set to own 15% and 14% of Anthropic, worth about $406 billion together at that price.
“The math doesn’t math”
Marcus’s other number is growth: Anthropic’s revenue jumped 147% from the first quarter to the second, then 47% in the third.
As Marcus put it, “these projections of them making 147% growth every quarter are just clearly wrong. And if they’re clearly wrong and they have $900 billion in liabilities, the math doesn’t math.”
He expects a sale, with a buyer opening at $200 billion and, after “some back and forth,” landing at “like $400 billion.”
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Anthropic has more runway than that
Growth has slowed, but 47% in a single quarter would more than quadruple revenue in a year. Anthropic’s revenue reached $33.2 billion in the first nine months of 2026, with an operating loss of $1.3 billion.
Anthropic expects about $84.6 billion of net proceeds at the midpoint of its range, on top of the more than $130 billion of cash and investments it already had. On Marcus’s own estimate of its bills, “a hundred billion something a year,” that’s about two years of runway before Anthropic collects a dollar of revenue.
Amazon stays ahead even at $400 billion
At $400 billion, Amazon’s 15% would be worth $60 billion and Alphabet’s 14% $56 billion. That’s still more than 3x the $18.0 billion Amazon has invested in Anthropic since 2023.
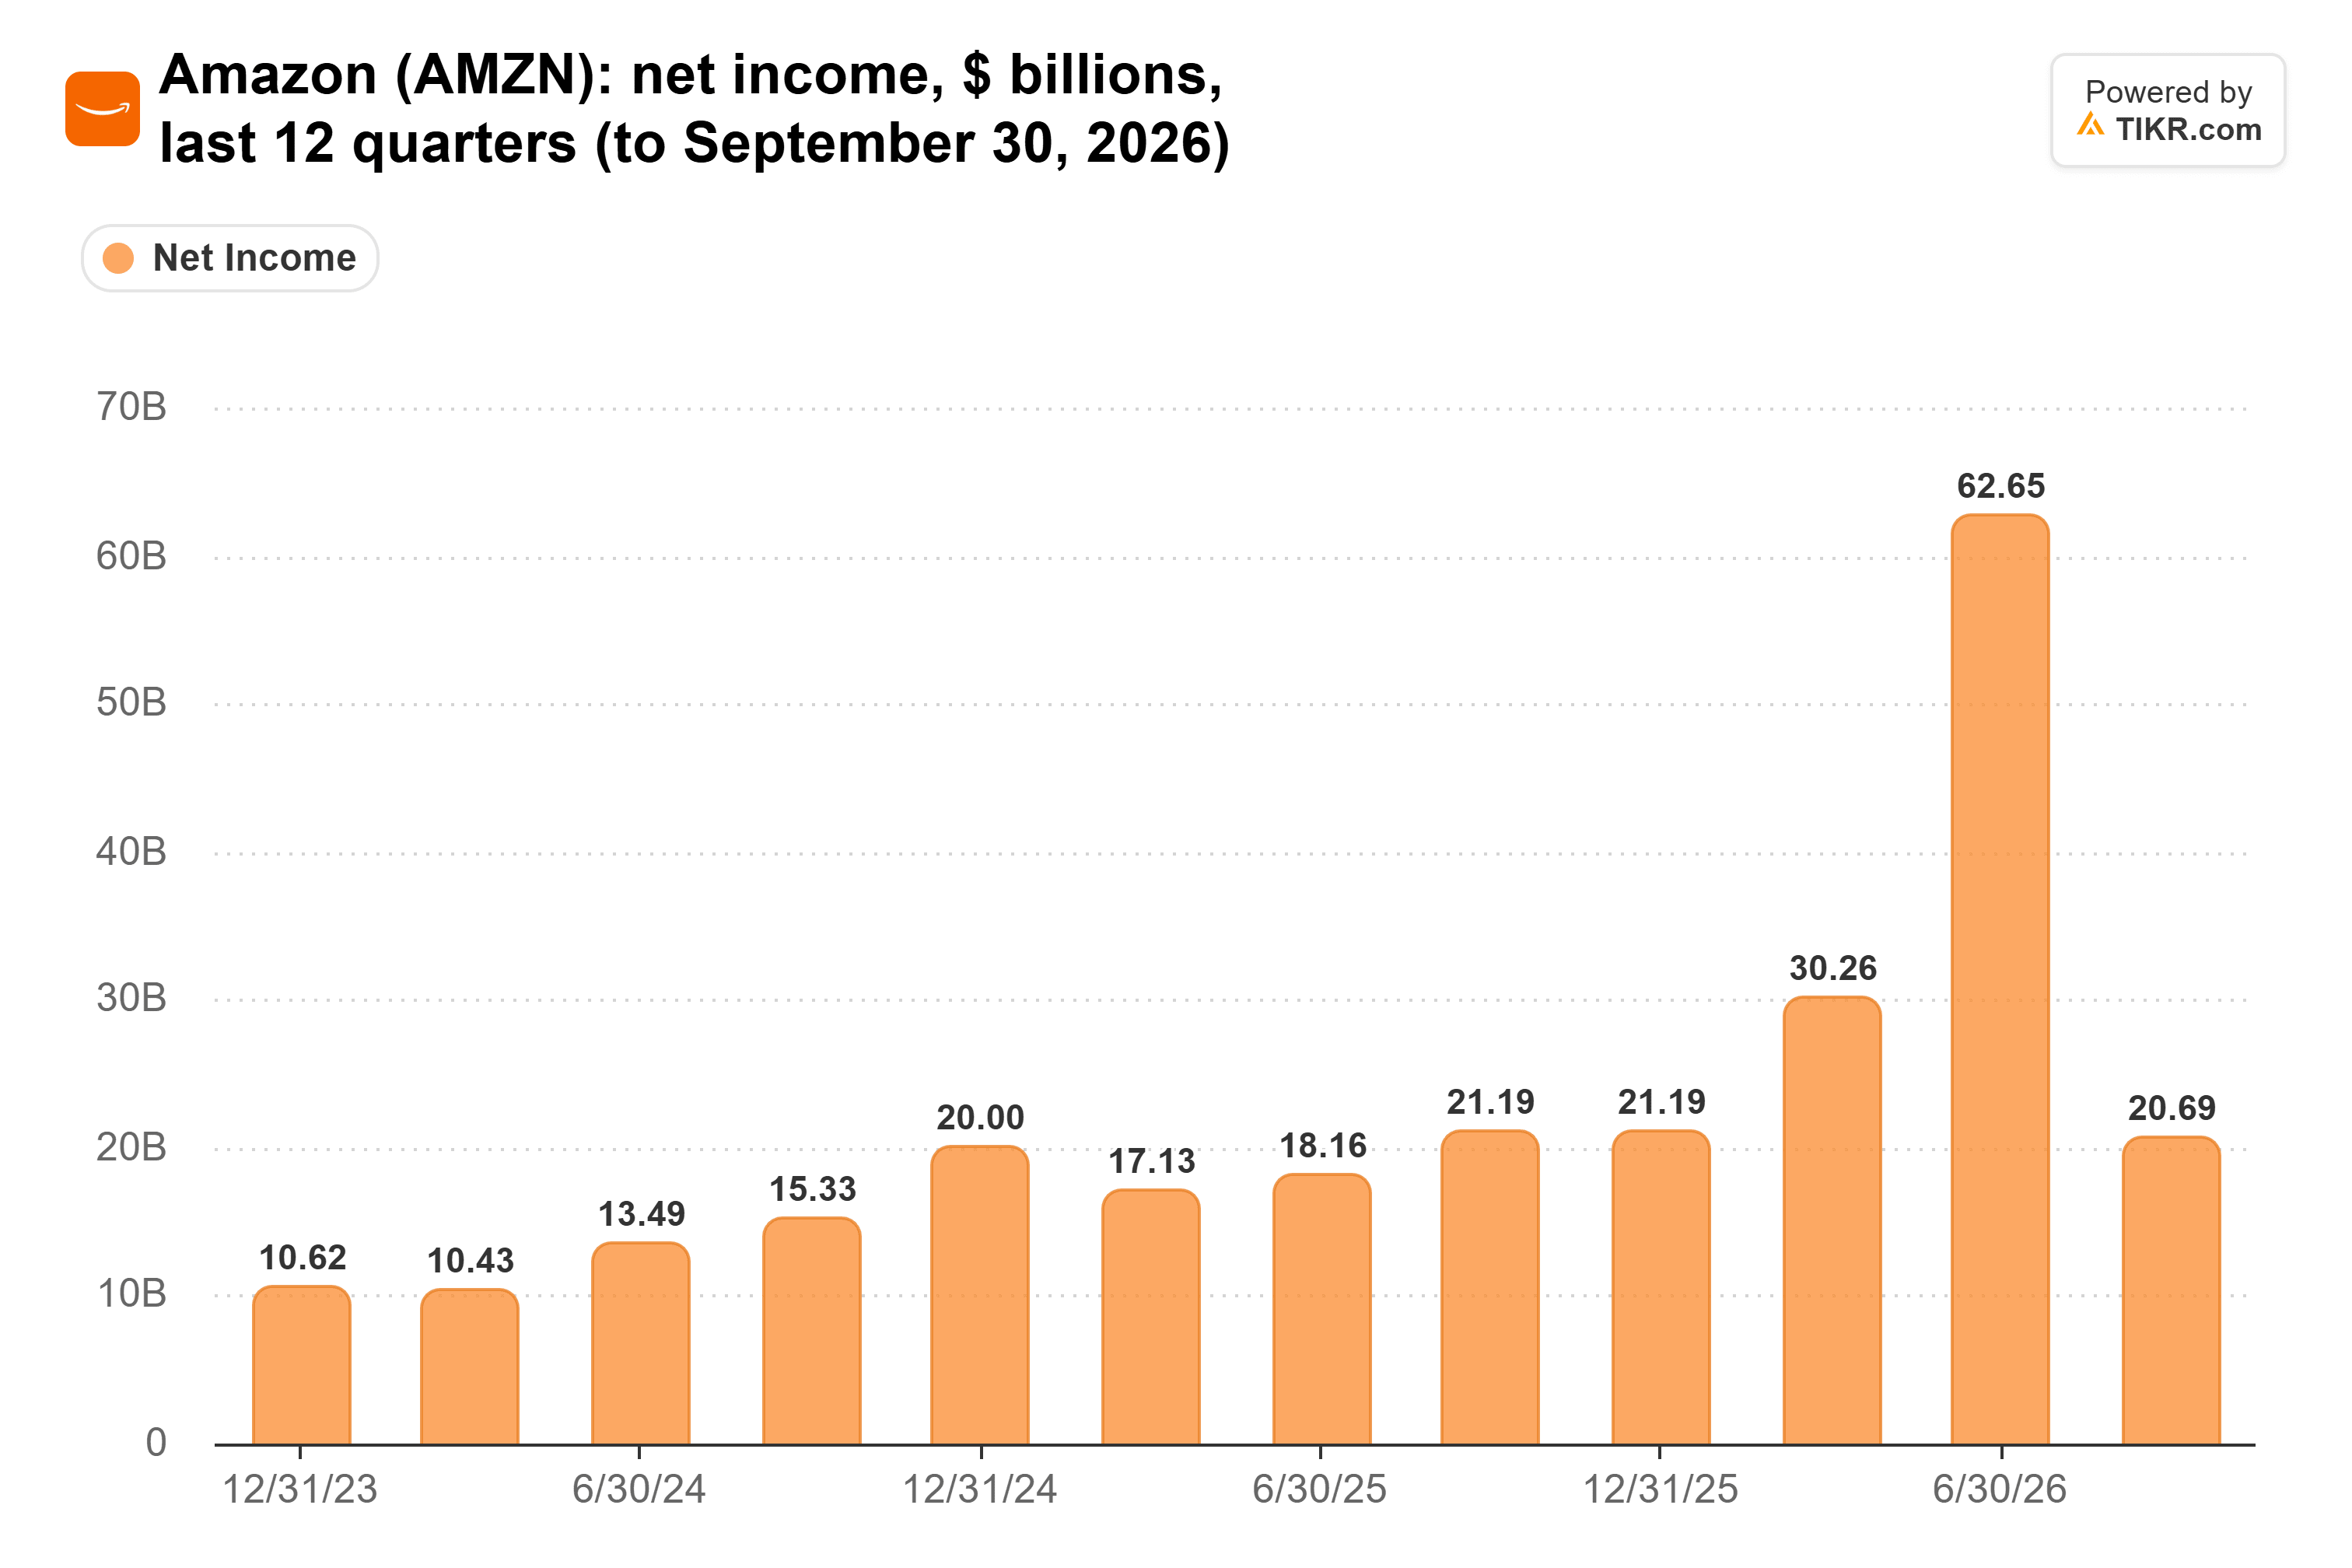
But Amazon would feel the drop in its reported profit, since markups on its Anthropic stake added $62.8 billion of pre-tax income in the first half of 2026. Its net income jumped to $62.7 billion in the second quarter, then fell back to $20.7 billion in the third:
Alphabet’s profit spiked the same way, to $112 billion in the second quarter from $28.2 billion a year earlier:
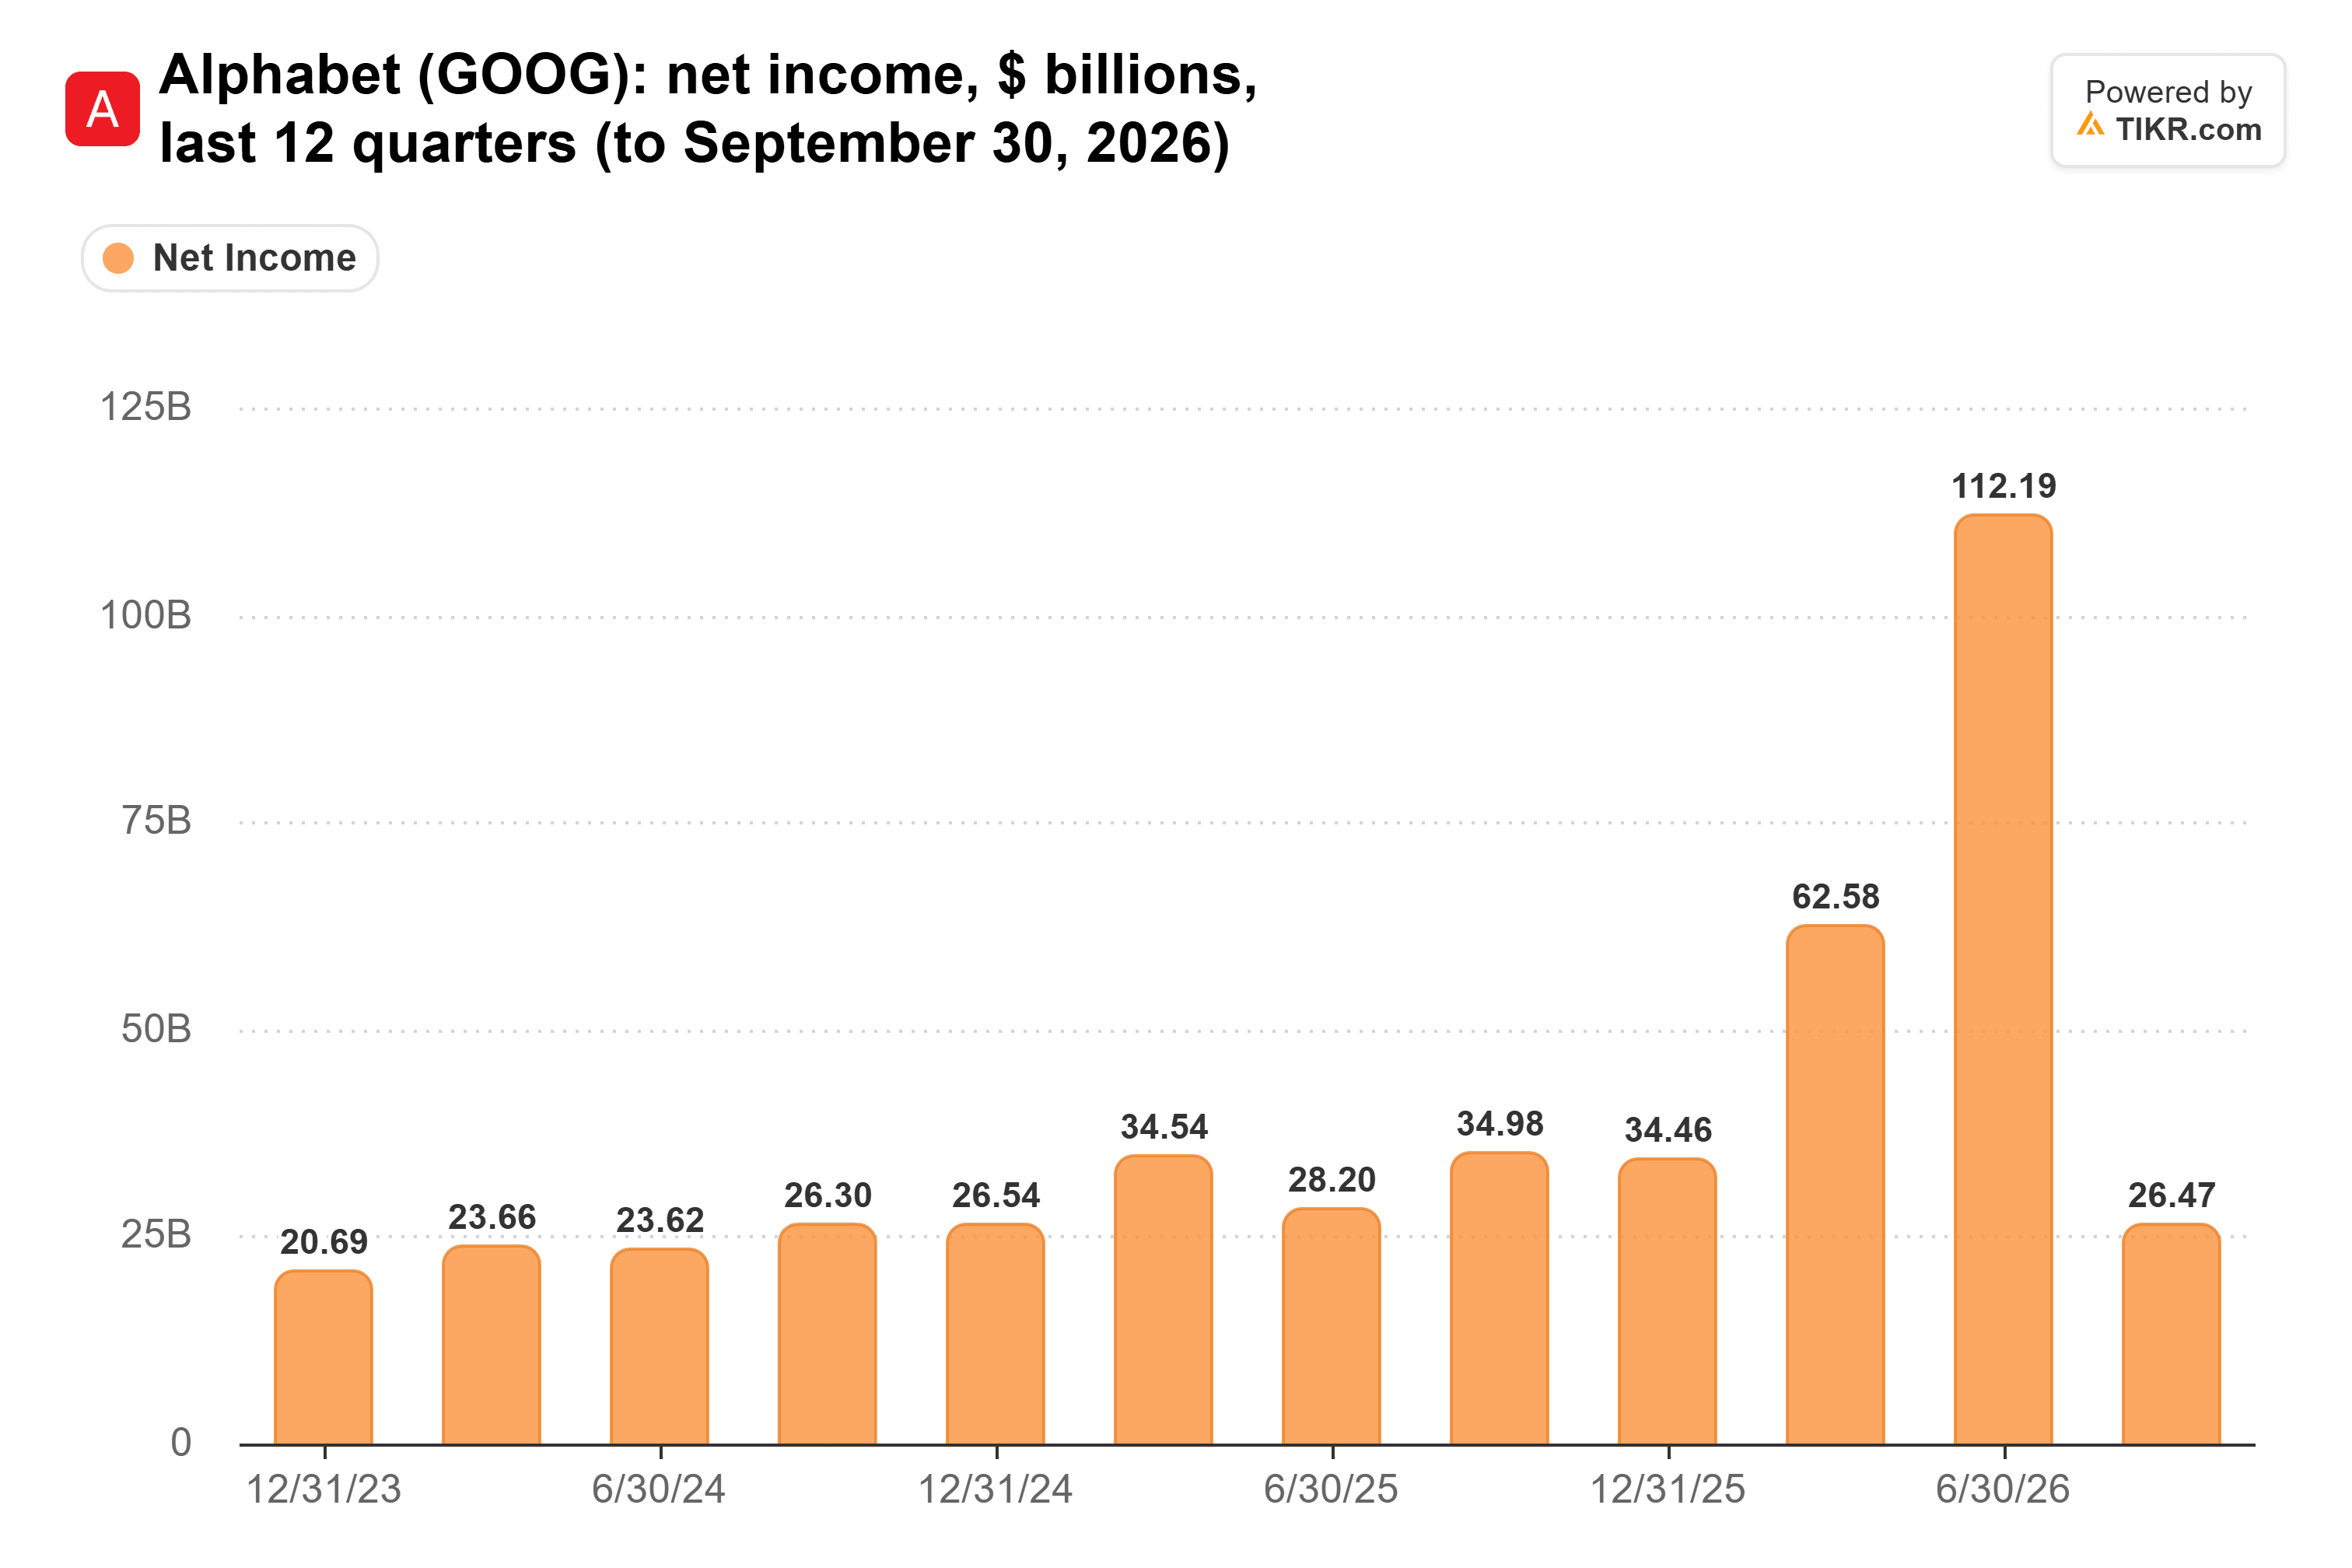
I suspect much of that came from the same place.
Amazon investors aren’t paying for Anthropic
Amazon’s bigger exposure is the more than $100 billion of AWS commitments Anthropic added in the second quarter, since a shortfall would land in Amazon’s cloud backlog.
But investors aren’t giving Amazon much credit for the stake. It trades at 25x forward earnings, about half its five-year average of 48x and close to the 23x low it hit on Oct. 30:

Marcus has a point on the price, and I wouldn’t rush to buy Anthropic on its first day. But “lunacy” goes too far for a company growing this fast with this much cash.
Of course, 47% is one quarter. Anthropic’s first report as a public company will show whether growth held up, and Amazon’s fourth-quarter results in early February will show where it marks its stake.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!




