Key Takeaways
- A Louisiana public authority’s Nov. 9 meeting packet includes a proposed agreement for up to $4.6 billion of revenue bonds to fund Applied Digital’s Delta Forge 1 campus, to be repaid from its Meta lease.
- Borrowing against Meta’s lease could cost Applied Digital far less than the neocloud debt market, where Steve Eisman says a 15% cost of debt makes AI data centers prohibitively expensive.
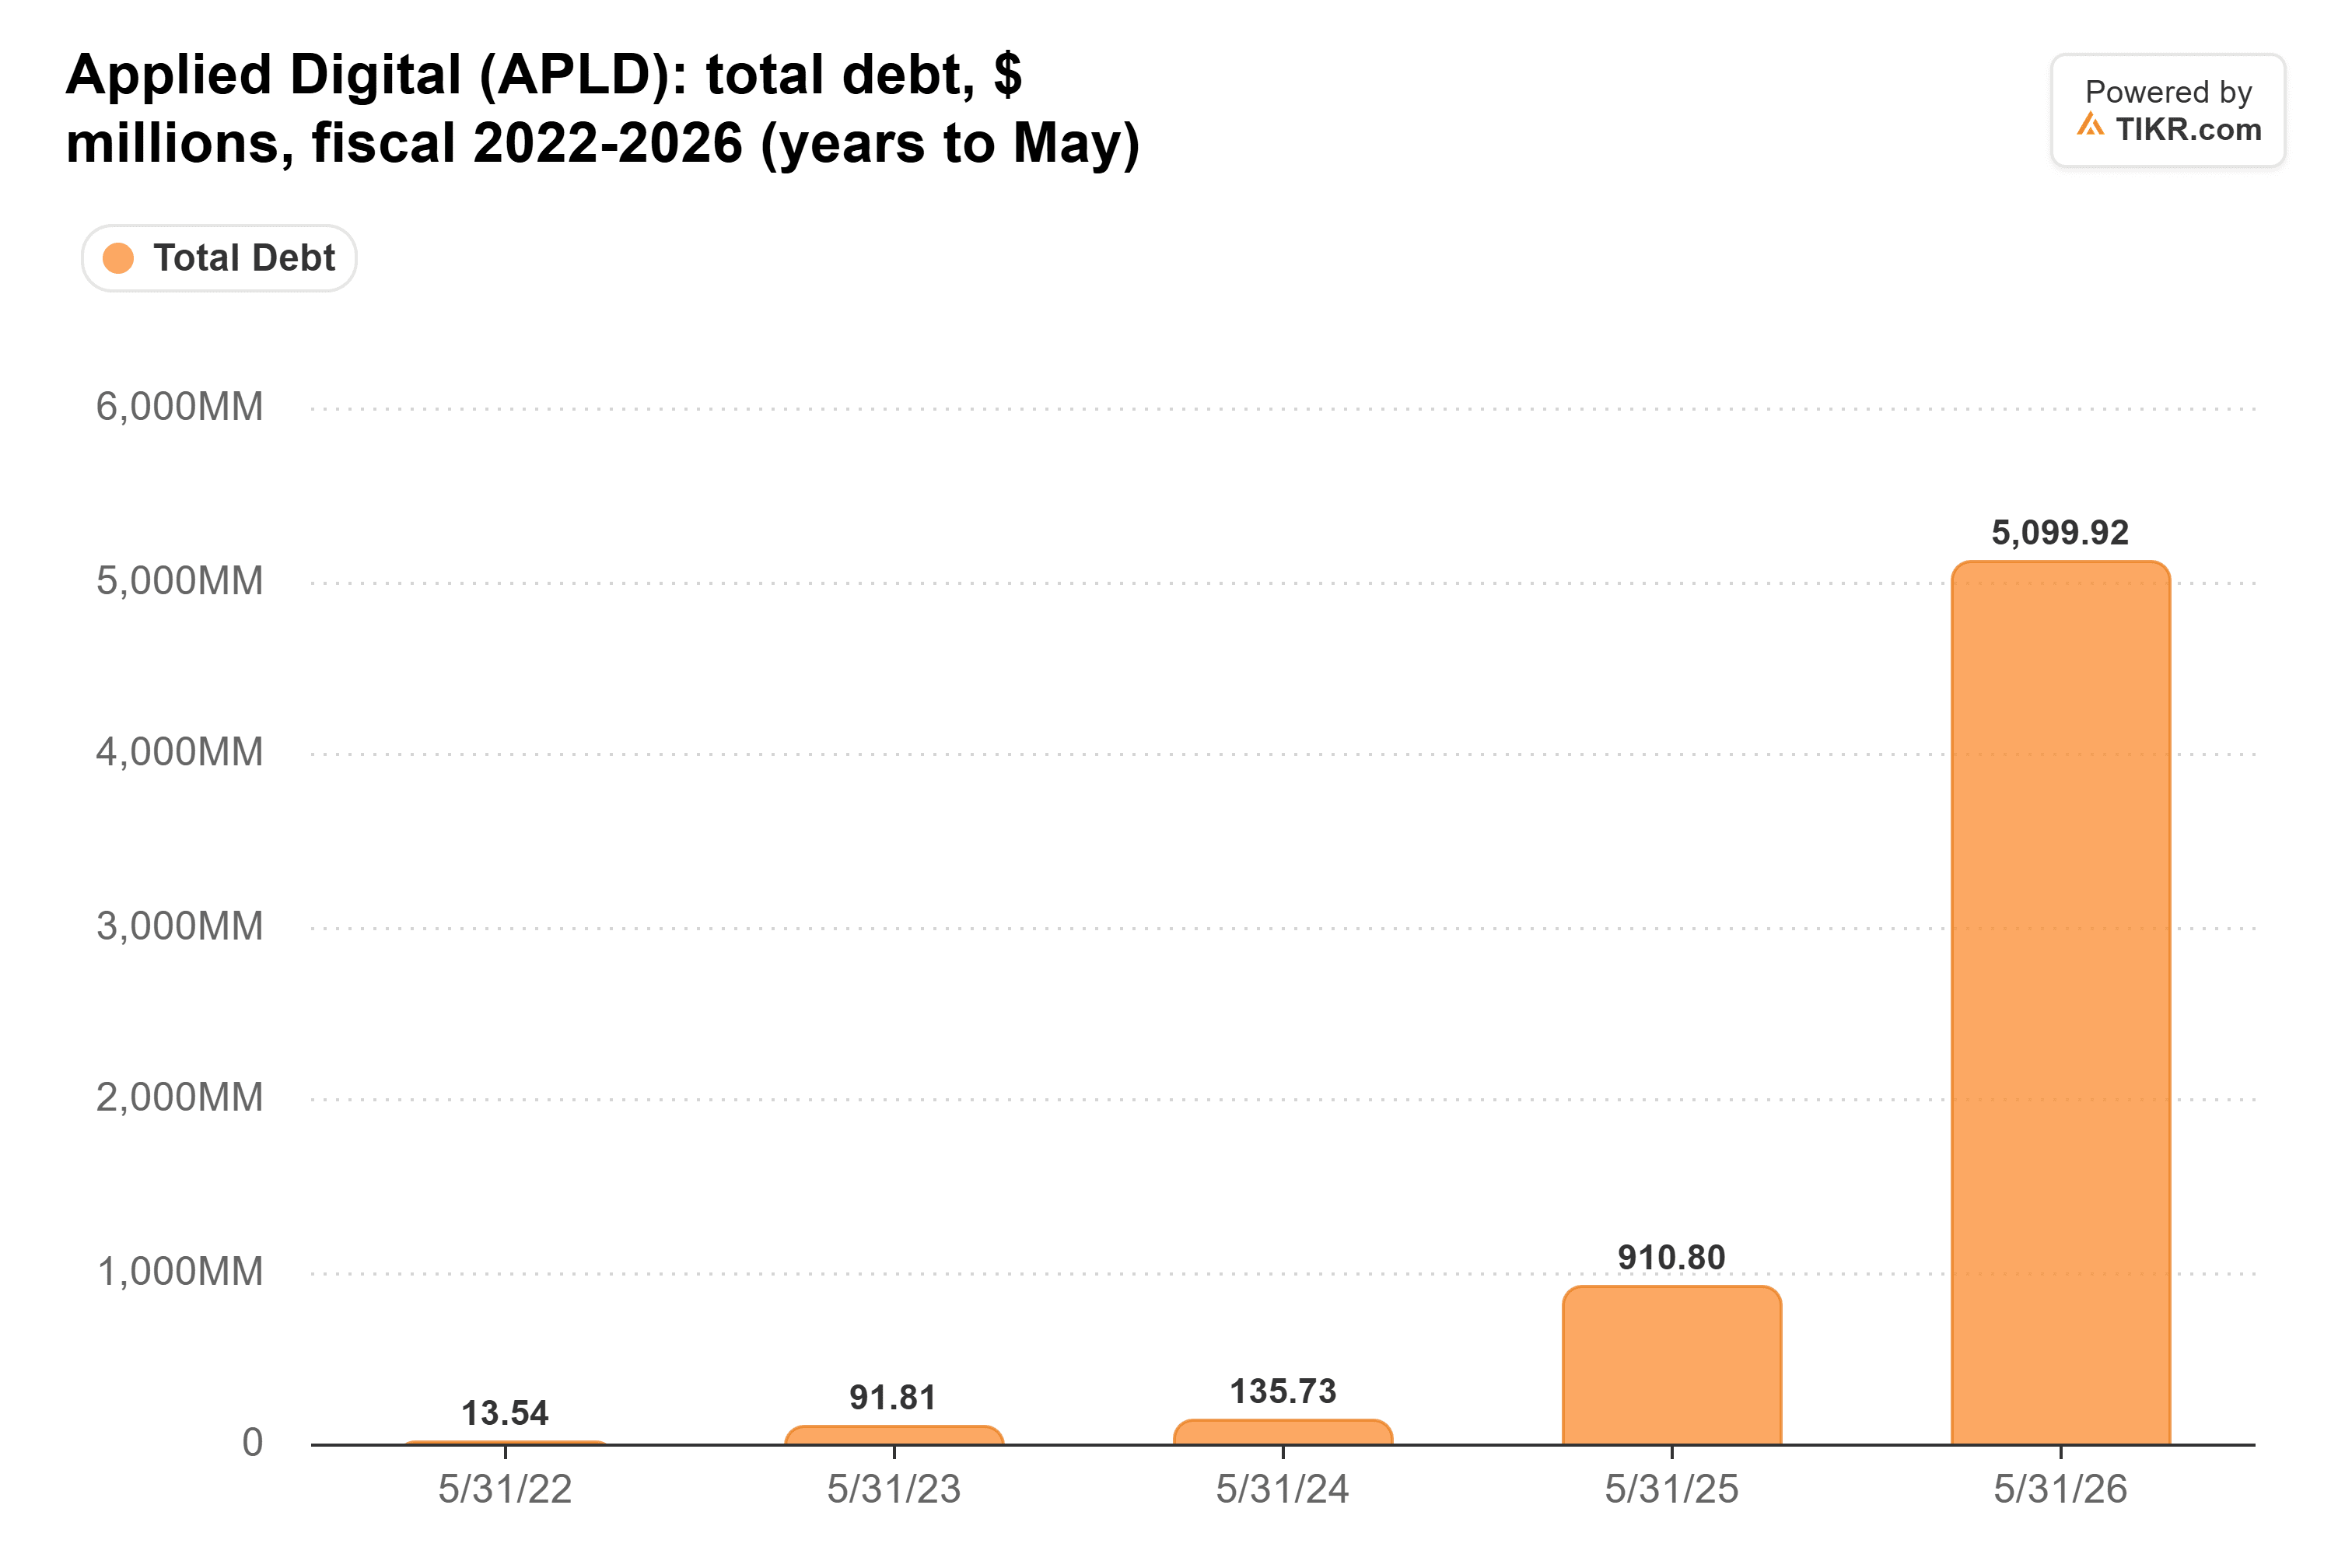
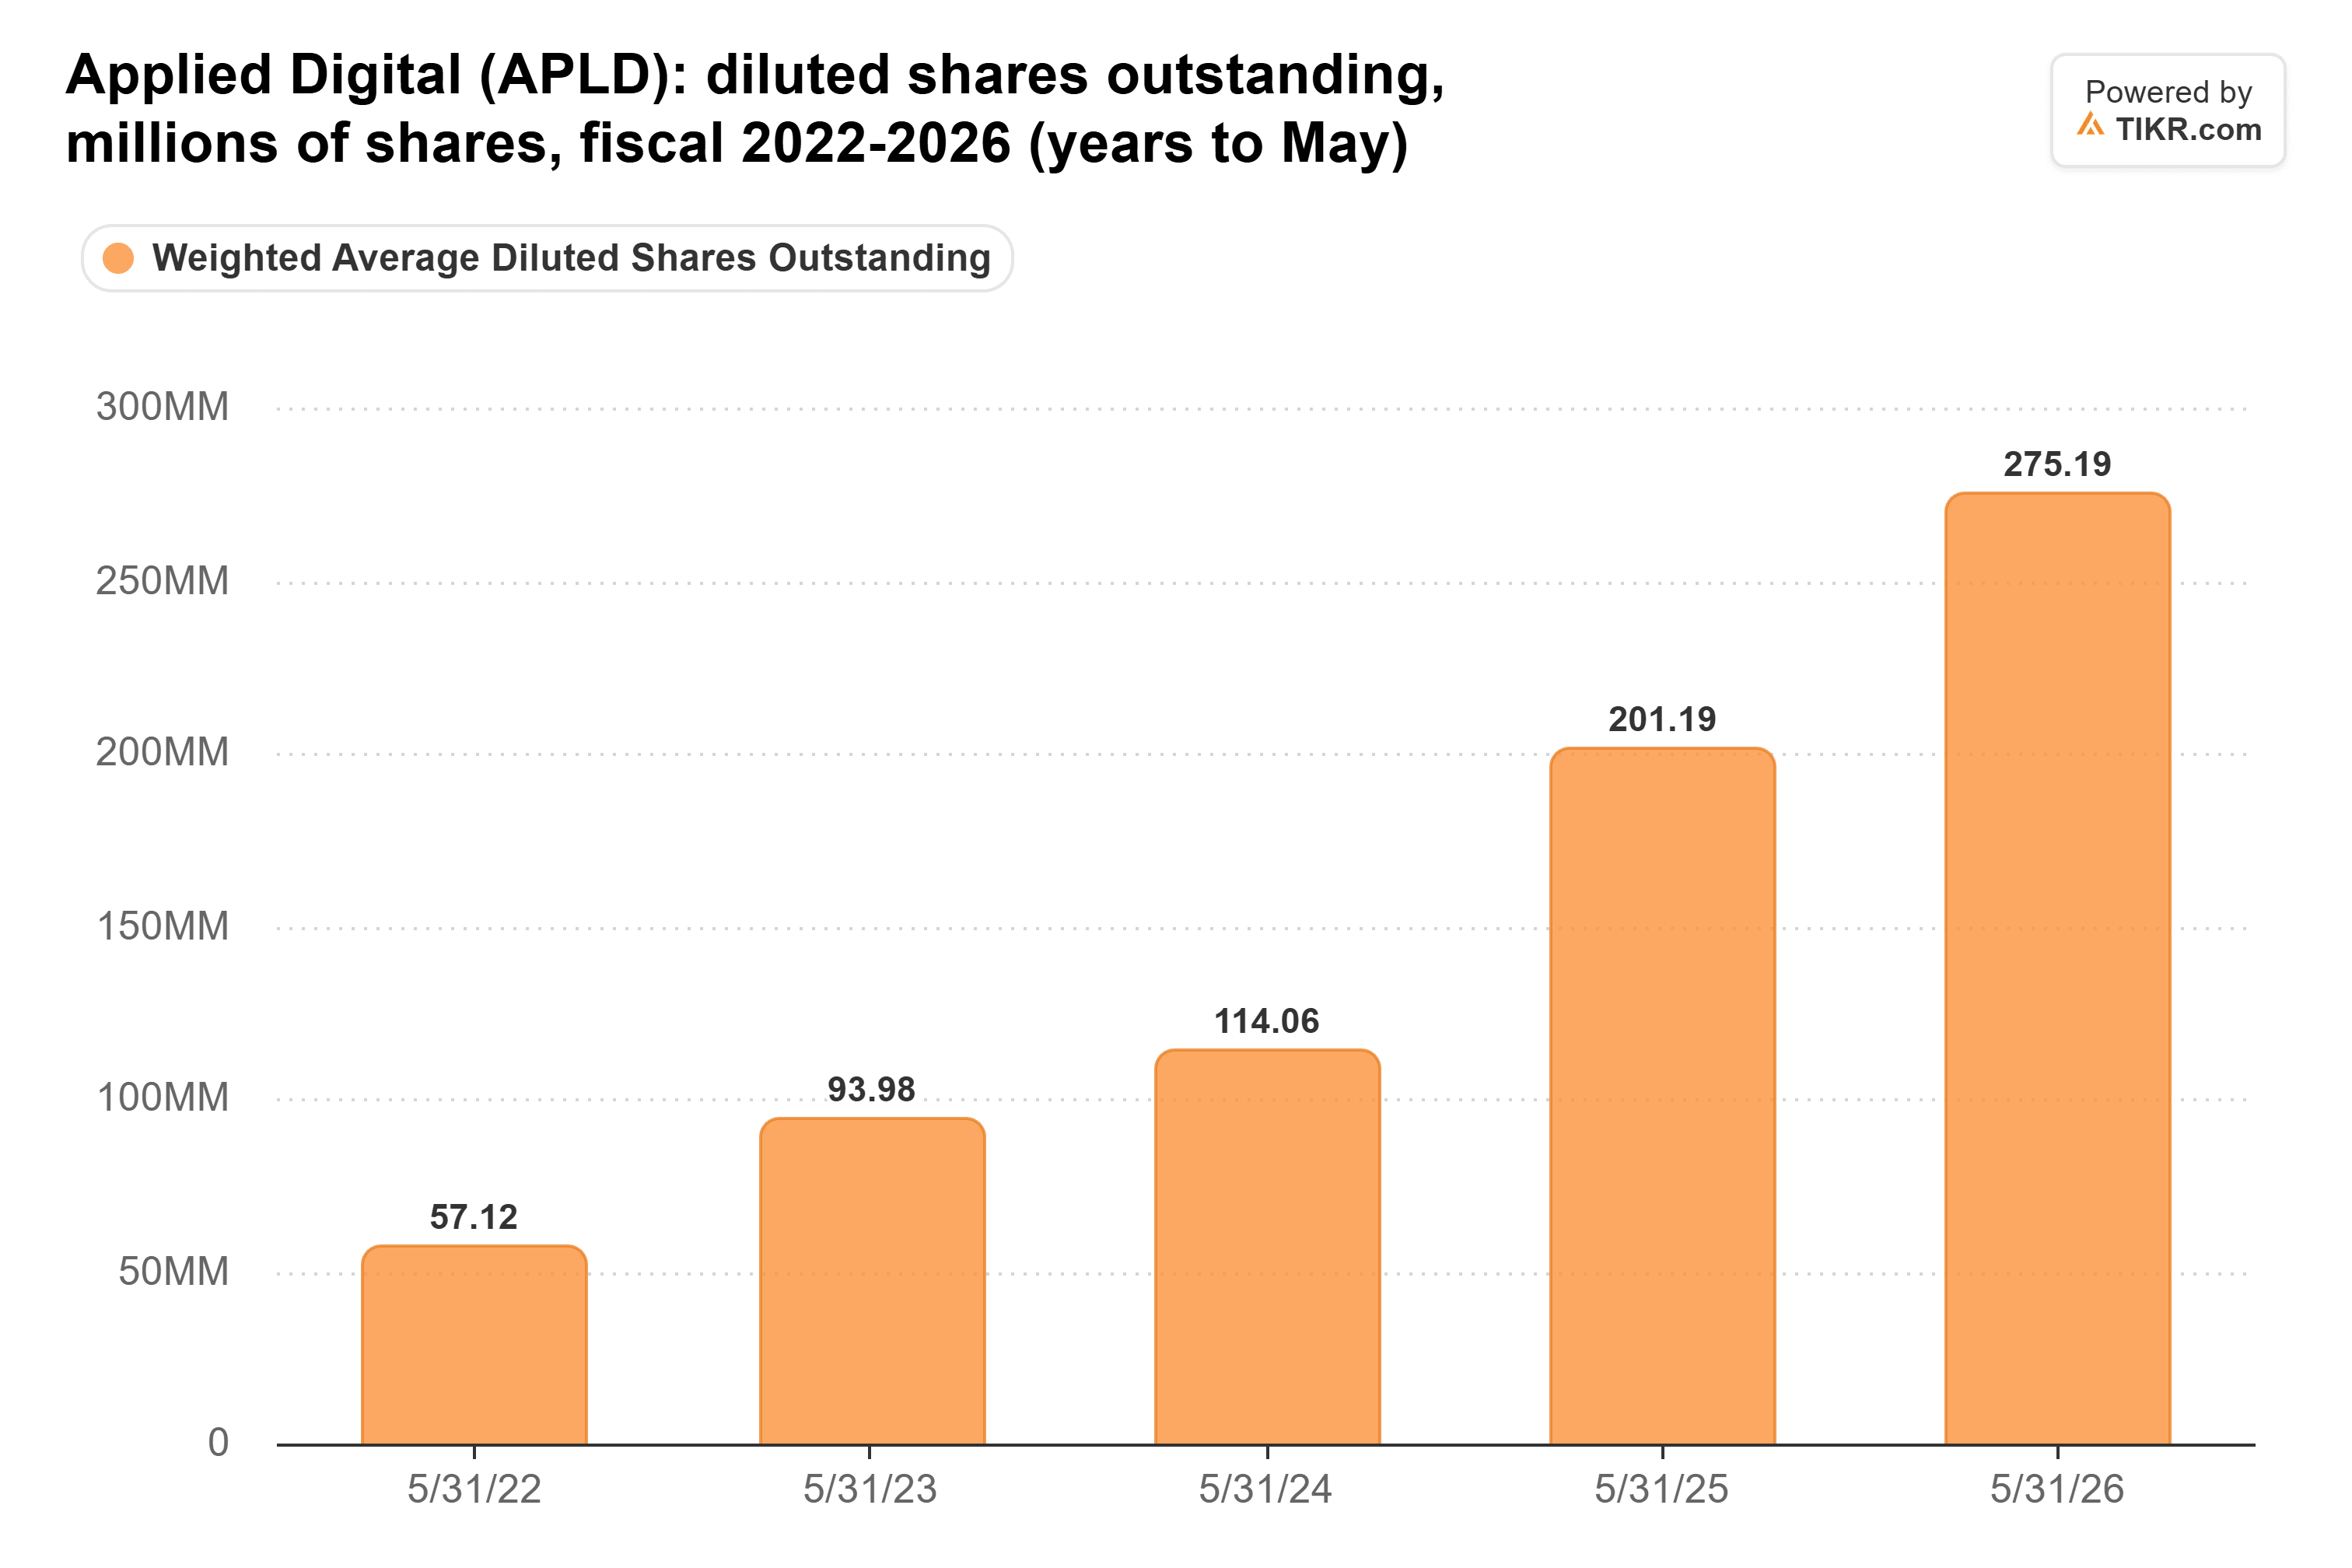
- Applied Digital’s total debt rose to $5.1 billion in fiscal 2026, and its diluted share count has nearly quintupled since fiscal 2022, so a cheaper way to pay for construction matters.
- The bonds are only proposed. There’s no rate, no maturity and no final approval yet, so the terms are what to watch.
Applied Digital (APLD) may have found a way to pay for its Louisiana AI campus on the strength of its tenant, Meta Platforms (META). A Louisiana public authority’s latest meeting packet proposes up to $4.6 billion of bonds for the project, to be repaid from Meta’s rent.
For a company that has paid for its growth with debt and new stock, that’s a big deal.
TIKR tracks 16 analysts on Applied Digital. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Digital, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Digital’s Analyst Ratings
What’s in the Louisiana packet
A poster on Reddit’s r/stocks flagged a 131-page packet for the Nov. 9 meeting of the England Economic and Industrial Development District. It includes a proposed agreement for:
- Up to $4.6 billion of revenue bonds, which the district would sell to institutional investors to pay for building Delta Forge 1, a 300 MW campus in Boyce, La.
- Payments on those bonds from Applied Digital’s project subsidiary, with Louisiana taxpayers responsible for none of it.
- A separate property-tax arrangement, with about $575 million of negotiated payments through 2052.
Meta is the campus’s tenant, on a 15-year lease the poster puts at about $7.5 billion. Spread evenly, that’s about $500 million a year, close to the $611 million of revenue Applied Digital booked in all of fiscal 2026 (the year ended May 2026). And analysts expect leases like this one to send its revenue sharply higher:
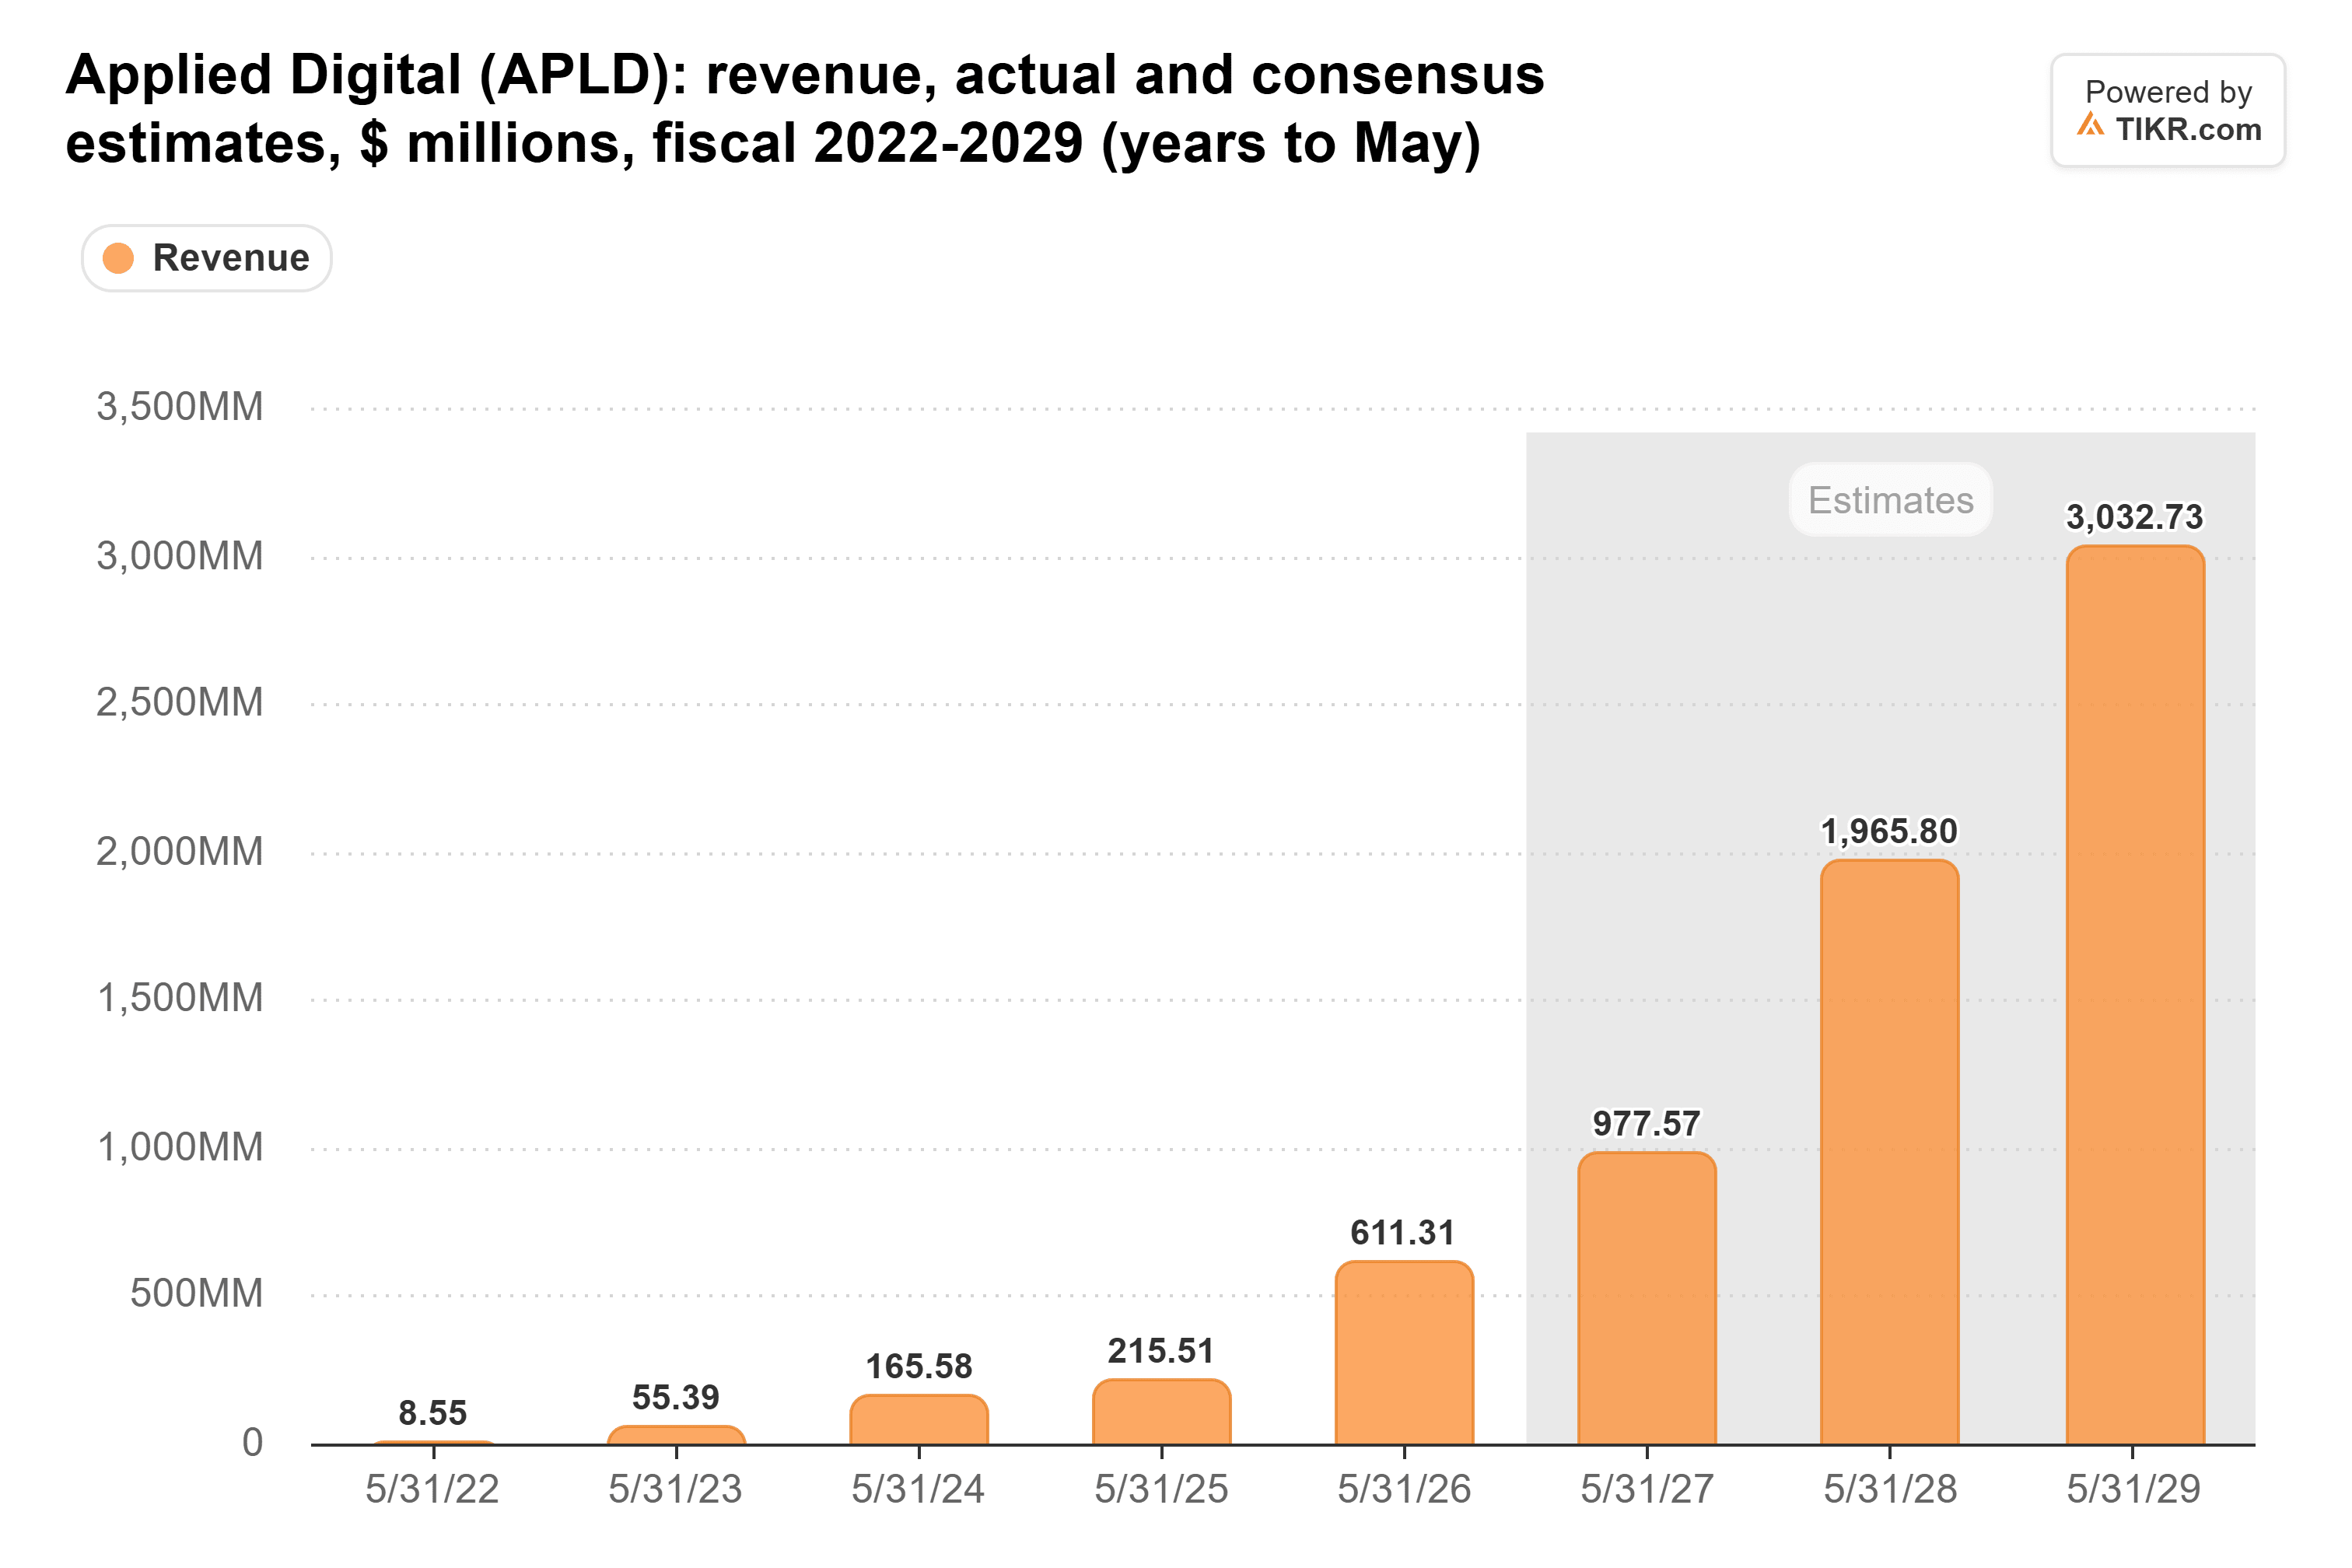
I wouldn’t expect a financing deal to move these estimates. The bigger question for shareholders is what that revenue costs to build.
Meta’s lease is the real collateral
The cost of money matters a lot in AI right now. Steve Eisman, the investor made famous by The Big Short, pointed on the Nov. 6 episode of The Real Eisman Playbook to CoreWeave’s debt being repriced from a yield of 9% to 15%, and said: “At a cost of debt of 15%, building AI data centers becomes prohibitively expensive.” CoreWeave’s bonds have since climbed to yields over 17%.
A revenue bond changes what lenders are pricing. Bondholders would be repaid from Meta’s rent, so what they’d mostly be judging is a 15-year lease from a company S&P rates AA-. S&P did cut its outlook on that rating to negative on Oct. 30 over Meta’s spending, but that’s still investment-grade credit, a long way from the neocloud borrowers Eisman describes.
Meta has a stake in this too. It guides 2026 capex, including finance-lease principal, to $135 billion to $145 billion, and at Sept. 30 it had $355.7 billion of signed leases that hadn’t started yet. Every one of those needs a landlord who can raise the money to build, and a way to borrow against Meta’s own lease makes that a lot easier.
Cheaper money, and fewer new shares
Applied Digital could use the help. Its total debt jumped from $911 million in fiscal 2025 to $5.1 billion in fiscal 2026:
It has sold plenty of stock along the way, too. The post’s big selling point is that Applied Digital wouldn’t need to issue billions of dollars of new shares for Delta Forge 1. Its diluted share count shows why that matters to holders, rising from 57.1 million in fiscal 2022 to 275 million in fiscal 2026:
Of course, no new shares still means new debt. The full $4.6 billion would nearly double what Applied Digital owed at the end of fiscal 2026 (if none of it replaces other financing already planned).
It’s a proposal until the bonds are sold
The $4.6 billion is a ceiling. The bonds haven’t been sold, there’s no rate or maturity yet, more approvals are needed, and the poster says Applied Digital’s own proposed guarantees deserve scrutiny. Other investors in the thread pointed out that the structure moves the risk onto the Meta lease and the build timeline: one tenant on the campus, and debt that has to be paid either way. Still, the district has backed Applied Digital before: it approved the project itself in April, NPR reported.
Bottom line: if Applied Digital can sell these bonds at a rate that reflects Meta’s credit, it builds Delta Forge 1 without another round of dilution and without paying neocloud rates. That’s a real win for the stock. The poster also counts three unfinanced campuses with Meta as the tenant, on $20.2 billion of leases, so Louisiana could be the template for the other two.
The number to watch is the rate. Until the district approves the agreement and the bonds actually price, Applied Digital has a financing route with no price tag on it yet.
So what is Applied Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Digital for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!