Key Takeaways
- Ed Zitron says two of CoreWeave’s bonds now yield more than 17%. A day earlier, Jason Lemkin put CoreWeave’s debt at about 15%.
- Lenders are pricing CoreWeave like distressed credit, so its next borrowing will cost more.
- CoreWeave’s free cash flow was -$7.25 billion in 2025, and its third-quarter interest guide is nearly four times its adjusted operating income guide.
- The bond market’s view is the more convincing one. The Nov. 10 third-quarter report is the first test.
CoreWeave (CRWV) has a lender problem: its bonds now trade like the debt of a company in trouble.
On Nov. 5, tech critic Ed Zitron posted on X: “There are now two CoreWeave bonds trading at over 17%, with one at 16.81%.” Earlier that day, he’d put two of them above 16%.
On the Nov. 4 episode of the 20VC podcast, SaaStr founder Jason Lemkin said 15%: “There’s wobbliness in the debt markets. CoreWeave debt is paying 15%. That’s wobbliness.”
The verified move is smaller but still sharp. CoreWeave’s dollar notes yielded about 15% to 16% on Nov. 2, and by Nov. 6 CNBC put its 2032 notes above 16%. That’s more than a wobble.
Wall Street Expects the Revenue to Show Up
Analysts expect CoreWeave’s revenue to grow more than eightfold from 2025 to 2028:
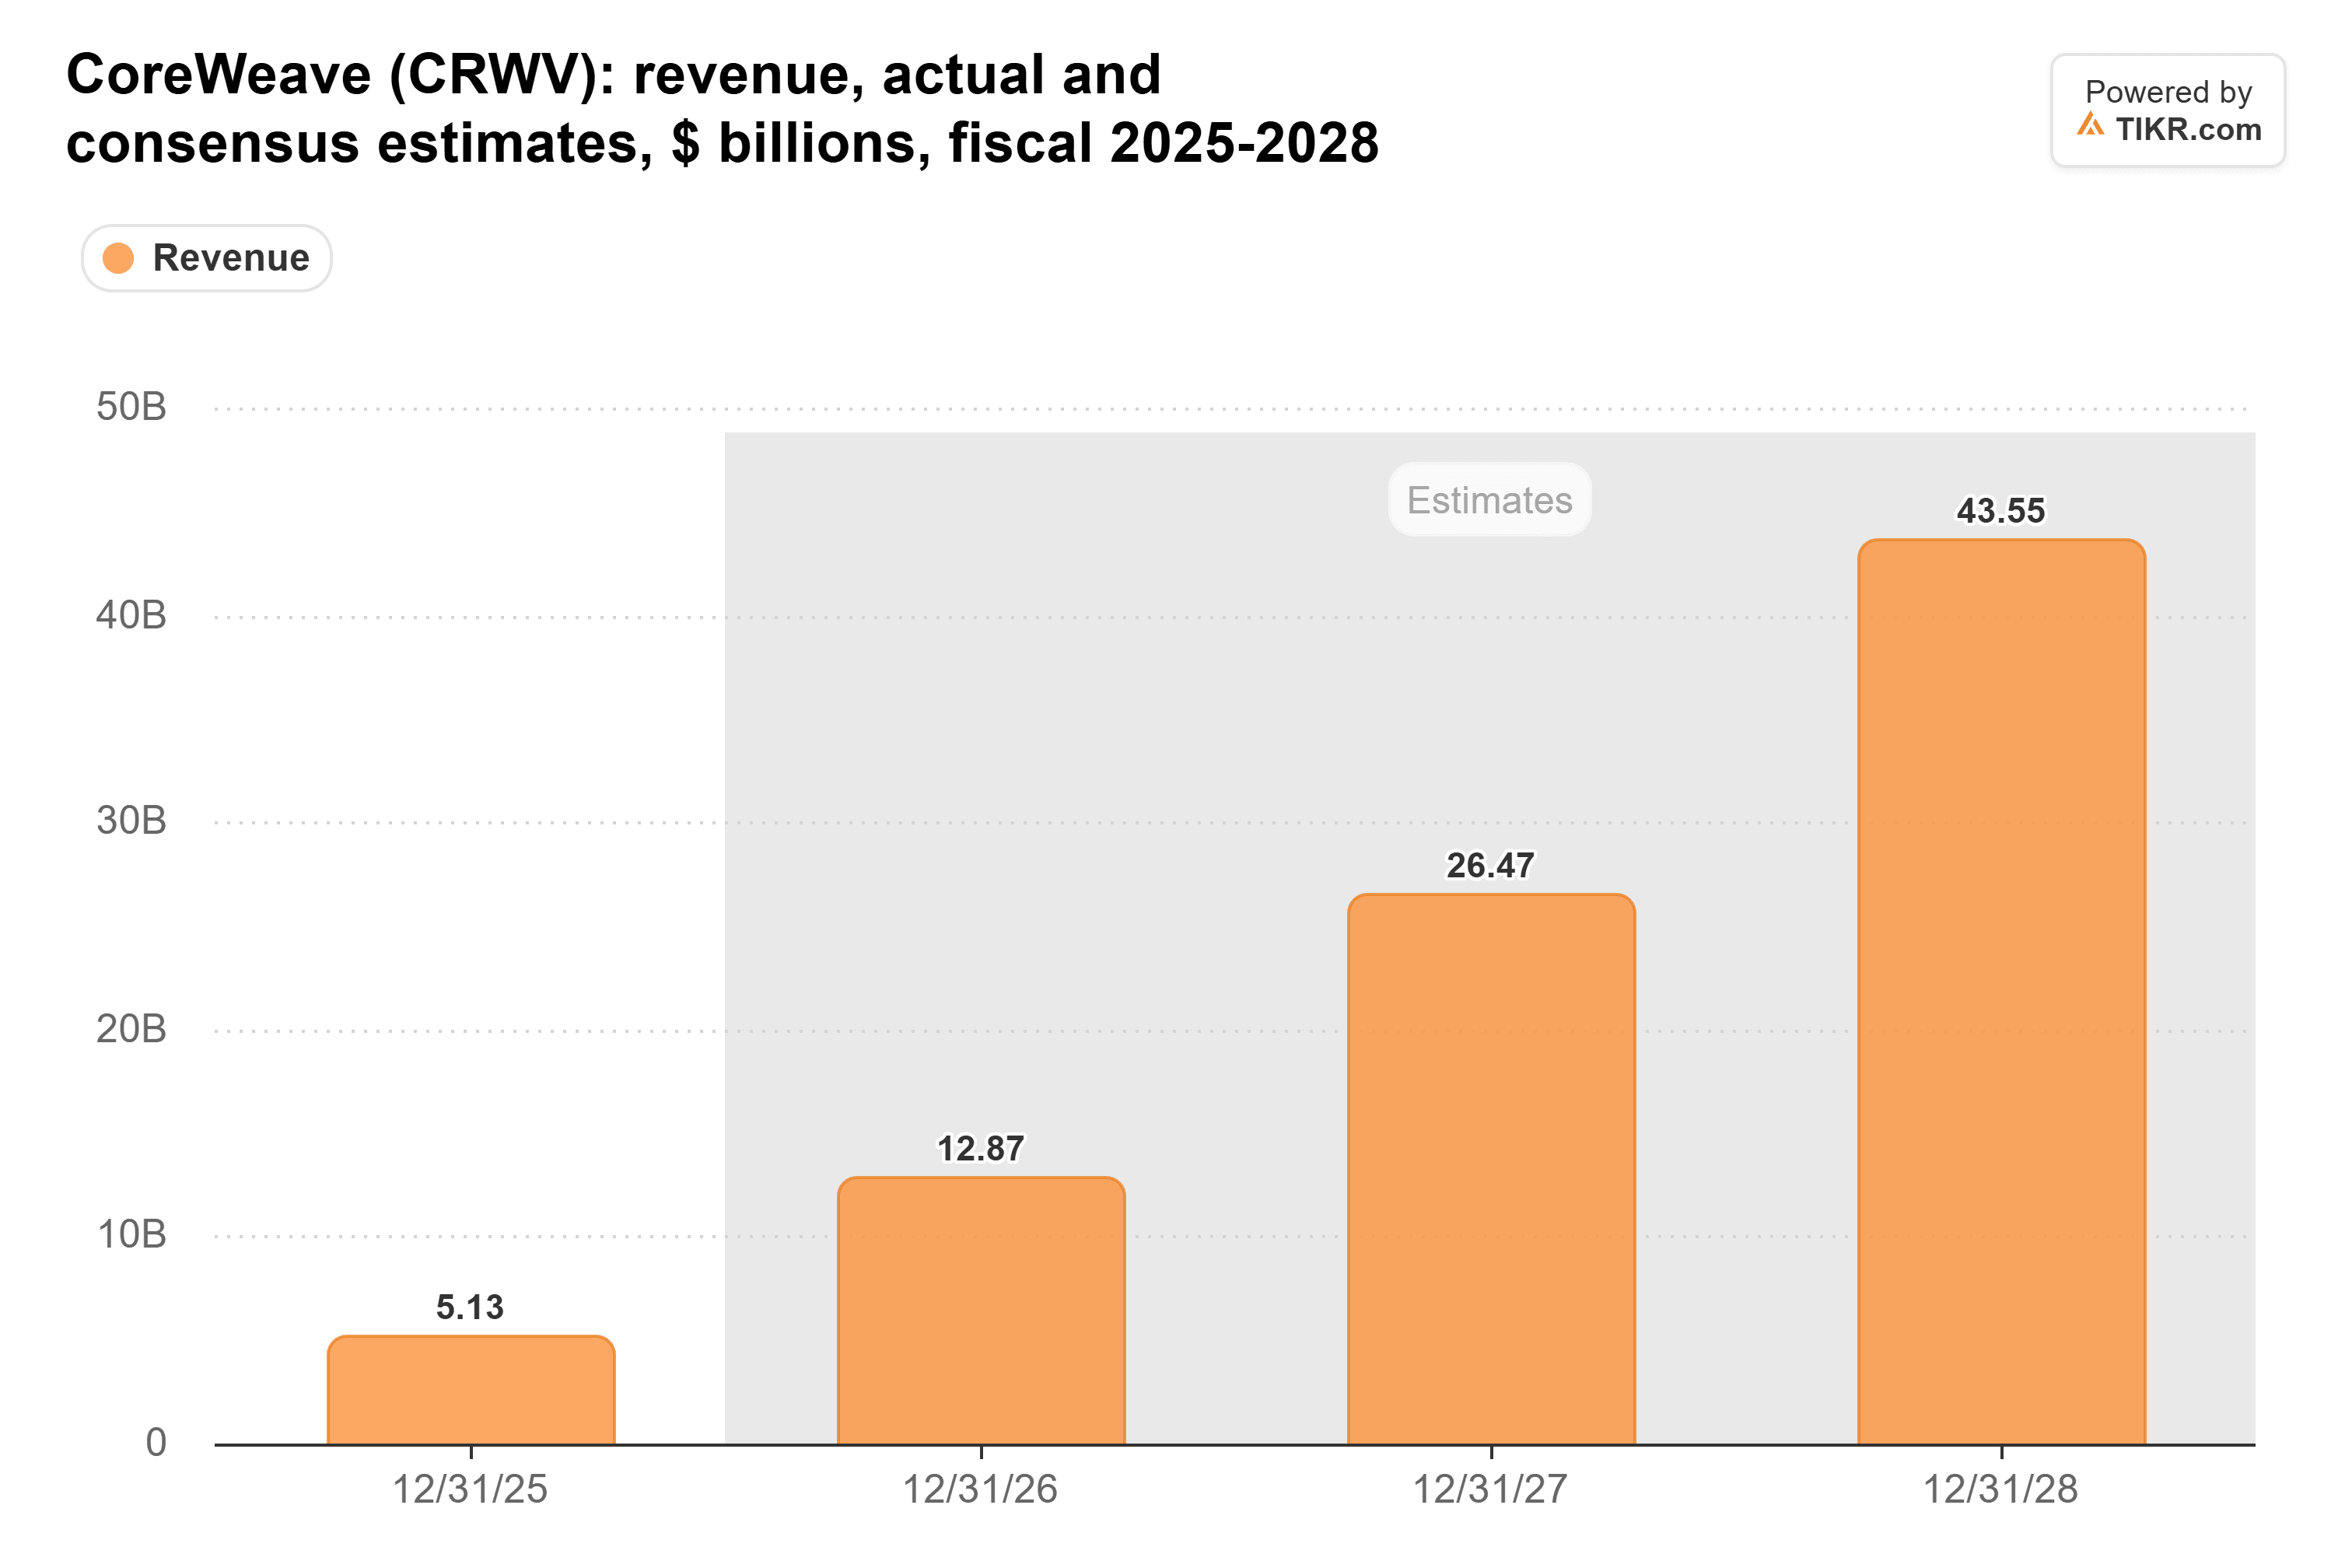
Lenders are counting on that growth to get paid back. But it has to build first, and that takes debt.
CoreWeave Builds on Borrowed Money
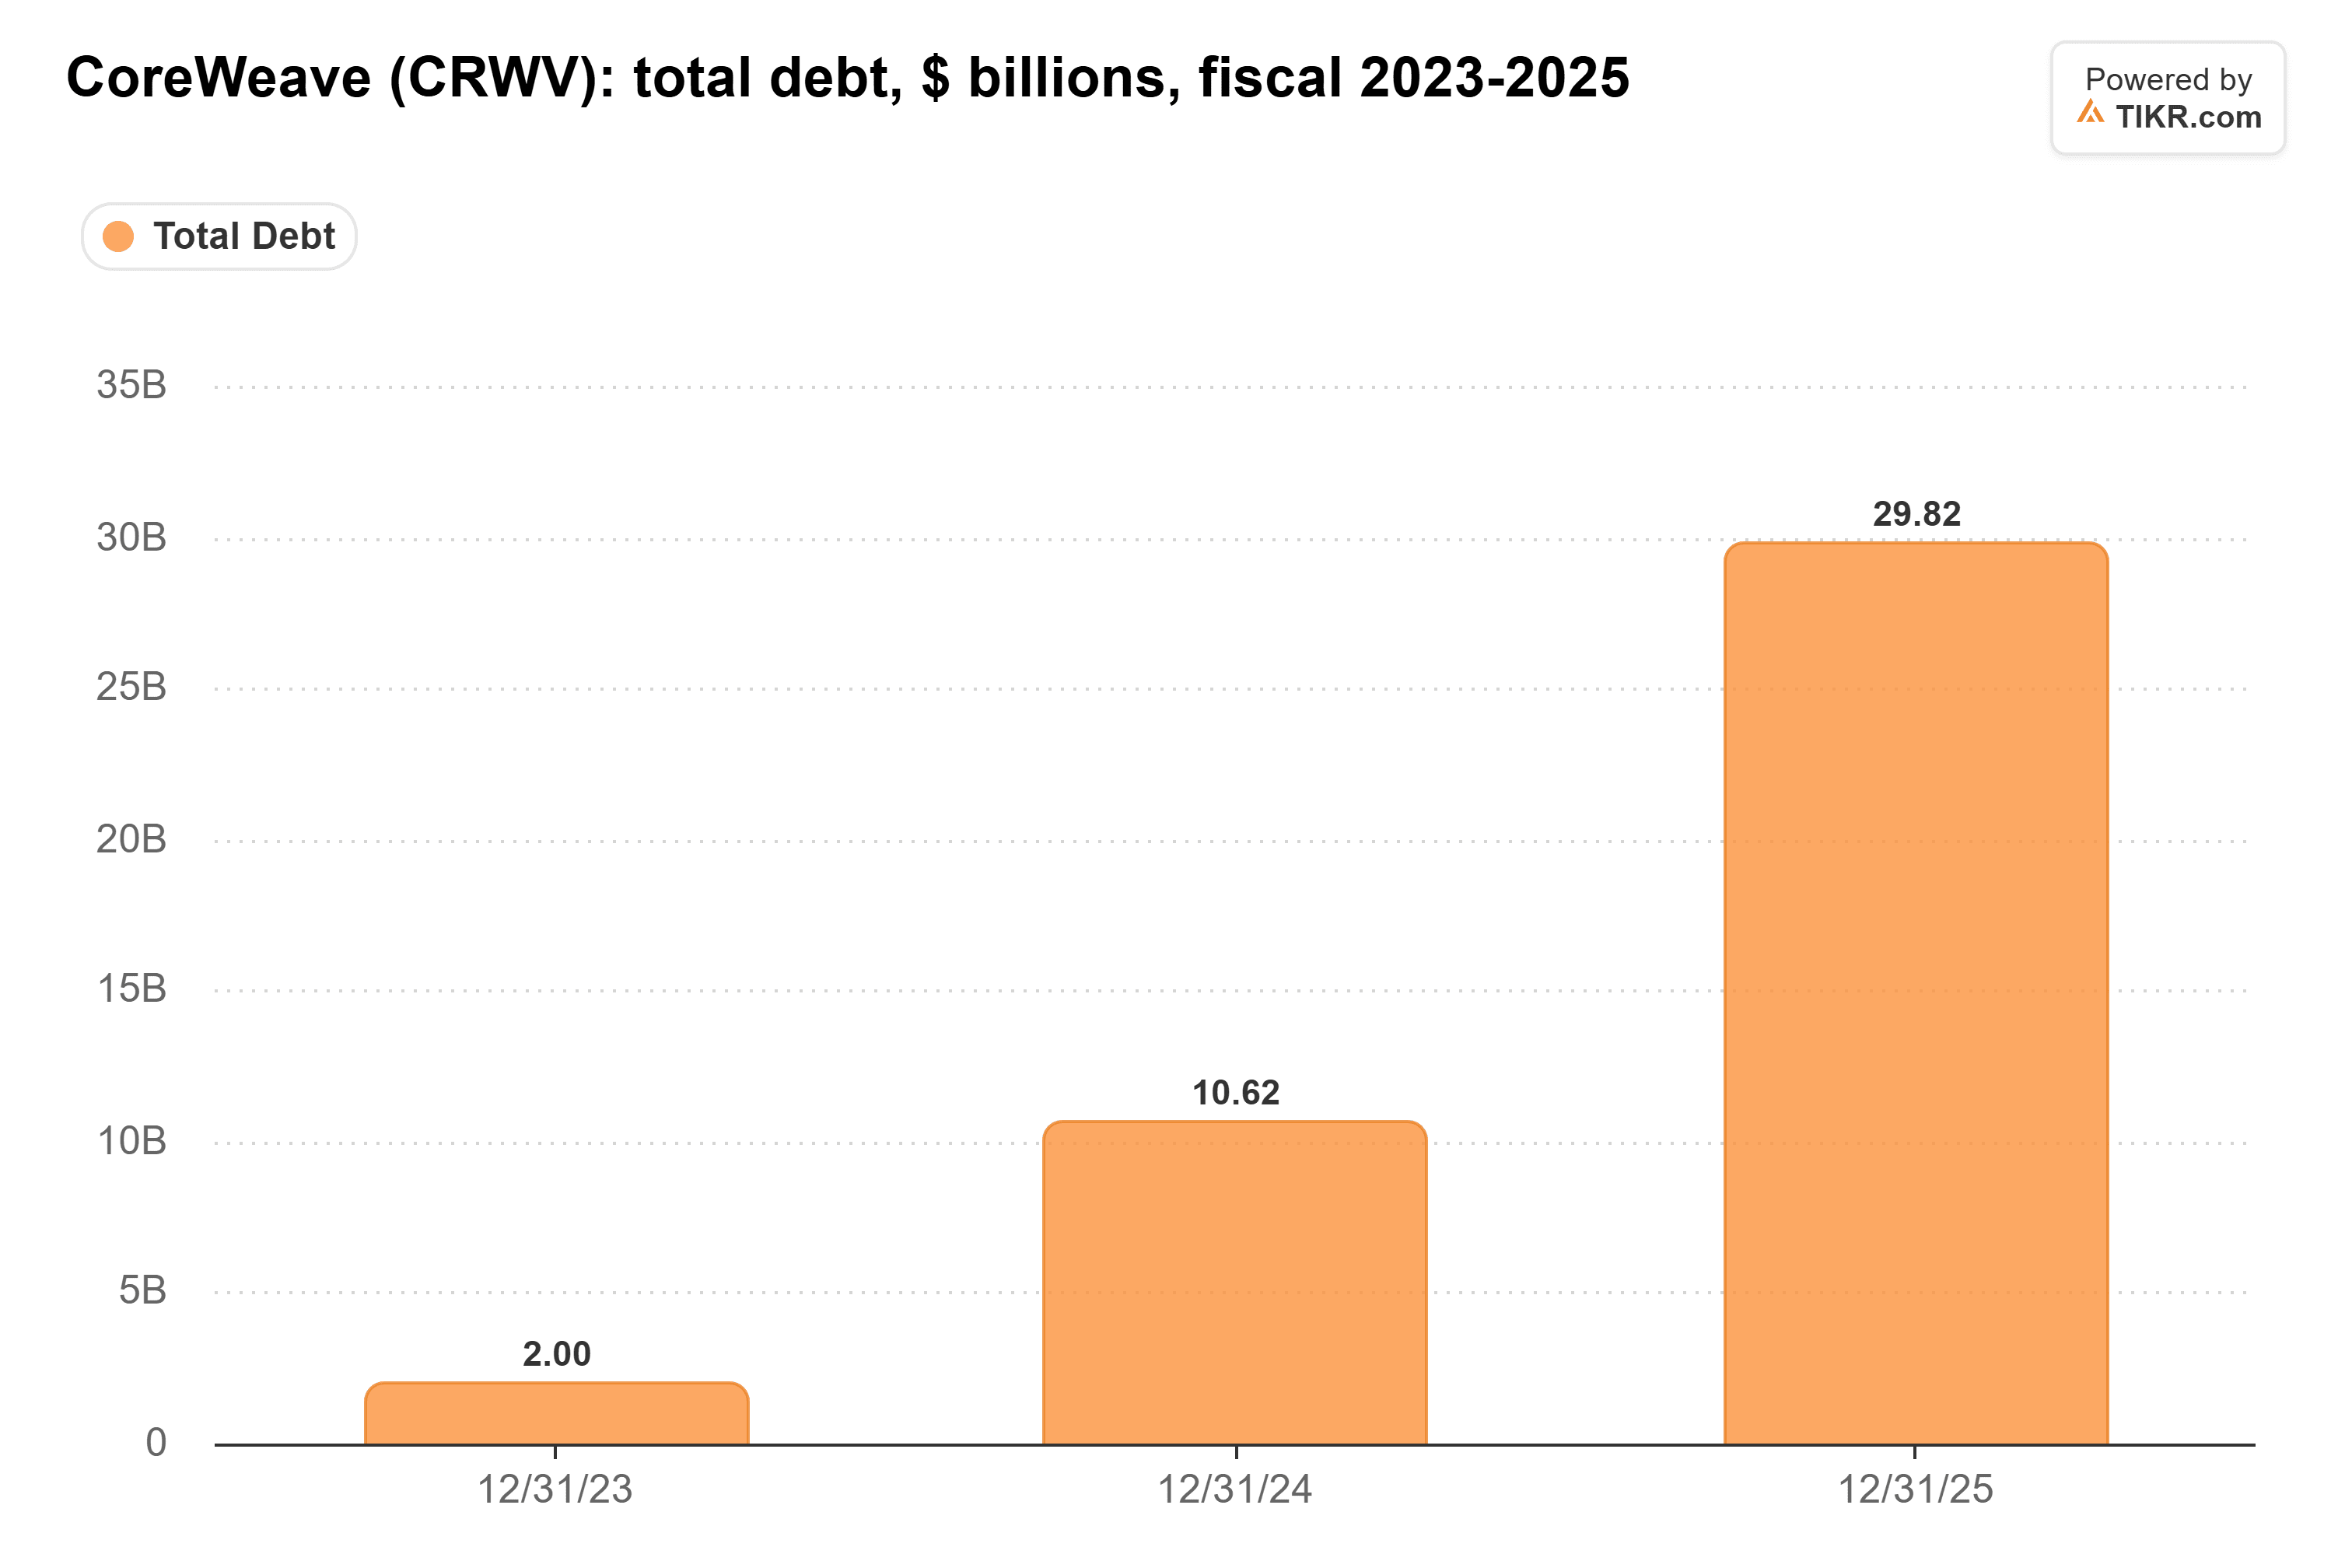
Its total debt on TIKR, which includes lease liabilities, rose from $2.0 billion at the end of 2023 to $29.8 billion at the end of 2025:
Free cash flow got more negative every year from 2022 to 2025:
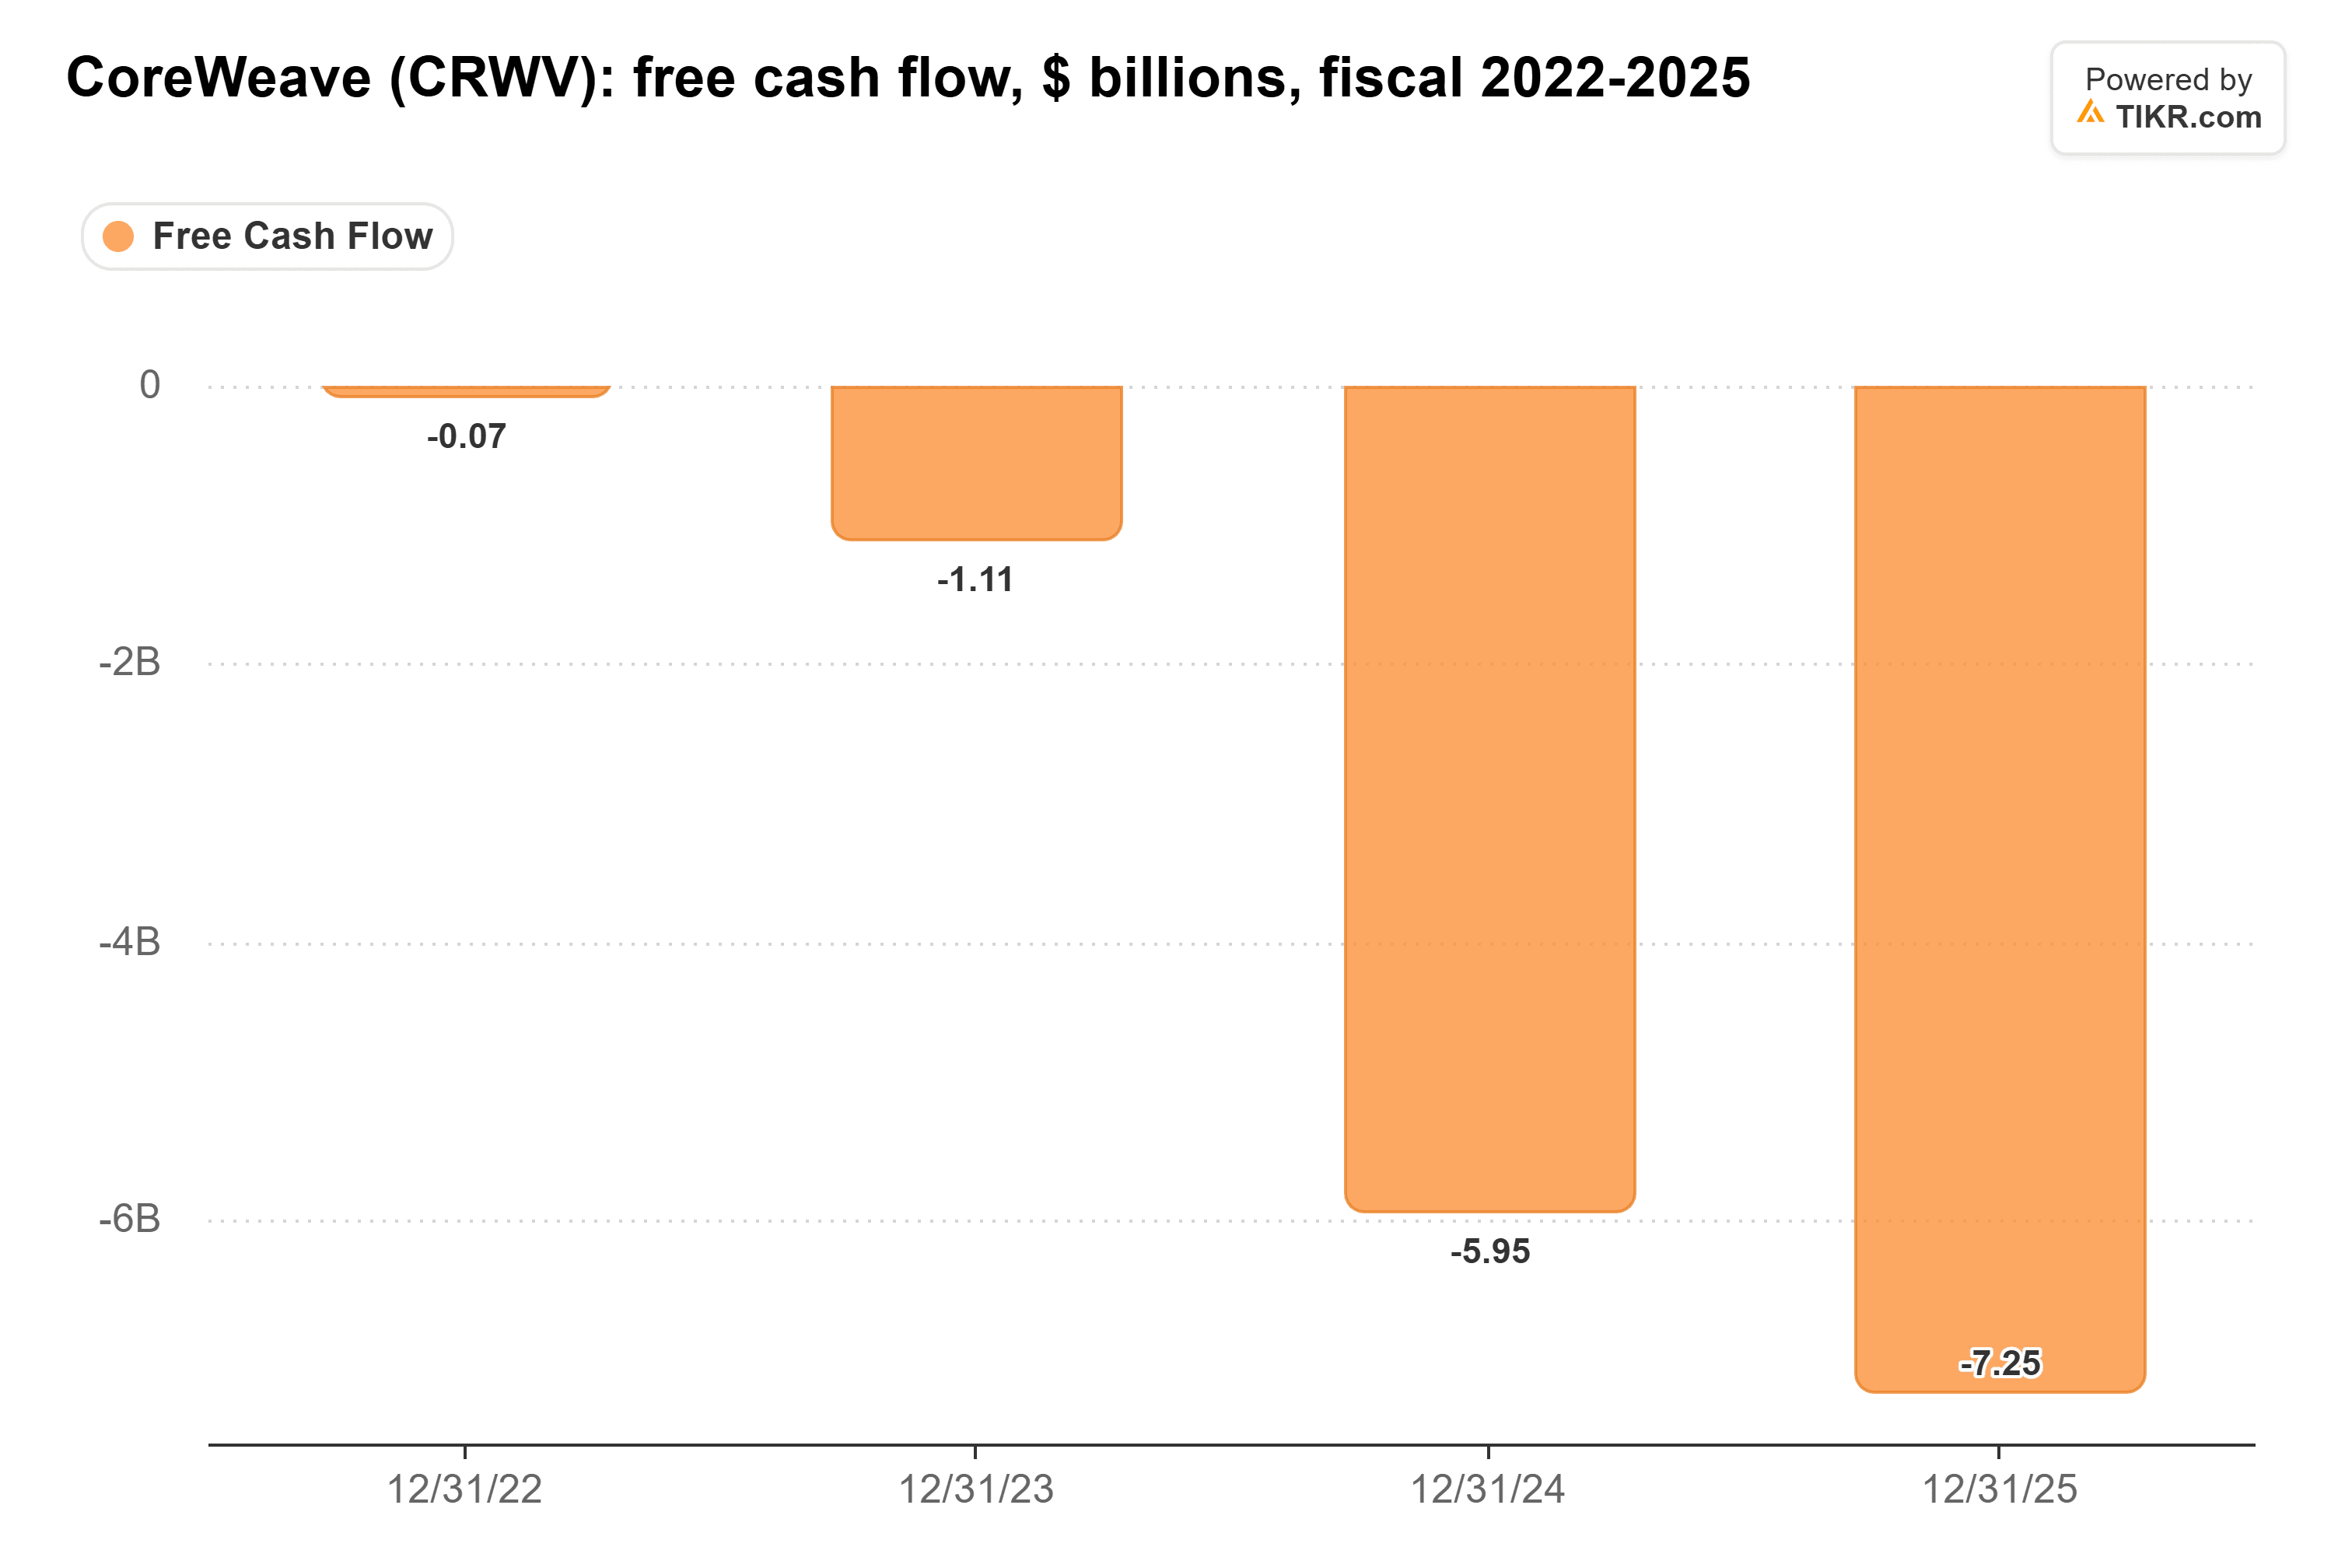
Consensus has free cash flow at -$28.8 billion this year and -$33.0 billion in 2027, and still negative in 2030.
6 Safe Dividend Stocks Paying Retirees 6%+ Yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Lenders Charge CoreWeave Two Very Different Rates
Interest already costs more than the business earns. CoreWeave guided third-quarter interest expense to $860 million to $940 million, against adjusted operating income of $200 million to $260 million, nearly four times at the midpoints.
CoreWeave pays two prices for new money. Loans backed by specific customer contracts got cheaper: its investment-grade DDTL 4.0 loan priced under 6% in March. Unsecured bonds got dearer, with coupons of 9.00% in July 2025, 9.75% in April 2026 and 9.625% in June.
With those bonds now yielding above 16%, a new unsecured lender would likely ask for something much closer to that than to 9.75%. Oracle, which is investment grade, priced $10 billion of notes on Nov. 2 at coupons of 7% to 8.65%.
Equity analysts are kinder. Citi cut its target to $128 from $159 on Nov. 4 and kept its Buy rating. But lenders get paid before shareholders.
The Midterms Help the Sites CoreWeave Already Has
Part of this is sector-wide. Democrats swept Congress on Nov. 3, and nearly every local data center ballot measure with results went against the projects.
The generous reading: if new data centers get harder to build, the 1.5 gigawatts CoreWeave had running at June 30 become scarcer and worth more. Rory O’Driscoll put it on the same 20VC episode: “if the other side of the equation, the demand side, holds up, all these things will be forgotten in six months.”
But CoreWeave’s growth depends on capacity it hasn’t built. It had 4.2 gigawatts under contract as of Aug. 11, and US customers brought in 93.6% of its 2025 revenue. Tougher local rules raise the odds of delays, and last November a developer’s delay already forced a 2025 revenue guidance cut.
What CoreWeave Has to Show on Nov. 10
I’m with the bondholders. Until operating profit covers interest, the stock carries the risk its lenders are pricing.
The third-quarter report on Nov. 10 is the first test. Adjusted operating income at or above $260 million, with full-year guidance held, would ease some of the pressure. After that, watch the coupon on CoreWeave’s next unsecured bond.
Enjoy Your Retirement In Style With These Safe 6%+ Dividend Yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!