Key Takeaways
- Earlier today, Sen. Ron Johnson said on Fox Business that Social Security can’t be fixed and should be shut down, an idea he floated on TV ahead of a Senate hearing he chaired.
- Under current law, the Social Security Trustees project that the retirement trust fund will run out in late 2032, and the taxes still coming in after that would pay 78% of scheduled benefits.
- A retiree collecting $2,000 a month would get $1,560 if Congress does nothing, and nothing at all if the program shut down.
- You can cover most of that gap by planning on 78% of your check, waiting until 70 to claim, and building your own income from savings and dividend stocks.
Sen. Ron Johnson (R-Wis.) doesn’t think Social Security can be saved. “At this point, there’s really no way to fix Social Security. It’s a Ponzi scheme. You can’t fix it, you just shut it down and hope that you can recover some of your money,” he said on Fox Business on Nov. 18. That was the morning he chaired a Senate Budget Committee hearing called “Social Security: The Reality.”
Update: At the hearing later that day, Johnson said he was “not saying shut down Social Security. I was talking about Ponzi schemes are shut down.” His proposal, he said, is to “change the law so we don’t reduce benefits.”
For now, that’s an idea one senator floated on TV, and it doesn’t hold up as a plan. There’s no account to recover your money from: the payroll taxes you paid went out the door as checks to the retirees of the time, which is how the program has always worked. Shutting it down would simply stop the checks, including those of everyone collecting today. Doing nothing at all leaves you far more, as the Trustees’ own figures show below. Still, if you’re retired or getting close, it’s a good reason to ask how much of your plan depends on a check from Washington, and what you’d do with less of it.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Even with no fix, most of the check keeps coming
The Social Security Trustees’ 2026 report projects that the trust fund paying retirees and survivors will run out of reserves in the fourth quarter of 2032. That’s one quarter earlier than last year’s report projected. After that, the taxes still coming in would cover 78% of scheduled benefits, and that share falls gradually to 62% by 2100. These are projections based on the Trustees’ best-estimate assumptions, and the law doesn’t set any date or cut.
You may have seen headlines about insolvency in 2034 instead. That’s when the money would run out if the retirement and disability funds were pooled, and the report says pooling them would take a change in the law. People on Social Security disability are paid from the disability fund, which the Trustees expect to stay funded for all 75 years they project.
A $2,000 check, three ways
Let’s say you’re retired and collecting $2,000 a month. The 78% is a share of all scheduled benefits, so if Congress does nothing, it’s safe to assume that your check drops to $1,560 once the reserves run out. That leaves you $440 a month short, or $5,280 a year. If the program shut down, you’d get nothing and lose the full $24,000 a year your checks pay now.
The bigger the check, the more there is to lose. A worker who earned the maximum taxed amount every year since 22 and retires at 70 in January 2027 starts at $5,358 a month, the most Social Security pays. At 78%, that falls to about $4,180, and in a shutdown it’s, of course, zero.
Plan on 78%, and claim later if you can
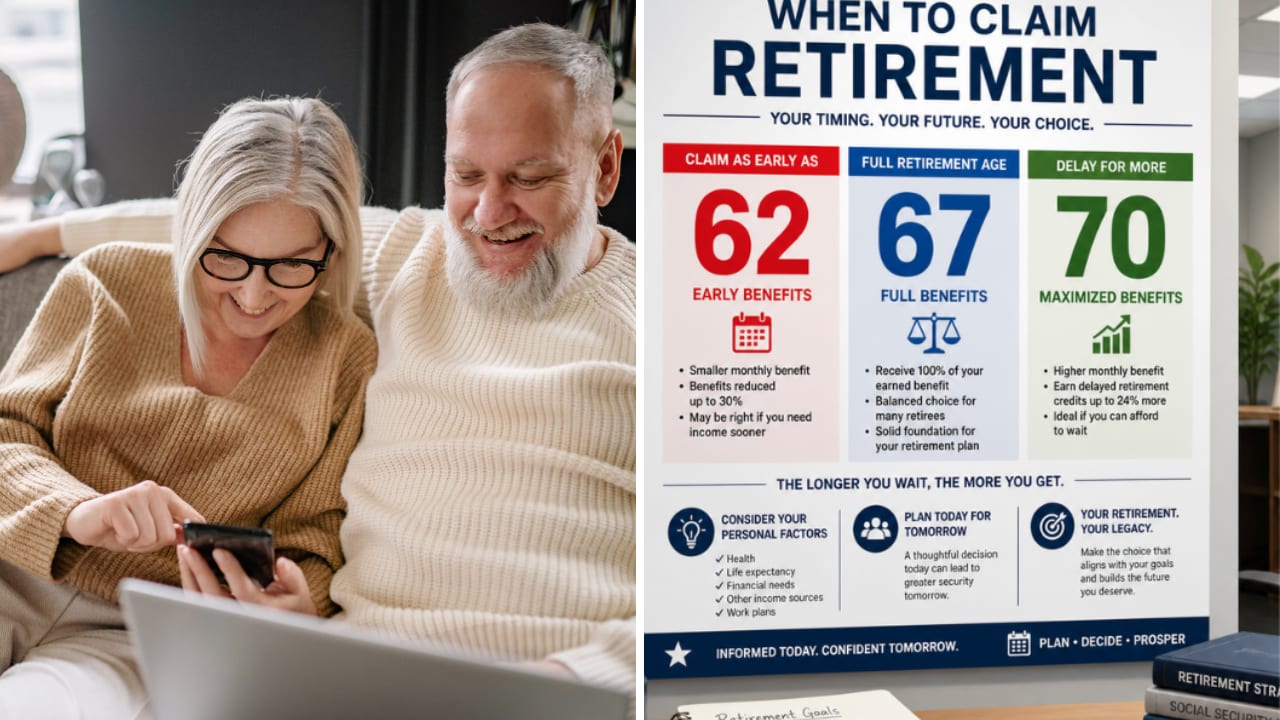
The simplest move is to build your retirement budget as if 78% of your estimated check shows up, and to treat anything more as a bonus. If you haven’t claimed yet, make that 78% as big as you can. If you were born in 1960 or later, your full retirement age is 67. If you claim at 62, your check is 30% smaller for life. If you wait past 67, it grows 8% for each year until 70.
Say your benefit at 67 is $2,000. That’s $1,400 a month at 62 and $2,480 at 70. At 78% of each, claiming at 62 leaves you about $1,090 a month. Waiting until 70 leaves you about $1,930, close to the full $2,000 you’d have gotten at 67.
Already collecting, and somewhere between 67 and 70? You can ask Social Security to suspend your payments. You’ll earn delayed credits for each month they’re stopped, and the payments start again on their own the month you turn 70. The catch is that you give up checks while you wait, so it’s mostly worth it for people who expect to live a long time.
Build a paycheck of your own
Whatever Social Security doesn’t pay has to come from you: savings, a pension if you have one, and stocks that pay dividends. That $440 monthly gap comes to $5,280 a year. Say your dividend stocks yield 4%: covering that gap takes $132,000 invested. Replacing all $24,000 a year would take $600,000. That’s a lot of money for most retirees, and one more reason claiming later matters so much.
Dividends can be cut too. That’s why income spread across several payers that comfortably cover their dividends is sturdier than one big yield.
Frankly, if Congress fixes Social Security, a budget built on 78% just leaves you with extra cushion. And if it doesn’t, you’re already prepared. The Trustees’ 2027 report, due around the middle of next year, will show whether the 2032 date holds.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!