Key Takeaways
- David Tepper’s Appaloosa filed its 13F for the quarter ended Sept. 30 on Nov. 16. It showed $7.56 billion of US stocks in 24 positions.
- Among its positions of 2% or more, Wall Street sees the most upside in Micron, Alibaba, Oracle, SpaceX and Lam Research, with average targets 72% to 119% above today’s prices.
- Four of the five have fallen 16% to 36% since Sept. 30, so much of that upside comes from the selloff.
- Micron, Appaloosa’s biggest position, is the one the numbers back best, though memory stocks have looked this cheap at past peaks.
David Tepper doesn’t spread his money thin. His Appaloosa, which manages $20.40 billion in all, held just 24 US stocks worth $7.56 billion at Sept. 30, according to its 13F for the quarter, filed Nov. 16.
Most of his big bets have taken a beating since. Here are the five of his positions of 2% or more where Wall Street sees the most upside: Micron (MU), Alibaba (BABA), Oracle (ORCL), SpaceX (SPCX) and Lam Research (LRCX).
1. Micron: Tepper’s biggest bet got bigger
Micron is Appaloosa’s largest holding by far: 1.25 million shares worth $1.33 billion at Sept. 30, or 17.6% of its 13F stocks, after it added 28% more shares in the quarter. The stock is down 33% since then, even though Micron’s revenue more than tripled to $133.2 billion in fiscal 2026 and it out-earned Apple last quarter.
Analysts have raised their numbers all year. Over the past 12 months, the average target has climbed from about $213 to $1,562, which is 119% above today’s price:
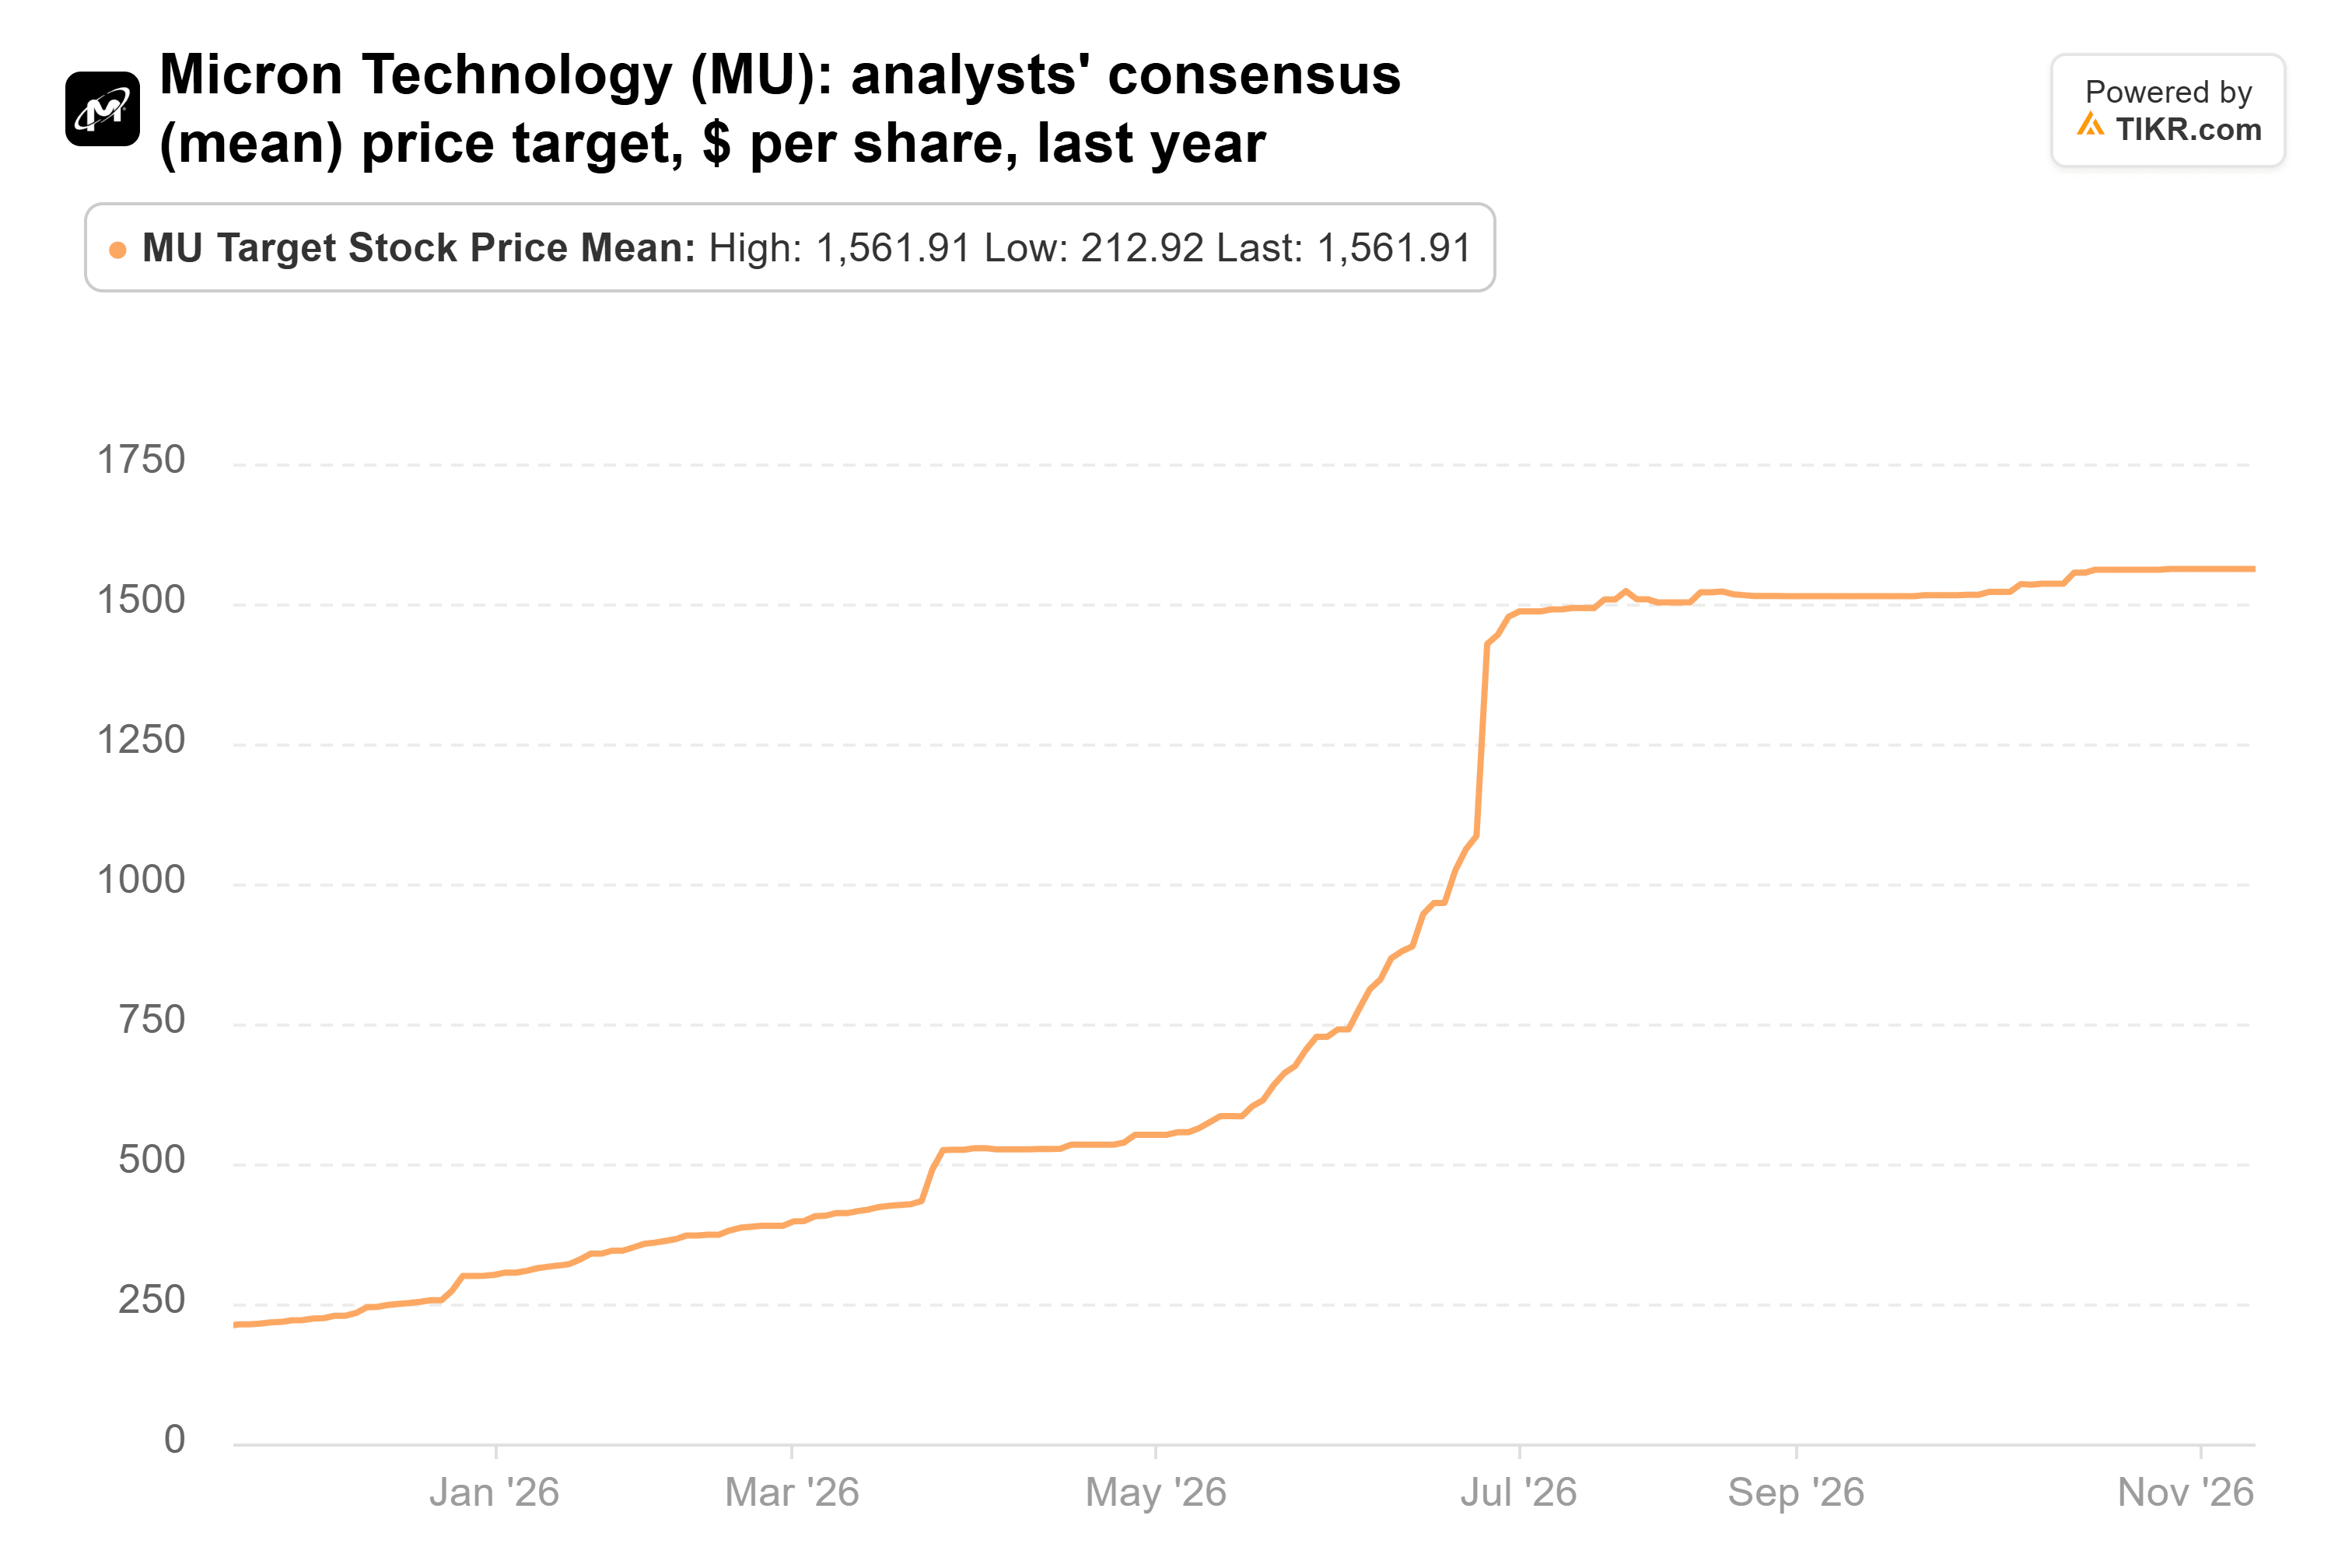
By our math, $1,562 is under 8x analysts’ fiscal 2028 earnings estimate. Micron has usually traded at about 10x since 2014. Today it trades at about 4x forward earnings. Its December report covers the quarter that management calls this fiscal year’s low point for gross margin.
TIKR tracks 50 analysts on Micron. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
2. Alibaba: the cloud is booming, but the cash isn’t there yet
Appaloosa trimmed its Alibaba stake by 7% in the third quarter, to 1.85 million shares worth $199 million, or 2.6% of its 13F stocks. The stock is down 19% since Sept. 30 and 52% below its 52-week high.
The cloud business is doing its part. Its revenue grew 45% in the June quarter to RMB 48.4 billion, and its adjusted EBITA margin rose to 11.6% from 7.2% a year earlier. But the AI apps unit lost RMB 13.9 billion in the same quarter, and free cash flow was an outflow of RMB 44.7 billion. Meanwhile, the US keeps tightening its chip curbs on Chinese AI companies.
The Street’s average target of $185 is 113% above today’s price. But analysts have been cutting it all year, and it’s about 12% lower than it was 12 months ago:
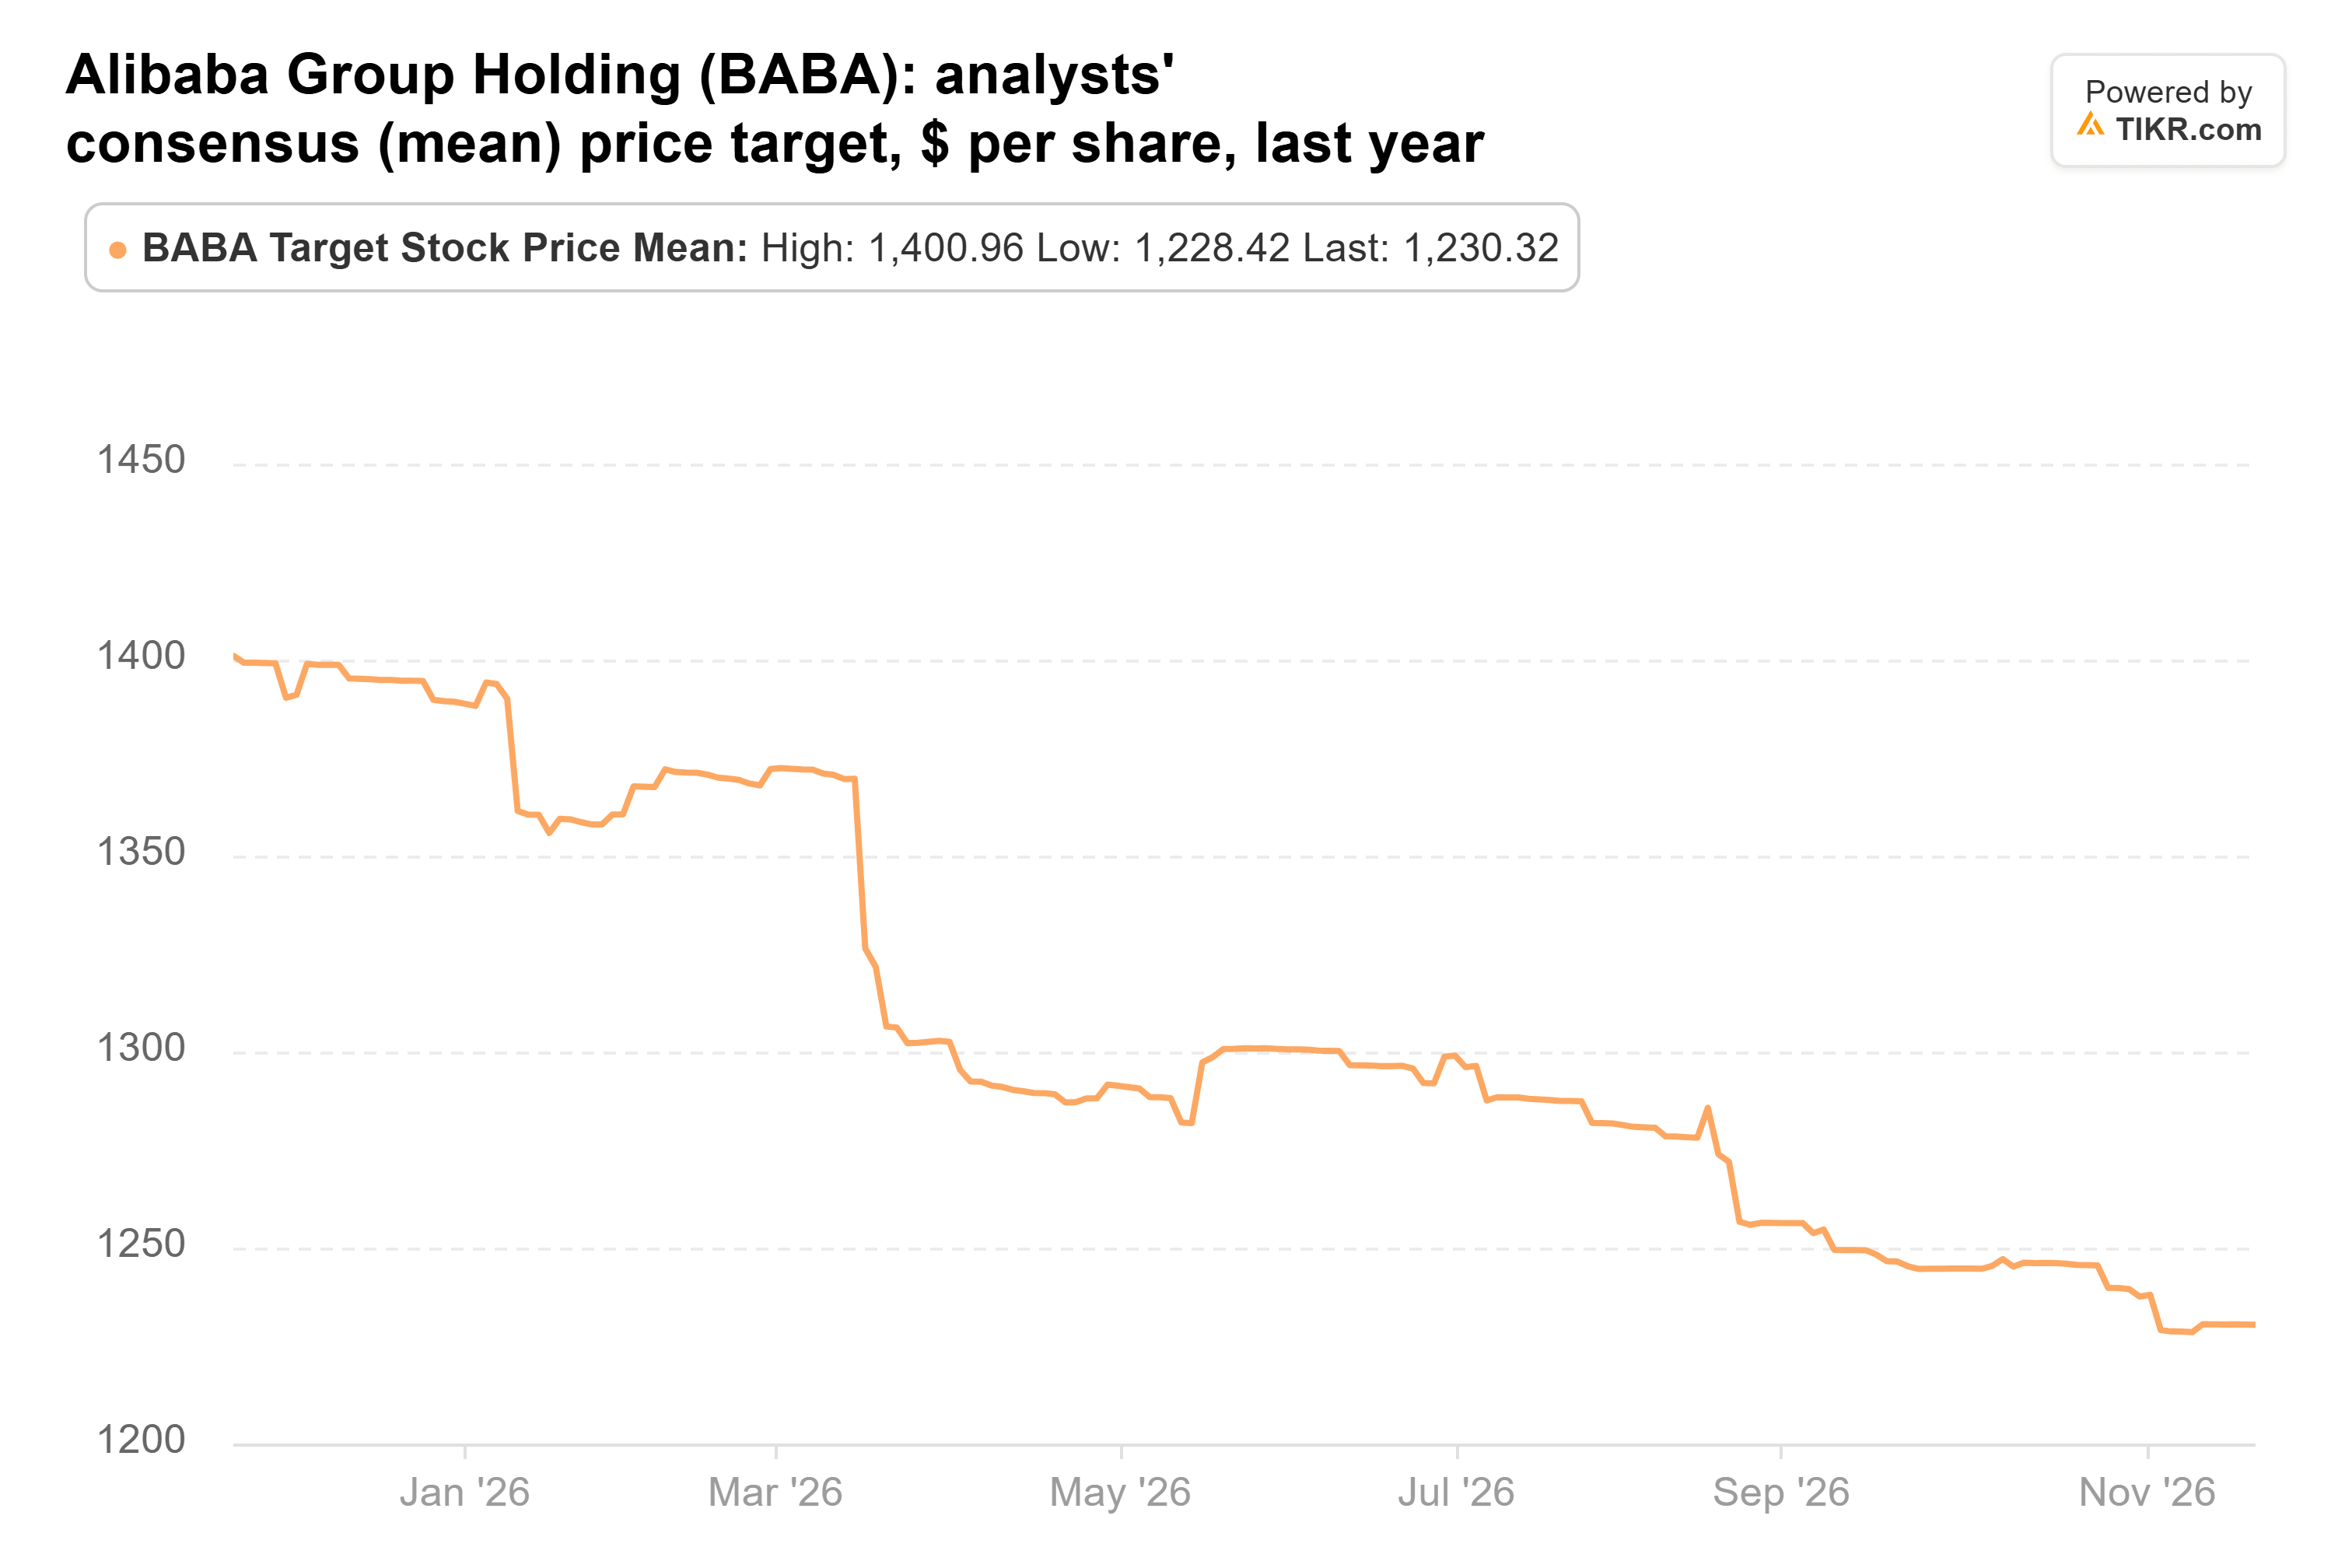
Alibaba reports its September quarter this week. A cloud margin above June’s 11.6% and a smaller loss in the AI apps unit would show the spending starting to pay off.
3. Oracle: a new position with a lot riding on OpenAI
Oracle is new to the portfolio. Appaloosa held 1.25 million shares worth $172 million at Sept. 30, or 2.3% of its 13F stocks. The stock is down 16% since then and 54% below its 52-week high.
Oracle’s contracted backlog reached $664 billion at Aug. 31, but S&P says about half of it is OpenAI. Building the data centers behind that backlog left free cash flow at negative $23.7 billion in fiscal 2026 (the year to May). CFO Hilary Maxson now promises more than $30 billion of free cash flow in fiscal 2029. Even so, analysts have cut their targets all year, and the average is down from $348 to $236:
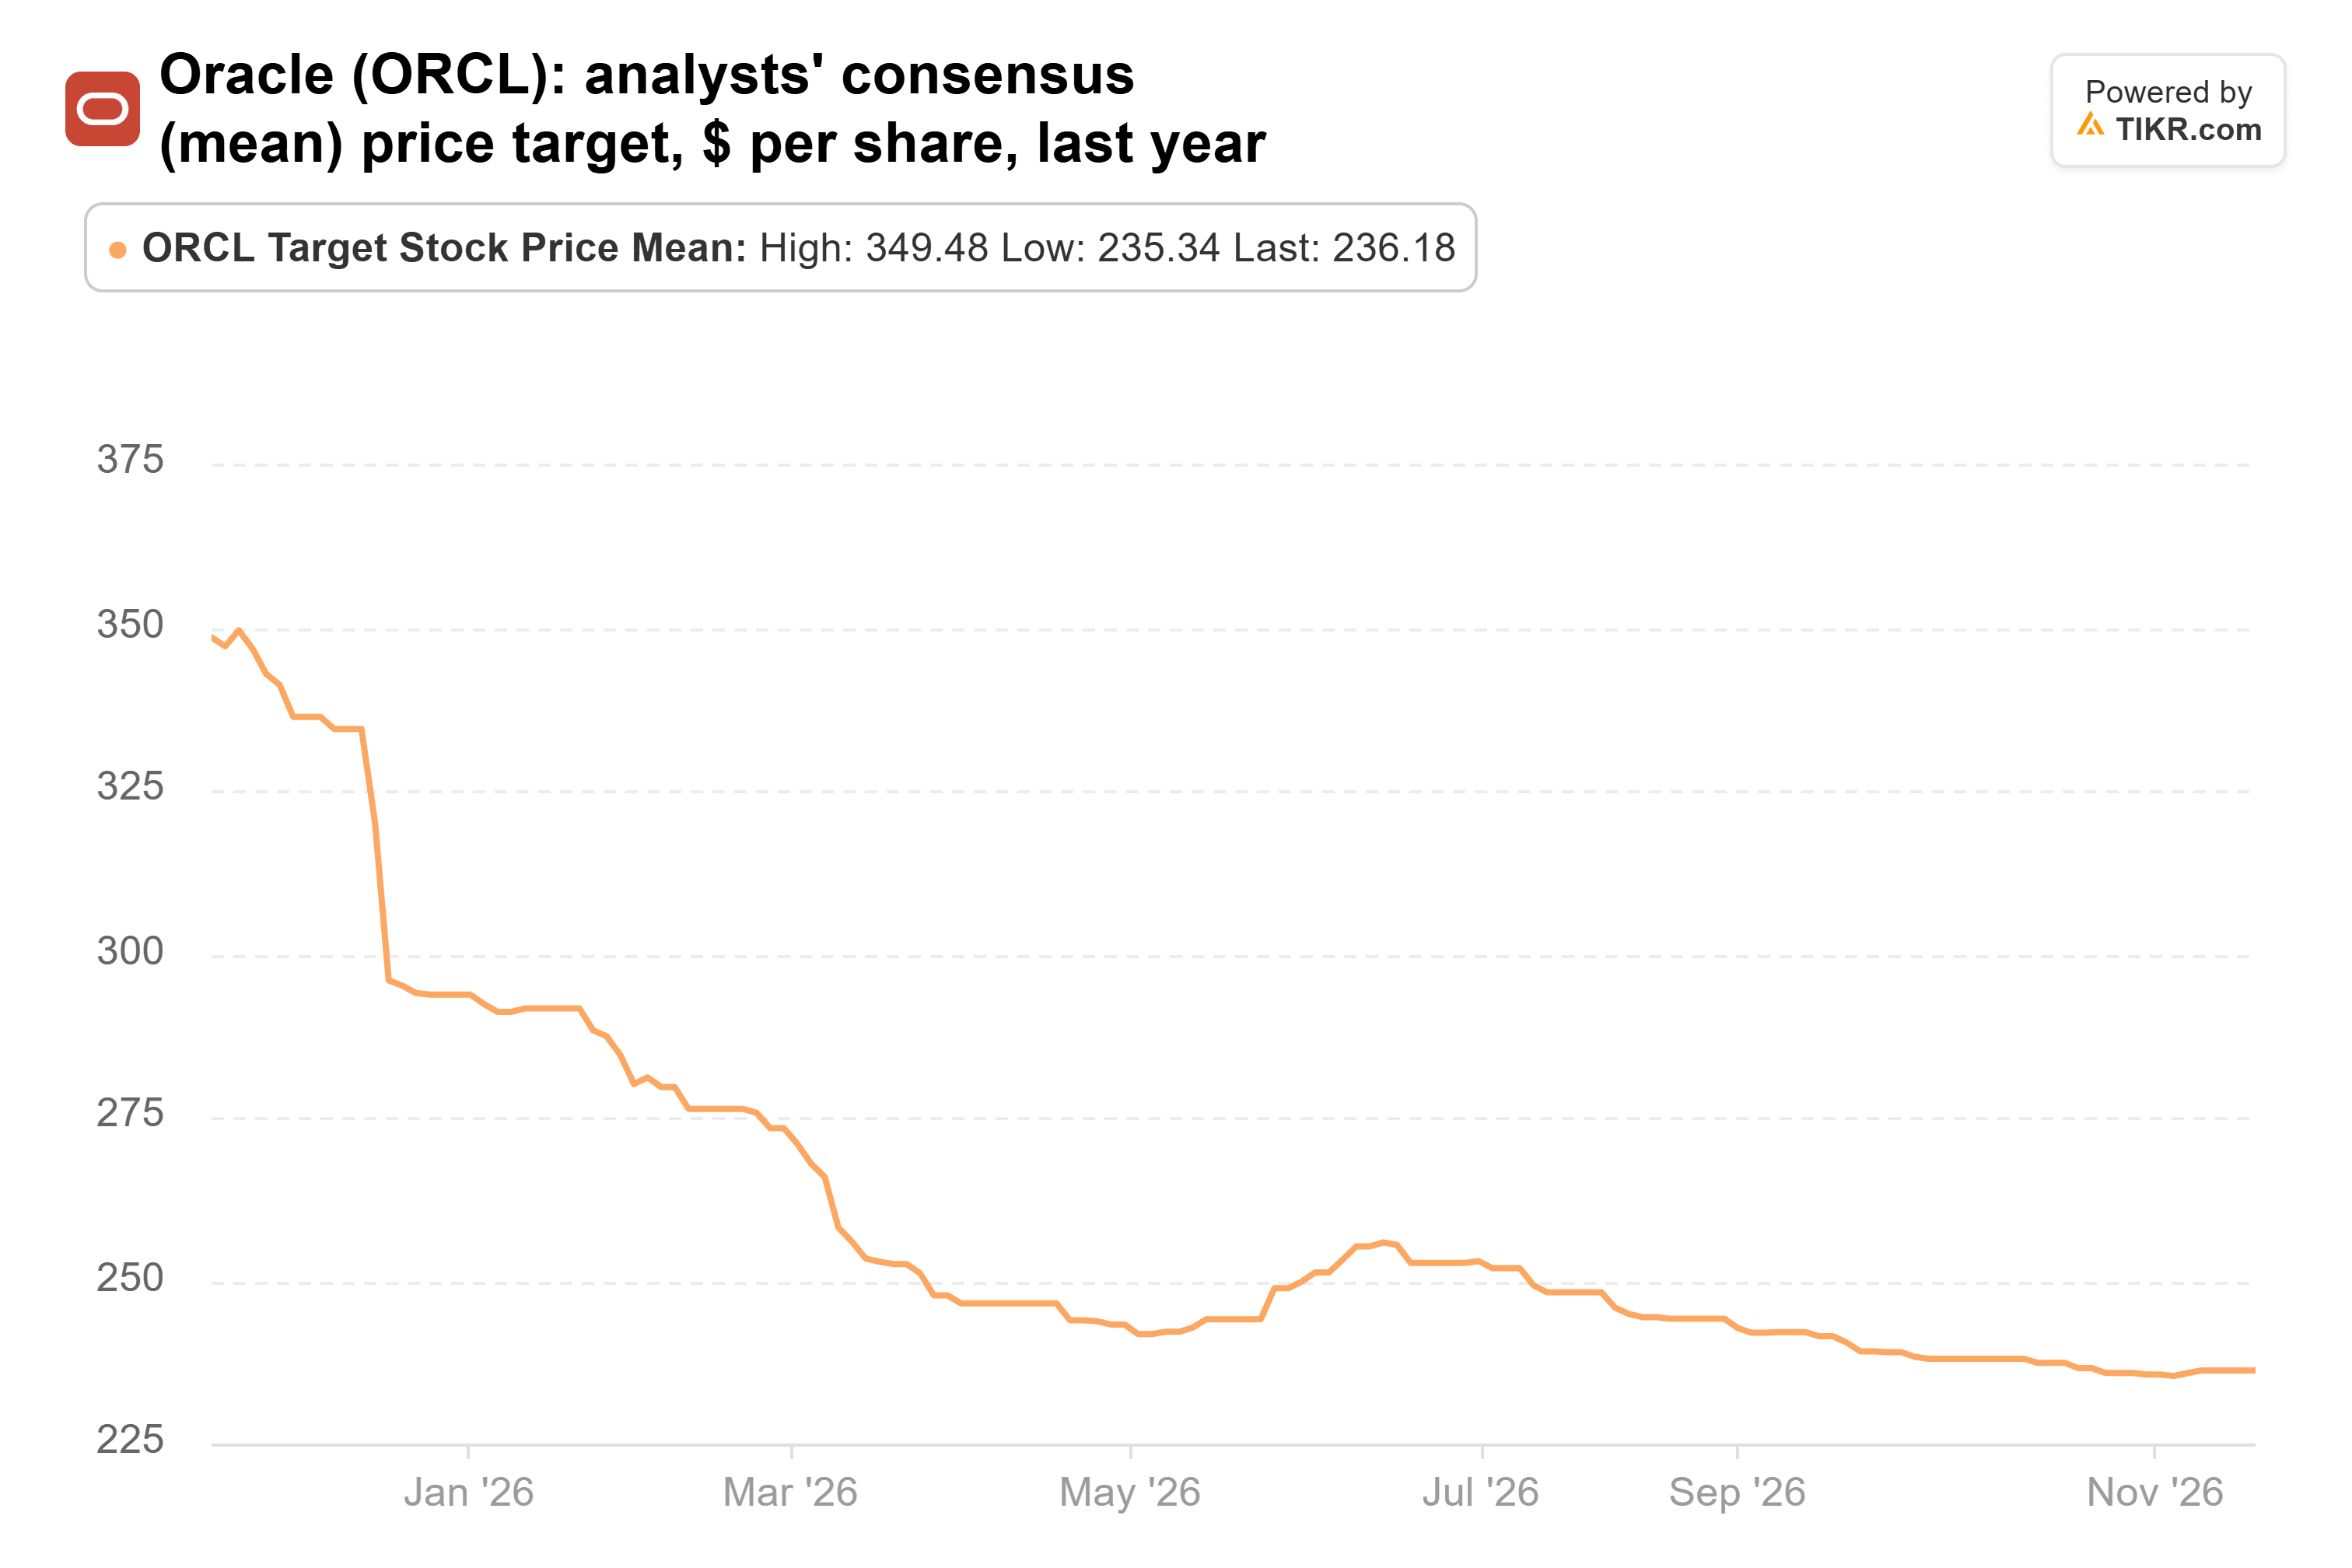
The lowest target, $110, is just below today’s price. On fiscal 2028 estimates, $236 is about 21x, right at Oracle’s five-year average. To get there, the estimates have to hold and the multiple has to climb back to its recent norm. Oracle reports again in mid-December.
4. SpaceX: the quarter’s big add
Appaloosa raised its SpaceX stake by 1,626% in the third quarter, to 3.88 million shares worth $557 million. That’s 7.4% of its 13F stocks and its No. 4 position. The stock is down just 1% since.
Third-quarter revenue rose 161% to $14.6 billion, and the AI cloud business, Super Intelligence, brought in more than half of it. One customer supplied 34.5% of the quarter’s revenue. The build-out also costs a lot: management expects $35 billion to $40 billion of capital spending in the fourth quarter alone.
Analysts have raised their average target from $114 when SpaceX listed in June to $258, which is 82% above today’s price:
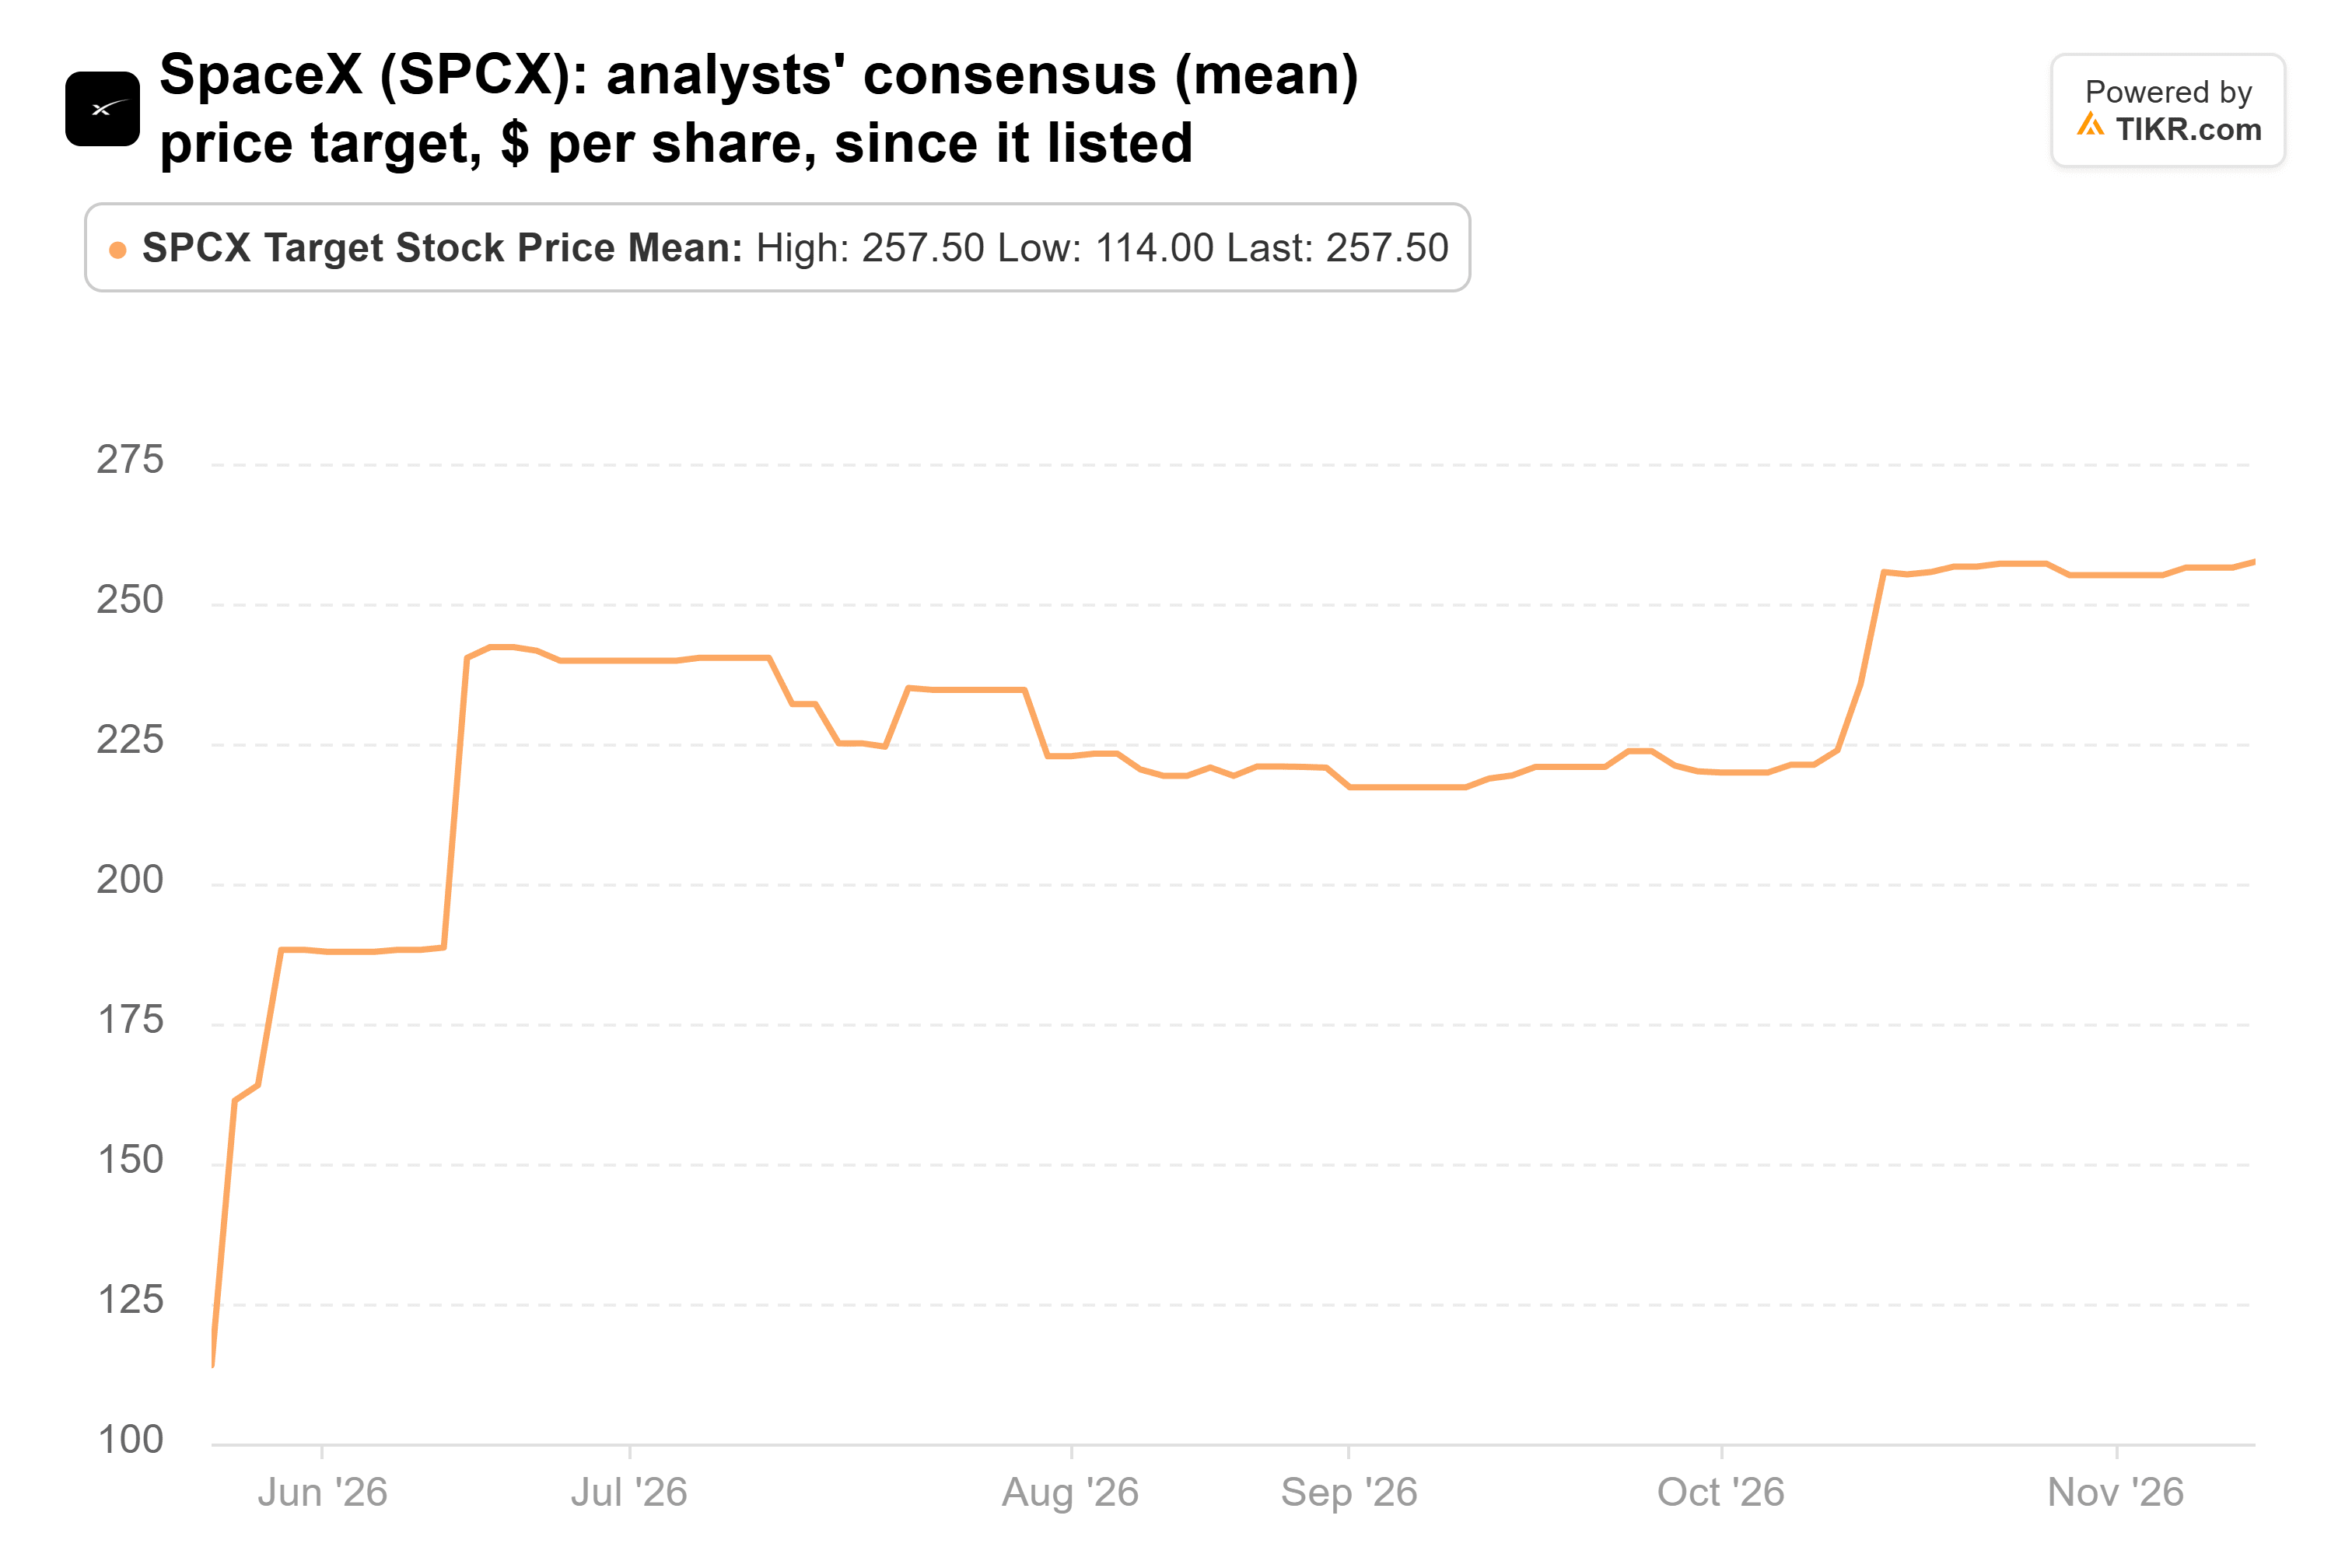
On Nov. 14, SpaceX caught Starship’s upper stage with its launch tower for the first time, and Citi then raised its target to $280 from $240. On 2028 estimates, $258 is about 43x, a touch below today’s 47x. So the target doesn’t need a higher multiple, only for the estimates to hold.
5. Lam Research: record sales and a $25 billion buyback
Appaloosa added 63% to its Lam Research stake in the third quarter, to 625,000 shares worth $205 million, or 2.7% of its 13F stocks. The stock is down 36% since Sept. 30 and 52% below its 52-week high.
The business hasn’t slowed down. Revenue hit a record $8.22 billion in the September quarter, up 54% from a year earlier. For the December quarter, Lam expects $8.6 billion, give or take $400 million, and management says supply-chain constraints held that figure back. After a brutal week for chip stocks, Lam answered with a $25 billion buyback, nearly a tenth of its market value.
Analysts’ average target has more than doubled over the past year to $362, which is 72% above today’s price:
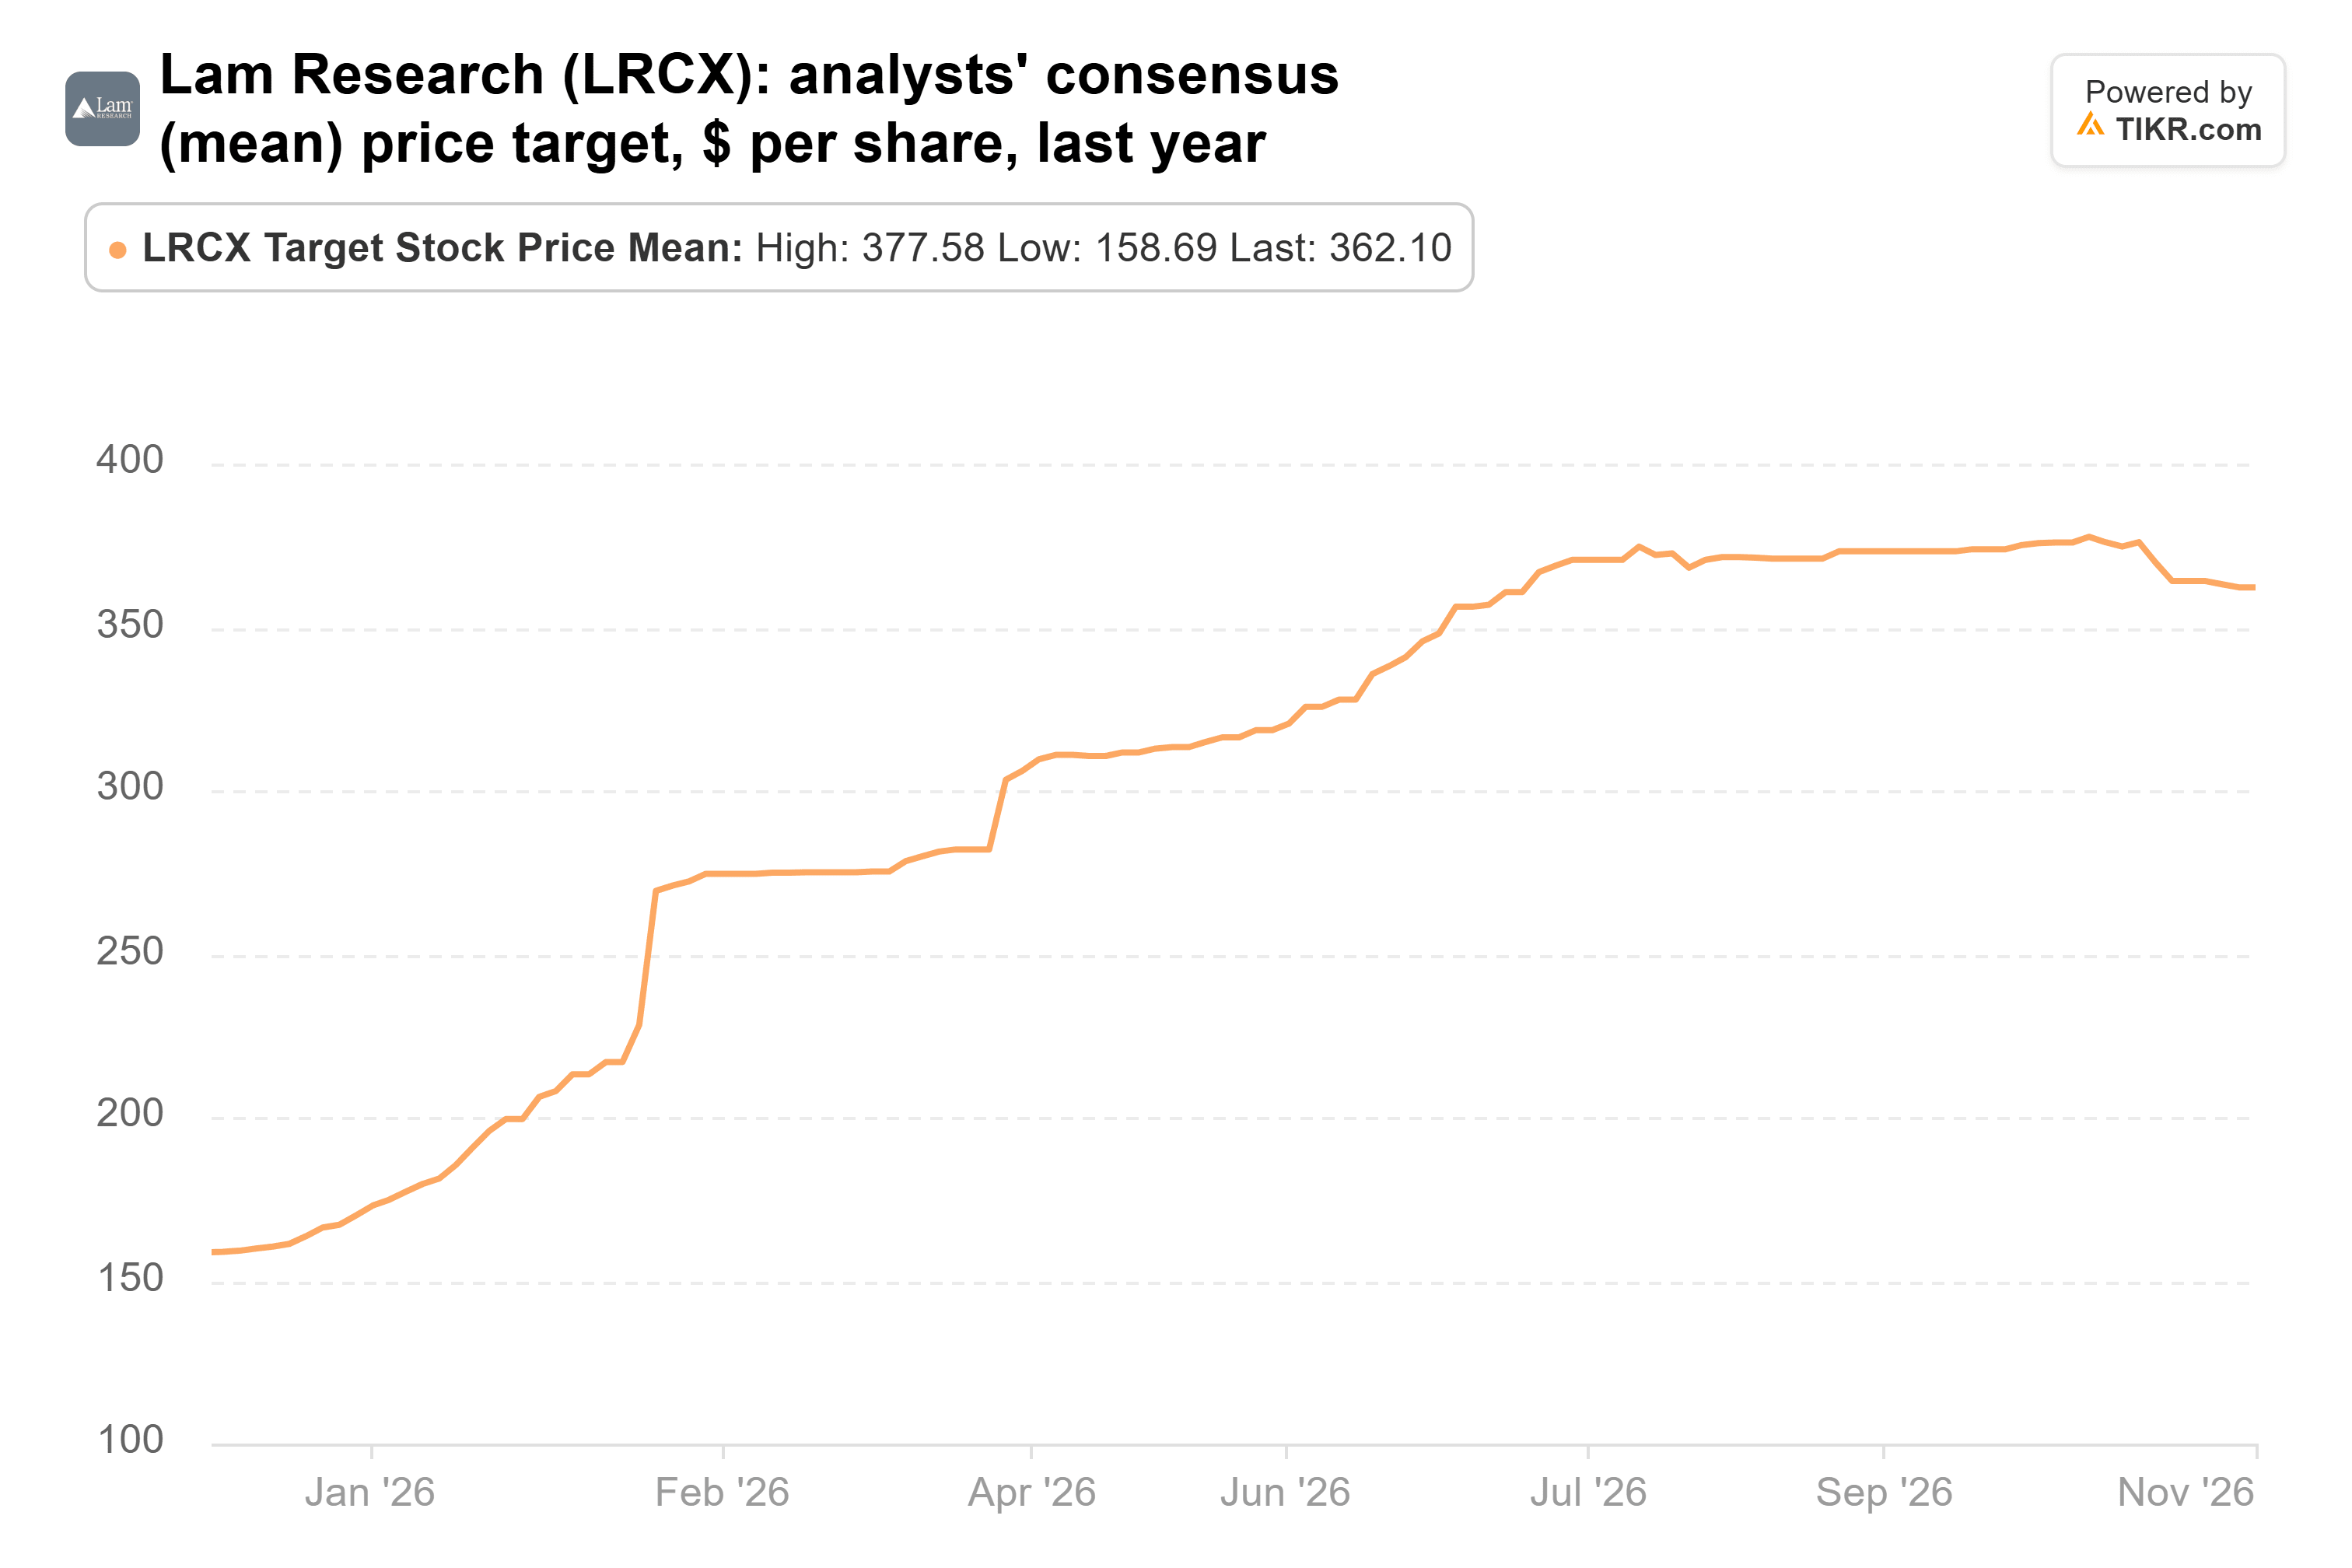
At about 20x forward earnings, Lam isn’t priced for a bust. Its next report, early next year, will show whether those supply constraints have eased.
Micron is the one I’d buy
If I could only buy one right now, it’d be Micron. It’s Tepper’s biggest bet, analysts keep raising their numbers, and Micron could reach their target without trading above its usual multiple.
The risk is the cycle. Micron last traded this cheaply in 2017 and 2018, right as the previous memory boom peaked. New fabs from Micron, its rivals and China’s CXMT also start producing in 2027 and 2028. Micron’s December report is the next test. Appaloosa’s next 13F, due in mid-February, will show whether Tepper is still holding on.
So what is Micron stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!