Key Takeaways
- Connectivity-Led Raise: Marvell lifted its fiscal 2028 revenue outlook to about $18 billion, and CEO Matt Murphy said connectivity, not the new Google agreement, was the largest driver of the $1.5 billion increase.
- Margins Holding Up: GAAP gross margin rose for five straight quarters to 53.1% in the quarter ended August 1, 2026, even as the lower-margin custom chip business started to ramp.
- Multiple Doing the Work: Marvell stock’s forward P/E roughly doubled from 23.7x in January to 48.0x on September 25, well above its 35.3x average since late 2023.
Marvell’s Raise Came From Connectivity, Not Google
At the Citi Global TMT Conference lunch on September 9, analyst Atif Malik introduced Matt Murphy by repeating Jensen Huang’s line that Marvell could be the next trillion-dollar company. Murphy’s reply: “That quieted the room.” Then he spent much of the conversation on optics, switches, and signal processors.
That focus is worth noticing. The headline of Marvell’s summer was the Google agreement signed on July 29 and disclosed on August 19, which gave Google a warrant for up to 58,970,907 shares at $206.58 each and covers custom programs Morgan Stanley ties to as much as $120 billion of cumulative revenue through fiscal 2033.
But on the Q2 2027 earnings call, Murphy said revenue from the warrant programs through fiscal 2028 was already inside the custom target Marvell had given before. The big Google contribution begins in fiscal 2029.
So the jump in fiscal 2028 guidance, from $16.5 billion to about $18 billion, came from somewhere else. Murphy called connectivity “probably the largest driver net-net,” pointing to 1.6T optical signal processors, scale-out switching that is on track to more than double this year, and scale-up optics that he said are now much larger than the roughly $300 million he outlined a quarter earlier.
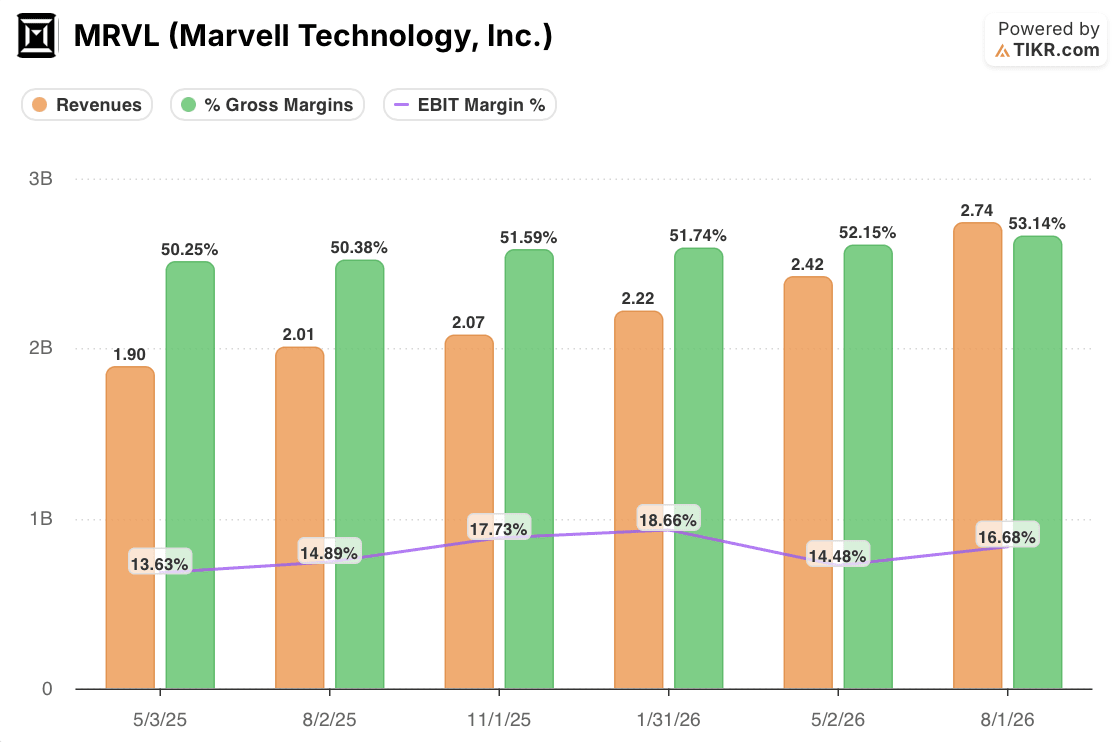
The quarterly numbers fit that account. Revenue climbed from $1.90 billion in the quarter ended May 3, 2025, to $2.74 billion in the quarter ended August 1, 2026, and year-over-year growth sped up from 27% to 37% between the last two quarters. GAAP gross margin rose from 50.4% a year earlier to 53.1%, consistent with high-margin merchant products leading the growth.
The margin story has a catch. Custom chips carry lower gross margins, and third-quarter guidance calls for non-GAAP gross margin of 57.5% to 58.5%, down from 58.9%, as that business ramps. Management still expects fiscal 2028 gross margin to stay in that range while custom revenue more than doubles, which only works if connectivity keeps growing alongside it.
Marvell Stock Is Paying Up for the Part of the Story That Hasn’t Arrived
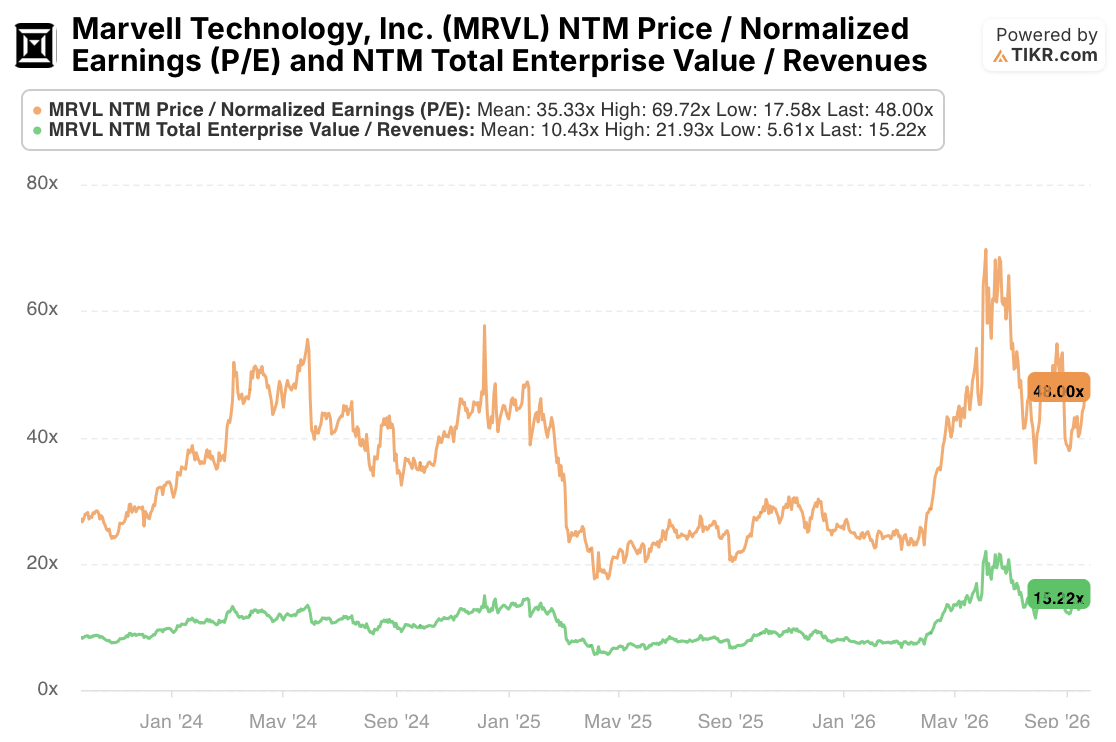
Marvell’s forward P/E went from 23.66x on January 31 to 48.00x on September 25, and forward EV-to-sales went from 7.30x to 15.22x. Earnings estimates rose over that stretch, but the multiple rose faster.
The last two months tell the story. The forward P/E was 41.24x on August 1, before the Google warrant became public and before the fiscal 2028 raise. It is now 48.00x, even as forward estimates rose with that raise. The timing lines up with the Google headlines, though it doesn’t prove that the warrant caused the rerating.
That leaves a split verdict. The business Marvell is reporting today runs on connectivity, and the revenue and margin data back that up. The premium on the stock is leaning more on the custom opportunity for fiscal 2029 and beyond, which management has not yet sized. At 48.0x, the stock trades well above its 35.3x average, though below the 69.7x it reached earlier this year, and the September 14 AI selloff, when Marvell fell 5.5% premarket, showed how quickly sentiment can shift.
The October 6 Investor Day is the next test. Marvell has pointed to more than $10 billion of custom revenue in fiscal 2029 and promised a range of outcomes that include the Google programs. A base case clearly above that level, together with fourth-quarter gross margin that holds within the 57.5% to 58.5% guide, would give the current multiple support. A range that mostly restates the old target would leave connectivity carrying a valuation built for more.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!