Key Takeaways
- Micron stock is up 208% in 2026 through Friday’s close. Its quarterly revenue more than doubled over the same stretch, from $23.86 billion in its fiscal second quarter to $54.23 billion in its fiscal fourth.
- The stock is 30% below its June high after selloffs driven by worries about AI spending and China’s CXMT, but analysts kept raising their earnings estimates.
- Micron says its 26 multiyear take-or-pay customer deals cover over 35% of its revenue through 2030, which makes this memory boom look sturdier than past ones.
- At 5x forward earnings, the stock looks like a buy. Fiscal first-quarter results in mid-December, against a $61.5 billion revenue guide, are the next test.
Micron Technology (MU) stock is up 208% in 2026 (through Friday’s close). It’s also 30% below the 52-week high it hit in June.
So is it time to take profits, or buy more?
Sales grew even faster than the stock
Micron’s run came from three quarterly reports in a row, each bigger than the last, as AI demand ran into a memory shortage:
- Fiscal second quarter (reported March 18): $23.86 billion of revenue
- Fiscal third quarter (June 24): $41.46 billion, at an 84.6% gross margin
- Fiscal fourth quarter (Sept. 30): $54.23 billion, up from $11.32 billion a year earlier
Here’s Micron’s revenue over the five years before…

…and fiscal 2026, the year ended Sept. 3, came in at $133.19 billion, against $37.38 billion in fiscal 2025.
TIKR tracks 49 analysts on Micron. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Micron, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Micron’s Analyst Ratings
Then the market got nervous
The stock closed at a record the day after the June report. Then fears that AI spending couldn’t last knocked it down more than 40% before it turned higher in August.
October brought a second leg down. Over the weekend of Oct. 10, China’s CXMT said it aims to launch server memory on a denser DRAM design by the end of 2026. Server memory sits inside Micron’s richest business: its core data center unit brought in $18.0 billion last quarter at a 90% gross margin.
Tesla CEO Elon Musk said on X that if China ramps its LP5 and LP6 memory as fast as other products it has ramped, “then 2028 will be a different story.”
Then came worries about how AI spending gets financed. On Thursday, a disappointing outlook from Lam Research and Tesla’s cut to its 2026 spending plan sent chip stocks lower again. Micron fell 6.3% that day, then won back 2.5% on Friday.
Through all of it, analysts kept raising their numbers…
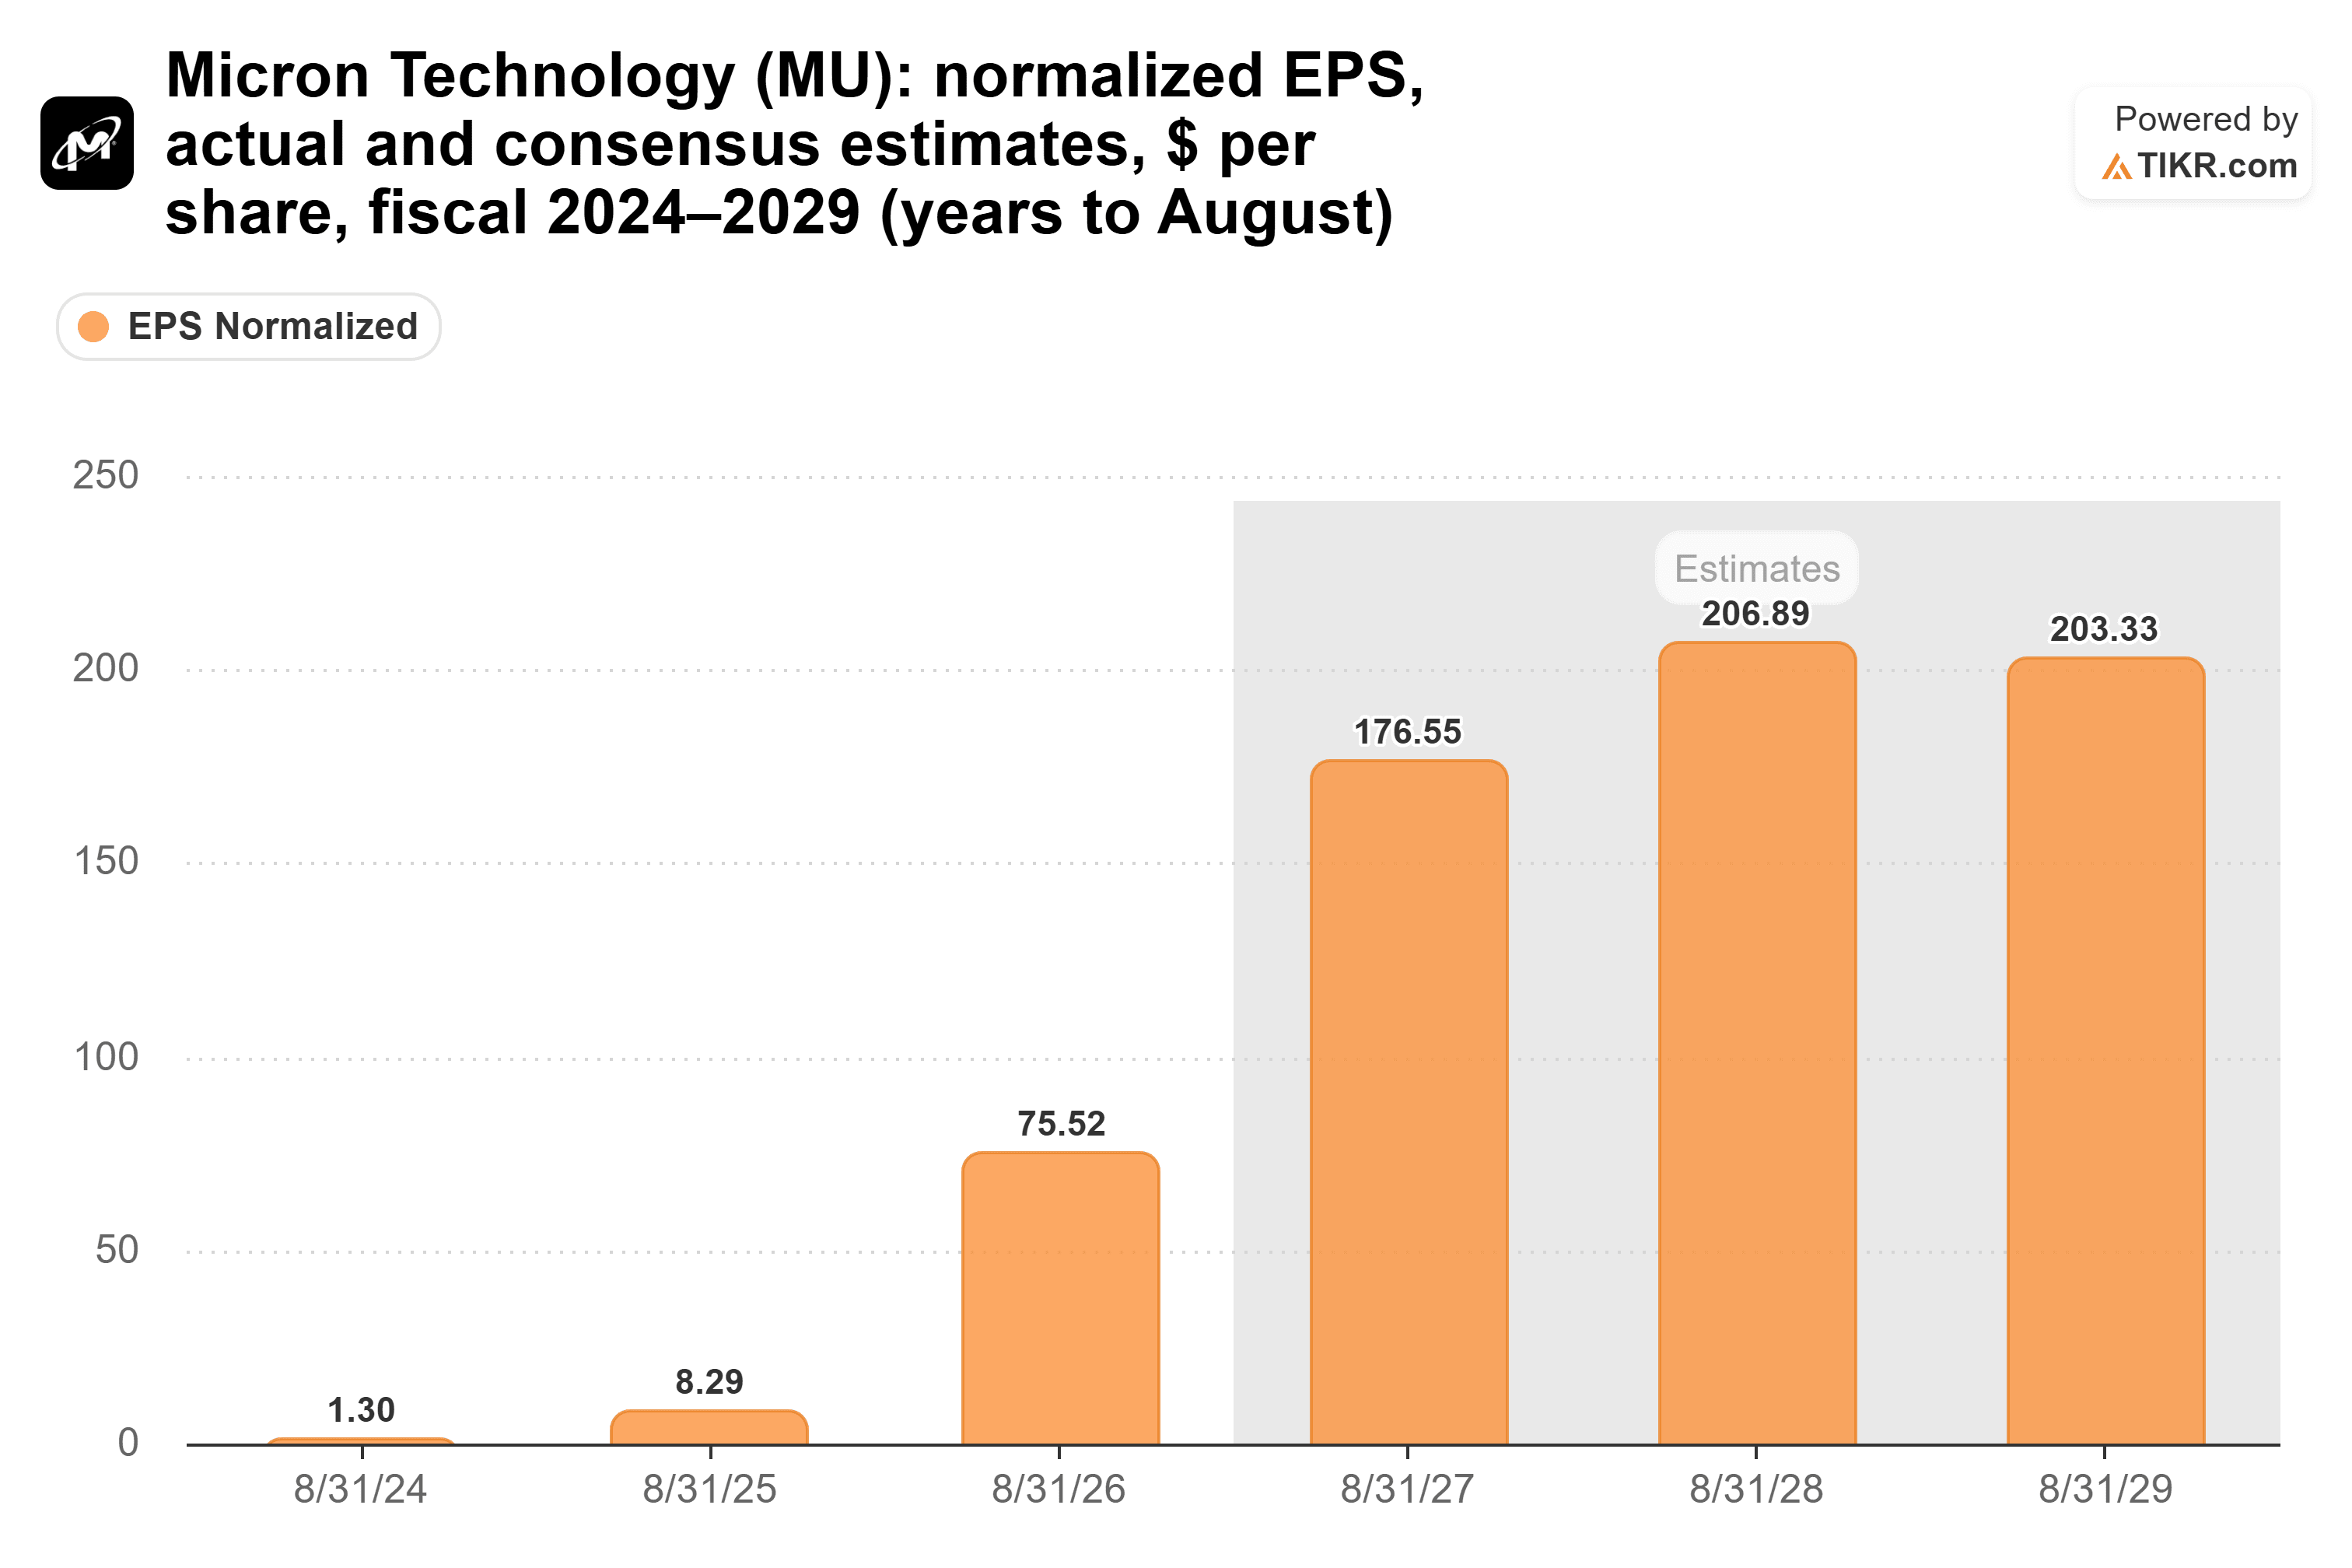
The fiscal 2027 consensus is now $176.55 a share, up from $156.52 in mid-September.
The deals behind “durability”
Memory prices swing hard, and so do Micron’s margins: its GAAP gross margin was negative 9.1% in fiscal 2023 and 80.7% in fiscal 2026.
Management says this boom is built to last longer. With the June results, Micron announced multiyear Strategic Customer Agreements, and CEO Sanjay Mehrotra said: “We believe our multi-year Strategic Customer Agreements will significantly enhance the durability and predictability of Micron’s strong financial performance.”
On the fourth-quarter call, Micron estimated that its 26 multiyear take-or-pay deals represent over 35% of its revenue through 2030. Three-quarters of that revenue comes with a defined pricing framework, mostly floor and ceiling prices. The rest is priced periodically against the market. Even at the floors, CFO Mark Murphy said, Micron expects “margins meaningfully above any prior cycle peak margins.”
Buy more at 5x
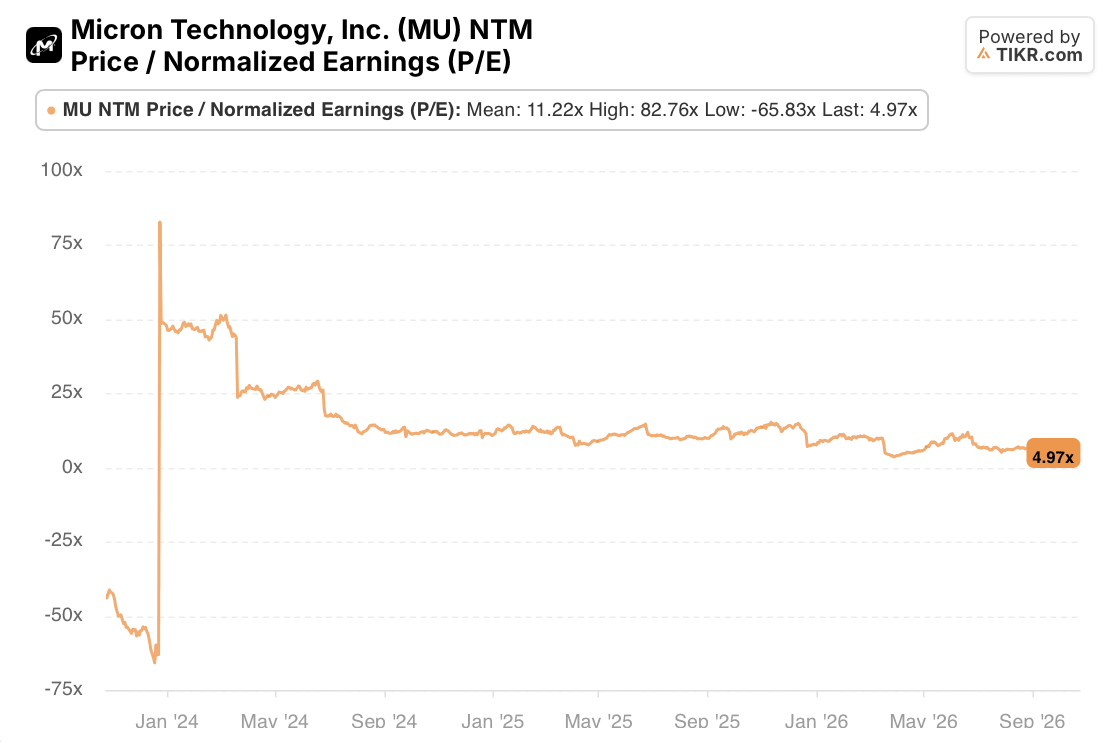
Yet Micron trades at 4.97x forward earnings, less than half its three-year average of 11.22x. That’s the kind of multiple the market gives profits it expects to collapse…
The 49 analysts TIKR tracks have a $1,561 consensus target, 78% above Friday’s close.
The risk is the memory cycle itself: a fast ramp at CXMT or anyone else would pull prices and margins down. Micron’s new quarterly employee bonus tied to profits adds a cost, too.
My take is plain and straightforward; it’s to buy more. At 5x earnings, the price already assumes the boom ends soon. With more than a third of revenue locked in through 2030, a sudden bust is less likely than in past cycles.
The next test is fiscal first-quarter results in mid-December, against guidance of $61.5 billion in revenue and $38.15 of adjusted EPS. Micron’s $35.16 billion buyback authorization kicks in on Dec. 9. Of course, if CXMT’s server memory ships on schedule and ramps fast, 2028 could look very different.
So what is Micron stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Micron could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!