


Key Takeaways
- Dell Technologies stock rose 1.5% to $462 as AI hardware names bounced back from an October rout.
- Dell booked a record $60.9 billion of AI server orders in fiscal Q2 and holds a $95 billion backlog.
- Gross margin sits at 19.9% because AI servers carry thin profit, so converting backlog profitably is the real test.
- Fiscal Q3 results, expected December 3, will show how much of the $74 billion AI server target is shipping on schedule.
Dell Technologies (DELL) stock is up 1.5% today after AI hardware names bounced back from an October rout. Shares now sit at $462, yet remain about 22.5% below their 52-week high of $596.
The demand story is settled. But profit is the open question.
The backlog is the story
In fiscal Q2, revenue jumped 58% to a record $47.0 billion. Adjusted earnings per share (profit per share minus one-time items) hit $7.04, beating estimates.
Three numbers stand out:
- $60.9 billion of AI server orders, a record
- A $95 billion backlog, meaning orders not yet shipped
- A $25 billion raise in full-year revenue guidance, to $192 billion
That puts growth near 70%, and the step up is clear in the forecasts…
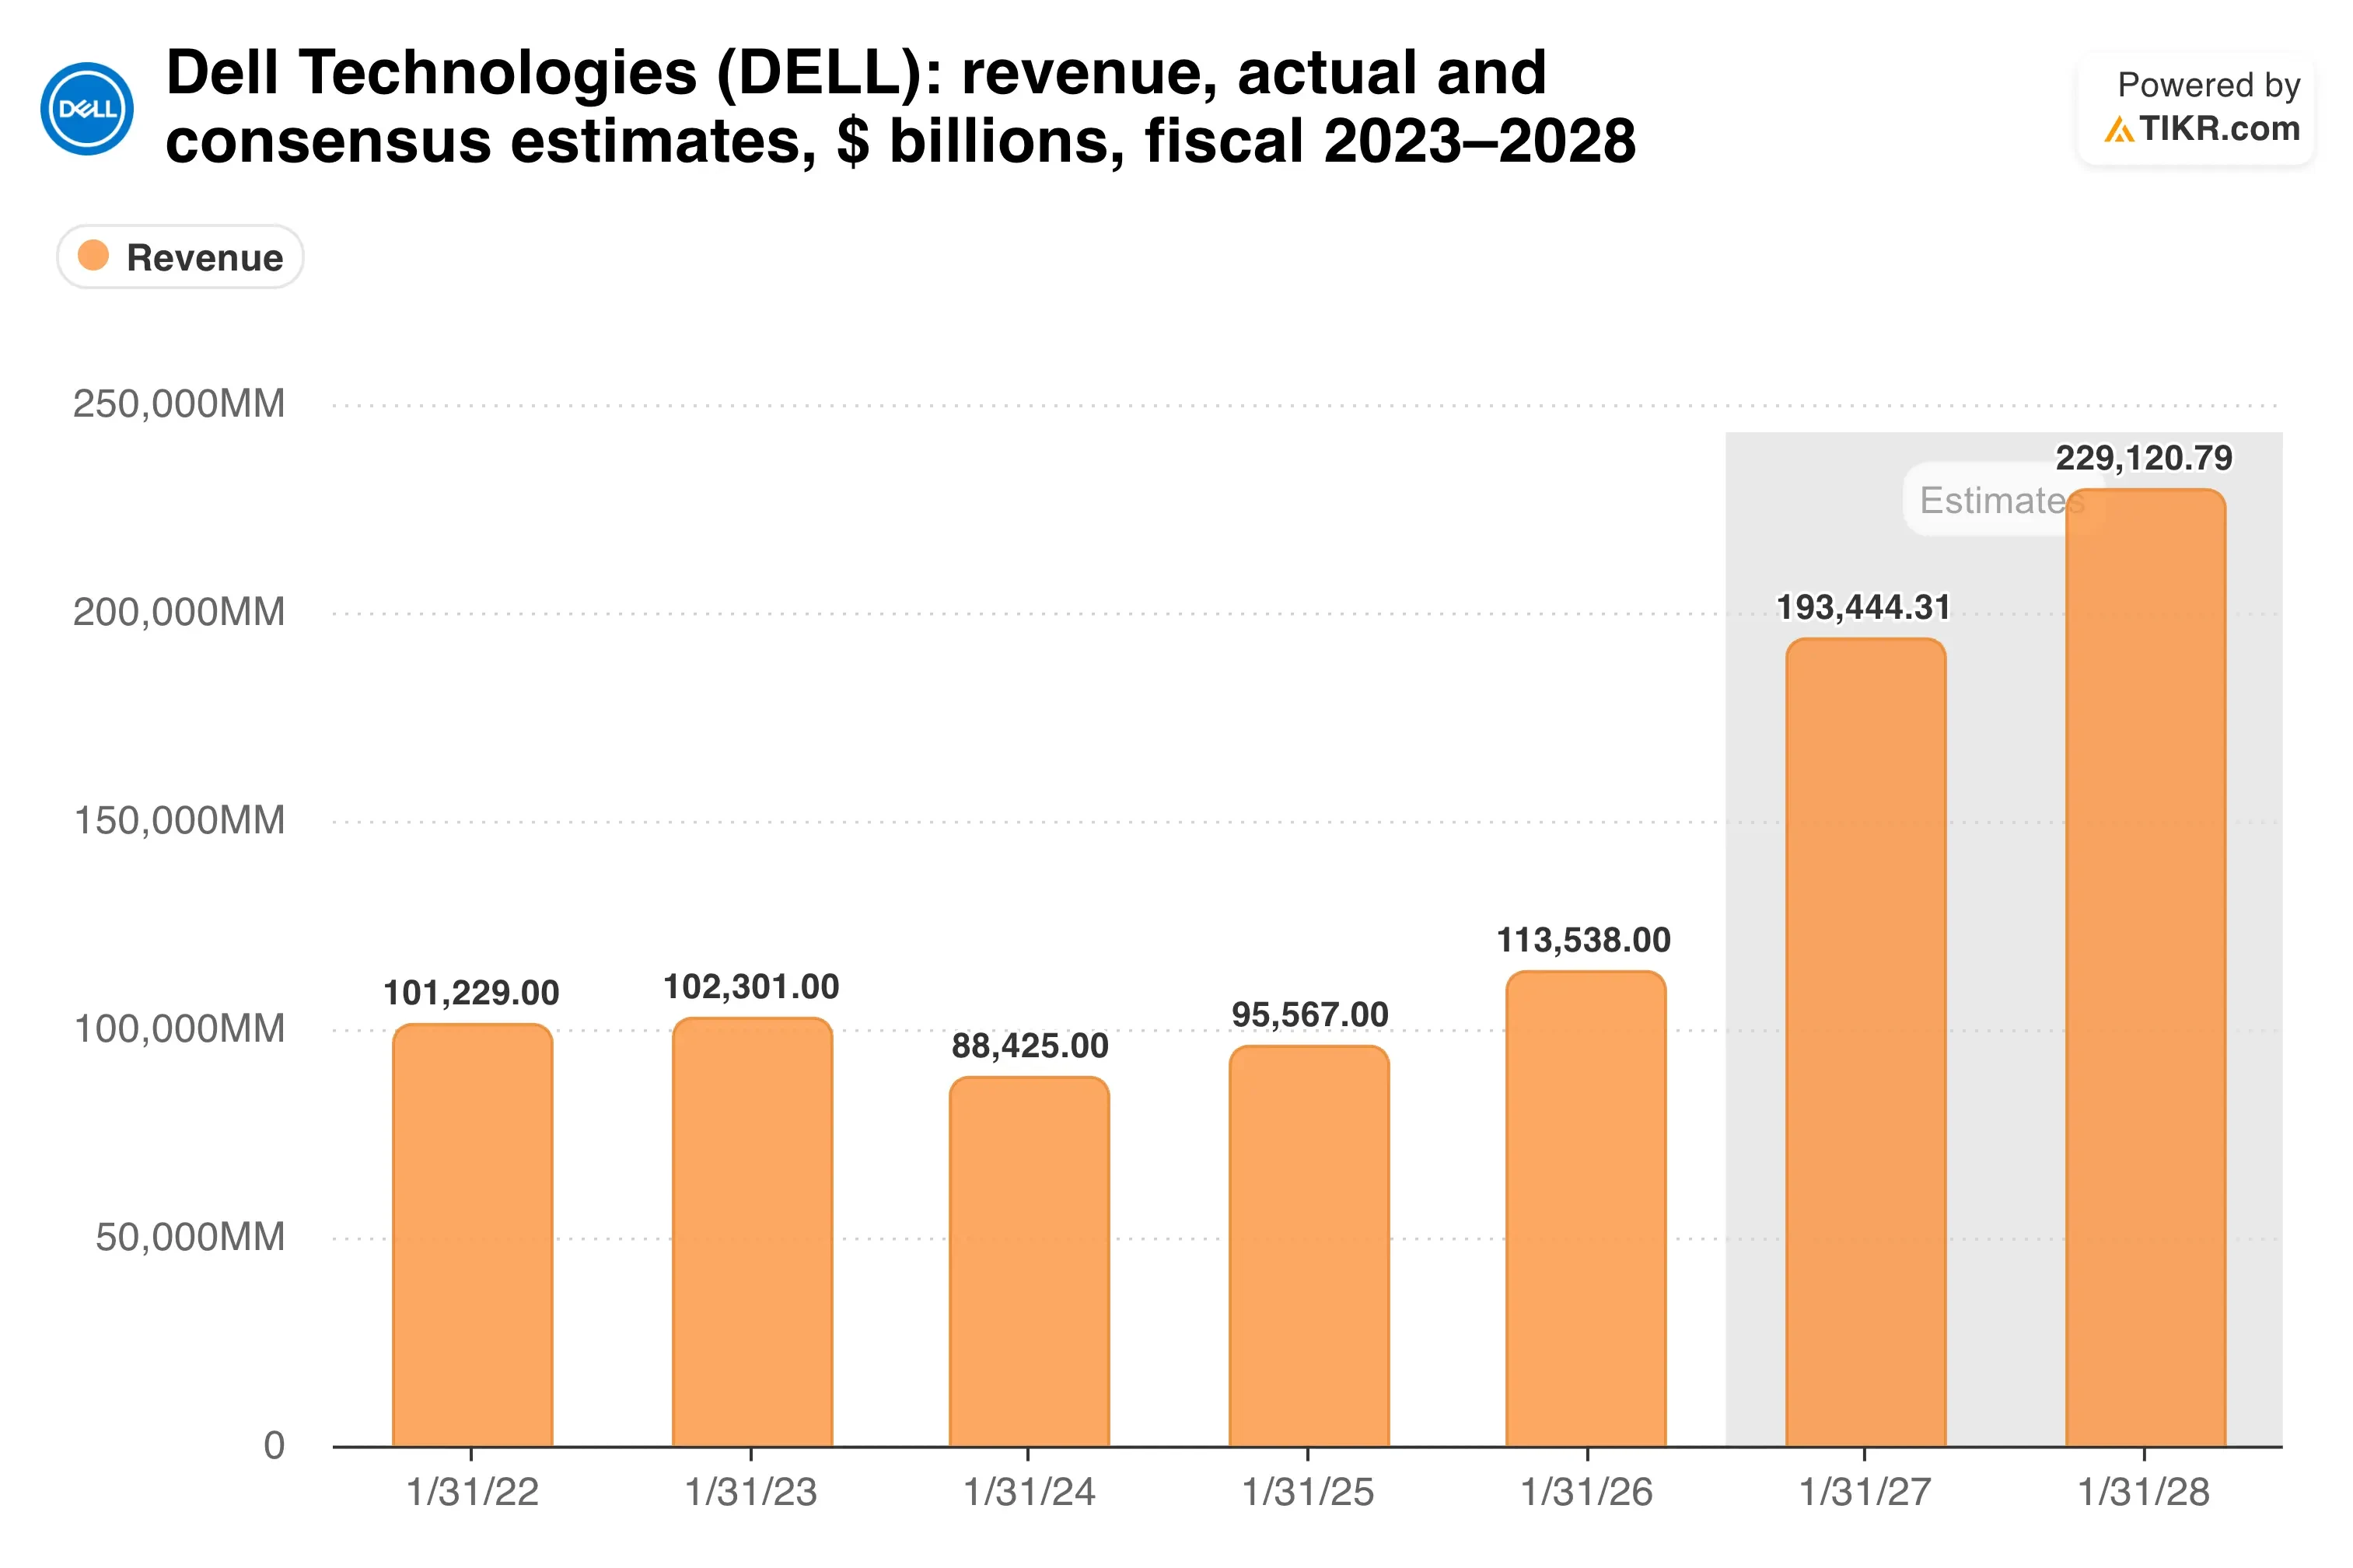
Analysts expect about 42% annual revenue growth over the next two years. Adjusted EPS guidance rose to $25.50, so profit is keeping pace.
Dell is widening its customer base
Dell now expects $74 billion of AI server revenue this year, up from $60 billion. That has reshaped the company’s sales mix…

Servers now drive growth, while PCs play a supporting role. AI servers brought in $16.4 billion in fiscal Q2 alone.
In Japan, Dell signed a preliminary agreement with JERA and RHAELM for an AI data center at JERA’s Chiba power plant. It targets up to 400 megawatts and over $15 billion of spending, with operations around 2028.
Meanwhile, Accenture is forming a dedicated Dell business group and training over 3,000 staff on Dell’s products. However, neither deal came with financial details.
Thin margins are the price
AI servers bring big revenue but thin profit, because Nvidia’s chips eat much of the price. That shows up in Dell’s margins…
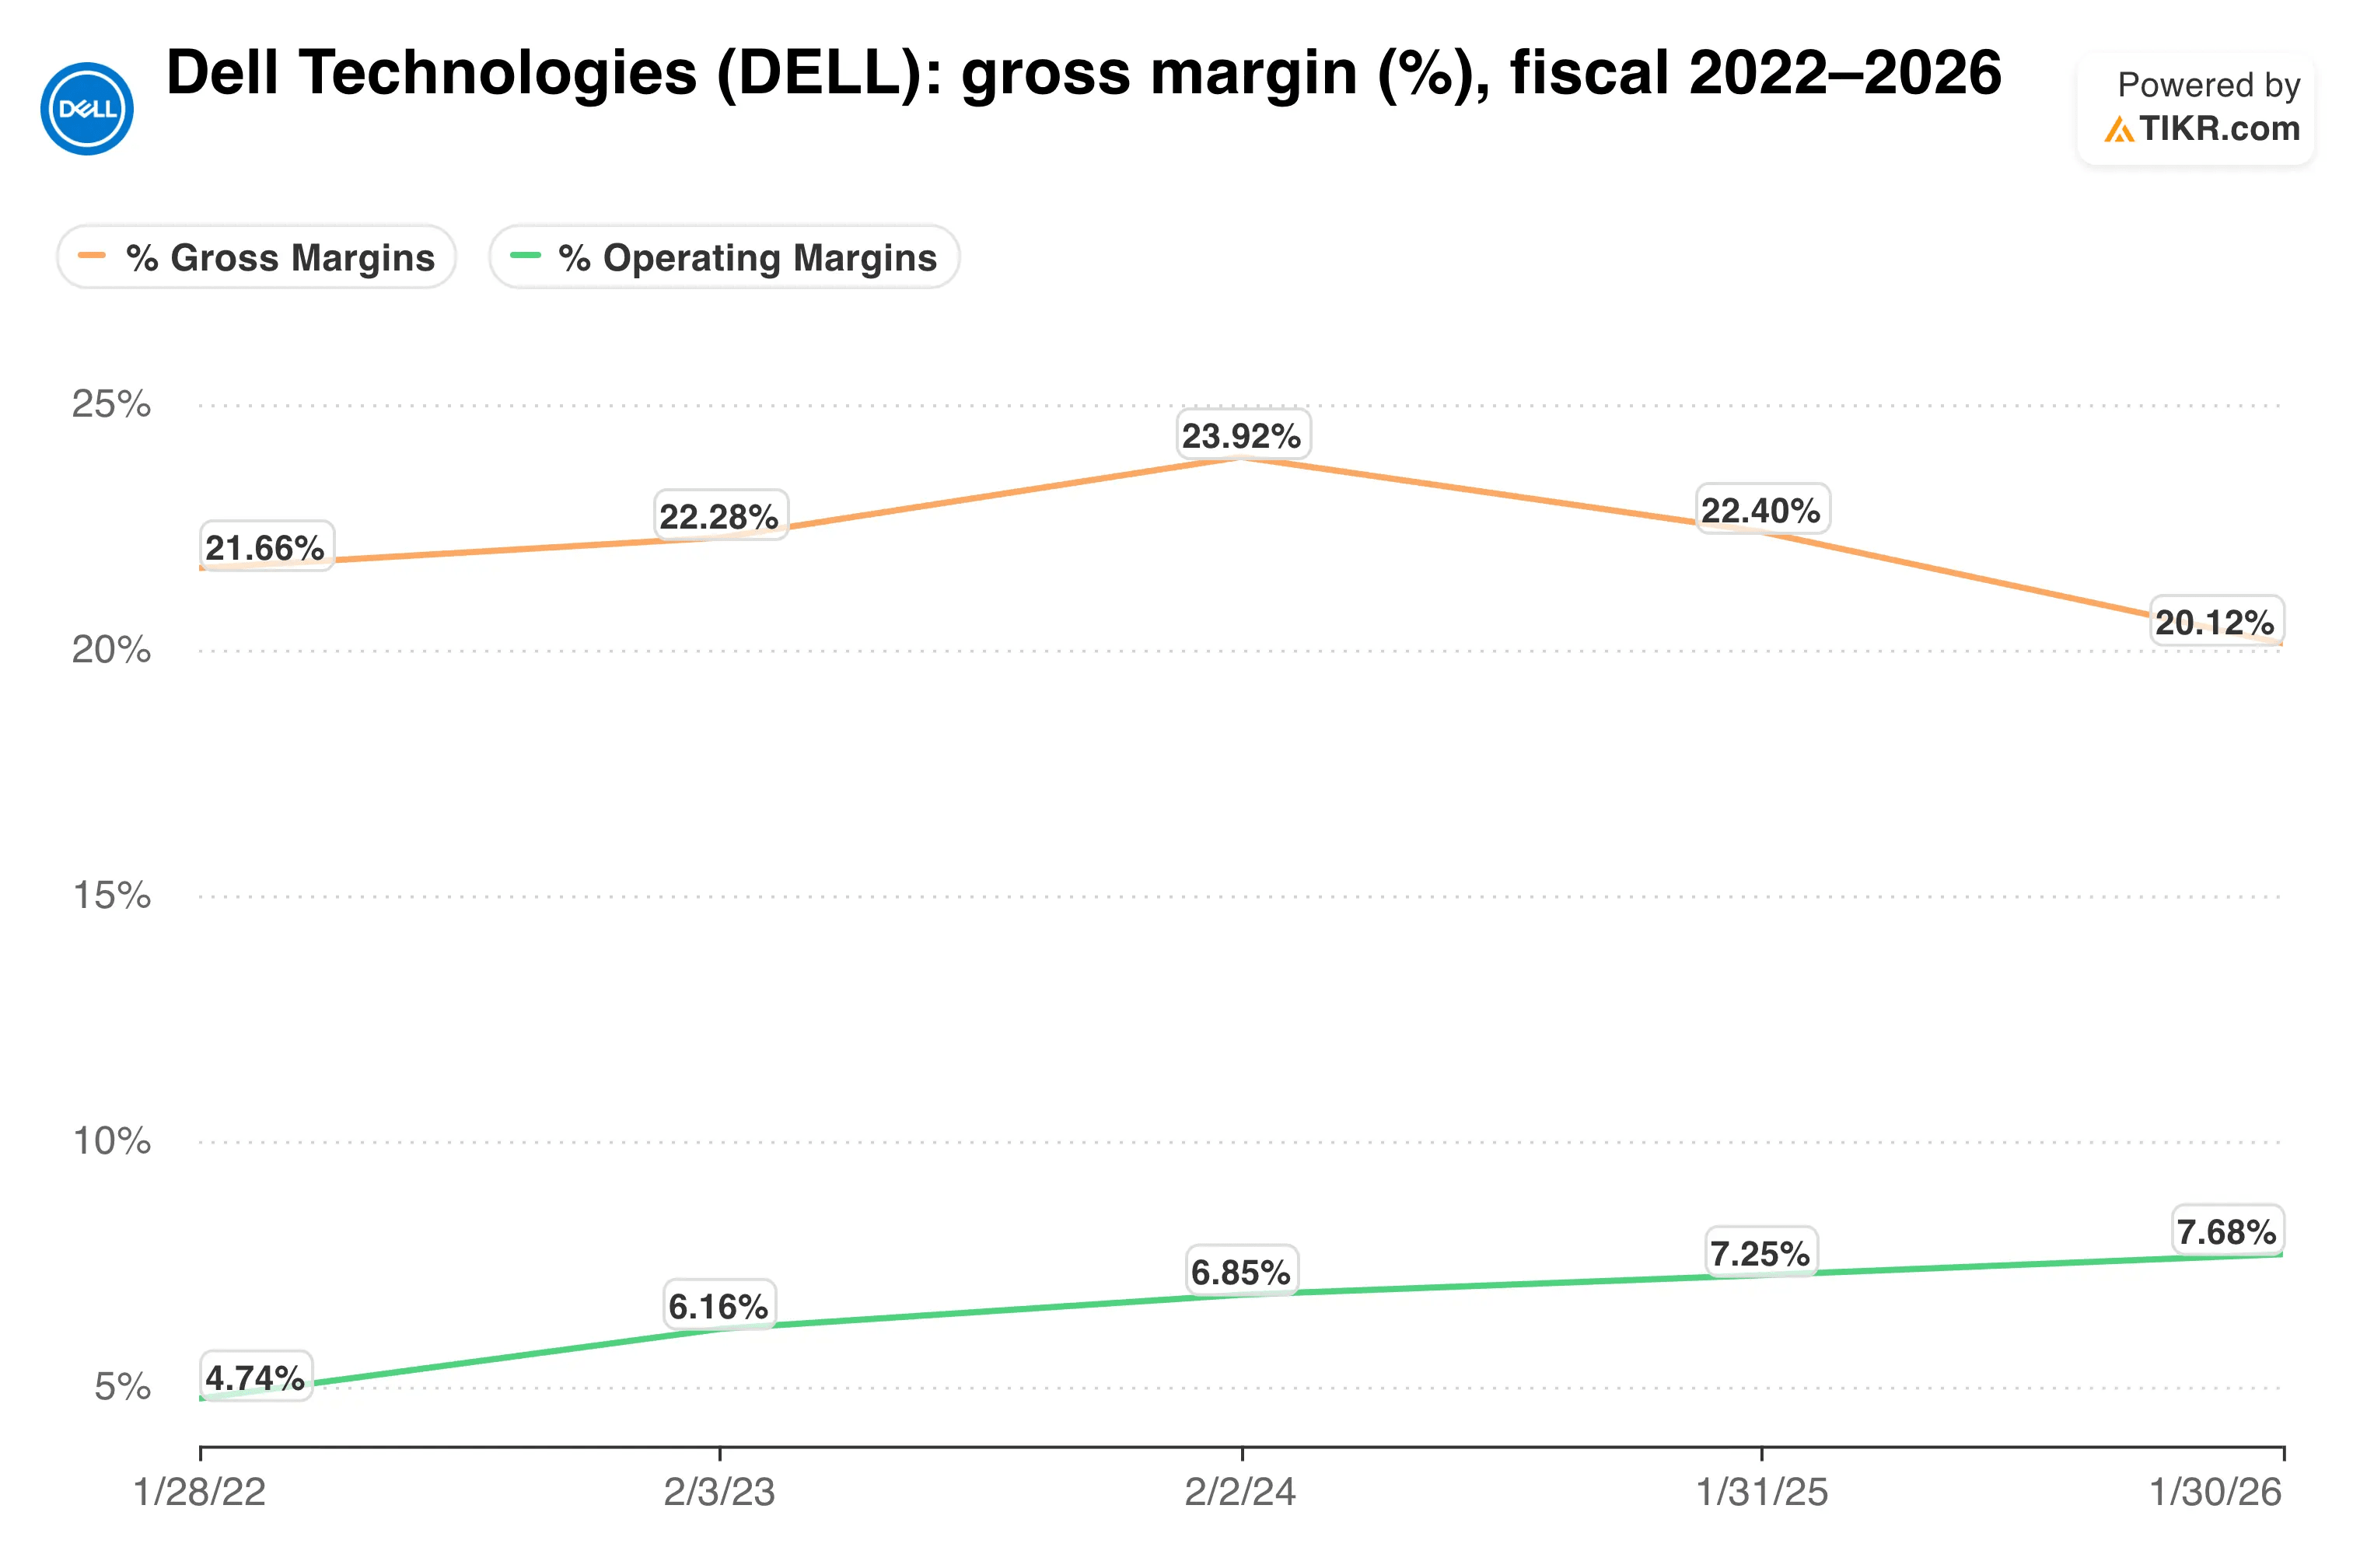
Gross margin sits at 19.9%, and operating margin is 9.9%. Dell earns more dollars, but fewer cents on each one.
Still, shares trade at just 16.4x forward earnings, and the $593 average analyst target implies 28% upside.
My take: I think demand is proven. But a $95 billion backlog only pays off if supply and pricing hold, so margins matter more than orders now.
Dell’s fiscal third quarter report, expected December 3, will show how much of that $74 billion target is shipping on schedule.
TIKR tracks 29 analysts on Dell Technologies. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Dell Technologies, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Dell Technologies’ Analyst Ratings
So what is Dell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Dell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


