Key Takeaways
- AppLovin stock fell 12.6% in the month through October 19, as advertising-growth concerns, litigation, and analyst price-target cuts weighed on investor sentiment.
- Seven investment firms reduced their price targets between October 8 and October 19, although five maintained Buy-equivalent ratings.
- APP recently traded at around 14x forward earnings, significantly below its five-year average, while consensus estimates still suggest substantial earnings growth.
- The November 4 earnings report could determine whether AppLovin’s valuation discount presents a buying opportunity or reflects deeper business challenges.
AppLovin (APP) stock fell 12.6% in the month through October 19, compared with a 0.6% gain for the S&P 500.
Concerns about AI-model improvements, litigation, and analyst target reductions have weighed on sentiment.
Yet earnings expectations have held up considerably better than the stock price, raising an important question: Has the market already priced in too much bad news?
What’s Driving AppLovin Stock Lower?
AppLovin reported second-quarter revenue of $1.924 billion, up 53% year over year but slightly below analysts’ expectations of $1.94 billion.
CEO Adam Foroughi acknowledged weaker-than-usual improvements in the company’s AI-driven advertising models during the quarter.
Meanwhile, AppLovin faced securities class-action allegations involving its AI technology and an ongoing legal dispute with Unity Software (U).
For comparison, Unity reported second-quarter revenue of $546 million, up 24% year over year. AppLovin’s 53% revenue growth was considerably faster, although the companies’ business mixes differ.
That growth advantage matters, but investors are increasingly concerned about whether AppLovin can sustain its momentum.
Wall Street Is Cutting AppLovin’s Price Targets
Seven major investment firms reduced their AppLovin price targets between October 8 and October 19.
Jefferies lowered its target from $550 to $375, while Citi reduced its target from $600 to $500.
However, five maintained Buy-equivalent ratings, suggesting analysts remain cautiously optimistic despite near-term uncertainty.

According to TIKR data, AppLovin’s average analyst price target declined from approximately $744 in January to around $477.
The consensus target nevertheless remained substantially above the October 19 closing price of $269.12, suggesting Wall Street still sees meaningful potential upside.
AppLovin’s Earnings Outlook Remains Strong
Despite the selloff, analysts have not reduced earnings expectations nearly as aggressively.
TIKR consensus estimates project normalized earnings per share rising from $10.64 in 2025 to approximately $21 by 2027, representing nearly 93% cumulative growth.
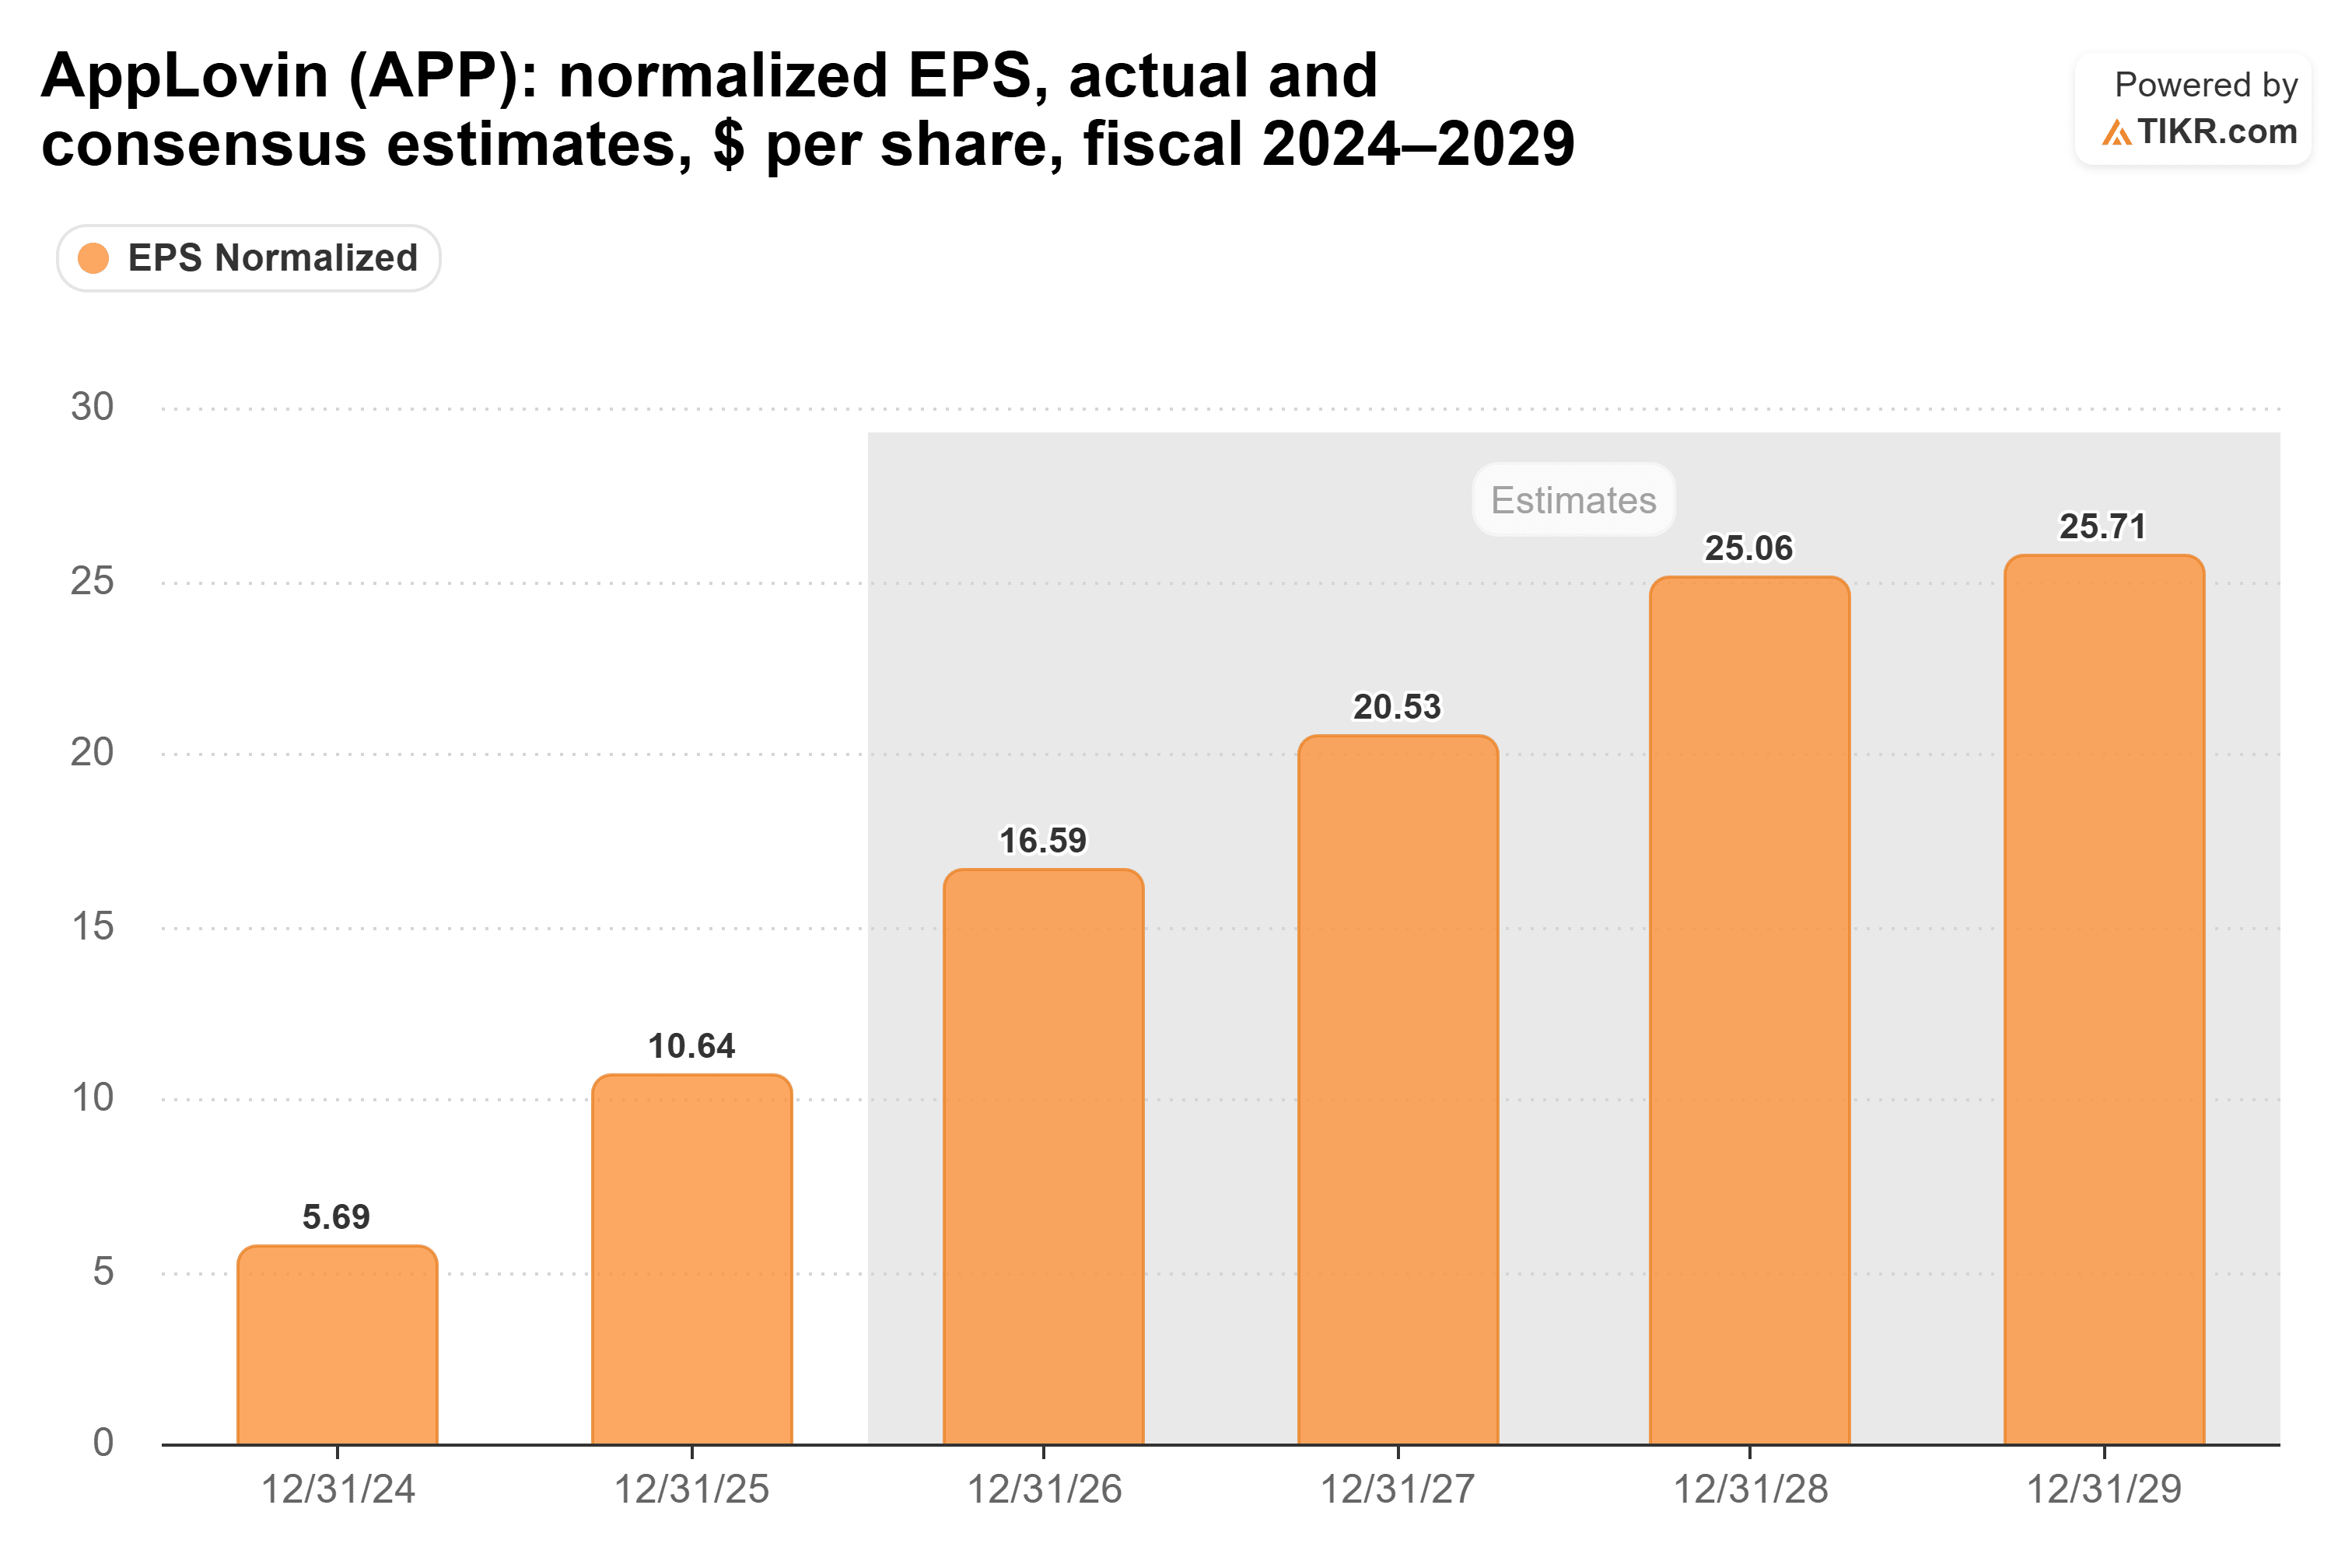
The contrast suggests that valuation compression, rather than collapsing earnings expectations, has driven much of the decline.
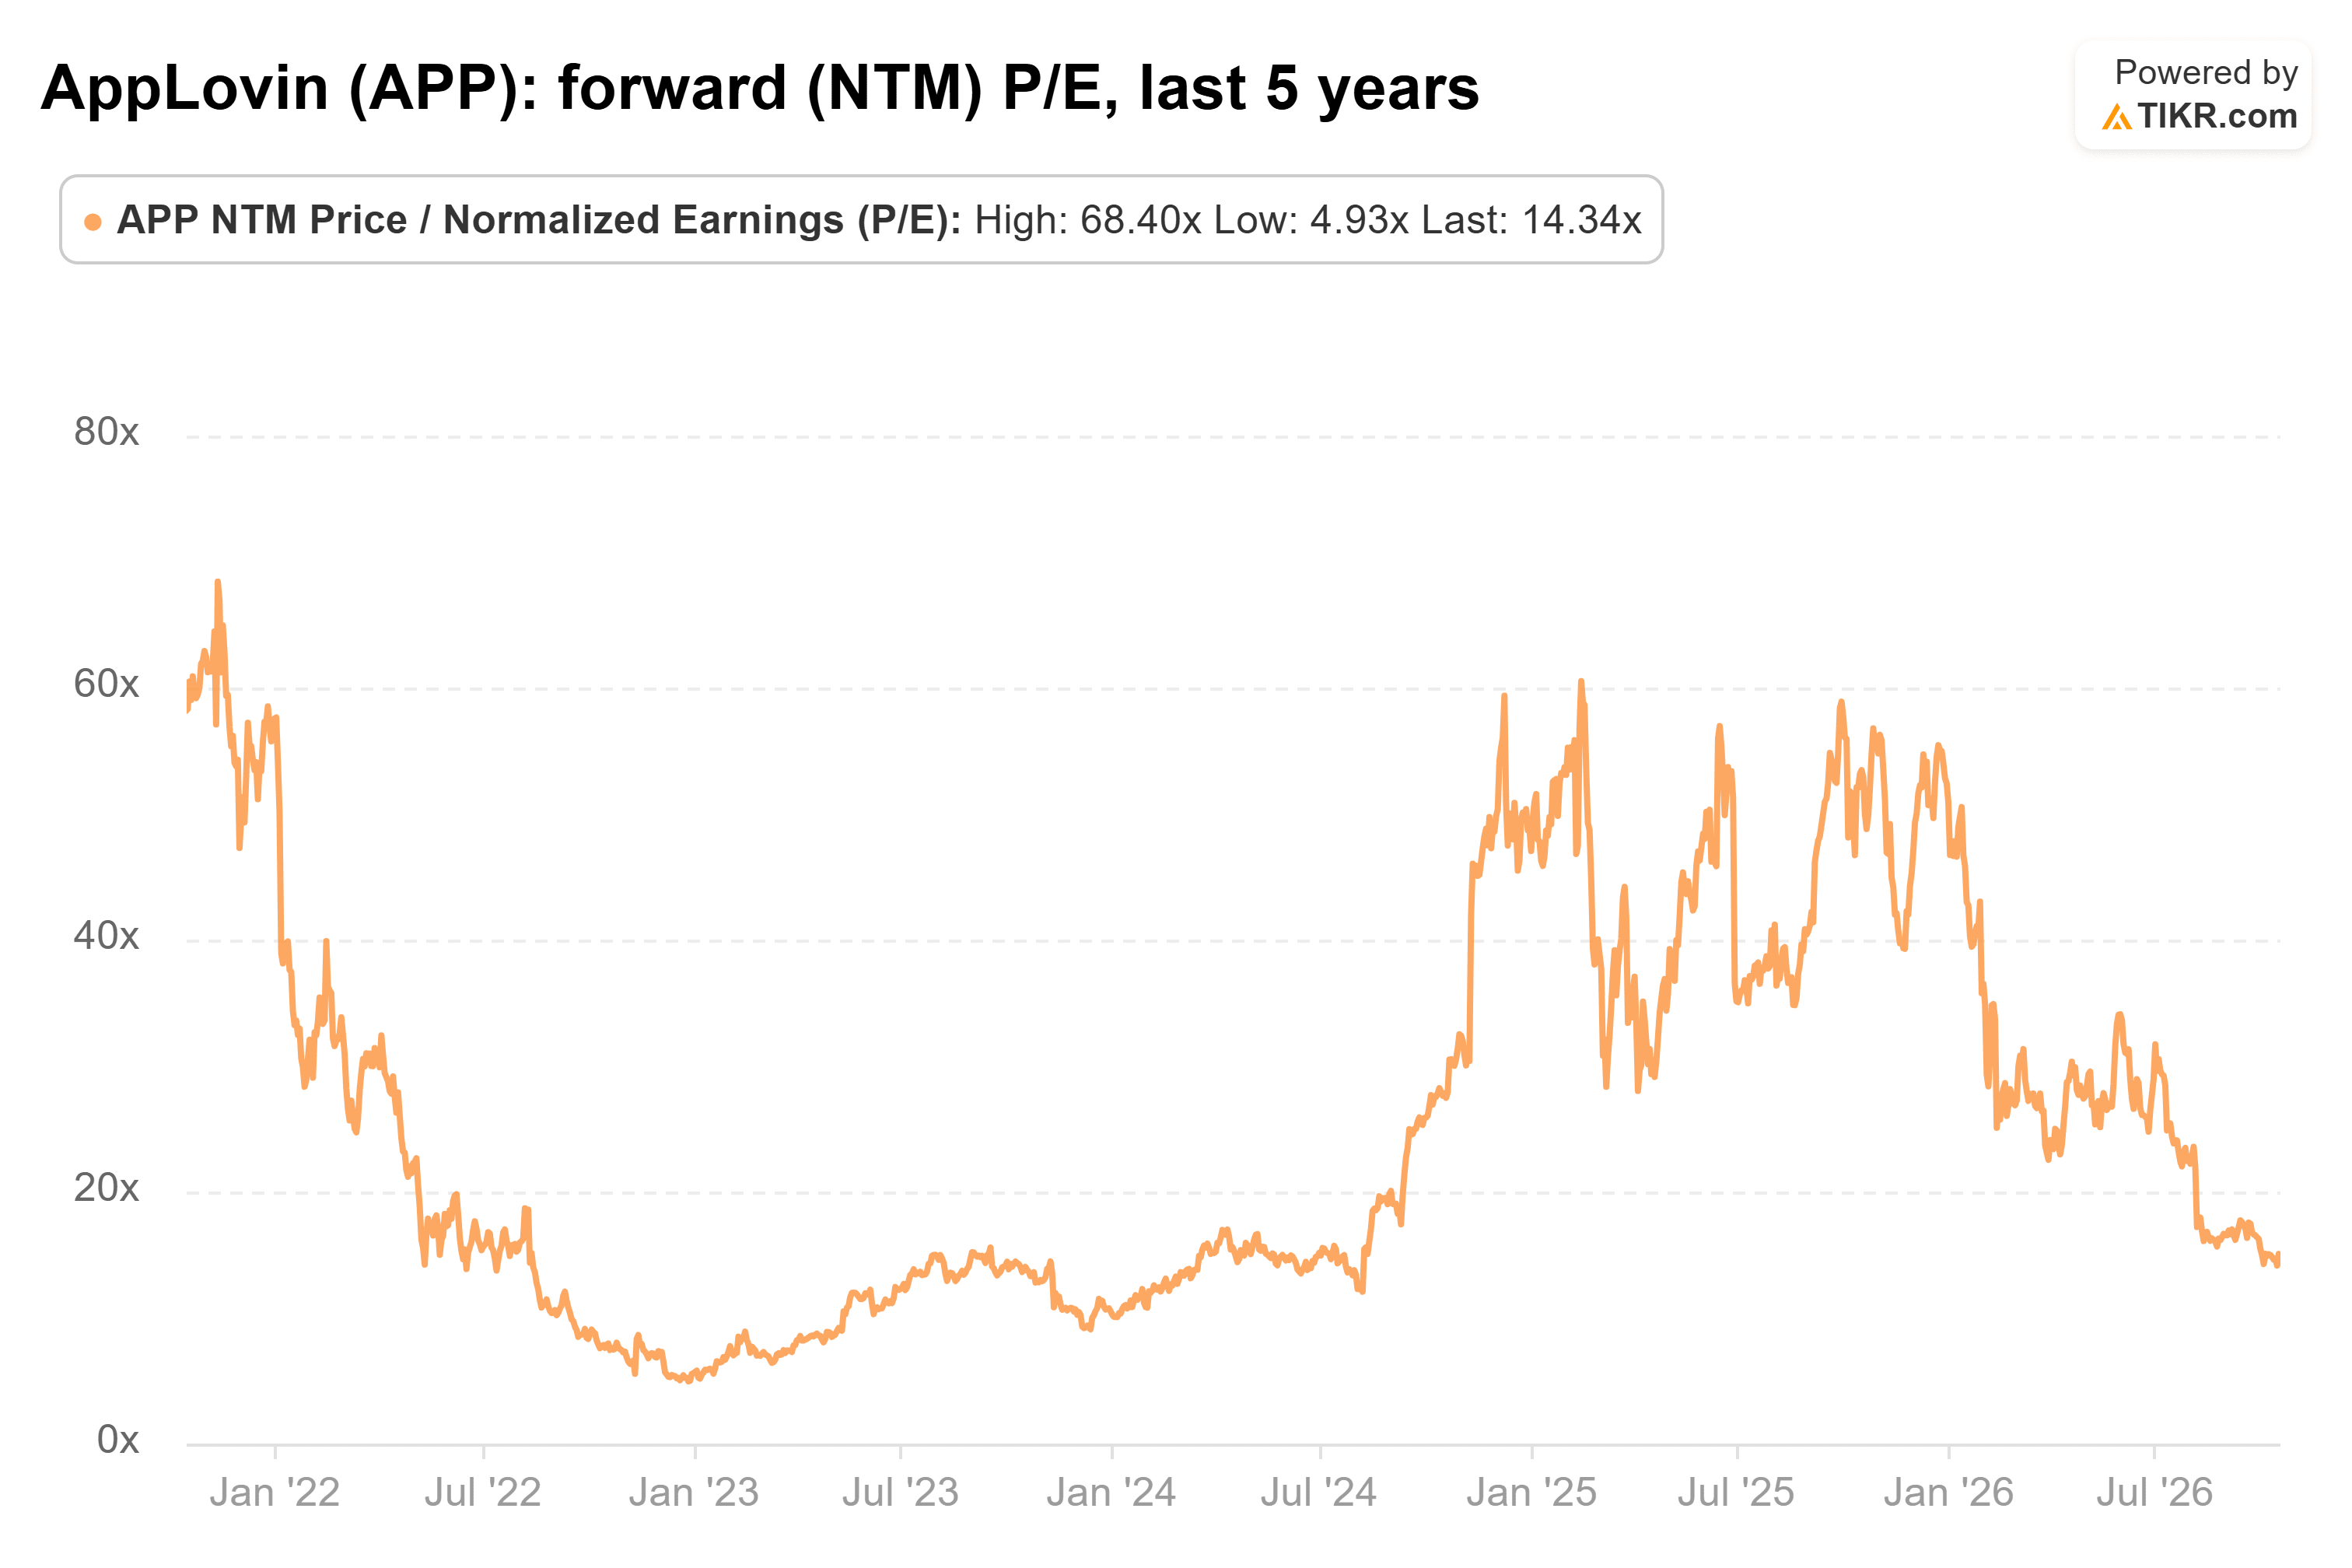
On October 16, APP traded at 14.3x forward earnings, compared with its five-year average of 25.6x.
That represents approximately 56% of its historical average valuation.
However, a lower multiple does not automatically mean a stock is undervalued, particularly if future earnings expectations decline.
Is AppLovin Stock a Buy or Sell After Its 12% Drop?
AppLovin looks more like a cautious buying opportunity than a stock investors need to sell simply because of its recent decline.
The company continues to generate strong revenue growth, while its valuation has contracted significantly.
AppLovin expects third-quarter revenue between $2.055 billion and $2.085 billion, with adjusted EBITDA guidance of $1.710 billion to $1.740 billion.
AppLovin will report third-quarter results on November 4, after the market closes.
If AppLovin meets guidance and demonstrates renewed AI-model improvements, its discounted valuation could offer substantial long-term upside.
However, another disappointing quarter could trigger further earnings-estimate reductions and share-price pressure.
For patient investors, APP presents a potential buying opportunity rather than an obvious sell, but the November earnings report will be critical in determining whether the selloff has gone too far.
So what is AppLovin stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AppLovin could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!