Key Takeaways
- Cloudflare shares fell 2.7% to $310 on Thursday ahead of its November 5 report, after gaining about 46% over six months.
- The company guided third-quarter revenue to $736 million to $737 million, up 31%, with adjusted EPS of $0.34.
- At 34x forward sales and 210x forward earnings, the stock leaves little room for a miss, and adjusted gross margin fell to 73.1% last quarter.
- Watch whether net retention holds near 120% and whether management raises full-year revenue guidance of $2.864 billion to $2.870 billion.
Last week, a cluster of PHP flaws knocked government websites offline and set off a global patching scramble. Cloudflare (NET) saw millions of exploit attempts after the disclosure.
Events like this are why customers pay Cloudflare. The stock still slipped 2.7% to $310 on Thursday.
Shares are up about 46% over the past six months but sit 16% below their 52-week high of $370. The real test comes November 5, when Cloudflare reports third-quarter results.
The bar for November 5
Cloudflare raised the bar itself in August. Second-quarter revenue rose 36% to $696.1 million, topping consensus by about $30 million, and adjusted EPS of $0.29 beat by two cents.
For the third quarter, management guided to:
- Revenue of $736 million to $737 million, up 31%
- Adjusted operating income of $129 million to $130 million
- Adjusted EPS of $0.34
It also raised full-year revenue guidance to $2.864 billion to $2.870 billion. Management has said it guides carefully because more deals now run on consumption and pool-of-funds contracts, which are harder to forecast.
Here’s the trend heading into the print…
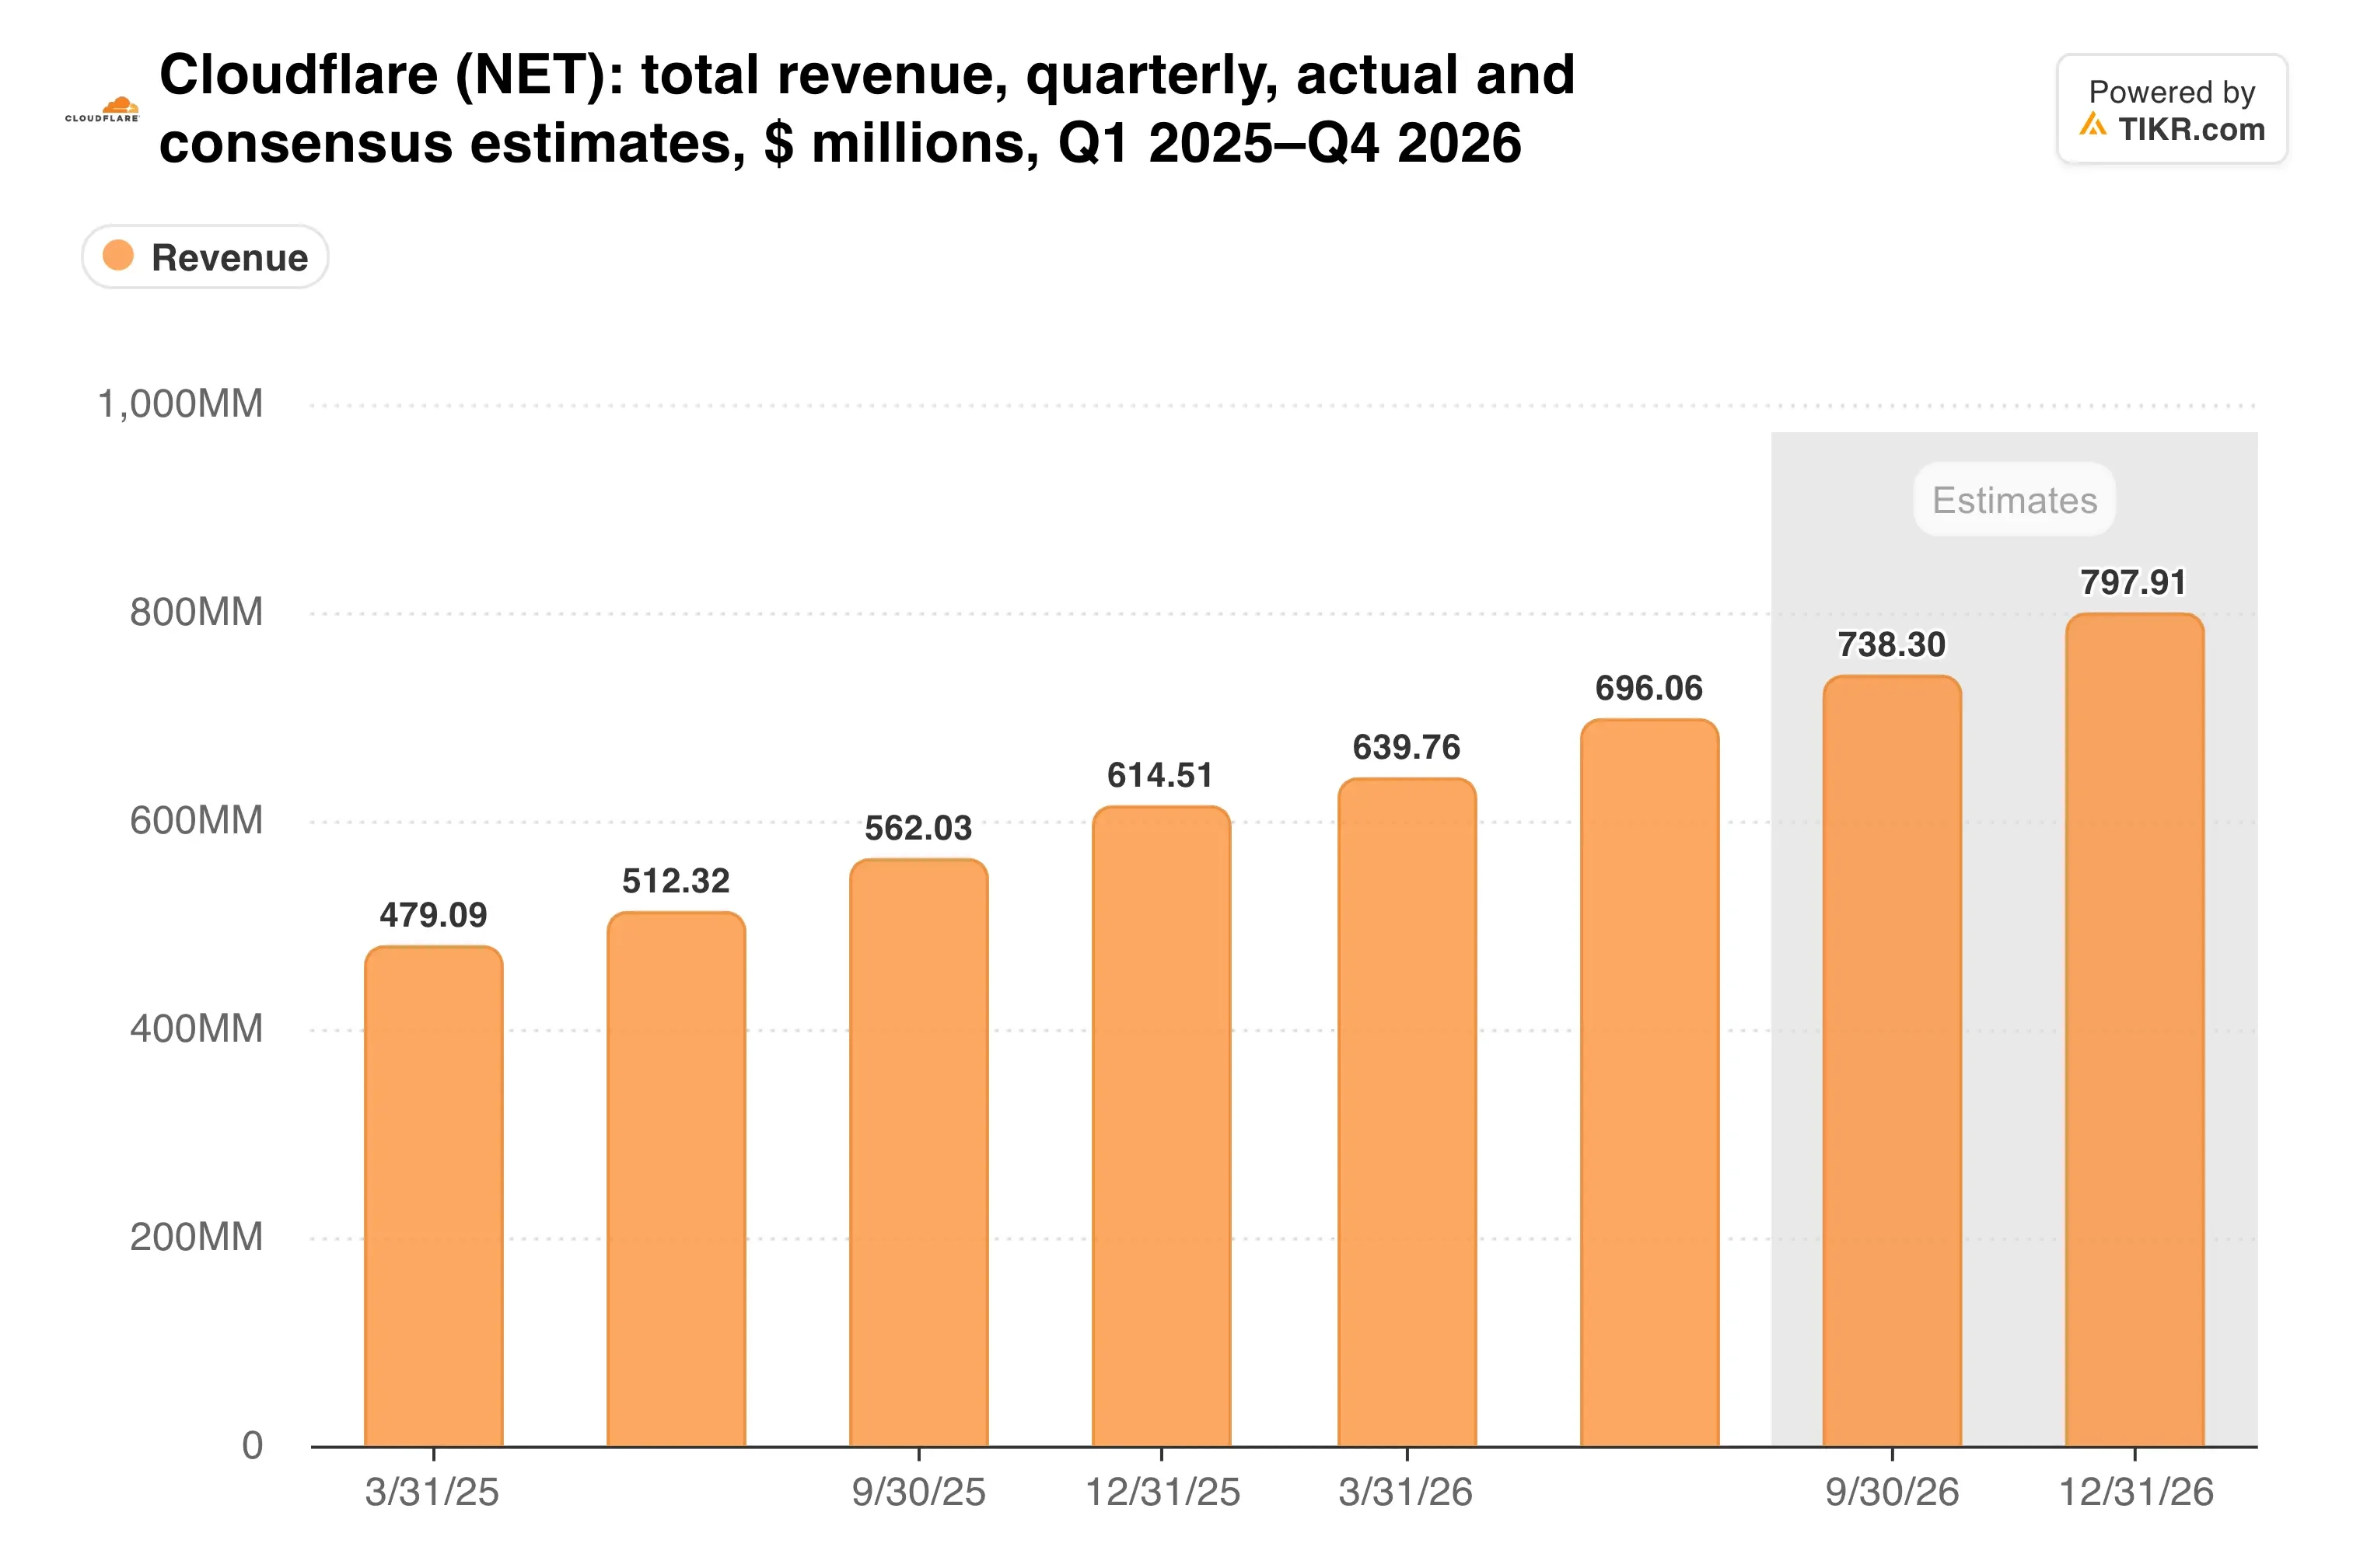
Growth would cool to 31% if Cloudflare lands on its guide. A beat like the second quarter’s would keep it in the mid 30s.
Machines are becoming the customer
CEO Matthew Prince framed the opportunity boldly in the second-quarter release. AI answer engines and agent-driven commerce are driving “a fundamental rewrite of the Internet for machine-to-machine traffic,” he said.
The customer data backs him up. Cloudflare’s developer base topped 10 million, up from 7.4 million a quarter earlier. Large customers rose 27% to 4,698 and now drive 73% of revenue.
Existing customers are spending more too. Dollar-based net retention climbed to 120%, up six points from a year ago, and current remaining performance obligations grew 35%.
Now compare that with the older incumbent…
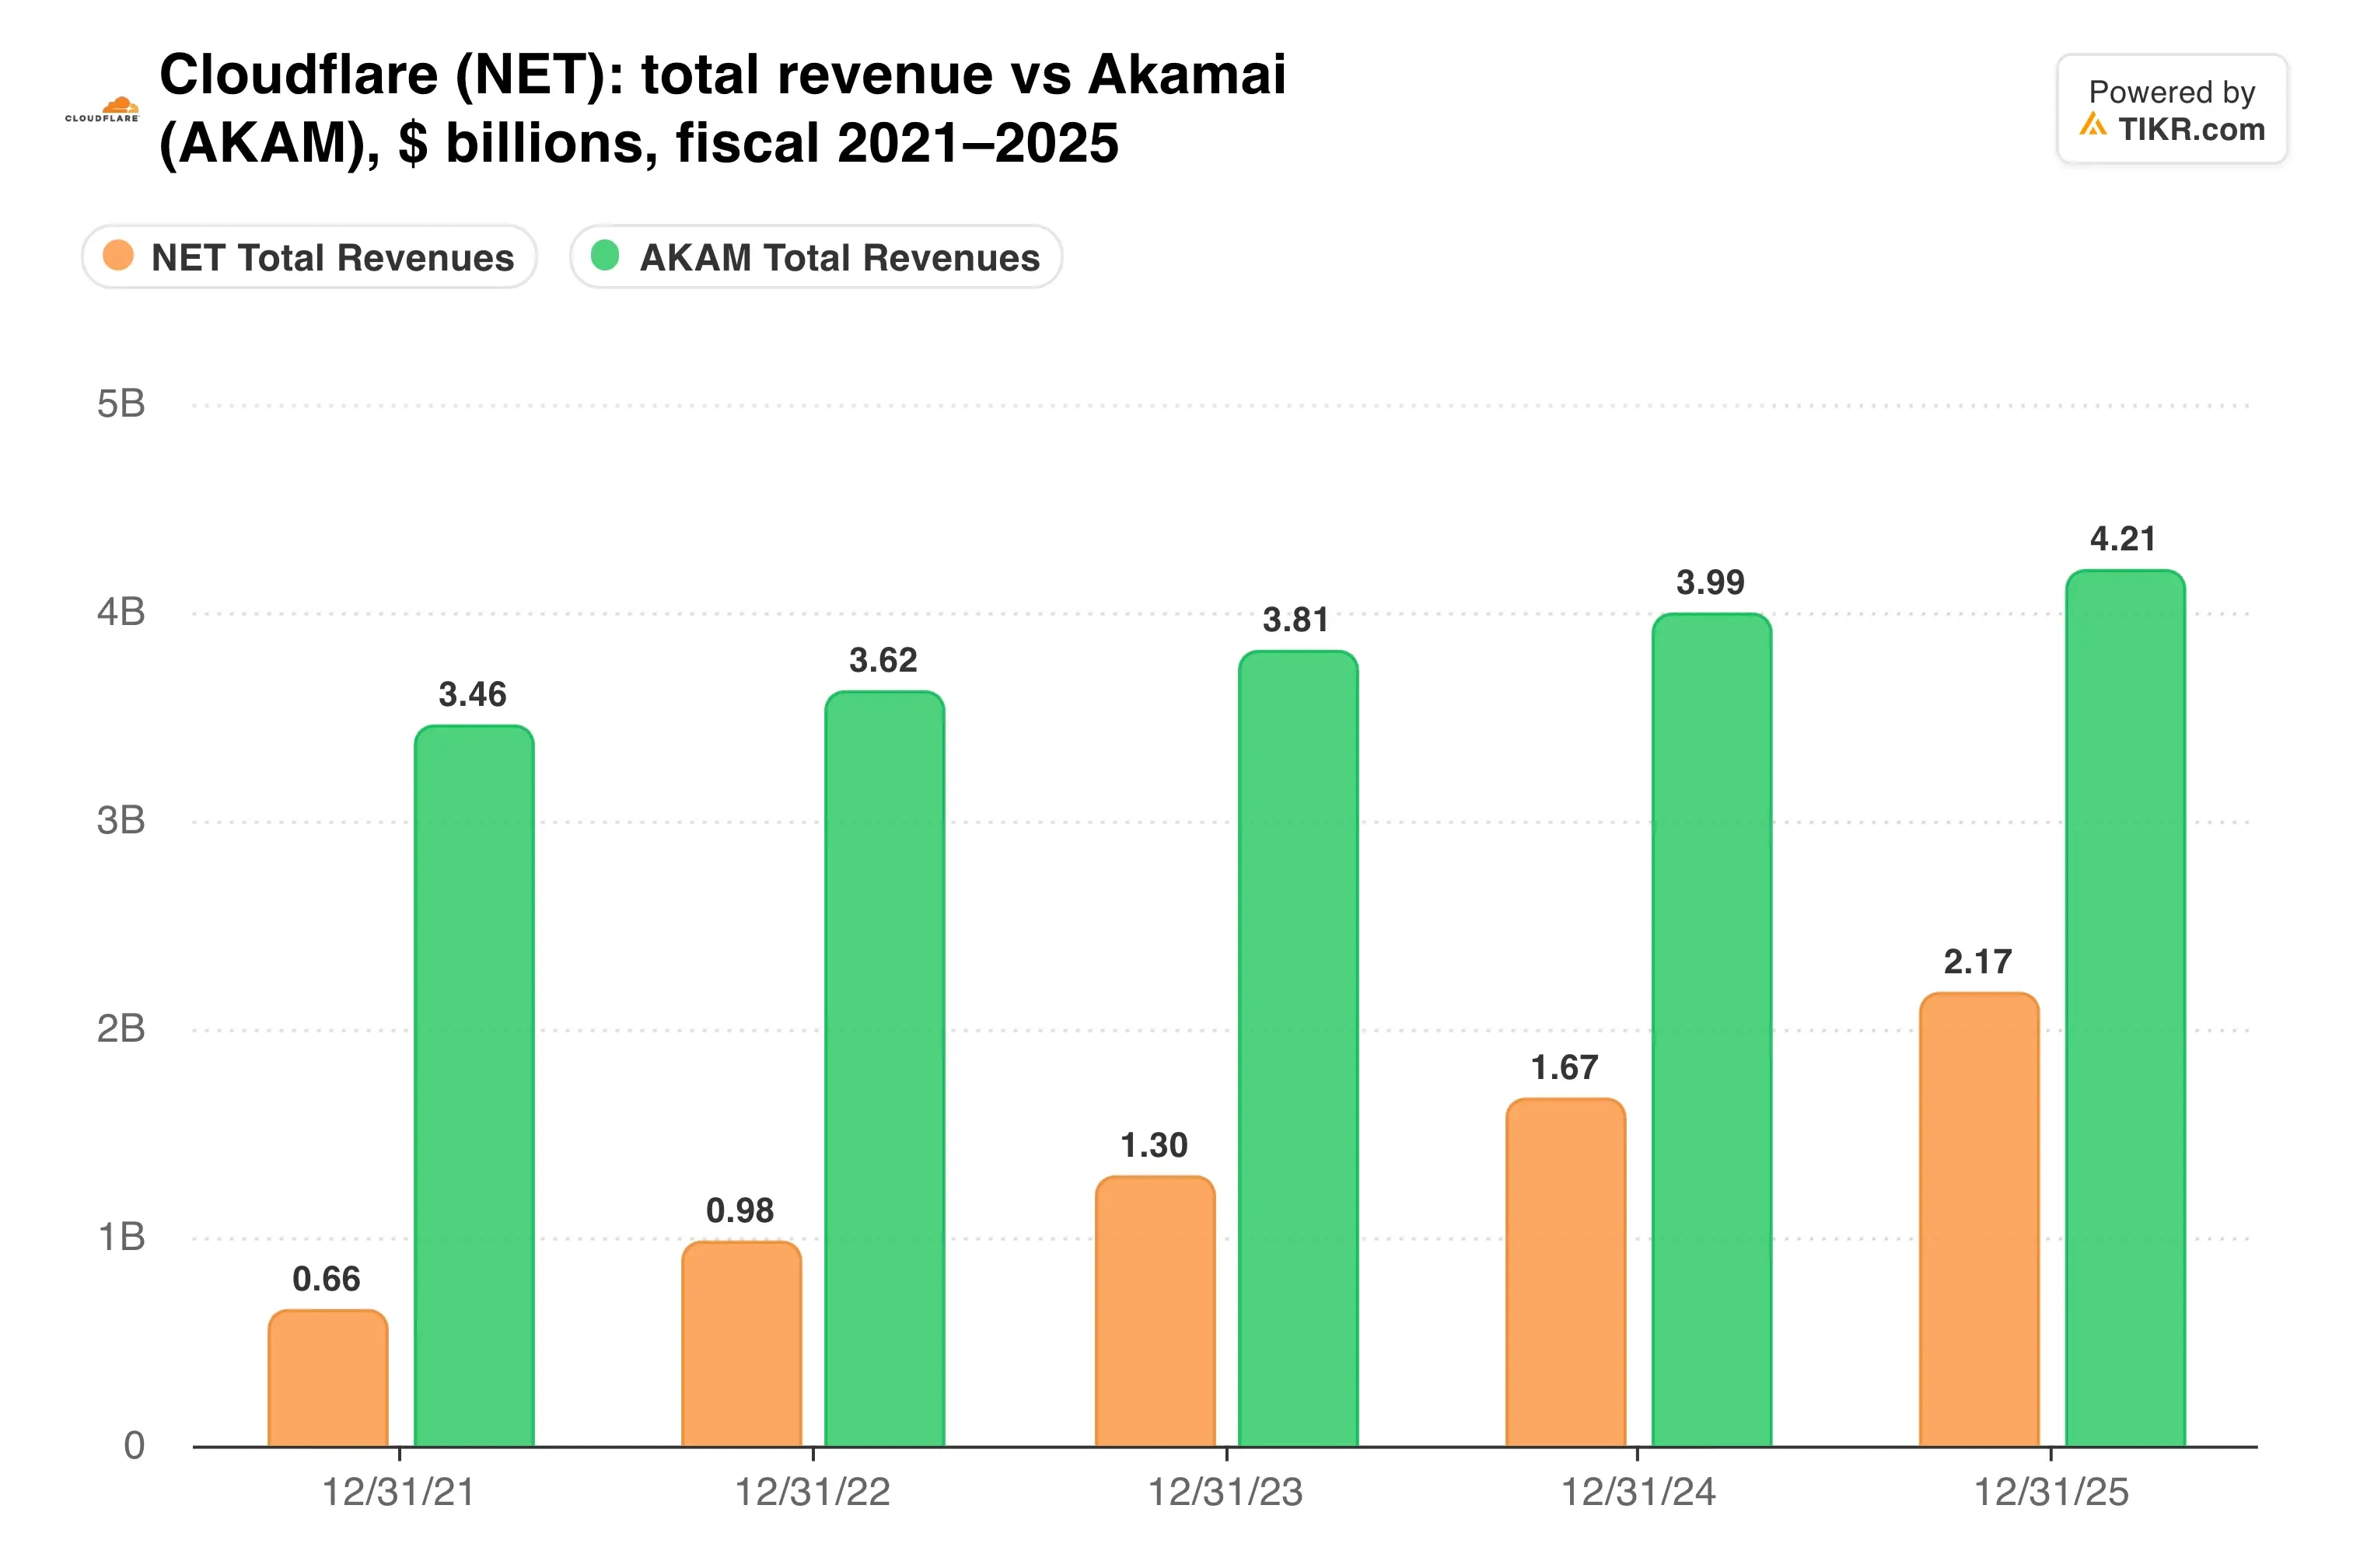
Akamai (AKAM) grew second-quarter revenue just 5% to $1.1 billion. Its cloud infrastructure unit grew 39%, but on only $99 million of revenue, so Cloudflare is closing the size gap fast.
TIKR tracks 34 analysts on Cloudflare. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cloudflare, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cloudflare’s Analyst Ratings
Paying up for the story
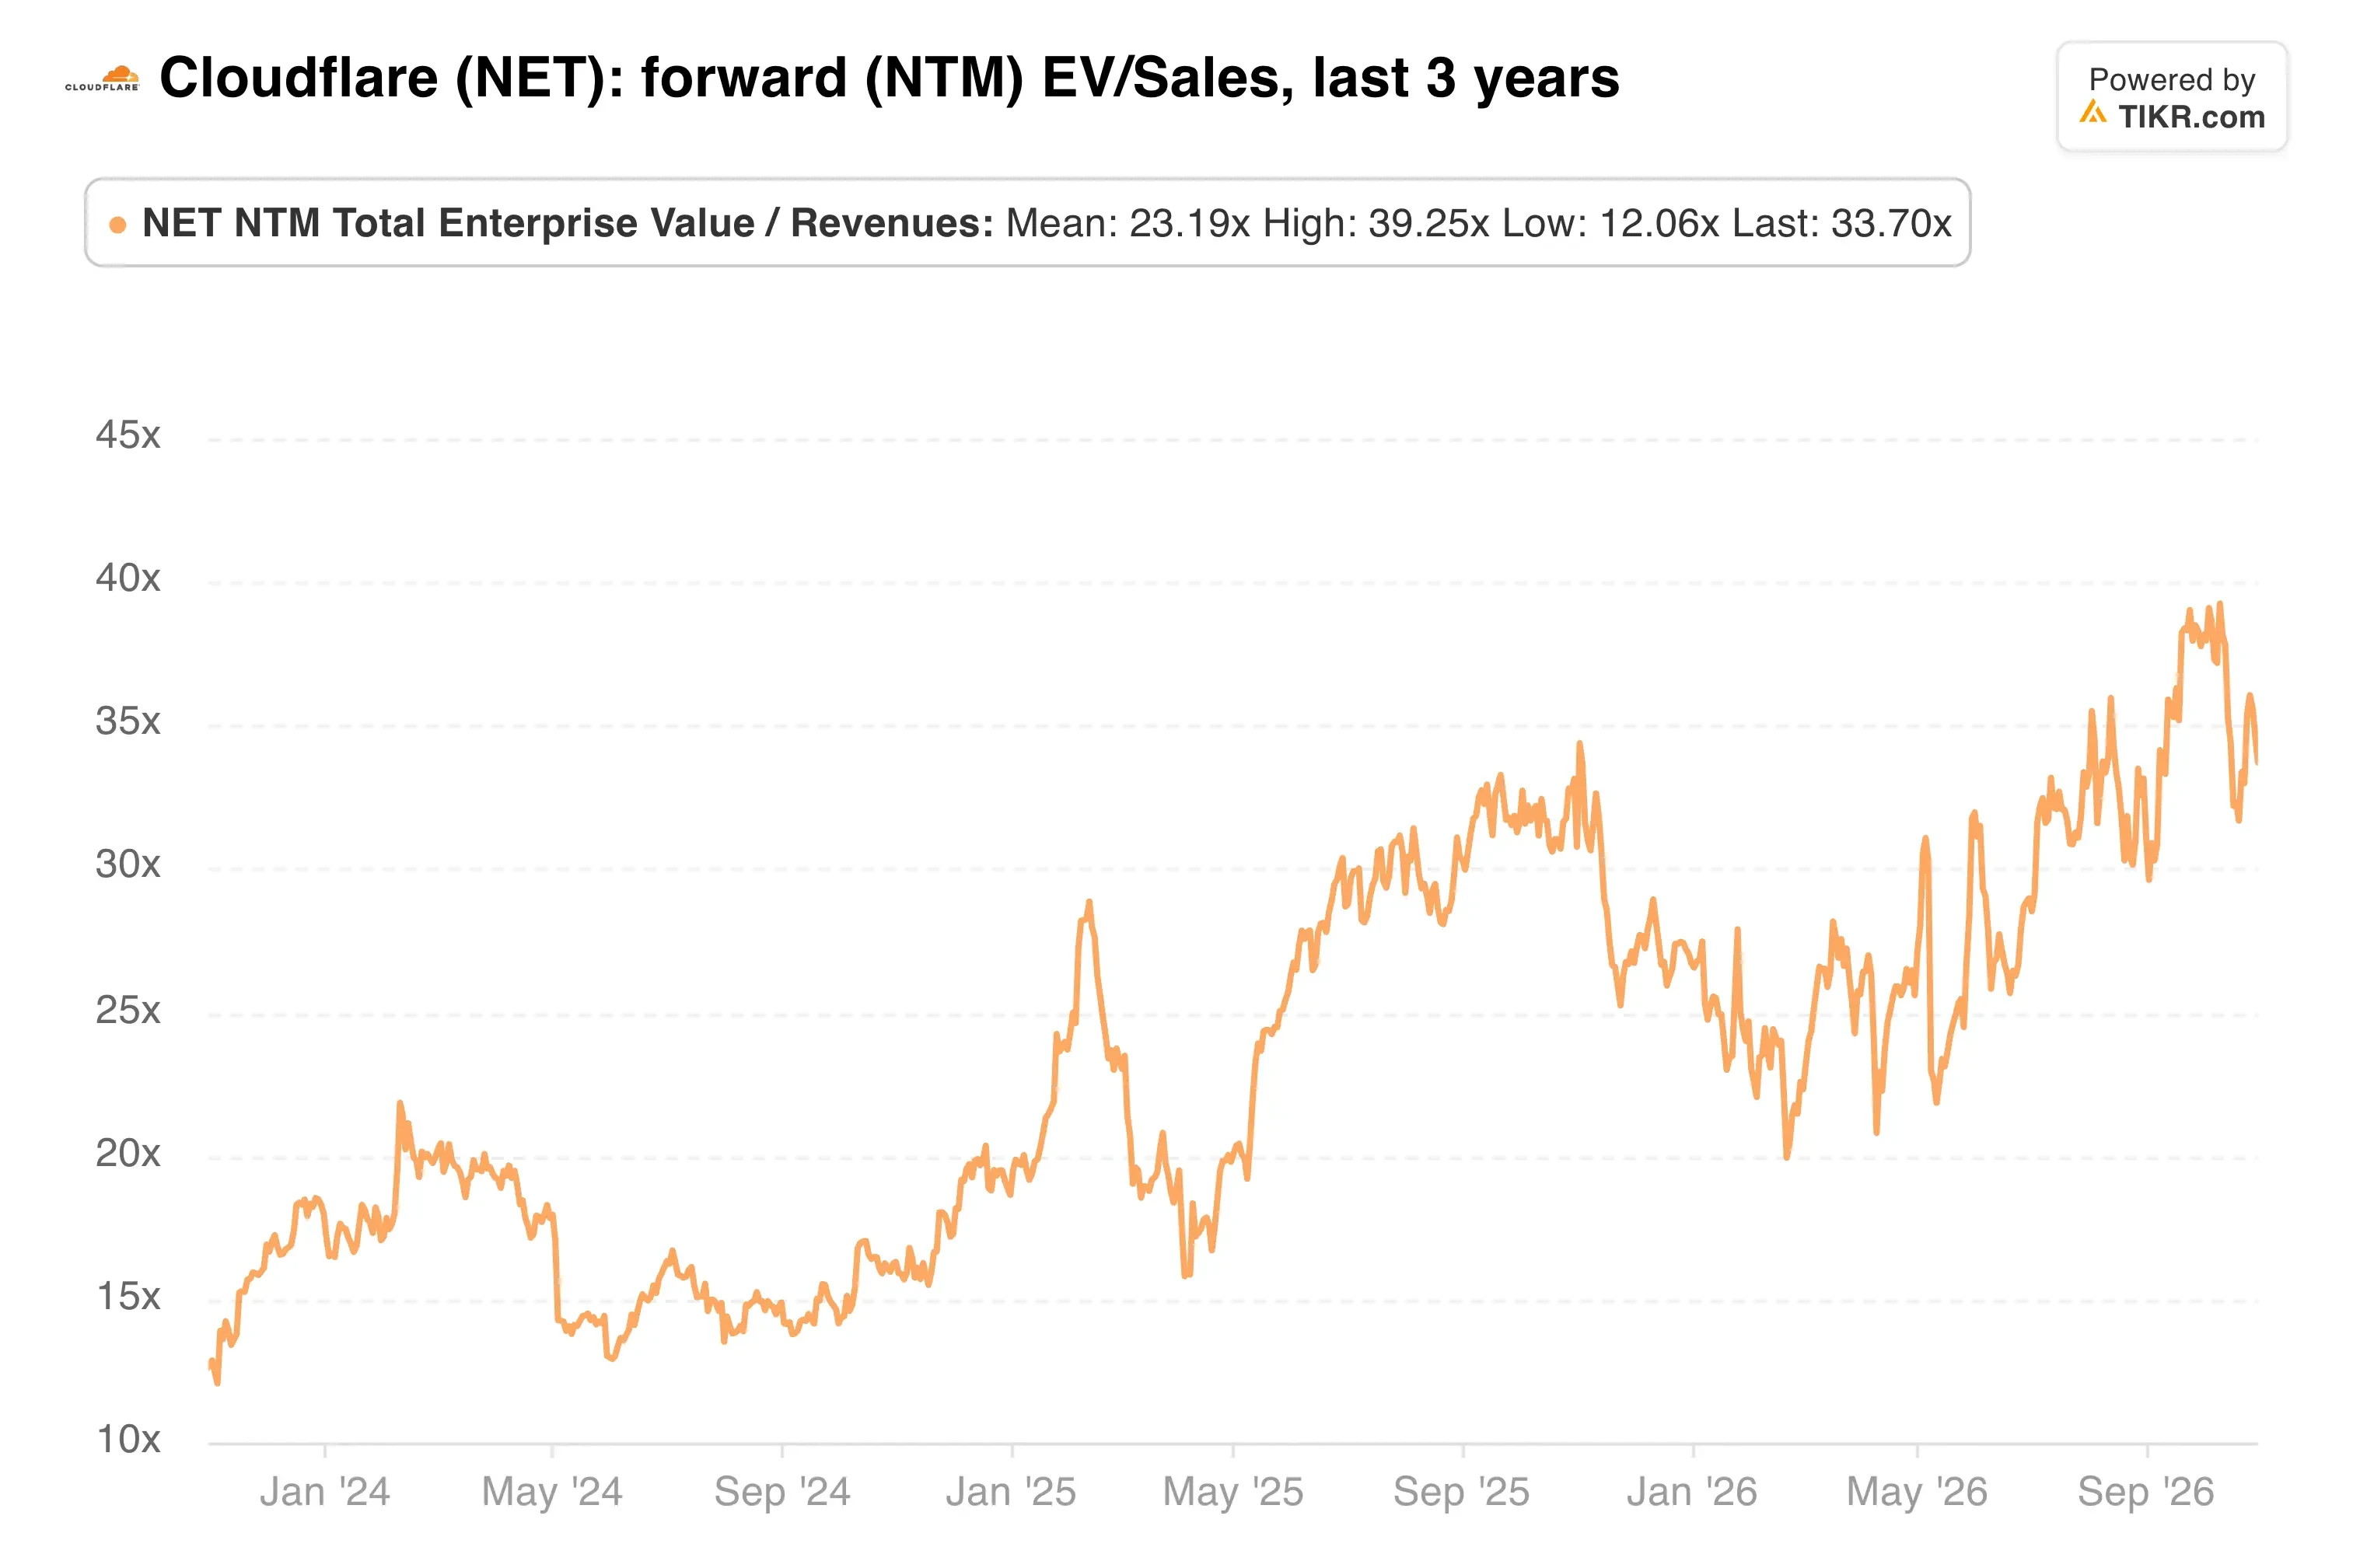
This is where it gets hard. Cloudflare trades at 34x forward sales and 210x forward earnings, and the average price target of $343 sits only about 11% above the current price.
What has that premium looked like over time?
Margins are also moving the wrong way. Adjusted gross margin fell to 73.1% in the second quarter from 76.3% a year earlier, and rising compute costs remain a risk. The GAAP operating loss reached $205.7 million after $151 million of restructuring charges.
Dilution is another overhang. Cloudflare sold $2.175 billion of 0% convertible notes due 2031 in August. Co-founder Michelle Zatlyn also sold about $27.5 million of stock in early October.
My take: Cloudflare is executing about as well as any software company right now, and the machine traffic story looks real to me. Yet at 34x sales, even a solid beat may not lift the stock much. I’d wait for a pullback before buying.
The checkpoint is November 5. A full-year guide raise and net retention holding near 120% would justify the multiple for another quarter.
So what is Cloudflare stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cloudflare could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!